
 United States Electric Kettle Market | 2026-2036
United States Electric Kettle Market Size, Share, and Industry Trends Forecast 2026-2036
United States Electric Kettle Market Analytics
Aftermarket service revenue for temperature calibration and scale-removal programs is fragmenting across third-party appliance-repair networks and direct-to-consumer subscription models. Spectrum Brands leverages its multi-brand portfolio to sustain replacement-part margins through proprietary heating-element designs. Hamilton Beach Brands anchors the mass-market channel with broad retail distribution, while Breville USA differentiates through precision-temperature engineering targeted at coffee enthusiasts.
An electric kettle is a corded or cordless vessel with an integrated resistive heating element, typically rated between 1,000 and 1,500 watts, designed to bring water to boiling point for beverage preparation or food service. Stainless steel and glass variants command premium positioning due to durability perceptions and aesthetic alignment with open-kitchen design trends. Temperature control kettles lead the product-type margin pool by addressing specialty coffee preparation protocols, while multifunctional kettles with integrated tea infusers represent the fastest-growing configuration among urban millennials.
The Consumer Product Safety Commission enforces cord-safety and burn-hazard standards that shape housing-material selection and auto-shutoff circuitry requirements. The Department of Energy's appliance efficiency regulations and California's Title 20 standards collectively pressure manufacturers toward lower standby-power designs and improved thermal insulation. Stakeholders must monitor evolving state-level efficiency mandates and the potential for federal right-to-repair legislation that would expand independent access to replacement heating elements and control modules.
Market Dynamics
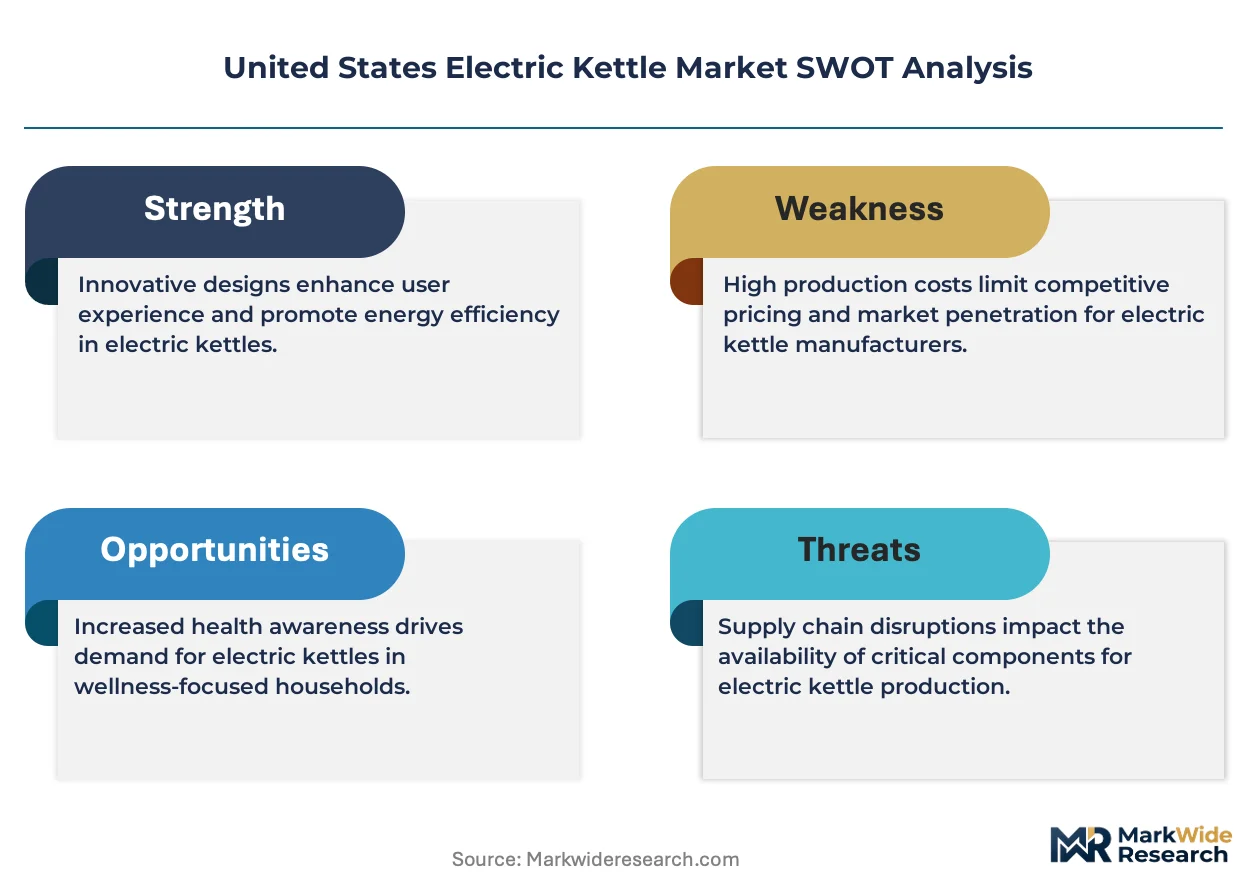
The United States electric kettle market is being restructured by the Department of Energy's appliance efficiency standards, which compress margins on conventional heating elements while rewarding variable-wattage designs that reduce standby power consumption.
Growth Catalysts
- Title 20 Standards:California's efficiency mandates accelerate replacement cycles in the nation's largest state market, pulling through premium temperature-control models.
- Specialty Coffee Shops:Boutique cafes across the Pacific Northwest and Northeast corridors are expanding procurement of precision-temperature equipment for pour-over protocols.
- Urban Kitchen Renovation:Premium renovation cycles in California, Texas, and New York concentrate demand for stainless steel and glass variants aligned with open-kitchen aesthetics.
Market Restraints
- Heating Element Cost Volatility:Nickel-chromium alloy prices fluctuate with stainless steel feedstock costs, squeezing margins on conventional resistive designs.
- Supply Concentration Risk:Control module and thermostat assembly concentrates in Southeast Asian contract manufacturers, exposing lead-time vulnerability.
- Regulatory Friction:The Consumer Product Safety Commission's evolving cord-safety and burn-hazard standards require continuous housing-material redesign and auto-shutoff circuitry investment.
Strategic Opportunities
- Aftermarket Service Expansion:Temperature calibration and scale-removal programs fragment across direct-to-consumer subscription models, creating recurring revenue streams.
- Right-to-Repair Tailwind:Pending federal legislation would expand independent access to replacement heating elements and control modules, opening parts-market entry.
- Multifunctional Convergence:Integrated tea infuser configurations address urban millennial demand for single-appliance versatility in space-constrained kitchens.
Industry Challenges
- Embedded Systems Talent Gap:Variable-wattage and precision-temperature engineering requires firmware expertise scarce in traditional small-appliance engineering teams.
- Certification Timeline Compression:DOE efficiency testing and CPSC safety validation cycles must accelerate to match seasonal retail stocking windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Electric Kettle Market |
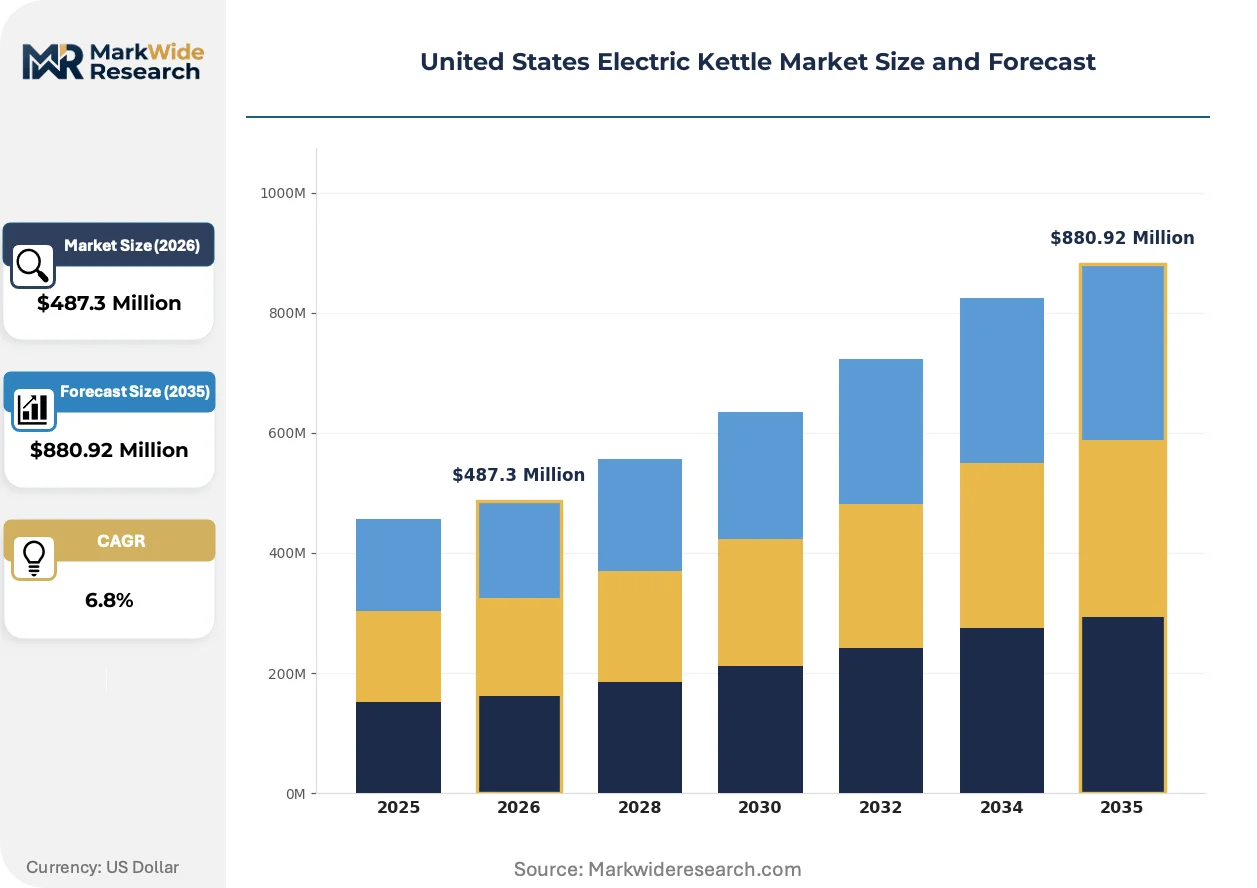
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Kettles, Travel Kettles, Multifunctional Kettles, Temperature Control Kettles Material: Stainless Steel, Glass, Plastic, Ceramic End User: Households, Cafes, Restaurants, Hotels Distribution Channel: Online Retail, Offline Retail, Specialty Stores, Supermarkets |
| Companies Covered | Cuisinart, Spectrum Brands, Hamilton Beach Brands, Electrolux, Groupe SEB USA, KitchenAid, Newell Brands, Smeg SPA, Breville USA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Electric Kettle Market Evolving Landscape
Variable-wattage heating architectures and smart connectivity modules are restructuring product development priorities, with manufacturers racing to embed precision control without triggering efficiency-penalty thresholds.
Induction-compatible base designs with integrated temperature sensors are rendering obsolete simple binary thermostats in mid-tier and premium segments. Specialty coffee enthusiasts and tea connoisseurs in metropolitan markets are adopting these systems at accelerating rates. The shift is compressing replacement cycles for conventional kettles while expanding the addressable margin pool for precision-engineered alternatives.
The Department of Energy's standby-power regulations and California's Title 20 standards collectively force redesign of thermal insulation and control-circuit efficiency. Manufacturers must now engineer housing assemblies that maintain temperature precision while minimizing idle energy draw. The Pacific Northwest and Northeast urban markets, where electricity rates run highest, show the strongest response to efficiency-certified models.
Direct-to-consumer subscription models for descaling agents and replacement filters are displacing traditional retail attachment sales. Urban millennial households, concentrated in California and New York, favor bundled service relationships over transactional parts purchases. This behavioral shift is most visible in the temperature-control kettle segment, where ongoing calibration maintenance preserves precision performance.
United States Electric Kettle Market Segmentation
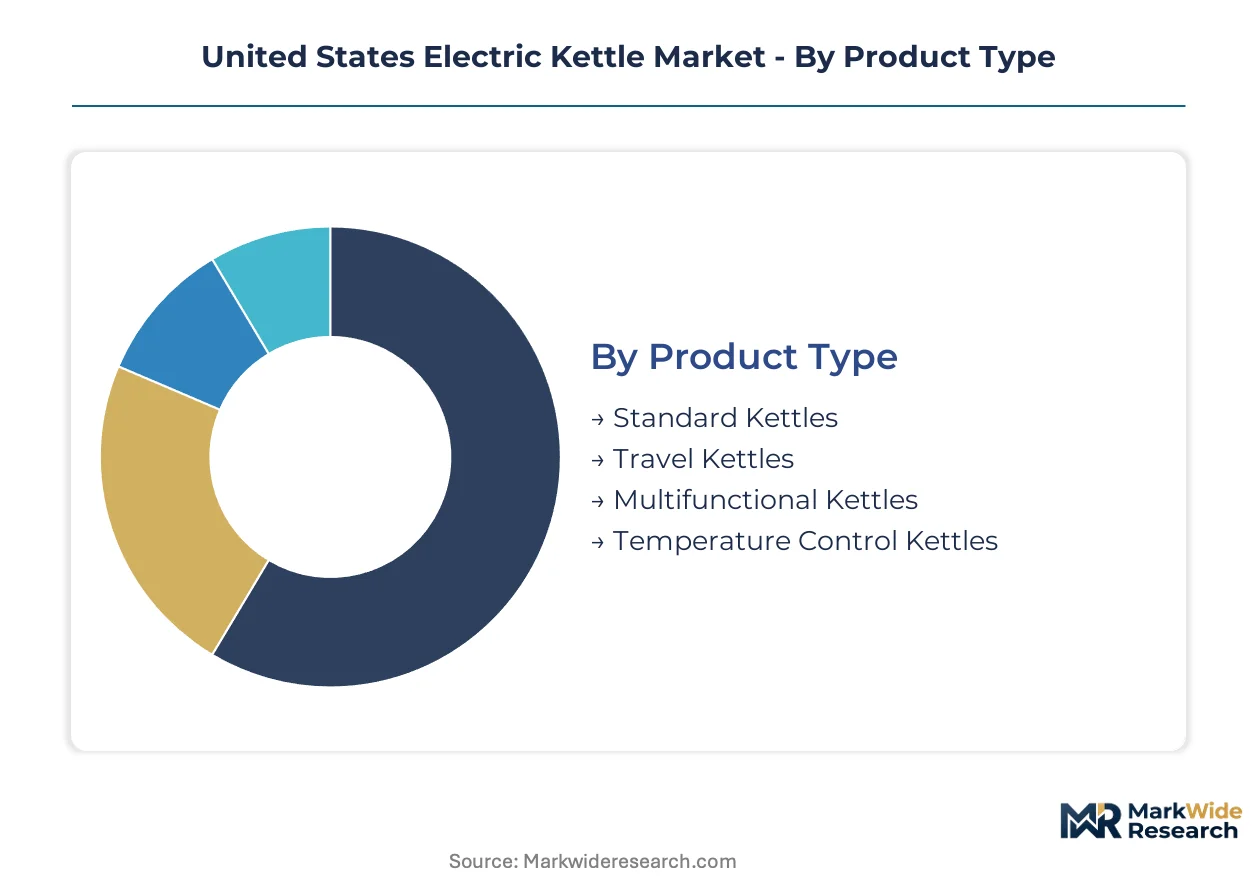
Electric kettle segmentation in the United States reflects divergent performance requirements across beverage preparation contexts and kitchen renovation cycles. Manufacturers calibrate material selection, heating architecture, and distribution strategy to match distinct margin profiles within each category.
Product Type:
Cost tier differentiation separates commodity boiling from precision-temperature engineering in the United States electric kettle market.
- Temperature Control Kettles:Variable-wattage heating elements with digital thermostats enable single-degree precision for pour-over coffee protocols. Specialty cafes in Seattle and Portland anchor commercial procurement, while California households drive residential adoption during premium kitchen renovations.
- Multifunctional Kettles:Integrated tea infusers and programmable steep timers consolidate single-appliance functionality for space-constrained urban kitchens. New York and Boston millennials favor these configurations for studio and one-bedroom apartment layouts.
- Standard Kettles:Binary thermostats and fixed-wattage elements serve basic boiling requirements across mass-market channels.
- Travel Kettles:Collapsible or compact designs with dual-voltage compatibility address transient lodging and business travel segments.
Temperature Control Kettles hold installed capacity. Multifunctional Kettles is rotating up the share rankings.
Material:
Application context dictates material selection, with aesthetic alignment and durability perception driving premium positioning decisions.
- Stainless Steel:Nickel-chromium alloy housings withstand thermal cycling and mechanical impact in high-frequency commercial environments. Texas restaurants and California boutique cafes specify brushed or polished finishes for open-kitchen visibility.
- Glass:Borosilicate construction enables visual monitoring of water clarity and boiling progression. Northeast urban households prioritize glass variants for design coherence with visible countertop appliance collections.
- Plastic:Polypropylene housings minimize unit cost for price-sensitive mass-market distribution.
- Ceramic:Glazed clay construction appeals to tea ceremony practitioners and aesthetic-driven kitchen renovators.
Stainless Steel dominates commercial specification. Glass is gaining share fastest among residential premium tiers.
End User:
Volume scale and replacement frequency diverge sharply across household and foodservice deployment patterns.
- Households:Residential procurement concentrates in California, Texas, and New York, where urban density and renovation activity overlap. Temperature-precision models are displacing conventional kettles at the fastest rate in Pacific Northwest metropolitan areas.
- Cafes:Independent coffee shops in Portland, Seattle, and Brooklyn drive demand for gooseneck spout designs with flow-rate control.
- Restaurants:Back-of-house boiling requirements prioritize speed and durability over temperature precision.
- Hotels:In-room amenity specifications favor compact, quiet operation with minimal counter footprint.
Households represent the volume anchor. Cafes are climbing the fastest as specialty coffee preparation expands.
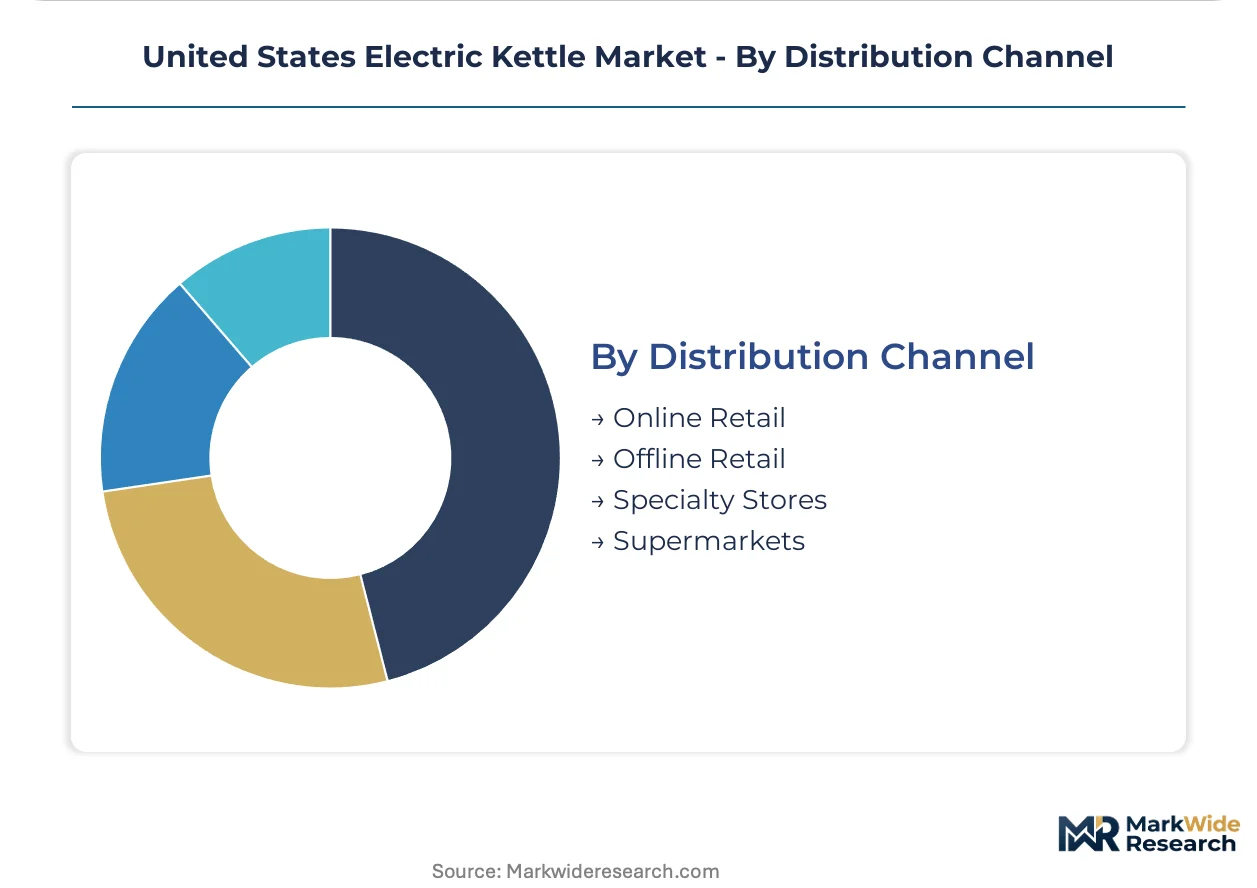
Distribution Channel:
Customer type determines channel selection, with subscription and direct relationships displacing transactional retail in precision-temperature segments.
- Online Retail:Direct-to-consumer platforms enable bundled accessory sales and subscription descaling programs. Urban millennial households in California and New York favor this channel for temperature-control kettle purchases.
- Specialty Stores:Sur La Table and Williams Sonoma locations provide hands-on demonstration for premium models. Coffee equipment retailers in Portland and San Francisco anchor regional specialty distribution.
- Offline Retail:Big-box chains sustain mass-market volume for standard kettles.
- Supermarkets:Grocery channel placement captures impulse replacement purchases.
Online Retail holds the steepest expansion trajectory. Specialty Stores maintain positioning power in premium segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California households favor temperature-precision models for pour-over coffee preparation, while Texas restaurants prioritize rapid-boiling durability for back-of-house operations. The Pacific Northwest and Northeast urban corridors exhibit divergent consumption patterns: Seattle and Portland cafes drive precision-equipment procurement, whereas New York and Boston millennials gravitate toward multifunctional designs for space-constrained apartments.
California
Premium kitchen renovation cycles and open-kitchen aesthetics fuel stainless steel and glass variant demand. The California Energy Commission's Title 20 appliance efficiency standards accelerate replacement cycles toward variable-wattage designs. Los Angeles and San Francisco metropolitan areas concentrate specialty coffee shop procurement of gooseneck spout configurations.
Texas
Restaurant and cafe back-of-house operations anchor commercial volume for high-durability nickel-chromium alloy housings. The state's deregulated electricity market reduces efficiency-premium sensitivity compared to coastal counterparts. Dallas and Houston urban clusters sustain mass-market channel volume for standard boiling configurations.
New York
Millennial apartment dwellers in studio and one-bedroom layouts drive multifunctional kettle adoption with integrated tea infusers. The state's right-to-repair legislation momentum shapes aftermarket parts accessibility expectations. Brooklyn and Manhattan specialty coffee retailers anchor precision-temperature equipment demonstration and sales.
Pacific Northwest
Seattle and Portland independent coffee shops constitute the densest commercial concentration of pour-over protocol equipment. High electricity rates in municipal utilities accelerate consumer response to DOE standby-power certified models. The region's boutique cafe culture normalizes premium price points for temperature-control engineering.
Northeast Corridor
Boston and Philadelphia metropolitan households exhibit strong glass variant preference for visible countertop appliance coherence. State-level appliance efficiency mandates in Massachusetts and Connecticut compress conventional product margins. Specialty kitchen retailers in the corridor maintain hands-on demonstration capacity for premium segment positioning.
United States Electric Kettle Market Competitive Landscape
Capability concentration sits with precision-temperature engineering specialists; scale advantage sits with mass-market distribution incumbents. The market structure exhibits tiered consolidation: a handful of multi-brand portfolios dominate volume, while specialist manufacturers capture premium margin pools. Three archetypes define competitive positioning: multi-brand conglomerates leveraging replacement-part ecosystems, precision-engineering specialists targeting coffee enthusiasts, and mass-market anchors sustaining broad retail presence. Dominant competitive moves include portfolio diversification across price tiers and strategic partnerships with specialty retail channels.
Within the multi-brand tier, Spectrum Brands and Hamilton Beach Brands exemplify divergent scale strategies: the former sustains proprietary component margins through captive heating-element design, while the latter anchors mass-market channel coverage. Breville USA occupies a position within the precision-engineering archetype, representing temperature-control specialization for specialty beverage preparation. These three entities collectively illustrate the capability-scale tension structuring competitive dynamics.
| Leading Market Players |
|---|
| Cuisinart |
| Spectrum Brands |
| Hamilton Beach Brands |
| Electrolux |
| Groupe SEB USA |
| KitchenAid |
| Newell Brands |
| Smeg SPA |
| Breville USA |
| Others |
Value Network & Pricing Analysis
Trans-Pacific container freight corridors from Shenzhen and Ningbo to Long Beach and Seattle determine landed cost spreads between contract-manufactured and domestically assembled units, compressing margin pools for temperature-control models while amplifying price differentiation between premium stainless steel variants and mass-market plastic configurations.
Pricing Analysis
Long-term offtake agreements between mass-market brands and big-box retailers anchor volume pricing, while spot procurement through direct-to-consumer channels enables dynamic premium positioning. Price differentiation rests on DOE efficiency certification tier and heating-element wattage precision, with California Title 20 compliance commanding measurable premiums. Cost compression in conventional fixed-wattage segments is intensifying because nickel-chromium alloy feedstock volatility squeezes contract manufacturers. Mass-market households exhibit highest price sensitivity, whereas specialty coffee shops demonstrate lowest sensitivity due to protocol-driven equipment specifications.
Supply Chain Analysis
Contract-manufacturing concentration sits with Foxconn, Flex, and Jabil Electronics for control module and thermostat assembly, with secondary capacity in Vietnam and Mexico diversifying geographic risk. Raw material dependencies draw from Chinese nickel-chromium alloy production, Malaysian polypropylene resin, and Taiwanese semiconductor components for precision-temperature firmware. Single-source vulnerability concentrates in Southeast Asian thermostat assembly, where lead-time disruptions ripple through seasonal retail stocking windows. Distribution runs through importer-of-record networks to West Coast consolidation points, then splits between big-box retail DCs and direct-to-consumer fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives against countertop induction systems and precision pour-over kettles with integrated grinders, which threaten to displace standalone electric kettle demand in premium kitchen renovations.
For Market Incumbents: Pre-empt precision-temperature capability erosion by acquiring firmware engineering talent scarce in traditional appliance teams, and backward integrate into nickel-chromium heating element production to offset alloy cost volatility. Defend against countertop induction substitution by embedding gooseneck flow-control designs into temperature-control portfolios.
For New Entrants and Emerging Players: Build out direct-to-consumer subscription service infrastructure for descaling agents and calibration maintenance, targeting Pacific Northwest and Northeast urban millennials in studio apartment configurations. White-space opportunity concentrates in multifunctional kettles with integrated tea infusers, where established brands underinvest in programmable steep-timer engineering.
For Investors and Strategic Acquirers: Carve-out targets emerge from multi-brand conglomerates seeking to divest non-core small-appliance divisions with captive heating-element production. Long-term viability hinges on right-to-repair legislative tailwinds expanding independent parts-market access. Signal to monitor: CPSC burn-hazard standard revisions that would obsolete existing housing inventories and trigger replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heating Element Production | Captive nickel-chromium alloy supply insulates margins from stainless steel feedstock volatility. |
| Direct-to-Consumer Subscription Launch | Descaling agent recurring revenue locks in urban millennial households across California and New York. |
| DOE Efficiency Certification Investment | Variable-wattage designs qualify for California Title 20 compliance premiums in renovation cycles. |
| Firmware Engineering Talent Acquisition | Precision-temperature control expertise addresses embedded systems capability gaps in traditional R&D teams. |
| Specialty Retail Partnership Expansion | Hands-on demonstration capacity at Sur La Table and Williams Sonoma anchors premium segment positioning. |
Research Methodology
Operator-level perspectives from appliance product managers, specialty coffee shop equipment buyers, big-box category merchants, contract manufacturing procurement leads, and CPSC regulatory affairs specialists anchored the qualitative base. Secondary validation drew from DOE appliance efficiency filings, California Energy Commission Title 20 compliance databases, CPSC recall and safety standard records, customs import manifests for electric kettle HS codes, and SEC 10-K disclosures from listed small-appliance manufacturers. Bottom-up channel volume estimates and top-down household penetration rates were triangulated to constrain forecast variance.
Scenario-bracketing around regulatory acceleration and supply disruption cases bounded projection uncertainty across the analysis window. Segmentation dimensions modeled included product type, material construction, end-user category, and distribution channel, with regional efficiency mandate intensity as an overlay variable. CAGRs were derived from fitted growth curves against historical replacement cycle data and renovation activity indices. Forecast inputs incorporated nickel-chromium alloy price trajectories and specialty coffee shop expansion rates in Pacific Northwest and Northeast corridors.
The forecast holds incumbent behavior within observed patterns; aggressive moves by countertop induction appliance specialists or precision-beverage equipment startups would shift outcomes beyond modeled ranges. Quarterly review of DOE efficiency standard comment periods, CPSC safety standard dockets, and nickel-chromium futures pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
China Induction Hobs Market
Appliances
Washing Appliances Market
Appliances
Asia Pacific Water Heater Market
Appliances
Saudi Arabia Electric Water Heater Market
Appliances
Kuwait Dishwasher Market
Appliances
Water Dispenser Market
Appliances
Saudi Arabia Microwave Ovens Market
Appliances
Mini Washing Machine Market
Appliances
Bahrain Dishwashers Market
Appliances
Household Beauty Appliances Market
Appliances
Bahrain Microwave Ovens Market
Appliances
India Washing Machine Market
Appliances
Germany Compact Dishwasher Market
Appliances
Minibar Refrigerators Market
Appliances
Lightwave Microwave Oven Market
Appliances
French Door Refrigerator Market