
 Small Electric Kettles Market | 2026-2036
Small Electric Kettles Market Size, Share, and Industry Trends Forecast 2026-2036
Small Electric Kettles Market Insights
Stainless steel is broadening its share in kettle chassis construction as borosilicate glass faces cost volatility and thermal-shock liability. Groupe SEB leverages European design heritage to sustain premium positioning across cordless and variable-temperature lines. Midea Group anchors high-volume production through integrated appliance manufacturing in Guangdong province. Xiaomi competes on connected-kettle ecosystems, extending its IoT platform into kitchen automation.
Small electric kettles are portable, self-contained vessels that convert electrical energy to thermal energy via integrated heating elements, typically rated between 1,000 and 3,000 watts, to boil water for beverage preparation or food reconstitution. Cordless kettles dominate residential volume, while variable-temperature kettles capture disproportionate margin pools among specialty coffee shops demanding precise extraction temperatures. Rapid boil technology lines gain share in corporate office settings where queue-time reduction shapes procurement criteria.
FDA food-contact material standards, EU Ecodesign Directive efficiency thresholds, and China's GB 4706 household appliance safety standards collectively determine product compliance costs and market access eligibility. Ecodesign requirements tighten standby-power limits, forcing redesigns of control boards and heating-element interfaces. Stakeholders must monitor how appliance-efficiency regulations in target jurisdictions interact with smart-feature power budgets to avoid stranded inventory in channels with shifting certification requirements.
Market Dynamics
EU Ecodesign Directive standby-power limits and China's GB 4706 safety standards are forcing simultaneous redesigns of control architectures and heating-element interfaces, compressing development cycles while elevating compliance costs across manufacturing footprints.
Growth Catalysts
- Specialty coffee infrastructure:Third-wave coffee shops in Melbourne, Portland, and Copenhagen demand variable-temperature precision for single-origin extraction protocols.
- REACH material restrictions:European chemical safety rules are accelerating stainless steel chassis substitution for borosilicate glass with thermal-shock liability.
- Boutique hotel amenity upgrades:Southeast Asian hospitality operators in Bangkok, Singapore, and Bali deploy cordless kettles as premium in-room differentiators.
Market Restraints
- Heating-element supply concentration:Ceramic and stainless steel element production clusters in Guangdong province create single-source vulnerability.
- Borosilicate glass cost volatility:Energy-intensive silica processing faces input price swings from natural gas and soda ash markets.
- F-Gas Regulation thermal limits:EU fluorinated gas rules constrain phase-change cooling options for high-wattage rapid-boil architectures.
Strategic Opportunities
- India hospitality penetration:Mid-tier hotel chains in Mumbai, Delhi, and Bengaluru remain undersupplied with branded in-room appliances.
- IoT platform convergence:Voice-assistant integration and energy-monitoring APIs merge kitchen automation with residential smart-home ecosystems.
- Corporate procurement centralization:Facility management aggregators in London, Frankfurt, and New York bundle electric kettles into workplace beverage service contracts.
Industry Challenges
- GB 4706.19 certification timelines:China's household appliance safety testing backlog extends product launch windows by four to six months.
- Control firmware integration complexity:Variable-temperature algorithms must interface with legacy building management systems in commercial installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Electric Kettles Market |
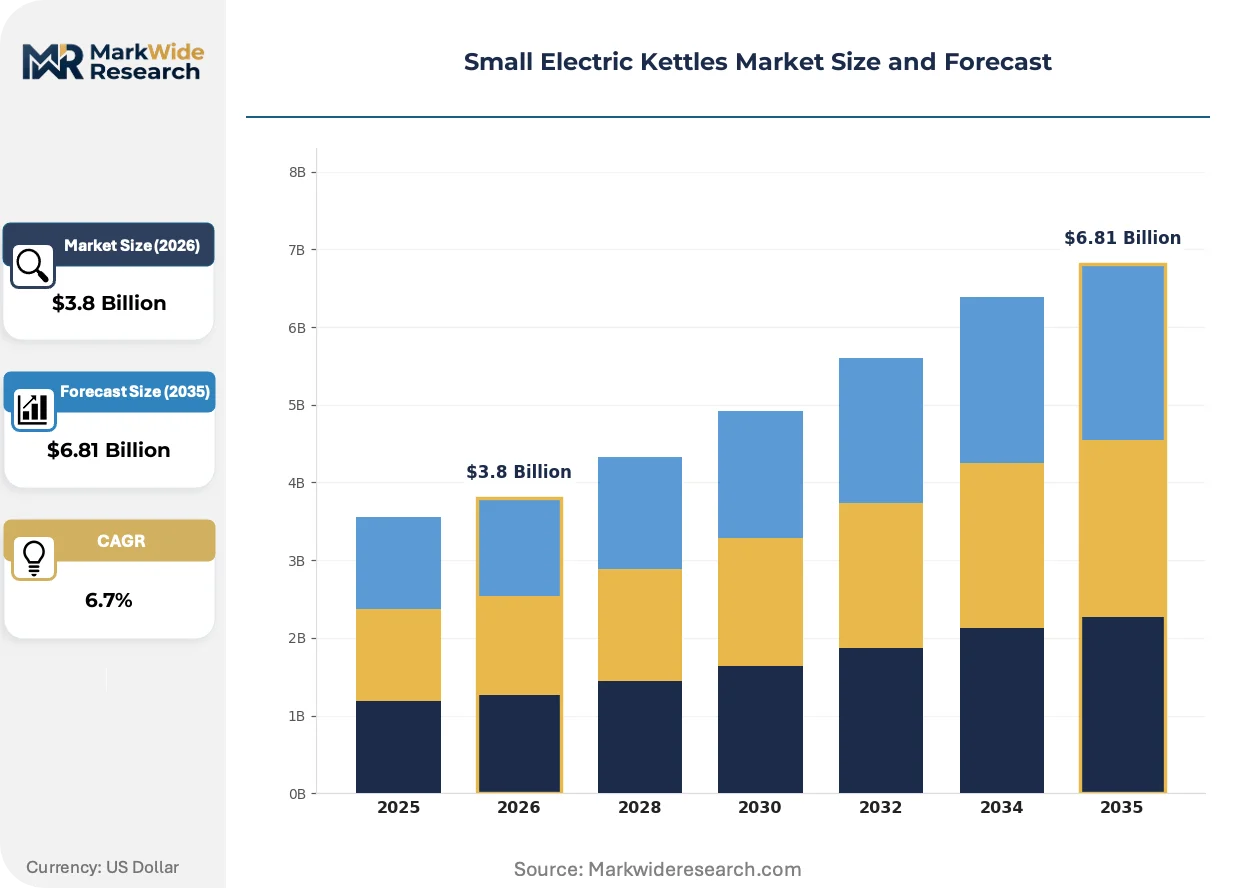
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cordless Kettles, Stovetop Electric Kettles, Travel Kettles, Variable Temperature Kettles Technology: Ceramic Heating, Glass Heating Element, Stainless Steel Heating, Rapid Boil Technology Application: Home Use, Office Use, Outdoor Activities, Boutique Hotels End User: Individual Consumers, Hospitality Sector, Corporate Offices, Specialty Coffee Shops |
| Companies Covered | Hamilton Beach Brands Holding Co., Groupe SEB, Koninklijke Philips N.V., Breville Pty Limited, Spectrum Brands Holdings, Cuisinart, De'Longhi Appliances S.r.l., Midea Group Co., Ltd., Xiaomi Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Electric Kettles Market Trends and Innovations
Heating architectures, material specifications, and distribution models are undergoing parallel transformation as efficiency mandates intersect with connected-appliance expectations and hospitality procurement consolidation.
Temperature-precision algorithms paired with induction-compatible base stations are automating extraction-parameter control for specialty beverage preparation. Roasters in Copenhagen, Melbourne, and Portland adopt these systems to eliminate manual temperature monitoring during cupping sessions and batch brewing. This automation is compressing training requirements for barista staff while standardizing output consistency across multi-location operations.
The EU F-Gas Regulation tightens restrictions on fluorinated greenhouse gases used in certain thermal management applications, forcing manufacturers to redesign high-performance heating elements around air-cooled or phase-change alternatives. Appliance engineers in Germany and Italy face extended validation cycles as they substitute thermal architectures. Premium rapid-boil product lines targeting commercial kitchens bear the steepest compliance cost increases.
Facility management aggregators now bundle electric kettles into comprehensive workplace beverage contracts, displacing direct procurement by individual corporate clients. London, Frankfurt, and New York office landlords increasingly specify appliance-inclusive service tiers to differentiate flex-space offerings. This channel shift concentrates buyer power among three to four national service integrators.
Small Electric Kettles Market Segmentation
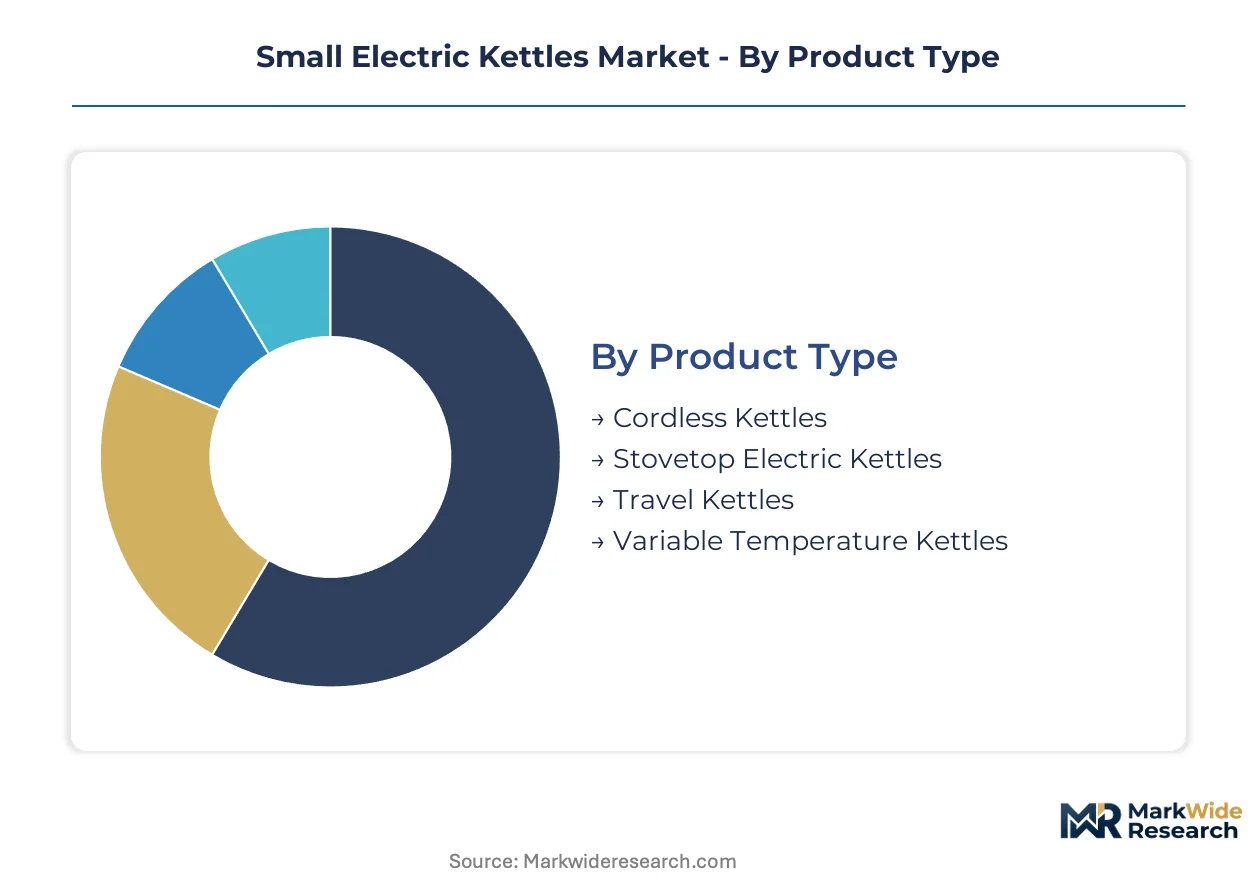
Segmentation in small electric kettles separates mass-market volume plays from precision-engineered premium tiers. Product architecture, heating technology, and procurement channel each create distinct margin pools and compliance burdens.
Product Type:
Cordless kettles dominate unit shipments while variable-temperature lines command disproportionate margin concentration.
- Cordless Kettles:Battery-free base-station designs with 360-degree rotation dominate residential kitchens across China and India. Hospitality procurement in Bangkok and Singapore standardizes on these for in-room deployment due to safety certification simplicity.
- Variable Temperature Kettles:PID-controlled heating algorithms enable single-degree precision for specialty coffee extraction. Third-wave roasters in Melbourne and Copenhagen specify these for cupping protocols, absorbing premium pricing for output consistency.
- Travel Kettles:Collapsible silicone or dual-voltage compact designs address airline weight limits and international voltage compatibility.
- Stovetop Electric Kettles:Hybrid designs retaining traditional whistling aesthetics with electric base compatibility serve retro-styled kitchen renovations.
Mature deployment sits with cordless kettles. Newer deployment is concentrated in variable-temperature lines.
Technology:
Heating-element material selection determines thermal efficiency, safety certification pathways, and supply chain vulnerability.
- Rapid Boil Technology:High-wattage architectures above 2,500 watts compress boil times for corporate office pantries where queue reduction drives procurement. EU F-Gas Regulation thermal constraints force German and Italian engineers toward air-cooled redesigns.
- Stainless Steel Heating:Immersed-element or base-plate designs using food-grade 304 or 316 alloys satisfy REACH material restrictions displacing borosilicate glass. Guangdong province concentration creates single-source exposure.
- Ceramic Heating:Alumina-based elements offer chemical inertness for tea purists concerned with metallic taste transfer.
- Glass Heating Element:Borosilicate tubes with printed conductive traces face thermal-shock liability and soda ash input volatility.
Stainless steel heating carries established certification pathways. Ceramic and glass alternatives face steepest regulatory headwinds.
Application:
Procurement authority varies sharply across settings, from individual discretionary purchase to centralized facility management contracts.
- Boutique Hotels:Southeast Asian operators in Bali and Phuket deploy branded cordless units as premium amenity differentiators, with procurement decisions centralized at regional hospitality group headquarters.
- Corporate Offices:London and New York facility management aggregators bundle kettles into comprehensive beverage service contracts, displacing direct enterprise purchasing.
- Home Use:Individual consumers prioritize countertop footprint and aesthetic coordination with kitchen cabinetry.
- Outdoor Activities:Camping and RV segments demand 12V automotive or portable power station compatibility.
Home use retains fragmented purchasing patterns. Boutique hotels and corporate offices are concentrating buyer power fastest.
End User:
Technical sophistication and price elasticity diverge sharply between consumer and commercial segments.
- Specialty Coffee Shops:Copenhagen and Portland roasters demand extraction-parameter precision, accepting hardware costs that amortize across high-margin beverage sales. Temperature algorithm integration with legacy POS systems creates implementation friction.
- Hospitality Sector:Mid-tier chains in Mumbai and Delhi remain undersupplied with branded in-room appliances, presenting white-space opportunity.
- Individual Consumers:Mass-market purchasing through e-commerce platforms prioritizes review velocity and price positioning.
- Corporate Offices:Procurement departments specify warranty terms and energy efficiency metrics over feature depth.
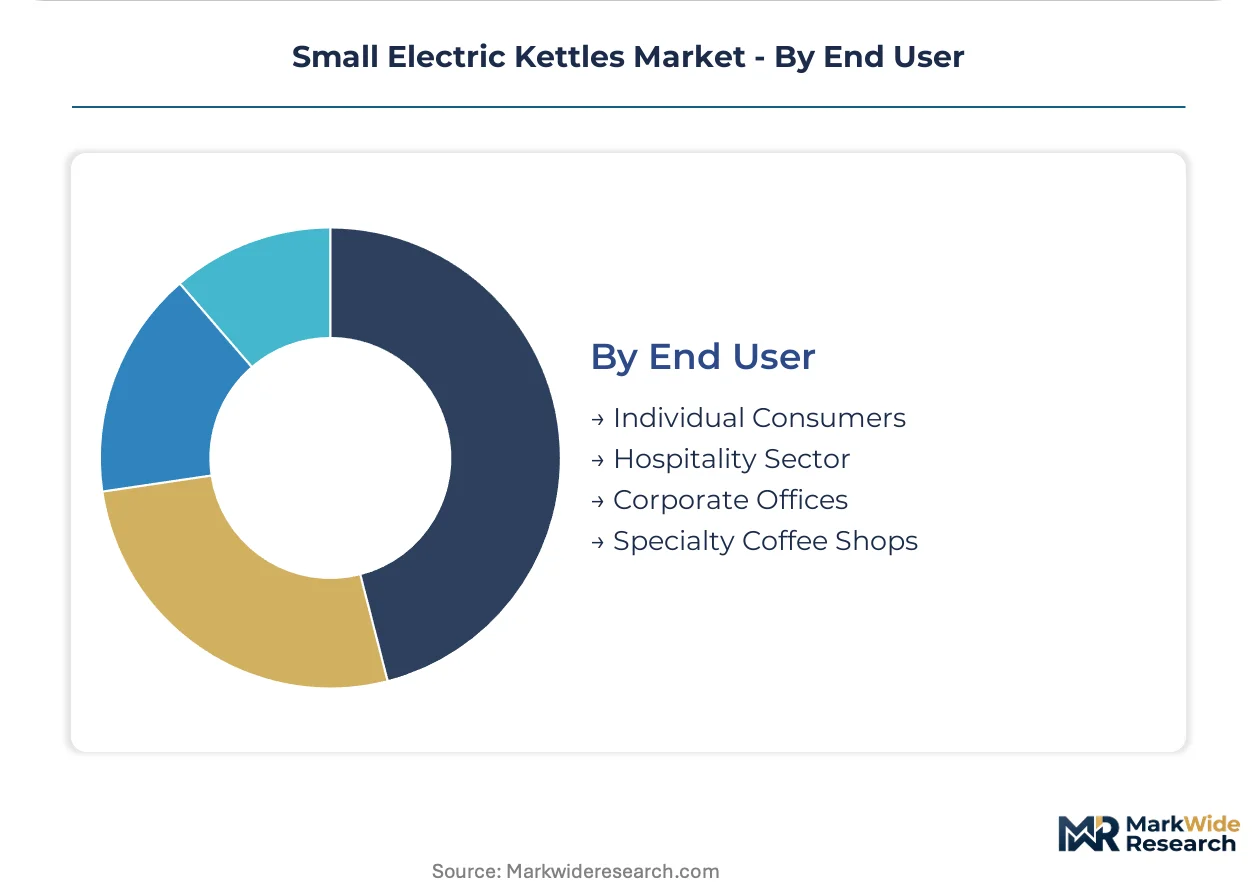
Individual consumers represent established volume. Specialty coffee shops and hospitality sector deployment are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs the highest unit volumes through mass-market residential demand and integrated manufacturing clusters. Boutique hotel procurement in Southeast Asia and specialty coffee infrastructure in Western markets create secondary demand poles with distinct margin profiles.
China
Guangdong province hosts vertically integrated appliance manufacturing where Midea Group and Xiaomi anchor production. GB 4706 household appliance safety standards and MIIT energy-efficiency mandates compress development cycles for export-bound product lines. The Pearl River Delta concentration creates single-source exposure for heating-element supply chains serving domestic and international markets.
United States
Specialty coffee shops in Portland and Seattle drive variable-temperature precision demand for third-wave extraction protocols. FDA food-contact material standards govern stainless steel and borosilicate glass specifications for import clearance. Facility management aggregators in New York bundle electric kettles into workplace beverage service contracts, concentrating procurement authority among national service integrators.
Germany
EU Ecodesign Directive standby-power limits and F-Gas Regulation thermal constraints force redesigns of rapid-boil architectures. Engineering teams in Stuttgart and Munich validate air-cooled heating-element alternatives for commercial kitchen applications. REACH material restrictions accelerate stainless steel substitution for borosilicate glass with thermal-shock liability.
India
Mid-tier hotel chains in Mumbai, Delhi, and Bengaluru remain undersupplied with branded in-room appliances, presenting white-space expansion opportunity. BIS certification requirements and FSSAI food-contact standards determine product compliance costs for import and domestic manufacture. The Maharashtra-Gujarat industrial corridor hosts emerging contract manufacturing capacity for hospitality-specified cordless units.
United Kingdom
Corporate office landlords in London specify appliance-inclusive service tiers to differentiate flex-space offerings. Ecodesign efficiency thresholds and CE marking requirements shape procurement specifications for workplace beverage infrastructure. The Southeast England logistics cluster channels distribution through facility management aggregators serving Frankfurt and Amsterdam satellite offices.
Small Electric Kettles Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium-tier positioning commanding disproportionate margin concentration. The vendor base organizes around three strategic archetypes: European heritage brands leveraging design differentiation, Chinese scale players optimizing integrated manufacturing costs, and smart-appliance specialists extending IoT platform ecosystems. Competitive moves center on hospitality procurement consolidation and voice-assistant integration partnerships rather than direct price confrontation.
Among heritage-positioned European specialists, Groupe SEB and De'Longhi Appliances S.r.l. occupy positions emphasizing cordless and variable-temperature lines. Midea Group exemplifies the scale-driven archetype through Guangdong-based integrated manufacturing. Xiaomi represents smart-appliance convergence, extending its IoT platform architecture into kitchen automation ecosystems. These three anchors illustrate how geographic origin and corporate structure map to distinct competitive vectors without requiring identical strategic postures.
| Leading Market Players |
|---|
| Hamilton Beach Brands Holding Co. |
| Groupe SEB |
| Koninklijke Philips N.V. |
| Breville Pty Limited |
| Spectrum Brands Holdings |
| Cuisinart |
| De'Longhi Appliances S.r.l. |
| Midea Group Co., Ltd. |
| Xiaomi Corp. |
| Others |
Pricing and Supply Chain Analysis
Soda ash futures volatility cascades through borosilicate glass supply chains, compressing margins for transparent-kettle specialists while stainless steel alternatives capture pricing power through REACH-compliant certification premiums. Procurement officers at Southeast Asian hospitality groups and European facility management aggregators now segment supplier tiers by material compliance grade rather than brand heritage alone.
Pricing Analysis
Volume concentration in cordless residential kettles diverges from margin capture in variable-temperature commercial lines. Three-tier pricing structure across precision-engineered, standard-certified, and economy-unbranded levels reflects GB 4706 testing backlog premiums and IoT integration costs. Pricing pressure stems from Guangdong heating-element supply concentration as buyers consolidate procurement authority. Corporate facility managers exhibit highest price sensitivity, while Copenhagen specialty roasters absorb premium hardware costs for extraction consistency.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Los Angeles anchor hub-and-spoke fulfillment for hospitality and corporate channel replenishment. Manufacturing gravity centers on Guangdong province, with secondary stainless steel forming capacity in Maharashtra-Gujarat and design engineering clusters in Stuttgart and Milan. Raw material flows draw from nickel ore processing in Indonesia, silica mining in China, and copper conductor drawing in Germany. Single-source vulnerability concentrates in ceramic heating-element substrates. Distribution runs through facility management aggregators consolidating buyer power across London, Frankfurt, and New York metro corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stainless steel heating architectures are displacing borosilicate glass and ceramic alternatives as EU REACH restrictions and thermal-shock liability reshape material specifications. Incumbents and challengers must reposition around compliance-grade supply security and connected-appliance platform integration.
For Market Incumbents: Anticipate margin compression in transparent-kettle portfolios as soda ash volatility and REACH enforcement accelerate stainless steel substitution. Secure captive supply of 304 and 316 alloy forming capacity in Guangdong or Maharashtra-Gujarat to defend cost position. Invest in GB 4706.19 pre-certification testing infrastructure to compress launch windows against backlog-constrained competitors. For New Entrants and Emerging Players: Voice-assistant integration modules offer wedge positioning against legacy control-board architectures. Target mid-tier hospitality chains in Mumbai, Delhi, and Bengaluru with white-label cordless units certified to BIS and FSSAI standards. Pursue direct procurement relationships with regional hospitality group headquarters bypassing established distributor markups. For Investors and Strategic Acquirers: Distressed-cycle entries favor contract manufacturers with GB 4706 pre-certified product platforms and existing hospitality channel relationships in Southeast Asia. Long-term viability hinges on backward integration into stainless steel forming and IoT firmware development capabilities. Monitor EU F-Gas Regulation enforcement intensity as inflection signal for rapid-boil technology write-downs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Steel Forming | Captive 304/316 alloy supply secures REACH compliance and margin protection against soda ash volatility. |
| IoT Platform Certification Investment | MIIT cybersecurity standards and GDPR data governance enable voice-assistant integration for Xiaomi-scale ecosystems. |
| Hospitality Procurement Direct Relationships | Bypassing facility management aggregators recaptures margin from London and New York channel concentration. |
| GB 4706.19 Pre-Certification Infrastructure | Compressed testing timelines defend launch velocity against China's household appliance safety backlog. |
| Variable-Temperature Algorithm Development | PID precision for Copenhagen and Portland specialty roasters commands premium positioning in commercial segments. |
Research Methodology
Independent corroboration across procurement directors at Southeast Asian hospitality groups, appliance manufacturing engineers in Guangdong, and specialty coffee roasters in Melbourne underwrites the qualitative findings. Primary interviews with facility management aggregators in London and New York, brand managers at European heritage manufacturers, and regulatory compliance officers at BIS and MIIT anchor supply-side and demand-side perspectives. Secondary validation draws from customs records for heating-element trade flows, SEC filings of listed appliance manufacturers, EU Ecodesign Directive implementation reports, and GB standards documentation. Bottom-up channel volume estimates triangulate against top-down macro appliance consumption benchmarks.
Rate-of-change decomposition separates volume growth in cordless residential units from value expansion in variable-temperature commercial lines across the projection horizon. Segmentation modeling incorporates product architecture, heating technology material, application setting, and end-user sophistication dimensions. CAGRs derive from fitted growth curves applied to channel shipment data and hospitality procurement contract values. Forecast inputs include GB 4706 certification timeline assumptions, REACH enforcement intensity scenarios, and IoT platform adoption curves in residential smart-home ecosystems.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EU F-Gas Regulation enforcement or Guangdong supply chain disruption scenarios. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Germany Compact Dishwasher Market
Appliances
Cooker Hoods Market
Appliances
Asia-Pacific Microwave Oven Market
Appliances
Japan Massage Equipment Market
Appliances
United Kingdom Tumble Dryers Market
Appliances
Smart Washing Machine Market
Appliances
Refrigerated Cabinet Market
Appliances
Shared Shoe Washing Machine Market
Appliances
Europe Garment Steamers Market
Appliances
France Household Side by Side Refrigerator Market
Appliances
Oman Dishwashers Market
Appliances
Electrical Appliances Plastics Market
Appliances
Egypt Microwave Ovens Market
Appliances
UAE Microwave Ovens Market
Appliances
Laundry Kiosk Market
Appliances
Mini Washing Machine Market