
 Electric Rice Cooker Market | 2026-2036
Electric Rice Cooker Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Rice Cooker Market Intelligence
Online retail is tilting toward multi-functional and smart-enabled electric rice cookers as consumers research specifications before purchase. Panasonic leverages its microcomputer-controlled technology leadership to sustain premium positioning in Japanese and North American markets. Midea Group anchors mass-market volume through manufacturing scale and direct-to-platform distribution across Southeast Asia. Tiger Corporation differentiates through induction heating specialization, occupying the high-performance tier where consumers prioritize texture consistency.
An electric rice cooker is an automated kitchen appliance that uses electric heating elements to boil, steam, and maintain rice at serving temperature through thermostatic or microprocessor-based control systems, typically operating between 500-1500 watts with inner pots of aluminum alloy or ceramic-coated stainless steel. The device eliminates manual monitoring while delivering uniform moisture distribution for commercial food service and household meal preparation. Multi-functional cookers now lead product type expansion by integrating steaming, slow-cooking, and yogurt-making capabilities that command higher margins than basic units. Fuzzy logic technology dominates the premium tier where algorithmic temperature adjustment justifies price premiums, while smart technology represents the fastest-growing segment as WiFi-enabled models sync with meal-planning applications.
Japan's METI enforces stringent energy efficiency standards that compel manufacturers to redesign heating coils and insulation layers for domestic market access. China's SAMR and GB standards mandate safety certifications for pressure-cooking functions, creating compliance barriers for unverified imports. The US FDA regulates food-contact surfaces under 21 CFR 177.1520, restricting certain non-stick coating chemistries in consumer appliances. Stakeholders must monitor how India's BIS certification expansion into smart kitchen appliances will reshape supplier qualification requirements for brands targeting that market.
Market Dynamics
China's GB standards for energy efficiency and smart appliance interoperability are forcing manufacturers to redesign heating systems and connectivity modules, compressing development cycles while elevating technical barriers to market entry.
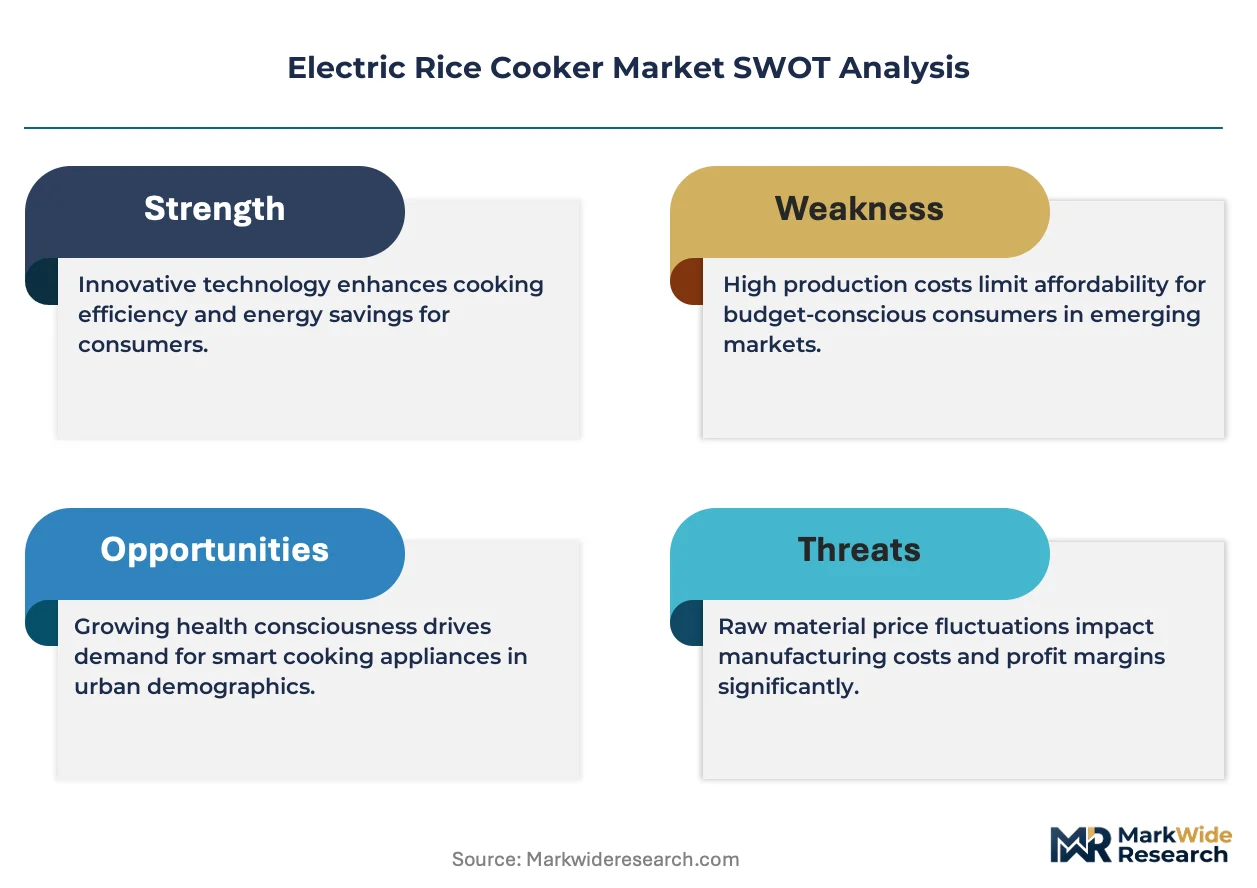
Growth Catalysts
- Cloud kitchen proliferation:India's food service startups are driving replacement cycles and first-time purchases as centralized meal prep demands consistent rice texture at volume.
- Fuzzy logic algorithm penetration:Microprocessor-controlled temperature adjustment is justifying price premiums in Japanese and North American premium tiers where texture consistency commands buyer loyalty.
- India's BIS certification expansion:The regulator's push into smart kitchen appliances is creating supplier qualification requirements that favor established brands with compliance infrastructure.
Market Restraints
- Aluminum alloy cost volatility:Inner pot material price swings squeeze margin structures for mass-market manufacturers dependent on thin-gauge metal forming.
- Induction heating component concentration:Specialized coil suppliers in Japan and South Korea create supply bottleneck risks for brands outside East Asian manufacturing networks.
- Pressure-cooking safety certification friction:China's SAMR mandates create compliance barriers for unverified imports, delaying market access for new entrants.
Strategic Opportunities
- Southeast Asian platform commerce:Direct-to-platform distribution channels are opening volume pathways for manufacturers with localized logistics partnerships.
- WiFi-enabled meal-planning convergence:Smart technology integration with recipe applications represents the fastest-growing segment for urban middle-class households.
- Japan's METI efficiency mandates:Stringent energy standards are compelling heating coil and insulation layer redesigns that create first-mover advantages for compliant suppliers.
Industry Challenges
- Embedded systems engineering scarcity:Firmware development for microcomputer-controlled units outpaces available talent pools in cost-competitive manufacturing geographies.
- Multi-functional certification complexity:Integrated steaming, slow-cooking, and yogurt-making capabilities trigger overlapping safety standards that extend validation timelines.
- Legacy coating chemistry transitions:US FDA 21 CFR 177.1520 restrictions on certain non-stick surfaces force reformulation investments without immediate price recovery mechanisms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Rice Cooker Market |
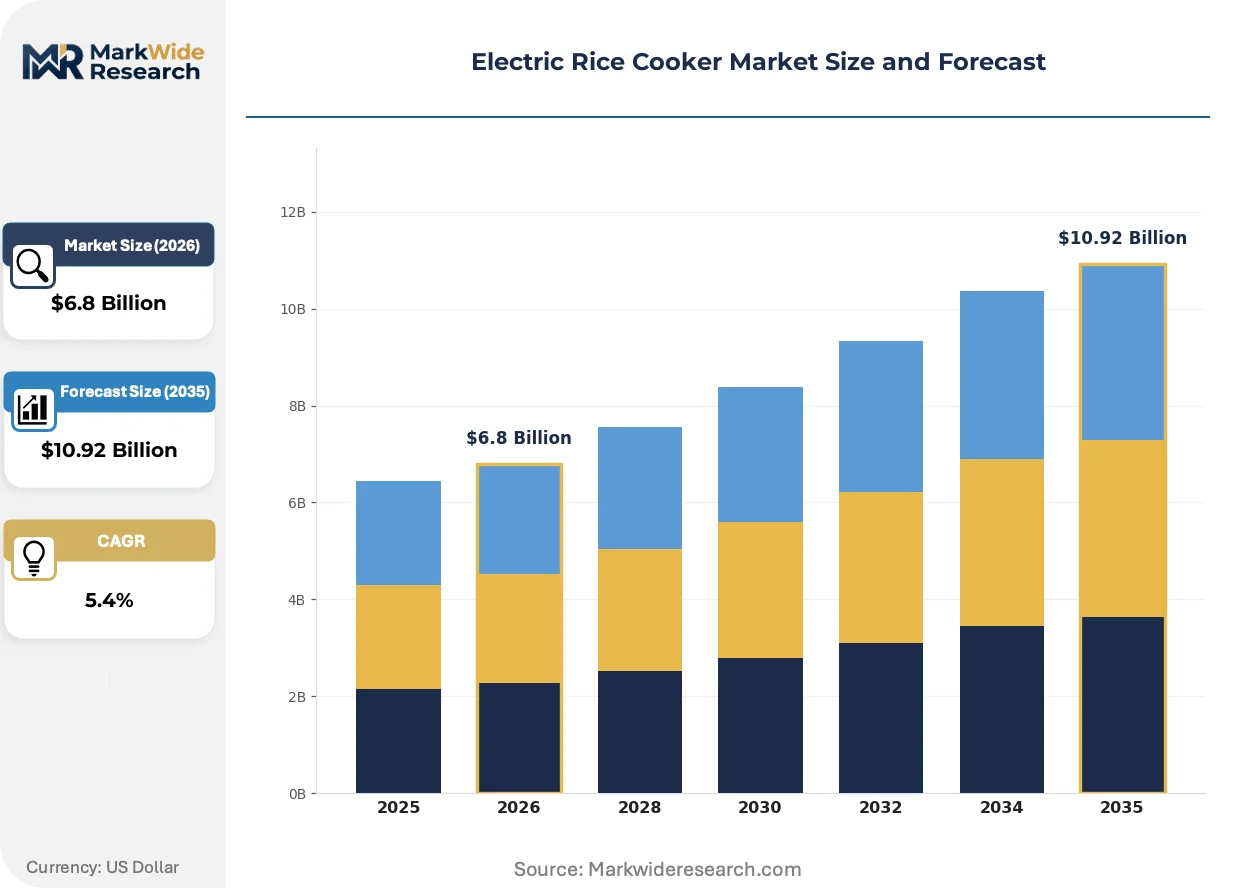
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Rice Cooker, Multi-Functional Cooker, Induction Rice Cooker, Pressure Cooker Technology: Fuzzy Logic, Microcomputer-Controlled, Basic Technology, Smart Technology End User: Household, Commercial, Institutional, Food Service Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Aroma Houseware Company, Toshiba Corporation, Panasonic Inc., Electrolux, Midea Group, Zojirushi America Corporation, Koninklijke Philips, TTK Prestige Limited, Tiger Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Rice Cooker Market Strategic Shifts & Innovations
Product architecture is compressing around modular heating platforms that support function expansion without hardware replacement, while regulatory pressure on energy consumption and material safety accelerates design iteration cycles.
Induction heating technology is collapsing the performance gap between residential and commercial rice preparation by delivering precise temperature gradients previously restricted to food service equipment. Japanese and South Korean appliance buyers are adopting these systems at accelerating rates as texture consistency becomes a visible purchase criterion. The technology is collapsing premium-tier price elasticity by embedding professional-grade outcomes into countertop formats.
China's dual carbon goals are reshaping appliance efficiency mandates through MIIT-administered standards that target standby power and active heating consumption simultaneously. Manufacturers serving the domestic market must now submit products for GB certification cycles that verify coil design and thermal insulation performance. The policy is concentrating supplier relationships around component vendors with pre-certified subassembly portfolios.
Urban middle-class households in India are unbundling purchase decisions from traditional retail relationships, completing specification research through platform commerce before committing to multi-functional units. Cloud kitchen procurement teams are compressing vendor qualification cycles by demanding WiFi-enabled inventory management integration. The shift is most visible in Mumbai and Bangalore where replacement purchases now outpace first-time acquisitions among established appliance owners.
Electric Rice Cooker Market Segmentation
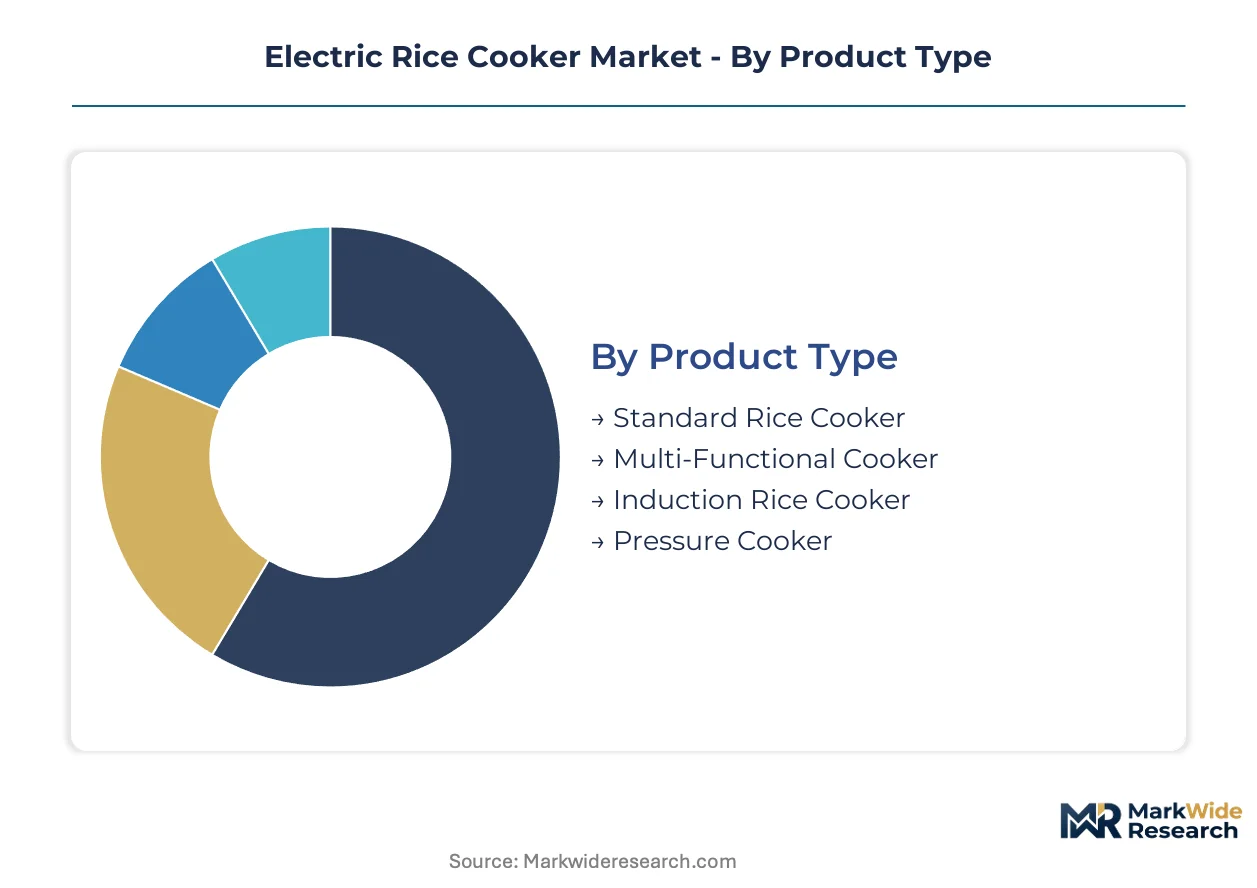
Segmentation in the electric rice cooker market reveals how technology tiers, user contexts, and purchase channels create distinct margin profiles. Manufacturers align R&D investment and distribution strategy against these divisions to capture value without cross-segment dilution.
Product Type:
Cost tier stratification determines material selection, heating system complexity, and certification burden across the four product architectures.
- Standard Rice Cooker:Single-function units with thermostatic control and aluminum alloy inner pots dominate rural India and Southeast Asian mass markets. Procurement teams at Indian cloud kitchen startups specify these for high-volume, low-complexity rice preparation where capital constraints outweigh texture precision requirements.
- Multi-Functional Cooker:Integrated steaming, slow-cooking, and yogurt-making capabilities command higher retail prices through component count expansion. Urban middle-class households in Mumbai and Bangalore research specifications online before purchasing these units for countertop consolidation.
- Induction Rice Cooker:Precise temperature gradient control via magnetic coil heating targets texture-conscious buyers in Japan and South Korea.
- Pressure Cooker:Sealed-vessel designs with safety interlocks face China's SAMR certification mandates that extend validation timelines for unverified imports.
Standard rice cookers command the established base. The steepest expansion runs through multi-functional units.
Technology:
Application sophistication separates algorithmic temperature control from fixed-cycle operation, with connectivity emerging as a new performance layer.
- Fuzzy Logic:Algorithmic microprocessors adjust heating intensity based on moisture sensors and rice variety detection. Japanese consumers accept price premiums for these systems where texture consistency drives repeat purchase loyalty.
- Smart Technology:WiFi-enabled units sync with meal-planning applications and support remote activation. Urban households in India's tier-1 cities adopt these fastest as platform commerce exposes specification comparisons before purchase.
- Microcomputer-Controlled:Pre-programmed cycle selection without adaptive learning occupies mid-tier positioning in North American retail.
- Basic Technology:Simple on-off thermostatic operation survives only at economy price points in price-sensitive geographies.
Fuzzy logic systems command the established base. The steepest expansion runs through smart technology integration.
End User:
Volume scale and usage intensity differentiate procurement criteria across domestic and professional contexts.
- Household:Individual and family units prioritize countertop footprint, aesthetic integration, and multi-functionality for daily meal preparation. India's urban middle-class replacement cycles accelerate as cloud kitchen visibility raises quality expectations for home-cooked rice.
- Food Service:Centralized meal prep operations demand consistent texture at volume with minimal labor intervention. Procurement teams compress vendor qualification cycles by requiring WiFi-enabled inventory tracking integration.
- Commercial:Non-food-service businesses with employee dining facilities specify durability-focused units with extended warranty terms.
- Institutional:Schools, hospitals, and military facilities prioritize safety certification depth and bulk procurement pricing.
Household end users command the established base. The steepest expansion runs through food service procurement.
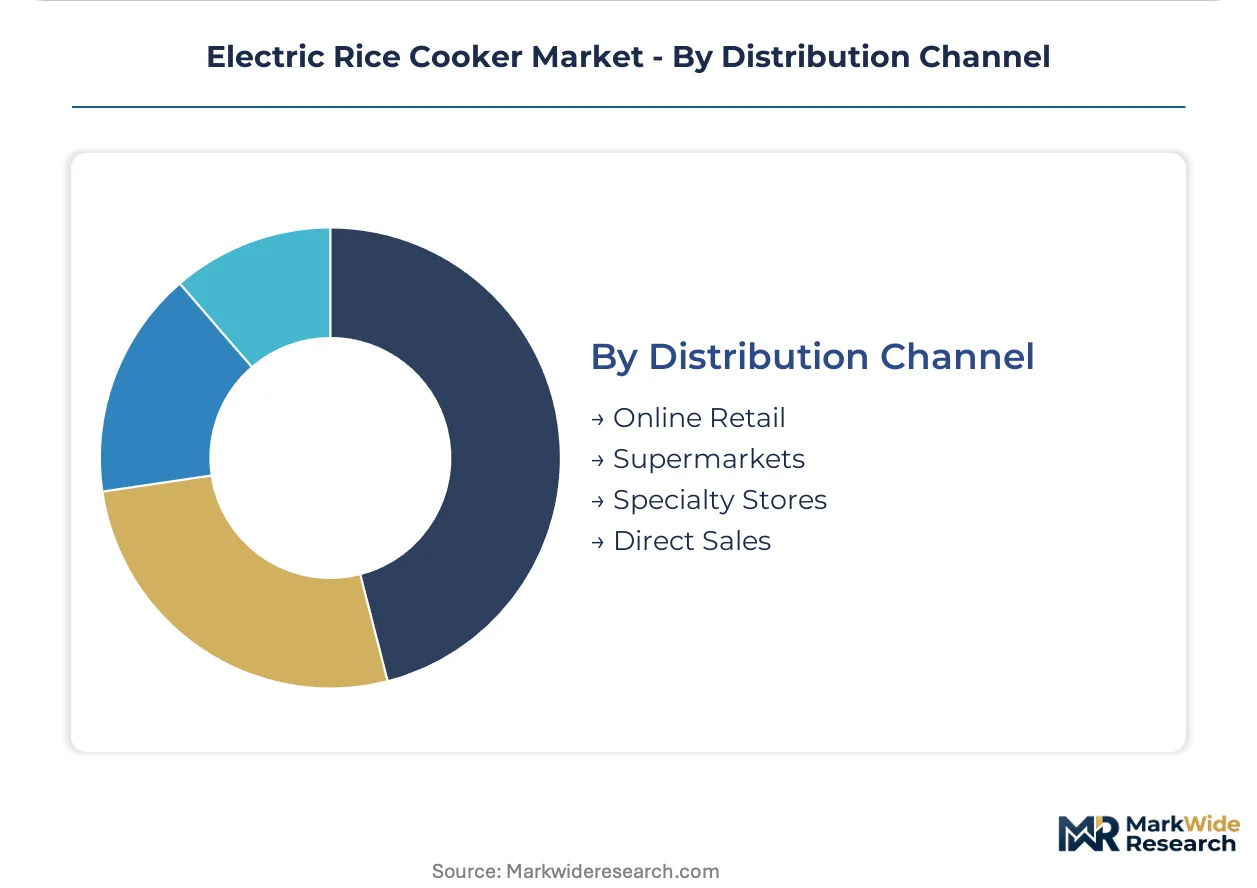
Distribution Channel:
Customer type and purchase journey stage determine channel economics, with specification research preceding commitment in premium tiers.
- Online Retail:Platform commerce enables specification comparison and review aggregation before purchase. Midea Group anchors volume through direct-to-platform distribution across Southeast Asia, bypassing traditional retail margin extraction.
- Supermarkets:Impulse and replacement purchases of standard units persist in Japan and South Korea where brand recognition reduces research requirements.
- Specialty Stores:Induction heating and fuzzy logic demonstrations require physical texture sampling that digital channels cannot replicate.
- Direct Sales:Institutional and commercial procurement teams negotiate volume contracts with manufacturers holding BIS certification infrastructure.
Supermarkets command the established base. The steepest expansion runs through online retail platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium induction heating units in Japan command price multiples exceeding mass-market products in India by substantial margins. This asymmetry reflects divergent technical requirements, certification burdens, and consumer willingness to pay for texture precision. Regional differentiation in energy standards and distribution infrastructure perpetuates these pricing gaps across the analysis window.
China
Urban middle-class households in Shanghai and Beijing are accelerating replacement cycles toward multi-functional smart-enabled units. MIIT-administered GB standards for energy efficiency and smart appliance interoperability compel manufacturers to redesign heating coils and connectivity modules. The Yangtze River Delta manufacturing cluster concentrates component suppliers with pre-certified subassembly portfolios serving domestic brands.
Japan
Texture-conscious consumers in Tokyo and Osaka sustain demand for fuzzy logic and induction heating systems at premium price points. METI enforces stringent energy efficiency standards that mandate insulation layer and coil redesigns for domestic market access. The Kansai industrial corridor hosts specialized magnetic coil suppliers that create supply bottlenecks for brands outside established East Asian networks.
India
Cloud kitchen startups in Mumbai and Bangalore are driving first-time purchases and replacement cycles as centralized meal prep demands consistent rice texture at volume. BIS certification expansion into smart kitchen appliances creates supplier qualification requirements favoring established brands with compliance infrastructure. The Maharashtra-Gujarat manufacturing belt anchors mass-market production for domestic consumption and regional export.
United States
North American households research specifications online before committing to microcomputer-controlled units with pre-programmed cycle selection. FDA regulation of food-contact surfaces under 21 CFR 177.1520 restricts certain non-stick coating chemistries, forcing reformulation investments. The Pacific Northwest and Northeast Corridor concentrate specialty retail channels where physical texture sampling supports premium-tier sales.
South Korea
Urban consumers in Seoul and Busan adopt induction heating technology at accelerating rates as texture consistency becomes a visible purchase criterion. MFDS-equivalent safety mandates for pressure-cooking functions extend validation timelines for imported products. The Busan-Ulsan industrial zone concentrates component fabrication capacity serving domestic appliance brands and regional OEM supply.
Electric Rice Cooker Market Key Industry Players
Scale-driven manufacturers and technology specialists split the market along price-performance vectors. The vendor base organizes into three strategic archetypes: diversified appliance conglomerates with platform commerce dominance, precision heating specialists commanding premium tiers, and regional fabricators serving price-sensitive geographies. Competitive moves concentrate on direct-to-platform distribution partnerships and firmware development capabilities for microcomputer-controlled units.
Within the diversified conglomerate tier, Midea Group and Panasonic exemplify scale-driven and technology-led positioning respectively. Midea anchors mass-market volume through manufacturing scale and Southeast Asian platform distribution. Panasonic leverages microcomputer-controlled technology leadership to sustain premium positioning in Japanese and North American markets. Tiger Corporation occupies the high-performance specialist position where induction heating expertise justifies price premiums for texture-conscious buyers.
| Leading Market Players |
|---|
| Aroma Houseware Company |
| Toshiba Corporation |
| Panasonic Inc. |
| Electrolux |
| Midea Group |
| Zojirushi America Corporation |
| Koninklijke Philips |
| TTK Prestige Limited |
| Tiger Corporation |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta freight corridor's container cost dynamics compress margin structures for mass-market manufacturers while amplifying price differentiation between premium induction heating units and basic thermostatic models. Supply concentration in East Asian magnetic coil fabrication feeds directly into downstream pricing power, with Japanese and South Korean component scarcity sustaining premium tiers even as aluminum alloy volatility squeezes standard-unit economics.
Pricing Analysis
The customization-premium spread separates fuzzy logic and induction heating configurations from basic thermostatic units by substantial multiples, with algorithmic temperature control and magnetic coil systems commanding buyer loyalty in Tokyo and Osaka. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, heating system complexity, and after-sales service bundling. Cost compression in mass-market tiers intensifies because aluminum alloy inner pot prices fluctuate without corresponding price recovery mechanisms. Cloud kitchen procurement teams in India exhibit highest price sensitivity, while texture-conscious Japanese households accept premiums for METI-compliant efficiency ratings.
Supply Chain Analysis
Supplier-financing facilities with extended payment terms anchor procurement relationships for Southeast Asian platform distributors serving Midea Group's direct-to-platform volume strategy. Component sourcing concentrates in China, Japan, and South Korea, with magnetic coil fabrication tethered to Kansai and Busan-Ulsan industrial zones. Raw material dependencies span aluminum alloy sheet, ceramic coating formulations, and microprocessor chipsets. Single-source vulnerability in specialized induction heating coil suppliers creates bottleneck exposure for brands outside established East Asian manufacturing networks. Distribution runs through platform commerce channels accelerating fastest in India's tier-1 cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric rice cooker market functions as a service-attach opportunity where firmware update subscriptions and extended warranty programs expand faster than hardware replacement cycles, particularly for WiFi-enabled smart technology tiers.
For Market Incumbents: Build certification infrastructure moats by securing pre-certified subassembly portfolios under China's GB standards and India's BIS expansion before compliance barriers harden. Anchor mass-market volume through captive supply of aluminum alloy inner pots to offset material volatility. Defend against emerging platform-native brands by controlling direct-to-platform distribution partnerships across Southeast Asia.
For New Entrants and Emerging Players: Establish a beachhead in India's cloud kitchen procurement segment where vendor qualification cycles compress and WiFi-enabled inventory management integration remains undersupplied. Target food service procurement teams in Mumbai and Bangalore demanding consistent texture at volume with minimal labor intervention. Pursue white-label manufacturing partnerships with Yangtze River Delta fabricators to bypass upfront certification investments.
For Investors and Strategic Acquirers: Component suppliers with pre-certified magnetic coil and microprocessor subassembly portfolios represent the most defensible acquisition archetype as GB and METI efficiency mandates concentrate supplier relationships. Long-term viability hinges on firmware development capabilities outpacing talent scarcity in cost-competitive geographies. Watch for BIS certification expansion completion as inflection indicator for supplier qualification consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Development Investment | Microcomputer-controlled algorithm development outpaces available embedded systems engineering talent pools. |
| Direct-to-Platform Distribution | Midea Group anchors Southeast Asian volume through localized logistics partnerships bypassing retail margin extraction. |
| Certification Infrastructure Buildout | Pre-certified subassembly portfolios under SAMR and BIS mandates create first-mover compliance advantages. |
| Induction Heating Specialization | Tiger Corporation occupies texture-conscious premium tiers where magnetic coil precision justifies price multiples. |
| Smart Technology Integration | WiFi-enabled meal-planning convergence represents fastest-expanding segment for urban middle-class households. |
Research Approach
Initial hypotheses were tested against primary input from appliance brand product managers, cloud kitchen procurement directors, platform commerce category leads, and component supplier technical directors and refined through secondary validation. Primary fieldwork combined structured interviews with manufacturing executives at Yangtze River Delta facilities and procurement officers at Mumbai-based food service startups. Secondary sources encompassed MIIT-administered GB standard filings, BIS certification registries, FDA 21 CFR 177.1520 guidance documents, and METI efficiency mandate disclosures. Bottom-up unit shipment estimates triangulated against top-down consumer appliance expenditure data.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning product architecture, heating technology tier, end-use context, and distribution channel type. CAGRs were derived from regression analysis of replacement cycle acceleration patterns and first-time purchase penetration curves. Industry-specific forecast inputs incorporated cloud kitchen startup formation rates in India's tier-1 cities and fuzzy logic algorithm adoption thresholds in Japanese premium retail.
Stress conditions across aluminum alloy price volatility, induction heating component supply disruption, and BIS certification timeline extension were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding urban middle-class income trajectory and platform commerce penetration rates. Macroeconomic contraction, regulatory acceleration beyond modeled timelines, or breakthrough solid-state heating technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Refrigerator Door Seal Market
Appliances
Asia-Pacific Washing Machine Market
Appliances
Germany Consumer Appliances Market
Appliances
Washing Appliances Market
Appliances
Small Electric Kettles Market
Appliances
United States Microwave Oven Market
Appliances
Electric Fan Market
Appliances
APAC White Goods Market
Appliances
Portable Dishwasher Market
Appliances
Saudi Arabia Electric Water Heater Market
Appliances
United States Electronics and Appliance Stores Market
Appliances
US Washing Machine Parts Market
Appliances
United Kingdom Handheld Vacuum Cleaners Market
Appliances
United States Commercial Laundry Appliances Market
Appliances
Smart Ceiling Fan Market
Appliances
Residential Space Heater Market