
 North America Personal Care Appliances Market | 2026-2036
North America Personal Care Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
North America Personal Care Appliances Market Analytics
Ceramic coatings are decoupling thermal performance from metal-dependent manufacturing costs in hair styling tools. Koninklijke Philips N.V. anchors its North American position through professional-grade temperature control systems. Helen of Troy leverages its portfolio breadth to dominate mid-market shelf space across mass retail. Wahl Clipper Corporation specializes in corded motor durability for barbershop segments where runtime reliability commands loyalty.
Personal care appliances comprise electrically powered devices designed for individual grooming, skin treatment, and hair management, typically operating at voltages between 110-120V with wattage ranging from 800W to 2400W depending on thermal output requirements; these products serve consumer and professional end users seeking repeatable cosmetic outcomes without salon dependency. Hair dryers occupy the largest volume position across the product type dimension, though epilators generate disproportionate margin contribution from replacement cartridge streams. The end user segment shows women driving absolute unit demand while men's electric shaver replacement cycles sustain steadier revenue predictability. Online retail channels are capturing share from department stores as video demonstration content reduces purchase hesitation for premium-tier items.
The U.S. FDA oversees laser and intense pulse light devices under medical device regulations, while Health Canada and Mexico's national health regulator apply parallel safety certifications that fragment compliance burdens for cross-border suppliers. California's Proposition 65 chemical disclosure requirements add labeling complexity that filters out smaller import competitors. Stakeholders must track how state-level energy efficiency mandates in Ontario and California reshape motor specifications before federal standards converge.
Market Dynamics
Professional salon operators are compressing appliance refresh cycles as consumer expectations for at-home styling performance converge with commercial-grade output standards. The U.S. FDA's tightening device classification rules for laser-based hair removal tools are forcing manufacturers to revalidate quality thresholds across the entire trade channel.
Growth Catalysts
- California's beauty-tech startup corridor:Direct-to-consumer brands use the state's dense investor and talent networks to test premium formats before committing to national retail distribution. This concentration accelerates product-market fit validation.
- Professional salon equipment refresh cycles:Barbershops and hair studios are replacing thermal tools every 18-24 months versus historical 36-month intervals, pulling inventory through wholesale channels.
- Energy efficiency mandates in Ontario:The province's motor performance standards are pushing manufacturers toward brushless DC architectures that reduce standby power draw while maintaining thermal output.
Market Restraints
- Neodymium magnet supply concentration:High-performance hair dryer motors depend on rare earth inputs where processing capacity clusters in a single Asian supply jurisdiction, exposing North American assemblers to price volatility and quota risk.
- California Proposition 65 labeling burden:Chemical disclosure requirements for ceramic coating precursors and polymer components add compliance overhead that filters out smaller import competitors lacking legal infrastructure.
- Laser device FDA premarket notification:The 510(k) clearance pathway for intense pulse light hair removal tools extends time-to-revenue by 12-18 months versus non-laser categories, compressing return windows for capital-intensive product development.
Strategic Opportunities
- Mexico's underpenetrated professional segment:Independent barbershops in Monterrey and Guadalajara remain underserved by durable corded clipper suppliers, creating whitespace for motor-technology specialists.
- Smartphone-integrated temperature control:Bluetooth-enabled styling tools with app-based heat profiling are capturing premium positioning among millennial buyers in Toronto and Vancouver.
- Health Canada streamlined certification:Recent mutual recognition agreements with U.S. test laboratories reduce duplicate safety testing for cross-border suppliers, lowering marginal cost of Canadian market entry.
Industry Challenges
- Embedded firmware validation timelines:Smart appliance connectivity features require FCC Part 15 certification cycles that frequently misalign with seasonal retail stocking deadlines.
- Cross-border warranty service integration:U.S. brands expanding into Canada face complexity harmonizing repair networks with provincial consumer protection statutes that mandate longer defect liability periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Personal Care Appliances Market |
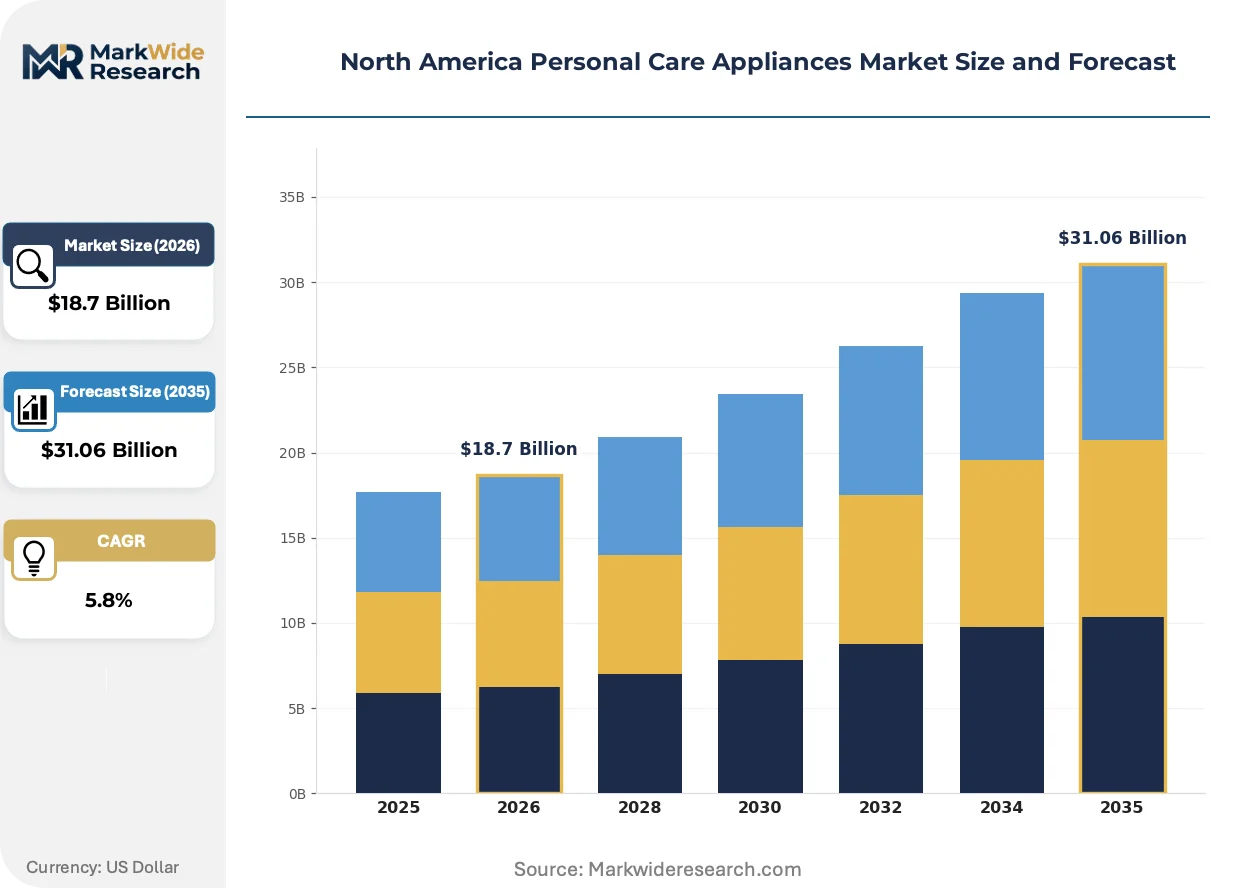
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hair Dryers, Electric Shavers, Hair Straighteners, Epilators End User: Men, Women, Children, Seniors Distribution Channel: Online Retail, Hypermarkets, Department Stores, Specialty Stores Price Tier: Economy, Mid-Range, Premium, Luxury |
| Companies Covered | Procter & Gamble, Koninklijke Philips N.V., Conair Corporation, Spectrum Brands, Wahl Clipper Corporation, Panasonic Corporation, Dyson Ltd, Helen of Troy, Andis Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Personal Care Appliances Market Evolving Landscape
Ceramic coating formulations are decoupling thermal performance from metal-dependent manufacturing economics, enabling regional production strategies that bypass traditional Asian supply chain concentration. This material shift is reshaping competitive positioning across the styling tool category.
Ionic generator technology is modularizing across the hair dryer category, allowing manufacturers to source discrete plasma modules from specialized vendors rather than engineering proprietary systems in-house. Mid-market brands in Texas and Illinois are adopting these plug-and-play subassemblies to compress development timelines. The technology is modularizing what was previously a captive competency, eroding differentiation for legacy thermal engineering specialists.
California's Proposition 65 enforcement is intensifying scrutiny of per- and polyfluoroalkyl substances in non-stick coating applications for thermal styling surfaces. Manufacturers serving the state's retail channel are reformulating ceramic composites to eliminate fluoropolymer layers entirely. The professional salon segment is absorbing these reformulation costs through premium pricing while mass-market suppliers delay compliance, creating a bifurcated regulatory exposure map.
Video demonstration content on social commerce platforms is displacing traditional retail touch-and-feel evaluation for premium appliance purchases. Direct-to-consumer brands in Los Angeles and New York are deploying micro-influencer tutorials to reduce purchase hesitation for $200-plus thermal tools. This channel shift concentrates marketing spend in content production rather than slotting fees, favoring agile digital-native suppliers over established mass retail incumbents.
North America Personal Care Appliances Market Segmentation
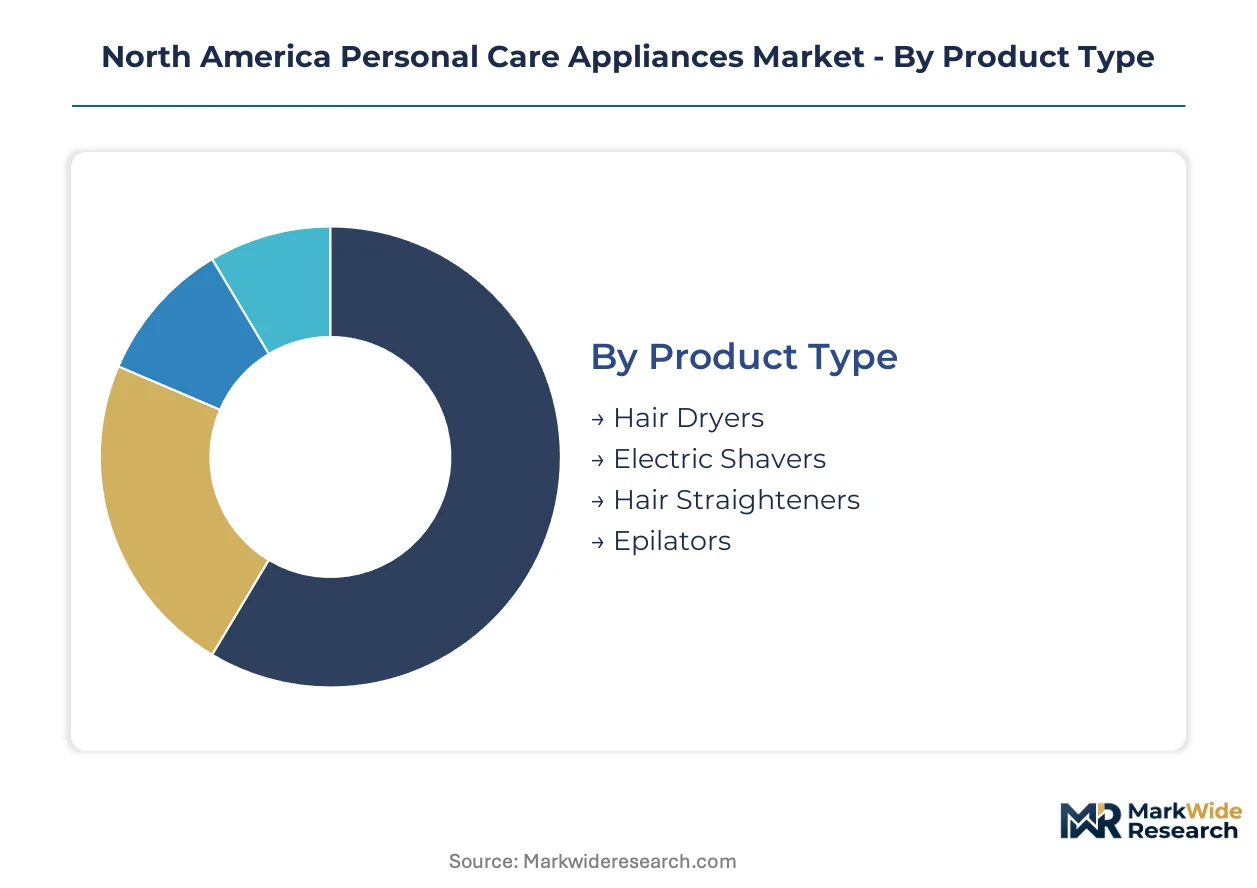
Personal care appliances demand heterogeneous engineering specifications across user profiles and purchase contexts. Manufacturers configure motor thermal output, blade geometry, and connectivity features differently for each segment cluster. The analysis below maps how these technical choices align with distinct value capture opportunities.
Product Type:
Customization intensity varies sharply across this category, with thermal tools requiring precision temperature calibration while removal devices prioritize ergonomic standardization.
- Hair Dryers:These appliances operate between 800W and 2400W with ceramic or tourmaline heating elements and ionic generator modules. Demand concentrates in California's direct-to-consumer testbed where professional-grade temperature control systems command premium positioning. The U.S. FDA's device classification rules for laser-based alternatives indirectly sustain dryer demand by constraining competing hair removal formats.
- Electric Shavers:Rotary and foil blade systems with lithium-ion power management dominate men's grooming routines. Replacement cartridge streams in Toronto and Vancouver sustain steadier revenue predictability than thermal tool categories. Men's electric shaver refresh cycles operate on 24-36 month intervals versus 18-24 months for professional salon thermal equipment.
- Hair Straighteners:Ceramic coating formulations are decoupling thermal performance from metal-dependent manufacturing economics.
- Epilators:These devices generate disproportionate margin contribution from replacement cartridge streams.
Leading the category by volume: Hair Dryers. Growing fastest: Epilators.
End User:
Volume concentration and margin profile diverge systematically across demographic clusters in this category.
- Men:Electric shaver replacement cycles sustain steadier revenue predictability across mass retail channels in Texas and Illinois. Corded motor durability commands loyalty in barbershop segments where runtime reliability outweighs cordless convenience.
- Women:This segment drives absolute unit demand across hair dryers, straighteners, and epilator categories. California's beauty-tech startup corridor tests premium formats specifically against millennial female buyers before national rollout.
- Children:Safety-certified lower-wattage devices with automatic shutoff features address parental purchase criteria.
- Seniors:Ergonomic grip designs and simplified control interfaces accommodate dexterity considerations in this expanding demographic.
Women dominate absolute unit movement. Men deliver the most predictable replacement revenue.
Distribution Channel:
Channel economics are restructuring around content-enabled purchase confidence versus physical evaluation.
- Online Retail:Video demonstration content on social commerce platforms is displacing traditional retail touch-and-feel evaluation for premium appliance purchases. Micro-influencer tutorials in Los Angeles and New York reduce purchase hesitation for thermal tools above $200.
- Hypermarkets:Mid-market shelf space consolidation favors portfolio-breadth players with established mass retail relationships.
- Department Stores:These channels are losing share as online retail captures premium-tier purchases previously requiring physical inspection.
- Specialty Stores:Professional salon supply outlets in Monterrey and Guadalajara remain underserved by durable corded clipper suppliers.
Online retail is expanding most quickly. Department stores are contracting as a share of premium transactions.
Price Tier:
Performance certification and material specification separate tiers rather than core functionality alone.
- Economy:Basic motor architectures without ionic generation or precision temperature control serve price-sensitive segments. California Proposition 65 compliance costs filter smaller import competitors from this tier.
- Mid-Range:Modular ionic generator technology from specialized vendors enables mid-market brands to compress development timelines. Texas and Illinois manufacturers adopt these plug-and-play subassemblies aggressively.
- Premium:Bluetooth-enabled styling tools with app-based heat profiling capture positioning among millennial buyers in Toronto and Vancouver.
- Luxury:Professional-grade temperature control systems with salon-equivalent output specifications anchor brand positioning for Koninklijke Philips N.V. in North America.
Premium tier generates the highest margin per unit. Mid-Range captures the broadest household penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's beauty-tech startup corridor concentrates venture capital and engineering talent, creating a testbed environment where direct-to-consumer brands validate premium appliance formats before national expansion.
United States
California's Proposition 65 chemical disclosure requirements filter smaller import competitors from mass retail channels. The U.S. FDA's device classification rules for laser-based hair removal tools tighten quality thresholds across the trade channel. Los Angeles and New York serve as content production hubs where micro-influencer tutorials reduce purchase hesitation for premium thermal tools.
Canada
Ontario's motor performance standards push manufacturers toward brushless DC architectures that reduce standby power draw. Health Canada's streamlined certification through mutual recognition agreements with U.S. test laboratories lowers marginal cost of market entry. Toronto and Vancouver anchor demand for Bluetooth-enabled styling tools with app-based heat profiling among millennial buyers.
Mexico
Independent barbershops in Monterrey and Guadalajara remain underserved by durable corded clipper suppliers, creating whitespace for motor-technology specialists. Mexico's national health regulator applies parallel safety certifications that fragment compliance burdens for cross-border suppliers. The Northern Border States concentrate manufacturing investment targeting U.S. retail replenishment cycles.
North America Personal Care Appliances Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with portfolio-breadth players dominating mid-market shelf space while single-category specialists capture professional loyalty. The vendor base organizes around three archetypes: diversified consumer goods conglomerates, dedicated personal care appliance engineers, and precision motor specialists serving barbershop segments. Consolidation pressure favors scale-driven procurement negotiations with retail channels. Competitive moves center on portfolio diversification into adjacent grooming categories and geographic expansion into underpenetrated professional segments.
Within the diversified conglomerate tier, Procter & Gamble and Spectrum Brands occupy positions defined by mass-market distribution infrastructure and cross-category marketing efficiency. Koninklijke Philips N.V. exemplifies the dedicated appliance engineer archetype, while Wahl Clipper Corporation represents precision motor specialization for professional end users.
| Leading Market Players |
|---|
| Procter & Gamble |
| Koninklijke Philips N.V. |
| Conair Corporation |
| Spectrum Brands |
| Wahl Clipper Corporation |
| Panasonic Corporation |
| Dyson Ltd |
| Helen of Troy |
| Andis Company |
| Others |
Value Network & Pricing Analysis
California's Proposition 65 chemical disclosure requirements filter qualified suppliers from mass-market channels while gating premium-tier pricing access for compliant manufacturers serving the state's retail corridor. This environmental mandate concentrates pricing power among established players with legal infrastructure to absorb labeling overhead, compressing margin recovery for smaller import competitors lacking reformulation capabilities.
Pricing Analysis
Short lead-time availability commands measurable premiums in professional salon supply channels where 18-24 month equipment refresh cycles compress inventory planning windows. Three-tier pricing structure across premium, standard, and economy levels separates Bluetooth-enabled app-integrated tools from modular ionic generator systems and basic motor architectures. Pricing pressure stems from neodymium magnet supply concentration exposing North American assemblers to quota risk. Mass-market buyers in Texas and Illinois exhibit highest price sensitivity, while Toronto and Vancouver millennial segments absorb premium positioning for connected devices.
Supply Chain Analysis
Regional distribution centers in Southern California and Texas anchor hub-and-spoke patterns serving direct-to-consumer testbeds and mass retail replenishment cycles. Manufacturing concentration clusters in China for ceramic coating precursors, Mexico's Northern Border States for corded motor assembly, and South Korea for lithium-ion power management systems. Rare earth processing capacity dependence creates single-source vulnerability for high-performance hair dryer motors. Distribution runs through wholesale professional salon suppliers in Monterrey and Guadalajara alongside big-box retail consolidation in the United States and Canada.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Neodymium magnet supply concentration props pricing across thermal tool categories, constraining volume expansion until alternative motor architectures achieve cost parity. This supply bottleneck sustains margin recovery for incumbents with long-term offtake agreements while elevating entry thresholds for capital-constrained challengers.
For Market Incumbents: Cement salon-equipment refresh cycle capture through professional-grade temperature control certification investments that lock out commodity competitors. Defend corded motor durability positioning in barbershop segments against cordless convenience marketing from emerging entrants by emphasizing runtime reliability in 24-36 month replacement intervals. Capacity addition in Mexico's Northern Border States reduces tariff exposure on finished goods while preserving proximity to California's beauty-tech startup corridor. For New Entrants and Emerging Players: Direct-to-consumer channel partners in Los Angeles and New York offer lowest-friction entry for premium-format testing before mass retail commitment. Independent barbershops in Monterrey and Guadalajara represent the most penetrable professional geography given incumbent underservice. Smartphone-integrated temperature control systems capture millennial positioning in Toronto and Vancouver through micro-influencer tutorial deployment rather than slotting fee competition. For Investors and Strategic Acquirers: FDA 510(k) clearance acceleration for intense pulse light devices is the leading indicator that regulatory arbitrage opportunities are compressing, favoring scaled players with established quality management systems. Long-term viability centers on portfolio diversification into adjacent grooming categories with shared thermal engineering competencies. Acquisition target archetype: precision motor specialists with captive rare earth supply relationships and Health Canada mutual recognition agreement access. Monitor brushless DC architecture adoption rates in Ontario as inflection signal for energy efficiency mandate propagation.| Strategic Initiative | Industry Significance |
|---|---|
| Professional-Grade Certification Investment | FDA 510(k) clearance for laser devices validates quality thresholds across trade channels. |
| Brushless DC Architecture Transition | Ontario's motor performance standards push standby power reduction while maintaining thermal output. |
| Direct-to-Consumer Channel Launch | Los Angeles and New York content production hubs reduce purchase hesitation for premium thermal tools. |
| Mexico Professional Segment Expansion | Monterrey and Guadalajara barbershops remain underserved by durable corded clipper suppliers. |
| Ceramic Coating Reformulation | Proposition 65 compliance eliminates fluoropolymer layers, filtering smaller import competitors. |
Research Methodology
Independent corroboration across appliance engineering directors, professional salon procurement managers, mass retail category buyers, and regulatory affairs specialists underwrites the qualitative findings. Primary interviews with ceramic coating formulators and rare earth supply chain participants combined with secondary validation from U.S. FDA device classification filings, Health Canada certification databases, California Proposition 65 enforcement records, and customs trade data establish demand-side and supply-side baselines. Bottom-up unit economics triangulate against top-down category spend estimates.
Comparable historical reference periods anchor the projection horizon across product type, end user demographic, distribution channel, and price tier dimensions. CAGRs derive from segment-specific growth rate modeling incorporating professional salon equipment refresh cycle compression, energy efficiency mandate propagation, and direct-to-consumer channel share capture. Industry-specific forecast inputs include neodymium magnet price volatility indices and FDA premarket notification clearance timelines for intense pulse light categories.
Caveats apply where rare earth supply quota restrictions, FDA regulatory pathway extensions, or California chemical disclosure enforcement intensification could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
United Kingdom Compact Dishwasher Market
Appliances
Kuwait Dishwasher Market
Appliances
Microwave Oven Market
Appliances
Refrigerator Repair Service Market
Appliances
Europe Microwave Oven Market
Appliances
Water Heater Market
Appliances
Clothing Iron Market
Appliances
Small Electric Kettles Market
Appliances
Electric Rice Cooker Market
Appliances
Household Beauty Appliances Market
Appliances
Electric Iron Market
Appliances
French Door Refrigerator Market
Appliances
United States Electric Kettle Market
Appliances
Dishwasher Market
Appliances
Oman Dishwashers Market
Appliances
Laundry Appliances Market