
 Toaster Ovens Market | 2026-2036
Toaster Ovens Market Size, Share, and Industry Trends Forecast 2026-2036
Toaster Ovens Market Analysis
Appliance engineering talent is rotating from conventional oven manufacturing into smart countertop development, tightening supply chains for legacy brands. Breville leverages its Sydney-based R&D hub to sustain premium positioning in convection-toaster hybrid designs. Hamilton Beach competes through mass-market channel control across North American big-box retail. COSORI specializes in direct-to-consumer online distribution with air-fryer integration as its core differentiator.
A toaster oven is an enclosed electric heating appliance typically operating between 150°C and 260°C, utilizing quartz or metal-sheathed heating elements with thermostat-controlled cycling for baking, toasting, or reheating food in residential and commercial settings. The countertop product type dominates unit volume while the toaster oven air fryer sub-segment captures expanding margin pools through premium pricing on multi-function claims. Among end users, households anchor baseline demand but cafés represent the fastest-growing commercial installation category as operators seek compact footprint alternatives to full-size convection ovens.
The US Department of Energy sets minimum efficiency standards under its appliance program, while the FCC governs wireless connectivity modules in smart-enabled units, and California's Title 20 regulations impose standby power limits that ripple through national product lines. These frameworks elevate compliance costs for entry-level manufacturers while creating specification barriers that favor established suppliers with certified testing infrastructure. Stakeholders must monitor how emerging state-level efficiency mandates interact with smart-home interoperability standards to determine which feature bundles justify development investment.
Market Dynamics
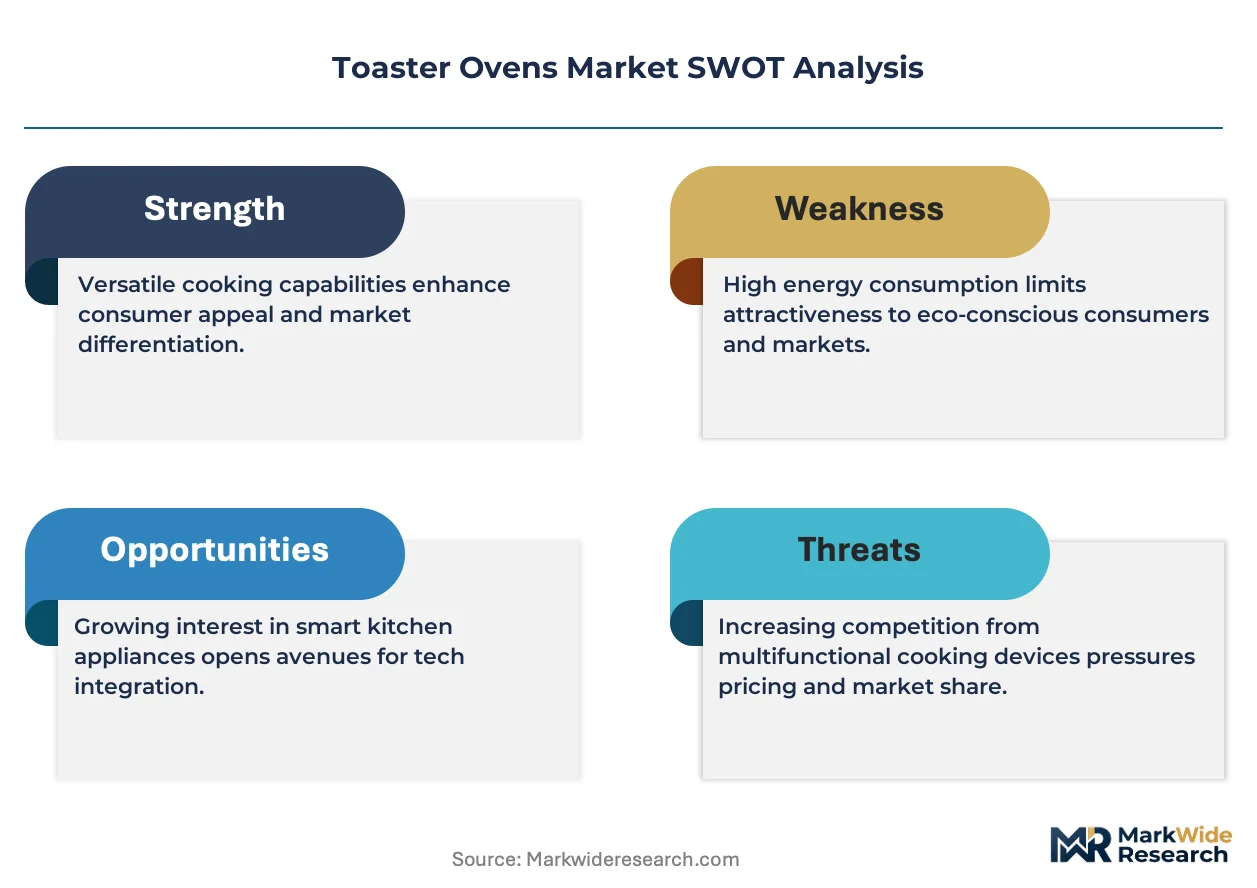
The US Department of Energy's appliance efficiency standards are compressing margins for legacy heating element designs while forcing rapid retooling toward improved insulation systems and smart thermostat integration.
Growth Catalysts
- Urban Countertop Constraints:Apartment dwellers in dense US metropolitan areas prioritize multi-function units that replace separate toasters, air fryers, and warming drawers. This spatial economics driver accelerates premium product turnover.
- Title 20 Standby Power Rules:California's regulations impose sub-watt standby limits that manufacturers must engineer into national product lines, creating specification barriers that favor certified suppliers with testing infrastructure.
- Ghost Kitchen Equipment Refresh:Rental kitchen operators and delivery-only food concepts are standardizing on compact convection-toaster hybrids to minimize footprint while maintaining menu versatility.
Market Restraints
- Quartz Heating Element Supply Concentration:Japanese and Chinese suppliers control high-purity quartz tube production, exposing manufacturers to input cost volatility and single-source risk.
- FCC Certification Friction:Wireless connectivity modules in smart-enabled units require lengthy electromagnetic compliance testing that delays product launches by 4-6 months.
- Full-Size Convection Substitution:Falling prices on commercial-grade countertop convection ovens threaten toaster oven relevance in café and small restaurant installations.
Strategic Opportunities
- Midwest US Appliance Replacement Cycles:Aging housing stock in Illinois, Ohio, and Michigan markets creates concentrated demand for countertop upgrades as kitchen renovations accelerate.
- Voice-Assistant Integration Convergence:Combining WiFi connectivity with Amazon Alexa and Google Home protocols enables premium pricing on hands-free cooking automation.
- Direct-to-Consumer Channel Expansion:Social commerce and influencer-driven launches bypass traditional big-box retail gatekeepers, capturing margin that previously flowed to distributors.
Industry Challenges
- Embedded Systems Firmware Talent Scarcity:Manufacturers struggle to hire IoT engineers capable of integrating thermostat controls with cloud-connected recipe platforms.
- UL Safety Certification Backlogs:Third-party testing laboratory capacity constraints extend time-to-market for new heating element configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Toaster Ovens Market |
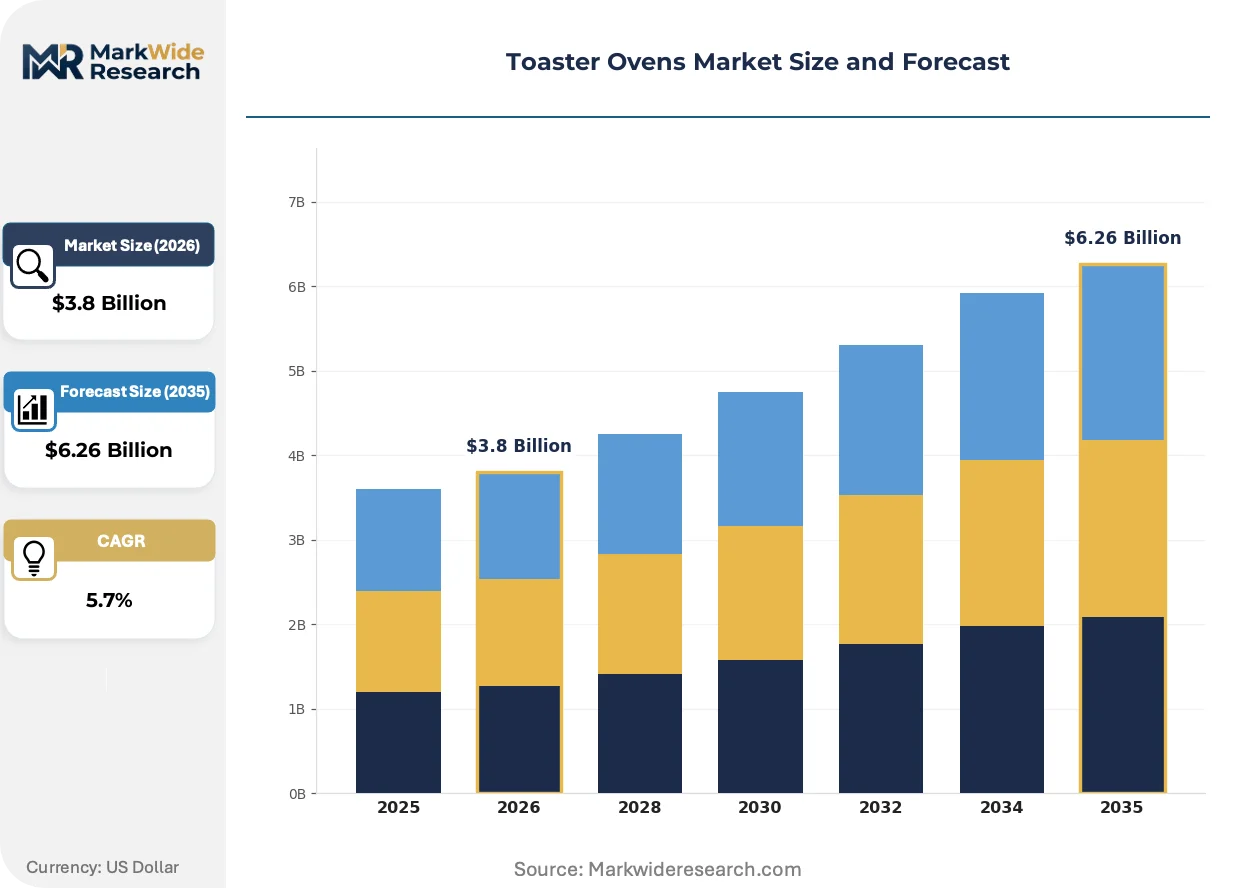
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Convection, Toaster Oven Air Fryer, Built-in End User: Households, Restaurants, Cafés, Catering Services Distribution Channel: Online Retail, Specialty Stores, Hypermarkets, Discount Stores Feature: Smart Technology, Energy Efficient, Multi-function, Compact Size |
| Companies Covered | Cuisinart, Instant, Breville, DeLonghi, Ninja, COSORI, Panasonic, Hamilton Beach, Black+Decker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Toaster Ovens Market Emerging Trajectories
Smart connectivity and multi-function convergence are rewriting product definitions, while regulatory pressure on standby power and materials safety is accelerating design obsolescence for legacy platforms.
Infrared quartz heating technology is displacing traditional metal-sheathed elements in mid-tier and premium product lines. Ghost kitchen operators and high-turnover café chains are adopting infrared models for faster preheat cycles and more consistent browning. This thermal efficiency gain is displacing conventional resistive heating as the default specification in commercial procurement tenders.
REACH substance restrictions in the European Union are limiting certain coatings and insulation materials previously standard in heating chamber construction. Manufacturers serving export markets must reformulate internal surfaces and gaskets to maintain compliance. This regulatory pressure most affects entry-level producers lacking in-house materials science capabilities, pushing consolidation toward suppliers with certified European testing partnerships.
Subscription-based recipe and maintenance services are unbundling from hardware sales in direct-to-consumer channels. Buyers increasingly expect cloud-connected units to receive over-the-air firmware updates and seasonal cooking program downloads. This service-layer monetization is most advanced in coastal US urban markets where smart home penetration already exceeds national averages.
Toaster Ovens Market Segmentation
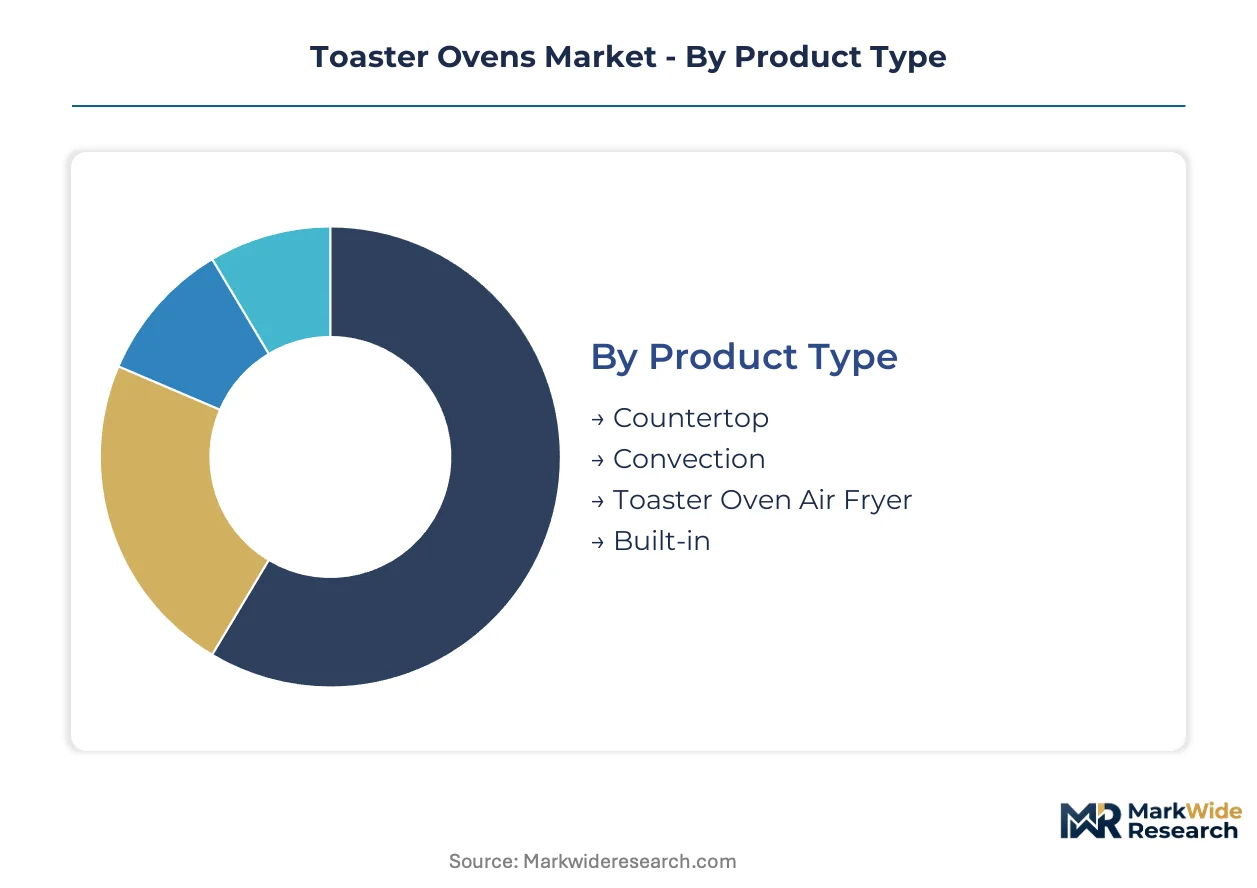
Toaster ovens fragment across four distinct category axes that determine pricing power and channel strategy. Product type and feature bundles define margin capture, while end-user concentration and distribution access govern volume throughput.
Product Type:
Premium margin pools concentrate in multi-function hybrids that command shelf space in urban retail corridors.
- Countertop:These units utilize quartz or metal-sheathed heating elements with thermostat-controlled cycling between 150°C and 260°C. Demand concentrates in United States urban apartment markets where counter space constraints drive replacement of separate toasters and warming drawers.
- Toaster Oven Air Fryer:Infrared quartz technology enables faster preheat cycles and consistent browning through convection-assisted airflow. Ghost kitchen operators in dense metropolitan clusters are standardizing on these hybrids to minimize footprint while maintaining menu versatility.
- Convection:Forced-air circulation systems distribute heat uniformly across the cooking chamber.
- Built-in:Under-cabinet and wall-integrated installations target kitchen renovation projects.
Countertop holds installed capacity. Toaster Oven Air Fryer is rotating up the share rankings.
End User:
Commercial installations are climbing the fastest as foodservice operators seek compact footprint alternatives to full-size convection ovens.
- Cafés:High-turnover coffee chains and independent operators deploy compact convection-toaster hybrids for pastry warming and small-batch baking. Equipment procurement in United States coastal cities accelerates as operators optimize limited back-of-house square footage.
- Households:Residential buyers anchor baseline demand through replacement cycles tied to kitchen renovations. Midwest United States markets—Illinois, Ohio, and Michigan—show concentrated activity as aging housing stock drives countertop upgrades.
- Restaurants:Full-service and fast-casual concepts utilize units for secondary cooking stations.
- Catering Services:Mobile food operations and event vendors prioritize portability and rapid heat recovery.
Households dominate unit shipments. Cafés are expanding most quickly in commercial procurement.
Distribution Channel:
Direct-to-consumer pathways capture margin previously flowing to traditional retail gatekeepers, though big-box control persists in mass-market segments.
- Online Retail:Social commerce and influencer-driven launches enable subscription-based recipe services and over-the-air firmware monetization. Coastal United States urban markets with elevated smart home penetration drive premium conversion rates.
- Specialty Stores:Curated assortments in kitchenware boutiques emphasize convection-toaster hybrid designs with premium positioning.
- Hypermarkets:Mass-market channel control concentrates volume across North American big-box retail footprints.
- Discount Stores:Entry-level price tiers target replacement demand with limited feature sets.
Hypermarkets maintain volume throughput. Online Retail is gaining share fastest in revenue terms.
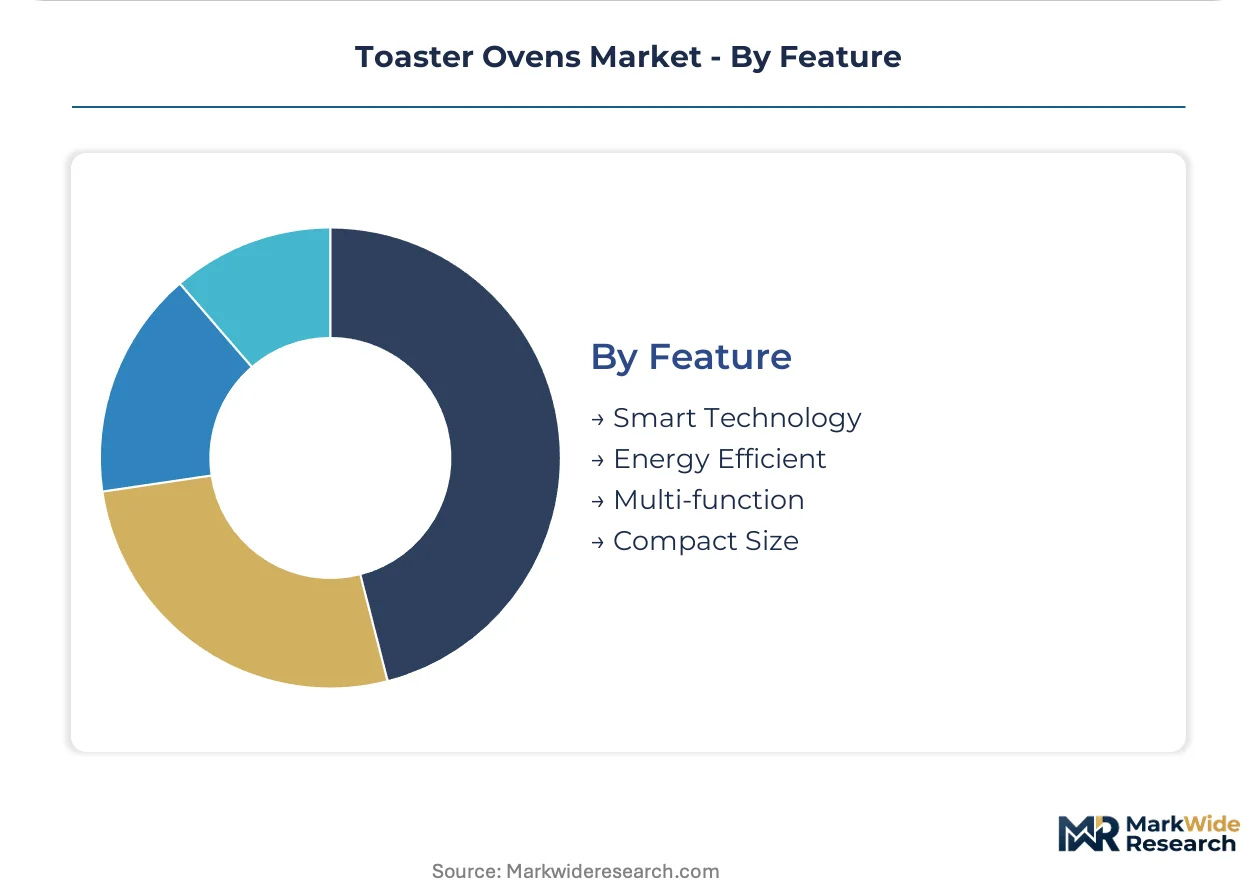
Feature:
Smart connectivity and energy compliance are restructuring competitive differentiation as regulatory pressure accelerates design obsolescence for legacy platforms.
- Smart Technology:WiFi-enabled units with Amazon Alexa and Google Home integration require FCC certification for electromagnetic compliance. Firmware talent scarcity delays product launches as manufacturers compete for IoT engineers capable of cloud-connected recipe platform integration.
- Energy Efficient:California Title 20 standby power rules impose sub-watt limits that manufacturers engineer into national product lines. Improved insulation systems and smart thermostat integration compress margins for legacy heating element designs.
- Multi-function:Convergence of toasting, air frying, baking, and warming capabilities displaces single-purpose appliances.
- Compact Size:Reduced footprint specifications target spatial constraints in dense urban residential markets.
Energy Efficient features anchor regulatory compliance. Smart Technology is climbing the fastest in premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Department of Energy's appliance efficiency standards anchor the dominant geography, compressing margins for legacy heating element designs while forcing rapid retooling toward improved insulation systems across national product lines.
United States
Urban apartment markets in New York, Chicago, and Los Angeles drive concentrated demand for compact multi-function units that replace separate toasters and air fryers. California's Title 20 regulations impose sub-watt standby power limits that manufacturers engineer into national product lines. Ghost kitchen operators in Miami and Austin are standardizing on convection-toaster hybrids to minimize back-of-house footprint.
Germany
REACH substance restrictions limit certain coatings and insulation materials previously standard in heating chamber construction, forcing reformulation of internal surfaces. The country's national energy regulator maintains strict efficiency benchmarks for residential appliances. Industrial clusters in Bavaria and Baden-Württemberg host testing partnerships that certify compliance for export-bound manufacturers.
China
Domestic demand concentrates in tier-one cities where counter space constraints mirror Western urban patterns. The Ministry of Industry and Information Technology governs wireless connectivity modules in smart-enabled units through national standards. Manufacturing gravity centers on Guangdong and Zhejiang provinces, where quartz heating element supply chains face input cost volatility.
Japan
METI efficiency guidelines push manufacturers toward infrared quartz technology with faster preheat cycles. High-turnover café chains in Tokyo and Osaka deploy compact convection-toaster hybrids for pastry warming. Domestic suppliers control high-purity quartz tube production, creating single-source exposure for manufacturers dependent on Japanese inputs.
United Kingdom
Smart home penetration in London and Southeast England drives premium conversion rates for WiFi-enabled units with voice-assistant integration. The country's national standards body aligns with EU efficiency frameworks post-Brexit. Kitchen renovation cycles in Manchester and Birmingham create replacement demand for countertop upgrades.
Toaster Ovens Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with premium positioning concentrated among R&D-intensive manufacturers and mass-market volume flowing through channel-dominant players. The vendor base fragments across four strategic archetypes: Sydney-based convection-toaster hybrid specialists, North American big-box retail channel controllers, direct-to-consumer air-fryer integrators, and Japanese electronics conglomerates with smart connectivity modules. Competitive moves center on FCC certification acceleration for wireless-enabled launches and backward integration into quartz heating element supply.
Among the premium-tier specialists, Breville exemplifies R&D-hub positioning through its Sydney-based development infrastructure. COSORI occupies the direct-to-consumer vector with online distribution specialization. Hamilton Beach anchors the mass-market tier through North American big-box retail channel control. These three represent the dominant competitive archetypes reshaping procurement patterns across household and commercial end-use segments.
| Leading Market Players |
|---|
| Cuisinart |
| Instant |
| Breville |
| DeLonghi |
| Ninja |
| COSORI |
| Panasonic |
| Hamilton Beach |
| Black+Decker |
| Others |
Supply Flow & Price Mechanics
Infrared quartz heating elements displacing metal-sheathed resistive technology simultaneously concentrate supply geography in East Asian manufacturing corridors and compress pricing economics for legacy component tiers. This substitution dynamic forces manufacturers to absorb retooling costs while competing on thermal efficiency claims that justify premium positioning.
Pricing Analysis
Long-term offtake contracts with Japanese and Chinese quartz suppliers anchor input cost stability for premium-tier manufacturers, while spot-market exposure punishes smaller players lacking volume scale. Price differentiation rests on UL certification tier and smart connectivity integration, with California Title 20 compliance adding fixed compliance premiums. Cost compression in entry-level segments intensifies as Chinese manufacturers bypass certification investment. Ghost kitchen operators show least price sensitivity, prioritizing rapid preheat performance over unit economics.
Supply Chain Analysis
China and Japan anchor high-purity quartz tube production, with Guangdong and Zhejiang provinces hosting heating element fabrication clusters. Manufacturing draws from borosilicate glass, nickel-chromium wire, and mica sheet inputs. Single-source vulnerability concentrates in Japanese suppliers controlling infrared quartz patents. Distribution runs through Shenzhen and Ningbo port logistics before diverting to North American big-box retail and direct-to-consumer fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in voice-assistant integration and subscription recipe services, as incumbent hardware margins compress and software-layer monetization remains underdeveloped across Midwest and Sun Belt residential markets.
For Market Incumbents: Secure backward integration into quartz heating element supply through partnerships with Zhejiang-based fabricators, insulating against Japanese supplier concentration. Accelerate FCC pre-certification for wireless modules to compress 4-6 month launch delays that cede share to direct-to-consumer entrants. Prioritize Title 20 compliance as a specification barrier against uncertified imports. For New Entrants and Emerging Players: Firmware update subscription gaps in incumbent product lines create white-space for cloud-connected recipe platform specialists. Target café and ghost kitchen segments in Miami and Austin where equipment refresh cycles concentrate. Pursue influencer-driven social commerce launches to bypass big-box retail gatekeeper margins. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed appliance roll-ups lacking IoT engineering depth. Five-to-ten year viability hinges on smart-home interoperability convergence rather than hardware replacement cycles alone. Monitor FCC certification backlog resolution as inflection indicator for product launch velocity and working capital efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| Quartz Heating Element Backward Integration | Captive supply from Zhejiang fabricators reduces Japanese supplier concentration exposure. |
| FCC Pre-Certification Investment | Accelerated electromagnetic compliance testing compresses smart-enabled product launch timelines. |
| Voice-Assistant Protocol Convergence | Amazon Alexa and Google Home integration enables premium pricing on hands-free automation. |
| Direct-to-Consumer Channel Expansion | Social commerce bypasses big-box retail margin extraction in coastal urban markets. |
| Subscription Recipe Service Layer | Over-the-air firmware monetization captures recurring revenue from hardware-installed base. |
Methodological Framework
Desk research of customs trade records, UL certification databases, and FCC equipment authorization filings preceded structured interviews with appliance engineering directors, big-box retail category buyers, ghost kitchen operators, and IoT firmware developers. Primary fieldwork across Shenzhen manufacturing corridors and Chicago distribution hubs validated production cost structures and channel margin stacks. Bottom-up unit shipment modeling triangulated against top-down retail audit data from Nielsen and Circana.
Variance decomposition across product type, end-user segment, distribution channel, and feature tier informed volume and value projections over the analysis window. CAGRs derived from replacement cycle analysis, urban household formation rates, and commercial foodservice equipment refresh patterns. Smart home penetration curves and Title 20 regulatory adoption timelines served as industry-specific forecast inputs.
Underlying assumptions cover steady-state quartz supply availability and stable FCC certification processing capacity, with deviation risk concentrated in trade policy shifts affecting Chinese component imports and state-level efficiency mandate acceleration. Recalibration cycles align with material shifts in standby power regulations and voice-assistant platform consolidation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Mexico Washing Machine Market
Appliances
GCC Dishwashers Market
Appliances
Electric Iron Market
Appliances
Japan Massage Equipment Market
Appliances
Industrial Gas Stove Market
Appliances
Space Heaters Market
Appliances
Commercial Microwave Ovens Market
Appliances
Europe Induction Hobs Market
Appliances
United Kingdom Tumble Dryers Market
Appliances
Mini Refrigerator Market
Appliances
Germany Consumer Appliances Market
Appliances
Egypt Microwave Ovens Market
Appliances
Hair Removal Appliances Market
Appliances
French Door Refrigerator Market
Appliances
Microwave Oven Market
Appliances
Egypt Dishwashers Market