
 Global Liver Diseases Therapeutics Market | 2026-2036
Global Liver Diseases Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Liver Diseases Therapeutics Market Foresight
A widening capital-intensity gap between biologics manufacturers and small-molecule specialists is reorganizing competitive tiers in liver therapeutics. Gilead Sciences leverages its nucleotide analogue portfolio to sustain dominance in hepatitis B and C antiviral segments. AbbVie anchors its position through immunology platforms that extend into autoimmune liver conditions. Bristol-Myers Squibb competes via checkpoint inhibitor pipelines targeting hepatocellular carcinoma adjacencies.
Liver diseases therapeutics comprise pharmaceutical agents designed to modify disease progression, reduce viral load, inhibit fibrogenesis, or restore hepatic function through targeted biochemical intervention. These compounds typically require hepatic metabolic profiling, cytochrome P450 interaction studies, and long-term safety monitoring given the compromised organ function of the patient population. Antiviral agents retain the largest revenue footprint due to sustained hepatitis B and C treatment volumes, while antifibrotic drugs represent the fastest-expanding category as nonalcoholic steatohepatitis programs advance through Phase III. Immunosuppressants command premium pricing in transplant settings where therapeutic monitoring and narrow therapeutic indices limit generic substitution.
The FDA maintains stringent black-box labeling requirements for hepatotoxicity risk, while the EMA enforces pharmacovigilance protocols through the EU Risk Management Plan framework. Both regulators are elevating histological and biomarker standards for NASH drug approvals, compressing development timelines for sponsors with marginal efficacy signals. Stakeholders must weigh regulatory pathway uncertainty against the commercial upside of first-mover antifibrotic approvals in what will become a crowded therapy area.
Market Dynamics
The FDA and EMA are simultaneously elevating histological endpoints for nonalcoholic steatohepatitis approvals, compressing development timelines for sponsors with marginal efficacy signals and forcing portfolio reprioritization across the antifibrotic pipeline.
Growth Catalysts
- EMA Risk Management Plans:Standardized pharmacovigilance frameworks accelerate conditional approval pathways for breakthrough liver therapies, reducing time-to-market for sponsors with robust safety databases.
- Specialty clinic networks:United States-based integrated delivery systems consolidate prescription volumes for advanced hepatology drugs, creating concentrated demand pools that justify premium pricing.
- Biomarker validation:Non-invasive diagnostic platforms for fibrosis staging expand addressable patient populations beyond biopsy-limited cohorts, enabling earlier therapeutic intervention.
Market Restraints
- Hepatotoxicity surveillance costs:FDA black-box labeling mandates require extensive post-market monitoring infrastructure, elevating total cost of ownership for marketed agents.
- Active pharmaceutical ingredient concentration:Nucleotide analogue synthesis depends on specialized contract manufacturers concentrated in India and China, exposing supply continuity to geopolitical friction.
- Generic substitution ceilings:Narrow therapeutic indices for immunosuppressants limit automatic pharmacy-level substitution, constraining volume expansion in transplant maintenance settings.
Strategic Opportunities
- Brazil's ANVISA accelerated review:Emerging regulatory harmonization with FDA standards opens pathway for priority review vouchers in Latin America's largest pharmaceutical market.
- Digital therapeutics convergence:Integration of prescription pharmacotherapy with adherence-monitoring applications creates reimbursement-advantaged bundles for payor contracting.
- Japan's PMDA Sakigake designation:Early approval framework for innovative liver disease treatments enables first-molecule positioning in Asia-Pacific's highest-value pricing environment.
Industry Challenges
- Hepatology trial recruitment:Competing NASH Phase III programs strain site capacity and patient availability, extending enrollment timelines and inflating per-patient costs.
- Legacy biomarker standardization:Discordance between academic medical centers on non-invasive fibrosis scoring creates regulatory submission variability and agency query cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Liver Diseases Therapeutics Market |
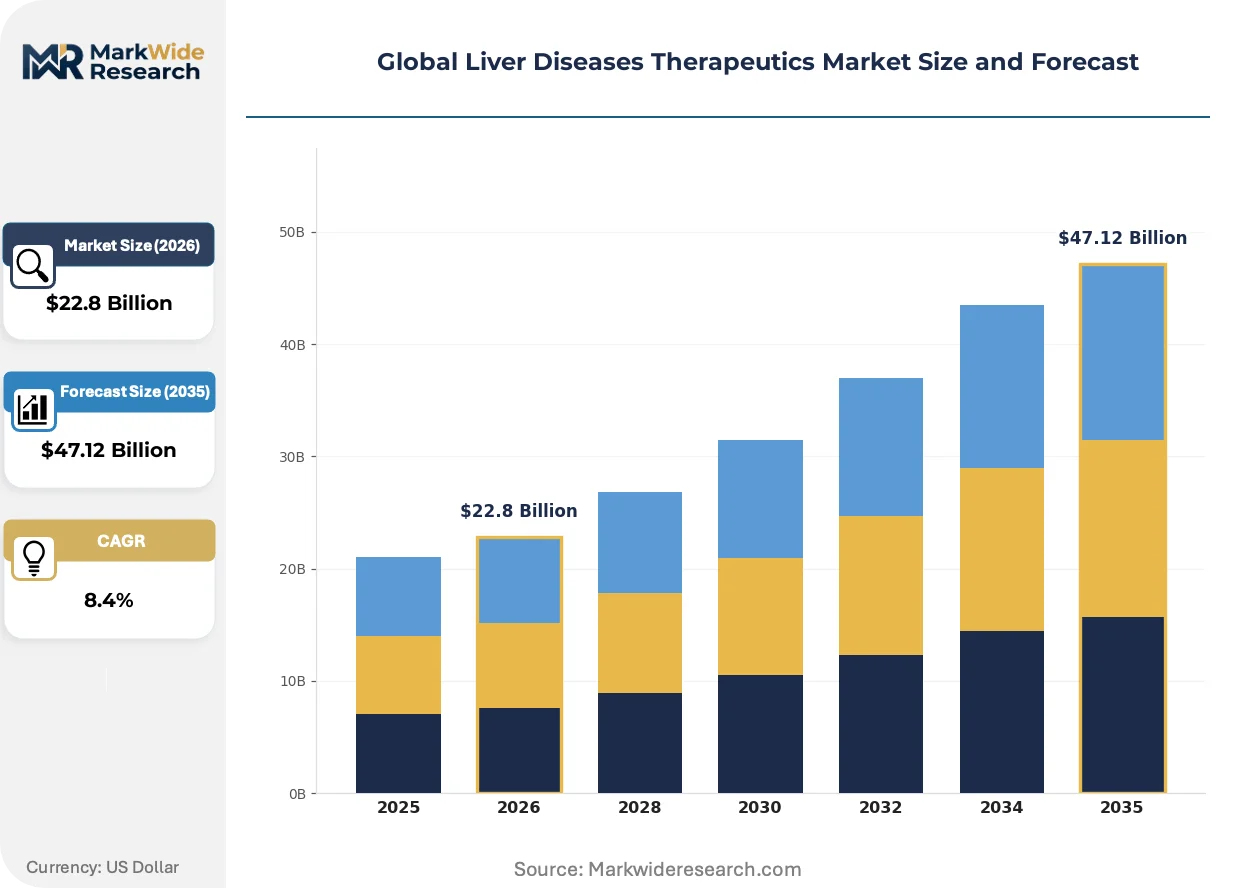
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $47.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiviral Agents, Immunosuppressants, Antifibrotic Drugs, Hepatoprotective Agents, Bile Acid Derivatives Therapy Area: Hepatitis B, Hepatitis C, Cirrhosis, Nonalcoholic Steatohepatitis, Alcoholic Liver Disease Care Setting: Hospitals, Specialty Clinics, Diagnostic Laboratories, Ambulatory Care Centers, Research Institutes Delivery Mode: Oral, Injectable, Transdermal, Nasal, Rectal |
| Companies Covered | Gilead Sciences, AbbVie, Bristol-Myers Squibb, F. Hoffmann-La Roche, Takeda Pharmaceutical, Johnson & Johnson, Merck & Co., Novartis, Pfizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Liver Diseases Therapeutics Market Shifts & Advancements
Antifibrotic mechanism diversity is expanding therapeutic modality options beyond small molecules, while regulatory science evolution and prescriber behavior shifts are compressing traditional commercialization timelines.
RNA interference platforms targeting hepatic gene expression are fragmenting the historical small-molecule dominance in NASH drug development. Academic medical centers in Germany and the United States are adopting these modalities for investigator-initiated trials at accelerating pace. This technology divergence is fragmenting payer formulary strategies, forcing parallel evidence-generation tracks for mechanism-specific reimbursement.
REACH registration requirements for novel chemical entities are tightening environmental fate disclosures for liver therapeutic manufacturing. European contract development organizations report extended regulatory chemistry timelines as ECHA scrutiny intensifies for hepatotoxicity-related structural alerts. Sponsors with pre-registered legacy assets retain competitive advantage in EU market access negotiations.
Integrated delivery systems in the United States are consolidating hepatology prescribing authority within specialty pharmacy carve-outs. Traditional wholesale distribution channels face displacement by health-system-owned dispensing entities that capture margin through 340B pricing arbitrage. This channel restructuring is most visible in transplant center networks across Texas, Florida, and California.
Global Liver Diseases Therapeutics Market Segmentation
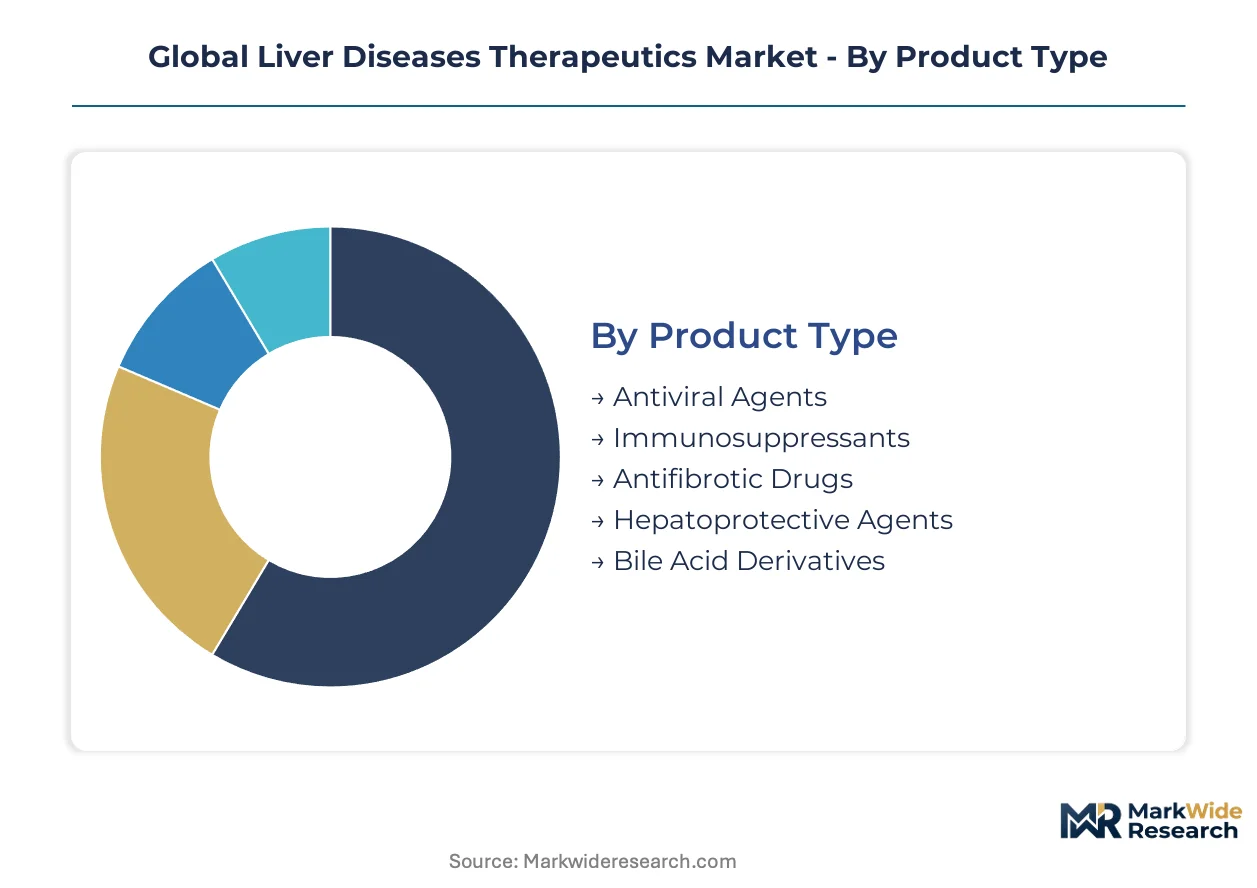
Segmentation in liver therapeutics reveals divergent competitive pressures across molecular modalities and care delivery models. Substitution threats vary sharply by mechanism of action and prescriber setting, reshaping portfolio prioritization for sponsors.
Product Type:
Substitution pressure concentrates in antiviral and hepatoprotective segments where generic erosion and functional food alternatives erode pricing power.
- Antiviral Agents:Nucleotide and nucleoside analogues targeting viral polymerase enzymes dominate current prescription volumes. Demand concentrates in United States integrated delivery systems managing hepatitis B and C patient cohorts, though curative therapy saturation in hepatitis C compresses expansion potential.
- Immunosuppressants:Calcineurin inhibitors and mTOR antagonists with narrow therapeutic indices command premium pricing in transplant maintenance. Procurement concentrates in academic medical center transplant networks across Germany, Japan, and the United States where therapeutic drug monitoring protocols limit interchangeability.
- Antifibrotic Drugs:Small-molecule and biologic inhibitors of fibrogenic signaling pathways represent the most contested development frontier. Clinical programs targeting nonalcoholic steatohepatitis are advancing through Phase III under elevated FDA and EMA histological endpoint standards.
- Hepatoprotective Agents:Cytoprotective compounds including silymarin derivatives and antioxidant formulations face intensifying competition from nutraceutical alternatives in European and Asian self-pay markets.
- Bile Acid Derivatives:Farnesoid X receptor agonists and ursodeoxycholic acid formulations address cholestatic liver diseases with established regulatory pathways.
Antiviral agents retain volume leadership; antifibrotic drugs hold the steepest expansion curve.
Therapy Area:
Cost tier stratification separates curative antiviral regimens from chronic management categories requiring sustained pharmacotherapy.
- Hepatitis B:Chronic suppressive nucleos(t)ide analogue therapy generates recurring revenue streams in Asia-Pacific markets with high prevalence. Patient monitoring infrastructure in South Korea and Taiwan supports long-term adherence programs.
- Hepatitis C:Direct-acting antiviral combinations have achieved cure rates exceeding 95%, collapsing treatment volumes in developed markets. Remaining demand concentrates in Medicaid populations and correctional health systems within the United States.
- Cirrhosis:Decompensated liver disease management spans diuretics, beta-blockers, and transplant evaluation pathways. Hospital admission rates for variceal bleeding and hepatic encephalopathy drive acute care pharmacotherapy in Brazil and India.
- Nonalcoholic Steatohepatitis:Metabolic liver disease with no approved pharmacotherapy represents the largest addressable expansion opportunity. Biopsy-confirmed prevalence estimates in the United States, United Kingdom, and Germany are driving payer investment in non-invasive diagnostic infrastructure.
- Alcoholic Liver Disease:Corticosteroid and pentoxifylline protocols for severe alcoholic hepatitis face limited pipeline innovation. Abstinence monitoring requirements restrict pharmaceutical intervention to acute decompensation episodes.
Hepatitis B maintains the largest treated population; nonalcoholic steatohepatitis is climbing the fastest toward commercialization.
Care Setting:
Volume concentration in hospital-based hepatology is accelerating as integrated delivery systems consolidate prescribing authority.
- Hospitals:Tertiary care centers manage decompensated cirrhosis, acute liver failure, and transplant evaluation. 340B pricing arbitrage in United States health systems is displacing traditional wholesale distribution for high-cost immunosuppressants.
- Specialty Clinics:Dedicated hepatology and gastroenterology practices in Germany, France, and the United States concentrate nonalcoholic steatohepatitis diagnosis and trial enrollment. Reimbursement for fibrosis staging via transient elastography is expanding clinic-based patient identification.
- Diagnostic Laboratories:Centralized testing for viral load quantification, genotyping, and pharmacogenomic profiling supports treatment initiation decisions.
- Ambulatory Care Centers:Infusion suites for biologic administration and interferon therapy are contracting as oral antiviral regimens dominate.
- Research Institutes:Academic medical centers in Japan, the Netherlands, and the United States conduct investigator-initiated trials for RNA interference platforms and combination antifibrotic protocols.
Hospitals retain volume leadership; specialty clinics hold the steepest expansion curve.
Delivery Mode:
Patient preference and adherence economics are shifting development investment toward oral formulations with optimized pharmacokinetic profiles.
- Oral:Once-daily nucleos(t)ide analogues and emerging antifibrotic tablets dominate prescription volumes. Fixed-dose combinations of sofosbuvir/velpatasvir and similar regimens have displaced interferon-based injectable protocols.
- Injectable:Pegylated interferon persists in limited hepatitis D and hepatitis B scenarios; biologic antifibrotics in development are evaluating subcutaneous administration for patient convenience.
- Transdermal:Patch-based delivery for chronic pain management in advanced liver disease remains investigational given hepatic metabolism concerns.
- Nasal:No approved liver therapeutic utilizes intranasal administration; preclinical programs explore this route for acute hepatic encephalopathy rescue.
- Rectal:Lactulose and rifaximin formulations for hepatic encephalopathy utilize this route in hospitalized patients with altered mental status.
Oral formulations retain volume leadership; injectable biologics hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in South Korea and Taiwan demonstrate the lowest price elasticity for chronic hepatitis B therapy, while Medicaid populations in the United States and correctional health systems exhibit acute sensitivity to antiviral regimen costs.
United States
Specialty clinic networks and integrated delivery systems concentrate prescription volumes for advanced hepatology drugs, with 340B pricing arbitrage displacing traditional wholesale distribution in transplant center networks across Texas, Florida, and California. FDA black-box labeling mandates for hepatotoxicity risk elevate post-market surveillance infrastructure costs. The Greater Boston cluster anchors RNA interference platform development through academic medical center partnerships.
Germany
Academic medical centers in Munich and Heidelberg adopt RNA interference modalities for investigator-initiated trials at accelerating pace, fragmenting payer formulary strategies. EMA pharmacovigilance protocols through the EU Risk Management Plan framework accelerate conditional approval pathways for breakthrough liver therapies. The Rhine-Ruhr metropolitan region concentrates calcineurin inhibitor procurement for transplant maintenance protocols.
Japan
PMDA Sakigake designation for innovative liver disease treatments enables first-molecule positioning in Asia-Pacific's highest-value pricing environment, with Tokyo-based specialty clinics driving nonalcoholic steatohepatitis diagnosis volumes. METI oversight of pharmaceutical pricing negotiations creates predictable reimbursement corridors for novel antifibrotic entrants. The Kansai region houses concentrated hepatology trial infrastructure for Phase III NASH programs.
Brazil
Hospital admission rates for variceal bleeding and hepatic encephalopathy drive acute care pharmacotherapy demand in São Paulo and Rio de Janeiro metropolitan areas. ANVISA accelerated review pathways, harmonizing with FDA standards, open priority review vouchers in Latin America's largest pharmaceutical market. The Southeast region anchors decompensated cirrhosis management capacity expansion.
India
Specialized contract manufacturers concentrated in Hyderabad and Ahmedabad produce nucleotide analogue active pharmaceutical ingredients, exposing supply continuity to geopolitical friction. CDSCO oversight of hepatitis B chronic suppressive therapy generates recurring revenue streams in high-prevalence markets. The western pharmaceutical corridor deepens backward integration into hepatotoxicity-related structural alert chemistry.
Global Liver Diseases Therapeutics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with nucleotide analogue portfolios and immunology platforms defining the upper stratum. The mid-market contains biologics manufacturers and small-molecule specialists separated by widening capital-intensity requirements. Two archetypes dominate: diversified pharmaceutical conglomerates with hepatology adjacencies, and pure-play antiviral developers with nucleic acid chemistry expertise. Competitive moves center on checkpoint inhibitor pipeline expansion into hepatocellular carcinoma and RNA interference platform licensing for NASH indications.
Within the integrated pharmaceutical tier, Gilead Sciences, AbbVie, and Bristol-Myers Squibb occupy positions that exemplify divergent strategic anchors. Gilead Sciences represents the nucleotide analogue specialist archetype with sustained hepatitis B and C antiviral segment presence. AbbVie exemplifies the immunology platform extender, leveraging autoimmune condition expertise into liver disease adjacencies. Bristol-Myers Squibb anchors the oncology-crossover position, with checkpoint inhibitor development targeting hepatocellular carcinoma. These three entities collectively illustrate how therapeutic modality concentration, rather than geographic origin, determines tier placement in this market.
| Leading Market Players |
|---|
| Gilead Sciences |
| AbbVie |
| Bristol-Myers Squibb |
| F. Hoffmann-La Roche |
| Takeda Pharmaceutical |
| Johnson & Johnson |
| Merck & Co. |
| Novartis |
| Pfizer |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts for nucleotide analogue active pharmaceutical ingredients lock in supply access for antiviral manufacturers while anchoring price visibility across multi-year procurement cycles. These agreements concentrate purchasing power among integrated delivery systems in the United States and academic medical center networks in Germany, compressing margin buffers for specialty clinic dispensers.
Pricing Analysis
Therapeutic drug monitoring service bundles drive lifetime value for immunosuppressant franchises in transplant maintenance settings. Three-tier pricing structure across premium, standard, and economy levels separates calcineurin inhibitor brands with proprietary pharmacogenomic support from generic alternatives with basic monitoring. Cost compression in hepatitis C direct-acting antiviral regimens is intensifying because cure-rate saturation eliminates recurring revenue pools. Medicaid populations in the United States exhibit acute price sensitivity for antiviral therapy, while South Korean and Taiwanese buyers demonstrate minimal elasticity for chronic hepatitis B nucleos(t)ide analogue therapy.
Supply Chain Analysis
India and China anchor nucleotide analogue active pharmaceutical ingredient production, with specialized contract manufacturers concentrated in Hyderabad, Ahmedabad, and eastern coastal provinces. These facilities draw from pyrimidine base precursors, phosphorylating reagents, and chiral resolution catalysts as critical inputs. Single-source vulnerability for specialized synthesis capabilities exposes continuity to geopolitical friction in active pharmaceutical ingredient trade. Distribution runs through health-system-owned specialty pharmacy carve-outs in Texas, Florida, and California transplant center networks, displacing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where FDA black-box labeling requirements and EMA pharmacovigilance protocols erect substantial compliance barriers against new antiviral and antifibrotic entrants.
For Market Incumbents: Fortify nucleotide analogue portfolios through backward integration into active pharmaceutical ingredient synthesis in India to mitigate supply disruption risk from geopolitical friction. Deepen therapeutic drug monitoring infrastructure partnerships with academic medical center transplant networks across Germany and Japan to cement immunosuppressant switching costs against biosimilar pressure. For New Entrants and Emerging Players: FDA breakthrough therapy designation fast-track opens priority review pathways for novel antifibrotic mechanisms targeting nonalcoholic steatohepatitis with robust histological endpoint data. White-space concentration exists in RNA interference platform development for metabolic liver disease, with investigator-initiated trial partnerships at German and United States academic medical centers offering credible entry positioning. Go-to-market execution should prioritize formulary access negotiations with integrated delivery systems before commercial launch. For Investors and Strategic Acquirers: Pure-play nucleic acid chemistry specialists with Phase III NASH assets represent the most attractive acquisition target archetype given modality convergence and regulatory pathway clarity. Long-term viability favors sponsors with pre-registered legacy chemical entities under REACH, as ECHA environmental fate scrutiny intensifies for novel hepatotoxicity-related structural alerts. The inflection signal to watch is biomarker validation for non-invasive fibrosis staging, which would expand addressable patient populations beyond biopsy-limited cohorts.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase III NASH programs with histological endpoints satisfy elevated FDA and EMA standards. |
| Regulatory Approval Pathway | PMDA Sakigake designation unlocks priority positioning in Japan's premium pricing environment. |
| Licensing Agreement | RNA interference platform partnerships fragment payer formulary strategies across mechanism categories. |
| Manufacturing Scale-Up | Backward integration into nucleotide analogue synthesis mitigates India-China supply concentration risk. |
| Pipeline Diversification | Checkpoint inhibitor expansion into hepatocellular carcinoma leverages oncology infrastructure. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases through structured interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Bottom-up patient-volume modeling and top-down revenue triangulation validate segment-level outputs.
Segmentation dimensions modeled span treatment line, dosage form, administration route, patient population, and regional regulatory cluster across the analysis window. CAGRs derive from epidemiological prevalence projections, pricing elasticity assumptions, and therapy penetration curves. Forecast inputs incorporate biopsy-confirmed nonalcoholic steatohepatitis diagnosis rates and transplant waitlist dynamics.
Decision-makers should treat outputs as directional under base assumptions of stable regulatory endpoint standards and continued nucleotide analogue supply continuity; material deviation in FDA histological requirements or India-China trade friction would warrant model refresh. Recalibration cycles align with material shifts in NASH biomarker validation and antifibrotic mechanism approvals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Loxoprofen Market
Pharmaceuticals
Asia-Pacific Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
US Sex Reassignment Hormone Therapy Market
Pharmaceuticals
Global Divalproex Sodium Market
Pharmaceuticals
Unfractionated Heparin Market
Pharmaceuticals
Marburg Virus Disease Therapeutics Market
Pharmaceuticals
G Protein Coupled Receptors (Gpcrs) Market
Pharmaceuticals
Antidiuretic Drugs Market
Pharmaceuticals
Global Narcolepsy Drugs Market
Pharmaceuticals
Quinolones Market
Pharmaceuticals
Myasthenia Gravis Therapeutics Market
Pharmaceuticals
Global Antipsychotic Drugs Market
Pharmaceuticals
Authorized Generics Market
Pharmaceuticals
Emergency Contraceptive Pills Market
Pharmaceuticals
Malaysia Oral Anti-Diabetic Drug Market
Pharmaceuticals
Global Seasonal Influenza Vaccines Therapeutics Market