
 Aramid Prepreg Market | 2026-2036
Aramid Prepreg Market Size, Share, and Industry Trends Forecast 2026-2036
Aramid Prepreg Market Analysis
Market Context with Strategic Players
Defense procurement agencies is unwinding legacy carbon-fiber contracts in favor of aramid solutions for ballistic protection. DuPont de Nemours anchors North American supply through captive Kevlar precursor production and downstream prepreg conversion. Teijin Limited dominates Asian defense channels with Twaron-based prepregs certified to multiple national armor standards. Hexcel Corporation competes in aerospace-grade segments where aramid-epoxy hybrids replace heavier metallic assemblies in rotorcraft and unmanned platforms.
Technical Definition and Structural Segments
Aramid prepreg consists of aromatic polyamide fibers pre-impregnated with thermoset resin matrices, typically epoxy or phenolic formulations cured under controlled temperature and pressure cycles to achieve specific areal densities and ballistic performance ratings. These materials serve primary industrial functions in impact-resistant structures, thermal barriers, and lightweight load-bearing assemblies where strength-to-weight ratios exceed conventional metals. Unidirectional configurations lead defense armor applications due to superior energy absorption along fiber axes, while fabric and woven forms capture expanding automotive penetration as OEMs seek crash-structure mass reduction without sacrificing occupant protection. Preformed shapes remain nascent but attract margin concentration from custom military vehicle retrofits requiring complex geometric conformance.
Regulatory Frame and Forward-Looking Close
FDA oversight governs aramid fiber biocompatibility claims in emerging medical device applications, while EPA emission standards constrain solvent-based resin impregnation processes at US manufacturing facilities. REACH registration requirements in Europe force reformulation of legacy phenolic systems, and ISO ballistic certification protocols determine market access for armor suppliers bidding on NATO tender programs. Stakeholders must monitor evolving dual-use export control classifications that could restrict aramid prepreg shipments to non-allied defense customers.
Market Dynamics
NATO armor modernization programs are compressing qualification timelines for aramid prepreg suppliers, forcing simultaneous compliance with REACH chemical safety mandates and ISO ballistic certification protocols.
Growth Catalysts
- REACH registration mandates:ECHA precursor handling requirements are accelerating reformulation of legacy phenolic resin systems toward lower-emission alternatives that qualify for EU defense tenders.
- Rotorcraft lightweighting:Aerospace OEMs are specifying aramid-epoxy hybrids to replace metallic assemblies in unmanned platforms and military helicopters, expanding addressable volume beyond traditional armor.
- German procurement acceleration:The Bundeswehr's personnel protection system upgrades are concentrating demand for unidirectional aramid configurations certified to STANAG ballistic standards.
Market Restraints
- Precursor supply concentration:Captive para-aramid fiber production by dominant chemical conglomerates limits independent prepreg converter access to Kevlar and Twaron feedstock.
- Phenolic resin volatility:Formaldehyde pricing fluctuations and EPA emission constraints on solvent-based impregnation processes compress margin predictability at US manufacturing facilities.
- UHMWPE substitution threat:Ultra-high molecular weight polyethylene composites are displacing aramid in select maritime and vehicle armor applications where weight reduction outweighs thermal performance requirements.
Strategic Opportunities
- Automotive crash structures:European OEMs are qualifying woven aramid prepregs for electric vehicle battery enclosure protection, creating volume outside defense contracting cycles.
- Medical device biocompatibility:FDA 510(k) pathways for implantable aramid mesh are opening procedural markets in hernia repair and soft tissue reconstruction.
- Preformed shape customization:Military vehicle retrofit programs requiring complex geometric conformance are attracting margin concentration from specialized fabrication capabilities.
Industry Challenges
- Dual-use export control navigation:Evolving Wassenaar Arrangement classifications restrict aramid prepreg shipments to non-allied defense customers, complicating international sales compliance.
- ISO ballistic certification timelines:Multi-year qualification protocols for NATO tender eligibility delay revenue recognition for new prepreg formulations and fiber-resin combinations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aramid Prepreg Market |
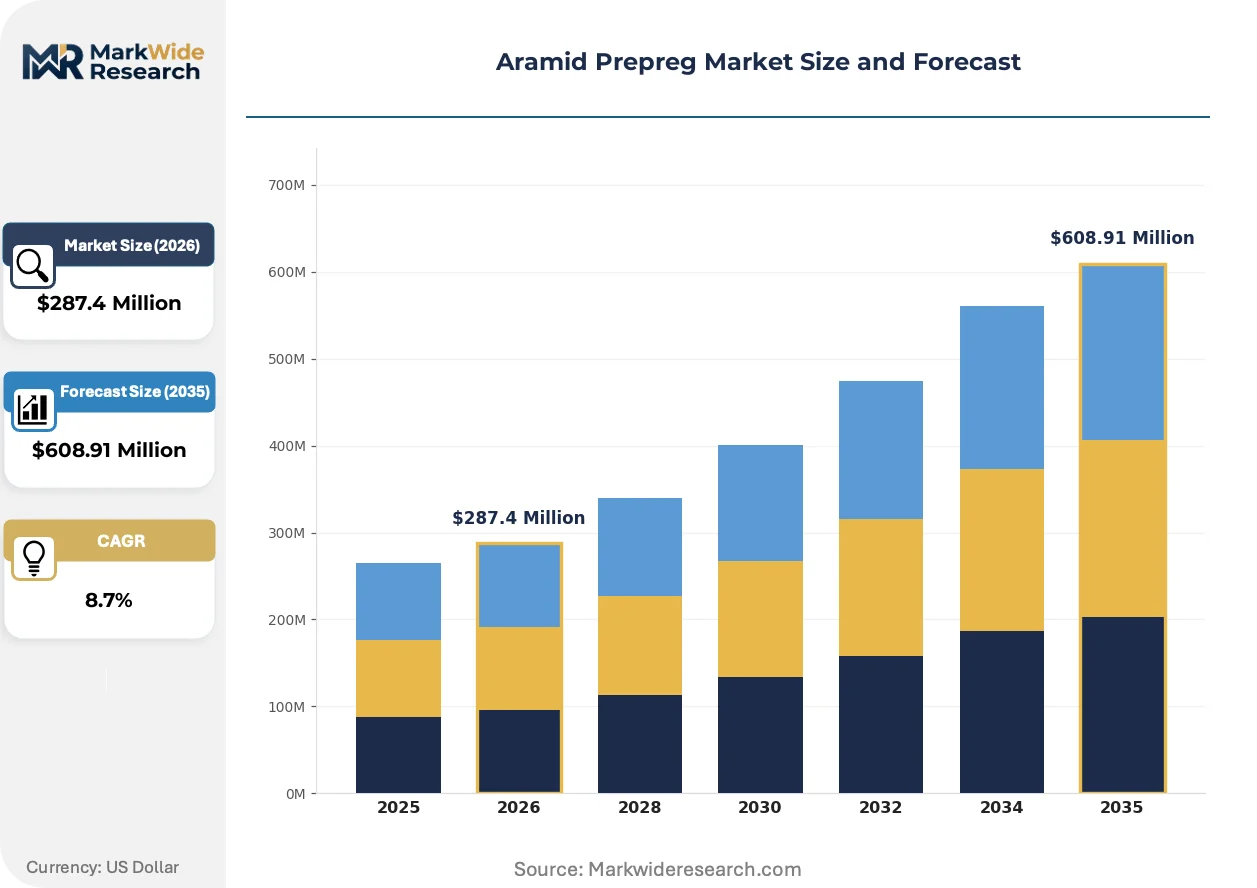
| Market Size in 2026 | $287.4 Million |
| Market Size in 2035 | $608.91 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unidirectional, Fabric, Preformed Shapes, Woven End Use Industry: Aerospace, Defense, Automotive, Wind Energy Form: Sheet, Roll, Panel, Custom Shapes Application: Structural Components, Armor, Insulation, Composites |
| Companies Covered | Hexcel Corporation, Mitsubishi Chemical Holdings, DuPont de Nemours, Kolon Industries, Gurit Holding AG, Teijin Limited, Solvay S.A., SGL Carbon SE, Toray Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aramid Prepreg Market Emerging Trajectories
Active reformulation of thermoset matrices and compression of fiber-resin interface engineering cycles are reshaping how aramid prepregs qualify for next-generation protection systems.
Out-of-autoclave curing systems are miniaturizing production footprints for aramid-epoxy prepregs. Tier-2 armor fabricators in Poland and the Czech Republic are adopting these systems to bypass capital-intensive autoclave investments. This diffusion is compressing geographic supply concentration and enabling regional qualification for NATO secondary supplier programs.
EU Green Deal chemical safety mandates are forcing phenolic resin suppliers to eliminate formaldehyde emissions from impregnation lines. German prepreg converters near Stuttgart and Hamburg are retrofitting solvent recovery systems to maintain REACH compliance. Defense armor segments face the steepest reformulation costs due to legacy ballistic performance baselines established under older resin systems.
Specification consolidation among prime defense contractors is compressing supplier qualification cycles. French and UK procurement agencies now require simultaneous STANAG and NIJ certification for cross-border tender eligibility. This dual-standard burden favors prepreg houses with existing multi-jurisdictional testing relationships, squeezing smaller regional converters from high-value armor contracts.
Aramid Prepreg Market Segmentation
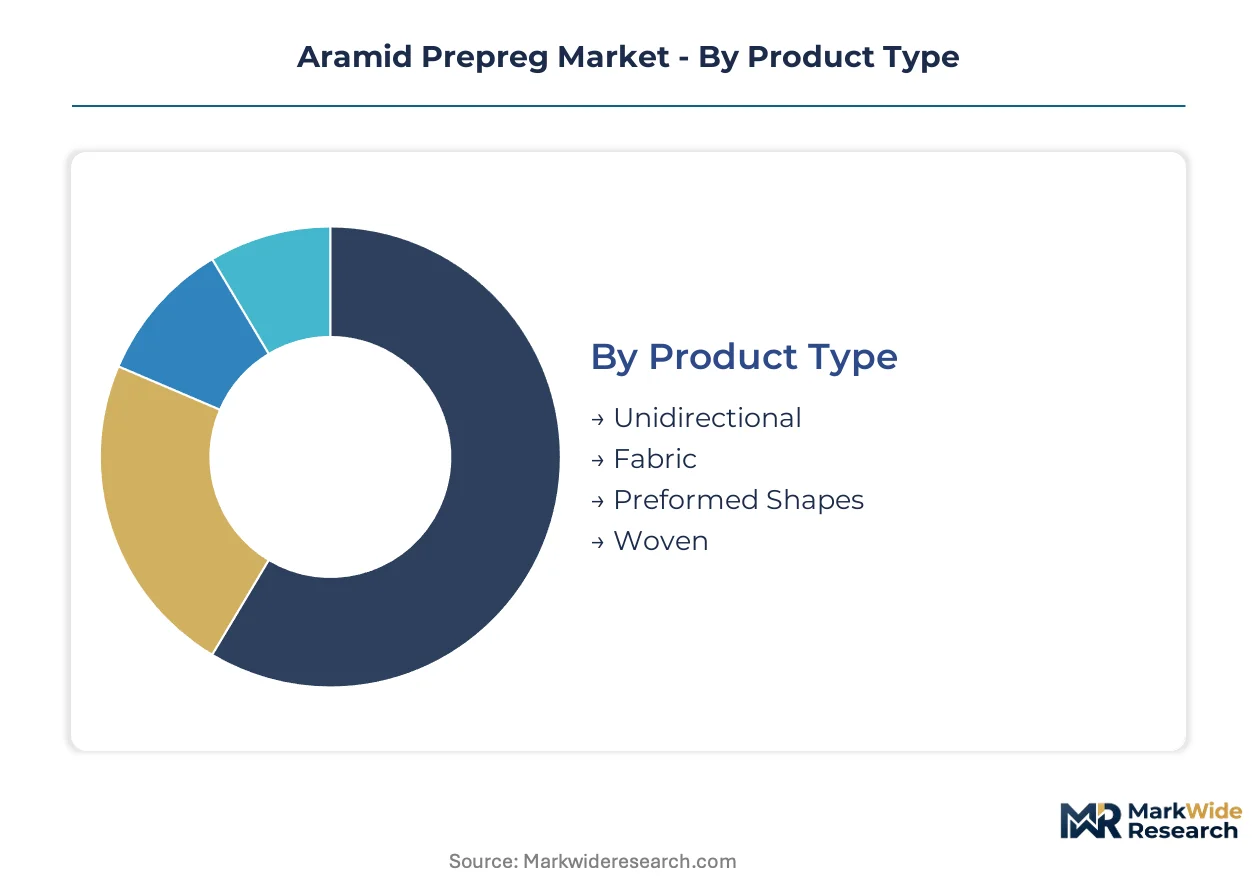
Aramid prepreg demand fragments across fiber architectures, end-use specifications, and delivery formats. Channel strategies diverge sharply between defense procurement programs and commercial industrial accounts.
Product Type:
Unidirectional configurations flow primarily through prime defense contractors, while woven and fabric forms serve tier-2 automotive suppliers through distributors.
- Unidirectional:Fibers align in a single axis with resin pre-impregnation optimized for ballistic energy absorption along the primary load path. Bundeswehr and French procurement agencies concentrate orders here for personnel armor plates meeting STANAG 4569 standards. REACH-mandated phenolic reformulation is compressing supplier margins in this channel.
- Fabric:Multi-axial fiber arrangements provide conformability for complex geometries in rotorcraft fairings and unmanned aerial vehicle structures. Aerospace OEMs in Germany and the United Kingdom specify fabric prepregs for secondary structural assemblies where damage tolerance outweighs maximum stiffness.
- Preformed Shapes:Near-net configurations for military vehicle retrofits requiring minimal post-cure machining.
- Woven:Interlaced fiber architectures supplying automotive crash structures and battery enclosure protection.
By volume, Fabric leads. By growth pace, Woven is ahead.
End Use Industry:
Cost tiers separate defense prime contracting from commercial segments, with aerospace occupying a mid-tier premium position.
- Defense:Ballistic protection systems absorb the majority of para-aramid fiber output. NATO armor modernization programs in Germany, France, and the United Kingdom are compressing qualification timelines. Dual-use export controls under the Wassenaar Arrangement restrict shipment flexibility to non-allied customers.
- Aerospace:Aramid-epoxy hybrids replace metallic assemblies in helicopter rotor hubs and unmanned platform structures. Lighter weight drives specification in applications where thermal performance must coexist with fatigue resistance.
- Automotive:European OEMs qualify woven prepregs for electric vehicle battery enclosures and crash-absorbing structures.
- Wind Energy:Blade root reinforcements and lightning strike protection layers specify aramid for dielectric properties.
Defense commands the dominant revenue share. Automotive is climbing the fastest as electrification accelerates mass-reduction targets.
Form:
Volume scale distinguishes roll-format supply for continuous processing from panel and custom configurations serving project-based demand.
- Roll:Continuous-format supply enables automated tape laying and fiber placement in aerospace manufacturing. Airbus Helicopters and BAE Systems facilities in Germany and the United Kingdom specify roll formats for production-rate rotorcraft programs.
- Sheet:Discrete flat stock for hand lay-up armor fabrication and prototype development. Polish and Czech tier-2 armor houses source sheet formats for NATO secondary supplier qualification.
- Panel:Cured or semi-cured rigid plates for direct integration into vehicle hulls and structural assemblies.
- Custom Shapes:Geometrically complex preforms for military vehicle retrofits requiring minimal post-machining.
Roll formats dominate throughput. Custom Shapes yield the highest per-kilogram margins.
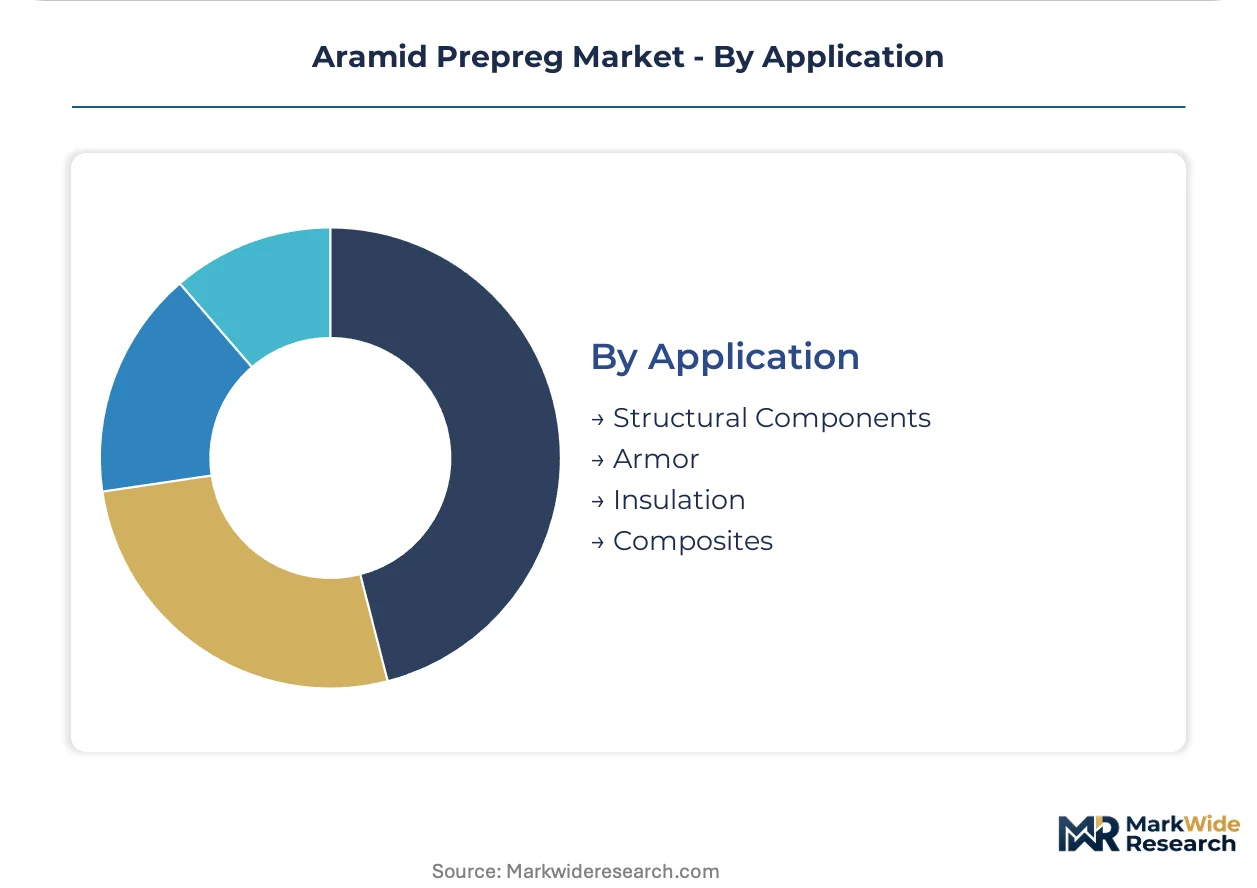
Application:
Customer type separates specification-grade armor and structural markets from industrial insulation accounts.
- Armor:Personnel and vehicle protection systems requiring ISO and STANAG ballistic certification. German and French procurement agencies mandate simultaneous multi-jurisdictional testing, favoring prepreg houses with established laboratory relationships.
- Structural Components:Load-bearing assemblies in rotorcraft, unmanned platforms, and select automotive chassis elements. Strength-to-weight ratios exceed aluminum alternatives in fatigue-critical locations.
- Insulation:Thermal and electrical barrier layers in industrial equipment and aerospace engine compartments.
- Composites:Hybrid material systems combining aramid with carbon or glass fibers for tailored property profiles.
Armor generates the largest absolute volume. Structural Components are expanding most quickly as aerospace lightweighting accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German prepreg converters supply NATO armor programs across Poland, the Czech Republic, and the Baltic states, establishing a procurement corridor that channels REACH-compliant formulations eastward toward secondary defense markets.
United States
Defense procurement agencies drive volume through Kevlar-based personnel protection systems. EPA emission standards constrain solvent-based resin impregnation at manufacturing facilities in Virginia and South Carolina. DuPont de Nemours anchors supply from Delaware through captive para-aramid fiber production and downstream prepreg conversion.
Germany
Bundeswehr armor modernization concentrates demand for unidirectional configurations meeting STANAG 4569 standards. REACH registration mandates force reformulation of legacy phenolic systems toward lower-emission alternatives. Stuttgart and Hamburg industrial clusters host prepreg converters retrofitting solvent recovery systems to maintain ECHA compliance.
France
French procurement agencies require simultaneous STANAG and NIJ certification for cross-border tender eligibility. EU Green Deal chemical safety mandates tighten precursor handling requirements at manufacturing facilities near Lyon and Toulouse. Prime defense contractors compress supplier qualification cycles, favoring prepreg houses with multi-jurisdictional testing relationships.
United Kingdom
BAE Systems and Airbus Helicopters facilities specify roll-format aramid-epoxy hybrids for rotorcraft production. ISO ballistic certification protocols determine market access for armor suppliers bidding on NATO tender programs. Aerospace clusters in the Midlands and Southwest England drive qualification of fabric prepregs for unmanned platform structures.
Japan
Teijin Limited dominates regional defense channels with Twaron-based prepregs certified to multiple national armor standards. METI industrial policy supports lightweight material adoption in aerospace applications. Nagoya and Osaka manufacturing bases supply aramid-epoxy hybrids for helicopter rotor hubs and secondary structural assemblies.
Aramid Prepreg Market Vendor Landscape
Player mix skews toward vertically integrated chemical conglomerates controlling captive fiber supply. The market structure concentrates around para-aramid precursor producers who internalize downstream prepreg conversion. Three archetypes dominate: fiber-origin majors with in-house resin formulation, independent converters dependent on merchant fiber supply, and aerospace-specialized composites houses. Competitive moves center on REACH-compliant resin reformulation and out-of-autoclave curing system adoption.
Within the fiber-origin tier, DuPont de Nemours, Teijin Limited, and Kolon Industries exemplify the integrated model. DuPont de Nemours occupies a position anchored in North American defense procurement through Delaware-based Kevlar production. Teijin Limited sits within the Asian defense channel, representing the Twaron-based supply archetype. Kolon Industries anchors Korean output, exemplifying regional concentration in para-aramid fiber manufacturing.
| Leading Market Players |
|---|
| Hexcel Corporation |
| Mitsubishi Chemical Holdings |
| DuPont de Nemours |
| Kolon Industries |
| Gurit Holding AG |
| Teijin Limited |
| Solvay S.A. |
| SGL Carbon SE |
| Toray Industries |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between NATO procurement agencies and German prepreg converters lock in para-aramid fiber access while anchoring price visibility across multi-year armor modernization programs. These arrangements insulate prime defense contractors from formaldehyde resin volatility but expose tier-2 suppliers to spot-market phenolic pricing swings.
Pricing Analysis
Next-generation out-of-autoclave curing systems command a 15-20% premium over legacy autoclave-dependent formulations, compressing the technology-generation pricing gap as Polish and Czech fabricators adopt miniaturized production footprints. Three-tier pricing structure across STANAG-certified premium, NIJ-standard mid-tier, and uncertified economy levels segments buyer access, with automotive OEMs driving the most aggressive price negotiation for woven battery enclosure materials. Cost compression in phenolic resin systems is intensifying because REACH-mandated formaldehyde elimination forces reformulation investment recovery through higher unit pricing. Defense primes exhibit the lowest price sensitivity due to mission-critical ballistic performance requirements, while tier-2 automotive suppliers demonstrate acute elasticity to per-kilogram quotes.
Supply Chain Analysis
Strategic stockpiling of para-aramid fiber by DuPont de Nemours and Teijin Limited contrasts with just-in-time resin sourcing by independent European converters, creating inventory-strategy divergence between captive fiber producers and merchant-dependent fabricators. Raw material flows concentrate through the United States, Germany, and Japan, with para-aramid precursor production, epoxy resin formulation, and phenolic hardener supply anchoring regional supply clusters. Single-source vulnerability pervades Kevlar and Twaron fiber access, as independent prepreg converters lack backward integration into aromatic polyamide polymerization. Distribution runs through prime defense contractor direct procurement for unidirectional armor configurations, while woven automotive grades channel through technical distributors serving tier-2 OEM suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in ballistic certification consulting and STANAG compliance advisory are expanding faster than base prepreg hardware sales, as NATO procurement agencies outsource multi-jurisdictional testing navigation to specialized technical partners.
For Market Incumbents: Shield market position by deepening captive fiber-to-prepreg integration and accelerating REACH-compliant phenolic reformulation ahead of regulatory deadlines. UHMWPE substitution in maritime armor applications threatens aramid volume retention, making ISO 9001 quality management certification and STANAG 4569 test house relationships critical defensive levers against displacement. For New Entrants and Emerging Players: Aftermarket technical support for military vehicle retrofit programs represents a service-layer gap where incumbents under-serve, offering white-space entry through preformed shape engineering and geometric conformance consulting. Electric vehicle battery enclosure protection in European automotive qualifies as the most penetrable segment, with qualification support services and crash-structure simulation capabilities providing differentiated go-to-market positioning against commodity woven suppliers. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale converters with established multi-jurisdictional testing relationships and out-of-autoclave curing capabilities, as these assets command premium multiples in a consolidating supplier landscape. Long-term viability across the analysis window rests on REACH compliance infrastructure and NATO secondary supplier program eligibility. Watch for Bundeswehr procurement acceleration announcements as the primary inflection indicator for German production cluster capacity utilization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Para-Aramid Fiber Production | Captive Kevlar or Twaron supply eliminates merchant fiber dependency and secures margin control. |
| REACH-Compliant Phenolic Reformulation | ECHA registration compliance opens EU defense tender access while legacy systems face exclusion. |
| Out-of-Autoclave Curing System Adoption | Polish and Czech tier-2 fabricators bypass capital-intensive autoclave investments through miniaturized production. |
| Multi-Jurisdictional Testing Relationship Expansion | Simultaneous STANAG and NIJ certification capability meets French and UK cross-border tender requirements. |
| Preformed Shape Customization Capability Buildout | Military vehicle retrofit programs yield highest per-kilogram margins through complex geometric conformance. |
Methodological Framework
Desk research of ECHA REACH registration databases, NATO tender documentation, and SEC 10-K filings from listed chemical conglomerates preceded structured interviews with defense procurement officers, prepreg plant managers, technical R&D directors at fiber producers, and tier-2 armor fabricators. Primary fieldwork combined with secondary validation through customs trade data and industry association reports enabled bottom-up volume triangulation against top-down defense budget allocation analysis.
Variance decomposition across fiber architecture, resin matrix type, and end-use certification tier shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include unidirectional versus woven configurations, epoxy versus phenolic resin systems, and defense versus automotive versus aerospace demand clusters. CAGRs derived from production capacity expansion announcements, procurement contract visibility, and substitution elasticity estimates for UHMWPE alternatives.
Forecasts assume regulatory continuity in EU REACH enforcement and Wassenaar Arrangement dual-use export classifications; material policy shifts would require re-modeling. Revision becomes warranted when Bundeswehr or French procurement acceleration crosses threshold visibility into firm order placement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Lithium Nitride Market
Advanced Alloys
Global Ti-6Al-4V Titanium Alloy Market
Advanced Alloys
Medium Entropy Alloys Market
Advanced Alloys
Global Metal Injection Molding Market
Advanced Alloys
Prepreg Market
Advanced Alloys
Maraging Steel Market
Advanced Alloys
High Temperature Alloys Market
Advanced Alloys
Europe Aluminum Casting Market
Advanced Alloys
Brazing Alloys Market
Advanced Alloys
Forgings Market
Advanced Alloys
Soft Magnetic Material for Electric Vehicle Market
Advanced Alloys
Plastic-Metal Hybrids Market
Advanced Alloys
Global Amorphous Alloy Band Market
Advanced Alloys
Nitinol Market
Advanced Alloys
Europe Ceramic Ball Bearings Market
Advanced Alloys
Global Metal Foams Market