
 Nitinol Market | 2026-2036
Nitinol Market Size, Share, and Industry Trends Forecast 2026-2036
Nitinol Market Foresight
Minimally invasive surgical device OEMs is bifurcating demand away from traditional open-surgery instrument suppliers. Fort Wayne Metals leverages captive melt-to-wire verticality to control titanium-nickel ingot sourcing for catheter components. Cook Medical sustains leadership in self-expanding stent grafts through proprietary tube-drawing operations in Indiana. Abbott Laboratories differentiates via superelastic wire architectures optimized for structural heart closure devices.
Nitinol, a near-equiatomic intermetallic alloy of nickel and titanium, exhibits thermoelastic martensitic transformation enabling shape recovery above its austenite finish temperature and superelastic strain recovery up to 8%. Manufacturers produce it through vacuum induction melting followed by hot working and cold drawing with intermediate anneals to achieve precise transformation temperatures. Medical Devices applications dominate value capture due to premium pricing for implant-grade material with full lot traceability. Wires command the largest volume position across product types, while Tubes generate superior margins in neurovascular and peripheral vascular catheter platforms. Superelastic Alloys technology leads commercial shipments, though Hybrid Alloys formulations are gaining traction in robotics actuators requiring tunable stiffness profiles.
FDA enforces Quality System Regulation and biocompatibility testing per ISO 10993 for nitinol implants, while EU MDR mandates notified body review of material composition and fatigue performance for CE marking. Japan's PMDA requires additional nickel ion release validation for long-term implantable devices, creating a multi-jurisdiction compliance burden for suppliers. Stakeholders must monitor evolving fatigue testing protocols and dual-carbon sourcing requirements as regulators tighten material provenance standards without harmonizing test methodologies across agencies.
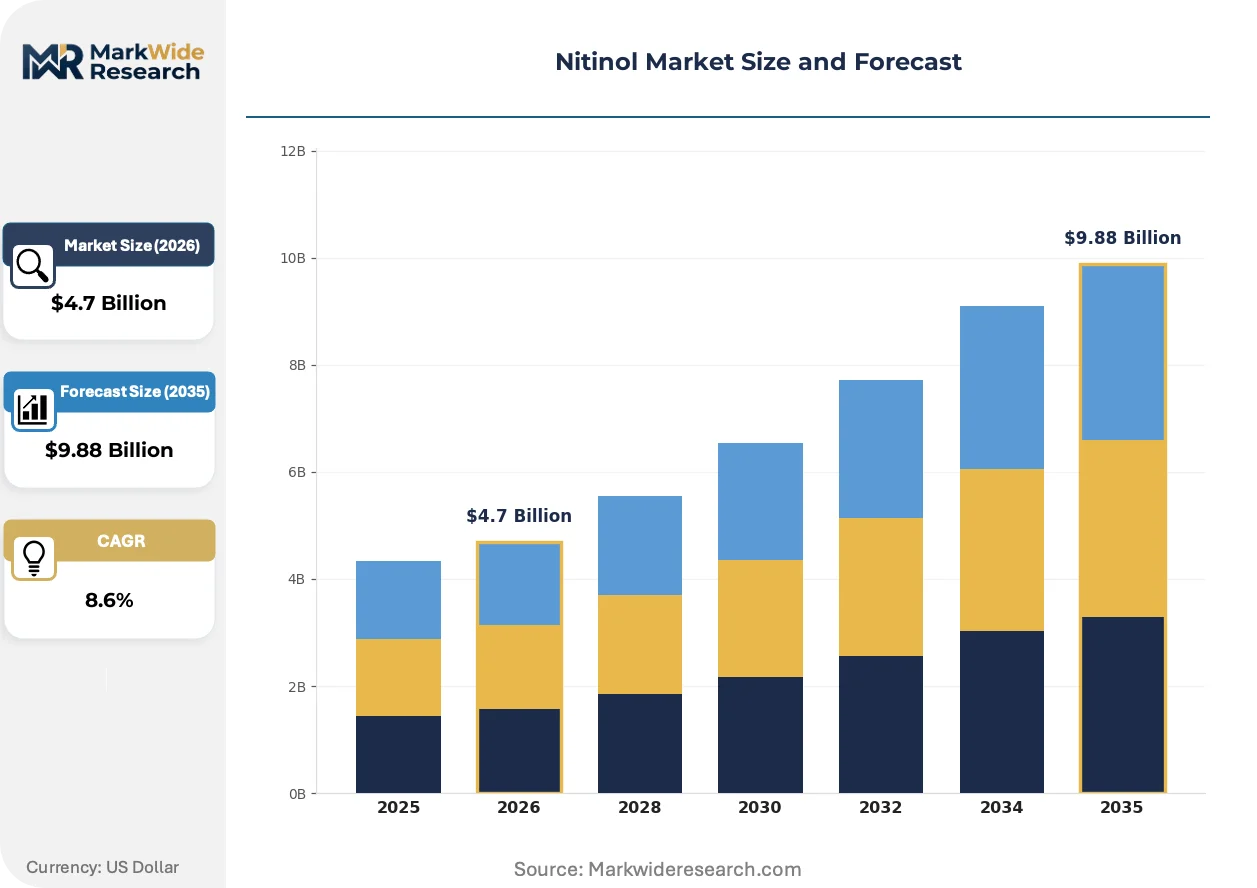
Market Dynamics
Orthopedic implant manufacturers are consolidating procurement around superelastic tubing suppliers capable of delivering full lot traceability under tightening FDA Quality System Regulation and EU MDR conformity pathways. This concentration pressure is compressing vendor bases while elevating technical qualification barriers.
Growth Catalysts
- EU MDR material traceability mandates:Implant-grade alloy suppliers with certified vacuum induction melting capabilities capture premium positioning as notified body scrutiny intensifies.
- Minimally invasive spine procedures:Superelastic nitinol tubing enables smaller access ports and reduced tissue trauma, driving replacement of conventional stainless steel instruments.
- Hybrid alloy robotics actuators:Tunable stiffness formulations from dual-phase microstructures expand addressable applications beyond medical into industrial automation.
Market Restraints
- Nickel price volatility:Near-equiatomic titanium-nickel compositions expose producers to London Metal Exchange nickel contract swings and Russian supply disruption risks.
- Indiana-centered tube drawing concentration:Self-expanding stent graft component supply chains cluster in a single U.S. state, creating geographic vulnerability.
- 8% superelastic strain ceiling:Thermoelastic martensitic transformation limits recoverable deformation versus competing polymer alternatives in high-flex catheter applications.
Strategic Opportunities
- Japan PMDA nickel ion release pathway:Validated low-leach formulations for long-term implantables open a regulatory moat against unqualified competitors.
- Structural heart closure devices:Optimized wire architectures for left atrial appendage occluders and septal defect repair expand cardiac intervention penetration.
- Digital twin process modeling:Finite element simulation of cold drawing with intermediate anneals reduces development cycles for patient-specific transformation temperatures.
Industry Challenges
- Vacuum metallurgy talent scarcity:Specialized melt-to-wire process engineers with titanium-nickel intermetallic expertise command premium compensation and limited availability.
- Dual-carbon sourcing verification:Smelter energy provenance documentation requirements under emerging supply chain disclosure rules strain legacy procurement systems.
- Fatigue test protocol divergence:Non-harmonized cyclic loading methodologies across FDA, PMDA, and EU MDR create redundant validation burdens without equivalent safety assurance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nitinol Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wires, Tubes, Sheets, Foils Application: Medical Devices, Actuators, Robotics, Aerospace End User: Hospitals, Manufacturers, Research Institutes, Aerospace Companies Technology: Shape Memory Alloys, Superelastic Alloys, Hybrid Alloys, Others |
| Companies Covered | Fort Wayne Metals, W. L. Gore & Associates, Abbott Laboratories, Cook Medical, Zimmer Biomet Holdings, Boston Scientific Corporation, Terumo Corporation, Arthrex, Medtronic plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nitinol Market Shifts & Advancements
Additive manufacturing of nitinol lattice structures is reshaping orthopedic implant design by enabling patient-specific pore architectures and reduced material waste. This fabrication shift compresses traditional forging and machining supply chains while demanding new powder qualification protocols.
Laser powder bed fusion is decomposing conventional wrought processing for complex geometries in cranial and maxillofacial plates. Device OEMs in structural heart and neurovascular segments are qualifying electron beam melted components for reduced lead times. The technology is decomposing multi-step tube-drawing and wire-drawing workflows into single-build near-net-shape production, though surface finish and transformation temperature control remain qualification hurdles.
EU MDR Annex I general safety and performance requirements are forcing recertification of legacy implant designs with enhanced biological evaluation documentation. Notified bodies now demand explicit fatigue performance data under simulated physiological loading conditions. Peripheral vascular stent manufacturers are responding by consolidating supplier audits and requiring ISO 10993-5 cytotoxicity and ISO 10993-10 irritation testing at the raw material stage rather than finished device.
Hospital procurement departments are unbundling after-sales technical support from material supply contracts, treating nitinol wire and tubing as commodity inputs with separate metallurgical consulting fees. This disintermediation pressures traditional full-service distributors and accelerates direct manufacturer-to-OEM relationships. The shift is most pronounced in United States orthopedic clusters where group purchasing organizations centralize negotiations across multiple hospital systems.
Nitinol Market Segmentation
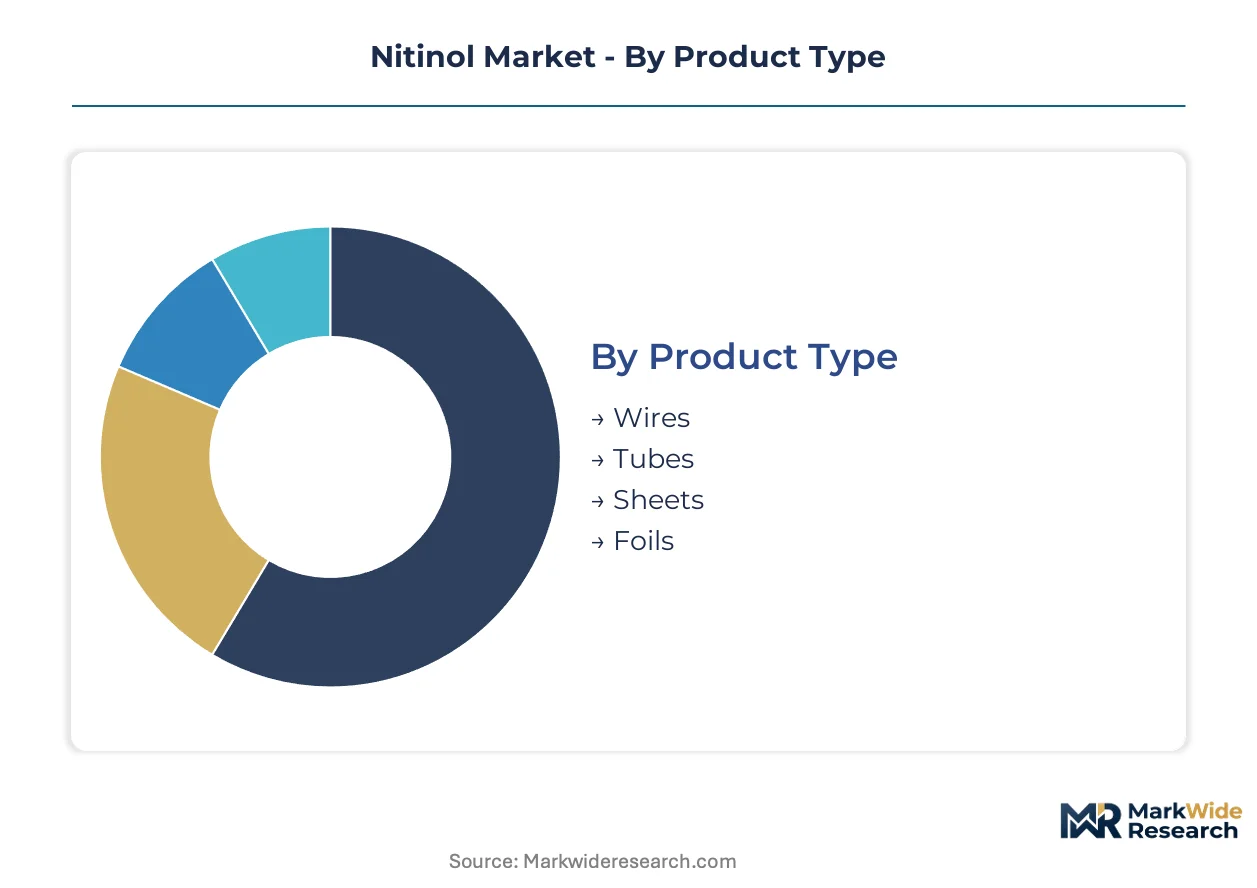
Nitinol's thermoelastic martensitic transformation creates distinct performance profiles across product geometries, forcing OEMs to match alloy specifications precisely to device mechanics. Segmentation reveals where polymer and cobalt-chrome substitutes exert pressure versus where nitinol maintains irreplaceable positioning.
Product Type:
Polymer catheter shafts and laser-cut hypotubes are displacing nitinol in cost-sensitive neurovascular delivery systems, yet superelastic recovery requirements protect wire and tube dominance in structural heart and orthopedic anchors.
- Wires:Cold-drawn round and flat configurations deliver 8% recoverable strain for guidewires, closure devices, and orthodontic archwires. Demand concentrates in United States structural heart clusters where Abbott Laboratories and Boston Scientific specify precise transformation temperatures for septal occluders. Nickel price volatility compresses margins on commodity wire grades.
- Tubes:Seamless superelastic tubing enables self-expanding stent grafts and minimally invasive spine retractors through controlled Af temperatures and wall thickness uniformity. Cook Medical's Indiana tube-drawing operations anchor procurement for peripheral vascular OEMs seeking full lot traceability under FDA Quality System Regulation.
- Sheets:Rolled plate stock serves craniomaxillofacial fixation plates and experimental robotics laminates.
- Foils:Ultra-thin gauge material under 0.1 mm enables micro-actuator diaphragms and thermal switch elements.
Wires retain volume leadership; tubes hold the steepest expansion curve.
Application:
Cost tier stratification separates premium implant-grade medical demand from industrial actuator volumes where nickel-titanium competes against shape memory polymers and piezoelectric ceramics.
- Medical Devices:Implant-grade vacuum induction melted material commands premium pricing for cardiovascular stents, orthopedic anchors, and dental archwires. EU MDR Annex I fatigue performance requirements and ISO 10993 biocompatibility testing create qualification moats against lower-grade suppliers. Japan's PMDA nickel ion release validation adds further regulatory burden for long-term implantables.
- Actuators:Thermal and electrical activation mechanisms deploy in automotive valves and HVAC controls where transformation temperature precision matters less than cost efficiency. Competing shape memory polymers undercut nitinol on price in consumer appliance applications.
- Robotics:Tunable stiffness hybrid alloys enable soft robotic grippers and surgical instrument articulation requiring variable compliance.
- Aerospace:High-cycle fatigue couplings and thermal isolation mounts exploit superelastic damping in satellite deployment mechanisms and morphing wing structures.
Medical Devices dominates value capture; Robotics shows the fastest volume gain trajectory.
End User:
Procurement concentration among United States group purchasing organizations is forcing direct manufacturer relationships, disintermediating traditional distributors serving smaller research and aerospace accounts.
- Hospitals:Academic medical centers and specialty cardiac hospitals drive demand for patient-specific implantable devices with certified material provenance. Hospital procurement departments increasingly unbundle metallurgical consulting from material supply contracts.
- Manufacturers:Device OEMs in Minnesota, Indiana, and Massachusetts constitute the primary demand anchor for implant-grade wire and tube with full vacuum induction melting traceability.
- Research Institutes:National laboratories and university engineering departments purchase experimental alloy formulations for next-generation actuator and robotics prototyping.
- Aerospace Companies:Prime contractors and Tier 1 suppliers qualify nitinol for thermal management and vibration isolation in satellite and unmanned aerial systems.
Manufacturers concentrate procurement volume; Research Institutes represent the most fragmented demand base.
Technology:
Supply concentration in vacuum metallurgy capabilities favors established superelastic alloy producers while hybrid formulations attract new entrants from advanced materials startups.
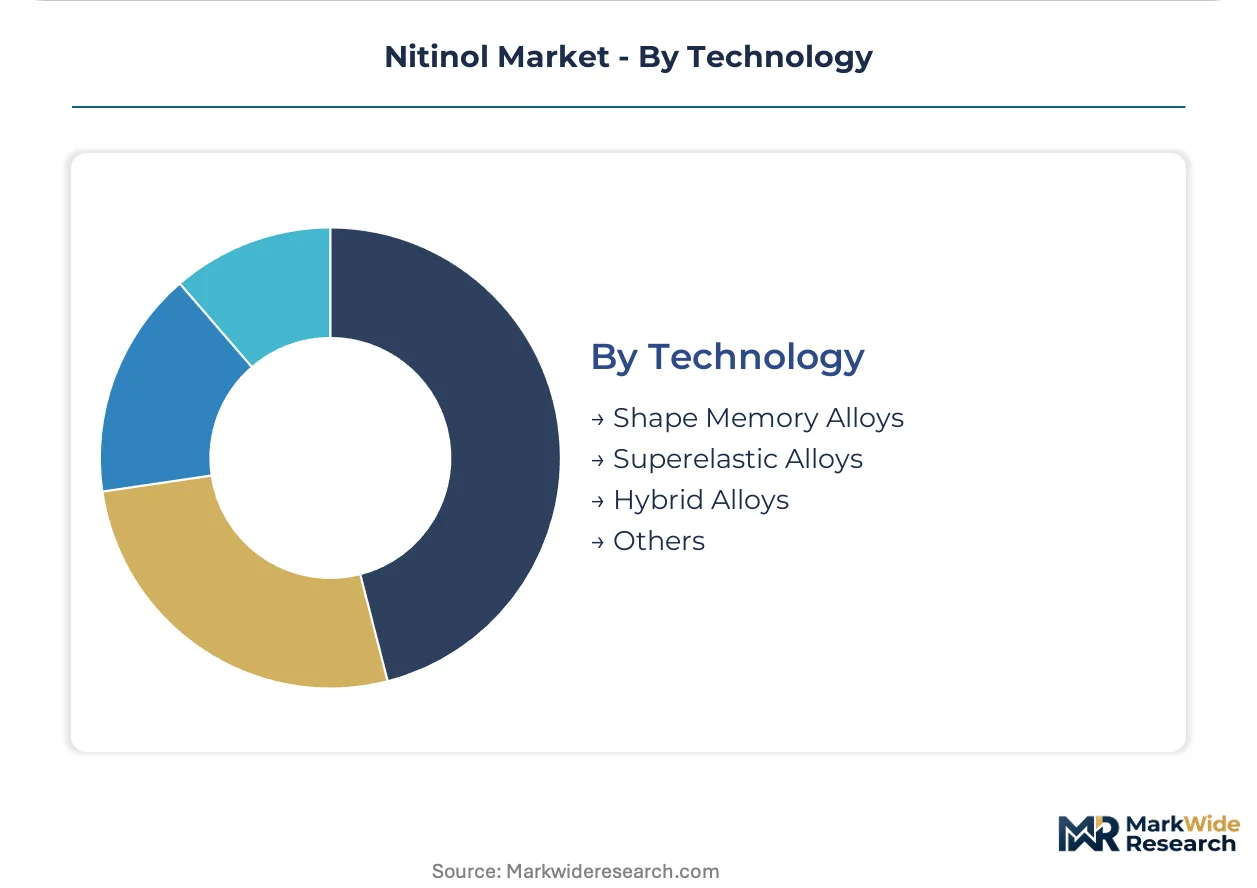
- Shape Memory Alloys:Heat-activated recovery above austenite finish temperature enables thermal actuators and orthodontic devices where one-way or two-way shape memory effect is required. Demand clusters in dental and consumer appliance applications with less stringent fatigue requirements than cardiovascular implants.
- Superelastic Alloys:Stress-induced martensitic transformation at body temperature delivers 8% recoverable strain without heating, essential for self-expanding stents and guidewires. Fort Wayne Metals and SAES Getters dominate melt-to-wire vertical integration for this technology tier.
- Hybrid Alloys:Dual-phase microstructures combining shape memory and superelastic regions enable tunable stiffness in robotics actuators and patient-specific orthopedic instruments.
- Others:Experimental compositions with copper or iron substitutions and additive manufacturing feedstock powders occupy pre-commercial development stages.
Superelastic Alloys maintains commercial dominance; Hybrid Alloys posts the steepest technology adoption curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German vacuum induction melting specialists export precision wire and tubing to United States medical device OEMs, establishing the dominant transatlantic trade corridor for implant-grade nitinol.
United States
Minneapolis and Boston cardiac device clusters drive procurement of superelastic tubing for structural heart occluders. FDA Quality System Regulation mandates full lot traceability from melt to finished component. Fort Wayne, Indiana anchors domestic wire-drawing capacity for catheter guidewires.
Germany
EU MDR notified body concentration in Berlin and Munich elevates demand for certified vacuum metallurgy capabilities. ECHA REACH compliance documentation requirements strain legacy suppliers lacking dual-carbon sourcing verification. Baden-Württemberg precision engineering firms supply laser-cut hypotubes to French vascular OEMs.
Japan
PMDA nickel ion release validation requirements create regulatory moats for long-term implantable devices. Tokyo and Osaka medical device manufacturers qualify low-leach alloy formulations for cardiac stents. Chubu region vacuum arc remelting specialists serve domestic orthopedic anchor producers.
China
NMPA medical device registration reforms accelerate domestic substitution for imported nitinol wire. Yangtze River Delta catheter OEMs qualify local superelastic tubing for neurovascular delivery systems. Shenzhen robotics manufacturers pilot hybrid alloy actuators for surgical instrument articulation.
Switzerland
Swissmedic oversight of implant-grade materials supports premium positioning for cranial fixation plate manufacturers. Zurich and Basel orthopedic clusters demand patient-specific transformation temperatures for spinal fusion devices. Geneva-area distributors bridge EU MDR-certified supply into Middle Eastern hospital procurement networks.
Nitinol Market Competitive Landscape
Player mix skews toward vertically integrated metallurgy specialists with captive vacuum induction melting capacity. The vendor base separates into three tiers: melt-to-wire integrators controlling titanium-nickel ingot sourcing, tube-drawing specialists with FDA-registered quality systems, and additive manufacturing feedstock suppliers. Consolidation pressure intensifies as notified body audits eliminate unqualified material traders. Capacity expansion and strategic technology licensing represent the dominant competitive vectors.
Among United States-based fabricators, Fort Wayne Metals exemplifies melt-to-wire vertical integration, while Cook Medical occupies a position spanning tube-drawing operations and finished device manufacturing. Abbott Laboratories anchors the premium-tier demand vector through structural heart closure device specifications. These three entities collectively represent the archetype spectrum from raw material control through component fabrication to OEM integration.
| Leading Market Players |
|---|
| Fort Wayne Metals |
| W. L. Gore & Associates |
| Abbott Laboratories |
| Cook Medical |
| Zimmer Biomet Holdings |
| Boston Scientific Corporation |
| Terumo Corporation |
| Arthrex |
| Medtronic plc |
| Others |
Supply & Pricing Matrix
Captive vacuum induction melting capacity at Fort Wayne Metals and Cook Medical anchors supply-side scale economies that simultaneously compress competitor margins and establish price floors for implant-grade material. Scale concentration in Indiana and Minnesota clusters elevates technical qualification barriers while limiting pricing power for unqualified traders lacking melt-to-wire verticality.
Pricing Analysis
Current-generation superelastic alloys command substantial premia over prior-generation shape memory formulations and experimental next-gen hybrid compositions. Three-tier pricing structure across implant-grade, industrial-grade, and research-grade levels reflects certification intensity and lot traceability depth. Price differentiation hinges on EU MDR notified body certification and FDA Quality System Regulation compliance tier, with nickel price volatility compressing margins on commodity wire grades. Hospital procurement departments exhibit highest price sensitivity through group purchasing organization consolidation, while structural heart device OEMs absorb premia for patient-specific transformation temperatures.
Supply Chain Analysis
Just-in-time inventory strategies dominate catheter guidewire procurement, whereas strategic stockpiling of titanium-nickel ingot concentrates among Indiana-based tube-drawing operations. Supply concentrates in the United States, Germany, and Japan, with German vacuum induction melting specialists exporting precision wire to American cardiac device clusters. Raw material dependencies rest on nickel from Russian and Indonesian sources, titanium sponge from Japanese and Chinese producers, and specialized vacuum metallurgy equipment from European suppliers. Single-state concentration in Indiana creates geographic vulnerability for self-expanding stent graft components. Distribution runs through direct manufacturer-to-OEM relationships, disintermediating traditional full-service distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent nitinol suppliers face intensifying substitution pressure from shape memory polymers in cost-sensitive actuator applications and laser-cut cobalt-chrome hypotubes in peripheral vascular delivery systems.
For Market Incumbents: Consolidate melt-to-wire verticality through captive titanium-nickel ingot sourcing to defend against nickel price volatility and Russian supply disruption risks. Deepen backward integration into vacuum metallurgy talent pipelines to address specialized process engineer scarcity. Lock in long-term offtake agreements with Minnesota and Boston cardiac device clusters before hybrid alloy robotics entrants capture share.
For New Entrants and Emerging Players: Differentiate on Japan PMDA nickel ion release validation to establish regulatory moats against unqualified competitors in long-term implantable segments. Target China NMPA domestic substitution initiatives for neurovascular delivery system tubing as the most penetrable geography. Pursue hospital system direct relationships unbundled from metallurgical consulting to bypass entrenched distributor networks.
For Investors and Strategic Acquirers: Additive manufacturing feedstock powder specialists with laser powder bed fusion qualification protocols represent the highest-conviction acquisition archetype. Long-term viability hinges on EU MDR Annex I recertification cycles creating sustained demand for certified vacuum induction melting capacity. Watch FDA fatigue testing protocol harmonization efforts as the signal for margin compression or expansion across the supplier base.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Annex I Recertification | Notified body scrutiny of fatigue performance data under ISO 10993 elevates qualified supplier premia. |
| Japan PMDA Nickel Ion Validation | Low-leach formulation certification opens structural heart and long-term orthopedic implant procurement channels. |
| Additive Manufacturing Feedstock Qualification | Laser powder bed fusion powder protocols reshape cranial plate and patient-specific implant supply chains. |
| Direct Manufacturer-to-OEM Relationships | Hospital GPO unbundling of technical support accelerates disintermediation of traditional distributors. |
| Hybrid Alloy Robotics Actuator Development | Tunable stiffness formulations expand addressable applications beyond medical into industrial automation segments. |
Research Methodology
Cross-validation between primary interviews with vacuum metallurgy process engineers, biomedical engineers at structural heart device OEMs, and hospital GPO contracts managers anchors the qualitative findings. Secondary validation draws from FDA 510(k) filings, EU MDR notified body documentation, SEC 10-K disclosures from public medical device manufacturers, and Japanese PMDA approval databases. Bottom-up segmentation modeling triangulates against top-down macroeconomic drivers across the analysis window.
Sensitivity analysis around nickel price volatility scenarios and EU MDR implementation timelines frames the forecast uncertainty bounds. The analytical framework models volume and value across product type, application, technology tier, and regional regulatory cluster throughout the forecast period. CAGRs derive from regression analysis of historical procurement patterns and forward-looking OEM capacity announcements. Transformation temperature precision requirements and fatigue test protocol divergence serve as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained FDA Quality System Regulation enforcement and EU MDR notified body capacity constraints would require recalibration. Forecasts reflect documented assumptions regarding nickel supply stability and vacuum metallurgy talent availability. Revision becomes warranted when shape memory polymer performance thresholds cross superelastic strain recovery parity or when dual-carbon sourcing verification mandates disrupt legacy procurement systems.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Polymer Blends Alloys Market
Advanced Alloys
Plastic-Metal Hybrids Market
Advanced Alloys
India Aluminum Extrusion Market
Advanced Alloys
Structural Power Composites Market
Advanced Alloys
Powder Metallurgy Components Market
Advanced Alloys
High Strength Steel (HSS) Market
Advanced Alloys
Middle East and Africa Aluminum Casting Market
Advanced Alloys
North America Braze Alloys Market
Advanced Alloys
Metal Replacement Market
Advanced Alloys
Global Amorphous Alloy Band Market
Advanced Alloys
Super Alloys Market
Advanced Alloys
Global Ferroalloys Market
Advanced Alloys
Europe Ceramic Ball Bearings Market
Advanced Alloys
Global Ti-6Al-4V Titanium Alloy Market
Advanced Alloys
Global Aluminum Silicon Carbide (Alsic) Market
Advanced Alloys
Quenched and Tempered Steel Market