
 Tungsten Alloy Market | 2026-2036
Tungsten Alloy Market Size, Share, and Industry Trends Forecast 2026-2036
Tungsten Alloy Market Analytics
A capital-intensity divergence between integrated miners and downstream fabricators is reorganizing competitive tiers in tungsten alloys. Xiamen Tungsten Co. Ltd. leverages captive ore reserves to control feedstock costs across heavy alloy production. Plansee SE sustains premium positioning through vacuum sintering expertise for medical and aerospace grades. Kennametal Inc. competes on cemented carbide tool systems that anchor industrial demand.
Tungsten alloys combine tungsten with nickel, iron, or copper binders to achieve densities exceeding 17 g/cm³ while maintaining machinability for radiation shielding, kinetic penetrators, and electrical contacts. Tungsten-carbide dominates value generation through cemented carbide cutting tools and wear parts serving metalworking and mining. Tungsten heavy alloys lead defense and aerospace applications where density and ductility requirements exceed pure tungsten capabilities. Pure tungsten occupies specialized niches in high-temperature furnace components and semiconductor ion implantation systems.
EPA oversight governs hazardous waste from tungsten carbide grinding sludge in the United States, while REACH registration in Europe restricts nickel powder handling in heavy alloy production. China's MIIT enforces dual carbon goals that tighten energy consumption limits on tungsten powder reduction furnaces. Stakeholders must monitor regulatory divergence between jurisdictions as it fragments certification requirements and reshapes supplier qualification timelines.
Market Dynamics
China's dominance in tungsten ore refining and heavy alloy fabrication capacity is concentrating supply-side leverage among integrated miners, forcing downstream fabricators to secure captive feedstock or accept margin compression on volatile powder costs.
Growth Catalysts
- Aerospace Radiation Shielding:Satellite constellation deployments and deep-space probe programs are expanding procurement of tungsten heavy alloys for gamma-ray attenuation in spacecraft hulls and instrument housings.
- REACH Nickel Restrictions:Europe's tightening heavy metal handling protocols are accelerating qualified supplier consolidation, favoring fabricators with certified vacuum sintering capabilities for medical-grade alloys.
- Kinetic Energy Penetrators:Defense modernization programs across NATO members are sustaining long-term offtake for tungsten-nickel-iron alloys in armor-piercing munitions where depleted uranium faces political constraints.
Market Restraints
- Scheelite/Wolframite Concentration:Over 80% of global tungsten ore reserves sit within Chinese borders, exposing non-integrated fabricators to export quota volatility and state-directed pricing.
- Cobalt Substitution Pressure:Tungsten carbide cutting tools face erosion from ceramic-matrix composites and polycrystalline diamond inserts in high-speed machining of aluminum aerospace alloys.
- EPA Grinding Sludge Rules:Hazardous waste classification of carbide grinding residue in the United States imposes disposal cost premiums that compress margins for job-shop tool reconditioners.
Strategic Opportunities
- India Defense Indigenization:The country's PLI scheme for critical minerals processing offers tariff and capital subsidies for joint ventures establishing tungsten powder reduction capacity outside China.
- Additive Manufacturing Convergence:Binder jet printing of tungsten heavy alloys is opening near-net-shape production of radiation collimators previously machined from wrought billet.
- EU Green Deal Critical Raw Materials Act:Strategic stockpiling mandates and recycling targets for tungsten are creating offtake guarantees for European secondary recovery facilities.
Industry Challenges
- Vacuum Sintering Technician Scarcity:The specialized metallurgical expertise required for medical-grade heavy alloy densification exceeds current vocational pipeline output in Western Europe and North America.
- Dual-Carbon Compliance Timelines:China's MIIT energy consumption caps on reduction furnaces are forcing capacity reconfiguration on compressed schedules without guaranteed power allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tungsten Alloy Market |
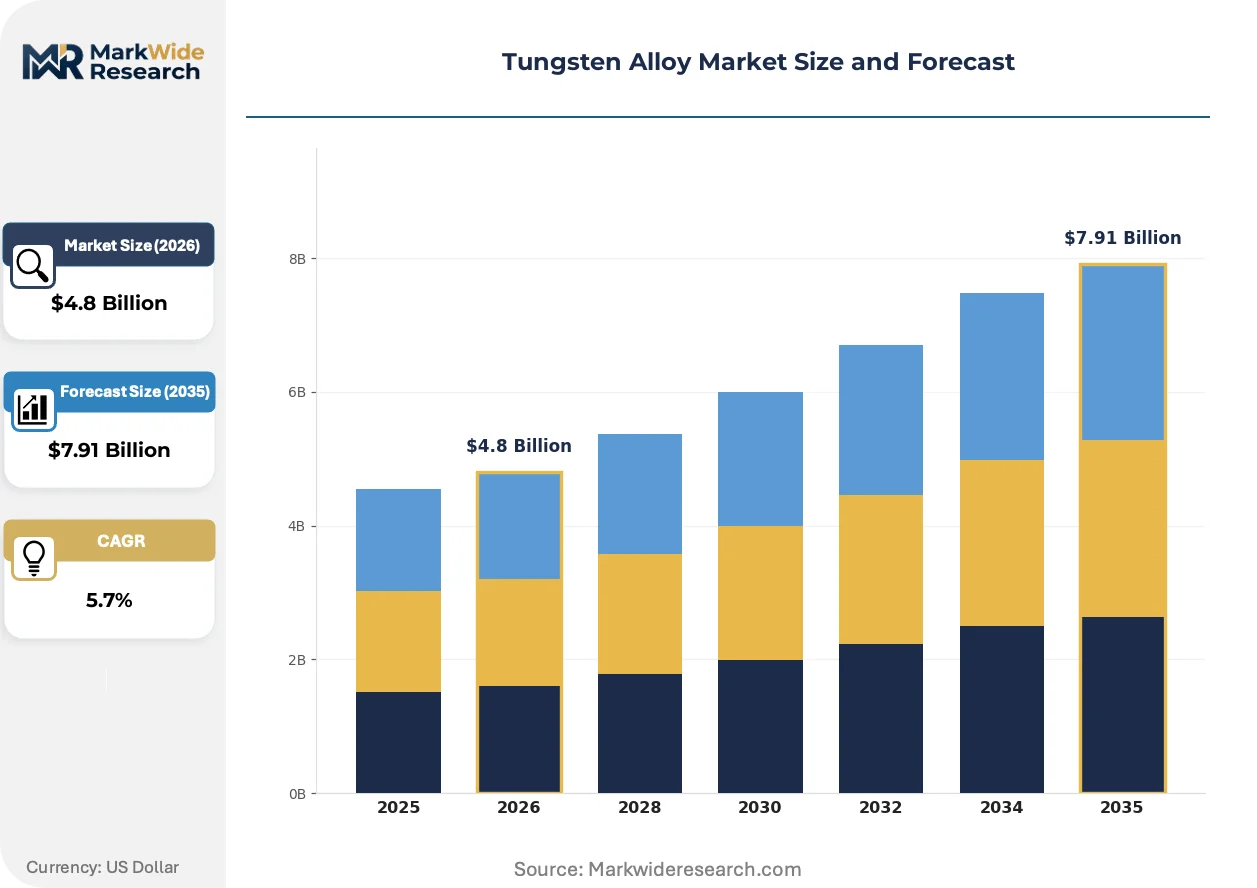
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tungsten Heavy Alloys, Tungsten-Carbide, Tungsten Copper, Pure Tungsten Application: Aerospace, Medical Devices, Defense, Industrial Equipment End User: Manufacturers, OEMs, Research Institutions, Government Agencies Distribution Channel: Direct Sales, Distributors, Online Retailers, Wholesalers |
| Companies Covered | Xiamen Tungsten Co. Ltd., China Tungsten & Hightech Materials Co. Ltd., CMOC Group Ltd., Chongyi Zhangyuan Tungsten Co. Ltd., H.C. Starck, Kennametal Inc., Sandvik AB, Plansee SE, Umicore N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tungsten Alloy Market Evolving Landscape
Process intensification in powder metallurgy and regulatory pressure on supply chain provenance are compressing traditional fabrication timelines while opening new application categories for additive and recycled feedstock routes.
Binder jet additive manufacturing of tungsten-nickel-iron heavy alloys is displacing conventional press-and-sinter methods for complex radiation shielding geometries in medical imaging equipment. Siemens Healthineers and Canon Medical Systems are qualifying printed collimator arrays that reduce machining waste by 60% while achieving density uniformity within 0.5% of wrought standards. The technology is displacing Swiss-style CNC turning centers from the critical path of proton therapy nozzle production.
REACH Annex XVII restrictions on nickel compound handling are forcing heavy alloy fabricators to relocate nickel powder storage and pre-alloying operations to dedicated facilities with enhanced ventilation and wastewater treatment. The regulation compresses operational flexibility for multi-metal job shops while creating compliance moats for specialists with purpose-built nickel-handling infrastructure. German fabricators are responding fastest due to prior investments under TA Luft air quality directives.
Consolidated procurement desks at tier-one aerospace OEMs are replacing spot-market tungsten carbide insert purchases with five-year direct agreements specifying recycled content minimums and Scope 3 emissions documentation. This behavior compresses distributor margins while rewarding miners with certified conflict-free and carbon-accounted supply chains. The shift is most visible in France and Germany where Airbus and Safran procurement teams have embedded sustainability scorecards into supplier qualification.
Tungsten Alloy Market Segmentation
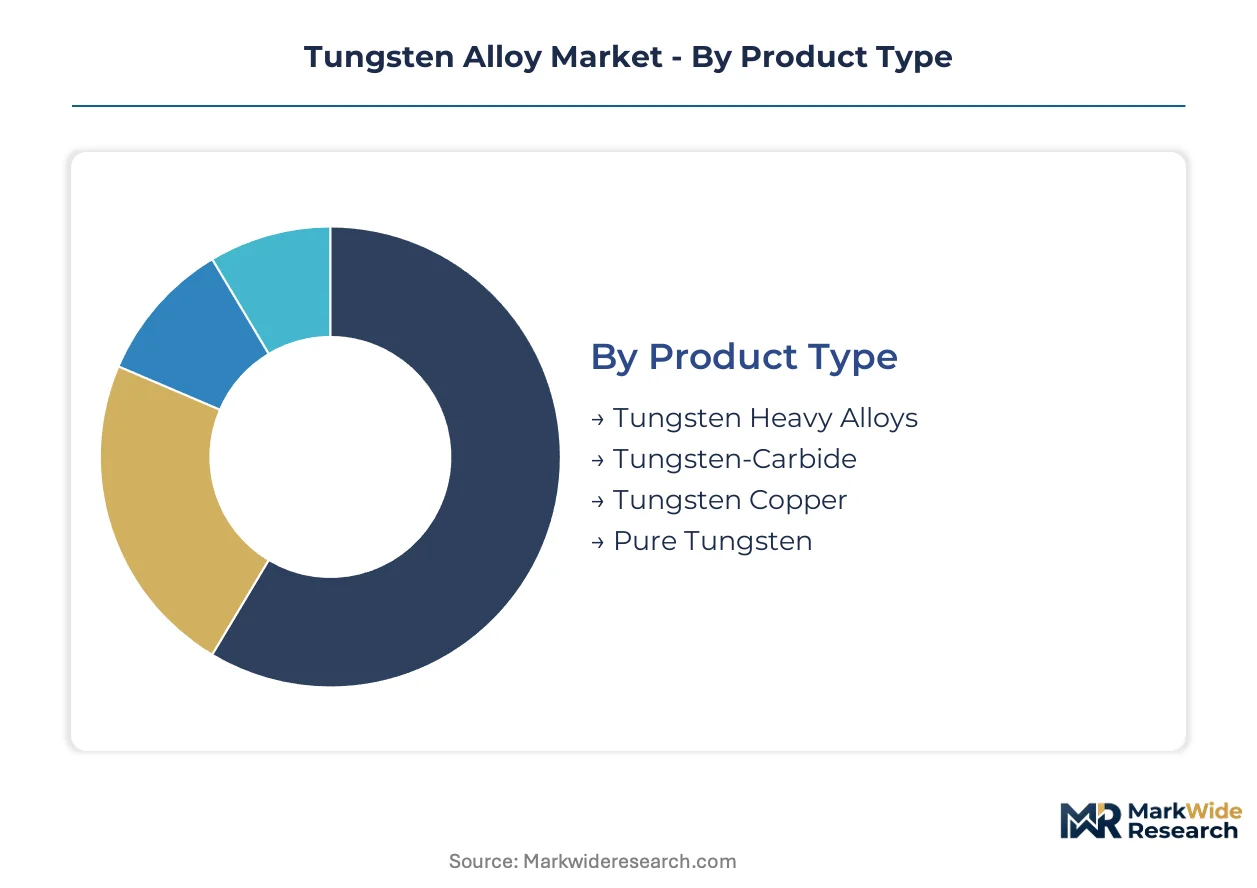
Tungsten alloy procurement patterns diverge sharply between captive supply chains serving defense primes and spot-market purchasing by industrial job shops. Segmentation reveals how product purity grades, application-critical certifications, and channel economics partition margin pools across the value chain.
Product Type:
Tungsten-carbide commands domestic offtake volumes through cemented carbide tool production clustered in Ohio and Illinois, while heavy alloy exports concentrate on European medical imaging and Asian defense contractors.
- Tungsten-Carbide:Cemented carbide formulations with cobalt binders dominate cutting tool and wear part fabrication. Demand clusters in US metalworking corridors where Kennametal and Sandvik maintain captive recycling loops for grinding sludge recovery.
- Tungsten Heavy Alloys:Tungsten-nickel-iron and tungsten-nickel-copper systems achieve densities exceeding 17 g/cm³ with retained ductility. European aerospace OEMs in France and Germany specify vacuum-sintered grades for satellite radiation shielding where REACH nickel handling compliance is mandatory.
- Tungsten Copper:Infiltrated composites combine high thermal conductivity with arc erosion resistance. Electrical contact manufacturers in Japan and South Korea dominate procurement for high-voltage switchgear.
- Pure Tungsten:Sintered and wrought forms serve furnace components and semiconductor ion implantation systems. US and German specialty metals houses control qualification pathways for semiconductor fab equipment.
Tungsten-carbide holds the largest share; momentum sits with heavy alloys as defense and space applications expand.
Application:
Cost tier stratification separates aerospace qualification programs with multi-year certification timelines from industrial equipment spot purchasing sensitive to powder price volatility.
- Defense:Kinetic energy penetrator programs across NATO members sustain long-term offtake for tungsten-nickel-iron alloys. Political constraints on depleted uranium alternatives lock in tungsten procurement for armor-piercing munitions.
- Aerospace:Satellite constellation builders in California and Washington State specify heavy alloy radiation shielding for gamma-ray attenuation in instrument housings. Deep-space probe programs at JPL and ESA drive qualification of additively manufactured collimator geometries.
- Medical Devices:CT scanner collimators and proton therapy nozzles require density uniformity within 0.5% of wrought standards. Siemens Healthineers and Canon Medical Systems are qualifying binder-jet printed arrays that reduce machining waste.
- Industrial Equipment:Cemented carbide cutting tools and wear parts serve metalworking and mining operations. Job-shop reconditioners face margin compression from EPA grinding sludge disposal cost premiums.
Defense commands the steepest pricing tier; medical devices are climbing fastest on additive manufacturing adoption.
End User:
Volume concentration separates OEMs with consolidated procurement desks from fragmented research institution purchasing that tolerates longer lead times for specialized grades.
- OEMs:Tier-one aerospace and medical equipment manufacturers negotiate five-year direct agreements specifying recycled content minimums and Scope 3 emissions documentation. Airbus and Safran procurement teams in France have embedded sustainability scorecards into supplier qualification.
- Manufacturers:Cutting tool fabricators and heavy alloy component shops balance captive powder inventory against spot market exposure. Chinese integrated miners leverage ore reserve control to dictate feedstock pricing.
- Government Agencies:Defense ministries and space agencies specify military-grade heavy alloys with traceable provenance. US DLA and European defence agencies maintain strategic stockpiles with qualified supplier lists.
- Research Institutions:National laboratories and university programs source small-batch pure tungsten for fusion reactor and plasma physics research. CERN and Oak Ridge National Laboratory operate dedicated procurement channels for experimental grades.
OEMs dominate procurement value; government agencies provide steadiest volume commitments through multi-year programs.
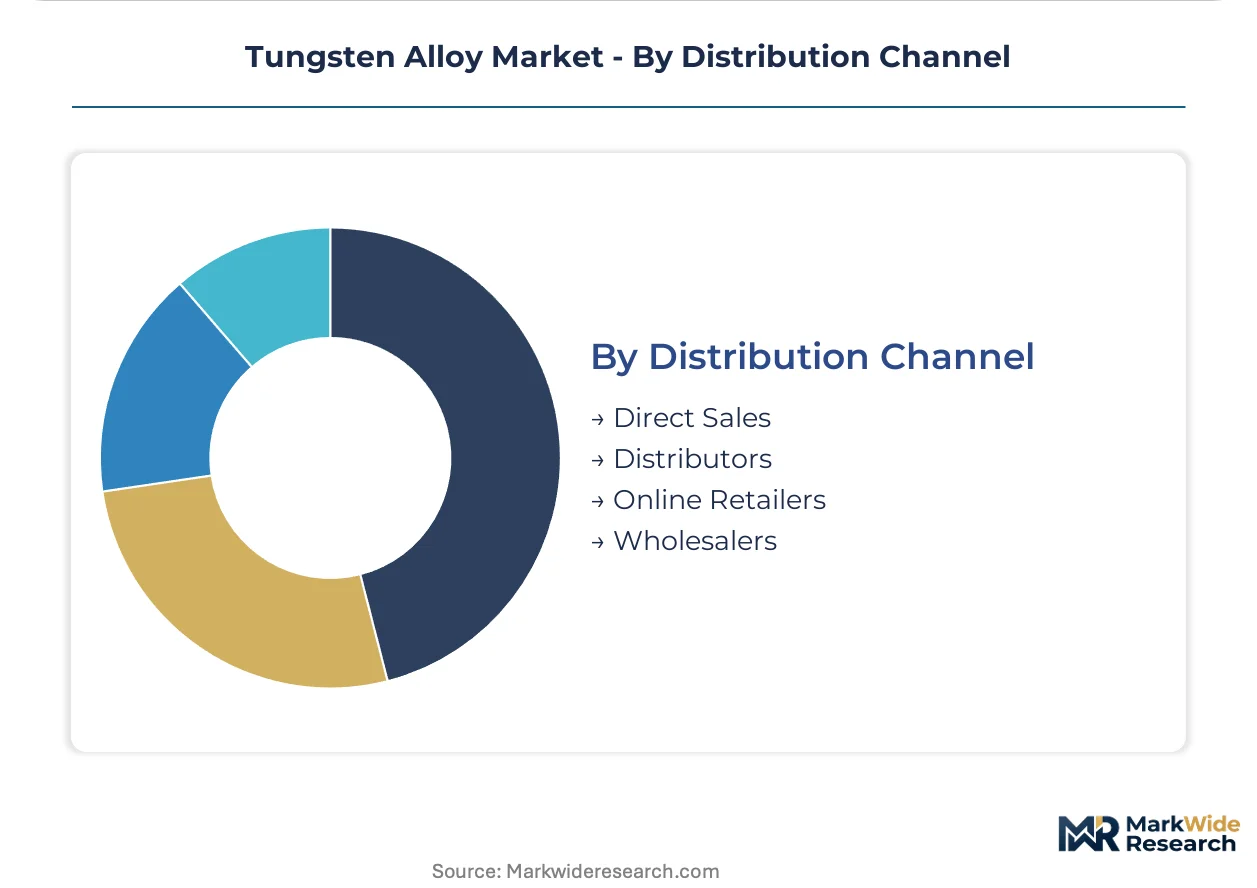
Distribution Channel:
Customer type determines channel selection, with qualified OEMs bypassing distributors while job shops rely on stocking intermediaries for powder and insert availability.
- Direct Sales:Long-term supply agreements link integrated miners and downstream fabricators to aerospace and defense primes. Xiamen Tungsten and Plansee SE operate dedicated account teams for tier-one OEM qualification.
- Distributors:Regional stocking intermediaries serve job-shop tool reconditioners and small-batch heavy alloy fabricators. Inventory carrying costs are rising with tungsten powder price volatility.
- Wholesalers:Bulk cemented carbide inserts and standard-grade heavy alloy billets flow through metal service centers. Pricing tracks LME-adjacent tungsten concentrate benchmarks with volume discounts.
- Online Retailers:Catalog sales of standard carbide inserts and pure tungsten rod stock serve prototype shops and maintenance-repair-operations purchasing. Limited to non-critical grades without certification requirements.
Direct sales capture the premium tier; distributors retain relevance in fragmented industrial equipment segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: China dominates ore refining and heavy alloy fabrication, Europe concentrates on medical-grade vacuum-sintered components, and the United States anchors defense procurement for kinetic penetrator programs.
China
Integrated miners control tungsten ore reserves and heavy alloy fabrication capacity across Jiangxi and Hunan provinces. MIIT dual-carbon goals tighten energy consumption limits on powder reduction furnaces, forcing rapid capacity reconfiguration. Xiamen Tungsten leverages captive feedstock to supply aerospace radiation shielding contracts.
United States
Defense modernization programs sustain long-term offtake for tungsten-nickel-iron kinetic energy penetrators. EPA hazardous waste rules classify carbide grinding sludge, imposing disposal cost premiums on job-shop tool reconditioners. Ohio and Illinois metalworking corridors host captive recycling loops for cemented carbide recovery.
Germany
Medical imaging OEMs in Bavaria and Baden-Württemberg specify vacuum-sintered heavy alloys for CT collimators and proton therapy nozzles. REACH Annex XVII nickel handling restrictions compress operational flexibility for multi-metal fabricators. Plansee SE maintains dedicated account teams for tier-one aerospace qualification.
France
Airbus and Safran procurement teams embed sustainability scorecards into supplier qualification for satellite radiation shielding. EU Green Deal Critical Raw Materials Act mandates strategic stockpiling and recycling targets for tungsten. Toulouse and Paris-Saclay aerospace clusters drive additive manufacturing adoption for near-net-shape collimator production.
Japan
Electrical contact manufacturers in Osaka and Nagoya dominate procurement of tungsten-copper infiltrated composites for high-voltage switchgear. METI industrial policy supports domestic heavy alloy fabrication for semiconductor ion implantation systems. Tokyo-based trading houses coordinate tungsten concentrate imports amid Chinese export quota volatility.
Tungsten Alloy Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with ore-reserve control separating price-makers from margin-compressed fabricators. Three archetypes populate the competitive map: captive miners with powder-to-component pipelines, vacuum-sintering specialists serving medical-aerospace grades, and cemented carbide tool system integrators. Consolidation pressure favors backward integration into ore reserves and additive manufacturing capability acquisitions.
Among Chinese integrated miners, Xiamen Tungsten Co. Ltd. and CMOC Group Ltd. exemplify the captive-reserve archetype that dictates feedstock economics. Plansee SE and Kennametal Inc. occupy positions on the premium-specialist and tool-system vectors respectively, representing how fabrication expertise and distribution scale create defensible tiers despite upstream concentration.
| Leading Market Players |
|---|
| Xiamen Tungsten Co. Ltd. |
| China Tungsten & Hightech Materials Co. Ltd. |
| CMOC Group Ltd. |
| Chongyi Zhangyuan Tungsten Co. Ltd. |
| H.C. Starck |
| Kennametal Inc. |
| Sandvik AB |
| Plansee SE |
| Umicore N.V. |
| Others |
Value Network & Pricing Analysis
Ceramic-matrix composite substitution in high-speed aluminum machining is simultaneously shifting demand geography toward aerospace-grade heavy alloy producers and compressing cemented carbide pricing power in general metalworking. This input displacement concentrates margin capture among vacuum-sintering specialists while forcing commodity-grade fabricators toward volume-driven contract structures.
Pricing Analysis
After-market grinding sludge recycling contracts now drive lifetime value for cemented carbide tool systems more than initial insert sales. Three-tier pricing structure across aerospace-certified, industrial-standard, and job-shop economy levels separates vacuum-sintered heavy alloys from press-and-sinter commodity grades. Cost compression in industrial-tier inserts is intensifying because EPA hazardous waste disposal premiums erode reconditioner margins. Job-shop tool reconditioners exhibit highest price sensitivity; satellite constellation OEMs demonstrate lowest sensitivity due to multi-year qualification lock-in.
Supply Chain Analysis
China and Vietnam anchor tungsten ore refining and heavy alloy powder reduction across Jiangxi and Thai Nguyen provinces. Downstream fabrication draws from wolframite concentrate, nickel powder, and cobalt binder feedstocks. Single-source vulnerability concentrates in Chinese export quota administration for tungsten concentrate. Distribution runs through direct long-term agreements for aerospace primes and regional distributors for fragmented industrial job shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tungsten alloy markets are cycling through defense modernization procurement waves, with NATO kinetic penetrator programs providing demand floor stability through multi-year offtake commitments.
For Market Incumbents: Shield heavy alloy margins by accelerating vacuum-sintering technician apprenticeship pipelines before REACH nickel handling compliance widens qualification gaps. Secure captive ore reserves or joint-venture powder reduction capacity outside Chinese MIIT dual-carbon jurisdiction to escape state-directed energy consumption caps. Additive manufacturing capability acquisition offers defensive positioning against binder-jet displacement of Swiss-style CNC collimator production. For New Entrants and Emerging Players: Post-processing service gaps in binder-jet printed heavy alloy densification present white-space entry points where incumbents under-serve medical imaging OEMs with limited hot isostatic pressing capacity. Target India's PLI-subsidized critical minerals processing corridor for tungsten powder reduction joint ventures with defense indigenization mandates. Lead with certified radiation shielding qualification support rather than commodity billet pricing to bypass incumbent scale advantages. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed cemented carbide tool distributors facing margin compression from OEM direct procurement consolidation. Five-to-ten year viability favors backward-integrated heavy alloy fabricators with REACH-compliant nickel handling infrastructure and additive manufacturing qualification pipelines. Monitor EU Green Deal strategic stockpiling mandate implementation velocity as demand inflection signal for European secondary recovery facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Ore Reserve Acquisition | Xiamen Tungsten's Jiangxi mining control eliminates feedstock cost volatility for aerospace contracts. |
| Vacuum Sintering Capacity Expansion | Plansee SE's Bavaria facilities meet REACH Annex XVII nickel handling mandates for medical-grade alloys. |
| Binder Jet Additive Manufacturing Qualification | Siemens Healthineers' printed collimator adoption reduces machining waste by sixty percent versus wrought billet. |
| India Defense PLI Joint Venture | Domestic powder reduction capacity secures tariff advantages under critical minerals processing subsidies. |
| Grinding Sludge Recycling Loop Integration | Kennametal's Ohio captive recovery systems offset EPA hazardous waste disposal premiums for cemented carbide. |
Research Methodology
Initial hypotheses were tested against primary input from powder metallurgy plant managers, aerospace procurement directors, defense ministry qualification officers, and medical device regulatory affairs leads and refined through secondary validation. Primary fieldwork combined structured interviews with downstream fabricators and integrated miners across China, Germany, and the United States. Secondary sources encompassed customs trade data for tungsten concentrate flows, EPA hazardous waste classification filings, REACH Annex XVII compliance registrations, and SEC 10-K disclosures from listed specialty metals houses. Bottom-up demand modeling across application segments triangulated against top-down ore reserve and refining capacity estimates.
Variance decomposition across product type, application criticality, and geographic regulatory cluster shaped the analytical framework. Modeled segmentation spanned tungsten-carbide, heavy alloy, tungsten-copper, and pure tungsten grades; defense, aerospace, medical device, and industrial equipment applications; and OEM direct, distributor, and wholesale channel structures. CAGRs were derived from production capacity expansion schedules, defense procurement program timelines, and additive manufacturing adoption curves. Industry-specific inputs included MIIT dual-carbon energy consumption caps, REACH nickel handling compliance costs, and satellite constellation deployment trajectories.
Forecasts assume regulatory continuity in EPA hazardous waste classification, REACH Annex XVII enforcement, and MIIT dual-carbon timelines; material policy shifts would require re-modeling. Commodity price volatility in tungsten concentrate, export quota administration by Chinese state planners, and ceramic-matrix composite substitution rates in aerospace machining present revision risks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Soft Magnetic Material for Electric Vehicle Market
Advanced Alloys
Nickel Alloy Market
Advanced Alloys
Steel Fiber Market
Advanced Alloys
Global Aluminum Silicon Carbide (Alsic) Market
Advanced Alloys
Europe Aluminum Casting Market
Advanced Alloys
Precipitation Hardening Market
Advanced Alloys
Super Alloys Market
Advanced Alloys
Global Aluminum Alloys Market
Advanced Alloys
Powder Metallurgy Components Market
Advanced Alloys
Aluminum Composite Panel Market
Advanced Alloys
Global High Performance Alloys Market
Advanced Alloys
Welding Alloys Market
Advanced Alloys
Global Aluminum Foams Market
Advanced Alloys
Nickel Boride Alloy Market
Advanced Alloys
Medium Entropy Alloys Market
Advanced Alloys
Middle East and Africa Aluminum Casting Market