
 Predisposition Biomarkers Market | 2026-2036
Predisposition Biomarkers Market Size, Share, and Industry Trends Forecast 2026-2036
Predisposition Biomarkers Market Analysis
Hospital procurement channels for predisposition biomarker testing is fragmenting as diagnostic labs and research institutes build direct sourcing relationships with assay developers. Roche Holding AG leverages its integrated diagnostics division to sustain captive supply chains across oncology testing workflows. Thermo Fisher Scientific anchors North American distribution through its centralized laboratory services network. QIAGEN N.V. competes on sample preparation automation that reduces hands-on time for high-throughput genomics laboratories.
Predisposition biomarkers comprise measurable biological indicators—encompassing DNA sequence variants, protein expression profiles, metabolic signatures, and RNA transcript levels—that reveal inherited or acquired susceptibility to disease before clinical manifestation. These biomarkers typically require extraction from blood, tissue, or biofluid specimens followed by amplification, hybridization, or mass spectrometry detection to achieve the sensitivity thresholds needed for early risk stratification. Genomics commands the largest revenue share among product types due to established reimbursement for hereditary cancer panels, while metabolomics represents the fastest-expanding category as lipid and small-molecule profiling platforms achieve clinical-grade reproducibility. Next-Generation Sequencing dominates technology utilization for multigene panel analysis, though PCR retains margin strength in single-site variant confirmation workflows where turnaround time drives purchasing decisions.
The FDA oversees premarket review of biomarker-based in vitro diagnostics through its Center for Devices and Radiological Health, while the Clinical Laboratory Improvement Amendments establish quality benchmarks for laboratory-developed tests that many predisposition assays currently follow. The EMA's In Vitro Diagnostic Regulation in Europe demands expanded clinical evidence for genetic risk tests, reshaping documentation requirements for manufacturers seeking CE marking. Stakeholders must monitor evolving payer coverage determinations for preventive genomic testing as health technology assessment bodies weigh population screening cost-effectiveness against individualized risk prediction value.
Market Dynamics
Companion diagnostic mandates from the FDA are compressing development timelines for predisposition assays, forcing assay developers to synchronize biomarker validation with therapeutic clinical trials rather than pursuing sequential regulatory pathways.
Growth Catalysts
- Hereditary cancer screening protocols:National health systems in Germany and France have expanded reimbursement for BRCA and Lynch syndrome panels, creating pull-through demand for multigene risk stratification workflows.
- IVDR compliance deadlines:The European Union's In Vitro Diagnostic Regulation is accelerating documentation investments among legacy assay manufacturers, filtering out undercapitalized competitors and consolidating certified supplier bases.
- Pharmacovigilance integration:Biopharma sponsors now embed predisposition biomarkers into Phase I protocols to preempt adverse event liability, expanding precompetitive research consortia for variant databases.
Market Restraints
- Reagent supply concentration:Polymerase and modified nucleotide production clusters in South Korea and Singapore, exposing assay manufacturers to geopolitical disruption risks and dual-use export controls.
- Variant interpretation bottlenecks:The American College of Medical Genetics and Genomics issues quarterly updates to pathogenicity classification frameworks, forcing laboratories to revalidate historical reports and absorb retrospective liability.
- Direct-to-consumer substitution:Wellness genotyping services from ancestry platforms erode clinical channel volumes for low-complexity carrier screening, compressing margin pools for moderate-risk panels.
Strategic Opportunities
- Metabolomic risk profiling:Lipidomics platforms achieve clinical-grade reproducibility for cardiovascular predisposition, opening reimbursement negotiations with German statutory health insurers for primary prevention programs.
- Polygenic risk score integration:Machine learning architectures combining thousands of common variants are penetrating psychiatric and autoimmune indications where monogenic tests hold limited predictive value.
- At-home sample collection:Dried blood spot logistics networks bypass clinic-based phlebotomy constraints, expanding addressable populations in rural Australia and Canadian provincial health systems.
Industry Challenges
- Bioinformatics workforce scarcity:Clinical laboratories compete with technology firms for variant curation specialists, inflating compensation packages and extending turnaround times for complex cases.
- Interoperability fragmentation:Electronic health record systems lack standardized APIs for structured genomic results, forcing manual transcription and elevating misclassification risks in multidisciplinary tumor boards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Predisposition Biomarkers Market |
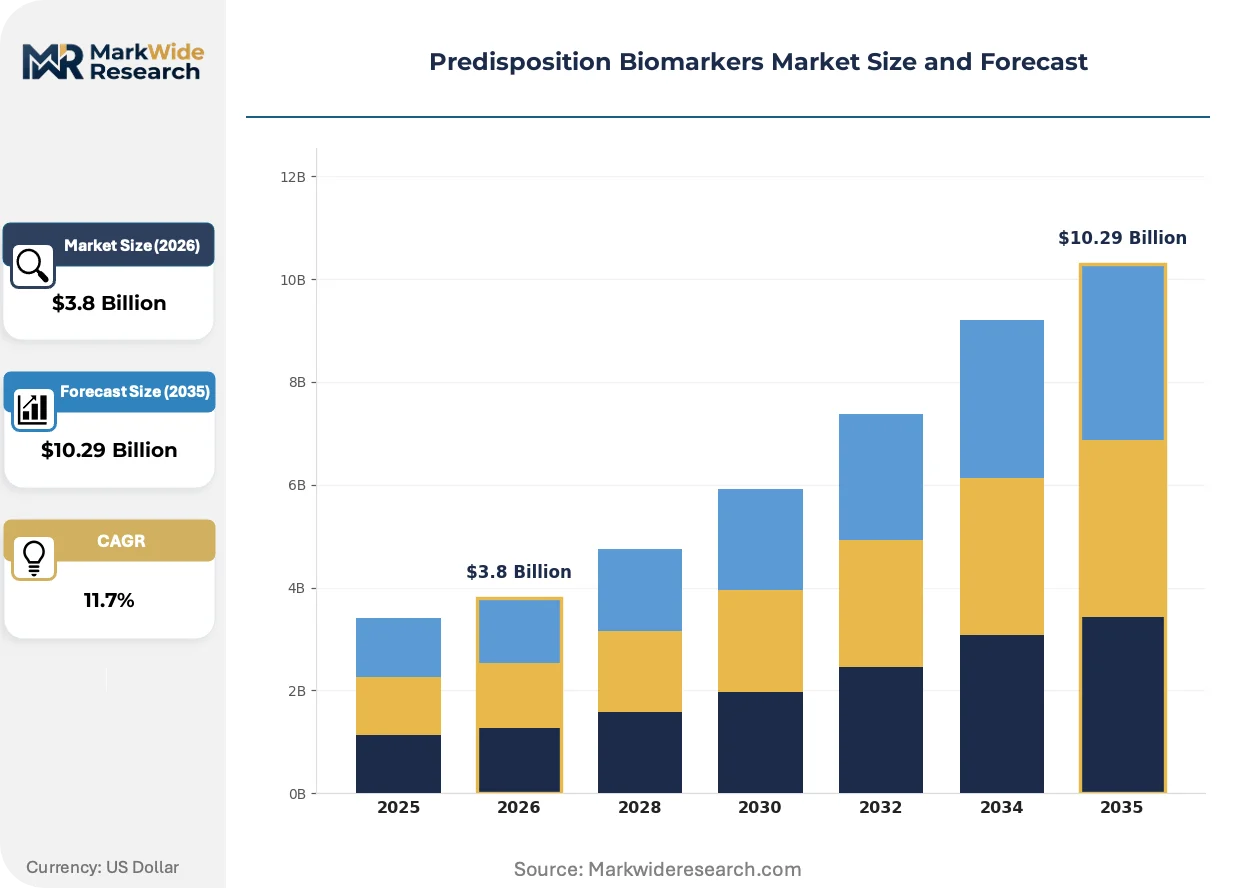
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proteomics, Genomics, Metabolomics, Transcriptomics Therapy Area: Oncology, Cardiovascular, Neurology, Rare Diseases End User: Hospitals, Diagnostic Labs, Research Institutes, Pharmaceutical Companies Technology: Next-Generation Sequencing, Microarray, PCR, ELISA |
| Companies Covered | Roche Holding AG, Thermo Fisher Scientific Inc., QIAGEN N.V., Illumina Inc., Bio-Rad Laboratories Inc., Myriad Genetics Inc., Agilent Technologies Inc., Merck KGaA, Epigenomics AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Predisposition Biomarkers Market Emerging Trajectories
Long-read sequencing architectures are compressing the variant detection workflow from days to hours, eliminating the batch-processing economics that historically favored centralized reference laboratories.
Oxford Nanopore's real-time basecalling chemistry is rendering obsolete the capital-intensive Illumina cluster generation step for structural variant detection in hereditary cardiovascular panels. Community hospitals in Texas and Florida are adopting portable PromethION configurations to retain oncology specimen volume that previously flowed to academic medical center core facilities. This decentralization is fragmenting the historical geographic monopoly of Boston and San Francisco sequencing hubs.
The FDA's 2024 guidance on artificial intelligence-enabled variant classification tools imposes locked-algorithm requirements and prospective validation protocols for machine learning-based pathogenicity predictions. Diagnostic developers must now submit software as a medical device premarket notifications for scoring algorithms previously treated as laboratory-developed test components. High-complexity molecular pathology laboratories in Maryland and North Carolina are rebuilding validation cohorts to satisfy the evidentiary threshold, delaying product launches by twelve to eighteen months.
Self-insured employers are contracting directly with reference laboratories for workforce genomic screening programs, disintermediating the health plan prior authorization layer that previously gatekept preventive testing access. This channel shift concentrates purchasing power among benefits consultants and third-party administrators rather than分散 across individual physician practices. The phenomenon is most pronounced in the Mountain West region where technology sector employers operate captive onsite clinics with embedded phlebotomy and courier logistics.
Predisposition Biomarkers Market Segmentation
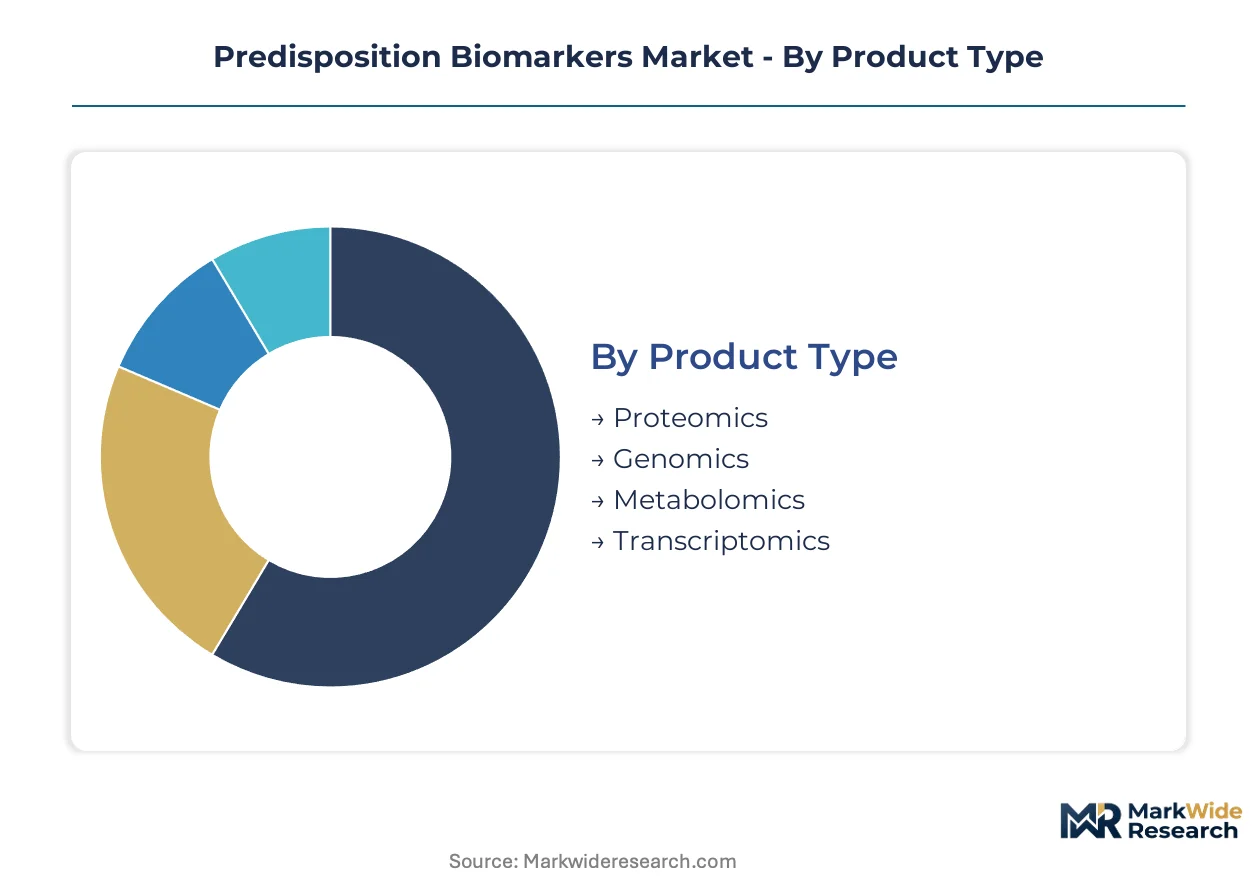
Predisposition biomarkers serve distinct clinical workflows ranging from hereditary cancer screening to pharmacogenomic dosing. Segmentation reveals how technology maturity, regulatory pathways, and reimbursement status fragment purchasing decisions across healthcare delivery settings.
Product Type:
Product categories span the maturity spectrum from established genomic platforms to emerging metabolomic applications gaining clinical traction.
- Genomics:DNA sequence variant analysis dominates hereditary cancer panel workflows, with BRCA and Lynch syndrome testing anchoring reimbursement in Germany and France. Academic medical centers in Boston and San Francisco concentrate multigene panel volume through centralized sequencing core facilities.
- Metabolomics:Lipid and small-molecule profiling platforms achieve clinical-grade reproducibility for cardiovascular risk stratification. German statutory health insurers are evaluating reimbursement for primary prevention programs utilizing lipidomics signatures.
- Proteomics:Protein expression biomarkers support autoimmune predisposition assessment through multiplexed immunoassay formats.
- Transcriptomics:RNA transcript level quantification enables dynamic risk assessment in psychiatric and inflammatory conditions where DNA variants alone prove insufficient.
Genomics retains volume leadership; metabolomics holds the steepest expansion curve.
Therapy Area:
Therapeutic applications distribute across cost tiers from premium-priced oncology panels to emerging rare disease categories.
- Oncology:Hereditary cancer screening commands the highest reimbursement rates with established coverage for BRCA1/2, TP53, and mismatch repair gene testing. The FDA's companion diagnostic mandates compress development timelines for predisposition assays synchronized with therapeutic trials.
- Cardiovascular:Polygenic risk scores for coronary artery disease and heritable cardiomyopathies are penetrating preventive cardiology workflows. Community hospitals in Texas and Florida are adopting portable sequencing configurations to retain specimen volume.
- Neurology:APOE genotyping for Alzheimer's risk stratification faces selective coverage limitations from US payers concerned about clinical utility.
- Rare Diseases:Exome-based predisposition testing for Mendelian conditions concentrates in pediatric genetics institutes and academic referral networks.
Oncology captures the premium pricing tier; cardiovascular applications are expanding most quickly into primary care settings.
End User:
Customer types fragment by procurement sophistication and volume scale, from centralized hospital systems to distributed research networks.
- Diagnostic Labs:High-throughput reference laboratories anchor North American distribution through centralized service networks. These facilities prioritize sample preparation automation and turnaround time metrics for competitive positioning.
- Hospitals:Academic medical centers maintain captive sequencing cores, while community hospitals increasingly outsource to regional reference laboratories.
- Pharmaceutical Companies:Biopharma sponsors embed predisposition biomarkers into Phase I protocols to preempt adverse event liability and accelerate patient stratification.
- Research Institutes:Precompetitive research consortia maintain variant databases supporting pathogenicity classification for rare and novel sequence variants.
Diagnostic labs concentrate the highest test volumes; pharmaceutical companies drive the fastest adoption growth for trial integration.
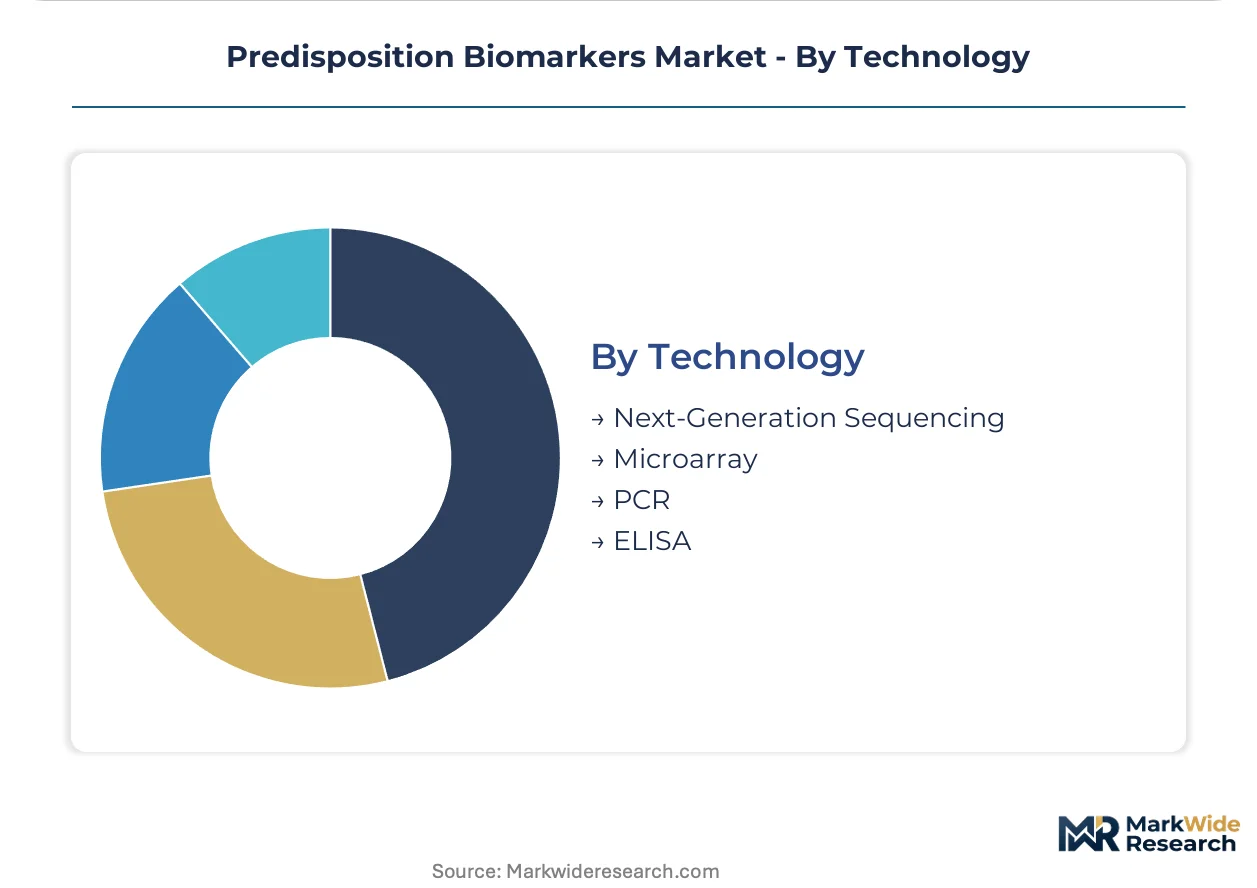
Technology:
Technology platforms distribute across application complexity, from high-throughput discovery to rapid clinical confirmation.
- Next-Generation Sequencing:Multigene panel analysis dominates hereditary risk assessment with established reimbursement frameworks. Long-read architectures from Oxford Nanopore are compressing variant detection workflows from days to hours.
- PCR:Single-site variant confirmation retains margin strength where turnaround time drives purchasing decisions, particularly in time-sensitive oncology workflows.
- Microarray:SNP genotyping platforms support polygenic risk score calculation for common disease predisposition across thousands of variants.
- ELISA:Enzyme-linked immunosorbent assays serve protein biomarker quantification in metabolic and inflammatory predisposition testing.
Next-Generation Sequencing commands the broadest application base; PCR maintains the most resilient margin structure in confirmation workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement expansion for hereditary cancer screening in Germany and France is pulling through demand for multigene risk stratification workflows across developed health systems. National genomic medicine programs in the United Kingdom and South Korea are accelerating clinical integration of predisposition testing. Regulatory frameworks in the United States and Japan are compressing development timelines through companion diagnostic mandates.
United States
Self-insured employers in the Mountain West region contract directly with reference laboratories for workforce genomic screening programs, disintermediating health plan prior authorization layers. The FDA's guidance on companion diagnostics and genomic testing standards accelerates clinical integration of predisposition assays. Academic medical centers in Boston and San Francisco concentrate multigene panel volume through centralized sequencing core facilities.
Germany
Statutory health insurers are evaluating reimbursement for primary prevention programs utilizing lipidomics signatures for cardiovascular predisposition. The country's national pharmaceutical regulator enforces the EU In Vitro Diagnostic Regulation's expanded clinical evidence requirements for genetic risk tests. Diagnostic laboratories in Bavaria and North Rhine-Westphalia prioritize sample preparation automation to reduce hands-on time for high-throughput genomics workflows.
China
Biopharma sponsors embed predisposition biomarkers into Phase I protocols to preempt adverse event liability and accelerate patient stratification. The national medical products administration oversees premarket review of biomarker-based in vitro diagnostics through quality benchmarks aligned with international standards. Genomic testing clusters in Shanghai and Beijing are adopting long-read sequencing architectures to compress variant detection workflows from days to hours.
United Kingdom
The National Health Service's genomic medicine service is expanding access to hereditary cancer panels through regional genomic laboratory hubs. The country's national pharmaceutical regulator aligns with EMA requirements for expanded clinical evidence in genetic risk testing documentation. Research institutes in London and Cambridge maintain precompetitive variant databases supporting pathogenicity classification for rare sequence variants.
Japan
Pharmaceutical companies integrate predisposition biomarkers into precision medicine development programs targeting psychiatric and autoimmune indications. The national pharmaceutical and medical devices agency reviews companion diagnostic submissions synchronized with therapeutic clinical trials. Medical centers in the Kanto region around Tokyo are rebuilding validation cohorts to satisfy evidentiary thresholds for artificial intelligence-enabled variant classification tools.
Predisposition Biomarkers Market Vendor Landscape
On the supply side, the industry is consolidating around integrated diagnostics divisions that sustain captive supply chains across oncology testing workflows. The vendor base stratifies across three tiers: multinational conglomerates with centralized laboratory services networks, specialized assay developers competing on sample preparation automation, and emerging platform vendors advancing real-time sequencing chemistries. Strategic moves concentrate on backward integration into reagent manufacturing and technology licensing partnerships for machine learning-based pathogenicity predictions.
Within the integrated diagnostics tier, Roche Holding AG exemplifies supply chain control through captive manufacturing of amplification and detection reagents. Thermo Fisher Scientific Inc. anchors North American distribution infrastructure through its laboratory services network. QIAGEN N.V. occupies a specialist position in sample preparation automation, reducing hands-on time requirements for high-throughput genomics laboratories processing predisposition screening volumes.
| Leading Market Players |
|---|
| Roche Holding AG |
| Thermo Fisher Scientific Inc. |
| QIAGEN N.V. |
| Illumina Inc. |
| Bio-Rad Laboratories Inc. |
| Myriad Genetics Inc. |
| Agilent Technologies Inc. |
| Merck KGaA |
| Epigenomics AG |
| Others |
Supply Flow & Price Mechanics
Air freight corridors connecting Singapore and South Korea to North American distribution hubs carry polymerase enzymes and modified nucleotides at rates that fluctuate with semiconductor export volumes, compressing margin buffers for assay developers while amplifying price spreads between FDA-certified and laboratory-developed test tiers.
Pricing Analysis
Certification level creates the primary spread across the predisposition biomarker market, with FDA-cleared companion diagnostics commanding premium positioning against CE-marked panels and laboratory-developed tests. Three-tier pricing structure across premium, standard, and economy levels reflects reimbursement status, turnaround time guarantees, and bioinformatics interpretation depth. Cost compression in the standard tier intensifies because direct-to-consumer genotyping platforms erode clinical channel volumes for carrier screening. Diagnostic laboratories exhibit the highest price sensitivity due to thin operating margins, while pharmaceutical sponsors prioritize speed over unit cost in trial-integrated biomarker workflows.
Supply Chain Analysis
Thermo Fisher Scientific's centralized laboratory services network and QIAGEN's automated sample preparation manufacturing anchor North American and European capacity, with reagent production clusters concentrated in Singapore, South Korea, and Germany. Polymerase supply draws from fermentation facilities in Singapore and South Korea, while modified nucleotide synthesis rests on specialty chemical producers in Germany and Switzerland. Single-source vulnerability in Taq polymerase supply exposes assay manufacturers to export control disruptions. Distribution runs through hospital procurement channels that fragment as research institutes build direct sourcing relationships with assay developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The predisposition biomarkers market is entering a cyclical recovery phase as IVDR compliance deadlines filter out undercapitalized competitors and consolidate certified supplier bases.
For Market Incumbents: Insulate core sequencing reagent franchises through backward integration into polymerase fermentation capacity in Singapore or South Korea, while embedding artificial intelligence-enabled variant classification tools into laboratory information management systems to preempt FDA software-as-medical-device enforcement. Long-read sequencing platforms from Oxford Nanopore threaten Illumina's installed base in hereditary cardiovascular panels.
For New Entrants and Emerging Players: Rural Australian and Canadian provincial health systems represent the most penetrable geographic whitespace, where dried blood spot logistics networks bypass clinic-based phlebotomy constraints and expand addressable populations for at-home sample collection models. Target metabolomic risk profiling for cardiovascular predisposition as lipidomics platforms achieve clinical-grade reproducibility ahead of German statutory health insurer reimbursement decisions.
For Investors and Strategic Acquirers: Specialized assay developers with automated sample preparation capabilities and established CE-marking documentation for EU IVDR compliance present the most attractive acquisition profile for portfolio diversification. Bioinformatics workforce scarcity inflates compensation packages and extends turnaround times, signaling capacity constraints that favor platforms with locked-algorithm variant classification tools. Watch for FDA enforcement actions against laboratory-developed tests utilizing unvalidated machine learning scoring as an inflection indicator for regulatory risk repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Compliance Documentation | CE-marking investments filter undercapitalized competitors and consolidate certified supplier bases across European genetic risk testing. |
| Long-Read Sequencing Adoption | Oxford Nanopore's real-time basecalling chemistry compresses variant detection workflows and fragments historical geographic monopolies of Boston and San Francisco hubs. |
| AI-Enabled Variant Classification | FDA's locked-algorithm requirements for machine learning pathogenicity predictions impose twelve-to-eighteen-month validation delays on diagnostic developers. |
| Direct Employer Contracting | Self-insured employers in the Mountain West disintermediate health plan prior authorization layers for workforce genomic screening programs. |
| Metabolomic Risk Profiling | Lipidomics platforms open reimbursement negotiations with German statutory health insurers for cardiovascular primary prevention programs. |
Methodological Framework
Desk research of FDA premarket notification databases, EMA IVDR technical documentation requirements, and Clinical Laboratory Improvement Amendments quality benchmarks preceded structured interviews with diagnostic laboratory directors, biopharma regulatory affairs leads, hospital procurement managers, and bioinformatics platform engineers. Secondary validation drew from SEC filings of publicly traded assay developers, CMS Medicare coverage determinations for preventive genomic testing, and precompetitive research consortium variant database disclosures. Bottom-up test volume estimates from hospital system sequencing cores were triangulated against top-down market sizing from centralized laboratory services networks.
Assumptions held fixed across the projection horizon include sustained FDA companion diagnostic mandate enforcement, stable reimbursement for hereditary cancer panels in Germany and France, and continued polymerase supply concentration in Singapore and South Korea. Segmentation dimensions modeled encompass product type, therapy area, end user, and technology platform, with CAGRs derived from test volume trajectories and average selling price evolution across certification tiers. Forecast inputs incorporated health technology assessment body evaluations of population screening cost-effectiveness and machine learning architecture penetration rates for polygenic risk score calculation.
Practitioners should monitor IVDR transition deadline extensions, FDA software-as-medical-device enforcement patterns, and German statutory health insurer lipidomics reimbursement decisions for early signals of forecast revision. Quarterly review of polymerase export control announcements, companion diagnostic approval synchronizations with therapeutic trials, and bioinformatics specialist compensation inflation is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Spatial OMICS Market
Genomics
North America Whole Exome Sequencing Market
Genomics
Global Pharmacogenomics Market
Genomics
Antisense Oligonucleotides Market
Genomics
Mendelian Disorders Testing Market
Genomics
Global Next-Generation Sequencing (NGS) Services Market
Genomics
Global Long Read Sequencing Market
Genomics
UAE Genetic Testing Market
Genomics
Middle East and Africa Genetic Testing Market
Genomics
Tumor-Sequencing Blood Testing Market
Genomics
Next-Generation Sequencing Data Analysis Market
Genomics
Multiomics Market
Genomics
Retail Genomics Market
Genomics
Global Mirna Sequencing and Assay Market
Genomics
United States DNA Sequencing Products Market
Genomics
Global Gene Expression Market