
 Direct-To-Consumer (DTC) Genetic Testing Market | 2026-2036
Direct-To-Consumer (DTC) Genetic Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Direct-To-Consumer (DTC) Genetic Testing Market Analysis
Clinical-grade reporting standards is unwinding the baseline consumer expectation for DTC genetic tests. 23andMe leverages its database scale to anchor health-risk interpretation services. Ancestry sustains brand dominance in genealogical DNA matching through proprietary reference populations. Dante Labs competes on whole-genome sequencing depth for consumers seeking comprehensive genomic data.
Direct-to-consumer genetic testing involves sample collection, DNA extraction, SNP array or sequencing analysis, and algorithmic interpretation of variants for ancestry, health traits, or pharmacogenomics without clinician intermediation. Saliva collection dominates as the non-invasive standard, while buccal swab methods serve pediatric and elderly cohorts with compliance challenges. Health Testing captures margin pools through physician-ordered follow-up services, whereas Nutrigenomics extends into subscription wellness platforms. Ancestry Testing remains the volume leader but faces saturation in North American markets.
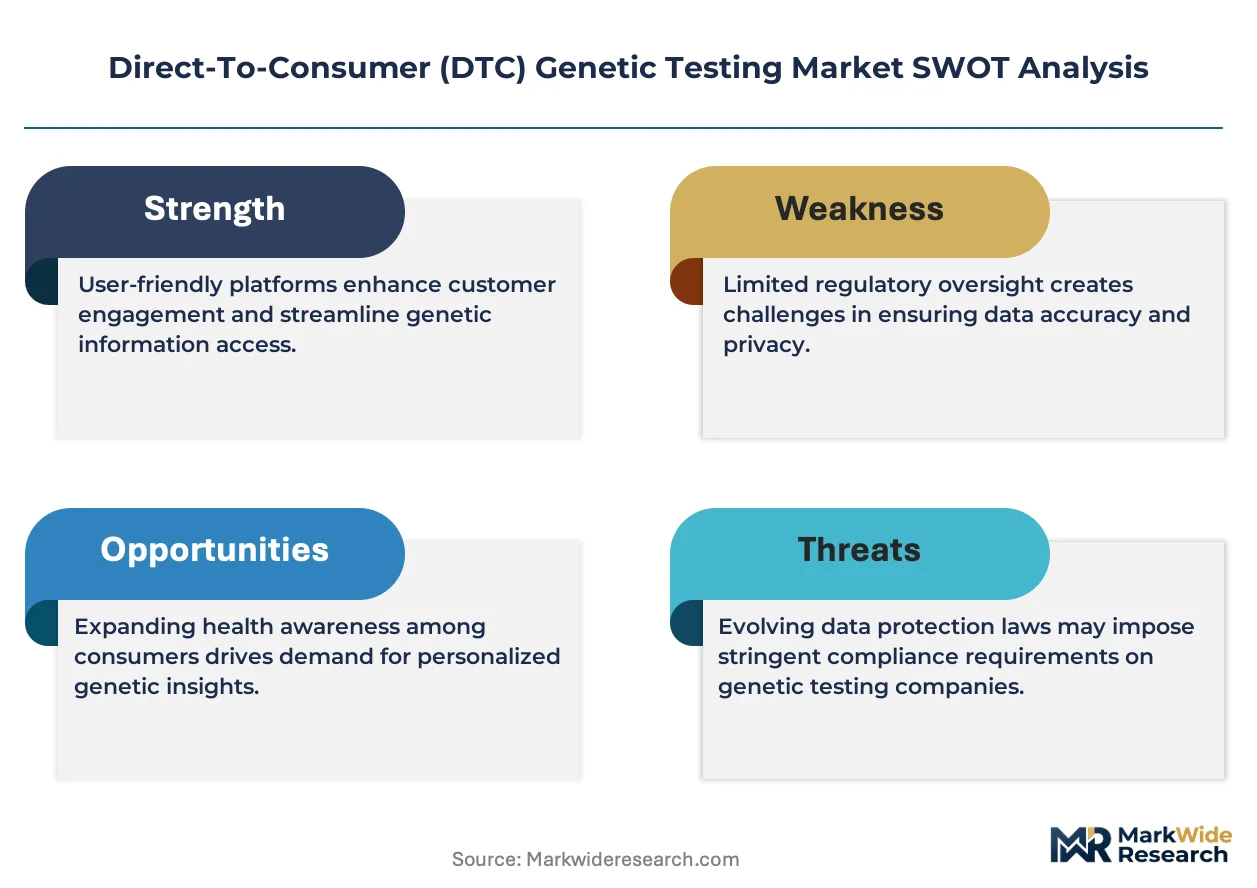
FDA regulates health-related genetic claims as medical devices under 21 CFR 809, while HIPAA governs downstream data privacy for clinical integrations. The EU AI Act and GDPR impose algorithmic transparency and consent requirements on automated health interpretations sold to European consumers. Stakeholders must monitor evolving classification boundaries between wellness information and regulated medical advice across jurisdictions.
Market Dynamics
FDA classification tightening under 21 CFR 809 is compressing the wellness-medical boundary, forcing DTC operators to either pursue full device authorization or retreat to ancestry-only positioning. This regulatory pressure cascades through product development timelines and capital allocation decisions.
Growth Catalysts
- Pharmacogenomic integration:Health systems in the United States are embedding DTC-derived pharmacogenomic data into electronic health records, creating pull-through demand for preemptive genetic screening. This clinical validation loop reinforces consumer willingness to pay for health-risk interpretations.
- HIPAA-compliant clinical pathways:The regulatory framework governing downstream data sharing enables seamless handoffs from consumer-initiated testing to physician-ordered confirmatory diagnostics. This integration expands addressable market depth beyond curiosity-driven purchases.
- Saliva collection standardization:Non-invasive sample methods have collapsed logistical barriers for pediatric and elderly cohorts previously excluded from genetic testing participation. Collection kit automation is driving unit cost reductions at scale.
Market Restraints
- Reference population bias:Proprietary ancestry databases skew toward European-descended populations, degrading interpretive accuracy for African, Asian, and Indigenous genetic backgrounds and limiting market penetration in those demographics.
- SNP array technical ceiling:Single nucleotide polymorphism analysis misses structural variants, copy number variations, and rare disease-causing mutations that whole-genome sequencing captures, constraining clinical utility perceptions.
- GDPR algorithmic transparency mandates:The EU AI Act and GDPR impose explainability requirements on automated health risk scoring that increase compliance costs and slow product launches in European markets.
Strategic Opportunities
- Nutrigenomics subscription platforms:Personalized dietary recommendations based on metabolic genetic profiles are extending customer lifetime value through recurring revenue models. This application bypasses stringent medical device classification while maintaining health-adjacent positioning.
- Whole-genome sequencing cost curves:Sequencing economics are approaching the $200-per-genome threshold, enabling comprehensive genomic data offerings that differentiate from SNP-limited competitors. Early adopters in wellness-committed consumer segments are pre-ordering deep sequencing services.
- Physician-ordered follow-up services:Health Testing margins expand through clinical integration where DTC results trigger reimbursable confirmatory testing and genetic counseling. This channel captures insurance-funded expenditure pools inaccessible to pure consumer-direct models.
Industry Challenges
- Bioinformatics talent scarcity:Variant interpretation algorithm development requires cross-trained computational biologists and clinical geneticists. Recruitment competition with pharmaceutical and academic research institutions is inflating compensation costs.
- CLIA laboratory certification timelines:Clinical Laboratory Improvement Amendments compliance for health-related claims requires 12-18 month validation cycles. Delays in proficiency testing and inspector availability are extending time-to-revenue for new assay launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Direct-To-Consumer (DTC) Genetic Testing Market |
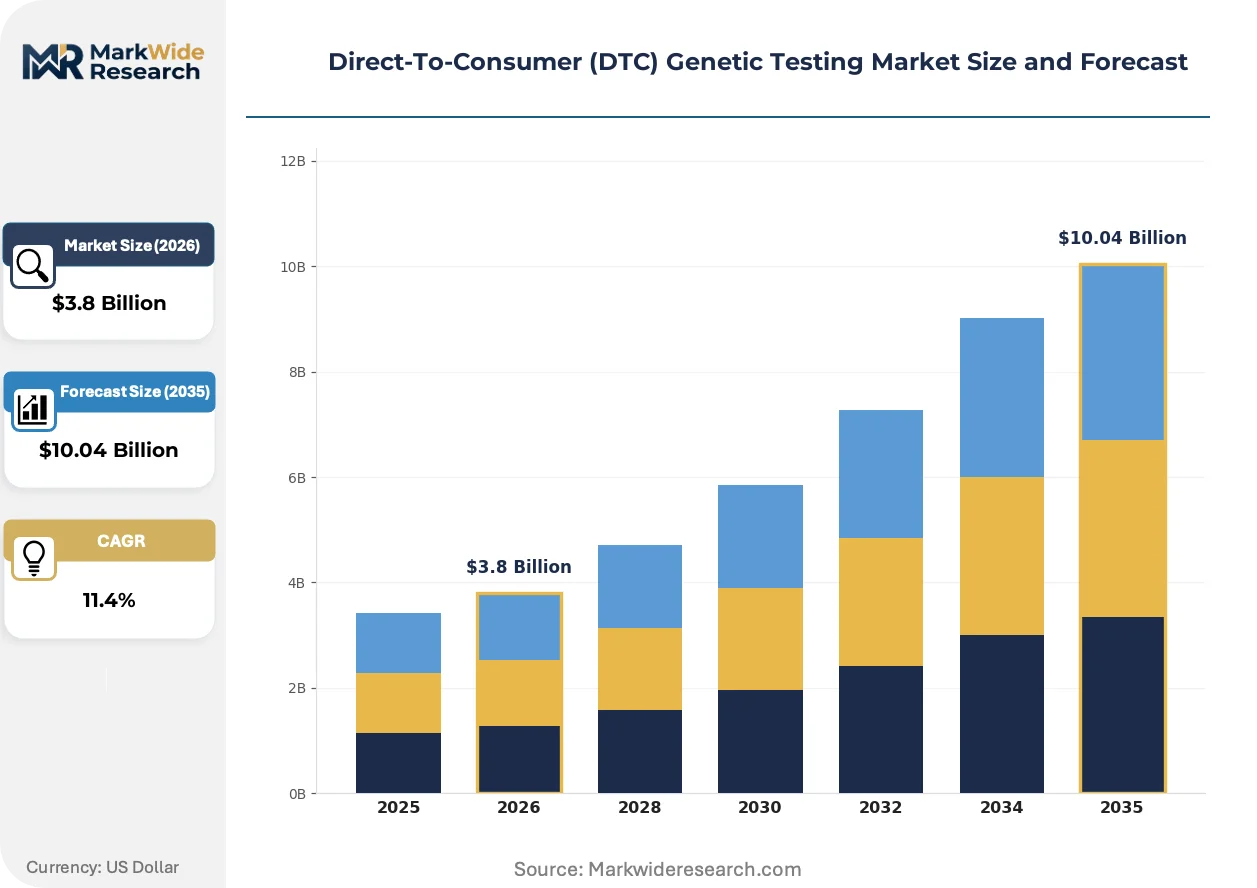
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Health Testing, Ancestry Testing, Predictive Testing, Nutrigenomics Testing Method: Saliva Collection, Blood Sample, Buccal Swab, Fingerstick End User: Individuals, Families, Researchers, Healthcare Providers Distribution Channel: Online Platforms, Retail Outlets, Healthcare Institutions, Direct Sales |
| Companies Covered | 23andMe, Ancestry, MyHeritage Ltd., Family Tree DNA, Gene by Gene, Living DNA Ltd., Color Health, Inc., Dante Labs, Genesis Healthcare Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Direct-To-Consumer (DTC) Genetic Testing Market Emerging Trajectories
Clinical-grade reporting standards are bifurcating consumer expectations, creating divergent demand pools for recreational ancestry exploration versus medically actionable genomic intelligence. This tension reshapes product architecture and pricing architecture simultaneously.
Polygenic risk scoring is bifurcating the health testing segment into single-gene Mendelian disorder screening and complex trait prediction. Wellness platforms are adopting cardiovascular and diabetes risk algorithms while medical-grade offerings emphasize BRCA and Lynch syndrome variants. The technology is bifurcating market positioning between lifestyle optimization and disease prevention narratives.
EU AI Act algorithmic transparency requirements are mandating interpretability documentation for automated health risk assessments sold to European consumers. Laboratory operators must maintain audit trails linking specific genetic variants to published clinical evidence. Germany's Federal Institute for Drugs and Medical Devices is enforcing these provisions through post-market surveillance, compressing deployment timelines for black-box machine learning models.
Subscription-based genetic counseling is displacing one-time test purchases as the dominant commercial model. Consumers in the United States are purchasing ongoing access to variant re-interpretation as scientific knowledge evolves. This behavioral shift concentrates lifetime value in relationship-driven service platforms rather than transactional kit sales, with highest penetration among family-planning demographics seeking hereditary cancer risk monitoring.
Direct-To-Consumer (DTC) Genetic Testing Market Segmentation
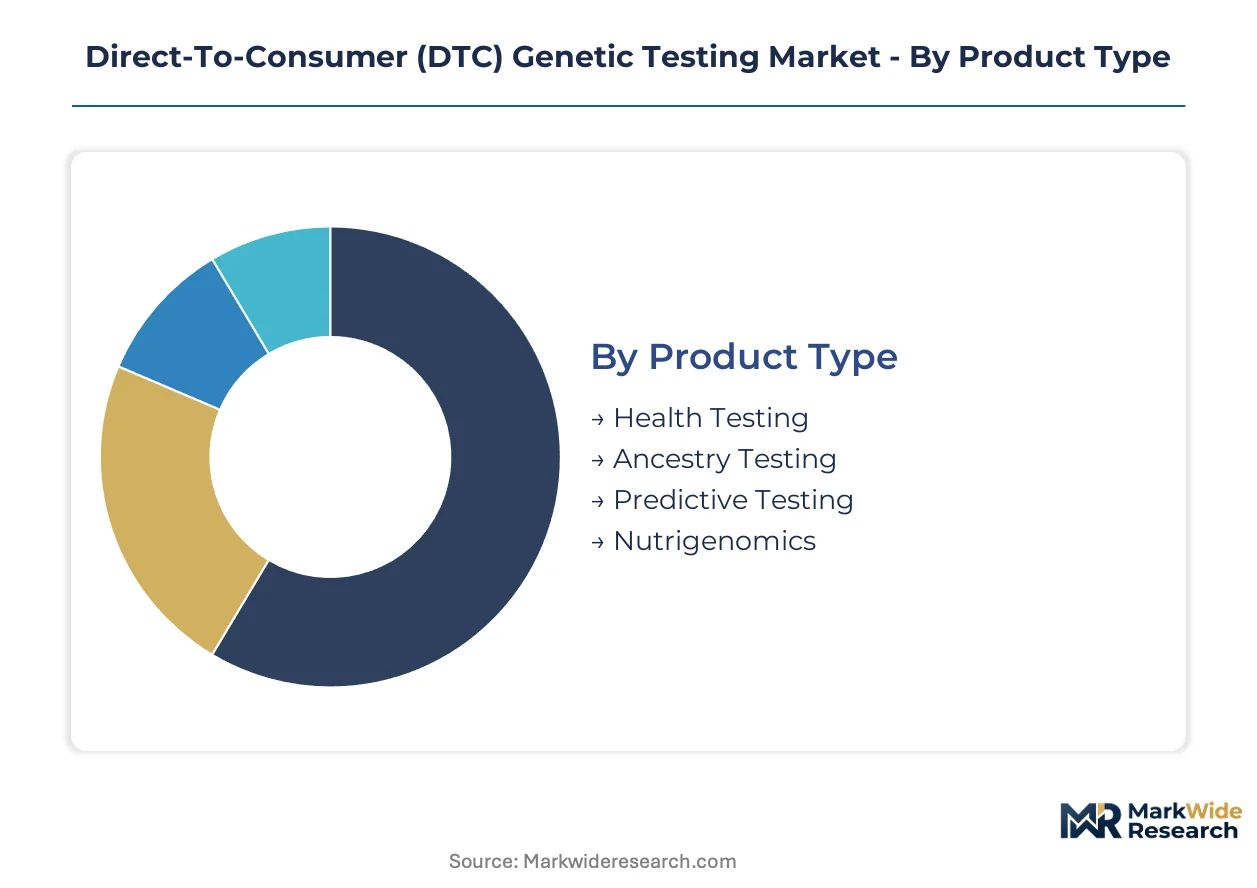
Regulatory boundaries fragment DTC genetic testing into distinct product categories with divergent compliance burdens. Testing method selection directly shapes laboratory certification requirements and consumer accessibility profiles.
Product Type:
FDA oversight intensity varies sharply across health claim categories, creating tiered market access barriers.
- Health Testing:Medical-grade variant interpretation for hereditary cancer and carrier status triggers 21 CFR 809 device classification. United States health systems embed pharmacogenomic results into Epic and Cerner EHRs, pulling through physician-ordered confirmatory testing.
- Ancestry Testing:Genealogical DNA matching against proprietary reference populations operates outside FDA medical device jurisdiction. Consumer familiarity with ethnicity estimates remains highest in the United States, though European-descended database bias degrades accuracy for African and Asian genetic backgrounds.
- Predictive Testing:Polygenic risk scoring for complex traits occupies a regulatory gray zone between wellness and medical advice. EU AI Act algorithmic transparency mandates impose explainability documentation on European sales.
- Nutrigenomics:Metabolic genetic profiles for personalized dietary recommendations bypass stringent medical classification. Subscription wellness platforms in the United States extend customer lifetime value through recurring revenue models.
Ancestry Testing handles the majority of throughput; Health Testing is expanding most quickly on share.
Testing Method:
Sample collection logistics determine pediatric and elderly cohort penetration, with automation economics driving unit cost curves.
- Saliva Collection:Non-invasive buccal cell harvesting via stabilized buffer tubes dominates kit-based DTC distribution. Automated extraction workflows at CLIA-certified laboratories achieve scale economies that compress per-sample processing costs.
- Buccal Swab:Cytobrush sampling serves compliance-challenged demographics including infants and nursing home residents. Collection failure rates run higher than saliva methods, requiring kit replacement logistics.
- Blood Sample:Fingerstick capillary blood spots enable metabolic and pharmacogenomic assays requiring plasma biomarkers. Clinical integration pathways favor this method for physician-ordered follow-up diagnostics.
- Fingerstick:Point-of-care lancet collection supports immediate result delivery in retail pharmacy settings. Dried blood spot stability simplifies transport without cold chain requirements.
Saliva Collection commands the volume base; Buccal Swab shows the steepest expansion trajectory among accessibility-focused segments.
End User:
Customer archetypes stratify by data literacy, privacy tolerance, and clinical integration willingness.
- Individuals:Curiosity-driven consumers purchasing single-kit ancestry or trait analysis represent the transactional revenue foundation. Privacy-conscious cohorts in Germany and California exhibit heightened sensitivity to biobank data retention policies.
- Families:Multi-generational pedigree building and hereditary risk assessment drive higher average order values. Family-planning demographics seek ongoing variant re-interpretation as scientific knowledge evolves.
- Researchers:Academic institutions license aggregated, de-identified genotype-phenotype databases for GWAS discovery. 23andMe and Ancestry monetize research partnerships separately from consumer-facing revenue.
- Healthcare Providers:Physician-ordered DTC testing bridges consumer-initiated screening with reimbursable clinical genetics. HIPAA-compliant data handoffs enable seamless EHR integration in United States health systems.
Individuals generate the bulk of kit sales; Healthcare Providers are climbing the fastest on margin contribution.
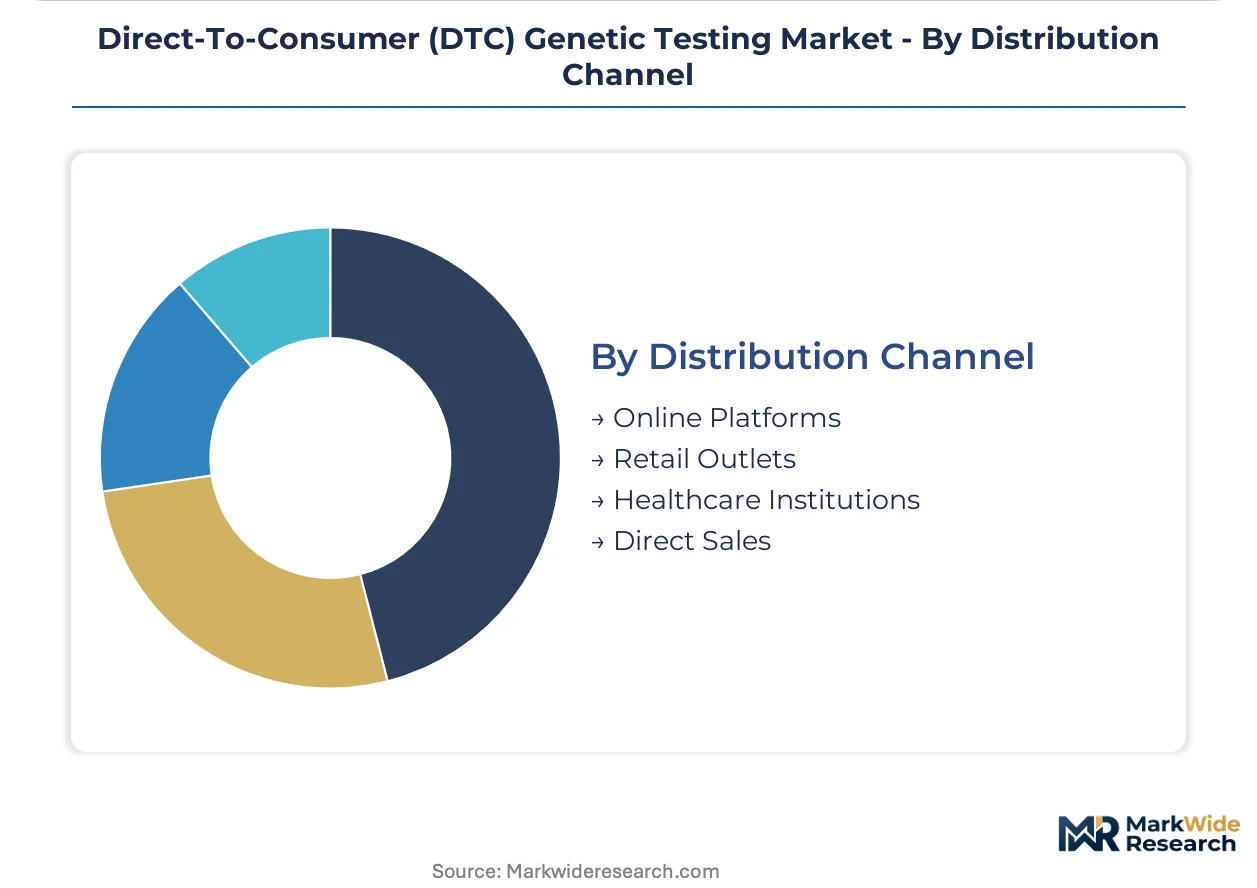
Distribution Channel:
Channel selection determines regulatory exposure, customer acquisition cost, and service attach rates.
- Online Platforms:Direct-to-consumer e-commerce with telehealth-integrated genetic counseling dominates United States market development. Digital native brands leverage subscription mechanics for lifetime value expansion.
- Retail Outlets:Pharmacy and big-box shelf placement captures impulse purchasers seeking giftable health products. CVS and Walgreens distribution requires FDA-compliant labeling for health-related claims.
- Healthcare Institutions:Hospital-affiliated laboratories and employee wellness programs embed DTC testing within clinical workflows. This channel captures insurance-funded expenditure pools inaccessible to pure consumer-direct models.
- Direct Sales:Multi-level marketing and employer benefit consultants target underserved demographics with high-touch education. Regulatory scrutiny of health claims intensifies for non-clinical sales contexts.
Online Platforms carry the majority of transaction flow; Healthcare Institutions are gaining share fastest on clinical validation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Laboratory certification and database scale concentrate competitive advantage in jurisdictions with mature clinical genetics infrastructure and permissive direct-to-consumer sales frameworks. Regulatory fragmentation across major economies forces operators to maintain parallel compliance architectures.
United States
FDA 21 CFR 809 classification for health-related claims creates tiered market access where CLIA-certified laboratories dominate medically actionable segments. HIPAA-compliant data pathways enable seamless EHR integration at health systems using Epic and Cerner platforms. The San Francisco Bay Area anchors database-scale operators while Boston's research corridor drives polygenic risk algorithm development.
Germany
BfArM medical device registration requirements and GDPR genetic data protections impose stringent consent documentation on DTC health offerings. The EU AI Act mandates algorithmic transparency for automated risk scoring sold to German consumers. Munich and Berlin concentrate bioinformatics talent pools serving both clinical diagnostic and consumer-facing genomic interpretation platforms.
United Kingdom
Medicines and Healthcare products Regulatory Agency oversight of health-related genetic claims operates alongside NHS genomic medicine service integration for clinically validated results. Genomics England's 100,000 Genomes Project established reference population infrastructure benefiting ancestry database accuracy. The Cambridge-London corridor houses sequencing technology developers and direct-to-consumer platform operators.
China
NMPA medical device classification for health-risk genetic testing requires clinical trial validation for market authorization, compressing the addressable consumer segment. National human genetic resource regulations restrict cross-border data transfer and foreign database access. Shenzhen and Beijing concentrate domestic sequencing platform manufacturers and genealogy service providers serving Han Chinese demographic majorities.
Australia
TGA medical device framework classifies health-related genetic tests according to risk stratification, with lower-risk ancestry products operating outside therapeutic goods jurisdiction. The National Health and Medical Research Council governs human research ethics for biobank-derived genomic studies. Sydney and Melbourne host clinical genetics services bridging consumer-initiated screening with specialist referral pathways.
Direct-To-Consumer (DTC) Genetic Testing Market Vendor Landscape
Concentration sits with database-scale ancestry platforms and clinical-grade health testing specialists. The vendor base spans three tiers: mass-market ancestry providers with proprietary reference populations, health-focused operators pursuing FDA device authorization, and whole-genome sequencing specialists competing on data depth. Strategic moves center on CLIA laboratory certification expansion and physician-ordered follow-up service integration to capture insurance-funded expenditure pools.
Within the database-scale tier, 23andMe and Ancestry occupy positions defined by consumer sample volume and longitudinal phenotype collection. Dante Labs exemplifies the comprehensive sequencing archetype targeting wellness-committed consumers seeking rare variant detection beyond SNP array limitations. These three entities represent divergent competitive vectors: population-scale biobank monetization, genealogical network effects, and clinical-grade data depth respectively.
| Leading Market Players |
|---|
| 23andMe |
| Ancestry |
| MyHeritage Ltd. |
| Family Tree DNA |
| Gene by Gene |
| Living DNA Ltd. |
| Color Health, Inc. |
| Dante Labs |
| Genesis Healthcare Co. |
| Others |
Supply Flow & Price Mechanics
Capacity reservation agreements with CLIA-certified laboratories lock in processing slots and stabilize per-unit costs for health-testing operators navigating FDA 510(k) validation timelines. These contractual structures anchor price visibility against sequencing reagent volatility while securing throughput priority during demand surges.
Pricing Analysis
FDA 21 CFR 809 device classification dictates the pricing tier structure across the DTC genetic testing landscape. Three-tier pricing structure across premium, standard, and economy levels separates whole-genome sequencing services from SNP-based health panels and ancestry-only kits. Price differentiation rests on CLIA certification grade and physician-ordered follow-up service bundling. Cost compression in the standard tier is intensifying because reference population database maintenance expenses are rising faster than kit volume growth. Individual curiosity-driven purchasers exhibit highest price sensitivity, whereas family-planning demographics seeking hereditary cancer monitoring demonstrate lowest elasticity.
Supply Chain Analysis
Container availability on Asia-Pacific to North America trade lanes constrains reagent and sequencing instrument delivery schedules for laboratory operators scaling CLIA capacity. Manufacturing concentration centers on the United States, China, and Germany for DNA extraction chemistries, microarray consumables, and next-generation sequencing platforms. Raw material dependencies draw from optical polymers for flowcell production, fluorophore-labeled nucleotides, and stabilized buffer formulations. Single-source vulnerability sits with Illumina's dominance in sequencing instrument supply. Distribution runs through direct laboratory procurement channels for high-volume operators and distributor networks for smaller DTC kit assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based genetic counseling services are expanding faster than transactional kit sales, converting one-time purchasers into recurring revenue relationships through variant re-interpretation access.
For Market Incumbents: Fortify CLIA laboratory certification moats by accelerating proficiency testing inspector relationships and expanding physician-ordered follow-up service networks. Database-scale operators face margin pressure from whole-genome sequencing specialists capturing wellness-committed consumers seeking rare variant detection. Vertical integration into in-house sequencing instrument maintenance capabilities reduces dependency on single-source platform vendors. For New Entrants and Emerging Players: Anchor in nutrigenomics subscription platforms where regulatory classification remains outside FDA medical device jurisdiction. The most penetrable segment comprises metabolic genetic profiling for personalized dietary recommendations delivered through wellness app ecosystems. A telehealth-integrated genetic counseling go-to-market angle bypasses traditional laboratory sales force requirements. For Investors and Strategic Acquirers: CLIA-certified mid-cap laboratories with established health system EHR integration represent the highest-conviction acquisition target archetype for platform consolidation plays. Long-term viability hinges on capturing insurance-funded confirmatory testing expenditure pools rather than pure consumer-direct transaction models. The signal to watch is FDA 510(k) clearance velocity for polygenic risk scoring algorithms, which would validate complex trait prediction as a reimbursable clinical service.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Laboratory Certification Expansion | Enables health-related claims under FDA 21 CFR 809 device classification, unlocking physician-ordered revenue channels. |
| Physician-Ordered Follow-Up Service Integration | Captures insurance-funded confirmatory testing and genetic counseling expenditure pools inaccessible to pure DTC models. |
| Subscription Genetic Counseling Platform Development | Converts transactional kit purchasers into recurring revenue relationships through ongoing variant re-interpretation access. |
| Whole-Genome Sequencing Cost Curve Positioning | Differentiates from SNP-limited competitors as per-genome economics approach the $200 threshold for wellness segments. |
| HIPAA-Compliant EHR Integration Pathway | Enables seamless data handoffs from consumer-initiated screening to Epic and Cerner health system workflows. |
Methodological Framework
A spread of perspectives from laboratory operations directors, CLIA compliance officers, genetic counseling service managers, and health system EHR integration specialists converged on the working assumptions shaping this analysis. Primary fieldwork with DTC platform executives and CLIA-certified laboratory administrators combined with secondary validation against FDA 510(k) filing databases, CMS reimbursement code trackers, and EU medical device registration portals. Bottom-up kit volume estimates triangulated against top-down addressable consumer spending projections.
Segmentation dimensions modeled span product type, testing method, end user archetype, and distribution channel across the projection horizon. Analytical framework deployment tracked health-testing margin expansion against ancestry-testing volume saturation through the forecast period. CAGRs were derived from regression analysis of historical kit shipment data and laboratory capacity expansion announcements. Industry-specific forecast inputs incorporated pharmacogenomic EHR integration adoption curves and EU AI Act algorithmic transparency compliance cost estimates.
Material uncertainties — regulatory reclassification of polygenic risk scoring, CLIA inspector availability bottlenecks, and sequencing reagent supply disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions about consumer privacy tolerance and health system willingness to integrate DTC-derived data. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
China Genetic Testing Market
Genomics
Global Mirna Sequencing and Assay Market
Genomics
Next Generation Sequencing (NGS) Informatics Market
Genomics
Genetic Analysis Services Market
Genomics
PCR and NGS Based Diagnostic Testing Market
Genomics
Global Genotyping Assay Market
Genomics
Digital Genome Market
Genomics
Targeted DNA RNA Sequencing Market
Genomics
Agrigenomics Market
Genomics
Genomic Biomarkers Market
Genomics
Next-Generation Sequencing for Non-Invasive Prenatal Testing Market
Genomics
Global Gene Expression Market
Genomics
Global Clinical Oncology Next Generation Sequencing Market
Genomics
Dna Polymerase Market
Genomics
Alagille Syndrome Market
Genomics
Spatial OMICS Market