
 Gene Synthesis (Research Use) Market | 2026-2036
Gene Synthesis (Research Use) Market Size, Share, and Industry Trends Forecast 2026-2036
Gene Synthesis (Research Use) Market Analytics
FDA oversight of synthetic nucleic acids is realigning the cost-of-entry calculus for gene synthesis providers serving research markets. GenScript Biotech Corporation leverages its vertically integrated manufacturing footprint across China and the United States to sustain cost advantages in custom gene production. Twist Bioscience Corporation anchors its competitive position through proprietary silicon-based DNA synthesis platforms that dominate high-throughput oligonucleotide markets. Integrated DNA Technologies competes on rapid turnaround times and specialized modification chemistries for demanding academic and pharmaceutical research workflows.
Gene synthesis for research use encompasses the de novo chemical assembly of DNA sequences ranging from short oligonucleotides to multi-kilobase gene constructs, employing phosphoramidite chemistry or enzymatic methods to achieve sequence fidelity typically exceeding 99.9% for standard applications. The primary commercial purpose centers on enabling hypothesis-driven molecular biology, protein engineering, and pathway construction without template-dependent amplification. Oligonucleotide synthesis occupies the highest volume tier due to its foundational role in PCR primer supply and CRISPR guide RNA production, while synthetic biology applications capture expanding margin pools as multigene pathway orders grow in complexity and value per project. Academic institutes represent the most fragmented yet largest addressable end-user base, though pharmaceutical firms generate superior per-customer revenue concentration through recurring high-complexity orders.
The FDA, EPA, and NIH Guidelines for Research Involving Recombinant or Synthetic Nucleic Acid Molecules collectively shape product standards, biosafety classifications, and institutional approval requirements that filter market access for gene synthesis vendors. ISO 13485 and GLP-adjacent quality benchmarks further segment suppliers into certified tiers that determine eligibility for pharmaceutical and clinical-translational research contracts. Stakeholders must monitor emerging biosecurity frameworks governing sequence screening and customer verification, as regulatory tightening in this domain will likely redefine operational overhead and competitive differentiation across the supplier landscape.
Market Dynamics
CRISPR-based gene editing workflows are pulling research-grade gene synthesis into higher-complexity, higher-volume procurement patterns as academic labs automate multigene pathway construction. This technology shift is compressing turnaround expectations and fragmenting supplier tiers by technical capability.
Growth Catalysts
- NIH Guidelines for Research Involving Recombinant or Synthetic Nucleic Acid Molecules:These biosafety protocols institutionalize gene synthesis procurement across federally funded U.S. research institutions, embedding vendor relationships into grant compliance workflows.
- Enzymatic DNA synthesis:This emerging chemistry platform reduces phosphoramidite waste streams and enables longer accurate reads, attracting sustainability-focused European academic consortia.
- Boston-San Francisco biotech clustering:Geographic concentration of venture-backed synthetic biology startups sustains premium demand for rapid-turnaround custom gene production with specialized modification chemistries.
Market Restraints
- Phosphoramidite raw material concentration:Supply of certified-grade reagents concentrates among specialty chemical producers in Germany and Switzerland, exposing synthesis providers to input cost volatility and currency risk.
- Sequence screening mandates:U.S. Select Agent Regulations and EU biosecurity frameworks impose customer verification and pathogen sequence detection requirements that add fixed compliance overhead regardless of order size.
- Template-dependent amplification alternatives:PCR-based gene retrieval from natural sources remains cost-competitive for simple constructs, capping pricing power in the economy synthesis tier.
Strategic Opportunities
- India's expanding biotechnology research infrastructure:Department of Biotechnology funding and IISc-IIT institutional networks create underpenetrated demand for outsourced gene synthesis as domestic phosphoramidite production scales.
- Cell-free protein synthesis integration:Convergence of synthetic DNA supply with in vitro expression systems enables suppliers to capture downstream value through bundled construct-to-protein workflows.
- ISO 13485 certification gap:Suppliers achieving medical-device-grade quality systems access pharmaceutical translational research contracts that standard academic-grade vendors cannot serve.
Industry Challenges
- Bioinformatics pipeline integration:Customer demand for direct LIMS-compatible sequence submission and automated quality reporting forces capital investment in software infrastructure that smaller synthesis shops struggle to fund.
- Multigene pathway assembly complexity:Rising order complexity for 10+ gene operon projects exposes quality control bottlenecks, with error rates compounding across junction sites and delaying delivery commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gene Synthesis (Research Use) Market |
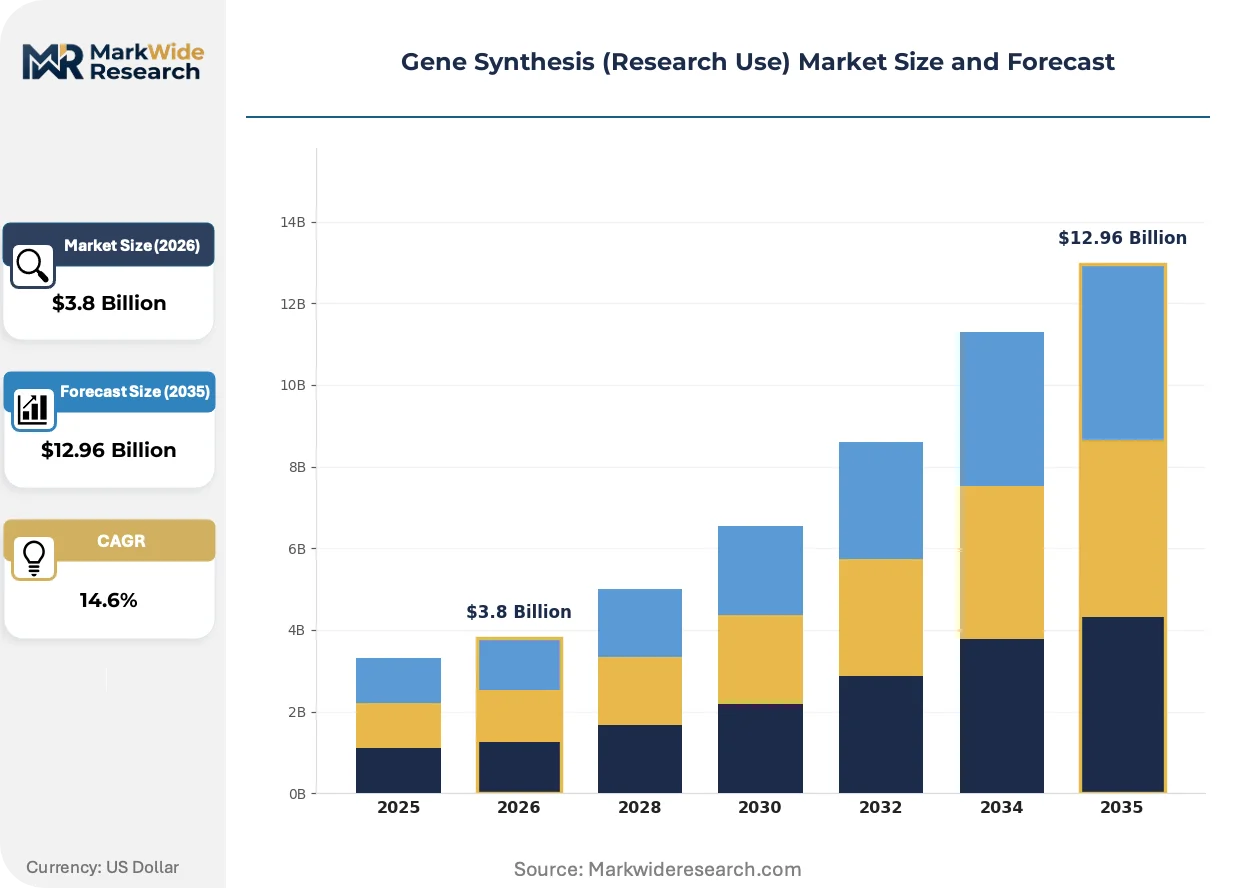
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oligonucleotides, Genes, Clones, Vectors End User: Academic Institutes, Biotechnology Companies, Pharmaceutical Firms, Research Laboratories Technology: Polymerase Chain Reaction, Next-Generation Sequencing, Microarray, CRISPR Application: Gene Expression Analysis, Synthetic Biology, Genetic Engineering, Vaccine Development |
| Companies Covered | GenScript Biotech Corporation, Thermo Fisher Scientific Inc., Twist Bioscience Corporation, Integrated DNA Technologies (Danaher), Azenta Inc. (GENEWIZ), Boster Biological Technology, ProteoGenix, Biomatik Corporation, OriGene Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gene Synthesis (Research Use) Market Evolving Landscape
Synthetic biology toolsets are compressing the design-build-test cycle for engineered organisms, forcing gene synthesis providers to embed themselves deeper into iterative research workflows rather than remaining transactional suppliers.
Enzymatic DNA synthesis platforms are expanding into the research gene synthesis market by enabling kilobase-scale accurate assembly without the error accumulation typical of phosphoramidite chemistry. Academic synthetic biology programs at MIT, ETH Zurich, and Tsinghua University are piloting these systems for multigene pathway construction. This technology is expanding into applications previously reserved for traditional chemical synthesis, compressing the cost curve for complex constructs and pressuring incumbent platform economics.
The FDA's evolving oversight of synthetic nucleic acids under the NIH Guidelines is tightening sequence screening and customer verification requirements for U.S.-based suppliers. Vendors must now maintain documented screening protocols and institutional biosafety committee liaison functions to retain eligibility for federally funded contracts. Research divisions of pharmaceutical firms are responding by consolidating supplier relationships toward vendors with pre-validated compliance infrastructure, fragmenting the competitive landscape into certified and non-certified tiers.
Research procurement teams are unbundling after-sales support from base synthesis pricing, negotiating standalone bioinformatics and construct optimization consulting as separate line items. This behavioral shift disrupts the traditional all-inclusive pricing model and exposes technical service capabilities as a standalone competitive battlefield. The pattern is most visible among Wellcome Trust and Howard Hughes Medical Institute-funded labs, where grant administrators now require detailed service-item invoicing for audit compliance.
Gene Synthesis (Research Use) Market Segmentation
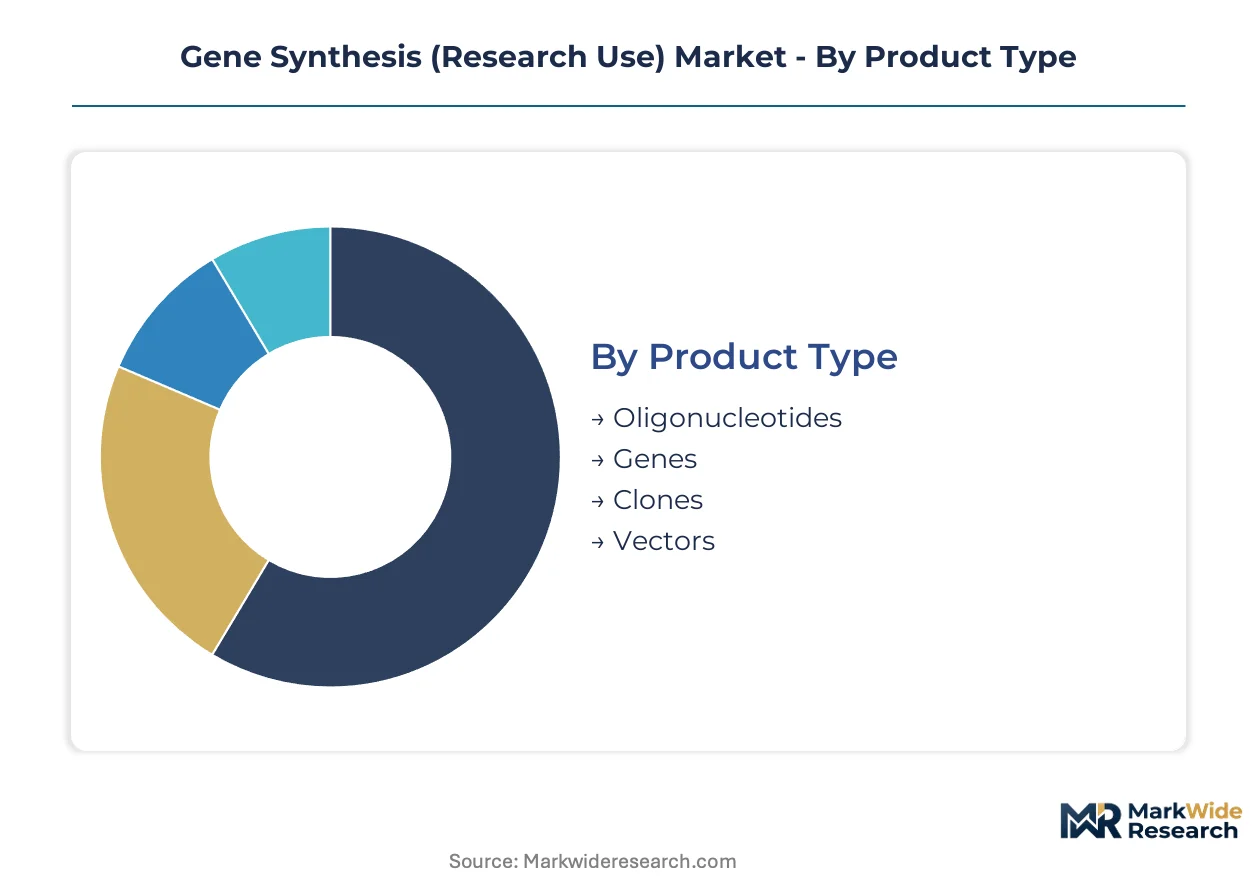
Segmentation in gene synthesis research markets reveals how technical complexity, regulatory exposure, and workflow integration depth fragment purchasing behavior across customer tiers. Suppliers must align production capabilities and compliance infrastructure with the specific demands of each segment cluster.
Product Type:
Oligonucleotides function as standalone procurement items for routine molecular biology, while genes and vectors embed into extended workflow chains requiring compatibility with downstream expression systems.
- Oligonucleotides:Short single-stranded DNA or RNA sequences synthesized via phosphoramidite chemistry, typically 15-120 nucleotides in length with 99.9% fidelity specifications. Demand concentrates in academic PCR primer supply and CRISPR guide RNA production workflows across NIH-funded U.S. institutions, where procurement volume scales with grant cycle timing and biosafety committee approval schedules.
- Genes:Multi-kilobase DNA constructs assembled de novo without template dependence, enabling codon optimization and synthetic pathway construction. Pharmaceutical translational research units in Boston and San Francisco biotech clusters drive premium demand for rapid-turnaround custom production with specialized modification chemistries and ISO 13485-adjacent quality documentation.
- Clones:Pre-assembled gene inserts in ready-to-use plasmid backbones, reducing in-house molecular cloning steps for time-constrained research programs.
- Vectors:Engineered delivery vehicles for gene transfer applications, including viral and non-viral systems optimized for specific cell types and expression requirements.
Volume placements concentrate in Oligonucleotides; the faster expansion belongs to Genes as multigene pathway orders grow in complexity.
End User:
Customer type determines pricing tolerance, compliance burden, and technical service intensity, with academic and commercial segments operating on fundamentally different procurement timelines and quality benchmarks.
- Academic Institutes:Federally funded research institutions with fragmented purchasing authority distributed across individual principal investigators. Grant compliance workflows under NIH Guidelines institutionalize vendor relationships, though per-customer revenue concentration remains low relative to commercial segments.
- Pharmaceutical Firms:Large and mid-cap drug developers with consolidated supplier management functions and recurring high-complexity orders for therapeutic candidate development. FDA oversight of synthetic nucleic acids is tightening sequence screening requirements, pushing these customers toward vendors with pre-validated compliance infrastructure.
- Biotechnology Companies:Venture-backed synthetic biology startups clustered around Boston and San Francisco, sustaining premium demand for rapid-turnaround production with specialized modification capabilities.
- Research Laboratories:Government, nonprofit, and contract research facilities with mixed funding sources and variable technical specifications.
Revenue concentration peaks with Pharmaceutical Firms; Biotechnology Companies are gaining share fastest as venture deployment into synthetic biology accelerates.
Technology:
Technology segments align with distinct workflow positions, from upstream sequence amplification through downstream editing and analysis functions.
- CRISPR:RNA-guided nuclease systems enabling precise genomic modifications with reduced off-target effects compared to earlier editing platforms. Academic labs automating multigene pathway construction are pulling gene synthesis into higher-complexity, higher-volume procurement patterns as guide RNA and donor template demand scales with editing throughput.
- Polymerase Chain Reaction:Thermal cycling amplification of DNA segments from template sources, remaining cost-competitive for simple construct retrieval from natural sources.
- Next-Generation Sequencing:High-throughput parallel sequencing platforms for construct verification and quality control, increasingly integrated into supplier bioinformatics pipelines.
- Microarray:Solid-phase oligonucleotide synthesis for multiplexed gene expression profiling and variant detection applications.
Procurement intensity clusters around CRISPR workflows; Next-Generation Sequencing integration is climbing the fastest as quality verification demands tighten.
Application:
Application segments span the research value chain from basic molecular characterization through engineered organism construction and therapeutic development.
- Synthetic Biology:Design and construction of novel biological systems and pathways, including multigene operon assembly and metabolic engineering. European academic consortia piloting enzymatic DNA synthesis platforms are expanding this segment into applications previously reserved for traditional chemical synthesis, compressing cost curves for complex constructs.
- Gene Expression Analysis:Quantification of transcript levels and regulatory mechanisms, foundational to hypothesis-driven molecular biology research programs.
- Genetic Engineering:Directed modification of organism genomes for improved phenotypes or novel functions, spanning agricultural and industrial biotechnology applications.
- Vaccine Development:Synthetic DNA-based antigen design and nucleic acid vaccine vector construction, with regulatory pathways shaped by FDA and EMA oversight frameworks.
Margin capture concentrates in Synthetic Biology; Vaccine Development is expanding most quickly as mRNA platform investments sustain nucleic acid synthesis demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized biotechnology economic zones in the United States, Switzerland, and Singapore concentrate gene synthesis demand through tax-advantaged R&D infrastructure and streamlined biosafety permitting. These zones anchor procurement intensity for custom DNA production.
United States
NIH grant cycles and institutional biosafety committee workflows institutionalize vendor relationships across federally funded research institutions. The FDA's evolving oversight of synthetic nucleic acids tightens sequence screening requirements for domestic suppliers. Boston and San Francisco biotech clusters sustain premium demand for rapid-turnaround custom gene production with specialized modification chemistries.
Switzerland
ETH Zurich and Basel-area pharmaceutical research units drive demand for high-fidelity multigene pathway construction. Swissmedic oversight frameworks align with EU biosecurity standards while permitting flexible research exemptions. The Greater Zurich Area anchors enzymatic DNA synthesis pilot programs as European academic consortia test alternative chemistry platforms.
China
Tsinghua University and CAS institutional networks expand domestic phosphoramidite production capacity to reduce import dependence. NMPA guidelines for synthetic nucleic acid research shape compliance requirements for domestic suppliers. Yangtze River Delta biotech parks attract venture-backed synthetic biology startups seeking integrated manufacturing partnerships.
Germany
Max Planck Institute and Helmholtz Centre research programs sustain demand for complex synthetic constructs. ECHA REACH regulations govern phosphoramidite chemical handling and waste stream management. Munich and Heidelberg clusters concentrate CRISPR-based workflow adoption as academic labs automate multigene pathway construction.
India
Department of Biotechnology funding and IISc-IIT institutional networks create expanding demand for outsourced gene synthesis. CDSCO research-use exemptions for synthetic nucleic acids reduce regulatory friction for academic procurement. Bangalore and Hyderabad biotech corridors scale domestic phosphoramidite production to capture regional supply contracts.
Gene Synthesis (Research Use) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered quality and compliance segments. The vendor base separates into certified pharmaceutical-grade suppliers, rapid-turnaround academic specialists, and emerging enzymatic platform operators. Three strategic archetypes dominate: vertically integrated manufacturers with captive chemical supply, silicon-based high-throughput platform operators, and rapid-turnaround service specialists with deep modification chemistry expertise. Capacity expansion and ISO 13485 certification drives competitive positioning as pharmaceutical customers consolidate supplier relationships.
Within the vertically integrated tier, GenScript Biotech Corporation represents manufacturers with cross-border production footprints spanning China and the United States. Among platform-technology specialists, Twist Bioscience Corporation exemplifies silicon-based DNA synthesis operators dominating high-throughput oligonucleotide markets. On the rapid-turnaround vector, Integrated DNA Technologies anchors specialists competing on turnaround speed and specialized modification capabilities for demanding research workflows.
| Leading Market Players |
|---|
| GenScript Biotech Corporation |
| Thermo Fisher Scientific Inc. |
| Twist Bioscience Corporation |
| Integrated DNA Technologies (Danaher) |
| Azenta Inc. (GENEWIZ) |
| Boster Biological Technology |
| ProteoGenix |
| Biomatik Corporation |
| OriGene Technologies Inc. |
| Others |
Value Network & Pricing Analysis
Pharmaceutical procurement teams consolidating supplier relationships under FDA sequence screening mandates are compressing vendor margins and forcing capacity investments in certified production infrastructure. This buyer-side consolidation is reshaping how synthesis providers structure pricing tiers and where they locate manufacturing assets.
Pricing Analysis
Expedited turnaround premiums dominate pricing differentiation in gene synthesis, with Boston and San Francisco biotech clusters paying substantial markups for sub-72-hour delivery of complex multigene constructs. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified pharmaceutical-grade production from academic-grade and spot-inventory tiers. Cost compression in the economy oligonucleotide tier is intensifying because PCR-based retrieval from natural sources caps pricing power for simple constructs. Academic institutes exhibit highest price sensitivity, while pharmaceutical translational research units absorb premium pricing for compliance documentation and rapid turnaround.
Supply Chain Analysis
Skilled technical workforce availability in Germany, Switzerland, and the United States anchors phosphoramidite chemistry production and quality control operations for high-fidelity synthesis. Supply draws from concentrated specialty chemical producers in Germany and Switzerland for certified-grade phosphoramidite reagents, from China for bulk nucleotide precursors, and from domestic fermentation facilities for enzymatic synthesis enzymes. Single-source vulnerability in phosphoramidite feedstock exposes providers to input cost volatility and currency risk. Distribution runs through direct vendor relationships with institutional procurement offices, supplemented by specialized distributors serving fragmented academic principal investigator networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic DNA synthesis platforms are displacing phosphoramidite chemistry in multigene pathway applications, compressing the technology transition window for incumbent asset positions. This chemistry shift demands immediate strategic repositioning across stakeholder archetypes.
For Market Incumbents: Deepen ISO 13485 certification coverage across production footprints to defend pharmaceutical contract eligibility against emerging enzymatic platform competitors. Secure captive phosphoramidite supply through backward integration into reagent manufacturing or long-term offtake agreements with German and Swiss specialty chemical producers, mitigating raw material concentration risk.
For New Entrants and Emerging Players: Launch via enzymatic synthesis platform deployments targeting European academic consortia at ETH Zurich and Tsinghua University pilot programs, where sustainability-driven procurement favors reduced chemical waste streams. Penetrate India's underdeveloped biotechnology research infrastructure through partnerships with IISc-IIT institutional networks as domestic phosphoramidite production scales.
For Investors and Strategic Acquirers: The window for entry favors enzymatic platform specialists with kilobase-scale accurate assembly capabilities and pre-validated biosecurity screening infrastructure. Long-term viability hinges on chemistry transition completion and regulatory certification depth. Watch for FDA enforcement discretion tightening on sequence screening protocols as the inflection signal for accelerated supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Platform Scale-Up | Enables kilobase-scale synthesis without phosphoramidite error accumulation, attracting ECHA REACH-conscious European academic buyers. |
| ISO 13485 Certification Investment | Unlocks pharmaceutical translational research contracts that standard academic-grade vendors cannot serve under FDA oversight. |
| India Manufacturing Partnership | Captures DBT-funded demand growth as Bangalore and Hyderabad biotech corridors expand domestic reagent production. |
| Cell-Free Protein Synthesis Integration | Bundles construct-to-protein workflows, capturing downstream value from synthetic DNA supply relationships. |
| Biosecurity Screening Infrastructure | Satisfies U.S. Select Agent Regulations and EU biosecurity frameworks for federally funded contract eligibility. |
Research Methodology
Document review covered SEC 10-K filings of publicly traded synthesis providers, NIH grant award databases, and FDA guidance documents on synthetic nucleic acid oversight, complemented by interviews with gene synthesis procurement managers at pharmaceutical translational research units, principal investigators at MIT and ETH Zurich synthetic biology programs, and regulatory affairs leads at CDSCO and Swissmedic. Secondary validation drew from customs records of phosphoramidite chemical imports, ISO certification registries, and European academic consortia pilot program disclosures. Bottom-up order volume analysis and top-down market sizing triangulated segment-level estimates.
Historical revenue trajectories of established synthesis providers were cross-referenced against panel input from industry stakeholders to anchor growth assumptions across the projection horizon. The analytical framework modeled segmentation across product type, end user, technology, and application dimensions, with regional regulatory clusters treated as distinct adoption environments. CAGRs were derived from slope analysis of technology diffusion curves and grant funding patterns, incorporating enzymatic synthesis platform maturation and CRISPR workflow automation as industry-specific forecast inputs.
Regulatory enforcement discretion shifts, enzymatic synthesis platform technical failures, and phosphoramidite supply disruptions are the dominant revision risks to modeled forecasts. Forecasts reflect documented assumptions about technology substitution rates and institutional procurement behavior. Material deviation in FDA sequence screening enforcement, EU biosecurity framework implementation timing, or enzymatic chemistry yield improvements warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Biology
Transient Protein Expression Market
Synthetic Biology
Synthetic Hormones Market
Synthetic Biology
Mutation Generation Systems Market
Synthetic Biology
Synthetic Genomics Market
Synthetic Biology
Asia-Pacific Gene Synthesis Market
Synthetic Biology
Synthetic Stem Cells Market
Synthetic Biology
Global Cell-Free Protein Expression Market
Synthetic Biology
DNA Synthesizer Market
Synthetic Biology
Difficult-To-Express Proteins Market