
 Wearable Temperature Sensors Market | 2026-2036
Wearable Temperature Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Temperature Sensors Market Analytics
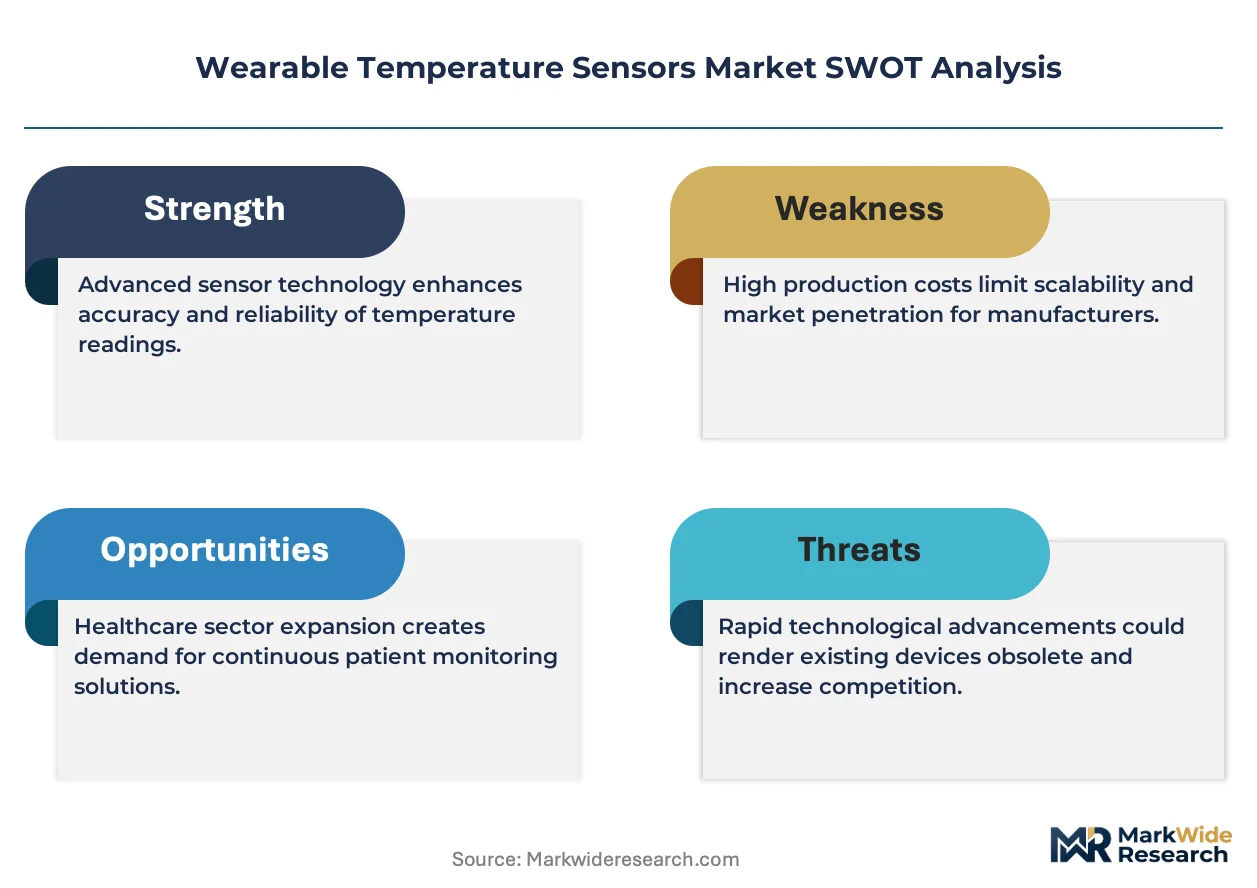
Polymer substrates are displacing traditional ceramic bases in flexible temperature sensing patches, which is recalibrating unit economics across the wearable ecosystem. STMicroelectronics NV leverages its MEMS foundry scale to anchor supply for skin-contact thermal arrays. Texas Instruments Inc. competes through integrated analog front-end designs that reduce bill-of-materials complexity for OEMs.
Wearable temperature sensors are thin-film thermal transducers, typically fabricated on polyimide or PET substrates with sensitivity ranges of 0.1°C to 0.5°C, designed for continuous dermal or near-body thermal monitoring in ambulatory and athletic settings. Health Monitoring applications generate the largest revenue pool due to reimbursement-adjacent deployments in remote patient monitoring, while Sports Performance segments exhibit the steepest adoption curve among professional and collegiate athletic programs. NTC Thermistor technology occupies the dominant share of current shipments, though Infrared non-contact modules are gaining traction in earwear form factors where skin contact is impractical.
FDA 510(k) clearance requirements govern clinical-grade wearable temperature devices in the United States, while the EU Medical Device Regulation imposes post-market surveillance obligations on manufacturers selling into European markets. ISO 10993 biocompatibility testing further constrains material selection for prolonged skin-contact applications. Stakeholders must weigh the capital requirements of multi-jurisdictional regulatory filings against the premium pricing that clinical certification commands in reimbursement-eligible segments.
Market Dynamics
Polymer substrate migration is compressing unit economics while expanding addressable form factors, forcing incumbents to retool MEMS foundries or cede patch-style sensor contracts to flexible electronics specialists.
Growth Catalysts
- FDA 510(k) pathway maturation:Streamlined clearance for continuous monitoring devices accelerates clinical adoption in US remote patient monitoring programs.
- Athletic program procurement:Collegiate and professional sports medicine departments deploy skin-contact thermal arrays for workload management and injury prevention protocols.
- NTC thermistor precision gains:Advances in negative temperature coefficient materials enable 0.1°C sensitivity at consumer price points, bridging clinical and wellness segments.
Market Restraints
- Polyimide supply concentration:High-performance substrate production clusters in East Asian chemical processing corridors, exposing OEMs to input volatility.
- ISO 10993 testing timelines:Biocompatibility validation for prolonged skin contact extends development cycles and consumes pre-revenue capital.
- Infrared module substitution:Non-contact thermal sensing in earwear and ambient formats threatens contact-based patch volumes in consumer wellness.
Strategic Opportunities
- Pediatric monitoring white space:Underpenetrated neonatal and infant thermal surveillance creates demand for hypoallergenic, miniaturized patch formats.
- EU MDR post-market surveillance:Surveillance obligations favor manufacturers with established quality management systems, creating competitive moats for certified entrants.
- AI-edge convergence:On-device thermal pattern recognition enables predictive health alerts without cloud dependency, opening premium pricing tiers.
Industry Challenges
- MEMS process engineering scarcity:Foundry talent capable of thermal array fabrication on flexible substrates commands premium compensation, constraining scale-up velocity.
- Multi-jurisdictional certification complexity:Simultaneous FDA, PMDA, and CE marking campaigns fragment engineering resources and delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Temperature Sensors Market |
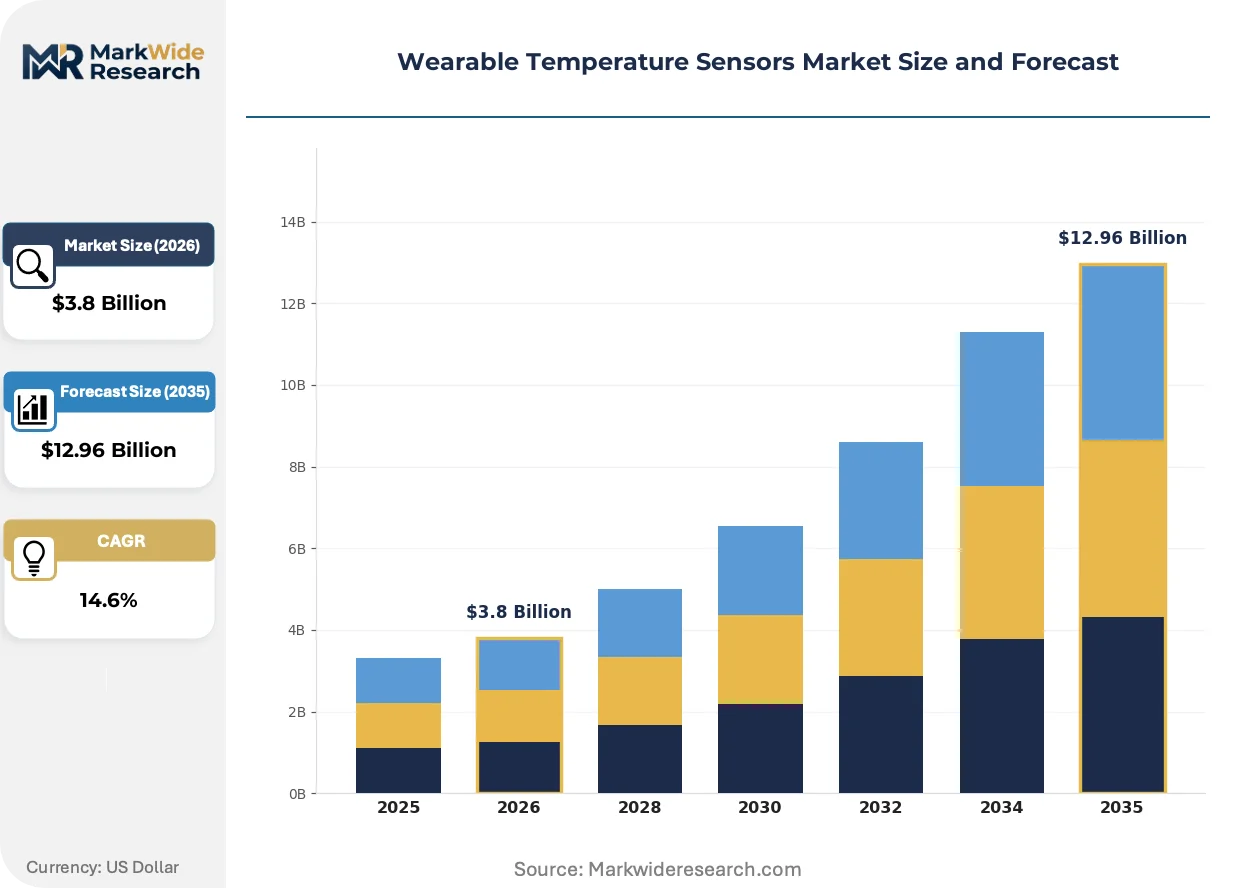
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Watches, Fitness Trackers, Health Monitors, Earwear Technology: Infrared, Thermocouple, NTC Thermistor, Wireless End User: Healthcare Professionals, Athletes, Consumers, Research Institutions Application: Health Monitoring, Sports Performance, Temperature Tracking, Medical Diagnostics |
| Companies Covered | Silicon Laboratories Inc., Maxim Integrated Products Inc., STMicroelectronics NV, Texas Instruments Inc., AMS-OSRAM AG, Melexis, Analog Devices Inc., TE Connectivity Ltd, Sensirion AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Temperature Sensors Market Evolving Landscape
Active materials innovation and regulatory recalibration are compressing development cycles while expanding the boundary between clinical-grade and consumer-grade thermal monitoring devices.
Flexible printed circuit integration with micro-thermistor arrays is consolidating the patch sensor supply chain by eliminating wire-bond interconnects. Wearable OEMs in athletic monitoring and remote patient care are adopting these consolidated architectures at accelerating volume. This consolidation is compressing bill-of-materials costs and enabling conformal designs that maintain signal integrity during motion.
The EU Medical Device Regulation's post-market surveillance requirements are tightening evidence-generation obligations for thermal monitoring devices sold into European clinical settings. Manufacturers must now maintain active safety monitoring systems and periodic clinical evaluation reports across product lifecycles. Class IIa thermal wearables face the steepest compliance burden, driving some entrants toward wellness-class positioning outside reimbursement channels.
Hospital procurement departments are unbundling sensor hardware from data platform subscriptions, reversing prior bundled SaaS contracts. Health systems in Germany and Japan now separately evaluate device accuracy, connectivity standards, and analytics vendors. This unbundling is fragmenting vendor relationships and elevating interoperability certifications as decisive selection criteria in enterprise tenders.
Wearable Temperature Sensors Market Segmentation
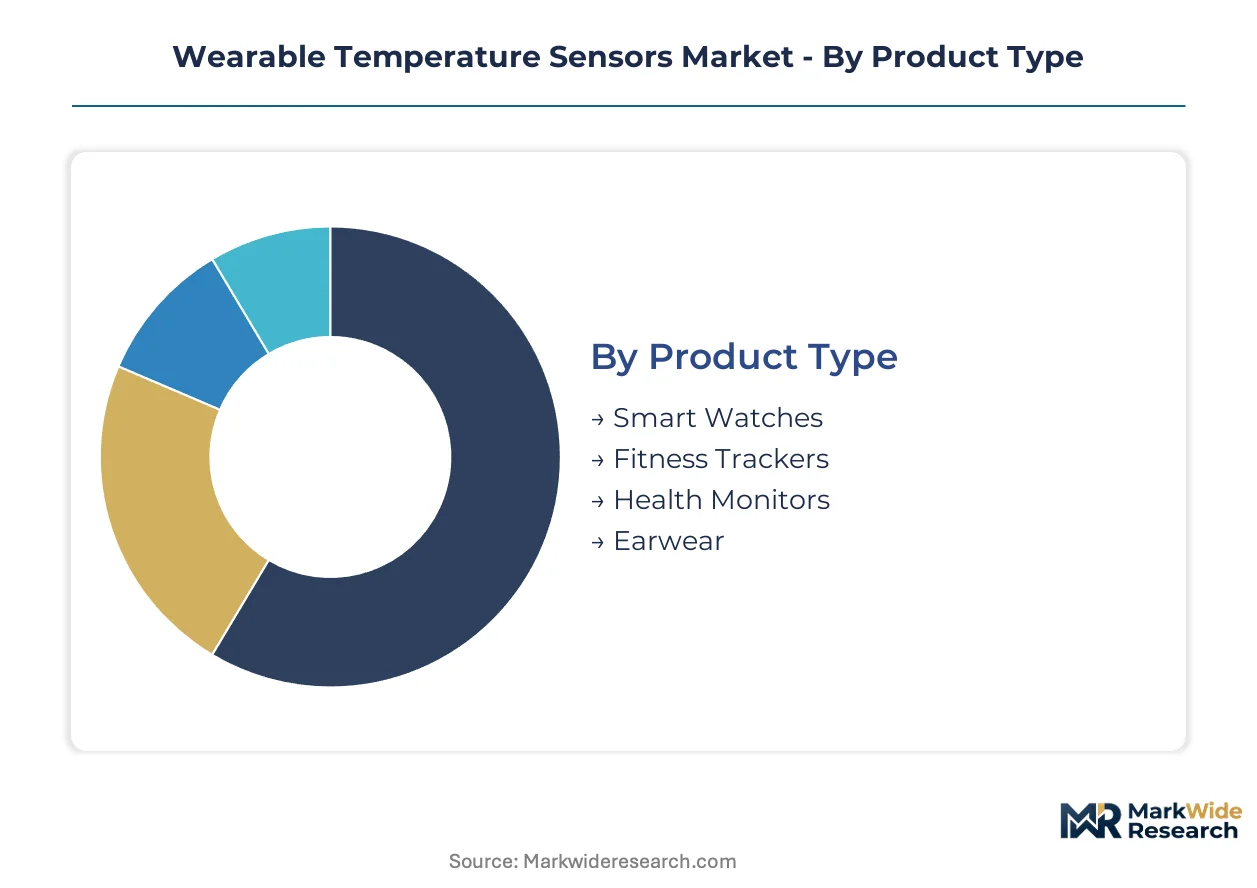
Segmentation in wearable temperature sensors reveals how clinical certification requirements, athletic performance demands, and consumer wellness expectations create divergent product specifications and pricing architectures across the market.
Product Type:
Volume concentration sits with wrist-worn devices, while premium pricing attaches to specialized clinical formats requiring extended wear biocompatibility.
- Smart Watches:These devices integrate thermal sensing alongside heart rate and SpO2 monitoring on rigid PCB substrates. Demand concentrates among Consumers in Germany and Japan where wellness tracking penetration exceeds other developed markets, constrained by battery thermal dissipation limits that compromise continuous monitoring accuracy.
- Health Monitors:Purpose-built clinical patches utilize polyimide substrates with medical-grade adhesives for 72-hour continuous wear. Healthcare Professionals in US remote patient monitoring programs drive procurement volumes, with FDA 510(k) clearance requirements filtering out uncertified competitors.
- Fitness Trackers:Entry-level thermal modules target Athletes with basic skin-contact sensing during workout intervals. Form factor constraints limit sensor placement to wrist or chest strap positions.
- Earwear:Infrared non-contact modules in earbuds and hearing aids avoid skin adhesion challenges. Tympanic membrane proximity offers core temperature correlation without ISO 10993 biocompatibility burdens.
Mature deployment sits with Smart Watches. Newer deployment is concentrated in Health Monitors.
Technology:
Cost tier separation runs from precision-calibrated clinical components to commoditized consumer-grade alternatives with widening accuracy gaps.
- NTC Thermistor:Negative temperature coefficient ceramic or polymer composites dominate current shipment volumes with 0.1°C sensitivity achievable at scale. Healthcare Professionals in Japan's aging care facilities specify these for reimbursement-eligible remote monitoring, though calibration drift over 10,000 thermal cycles requires periodic replacement protocols.
- Infrared:Non-contact thermal radiation detection enables ear canal and ambient measurement without skin adhesion. Athletes in US collegiate sports medicine programs favor these for rapid non-invasive screening during training intervals, with MEMS-based pyroelectric arrays reducing module size for wearable integration.
- Thermocouple:Junction-based differential measurement offers wide temperature range but requires cold junction compensation circuitry. Research Institutions specify these for laboratory-grade validation studies.
- Wireless:RF-enabled passive or semi-passive sensors eliminate battery constraints through inductive or backscatter power harvesting. Emerging deployments target neonatal monitoring where wired connections disturb patient handling.
Established volume sits with NTC Thermistor. Expanding most quickly is Infrared.
End User:
Customer type determines regulatory pathway complexity and pricing power, with clinical certification commanding substantial premiums over wellness positioning.
- Healthcare Professionals:Hospital systems and remote patient monitoring providers require FDA-cleared or CE-marked devices with documented clinical accuracy. Procurement in Germany's Klinikum networks now unbundles hardware from analytics subscriptions, elevating interoperability certifications.
- Consumers:Wellness-oriented buyers prioritize form factor aesthetics and smartphone app integration over clinical-grade precision. Price sensitivity limits acceptable bill-of-materials costs.
- Athletes:Professional and collegiate sports programs deploy thermal arrays for workload management, heat illness prevention, and recovery optimization. US NCAA athletic departments represent concentrated procurement volume.
- Research Institutions:Academic medical centers and physiology laboratories specify calibrated reference-grade sensors for validation studies and algorithm development.
Revenue concentration sits with Healthcare Professionals. Gaining share fastest are Athletes.
Application:
Use case maturity separates reimbursement-adjacent clinical workflows from emerging performance optimization contexts with evolving evidence standards.
- Health Monitoring:Continuous thermal surveillance for fever detection, ovulation tracking, and chronic condition management. Remote patient monitoring programs in the United States drive enterprise procurement with Medicare reimbursement tailwinds.
- Sports Performance:Real-time core temperature estimation and heat strain alerting during exertion. Professional football and soccer programs in Germany and Japan deploy skin-contact arrays for training load individualization.
- Temperature Tracking:General wellness and environmental thermal logging without diagnostic claims. Consumer fitness enthusiasts represent the addressable base.
- Medical Diagnostics:Fever screening and infection monitoring with diagnostic intent, triggering stricter regulatory classification. EU MDR post-market surveillance obligations apply to Class IIa deployments.
Established revenue sits with Health Monitoring. Steepest expansion trajectory belongs to Sports Performance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Suzhou channel semiconductor packaging investment toward flexible sensor substrates, concentrating polymer substrate conversion capacity in East Asian chemical processing corridors.
United States
Remote patient monitoring programs at Mayo Clinic and Cleveland Clinic anchor clinical-grade procurement volumes, with FDA 510(k) clearance requirements filtering market entrants. Medicare reimbursement tailwinds for continuous thermal surveillance accelerate hospital system adoption. Boston's Route 128 corridor hosts MEMS design houses serving patch-style sensor OEMs.
Germany
Charité Berlin and Klinikum Stuttgart networks unbundle sensor hardware from analytics subscriptions, elevating interoperability certifications as selection criteria. EU Medical Device Regulation post-market surveillance obligations apply to Class IIa thermal wearables. Munich's semiconductor cluster supplies analog front-end components for skin-contact arrays.
Japan
PMDA regulatory pathways govern clinical-grade device approval, with METI funding programs supporting aging-care facility deployments. NTC thermistor precision specifications dominate procurement by Japan's municipal long-term care insurers. Osaka's chemical processing corridor manufactures high-performance polyimide substrates for 72-hour wear patches.
China
NMPA medical device classification rules separate diagnostic-intent thermal monitors from wellness-grade alternatives. MIIT industrial policy directs flexible electronics investment toward Yangtze River Delta special zones. Suzhou's MEMS foundry complex hosts thermal array fabrication for export-oriented OEMs.
South Korea
MFDS fast-track approval pathways for digital therapeutics accelerate wearable thermal sensor integration into chronic disease management platforms. Seoul National University Hospital pilots AI-edge thermal pattern recognition for predictive fever alerts. Songdo's biotech cluster attracts contract manufacturers serving pediatric patch formats.
Wearable Temperature Sensors Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with MEMS foundry scale commanding premium positioning in clinical-grade supply chains while flexible electronics specialists capture patch-format contracts. The vendor base organizes around three archetypes: integrated semiconductor conglomerates with analog front-end expertise, MEMS pure-plays leveraging thermal array fabrication scale, and flexible substrate converters bridging polymer chemistry to conformal sensor design. Competitive moves concentrate on strategic partnerships with remote patient monitoring platforms and capacity expansion in East Asian polymer processing corridors.
Among European-based semiconductor specialists, STMicroelectronics NV and AMS-OSRAM AG occupy positions anchored by MEMS foundry infrastructure and optical sensing portfolios respectively. Texas Instruments Inc. represents the integrated analog design archetype, with Silicon Laboratories Inc. and Maxim Integrated Products Inc. sitting within the mixed-signal specialist tier alongside Analog Devices Inc. Sensirion AG exemplifies the environmental sensing pure-play model, while TE Connectivity Ltd anchors the connectivity component segment. Melexis occupies a position bridging automotive thermal sensing expertise toward wearable format adaptation.
| Leading Market Players |
|---|
| Silicon Laboratories Inc. |
| Maxim Integrated Products Inc. |
| STMicroelectronics NV |
| Texas Instruments Inc. |
| AMS-OSRAM AG |
| Melexis |
| Analog Devices Inc. |
| TE Connectivity Ltd |
| Sensirion AG |
| Others |
Value Network & Pricing Analysis
Clinical certification tiers bifurcate the wearable temperature sensor market into premium FDA-cleared patches and commoditized wellness-grade alternatives, with this divergence manifesting in both bill-of-materials multiples and the geographic locus of polymer substrate conversion capacity. Supply chain configuration favors East Asian chemical processing corridors for high-performance polyimide, while pricing power concentrates with MEMS foundries capable of thermal array fabrication at clinical precision.
Pricing Analysis
Volume concentration in wrist-worn wellness devices runs on thin margins, while clinical-grade patches with FDA 510(k) clearance command substantial premiums through reimbursement eligibility. Price differentiation rests on ISO 10993 biocompatibility certification and continuous monitoring accuracy specifications. Pricing pressure stems from infrared non-contact modules displacing skin-contact formats in consumer earwear. Consumers exhibit highest price sensitivity, constraining acceptable component costs, whereas hospital procurement committees prioritize interoperability certifications over unit economics.
Supply Chain Analysis
MEMS process engineering scarcity in Shenzhen and Suzhou constrains foundry expansion velocity for flexible thermal arrays. Manufacturing concentration centers on China, Japan, and South Korea for polymer substrate conversion and analog front-end component production. Raw material dependencies include high-purity polyimide films, NTC thermistor ceramic composites, and medical-grade adhesive formulations. Single-source vulnerability runs through East Asian polyimide supply corridors exposed to logistics disruption. Distribution feeds from contract manufacturers through OEM integration partnerships to hospital procurement departments and athletic program tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polymer substrate conversion capacity acts as the binding constraint propping pricing power for clinical-grade patches, with foundry slot availability determining OEM delivery timelines across the forecast window.
For Market Incumbents: Acquire flexible electronics specialists with established ISO 13485 quality management systems to secure patch-format manufacturing capacity. Deepen backward integration into polyimide substrate supply through offtake agreements with Osaka chemical processing corridors. Infrared module substitution in earwear formats threatens contact-based patch volumes, necessitating defensive patent positioning in MEMS pyroelectric arrays.
For New Entrants and Emerging Players: AI-edge thermal pattern recognition capabilities offer technology-first entry into predictive health alert segments without cloud dependency overhead. Pediatric monitoring white space presents the most penetrable application, with hypoallergenic miniaturized patches underserved by incumbent form factors. Go-to-market execution should target NCAA athletic department procurement cycles with rapid non-invasive screening value propositions.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by remote patient monitoring platforms seeking vertical integration into sensor hardware. Long-term viability favors manufacturers with simultaneous FDA, PMDA, and CE marking capabilities across the analysis window. Acquisition target archetype: MEMS pure-plays with thermal array fabrication scale and established biocompatibility testing protocols. Watch for unbundling of sensor hardware from analytics subscriptions in German Klinikum networks as inflection signal for interoperability premium capture.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Unlocks Medicare reimbursement eligibility for US remote patient monitoring deployments. |
| Polymer Substrate Supply Agreement | Secures polyimide capacity from Osaka chemical corridors for 72-hour wear patches. |
| AI-Edge Thermal Pattern Recognition | Enables predictive fever alerts without cloud dependency, opening premium pricing tiers. |
| Hospital System Partnership | Positions vendors for unbundled procurement evaluations elevating interoperability certifications. |
| EU MDR Post-Market Surveillance Investment | Creates competitive moats through quality management system differentiation in European clinical segments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with biomedical engineers, hospital GPO contracts managers, MEMS foundry operations directors, and athletic program procurement officers. FDA 510(k) submission databases, PMDA approval registries, EU MDR notified body certificates, and ISO 13485 certification records provided structured secondary validation. Bottom-up shipment estimates from polymer substrate converters reconciled with top-down healthcare expenditure allocations across remote patient monitoring programs.
Data-stream reconciliation across component supplier interviews, OEM production schedules, and end-user procurement databases informed the analytical framework. Segmentation dimensions modeled include product type, sensing technology, end-user archetype, and application context across the projection horizon. CAGRs derived from unit economics trajectories of NTC thermistor versus infrared module cost curves, calibrated against reimbursement policy velocity in US Medicare and Japan's municipal long-term care insurance systems.
Forecast precision tightens around the base case; tail outcomes carry wider variance under PMDA regulatory timeline delays or polyimide supply corridor disruption. Forecasts reflect documented assumptions regarding FDA clearance pathway maturation and athletic program procurement cycles. Material deviation in Medicare reimbursement policy for continuous thermal surveillance warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Calibrator Market
Sensors and Controls
Europe Gas Sensors Market
Sensors and Controls
Smart Sensor Market
Sensors and Controls
MEMS Gyroscope Market
Sensors and Controls
Biometric Sensors Market
Sensors and Controls
Air Flow Monitoring System Market
Sensors and Controls
Global Load Cell Market
Sensors and Controls
Global Nanosensors Market
Sensors and Controls
Europe Machine Condition Monitoring Market
Sensors and Controls
Weather Radar Market
Sensors and Controls
Nano Radiation Sensors Market
Sensors and Controls
Speech Intelligibility Devices Market
Sensors and Controls
SQUID Sensor Market
Sensors and Controls
Industrial Combustion Control Components and Systems Market
Sensors and Controls
60GHz Radar Evaluation Kit Market
Sensors and Controls
Global Intelligent Flow Meter Market