
 Australia Last Mile Delivery Market | 2026-2036
Australia Last Mile Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Last Mile Delivery Market Outlook
Urban courier networks is fragmenting as same-day and contactless service tiers multiply across Australian capitals. Australia Post sustains unmatched coverage through its postal infrastructure and community service obligations. Toll Group leverages integrated logistics assets to control B2B final-leg movements in dense industrial zones. Sendle competes aggressively on small-business pricing, carving share from established parcel incumbents.
Last mile delivery encompasses the terminal transportation of goods from distribution hubs to end recipients, typically spanning distances under 50 kilometers and requiring real-time tracking, proof-of-delivery capture, and flexible recipient interaction protocols. The segment relies on route optimization algorithms and mobile dispatch platforms to minimize per-stop cost and maximize delivery density within constrained time windows. Express delivery and same-day delivery represent the fastest-expanding service tiers, driven by consumer expectations set by major retail platforms. Van-based delivery mode still dominates operational economics, though bicycle and motorcycle fleets gain traction in congested inner-urban corridors where parking scarcity and access restrictions elevate smaller-vehicle efficiency.
The National Heavy Vehicle Regulator enforces fatigue management and mass limits that shape fleet composition and driver scheduling across interstate and intrastate operations. Australian Competition and Consumer Commission oversight of consumer guarantees and delivery promises influences service-level advertising and dispute resolution protocols. State-level environmental regulations in New South Wales and Victoria increasingly constrain diesel van access in central business districts, pressuring operators toward electric fleet transitions. Stakeholders must weigh capital intensity of electrification against regulatory compliance timelines and evolving urban access rules.
Market Dynamics
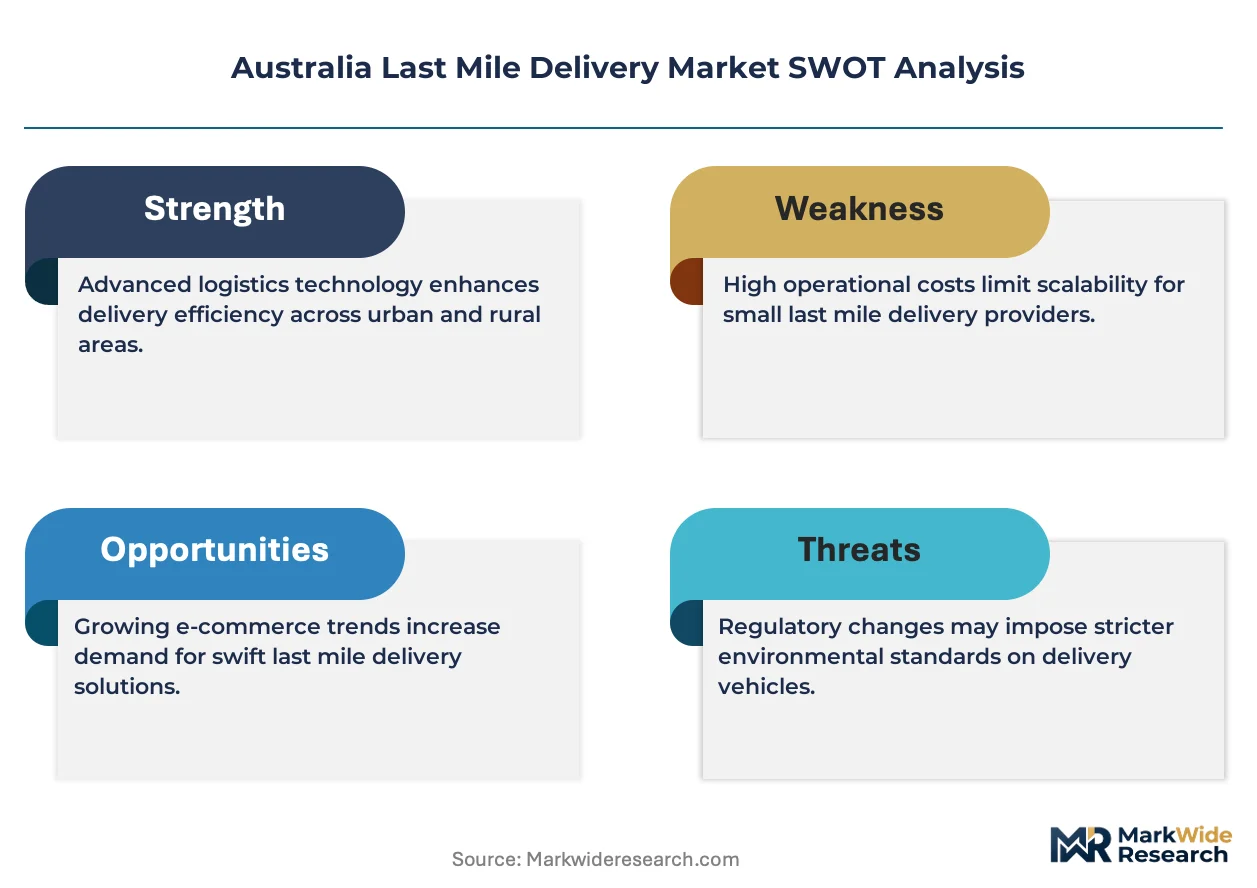
Electric fleet mandates in New South Wales and Victoria are forcing capital reallocation across Australian last mile operators, compressing diesel vehicle replacement cycles and reshaping depot infrastructure planning.
Growth Catalysts
- E-commerce parcel density:Metro fulfillment hubs in Sydney and Melbourne generate delivery corridor consolidation that improves stop economics for van-based networks.
- Heavy Vehicle National Law:Standardized fatigue protocols and mass limits reduce interstate compliance friction, enabling fleet pooling across state borders.
- Contactless proof-of-delivery:Mobile capture protocols reduce dwell time per stop and lower dispute resolution costs for residential delivery tiers.
Market Restraints
- Lithium-ion battery supply:Electric van procurement faces cell allocation competition from passenger EV manufacturers, extending delivery lead times.
- Driver availability:Heavy vehicle license acquisition timelines constrain fleet expansion velocity in peak demand periods.
- CBD access restrictions:Diesel van exclusion zones in Sydney and Melbourne central business districts strand existing fleet assets before replacement cycles complete.
Strategic Opportunities
- Regional Queensland penetration:Lower courier density outside Brisbane creates whitespace for hub-and-spoke micro-fulfillment models.
- Bicycle fleet corridors:Inner-urban parking scarcity enables two-wheeled delivery substitution in Melbourne's laneway networks and Sydney's inner west.
- Renewable depot energy:Solar-plus-storage installations at sorting facilities qualify for state-level clean energy incentives while reducing diesel generator dependence.
Industry Challenges
- Telematics integration:Legacy route optimization platforms require API reconfiguration to ingest real-time traffic and recipient availability data.
- Proof-of-delivery verification:Photographic evidence standards vary across retailers, creating reconciliation friction for multi-client courier operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Last Mile Delivery Market |
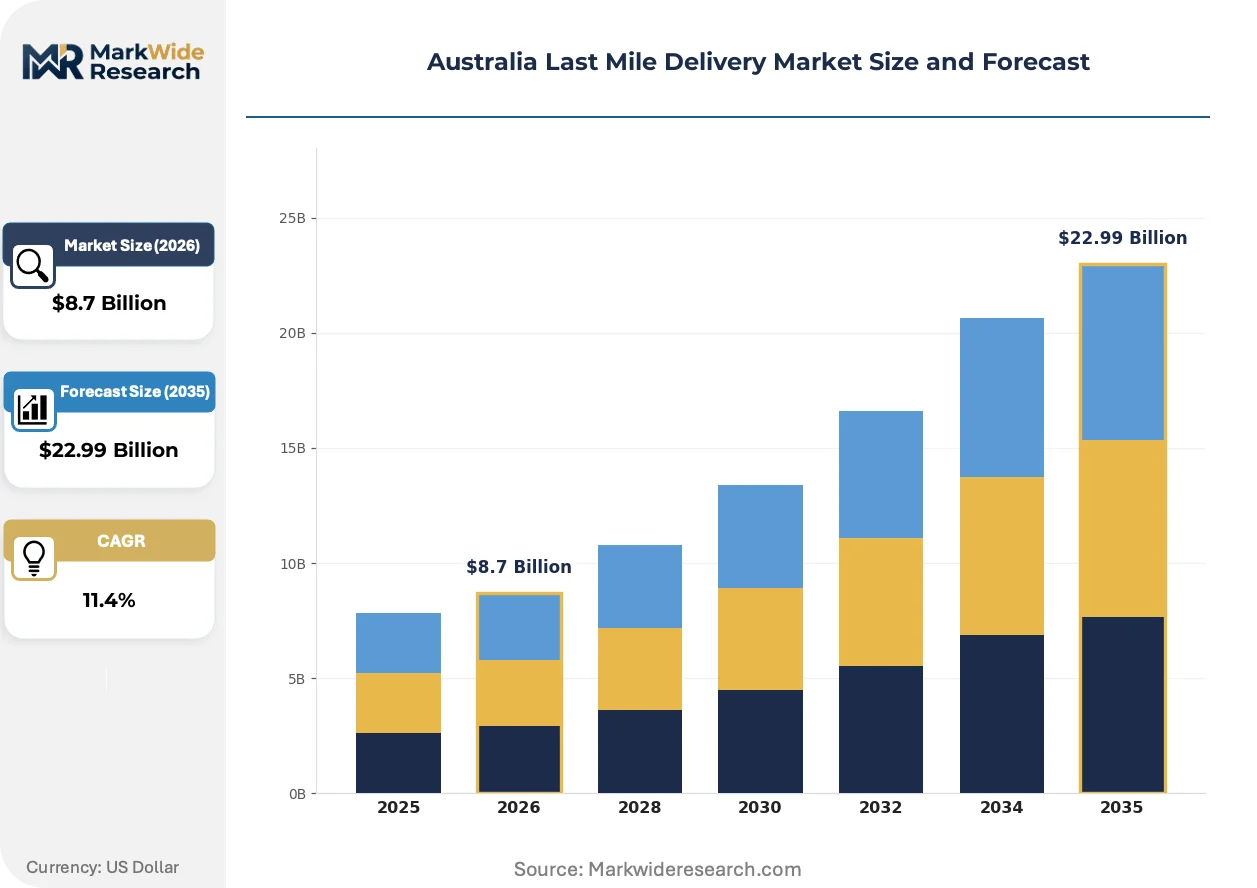
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Standard Delivery, Express Delivery, Same-Day Delivery, Contactless Delivery Delivery Mode: Van, Bicycle, Motorcycle, Drone End User: E-commerce, Retail, Food Service, Pharmaceuticals Technology: GPS Tracking, Route Optimization, Automated Sorting, Mobile Application |
| Companies Covered | Australia Post, Toll Group, DHL Express, FedEx Express, Aramex Australia, CouriersPlease, StarTrack, Team Global Express, Sendle, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Last Mile Delivery Market Strategic Shifts
Operational technology stacks are fragmenting as specialized point solutions for dynamic routing, recipient communication, and emissions tracking displace monolithic legacy platforms. Three developments dominate competitive positioning.
Dynamic route optimization software is migrating from static morning dispatch to continuous resequencing through the delivery window. Mid-size courier fleets in Perth and Adelaide adopt cloud-native platforms that ingest real-time traffic, recipient location updates, and parcel-level dimensional data. This compression of planning cycles enables same-day service tiers without proportional fleet expansion.
The National Heavy Vehicle Regulator's Chain of Responsibility amendments extend liability for delivery scheduling practices to consignors and receivers, not just transport operators. E-commerce platforms and third-party logistics providers now face direct accountability for setting unrealistic delivery windows that induce driver fatigue. Major retailers are responding by widening promised delivery windows and penalizing suppliers who impose tight handoff deadlines.
Recipient-controlled delivery windows are displacing fixed-route scheduling as the default service expectation. Australian consumers increasingly select 2-hour arrival slots through retail apps, forcing courier networks to trade density for precision. This behavioral shift concentrates in Sydney and Melbourne metro zones where population density supports slot-level granularity without catastrophic efficiency loss.
Australia Last Mile Delivery Market Segmentation
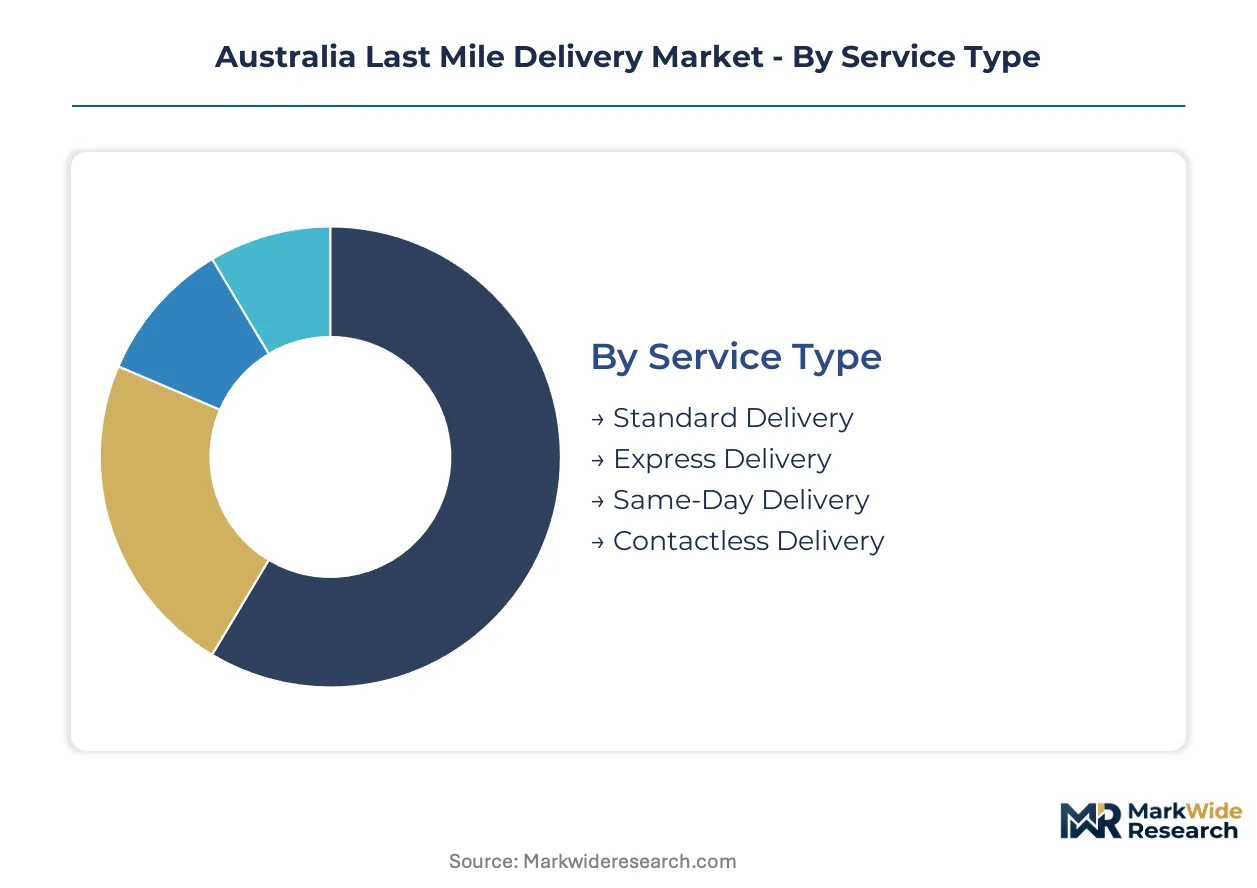
Last mile delivery operators in Australia configure service portfolios around speed tiers, vehicle assets, and recipient technology interfaces. Segment boundaries blur as e-commerce platforms bundle fulfillment options and courier networks diversify fleet composition across metropolitan zones.
Service Type:
Speed-based service tiers structure pricing and operational investment across Australian courier networks.
- Standard Delivery:Two-to-five-day windows dominate non-urgent parcel flows between capital cities and regional centers. Australia Post's community service obligations preserve universal coverage at this tier, though private carriers undercut on inter-capital lanes.
- Express Delivery:Next-day guarantees command premium positioning for time-sensitive B2B documents and high-value retail. Sydney-Melbourne air corridors concentrate volume, with Toll Group and StarTrack leveraging depot density for morning cutoff reliability.
- Same-Day Delivery:Metro fulfillment hubs enable three-hour windows in Sydney and Melbourne inner zones. Consumer expectations set by major retail platforms are forcing courier networks to absorb density penalties for speed differentiation.
- Contactless Delivery:Photographic proof-of-delivery protocols reduce dwell time and dispute resolution costs. Residential demand surged during public health periods and now persists as a default preference for unattended receipt.
Standard delivery commands the established base. The steepest expansion runs through same-day delivery.
Delivery Mode:
Fleet composition decisions hinge on parking access, cargo volume, and regulatory constraints across Australian urban zones.
- Van:One-to-three-cubic-meter capacity vehicles handle bulk parcel flows and furniture deliveries. Diesel van exclusion zones in Sydney and Melbourne CBDs are compressing replacement cycles toward electric alternatives before asset lifecycles complete.
- Bicycle:Cargo bikes navigate Melbourne's laneway networks and Sydney's inner west where parking scarcity and access restrictions strand larger vehicles. Food service aggregators dominate this mode for sub-five-kilometer radius operations.
- Motorcycle:Two-wheeled fleets penetrate congested corridors with lower per-kilometer operating costs than vans. Document and pharmaceutical couriers favor this mode for speed-critical handoffs in dense commercial districts.
- Drone:Experimental deployments target remote regional deliveries beyond economical van coverage. Civil Aviation Safety Authority regulations constrain beyond-visual-line-of-sight operations, limiting scale to pilot corridors.
Van-based operations anchor network economics. The steepest expansion trajectory belongs to bicycle fleets in access-restricted inner-urban zones.
End User:
Customer verticals impose divergent service-level requirements and proof-of-delivery protocols.
- E-commerce:Platform-integrated fulfillment demands real-time tracking and flexible recipient rescheduling. Parcel volumes concentrate in Sydney and Melbourne metro zones where fulfillment hub density supports same-day tiers.
- Retail:Click-and-collect and ship-from-store models blur last mile boundaries. Major chains are internalizing final-leg movements to preserve margin on high-value transactions.
- Food Service:Temperature control and sub-30-minute windows dominate operational requirements. Aggregator platforms have fragmented courier relationships, forcing restaurants onto multi-homing arrangements.
- Pharmaceuticals:Cold chain integrity and chain-of-custody documentation impose specialized handling. The Therapeutic Goods Administration's distribution record requirements extend liability to transport operators.
E-commerce absorbs the dominant share of courier capacity. Pharmaceuticals is climbing the fastest as specialized handling commands premium rate structures.
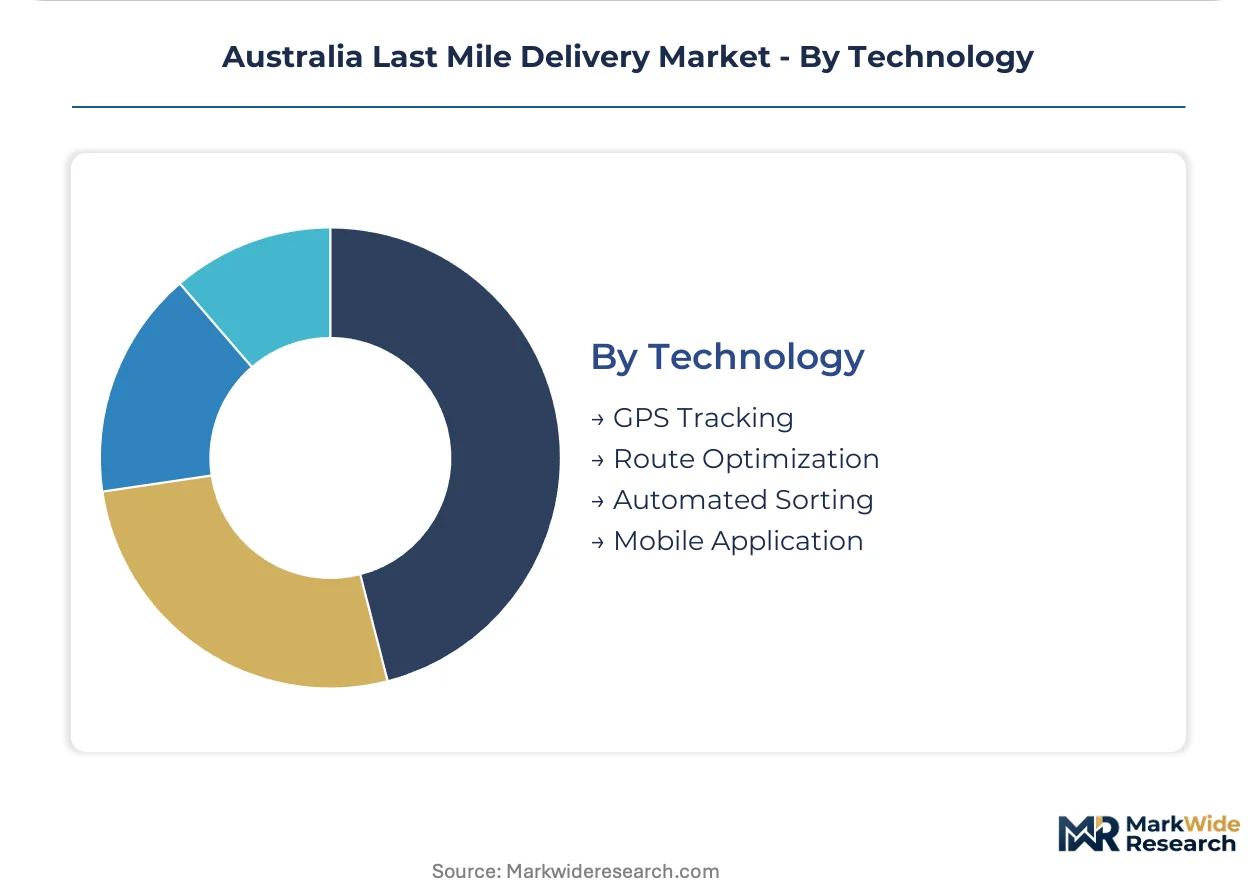
Technology:
Operational technology stacks determine routing efficiency, recipient communication quality, and network visibility.
- GPS Tracking:Real-time location streaming enables proactive delay notification and recipient arrival estimation. Cloud-native platforms in Perth and Adelaide are displacing legacy telematics with sub-minute update frequencies.
- Route Optimization:Dynamic resequencing through delivery windows compresses planning cycles from morning dispatch to continuous adjustment. Mid-size fleets report density improvements without proportional vehicle expansion.
- Automated Sorting:Parcel dimensioning and destination coding at hub facilities reduce manual handling and mis-sort rates. Capital intensity limits deployment to high-volume facilities in Sydney and Melbourne.
- Mobile Application:Recipient-controlled delivery windows and photographic proof-of-capture displace fixed-route scheduling. Consumer preference for slot-level granularity concentrates in dense metro zones.
GPS tracking provides the foundational layer. Route optimization is gaining share fastest as dynamic algorithms displace static dispatch models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New South Wales commands premium pricing power over South Australia due to Sydney's fulfillment hub density and congestion-driven speed premiums, while Queensland's regional whitespace forces rate compression to penetrate lower-density corridors.
New South Wales
Sydney's metropolitan fulfillment concentration generates delivery corridor economics that support same-day service tiers at scale. The National Heavy Vehicle Regulator enforces fatigue protocols that shape driver scheduling across interstate lanes terminating in Sydney. Parramatta and Blacktown industrial zones anchor depot networks where electric van transition timelines compress against diesel exclusion deadlines in the CBD.
Victoria
Melbourne's laneway network and inner-west parking scarcity accelerate bicycle fleet substitution for sub-five-kilometer radius operations. State-level environmental regulations constrain diesel van access in the central business district, forcing premature asset replacement cycles. Dandenong South and Truganina logistics precincts concentrate automated sorting infrastructure that feeds last-mile density into Port Phillip Bay catchments.
Queensland
Brisbane metro parcel density supports standard express tiers, but regional penetration beyond the southeast corner remains economically challenging. The state's renewable energy incentives qualify solar-plus-storage depot installations that reduce diesel generator dependence. Gold Coast and Sunshine Coast corridors exhibit fastest courier network expansion as population growth outpaces infrastructure maturity.
Western Australia
Perth's geographic isolation from eastern fulfillment hubs elevates air freight dependency for express service reliability. The Heavy Vehicle National Law standardizes mass limits across the Nullarbor corridor, enabling fleet pooling with South Australian operators. Welshpool and Kewdale industrial zones concentrate cross-dock facilities that bridge interstate rail arrivals with metropolitan van distribution.
South Australia
Adelaide's smaller metro footprint enables mid-size courier fleets to achieve stop densities comparable to larger capitals with fewer vehicles. State-level clean energy incentives accelerate depot electrification timelines ahead of national benchmarks. Edinburgh Parks and Wingfield logistics zones anchor hub-and-spoke configurations serving Barossa Valley and Fleurieu Peninsula regional extensions.
Australia Last Mile Delivery Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in fleet technology and routing software. The Australia last mile delivery market exhibits tiered concentration where postal infrastructure operators, integrated logistics groups, and digital-native challengers occupy distinct competitive strata. Three strategic archetypes dominate: universal coverage incumbents leveraging fixed-cost infrastructure, asset-heavy B2B specialists optimizing industrial zone density, and pricing-disruptive platforms targeting small-business volume. Competitive moves concentrate on electric fleet procurement acceleration and dynamic routing platform licensing.
Within the universal coverage tier, Australia Post occupies a position exemplifying community service obligation leverage, while Toll Group anchors integrated logistics archetype representation. Among digital-native challengers, Sendle sits within the small-business pricing disruption archetype. These three entities collectively illustrate how infrastructure depth, asset integration, and platform agility define competitive positioning across Sydney-Melbourne corridor economics versus regional whitespace penetration.
| Leading Market Players |
|---|
| Australia Post |
| Toll Group |
| DHL Express |
| FedEx Express |
| Aramex Australia |
| CouriersPlease |
| StarTrack |
| Team Global Express |
| Sendle |
| Others |
Value Chain & Pricing Dynamics
Single-source lithium-ion battery cell dependency from East Asian manufacturers compresses pricing tier spreads while forcing depot electrification timelines that reshape Australian fleet procurement patterns. This input concentration simultaneously elevates premium rates for guaranteed electric vehicle availability and strands diesel assets before depreciation cycles complete.
Pricing Analysis
The customization-premium spread separates configured-to-order same-day delivery slots from standard multi-day windows across Sydney and Melbourne corridors. Three-tier pricing structure across premium, standard, and economy levels dominates, with price differentiation driven by speed guarantees and recipient-controlled arrival slots. Cost compression in the standard tier intensifies because Sendle and digital-native platforms undercut legacy postal rates for small-business volume. E-commerce aggregators exhibit highest price sensitivity, while pharmaceutical cold-chain clients accept premium positioning for chain-of-custody documentation.
Supply Chain Analysis
Export-control regimes on advanced battery management systems and electric drivetrain components limit technology transfer from South Korea and Japan into Australian fleet operations. Vehicle procurement draws from China, South Korea, and Japan for electric van chassis, while telematics hardware sources from Taiwan and the United States. Single-source vulnerability concentrates in lithium cell supply, where Korean and Chinese manufacturers allocate capacity to passenger EV producers ahead of commercial van fleets. Distribution runs through importer-distributor networks anchored in Melbourne and Sydney industrial zones before radiating to metropolitan depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where dynamic routing software subscriptions and recipient communication platforms expand faster than vehicle hardware depreciation cycles.
For Market Incumbents: Entrench depot network density in Parramatta and Dandenong South logistics precincts to defend against micro-fulfillment challengers. Accelerate solar-plus-storage installations at sorting facilities to lock in state-level clean energy incentives before compliance deadlines tighten. Vertical integration into route optimization software licensing creates switching costs for multi-client courier operations.
For New Entrants and Emerging Players: Build out hub-and-spoke micro-fulfillment nodes in Gold Coast and Sunshine Coast corridors where population growth outpaces courier density. Regional Queensland whitespace offers lowest competitive intensity for same-day service tier introduction. Partner with renewable energy developers to qualify clean energy incentives that offset depot electrification capital intensity.
For Investors and Strategic Acquirers: New South Wales and Victoria electric fleet mandates reshape the acquisition landscape toward operators with accelerated EV transition timelines already deployed. Long-term viability centers on depot infrastructure ownership rather than pure fleet asset plays. Watch for Civil Aviation Safety Authority beyond-visual-line-of-sight drone regulation relaxation as signal for autonomous delivery inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Procurement Acceleration | State-level diesel exclusion deadlines in Sydney and Melbourne CBDs compress replacement cycles ahead of depreciation. |
| Dynamic Routing Platform Licensing | Cloud-native algorithms from Perth and Adelaide providers displace legacy telematics through sub-minute update frequencies. |
| Renewable Depot Energy Installation | Solar-plus-storage configurations qualify for Queensland and South Australian clean energy incentives while reducing diesel generator dependence. |
| Regional Micro-Fulfillment Expansion | Hub-and-spoke models in Gold Coast and Sunshine Coast corridors capture population growth ahead of infrastructure maturity. |
| Recipient Communication Platform Development | Mobile applications enabling slot-level granularity concentrate demand in dense metro zones without catastrophic efficiency loss. |
Study Parameters
Operator-level perspectives from fleet managers, depot operations directors, route optimization software engineers, and e-commerce platform logistics leads anchored the qualitative base. Primary interviews combined with secondary validation against National Heavy Vehicle Regulator compliance filings, Australian Competition and Consumer Commission dispute records, and state-level environmental regulation databases. Customs and trade data on electric vehicle imports, plus SEC filings from listed logistics technology providers, supplemented demand-side triangulation. Bottom-up parcel volume modeling across Sydney-Melbourne-Brisbane corridors cross-checked against top-down market sizing from fulfillment hub throughput disclosures.
Scenario-bracketing framed low-case electric fleet adoption delays against high-case regulatory acceleration across the projection horizon. Segmentation dimensions modeled include speed tier, vehicle mode, end-user vertical, and technology stack deployment. CAGRs derived from parcel volume elasticity to e-commerce penetration rates and fleet capacity expansion timelines. Heavy Vehicle National Law fatigue protocol amendments and state-level diesel exclusion zone phase-ins served as structural forecast inputs.
Sensitivities concentrate around lithium-ion battery cell allocation competition from passenger EV manufacturers and Civil Aviation Safety Authority drone regulation relaxation timelines. Forecasts reflect assumptions on electric van procurement lead times and recipient preference evolution toward slot-level granularity. Material shifts in state-level environmental compliance deadlines or beyond-visual-line-of-sight operational approvals would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
New Zealand Freight and Logistics Market
Logistics and Shipping
Italy Courier Market
Logistics and Shipping
China Third-Party Logistics (3PL) Market
Logistics and Shipping
Logistics Automation Market
Logistics and Shipping
Japan Logistics Market
Logistics and Shipping
GCC Trailer Market
Logistics and Shipping
Netherlands Freight and Logistics Market
Logistics and Shipping
France Parcel Market
Logistics and Shipping
Remanufacturing and Core Returns Logistics Management Market
Logistics and Shipping
China Freight Forwarding Market
Logistics and Shipping
Europe less-Than Container Load Market
Logistics and Shipping
Australia Freight Forwarding Market
Logistics and Shipping
Canada 3PL Market
Logistics and Shipping
United States Chemical Logistics Market
Logistics and Shipping
UAE Contract Logistics Market
Logistics and Shipping
Asia-Pacific Cold Chain Logistics Market