
 FMCG Logistics Market | 2026-2036
FMCG Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
FMCG Logistics Market Intelligence
Biodegradable packaging films are restructuring cost structures across temperature-sensitive FMCG corridors. DHL Group leverages its pharmaceutical-grade cold-chain infrastructure to anchor premium perishable contracts. FedEx Corporation competes through dense last-mile node networks in metropolitan zones. Kuehne + Nagel differentiates via digital freight platforms that compress booking-to-delivery cycles.
FMCG logistics coordinates the movement, storage, and delivery of fast-moving consumer goods through temperature-controlled vehicles, automated sortation hubs, and real-time inventory tracking systems, ensuring product integrity from manufacturer to retail shelf. Transportation services dominate value capture due to fuel and fleet asset intensity, while last-mile delivery within the delivery model dimension is expanding fastest as e-commerce platforms demand sub-24-hour fulfillment windows. Warehousing services retain stable margin pools through bonded storage and customs-adjacent facilities.
The US Department of Transportation enforces hours-of-service rules that cap driver availability and push fleets toward autonomous convoy pilots. The EU Green Deal mandates progressive CO2 reductions for heavy-duty vehicles, compelling operators to phase diesel rigs from intra-European lanes. India's FSSAI cold-chain directives mandate end-to-end temperature logging for dairy and frozen categories. Stakeholders must weigh electrification capex against regulatory penalty exposure when rebuilding fleet profiles.
Market Dynamics
EU Green Deal mandates are forcing fleet operators to retire diesel rigs ahead of depreciation cycles, compressing capital planning horizons and redrawing procurement criteria across temperature-controlled corridors.
Growth Catalysts
- FSSAI Cold-Chain Directives:India's food-safety regulator mandates end-to-end temperature logging for dairy and frozen categories, pulling investment into compliant warehousing and vehicle telematics.
- Battery-Electric Drivetrains:Zero-emission mandates in urban freight zones are accelerating depot electrification and overnight charging infrastructure deployment.
- Organized Retail Expansion:India's supermarket and hypermarket format growth is generating demand for consolidated distribution networks with multi-temperature capabilities.
Market Restraints
- Lithium-Ion Battery Supply Concentration:Cell manufacturing concentrates in China, exposing fleet electrification timelines to raw material export controls and shipping bottlenecks.
- Driver Availability Caps:US Department of Transportation hours-of-service rules restrict daily driving windows, constraining asset utilization rates for long-haul temperature-controlled lanes.
- Hydrogen Infrastructure Gaps:Fuel-cell truck deployment stalls where refueling station networks remain undeveloped, particularly on transcontinental European corridors.
Strategic Opportunities
- Secondary Cities in India:Tier-2 and Tier-3 urban clusters lack organized cold-chain penetration, creating first-mover advantage for operators building compliant hub-and-spoke networks.
- Biodegradable Packaging Convergence:Integration of compostable films with active temperature monitoring is opening premium perishable contracts in European organic retail channels.
- EU Emissions Trading System:Carbon credit mechanisms for logistics operators are subsidizing early fleet electrification and hydrogen pilot programs.
Industry Challenges
- Telematics Integration Complexity:Legacy warehouse management systems require costly middleware upgrades to interface with real-time vehicle temperature loggers mandated by food-safety regulators.
- Refrigeration Technician Scarcity:Qualified service personnel for transport refrigeration units are concentrated in mature markets, leaving emerging economy fleets exposed to extended downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | FMCG Logistics Market |
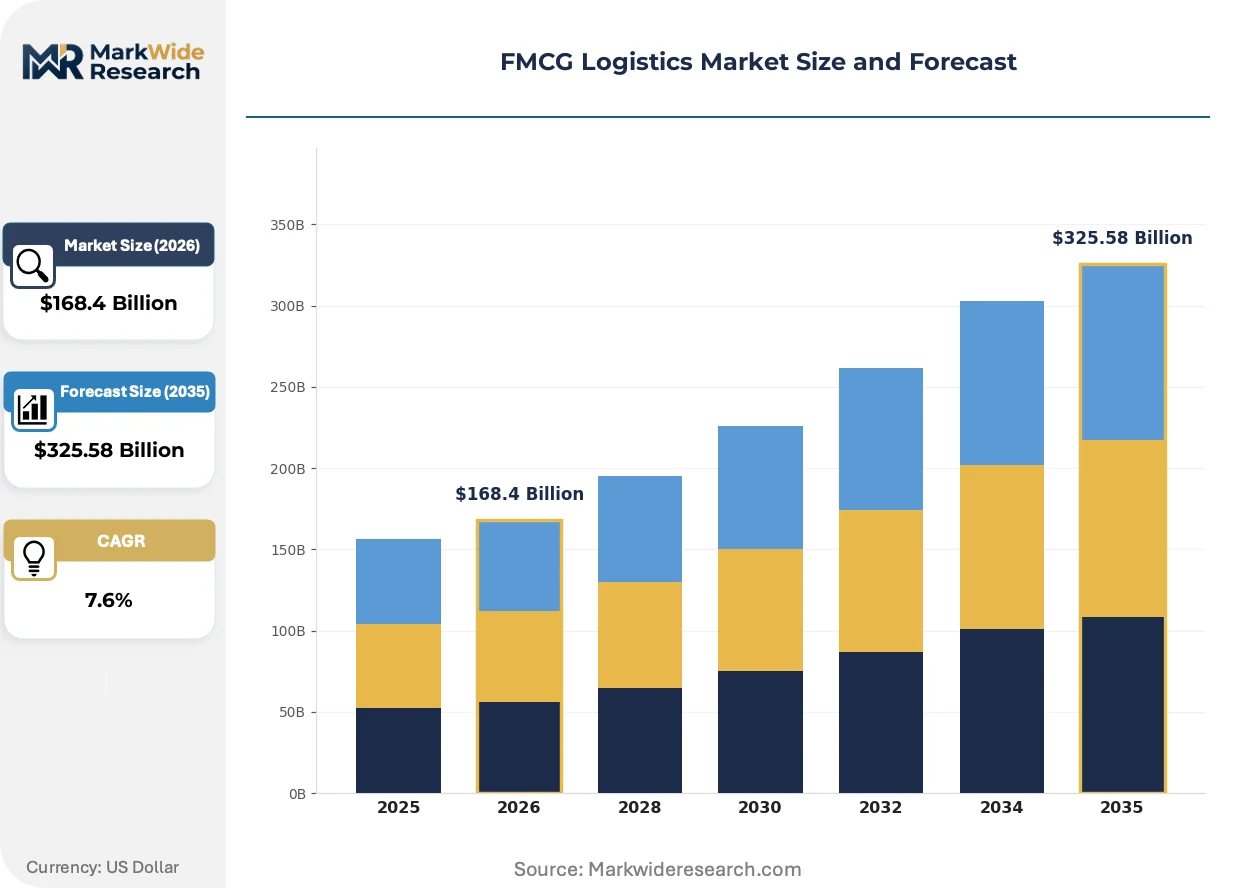
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $325.58 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Distribution, Value-Added Services Delivery Model: Direct Delivery, Cross-Docking, Last-Mile Delivery, Freight Consolidation Customer Type: Retailers, Wholesalers, Distributors, E-commerce Platforms Product Type: Packaged Goods, Perishable Items, Beverages, Household Products |
| Companies Covered | DSV, FedEx Corporation, DHL Group, XPO Logistics, Ceva Logistics, C.H. Robinson Worldwide, DB Schenker, A.P. Moller – Maersk, Kuehne + Nagel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
FMCG Logistics Market Strategic Shifts & Innovations
Digital freight platforms are compressing booking-to-delivery cycles while autonomous convoy pilots and hydrogen fuel-cell drivetrains restructure fleet economics. Three developments are commanding capital allocation.
AI-powered route optimization is unifying dynamic traffic data, temperature telemetry, and delivery window constraints into single-dashboard dispatch decisions. Grocery retailers with sub-24-hour fulfillment mandates are adopting these systems fastest. The technology is unifying previously siloed planning functions, collapsing coordination overhead between warehouse slotting and last-mile sequencing.
REACH chemical safety regulations are restricting hydrofluorocarbon refrigerants in European transport refrigeration units. Equipment manufacturers are accelerating natural refrigerant and CO2-based system development. Dairy and frozen food carriers operating EU cross-border lanes face accelerated retrofit deadlines and are pre-ordering compliant assets.
Direct-to-store delivery models are displacing traditional distributor intermediaries in metropolitan India. Quick-commerce platforms are contracting dedicated temperature-controlled fleets, bypassing conventional wholesale channels. Mumbai and Bangalore clusters exhibit the fastest channel restructuring, with dark store networks absorbing inventory previously held by regional distributors.
FMCG Logistics Market Segmentation
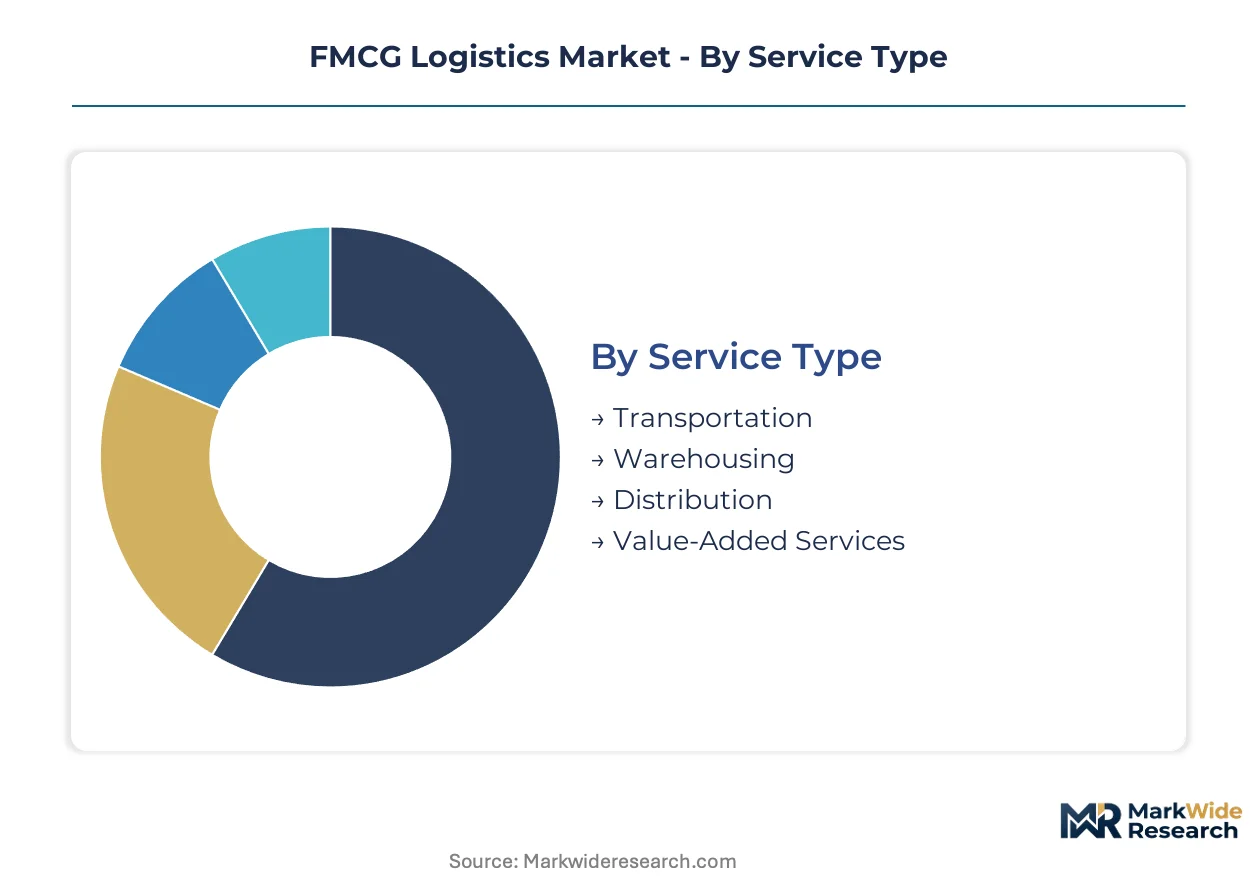
FMCG logistics operators configure service portfolios around asset intensity and temperature requirements. Segmentation reveals where capital deployment concentrates and which delivery models capture margin expansion.
Service Type:
Transportation commands the heaviest upfront capital outlays through fleet acquisition and fuel hedging infrastructure.
- Transportation:Temperature-controlled vehicle fleets absorb depreciation schedules tied to emissions compliance deadlines. Indian dairy corridors and European frozen-food lanes concentrate demand as FSSAI and EU Green Deal mandates tighten.
- Warehousing:Multi-temperature facilities require bonded storage zones and customs-adjacent positioning. Organized retail expansion in Indian metropolitan clusters pulls investment into compliant cold storage.
- Distribution:Hub-and-spoke configurations optimize inventory velocity across fragmented retail networks.
- Value-Added Services:Packaging customization and quality inspection add fee-based revenue streams with lighter asset requirements.
Transportation absorbs the bulk of installed capacity; value-added services are expanding most quickly.
Delivery Model:
Direct delivery and cross-docking split operational complexity between inventory ownership and network coordination.
- Last-Mile Delivery:Sub-24-hour fulfillment windows demand dense node networks in metropolitan zones. Quick-commerce platforms in Mumbai and Bangalore contract dedicated temperature-controlled fleets, bypassing wholesale intermediaries.
- Direct Delivery:Manufacturer-to-retailer shipment eliminates distributor margins but requires customer-specific routing algorithms.
- Cross-Docking:Minimal inventory dwell time reduces refrigeration energy costs in high-throughput facilities.
- Freight Consolidation:Multi-customer load pooling improves asset utilization on long-haul lanes with compatible temperature requirements.
Direct delivery retains the largest operational footprint; last-mile delivery is climbing the fastest.
Customer Type:
E-commerce platforms and retailers impose diverging service-level specifications on shared infrastructure.
- E-commerce Platforms:Real-time tracking and flexible delivery windows command premium pricing. Dark store networks in Indian Tier-1 cities absorb inventory previously held by regional distributors.
- Retailers:Supermarket and hypermarket formats generate consolidated distribution demand with multi-temperature capabilities.
- Wholesalers:Volume-based contracting favors standardized service tiers over customization.
- Distributors:Traditional intermediaries face displacement as direct-to-store models penetrate metropolitan India.
Retailers anchor current revenue concentration; e-commerce platforms are gaining share fastest.
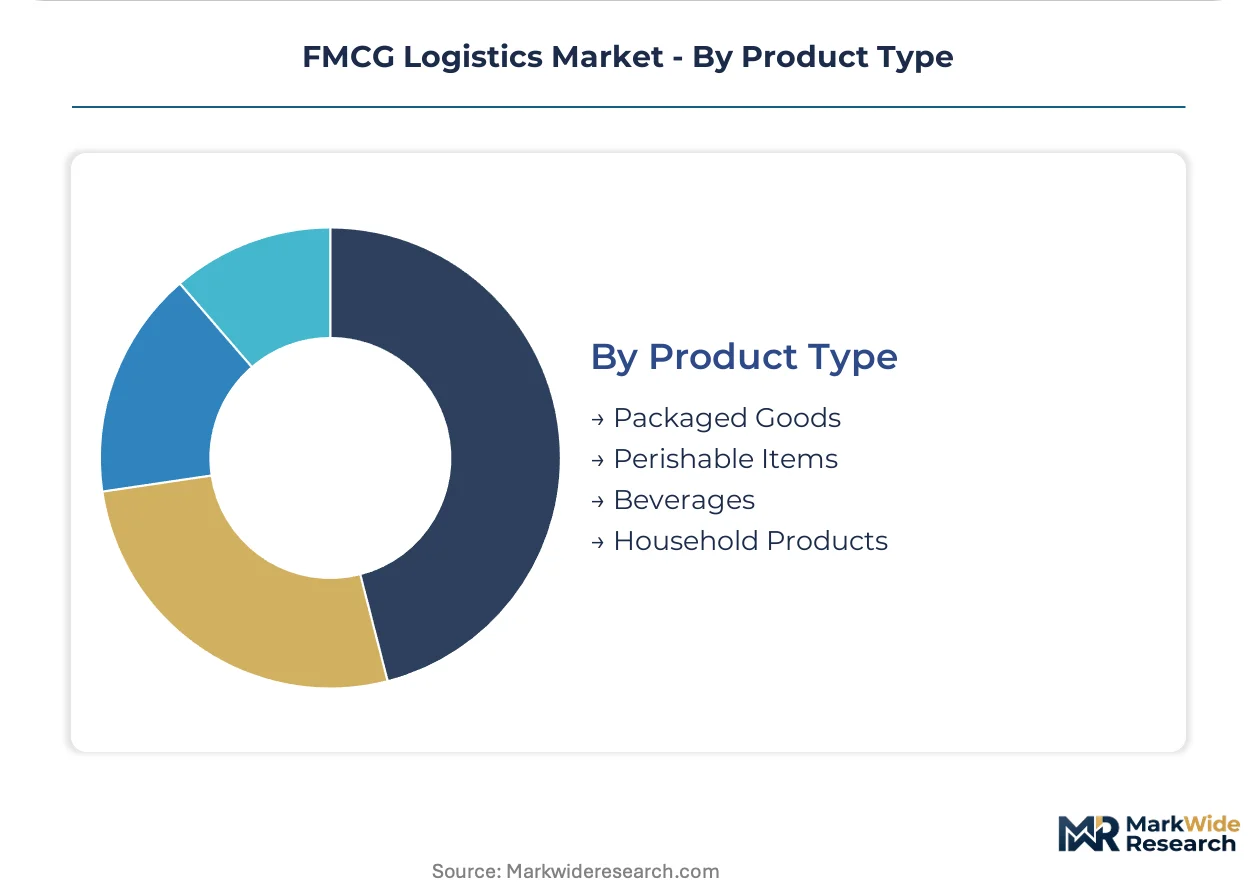
Product Type:
Perishables and beverages impose divergent temperature protocols on shared vehicle assets.
- Perishable Items:Dairy and frozen categories mandate end-to-end temperature logging under FSSAI directives. Natural refrigerant retrofits accelerate as REACH restrictions phase out hydrofluorocarbon systems.
- Beverages:Ambient and chilled distribution splits fleet deployment between insulated and mechanically refrigerated units.
- Packaged Goods:Dry storage requirements allow higher vehicle utilization through reduced energy consumption.
- Household Products:Non-food categories tolerate wider handling tolerances, enabling consolidated shipment with packaged goods.
Packaged goods dominate current throughput volume; perishable items are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in India and Vietnam accelerate cold-chain infrastructure concentration through tax holidays and duty exemptions on refrigeration equipment imports.
United States
E-commerce grocery platforms and quick-commerce startups drive refrigerated last-mile capacity expansion. The Department of Transportation enforces hours-of-service caps that constrain driver utilization on long-haul dairy corridors. Chicago and Dallas-Fort Worth anchor multi-temperature consolidation hubs serving fragmented retail networks.
Germany
Cross-border frozen food traffic between Poland and the Netherlands requires compliant natural refrigerant fleets. The EU Green Deal mandates progressive CO2 reductions for heavy-duty vehicles operating intra-European lanes. The Rhine-Ruhr industrial cluster hosts hydrogen fuel-cell truck pilot programs for temperature-controlled freight.
India
Organized retail penetration in Tier-2 cities generates demand for compliant hub-and-spoke cold networks. FSSAI directives mandate end-to-end temperature logging for dairy and frozen categories nationwide. The Mumbai-Pune corridor absorbs the bulk of quick-commerce dark store investments bypassing traditional wholesale channels.
China
Fresh food e-commerce platforms contract dedicated refrigerated fleets for sub-24-hour fulfillment windows. SAMR enforcement of food safety traceability standards accelerates telematics deployment across transport refrigeration units. The Yangtze River Delta concentrates battery-electric cold-chain vehicle manufacturing capacity.
Brazil
Supermarket format expansion in São Paulo and Rio de Janeiro pulls investment into multi-temperature distribution centers. ANVISA pharmaceutical-grade cold-chain standards extend into perishable food corridors through voluntary certification adoption. The Campinas logistics cluster anchors São Paulo state consolidation for frozen protein exports.
FMCG Logistics Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with asset-heavy transportation operators consolidating around fleet scale and pharmaceutical-grade cold-chain credentials. The vendor base organizes into three tiers: global integrators with end-to-end temperature capabilities, regional specialists dominating specific trade lanes, and technology-enabled platforms compressing booking cycles. Dominant competitive moves include strategic partnerships with grocery retailers for dedicated fleet contracts and geographic expansion into Indian Tier-2 cities through compliant hub-and-spoke networks.
Among European-based integrated logistics providers, DHL Group and DB Schenker occupy positions emphasizing pharmaceutical-grade infrastructure adaptation for premium perishable contracts. FedEx Corporation anchors the express-heavy segment with dense metropolitan node networks. These three exemplify divergent archetypes: cold-chain infrastructure leverage, lane-specific consolidation expertise, and last-mile density optimization.
| Leading Market Players |
|---|
| DSV |
| FedEx Corporation |
| DHL Group |
| XPO Logistics |
| Ceva Logistics |
| C.H. Robinson Worldwide |
| DB Schenker |
| A.P. Moller – Maersk |
| Kuehne + Nagel |
| Others |
Cost & Logistics Intelligence
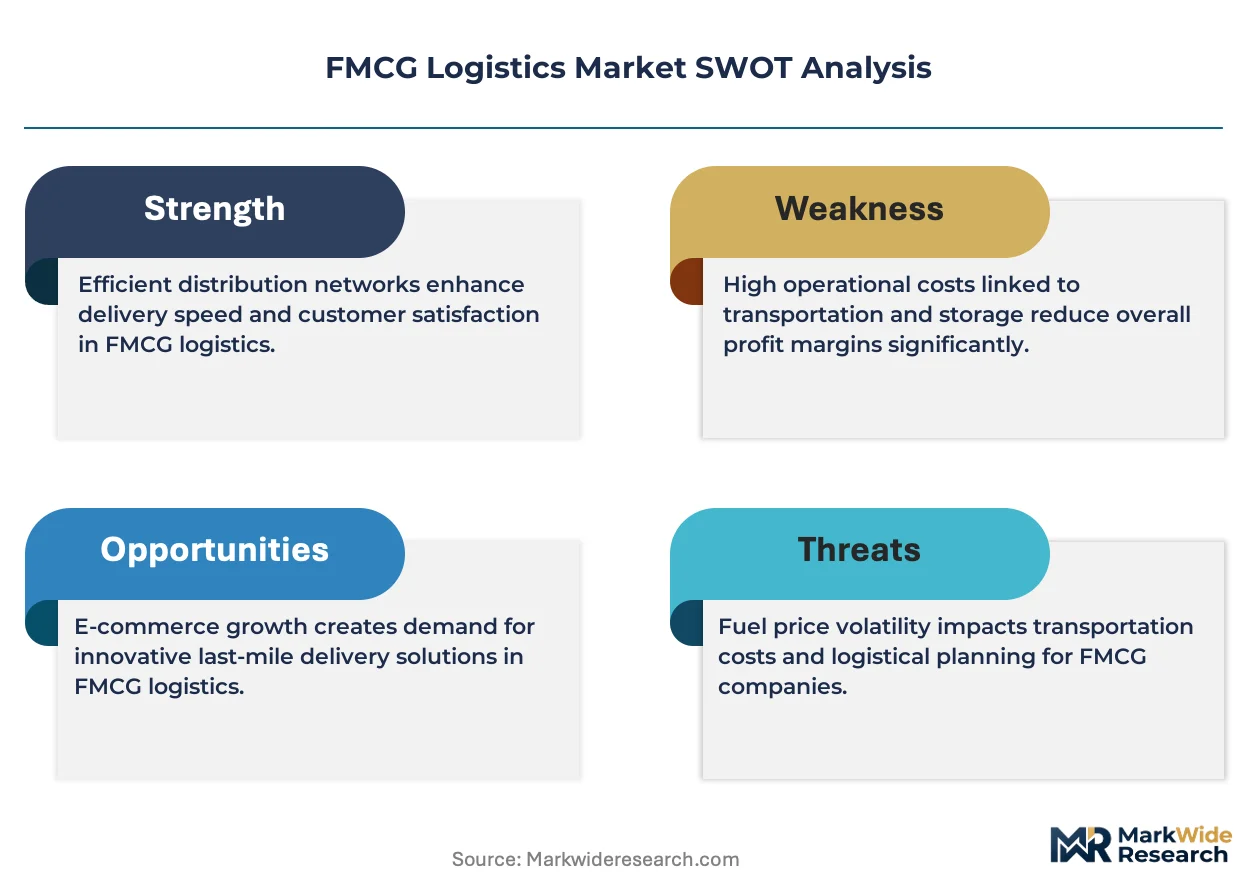
Lithium-ion cell costs cascade through three distinct pricing tiers, with battery-electric fleet operators in Germany and China absorbing premium rates for fast-charging-compatible packs while Indian dairy distributors negotiate standard-tier contracts for depot-charged vehicles and spot-market buyers in Brazil face economy-tier exposure to commodity cell volatility.
Pricing Analysis
Short lead-time premiums dominate contract structures, with sub-48-hour refrigerated capacity commanding 15-25% markups over planned lanes in Mumbai and São Paulo corridors. Three-tier pricing structure across premium pharmaceutical-grade, standard food-grade, and economy ambient segments separates cold-chain certification levels. Cost compression in standard-tier dairy logistics is intensifying because FSSAI compliance investments are compressing operator margins. E-commerce platforms exhibit lowest price sensitivity due to sub-24-hour fulfillment mandates, while traditional wholesalers face highest sensitivity as direct-to-store models erode their volume leverage.
Supply Chain Analysis
Reverse logistics for temperature-controlled packaging—insulated box refurbishment, phase-change material reclamation, and telematics device recovery—anchors circular economy programs at DHL Group and Kuehne + Nagel hub facilities. Manufacturing concentrates in China for battery cells, Germany for transport refrigeration units, and India for vehicle telematics assembly. Fleet electrification draws from lithium carbonate, nickel sulfate, and rare earth magnet inputs. Single-source vulnerability concentrates in Chinese cathode active material production. Distribution runs through bonded cold-storage zones at Mumbai JNPT, Rotterdam, and Los Angeles-Long Beach before last-mile node dispersal.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FMCG logistics is transitioning from diesel-dependent fleet economics to battery-electric and hydrogen fuel-cell infrastructure, with EU Green Deal mandates and FSSAI directives accelerating technology replacement timelines.
For Market Incumbents: Deploy pharmaceutical-grade cold-chain certification as a defensive moat against quick-commerce entrants seeking perishable contracts. Retrofit legacy warehouse management systems with API middleware to interface with real-time temperature loggers mandated by India's food-safety regulator. Consolidate Tier-2 Indian hub capacity before organized retail penetration deepens competitive density. For New Entrants and Emerging Players: Capture secondary city cold-chain white space in India's Tier-2 urban clusters where compliant infrastructure remains underdeveloped. Target quick-commerce platform contracts in Mumbai and Bangalore corridors where dark store networks are displacing traditional distributors. Enter through digital freight platform partnerships that compress booking-to-delivery cycles without heavy fleet asset ownership. For Investors and Strategic Acquirers: EU carbon credit mechanism expansion is the leading indicator that early fleet electrification will generate sustained margin advantages over diesel-dependent competitors. Acquisition candidates with bonded multi-temperature warehousing in customs-adjacent positioning offer longest-horizon viability. Monitor hydrogen refueling station deployment velocity on transcontinental European corridors as inflection signal for fuel-cell truck economics.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Cold-Chain Certification | FSSAI and EU REACH mandates are pulling investment into compliant warehousing and vehicle telematics infrastructure. |
| Battery-Electric Fleet Conversion | EU Green Deal CO2 reduction timelines are compressing capital planning horizons for heavy-duty vehicle procurement. |
| Digital Freight Platform Integration | AI-powered route optimization unifies traffic data, temperature telemetry, and delivery constraints into single-dashboard dispatch. |
| Tier-2 India Hub-and-Spoke Expansion | Organized retail penetration in secondary cities generates first-mover advantage for compliant cold-network operators. |
| Hydrogen Fuel-Cell Pilot Deployment | Rhine-Ruhr industrial cluster programs test temperature-controlled freight viability on transcontinental European lanes. |
Research Approach
Document review covered EU Green Deal implementation guidance, FSSAI cold-chain directives, and REACH refrigerant phase-out schedules, complemented by interviews with fleet procurement directors at integrated logistics providers, cold-storage facility operators in India and Brazil, and quick-commerce supply chain heads in metropolitan Asian markets. Secondary validation drew from customs trade data, SEC 10-K logistics segment disclosures, and automotive OEM electrification roadmaps. Bottom-up service demand modeling and top-down macroeconomic triangulation anchored value estimates.
Segment-level outputs across transportation, warehousing, and value-added services were calibrated against delivery model splits and customer-type concentrations throughout the forecast period. Service type, delivery model, customer archetype, and product temperature requirements formed core segmentation dimensions. CAGRs emerged from logistic curve fitting of fleet electrification adoption rates and organized retail penetration trajectories. Battery cost decline curves and hydrogen infrastructure build-out schedules supplied industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to lithium raw material export controls, hydrogen refueling network deployment velocity, and FSSAI enforcement intensity across Indian states. Forecasts reflect documented assumptions about regulatory mandate timelines and technology cost curves. Material deviation in battery cell supply availability or EU carbon credit pricing mechanisms warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Mexico Cold Chain Logistics Market
Transportation & Logistics
Road Haulage Market
Transportation & Logistics
India less than-Truck-Load (LTL) Market
Transportation & Logistics
Slovakia Road Freight Transport Market
Transportation & Logistics
Multimodal Transport Market
Transportation & Logistics
Ride-Hailing and Taxi Market
Transportation & Logistics
Latin America Cross Border Road Freight Market
Transportation & Logistics
Spain Road Freight Transport Market
Transportation & Logistics
Romania Road Freight Transport Market
Transportation & Logistics
North America Road Freight Transport Market
Transportation & Logistics
Chile Road Freight Transport Market
Transportation & Logistics
Parking Meter Market
Transportation & Logistics
United States Refrigerated Transport Market
Transportation & Logistics
Poland Road Freight Transport Market
Transportation & Logistics
Malaysia Refrigerated Trailer Market
Transportation & Logistics
Refrigerated Trailer Market