
 Europe Ship Bridge Simulators Market | 2026-2036
Europe Ship Bridge Simulators Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Ship Bridge Simulators Market Foresight
Multi-source procurement among European maritime training institutions is shifting toward integrated simulator suites that bundle hardware, software, and certification support. Kongsberg Digital dominates the high-fidelity full-mission segment through its long-standing R&D presence in Norway. Wärtsilä leverages its Helsinki engineering base to sustain strong relationships with Baltic Sea naval customers. Rheinmetall AG anchors the defense-oriented end user channel with specialized naval combat bridge systems.
Europe Ship Bridge Simulators are hardware-software platforms that replicate vessel bridge environments with physical consoles, visual projection systems, and hydrodynamic physics engines generating vessel motion responses to helm, engine, and environmental inputs; their primary purpose is to train deck officers in navigation, collision avoidance, and emergency response without operational risk. Full Mission systems command the premium tier due to their complete physical bridge replication and DNV certification requirements, while Virtual Reality technology represents the fastest-expanding segment as headsets reduce footprint costs for smaller maritime academies. Desktop and Part Task configurations occupy the volume tier, serving refresher training and specific skill modules where capital constraints limit full-mission investment.
EMSA enforces STCW-aligned training standards that mandate simulator hours for officer certification upgrades, directly expanding replacement demand across European maritime academies. The EU's F-Gas Regulation and CE marking requirements constrain hardware sourcing for motion platforms and visual systems, favoring suppliers with established European assembly and service networks. Stakeholders must monitor the divergence between national flag-state interpretations of STCW simulator requirements, as stricter implementations in Germany and the Netherlands will reshape competitive positioning for training center contracts.
Market Dynamics
EMSA's tightened STCW implementation through national flag-state authorities is forcing maritime academies across Northern Europe to replace aging simulator hardware before certification deadlines expire.
Growth Catalysts
- STCW Certification Mandates:EMSA-aligned training standards now require documented simulator hours for bridge officer upgrades, compelling maritime academies in Germany and the Netherlands to expand fleet capacity.
- Maritime Cluster Expansion:Training centers in Norway are scaling simulator-based programs to serve offshore vessel operators preparing crews for autonomous navigation protocols.
- F-Gas Hardware Replacement:The EU F-Gas Regulation is phasing out refrigerants used in legacy motion platform cooling systems, triggering systematic equipment refresh cycles across Baltic Sea training facilities.
Market Restraints
- Visual System Supply Concentration:High-lumen laser projection hardware for 360-degree bridge domes relies on a narrow supplier base concentrated in German and Dutch industrial clusters, creating procurement bottlenecks.
- CE Marking Complexity:Motion platform safety certification under EU machinery directives extends delivery timelines by eight to fourteen months for non-European component integrators.
- Desktop Simulator Substitution:Part-task and VR-based training modules are capturing refresher certification segments that previously required full-mission bridge investments.
Strategic Opportunities
- Polish Maritime Academy Network:Underpenetrated training infrastructure along the Baltic corridor presents first-mover positioning for integrated simulator suite vendors before EMSA compliance deadlines tighten.
- Naval Combat Bridge Convergence:Civilian full-mission platforms are incorporating military-grade radar simulation and electronic warfare modules to serve dual-use procurement channels in Scandinavian defense markets.
- Cloud-Based Instructor Stations:Remote monitoring and scenario deployment capabilities are opening subscription revenue models for simulator OEMs serving distributed maritime training networks.
Industry Challenges
- Hydrodynamic Modeling Talent Scarcity:Physics engine calibration requires specialized naval architects capable of coding vessel-specific motion responses, a skill set concentrated among retiring specialists in Norway and Germany.
- DNV Certification Timelines:Type approval for new full-mission configurations demands eighteen to twenty-four months of sea-trial correlation studies, compressing product development windows against regulatory deadlines.
- Legacy Integration Friction:Maritime academies operating 2015-era Kongsberg and Wärtsilä platforms face proprietary protocol barriers when adding third-party radar or ECDIS modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Ship Bridge Simulators Market |
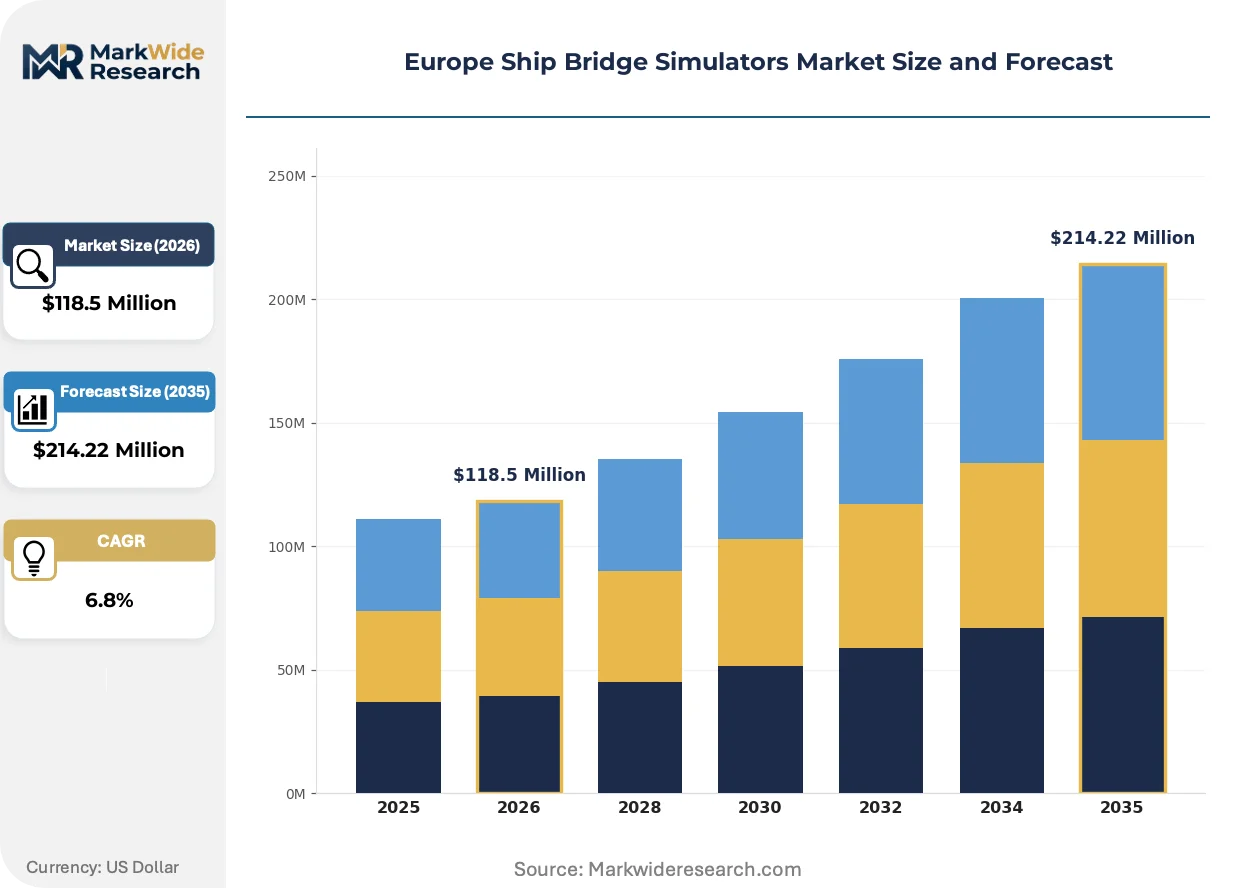
| Market Size in 2026 | $118.5 Million |
| Market Size in 2035 | $214.22 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Mission, Part Task, Desktop, Portable Application: Training Centers, Research Institutions, Maritime Academies, Shipping Companies Technology: Virtual Reality, Augmented Reality, 3D Visualization, Motion Simulation End User: Naval Forces, Coast Guard, Commercial Shipping, Offshore Industry |
| Companies Covered | Rheinmetall AG, AVEVA Group plc, BMT Group Ltd, General Dynamics Information Technology, Wärtsilä, Kongsberg Digital, FORCE TECHNOLOGY, VSTEP BV, ARI Simulation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Ship Bridge Simulators Market Shifts & Advancements
Virtual reality headsets are compressing footprint requirements for bridge simulator deployment, while cloud-based scenario libraries are unbundling content from hardware lock-in. These shifts are redistributing competitive advantage toward software-native vendors.
VR-based part-task trainers are expanding into collision avoidance and restricted visibility modules previously reserved for full-mission domes. Maritime academies in the Netherlands are deploying these configurations for entry-level cadet screening. The technology is expanding into cost-sensitive training segments without compromising STCW-mandated learning objectives.
REACH chemical restrictions and the EU F-Gas Regulation are constraining coolant selection for hydraulic motion platforms. Equipment manufacturers with established European assembly networks are securing faster CE marking pathways than import-dependent competitors. German flag-state authorities are interpreting these environmental rules most strictly, reshaping supplier qualification criteria for training centers under Bremen and Hamburg jurisdiction.
Multi-year leasing arrangements with bundled certification support are displacing outright purchase models for full-mission systems. Maritime training clusters in Norway are negotiating outcome-based contracts where payment scales to cadet throughput and certification pass rates. This restructuring concentrates vendor risk while transferring capital burden from academy balance sheets to OEM financing arms.
Europe Ship Bridge Simulators Market Segmentation
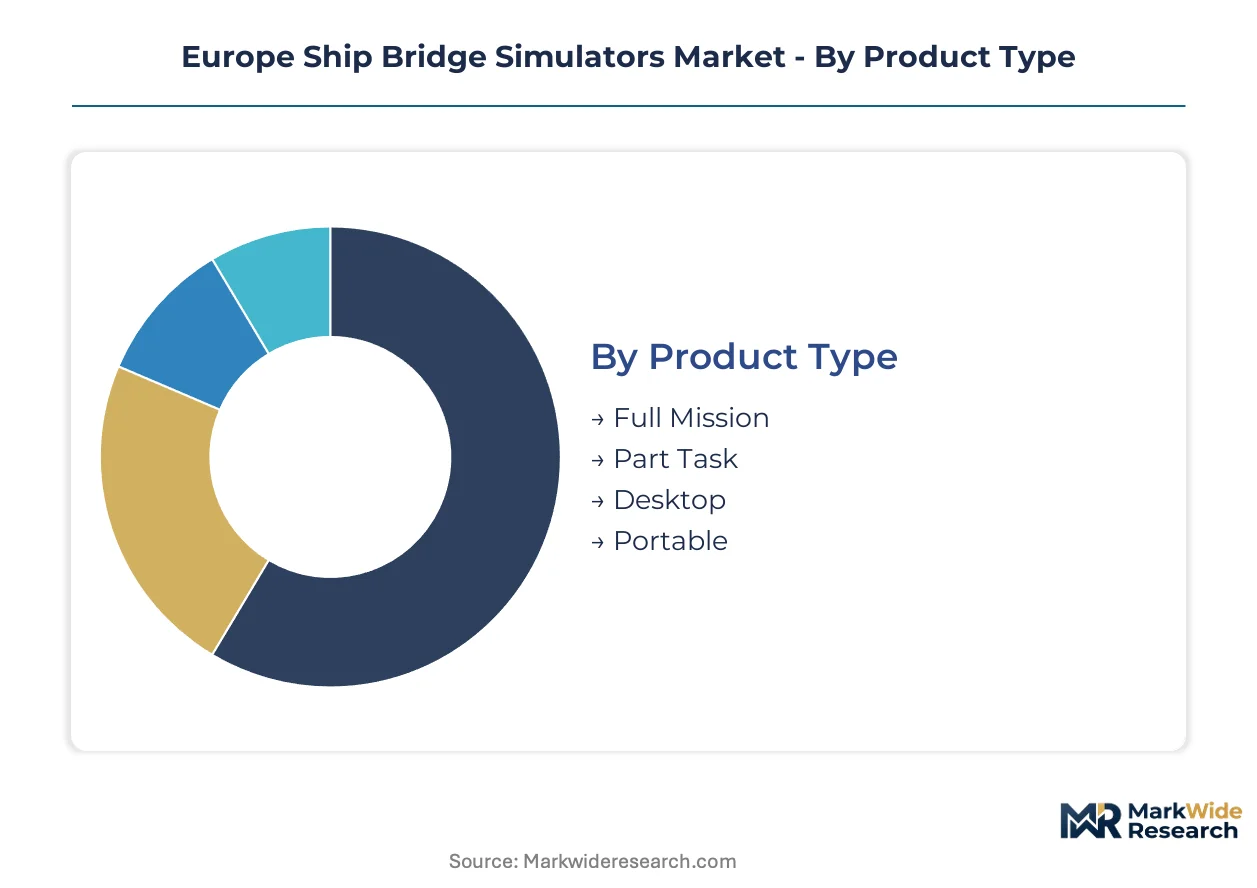
Ship bridge simulator procurement across Europe follows distinct technology-performance tiers that align with EMSA certification requirements and capital constraints. Training institutions balance DNV type-approval mandates against footprint limitations and cadet throughput targets when selecting configurations.
Product Type:
Physical fidelity and certification grade separate configurations across the European maritime training landscape.
- Full Mission:Complete physical bridge replicas with 360-degree visual domes, integrated radar consoles, and DNV-certified hydrodynamic physics engines satisfy STCW-mandated assessment protocols for unlimited license upgrades. Maritime academies in Norway and Germany concentrate replacement demand here as legacy Kongsberg and Wärtsilä systems approach end-of-life.
- Part Task:Modular configurations isolate specific bridge functions—ECDIS operation, ARPA radar plotting, or GMDSS communication—for targeted skill certification without full-mission capital outlay. Dutch training centers deploy these for refresher modules and flag-state endorsement programs.
- Desktop:Screen-based simulations running on standard computing hardware support theoretical navigation exercises and rule-of-the-road instruction at minimal infrastructure cost.
- Portable:Containerized or trailer-mounted systems enable temporary deployment to remote maritime clusters and naval mobilization exercises across Baltic Sea jurisdictions.
Full Mission leads on scale; Part Task leads on momentum.
Application:
End-use procurement patterns reflect divergent certification authority and funding mechanisms.
- Maritime Academies:Publicly funded institutions under German, Dutch, and Norwegian flag-state jurisdiction drive volume demand for STCW-compliant full-mission suites with documented sea-time equivalency.
- Training Centers:Commercial operators serving multiple flag administrations prioritize flexible scenario libraries and rapid certification turnaround for employed seafarers.
- Research Institutions:Universities and maritime innovation hubs in Denmark and Sweden acquire platforms with open architecture for autonomous navigation algorithm development and human factors studies.
- Shipping Companies:In-house facilities at major European operators focus on company-specific route familiarization and crisis response drills rather than license preparation.
Maritime Academies dominate procurement volume; Training Centers capture the steepest expansion trajectory as outsourced certification grows.
Technology:
Immersive depth and motion fidelity differentiate technical approaches to bridge environment replication.
- Virtual Reality:Headset-based immersion eliminates physical dome construction and reduces footprint requirements by eighty percent compared to projection systems. Maritime academies in the Netherlands are deploying VR configurations for entry-level cadet screening and collision avoidance modules.
- Motion Simulation:Six-degree-of-freedom platforms with hydraulic actuators generate vessel motion cues for seasickness acclimatization and heavy-weather maneuver training. REACH and F-Gas Regulation constraints on coolant chemistry are reshaping supplier qualification for Baltic Sea training facilities.
- 3D Visualization:Multi-channel projection arrays render photorealistic port approaches and traffic scenarios for full-mission domes.
- Augmented Reality:Overlay systems blend physical bridge instrumentation with synthetic visual elements for hybrid training architectures.
3D Visualization anchors established installations; Virtual Reality gains share fastest among new procurement.
End User:
Operational mission dictates simulator specification priorities and procurement channels.
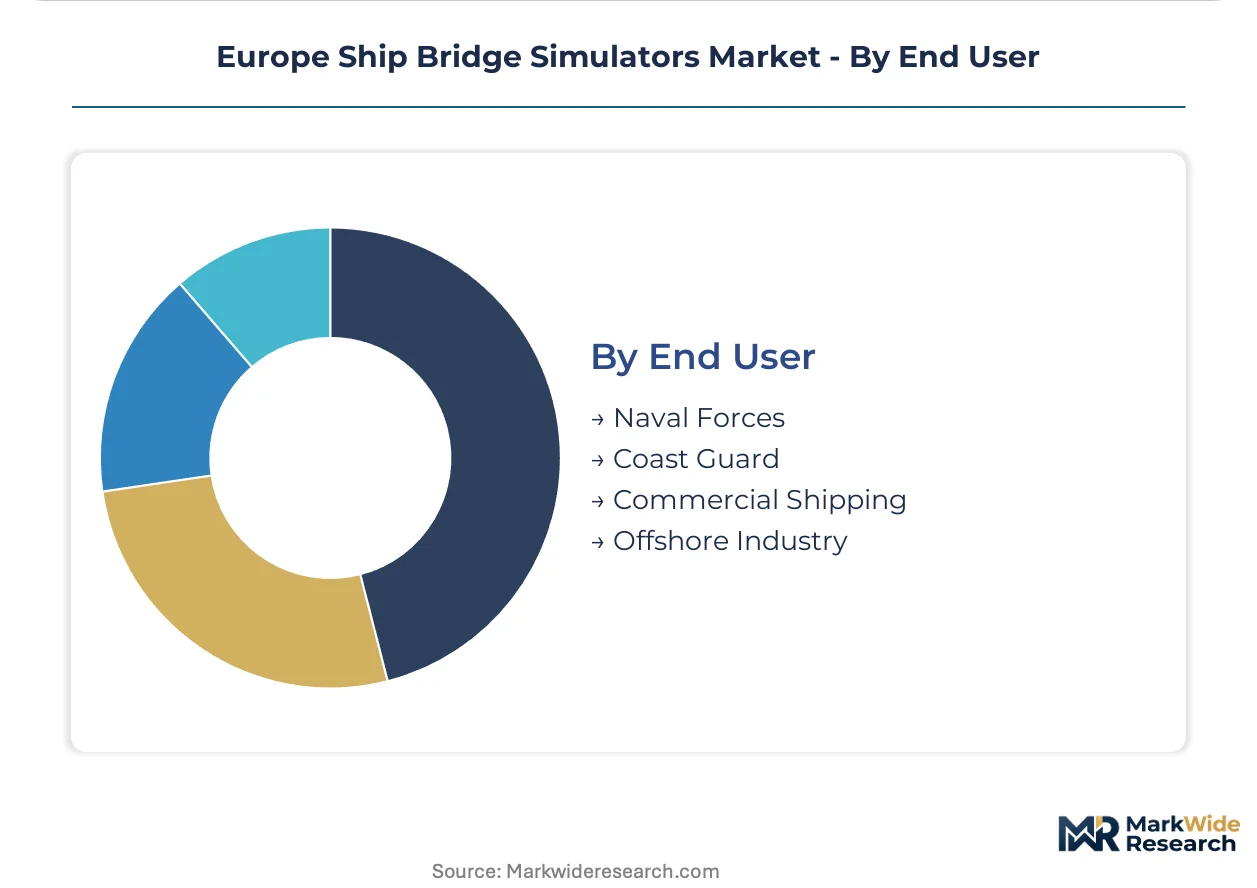
- Commercial Shipping:Container lines, tanker operators, and ferry companies prioritize route-specific scenario libraries and fuel-efficient maneuver optimization for officer continuing education.
- Naval Forces:Scandinavian defense procurement channels demand combat bridge configurations with electronic warfare simulation, threat response protocols, and NATO interoperability standards.
- Offshore Industry:Dynamic positioning integration and anchor-handling simulation serve North Sea oil and gas vessel operators preparing crews for platform supply and construction support missions.
- Coast Guard:Search and rescue scenario libraries, small-craft interception protocols, and pollution response coordination dominate specification requirements.
Commercial Shipping leads on unit volume; Naval Forces command the highest per-unit specification tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The maritime training corridor stretching from Hamburg to Rotterdam anchors European demand for certified bridge simulation systems. National flag-state authorities in Germany and the Netherlands are enforcing EMSA-aligned STCW mandates ahead of 2027 certification deadlines. Maritime academies in Norway and Poland are expanding capacity to capture spillover demand from congested North Sea training infrastructure.
Germany
Maritime academies in Bremen and Hamburg are replacing legacy Kongsberg installations to meet German flag-state interpretations of EMSA's tightened simulator hour requirements. The Federal Maritime and Hydrographic Agency enforces stricter DNV correlation study documentation than neighboring jurisdictions. Training centers along the Elbe River corridor are consolidating procurement through multi-year leasing arrangements with integrated certification support.
Norway
Offshore vessel operators in Stavanger and Bergen are scaling simulator programs for autonomous navigation protocol training. The Norwegian Maritime Authority aligns STCW implementation with EMSA guidelines while adding supplementary requirements for dynamic positioning certification. Kongsberg Digital maintains its R&D headquarters in Kongsberg, supplying high-fidelity full-mission systems to maritime academies in Ålesund and Horten.
Netherlands
Maritime training clusters in Rotterdam and Delft are deploying VR-based part-task trainers for entry-level cadet screening. The Human Environment and Transport Inspectorate enforces REACH-compliant coolant specifications for hydraulic motion platforms more strictly than Baltic counterparts. Dutch training centers are negotiating outcome-based contracts where vendor payments scale to certification pass rates.
Poland
The Polish Maritime Academy network in Gdynia and Szczecin presents underpenetrated infrastructure for integrated simulator suite vendors. National regulators are accelerating EMSA compliance timelines to align with EU accession commitments for maritime education standards. Baltic corridor training facilities are upgrading from desktop configurations to full-mission domes ahead of 2026 certification deadlines.
United Kingdom
Maritime academies in Southampton and Glasgow are refreshing simulation fleets following post-Brexit realignment with EMSA standards. The Maritime and Coastguard Agency maintains STCW implementation rules that diverge minimally from continental EMSA guidance. Training centers in Liverpool and Plymouth are incorporating naval combat bridge modules to serve dual-use procurement channels.
Europe Ship Bridge Simulators Market Competitive Landscape
Global majors compete with regional champions across certification-grade fidelity tiers and national flag-state relationships. The vendor base organizes around three strategic archetypes: Nordic engineering conglomerates with captive maritime heritage, defense contractors leveraging naval combat bridge expertise, and specialized simulation software houses unbundling content from hardware. Consolidation pressure is accelerating as leasing models transfer capital burden from academy balance sheets to OEM financing arms. Strategic partnerships between projection hardware suppliers and physics engine developers are reshaping procurement evaluation criteria.
Among defense-oriented fabricators, Rheinmetall AG exemplifies the naval combat bridge convergence archetype. Kongsberg Digital and Wärtsilä occupy positions within the integrated full-mission suite tier, with the former representing Nordic engineering heritage and the latter anchoring Baltic Sea customer relationships through its Helsinki engineering base. These three entities illustrate how geographic proximity to maritime training clusters shapes competitive positioning across Northern European procurement channels.
| Leading Market Players |
|---|
| Rheinmetall AG |
| AVEVA Group plc |
| BMT Group Ltd |
| General Dynamics Information Technology |
| Wärtsilä |
| Kongsberg Digital |
| FORCE TECHNOLOGY |
| VSTEP BV |
| ARI Simulation |
| Others |
Supply & Pricing Matrix
VR headset adoption across Dutch and Norwegian maritime academies is compressing physical infrastructure requirements while redistributing cost structures toward software licensing and away from capital-intensive dome construction. This technology transition simultaneously weakens pricing power for projection hardware specialists and strengthens subscription-based revenue models for physics engine developers serving distributed training networks.
Pricing Analysis
Input-cost pass-through from laser projection hardware and hydraulic motion platform coolants shapes pricing dynamics across certification tiers. Pricing stratifies across DNV-certified full-mission suites, EMSA-compliant part-task modules, and desktop configurations for theoretical instruction. Cost compression in motion platforms is intensifying because REACH and F-Gas Regulation constraints on refrigerant chemistry are forcing equipment refresh cycles. Maritime academies in Germany exhibit lowest price sensitivity due to bundled leasing arrangements with certification guarantees, while Polish training centers remain most sensitive to upfront capital outlays.
Supply Chain Analysis
Reverse-logistics flows for simulator hardware refurbishment center on Norway, Germany, and the Netherlands where Kongsberg Digital and Wärtsilä maintain captive service networks for legacy platform upgrades. The supply chain draws from specialized laser projection manufacturers in German industrial clusters, hydraulic actuator producers in Italy, and semiconductor suppliers from Taiwan and South Korea. Single-source vulnerability concentrates in high-lumen projection engines for 360-degree visual domes. Distribution runs through direct OEM relationships with maritime academies rather than channel intermediaries, reflecting the complexity of DNV certification integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge from divergent EMSA implementation timelines, with Polish and Baltic training centers facing compressed compliance deadlines that German and Dutch institutions have already absorbed. This regulatory lag creates cost-efficient entry positioning for vendors willing to finance academy upgrades against future certification revenue streams.
For Market Incumbents: Lock in multi-year leasing arrangements with Polish maritime academies before EMSA compliance deadlines eliminate negotiating leverage. Secure exclusive physics engine licensing agreements with emerging VR-native software houses to preempt substitution threats from unbundled content providers. Deepen backward integration into laser projection hardware through strategic partnerships with German industrial optics specialists.
For New Entrants and Emerging Players: Launch via cloud-based instructor station subscriptions targeting underpenetrated training centers along the Baltic corridor. The Polish Maritime Academy network in Gdynia and Szczecin represents the most penetrable geography, with desktop-to-full-mission upgrade demand accelerating ahead of 2026 certification deadlines. Prioritize outcome-based contracting models where payment scales to cadet throughput rather than capital equipment sales.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized hydrodynamic modeling software houses with aging founder-owners and no succession planning. Long-term viability hinges on captive relationships with Norwegian and German flag-state authorities that resist standardization. Acquisition targets should demonstrate proven DNV type-approval pathways and established EMSA certification documentation. Monitor divergence between national flag-state interpretations of STCW simulator hour requirements as the inflection signal for competitive repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Based Instructor Station Deployment | Enables subscription revenue models for OEMs serving distributed maritime training networks across Northern Europe. |
| DNV Type-Approval Investment | Accelerates market access for full-mission configurations in German and Norwegian maritime academies facing replacement deadlines. |
| Polish Maritime Academy Partnership | Captures first-mover positioning in underpenetrated Baltic corridor before EMSA compliance timelines tighten. |
| VR-Native Physics Engine Acquisition | Defends against unbundled software vendors displacing integrated hardware-software suites in cost-sensitive segments. |
| Outcome-Based Contracting Structure | Transfers capital burden from academy balance sheets to OEM financing arms while aligning vendor incentives with certification pass rates. |
Research Methodology
Multiple input streams — structured interviews with maritime academy procurement directors, simulator OEM technical sales leads, and EMSA certification auditors — were reconciled against secondary validation from EMSA training standard documentation, DNV type-approval registries, and national flag-state regulatory filings. Bottom-up demand modeling aggregated replacement cycles across German, Norwegian, Dutch, Polish, and UK maritime training infrastructure. Top-down triangulation cross-referenced vendor shipment disclosures and leasing contract announcements reported in maritime industry press.
Historical capacity deployment patterns were cross-referenced against panel input from physics engine developers and projection hardware specialists to anchor growth assumptions across the analysis window. Segmentation modeling incorporated product type tiers, application categories, technology approaches, and end-user missions. CAGRs were derived from correlated equipment replacement timelines and regulatory deadline schedules. Hydrodynamic modeling talent scarcity and REACH coolant restriction timelines served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EMSA implementation by German flag-state authorities or prolonged DNV certification delays. Practitioners should monitor divergence between national interpretations of STCW simulator hour requirements and F-Gas Regulation enforcement intensity across Baltic Sea jurisdictions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Simulation and Training
Flight Simulator Market
Simulation and Training
Trainer Aircraft Market
Simulation and Training
Middle East and Africa Ship Bridge Simulators Market
Simulation and Training
Military Simulation Software Market
Simulation and Training
Asia-Pacific Civil Aviation Simulators Market
Simulation and Training
North America Simulator Windows and Simulator Skylights Market
Simulation and Training
Live Laser-Based Training and Simulation Platforms Market
Simulation and Training
Europe Flight Training and Simulation Market
Simulation and Training
RADAR Simulator Market
Simulation and Training
Pilot Training Market
Simulation and Training
Global Ship Bridge Simulators Market
Simulation and Training
Military Simulation and Training Market
Simulation and Training
Middle East Civil Aviation Flight Training and Simulation Market
Simulation and Training
Dynamic Flight Training Compartments Market
Simulation and Training
Civil Aviation Simulator Market
Simulation and Training
Military Simulation Virtual Training Market