
 Middle East Civil Aviation Flight Training and Simulation Market | 2026-2036
Middle East Civil Aviation Flight Training and Simulation Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Civil Aviation Flight Training and Simulation Market Foresight
Airline operator investment in pilot readiness is pivoting toward in-house academies rather than outsourced programs. CAE Inc. anchors the regional installed base through long-term training service agreements with Gulf carriers. Emirates Flight Training Academy leverages its Dubai headquarters to supply cadet pipelines for Emirates Airline's wide-body fleet expansion. Etihad Aviation Training competes on Abu Dhabi sovereign backing and co-location with Zayed International Airport operations.
Middle East civil aviation flight training and simulation encompasses synthetic training environments replicating aircraft flight dynamics, cockpit systems, and emergency scenarios through certified devices meeting ICAO Type VII standards and local aviation authority criteria. These systems reduce live-flight training hours, cut fuel consumption, and eliminate weather-dependent scheduling risks for commercial and military operators. Full flight simulators command the premium product tier due to Level D certification requirements and motion platform complexity, while virtual reality modules represent the fastest-growing technology segment as headset fidelity improves and procurement costs decline. Fixed-base simulators retain strong demand from flight schools serving private pilot and recreational application markets where motion cueing offers diminishing instructional returns.
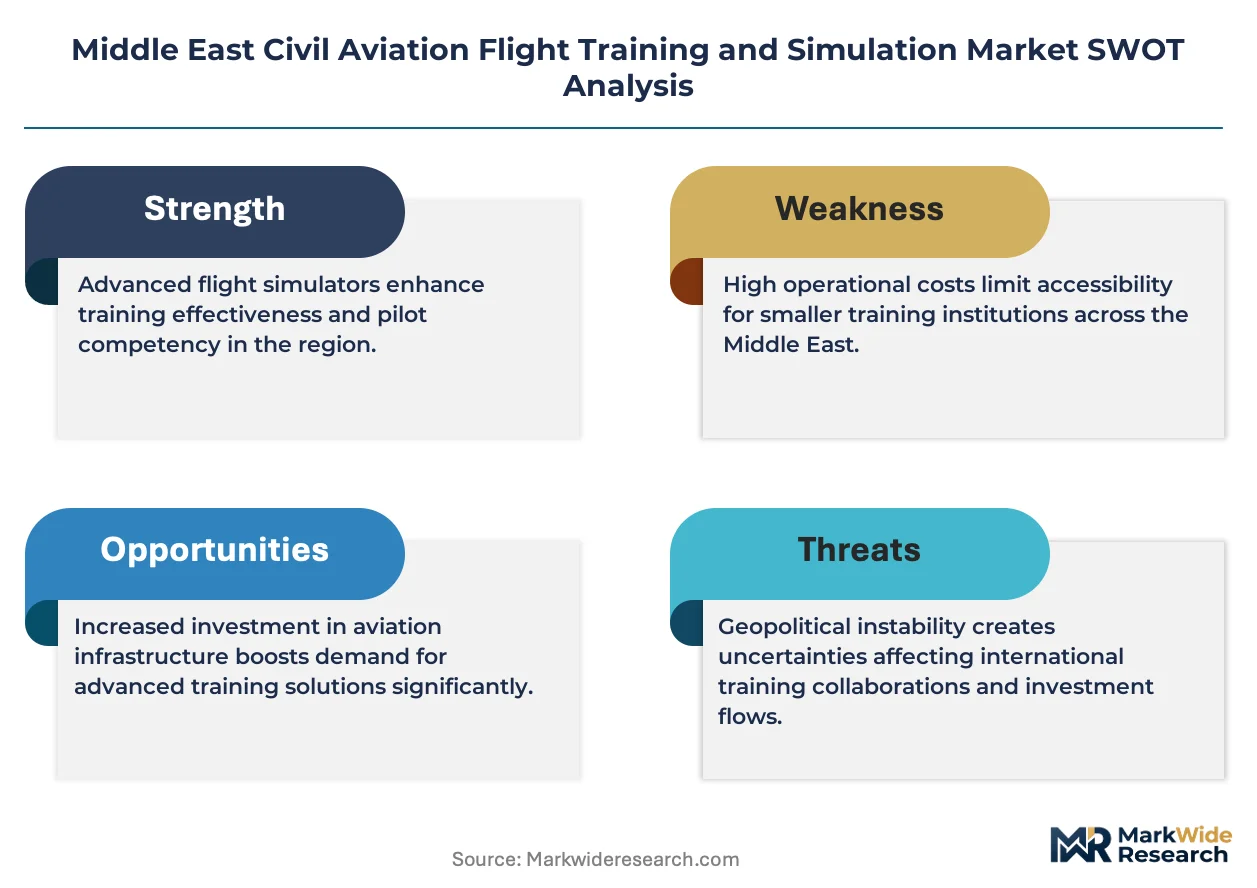
The UAE's General Civil Aviation Authority and Saudi Arabia's General Authority of Civil Aviation enforce ICAO-compliant pilot licensing standards that mandate recurrent simulator-based training, directly expanding device utilization rates. EASA cross-recognition agreements with Gulf regulators enable European-trained instructors to staff regional academies, accelerating knowledge transfer without duplicative certification regimes. Stakeholders must monitor how Saudi Arabia's localization mandates under Vision 2030 reshape foreign versus indigenous training provider market access.
Market Dynamics
Regulatory mandates from the UAE's General Civil Aviation Authority and Saudi Arabia's General Authority of Civil Aviation are compressing pilot certification timelines and forcing carriers to expand synthetic training capacity faster than physical infrastructure can scale.
Growth Catalysts
- ICAO Type VII Compliance Mandates:Recurrent simulator-based training requirements under GCAA and GACA regulations directly expand device utilization rates across Gulf carriers.
- Wide-Body Fleet Expansion:Emirates, Etihad, and Saudia are adding Boeing 777X and Airbus A350 aircraft, creating demand for corresponding Full Flight Simulator configurations.
- Localization Under Vision 2030:Saudi Arabia's sovereign mandates are redirecting training expenditure toward indigenous academies and joint ventures with established simulator OEMs.
Market Restraints
- Motion Platform Supply Concentration:Hydraulic and electric motion base production concentrates in North American and European specialist suppliers, exposing regional integrators to extended lead times.
- Level D Certification Burden:The technical complexity of achieving FAA/EASA Level D equivalence under GCAA validation creates 18-24 month approval cycles for new simulator installations.
- Visual System Component Costs:Collimated display domes and LED-based image generators represent 35-40% of total simulator capex, with single-source dependencies on projection technology.
Strategic Opportunities
- Virtual Reality Module Integration:Headset-based procedural trainers from Varjo and Pico are converging with traditional FTD architectures, opening lower-cost entry points for ab initio programs.
- Kuwait and Oman Market Entry:Underpenetrated training infrastructure in these GCC states offers first-mover positioning as their flag carriers expand narrow-body operations.
- EASA Cross-Recognition Leverage:Bilateral agreements enabling European-trained instructors to staff regional academies reduce certification duplication and accelerate knowledge transfer.
Industry Challenges
- Simulator Instructor Scarcity:Type-rated pilots with instructional certification remain concentrated at legacy carriers, constraining academy scaling.
- Legacy Device Obsolescence:Older Level C platforms require avionics retrofitting to match current fleet configurations, complicating training standardization.
- Data Rights Fragmentation:OEM flight model data packages carry restrictive licensing terms that limit third-party simulator development and maintenance autonomy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Civil Aviation Flight Training and Simulation Market |
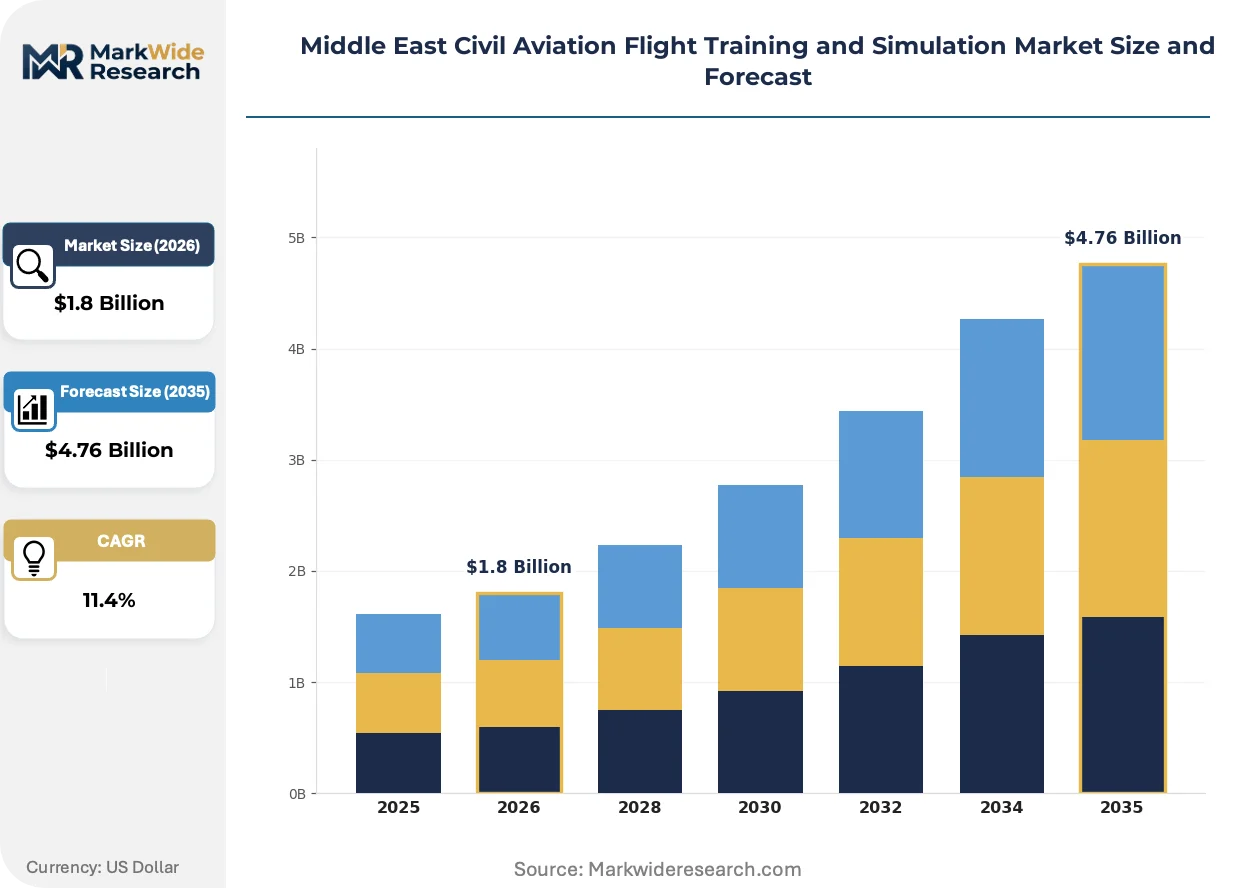
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Flight Simulator, Flight Training Devices, Cockpit Procedure Trainers, Aerial Work Platforms End User: Airline Operators, Military, Private Pilots, Flight Schools Technology: Virtual Reality, Augmented Reality, Motion-Based Systems, Fixed-Base Simulators Application: Commercial Aviation, Military Aviation, Recreational, Emergency Response |
| Companies Covered | Etihad Aviation Training, FlightSafety International, CAE Inc., Egyptair Training Academy, Thales Group, L3Harris Technologies, Turkish Airlines Flight Academy, TRU Simulation + Training, Emirates Flight Training Academy, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Civil Aviation Flight Training and Simulation Market Shifts & Advancements
Training technology architectures are pivoting from discrete device categories toward integrated ecosystems where virtual, mixed, and full-flight modalities share common software cores and data infrastructure.
Extended reality headsets with eye-tracking and haptic feedback gloves are consolidating procedural training previously handled by fixed-base simulators. Regional flight schools in the UAE and Saudi Arabia are adopting these configurations for instrument rating preparation, compressing the addressable market for entry-level FTDs while expanding total training throughput per dollar invested.
The UAE's General Civil Aviation Authority has tightened recurrent training hour requirements for multi-crew pilot license holders, effective across all AOC holders operating from Dubai and Abu Dhabi. This regulatory compression is forcing low-cost carriers to secure dedicated simulator blocks rather than relying on spot-market access, reshaping capacity planning at Etihad Aviation Training and third-party providers.
Airline procurement of training services is fragmenting from long-term bundled contracts toward modular subscriptions tied to specific fleet types and pilot seniority. This unbundling is most visible among Saudi carriers responding to GACA pressure for cost transparency, where finance departments now negotiate simulator hours separately from instructor provision and curriculum design.
Middle East Civil Aviation Flight Training and Simulation Market Segmentation
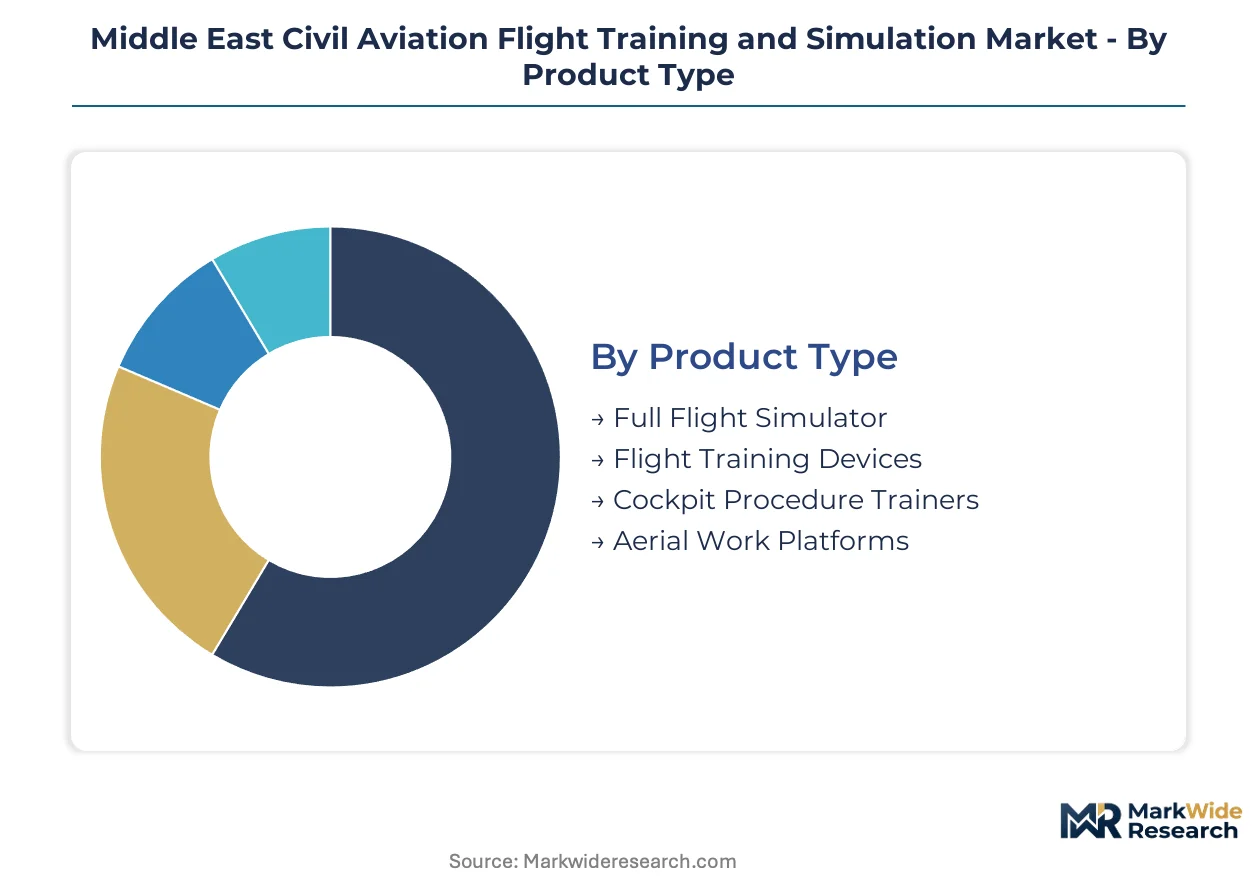
Segmentation in Middle East civil aviation flight training reveals distinct procurement patterns across device tiers and operator categories. Gulf carriers prioritize Level D certified platforms for wide-body fleets, while emerging academies balance cost constraints against regulatory compliance mandates from GCAA and GACA.
Product Type:
Capital intensity and certification grade drive purchasing decisions across the device hierarchy.
- Full Flight Simulator:Level D certified platforms replicate complete aircraft flight envelopes with six-degree-of-freedom motion bases and collimated visual systems. Emirates Flight Training Academy and Etihad Aviation Training anchor regional demand in the UAE as both carriers expand Boeing 777X and Airbus A350 fleets requiring type-specific configurations.
- Flight Training Devices:FTDs bridge procedural rehearsal and full-flight immersion without motion platforms, targeting instrument rating and systems familiarization. Saudi Arabia's indigenous academies under Vision 2030 localization mandates are expanding FTD procurement to reduce dependency on outsourced training blocks.
- Cockpit Procedure Trainers:Fixed-base units emphasize checklist execution and emergency drill repetition at entry-level price points.
- Aerial Work Platforms:Specialized configurations serve helicopter external load and search-and-rescue mission training for military and parapublic operators.
Full Flight Simulator leads on scale; Cockpit Procedure Trainers lead on momentum.
End User:
Training volume concentrates where fleet expansion and regulatory mandates intersect.
- Airline Operators:Flag carriers and low-cost airlines across the GCC account for the dominant share of simulator utilization, driven by recurrent training mandates and new-hire pipelines. Emirates, Etihad, and Saudia are expanding in-house academy capacity to secure dedicated device access rather than competing for spot-market slots.
- Military:Royal Saudi Air Force and UAE Air Force procurement emphasizes mission rehearsal and tactical flight training for fighter and transport platforms, with sovereign funding insulating this segment from commercial aviation cyclicality.
- Private Pilots:Recreational and business aviation operators generate steady demand for single-engine and light jet familiarization.
- Flight Schools:Ab initio academies in Dubai and Jeddah serve cadet pipelines for regional carriers, with enrollment climbing alongside GCC aviation hub expansion.
Airline Operators dominate absolute hours; Military contracts deliver longest tenors.
Technology:
Immersion fidelity and procurement cost trade-offs are restructuring the technology mix.
- Virtual Reality:Headset-based systems from Varjo and Pico are converging with traditional architectures, enabling procedural training at fraction of full-flight simulator capex. UAE flight schools are adopting VR configurations for instrument rating preparation, compressing addressable demand for entry-level FTDs.
- Motion-Based Systems:Hydraulic and electric motion bases remain essential for upset recovery and manual handling skill retention, though supply concentration in North American and European specialist vendors extends regional lead times.
- Augmented Reality:Overlay applications blend physical cockpit panels with synthetic external visuals for hybrid training scenarios.
- Fixed-Base Simulators:Non-motion platforms retain strong demand where motion cueing offers diminishing instructional returns, particularly in private pilot and recreational markets.
Motion-Based Systems anchor installed base value; Virtual Reality is climbing the fastest.
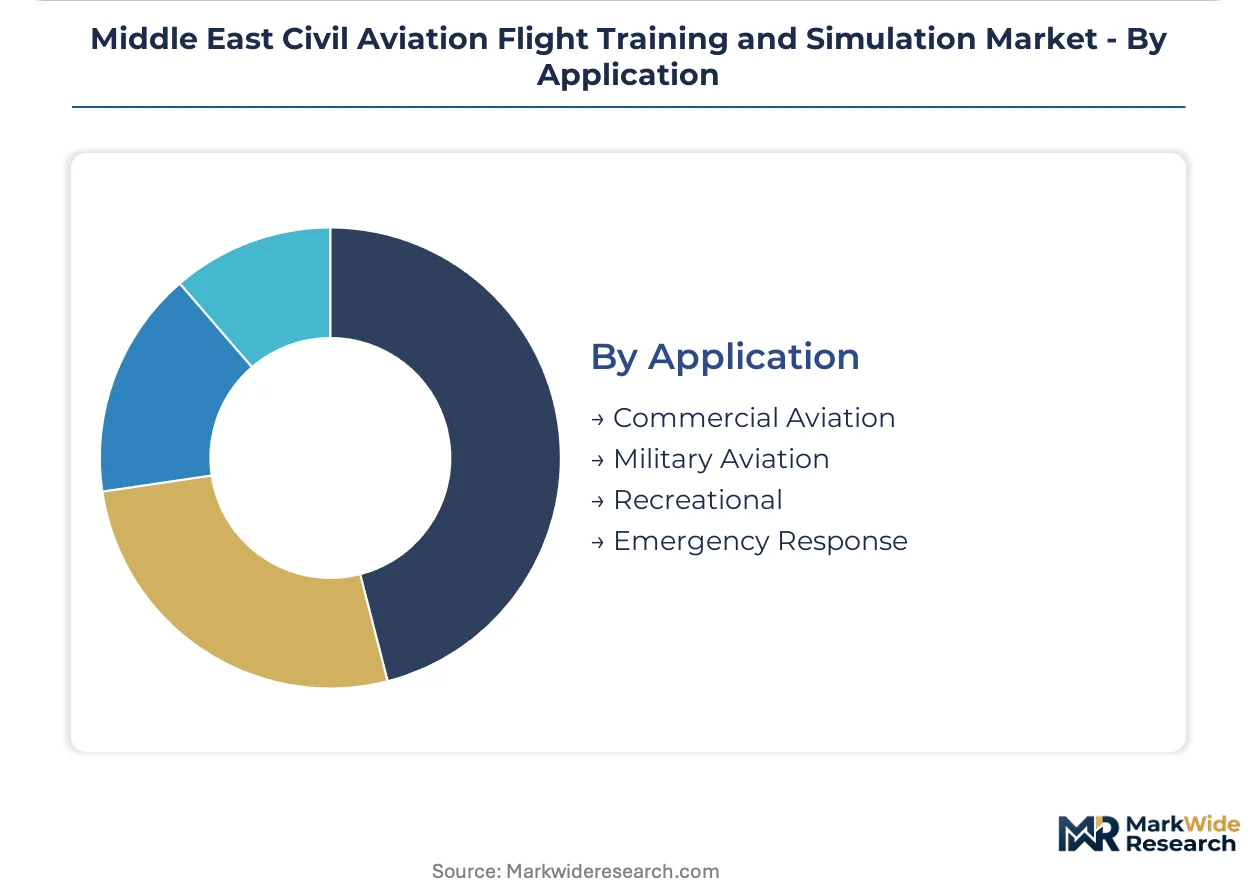
Application:
Regulatory scope and operational risk profiles determine device configuration requirements.
- Commercial Aviation:Multi-crew pilot license recurrent training mandates from GCAA and GACA compress certification timelines and expand synthetic training hours. Low-cost carriers in Saudi Arabia are securing dedicated simulator blocks under GACA pressure for cost transparency and operational control.
- Military Aviation:Combat mission rehearsal and tactical transport training require classified terrain databases and threat environment modeling, with procurement routed through defense ministry channels rather than civil aviation authorities.
- Recreational:Private pilot certificate preparation and instrument rating maintenance generate utilization at regional flight schools.
- Emergency Response:Search-and-rescue and firefighting mission training for parapublic operators demands helicopter-specific platforms with winch and hoist simulation.
Commercial Aviation leads on device utilization; Military Aviation leads on per-hour revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's aviation corridor concentrates the Middle East's flight training infrastructure through Emirates Flight Training Academy and Etihad Aviation Training, with sovereign investment redirecting capacity expansion toward Saudi Arabia's domestic academies under Vision 2030 mandates.
United Arab Emirates
Emirates and Etihad anchor device procurement for Boeing 777X and Airbus A350 fleet expansion. The General Civil Aviation Authority enforces ICAO Type VII recurrent training mandates across Dubai and Abu Dhabi AOC holders. Dubai South and Al Ain host the region's densest simulator clusters, with dedicated academy facilities co-located at operational hubs.
Saudi Arabia
Saudia's wide-body fleet growth and localization mandates under Vision 2030 are redirecting training expenditure toward indigenous academies. The General Authority of Civil Aviation compresses pilot certification timelines through synthetic training hour requirements. Riyadh and Jeddah host emerging simulator installations as joint ventures with established OEMs displace outsourced programs.
Qatar
Qatar Airways' narrow-body and wide-body fleet expansion generates demand for type-specific simulator configurations. The Qatar Civil Aviation Authority aligns licensing standards with ICAO frameworks while maintaining distinct validation protocols. Doha's aviation zone concentrates training infrastructure adjacent to Hamad International Airport operations.
Kuwait
Kuwait Airways' fleet modernization creates latent demand for synthetic training capacity currently met through regional spot-market access. The Directorate General of Civil Aviation maintains regulatory frameworks compatible with GCC harmonization initiatives. Kuwait City's underpenetrated training infrastructure offers positioning for first-mover academy development.
Egypt
Egyptair Training Academy serves domestic carrier requirements and regional export demand for ab initio programs. The Egyptian Civil Aviation Authority enforces pilot licensing standards with cross-recognition limitations affecting instructor mobility. Cairo concentrates the country's simulator installed base through sovereign carrier investment.
Middle East Civil Aviation Flight Training and Simulation Market Competitive Landscape
Strategic partnerships dominate the current landscape as sovereign carriers secure long-term training service agreements with established simulator OEMs. The market structures around three tiers: integrated academies owned by flag carriers, independent third-party providers, and OEM-affiliated training centers. Two archetypes anchor competitive positioning — vertically integrated airline academies and technology-licensed independent operators. M&A activity and capacity expansion constitute the dominant competitive moves, with carriers acquiring dedicated device access rather than competing for spot-market slots.
Within the integrated academy tier, Emirates Flight Training Academy and Etihad Aviation Training exemplify sovereign-carrier vertical integration into synthetic training infrastructure. CAE Inc. occupies a position as the established OEM-affiliated anchor through long-term service agreements with Gulf operators. These three entities represent the spectrum from captive airline provision to outsourced technology partnership that defines regional competitive dynamics.
| Leading Market Players |
|---|
| Etihad Aviation Training |
| FlightSafety International |
| CAE Inc. |
| Egyptair Training Academy |
| Thales Group |
| L3Harris Technologies |
| Turkish Airlines Flight Academy |
| TRU Simulation + Training |
| Emirates Flight Training Academy |
| Others |
Supply & Pricing Matrix
ICAO Type VII compliance mandates from the UAE's General Civil Aviation Authority and Saudi Arabia's General Authority of Civil Aviation gate both qualified simulator supply and premium-tier pricing access, as certification-grade devices command substantial premiums over uncertified alternatives while excluding non-compliant vendors from procurement shortlists.
Pricing Analysis
Direct-to-airline contract structures dominate, with long-term training service agreements replacing spot-market purchases as carriers seek dedicated device access. Three-tier pricing structure across Level D full-flight simulators, intermediate flight training devices, and entry-level cockpit procedure trainers reflects certification grade and motion platform complexity. Cost compression in FTD segments is intensifying because VR headset alternatives are displacing fixed-base units for ab initio instrument training. Low-cost carriers exhibit highest price sensitivity, while flag carriers prioritize availability guarantees over unit economics.
Supply Chain Analysis
Freight costs for motion platform components from North American and European specialist suppliers extend lead times and inflate landed costs for regional integrators. Hydraulic and electric motion base production concentrates in the United States, Germany, and Canada, while collimated display domes and LED image generators source primarily from Japanese and South Korean optical component manufacturers. Single-source dependencies on projection technology create vulnerability to supply disruption. Distribution runs through OEM-affiliated training centers, integrated airline academies, and independent third-party providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East civil aviation flight training and simulation market functions as a geographic-arbitrage play, with Saudi Arabia's localization mandates under Vision 2030 creating cost advantages for indigenous academies versus UAE-based training imports.
For Market Incumbents: Lock in long-term training service agreements with expanding Gulf carriers before spot-market alternatives erode pricing power. Secure exclusive motion platform supply allocations from North American and European vendors to constrain competitor capacity scaling. Deepen backward integration into simulator maintenance and avionics retrofitting capabilities to capture lifecycle revenue streams. For New Entrants and Emerging Players: Underserved low-cost carriers in Saudi Arabia present immediate white-space opportunity, as GACA cost-transparency mandates fragment procurement from bundled contracts toward modular subscriptions. Kuwait and Oman offer first-mover positioning with underpenetrated training infrastructure and expanding flag carrier fleets. License VR-based procedural training technology from established headset manufacturers to bypass Level D certification barriers. For Investors and Strategic Acquirers: Roll-up economics work for independent third-party training providers because regulatory fragmentation across GCAA, GACA, and Qatar Civil Aviation Authority validation protocols favors regional scale over global reach. Target mid-cap academies with established instructor pipelines and bilateral EASA cross-recognition agreements. Monitor GACA localization enforcement intensity as inflection indicator for Saudi market access shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Level D Certification Investment | GCAA validation enables premium pricing and exclusive airline contracts. |
| VR Module Integration | Varjo and Pico headset partnerships reduce ab initio training capex thresholds. |
| Indigenous Academy Joint Venture | Vision 2030 mandates redirect Saudi expenditure from UAE imports. |
| EASA Instructor Cross-Recognition | Bilateral agreements accelerate knowledge transfer without certification duplication. |
| Wide-Body Fleet Type-Specific Configuration | Boeing 777X and Airbus A350 simulators anchor Emirates and Etihad demand. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with flight training academy directors, GCAA and GACA regulatory affairs officers, airline fleet planning executives, and simulator OEM sales directors with secondary validation against ICAO training device standards, civil aviation authority regulatory filings, and carrier fleet expansion announcements. Bottom-up device installation counts and top-down training hour demand estimates were triangulated to anchor market sizing.
Segment-weighting approaches modeled value distribution across product type, end user, technology, and application dimensions throughout the forecast period. CAGRs were derived from regression analysis against fleet expansion schedules and regulatory mandate implementation timelines. Type-specific simulator demand was cross-referenced against Boeing and Airbus delivery forecasts for the region.
Inputs from GCAA and GACA regulatory filings were available through the study window; gaps in proprietary airline training expenditure data introduce uncertainty bands around low-cost carrier segment estimates. Forecasts reflect assumptions regarding Vision 2030 localization enforcement and EASA cross-recognition continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Simulation and Training
Military Simulation Virtual Training Market
Simulation and Training
Global Military Airborne Simulation and Training Market
Simulation and Training
Police and Military Simulation Training Market
Simulation and Training
Military Simulation and Training Market
Simulation and Training
Civil Aerospace Simulation and Training Market
Simulation and Training
Flight Simulation Training Device Market
Simulation and Training
Military Training Aircraft Market
Simulation and Training
Military Simulation Software Market
Simulation and Training
Europe Flight Training and Simulation Market
Simulation and Training
Drone Simulator Market
Simulation and Training
Civil Aviation Simulator Market
Simulation and Training
Military Aerospace Simulation and Training Market
Simulation and Training
Europe Ship Bridge Simulators Market
Simulation and Training
UAV Flight Training and Simulation Market
Simulation and Training
GNSS Simulators Market
Simulation and Training
RADAR Simulator Market