
 Police and Military Simulation Training Market | 2026-2036
Police and Military Simulation Training Market Size, Share, and Industry Trends Forecast 2026-2036
Police and Military Simulation Training Market Analytics
High-fidelity combined arms simulation is redrawing procurement priorities across defense ministries and federal law enforcement agencies. Lockheed Martin Corporation leverages its integrated warfare systems heritage to anchor large-scale military training contracts across multiple continents. Thales Group competes through specialized virtual reality platforms that dominate European tactical training installations. L3Harris Technologies, Inc. differentiates via proprietary data analytics layers that extend scenario replay and performance benchmarking capabilities for special operations units.
Police and military simulation training encompasses synthetic environments that replicate combat, emergency response, and tactical law enforcement scenarios through immersive hardware and software architectures, typically employing motion platforms, ballistics calculators, and networked multi-participant protocols to deliver repeatable, measurable skill development without live ammunition expenditure. Virtual reality and artificial intelligence segments command disproportionate R&D investment as defense agencies prioritize adaptive enemy behavioral modeling and reduced logistical footprints. Live fire maintains entrenched demand for terminal ballistic validation, though margin pools increasingly shift toward software-defined scenario libraries and cloud-deployable training modules.
Federal procurement regulations under the US Federal Acquisition Regulation, NATO standardization agreements for interoperability, and the EU AI Act's risk-classification framework for autonomous training systems collectively shape product certification pathways and cross-border sales eligibility. The US FAA and military airworthiness boards additionally govern aviation-linked simulation hardware, constraining design choices for vendors serving joint-force customers. Stakeholders must monitor evolving classification standards for AI-generated training content and alignment with emerging cybersecurity mandates for networked defense infrastructure.
Market Dynamics
Artificial intelligence-driven adaptive scenario generation is restructuring procurement priorities across defense ministries and federal law enforcement agencies, compressing development cycles for synthetic training curricula while elevating software vendors above legacy hardware suppliers.
Growth Catalysts
- NATO Standardization Agreements:Interoperability mandates for combined arms simulation suites accelerate cross-border procurement and reduce vendor lock-in across member state defense ministries.
- Live-Fire Cost Escalation:Ballistics validation exercises consume finite training budgets, pushing military organizations toward repeatable synthetic alternatives with measurable skill retention metrics.
- Cloud-Deployable Training Modules:Reduced logistical footprints enable distributed special operations preparation without centralized facility dependency.
Market Restraints
- Motion Platform Supply Concentration:High-fidelity hardware fabrication clusters in Germany and the United States, creating single-source vulnerability for international customers.
- EU AI Act Risk Classification:Autonomous training systems face elevated compliance scrutiny, extending certification timelines for adaptive enemy behavioral modeling.
- Terminal Ballistic Validation Requirements:Live ammunition retains entrenched demand for terminal effects confirmation, limiting pure synthetic substitution in certain curriculum segments.
Strategic Opportunities
- Australian Defense Modernization:Synthetic training environment prioritization in Canberra's procurement pipeline creates white space for scenario library vendors.
- Extended Reality Convergence:Virtual reality platforms integrating haptic feedback systems open new installation categories for urban tactical training.
- Federal Acquisition Regulation Streamlining:US defense procurement pathway reforms accelerate vendor onboarding for mid-tier simulation specialists.
Industry Challenges
- AI-Generated Content Classification:Emerging cybersecurity mandates for networked defense infrastructure create compliance ambiguity around synthetic scenario provenance.
- Legacy System Integration:Motion platform architectures from prior decades resist seamless interoperability with modern data analytics layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Police and Military Simulation Training Market |
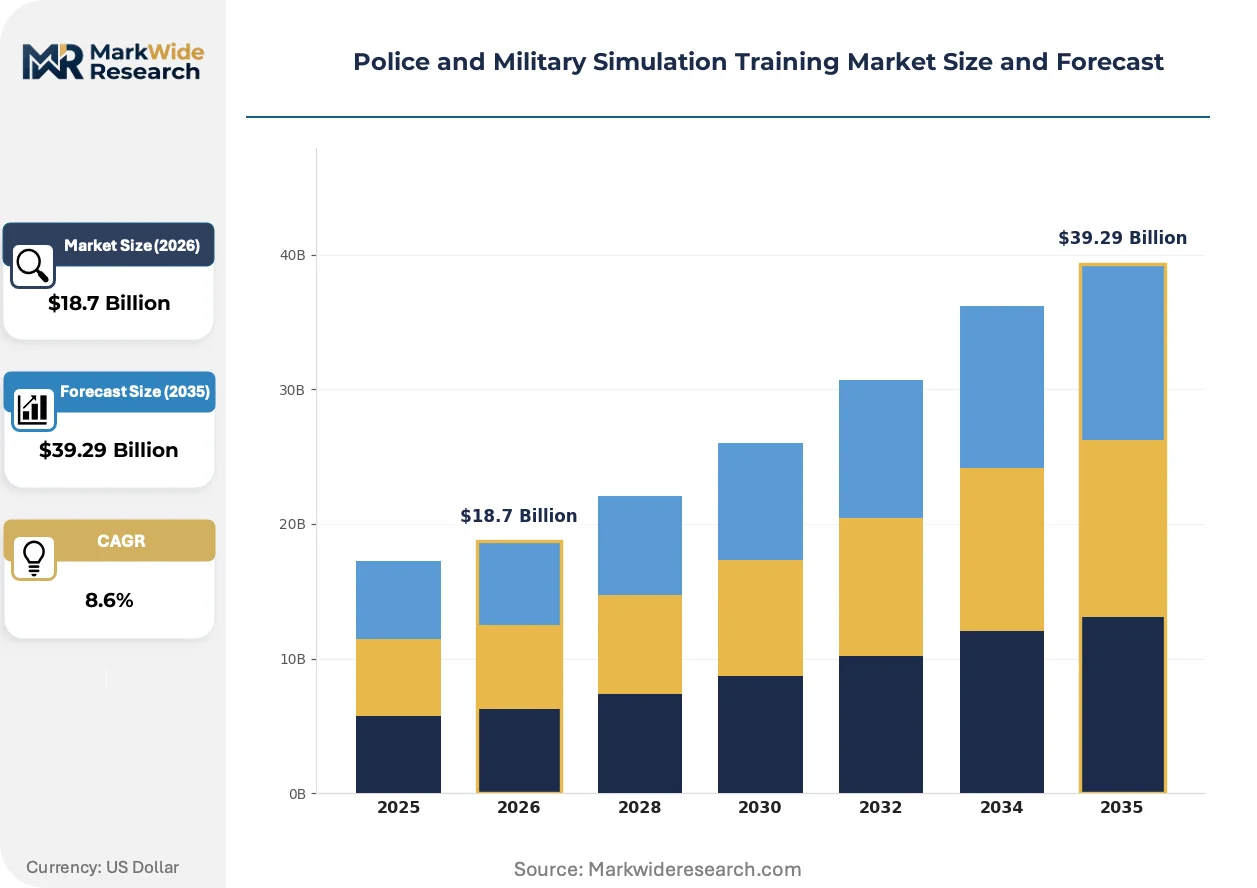
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Training Type: Virtual Reality, Live Fire, Combined Arms, Tabletop Exercises Technology: Artificial Intelligence, Augmented Reality, Scenario Simulation, Data Analytics End User: Law Enforcement Agencies, Military Organizations, Private Security Firms, Educational Institutions Application: Tactical Training, Emergency Response, Crowd Control, Marksmanship |
| Companies Covered | Northrop Grumman Corporation, Thales Group, Lockheed Martin Corporation, Cubic Corporation, BAE Systems plc, CAE Inc., L3Harris Technologies, Inc., FAAC Incorporated, Raytheon Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Police and Military Simulation Training Market Evolving Landscape
Software-defined scenario libraries are displacing hardware-centric training architectures, compressing margin pools toward cloud-deployable modules while motion platforms commoditize.
Generative adversarial networks for adaptive enemy behavioral modeling are decomposing static curriculum design. Special operations units across NATO member states pilot these systems for irregular warfare preparation. The technology is decomposing traditional scenario development timelines from months to days.
The EU AI Act's risk-classification framework for autonomous training systems imposes documentation burdens on vendors deploying machine learning in tactical simulations. German and French defense ministries now require algorithmic transparency attestations for procurement eligibility. Simulation vendors respond by segregating AI-driven and rule-based product lines to manage compliance exposure.
Subscription-based scenario library access supersedes perpetual license models among federal law enforcement agencies. Training coordinators purchase modular content packs rather than comprehensive platform overhauls. This pattern concentrates in the United States where FBI and Homeland Security procurement flexibility exceeds military acquisition rigidity.
Police and Military Simulation Training Market Segmentation
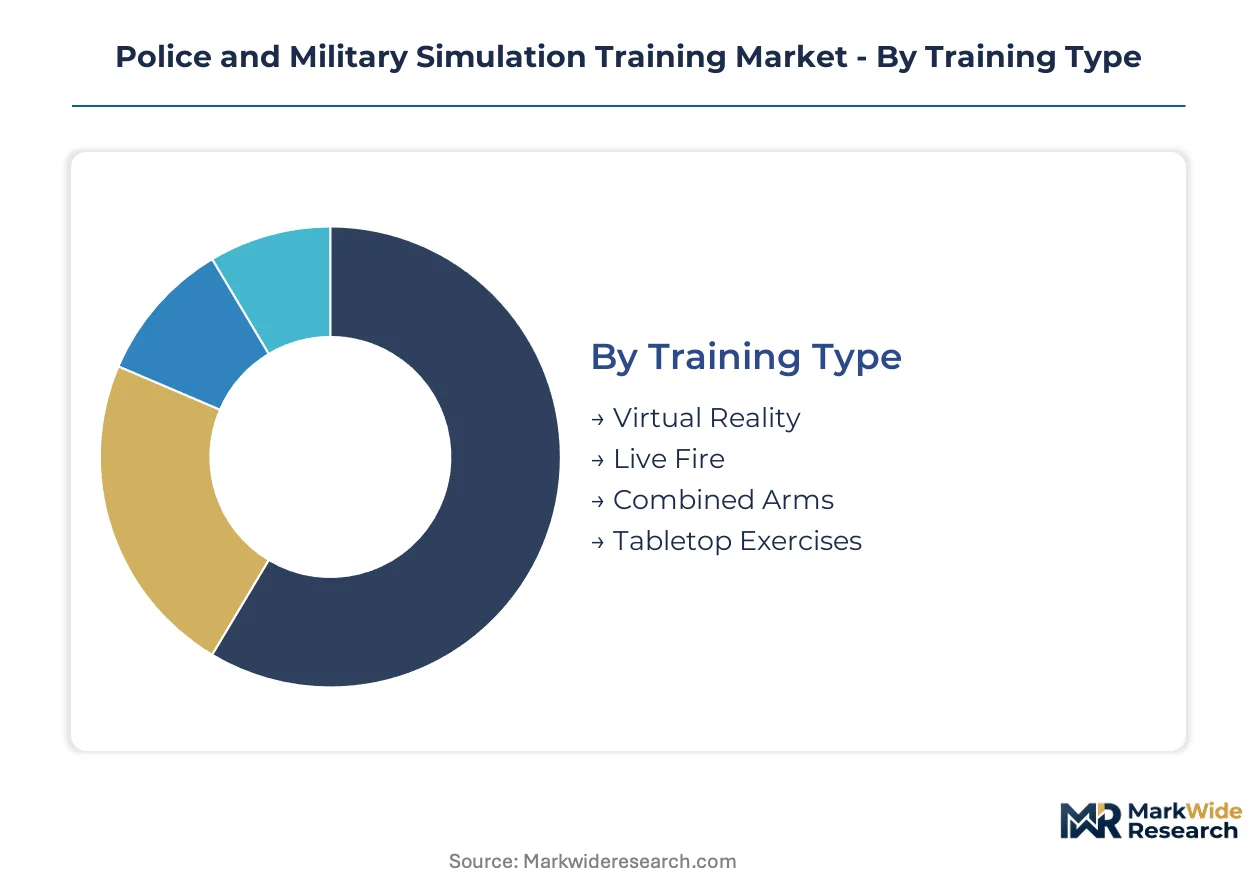
Segmentation in police and military simulation training reveals divergent procurement pathways shaped by regulatory classification, operational tempo, and budget authority. Defense ministries prioritize combined arms architectures with NATO interoperability certification, while federal law enforcement agencies favor modular acquisitions that bypass military acquisition rigidity.
Training Type:
EU AI Act risk tiers classify autonomous training systems differently across synthetic and live modalities, with high-fidelity virtual environments facing elevated documentation burdens for algorithmic transparency.
- Virtual Reality:Head-mounted displays with six-degrees-of-freedom tracking and haptic feedback systems replicate urban combat geometries. Demand concentrates in German tactical training installations where the KBA certifies motion platform safety for federal police academies, constrained by EU AI Act documentation requirements for adaptive scenario generation.
- Live Fire:Ballistics validation ranges with instrumented targets and acoustic shot detection maintain terminal effects confirmation protocols. Military organizations across Australia retain entrenched procurement for special operations marksmanship certification despite synthetic alternatives, driven by TGA-equivalent defense materiel safety mandates.
- Combined Arms:Networked suites integrating armor, aviation, and infantry simulation protocols for joint-force coordination.
- Tabletop Exercises:Map-based strategic wargaming for command-level decision rehearsal without hardware dependency.
Combined Arms handles the majority of throughput; Virtual Reality is expanding most quickly on share.
Technology:
Cost tier differentiation separates enterprise-grade AI platforms from rule-based scenario engines, with procurement budgets stratifying across defense ministry and municipal police authority levels.
- Artificial Intelligence:Generative adversarial networks produce adaptive enemy behavioral models that compress curriculum development timelines. French defense procurement now requires algorithmic transparency attestations from vendors deploying machine learning in tactical simulations, segregating product lines to manage compliance exposure.
- Data Analytics:Proprietary performance benchmarking layers capture biometric stress indicators and decision latency metrics for after-action review. Special operations units across the United States prioritize these capabilities for measurable skill retention validation under Federal Acquisition Regulation streamlining initiatives.
- Augmented Reality:Optical see-through displays overlay tactical symbology on physical training environments.
- Scenario Simulation:Rule-based event sequencing engines without machine learning components for reduced regulatory burden.
Data Analytics captures the highest margin pool; Artificial Intelligence is gaining share fastest.
End User:
Customer type determines contract structure, with military organizations favoring multi-year platform acquisitions and private security firms purchasing subscription-based scenario library access.
- Military Organizations:Combined arms simulation suites with NATO standardization agreement compliance for cross-border interoperability. Procurement concentrates in the United States, Germany, and Australia where defense modernization budgets prioritize synthetic training environments over live-fire cost escalation.
- Law Enforcement Agencies:Modular virtual reality installations for urban tactical training and de-escalation protocols. FBI and Homeland Security procurement flexibility in the United States exceeds military acquisition rigidity, enabling subscription-based scenario library purchases rather than comprehensive platform overhauls.
- Private Security Firms:Commercial off-the-shelf packages with reduced certification requirements for executive protection training.
- Educational Institutions:Entry-level simulation platforms for criminal justice and military science curricula.
Military Organizations command the largest contract values; Law Enforcement Agencies show the steepest expansion trajectory.
Application:
Volume concentration aligns with operational frequency, with tactical training consuming the majority of simulation hours across both defense and law enforcement contexts.
- Tactical Training:Close-quarters battle simulation with dynamic entry protocols and room-clearing procedures. Urban warfare preparation across NATO member states drives demand for extended reality convergence with haptic feedback systems.
- Emergency Response:Multi-casualty incident command and hazardous materials response coordination.
- Crowd Control:Public order management simulation with kinetic and non-kinetic option deployment.
- Marksmanship:Precision shooting fundamentals with ballistics calculators and windage compensation algorithms.
Tactical Training absorbs the majority of platform utilization; Emergency Response is climbing the fastest on procurement priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Simulation hardware fabrication clusters in Germany and the United States concentrate supply-side capacity for motion platforms and networked training architectures. Defense procurement pipelines in Australia, Canada, and the United Kingdom are accelerating synthetic environment adoption to contain live-fire expenditure escalation. Regulatory frameworks across NATO jurisdictions impose divergent certification burdens on adaptive scenario generation systems.
United States
The Pentagon's combined arms modernization prioritizes cloud-deployable training modules for distributed special operations preparation. Federal Acquisition Regulation streamlining accelerates vendor onboarding for mid-tier simulation specialists seeking military contracts. Lockheed Martin Corporation anchors large-scale training system deployment from its integrated warfare systems heritage across multiple continents.
Germany
The KBA certifies motion platform safety for federal police academies operating high-fidelity virtual reality installations. EU AI Act documentation requirements for adaptive scenario generation extend certification timelines for algorithmic transparency attestations. Thales Group competes through specialized virtual reality platforms dominating European tactical training installations.
Australia
Canberra's defense procurement pipeline prioritizes synthetic training environment acquisition over live-fire range maintenance. TGA-equivalent defense materiel safety mandates retain entrenched demand for terminal ballistic validation in special operations marksmanship certification. Scenario library vendors find white space in Australian modernization budgets seeking reduced logistical footprints.
United Kingdom
BAE Systems plc leverages domestic defense industrial base relationships for NATO interoperability-certified simulation suite delivery. UK Ministry of Defence standardization agreements accelerate cross-border procurement with reduced vendor lock-in. British special operations units pilot generative adversarial networks for irregular warfare preparation with compressed curriculum development timelines.
Canada
CAE Inc. anchors aviation-linked simulation hardware supply serving joint-force customers under FAA and military airworthiness board governance. Canadian defense procurement flexibility enables subscription-based scenario library access for federal law enforcement coordination. North American motion platform supply concentration creates single-source vulnerability for international customers seeking hardware fabrication alternatives.
Police and Military Simulation Training Market Competitive Landscape
Concentration sits with integrated defense conglomerates possessing multi-decade military contracting relationships and proprietary data analytics layers. The vendor base stratifies across three tiers: prime contractors delivering combined arms architectures, specialized virtual reality platform developers, and mid-tier scenario library vendors. Strategic moves center on M&A for AI-driven adaptive generation capabilities and strategic partnerships for NATO interoperability certification.
Within the prime contractor tier, Lockheed Martin Corporation, Thales Group, and L3Harris Technologies, Inc. represent distinct competitive archetypes. Lockheed Martin anchors large-scale military training contracts through integrated warfare systems heritage. Thales exemplifies European virtual reality specialization for tactical training installations. L3Harris occupies a position emphasizing proprietary data analytics layers for special operations performance benchmarking. These three entities collectively illustrate how vendor differentiation converges on software-defined scenario libraries while motion platforms commoditize.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| Thales Group |
| Lockheed Martin Corporation |
| Cubic Corporation |
| BAE Systems plc |
| CAE Inc. |
| L3Harris Technologies, Inc. |
| FAAC Incorporated |
| Raytheon Technologies Corporation |
| Others |
Value Network & Pricing Analysis
Ninety-day certification timelines for EU AI Act algorithmic transparency attestations compress procurement cycles and concentrate pricing power with vendors possessing pre-cleared adaptive scenario generation platforms. This lead-time compression rewards German and United States-based incumbents while elevating compliance documentation as a cost component that stratifies contract values across NATO defense ministries and federal law enforcement agencies.
Pricing Analysis
The EU AI Act dictates the pricing tier structure for autonomous training systems, segregating vendors into algorithmic-transparency-certified and rule-based product lines. Three-tier pricing structure across premium, standard, and economy levels separates NATO interoperability-certified combined arms suites from modular virtual reality installations and commercial off-the-shelf packages. Cost compression in mid-tier scenario library subscriptions is intensifying because FBI and Homeland Security procurement flexibility enables modular content pack purchases rather than comprehensive platform overhauls. Municipal police authorities exhibit highest price sensitivity; special operations units within defense ministries demonstrate lowest sensitivity due to measurable skill retention validation requirements.
Supply Chain Analysis
Motion platform fabrication lead-times extending sixteen weeks from German and United States suppliers create inventory buffers that downstream vendors must carry for NATO interoperability certification deadlines. High-fidelity hardware production concentrates in Germany and the United States, while scenario software development clusters in France and Australia. Supply chains draw from precision motion control actuators, ballistic calculation engines, and networked multi-participant protocol licenses. Single-source vulnerability pervades international customer procurement for motion platform alternatives. Distribution runs through defense ministry procurement offices and federal law enforcement acquisition channels with divergent contract structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Police and military simulation training sits in early-cycle expansion as cloud-deployable training modules penetrate special operations preparation workflows previously dependent on centralized facility infrastructure. NATO standardization agreement mandates for cross-border interoperability accelerate vendor onboarding velocity beyond traditional defense procurement timelines.
For Market Incumbents: Shield proprietary data analytics layers through backward integration into biometric stress indicator capture hardware and algorithmic transparency documentation services. Incumbent vendors face emerging threat from mid-tier scenario library specialists leveraging Federal Acquisition Regulation streamlining to bypass multi-decade military contracting relationships. Priority lever rests on segregating AI-driven and rule-based product lines to manage EU AI Act compliance exposure without contaminating premium-tier certification pathways.
For New Entrants and Emerging Players: Differentiate on adaptive enemy behavioral modeling speed for Australian defense modernization procurement, where Canberra's synthetic training environment prioritization creates white space absent entrenched vendor relationships. Most penetrable segment spans subscription-based scenario library access for federal law enforcement agencies purchasing modular content packs rather than comprehensive platform overhauls. Go-to-market angle emphasizes compressed curriculum development timelines from months to days using generative adversarial network pilot programs with British special operations units.
For Investors and Strategic Acquirers: Long-term, this sits as a defense software consolidation play because margin pools are compressing toward cloud-deployable modules while motion platforms commoditize. Acquisition target archetype encompasses mid-tier scenario library vendors possessing NATO interoperability certification and algorithmic transparency pre-clearance under EU AI Act risk tiers. Signal to watch is Federal Acquisition Regulation streamlining initiative expansion enabling vendor onboarding velocity acceleration for simulation specialists previously excluded from prime contractor relationships.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Adaptive Scenario Generation | Generative adversarial networks compress curriculum development timelines from months to days for NATO special operations preparation. |
| Cloud-Deployable Training Module Development | Distributed preparation eliminates centralized facility dependency for Australian and United States special operations units. |
| NATO Interoperability Certification Investment | Standardization agreement compliance accelerates cross-border procurement across German, United Kingdom, and Canadian defense ministries. |
| EU AI Act Algorithmic Transparency Pre-Clearance | Documentation attestation segregation enables premium-tier pricing for machine learning-driven tactical simulation platforms. |
| Subscription-Based Scenario Library Access | FBI and Homeland Security procurement flexibility exceeds military acquisition rigidity for modular content pack monetization. |
Research Methodology
Initial hypotheses were tested against primary input from defense procurement officers, simulation platform engineers, federal law enforcement training coordinators, and special operations curriculum designers and refined through secondary validation. Defense ministry budget documentation, NATO standardization agreement filings, Federal Acquisition Regulation procurement records, and EU AI Act implementation guidance provided foundational secondary data. Bottom-up triangulation across vendor revenue segmentation and top-down cross-check against defense modernization budget allocations anchored market size estimates.
Variance decomposition across training type, technology tier, end-user category, and application intensity shaped analytical framework construction over the projection horizon. Segmentation dimensions modeled encompass synthetic versus live modalities, AI-driven versus rule-based scenario engines, military organization versus law enforcement versus private security customer types, and tactical training versus emergency response utilization patterns. CAGRs derived from historical procurement velocity analysis adjusted for regulatory timeline compression effects and cloud-deployment adoption curve inflection points.
Forecasts assume regulatory continuity in EU AI Act risk-classification enforcement and Federal Acquisition Regulation streamlining initiatives; material policy shifts would require re-modeling adoption curve assumptions. Scenario library vendor consolidation velocity and motion platform supply concentration disruption represent primary revision triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Simulation and Training
RADAR Simulator Market
Simulation and Training
Military Simulation and Training Market
Simulation and Training
Trainer Aircraft Market
Simulation and Training
Global Military Airborne Simulation and Training Market
Simulation and Training
Civil Aerospace Simulation and Training Market
Simulation and Training
Europe Ship Bridge Simulators Market
Simulation and Training
Drone Simulator Market
Simulation and Training
Military Simulation Software Market
Simulation and Training
Satellite Simulator Market
Simulation and Training
Civil Aviation Simulator Market
Simulation and Training
Military Aerospace Simulation and Training Market
Simulation and Training
Military Training Aircraft Market
Simulation and Training
Flight Simulation Training Device Market
Simulation and Training
North America Simulator Windows and Simulator Skylights Market
Simulation and Training
Dynamic Flight Training Compartments Market
Simulation and Training
Middle East and Africa Ship Bridge Simulators Market