
 Trainer Aircraft Market | 2026-2036
Trainer Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Trainer Aircraft Market Outlook
Glass cockpit integration is tilting trainer aircraft design toward digital avionics architectures that reduce pilot transition time to frontline fighters. Leonardo SpA leverages its M-346 platform to anchor European advanced jet training programs with integrated synthetic mission systems. Boeing sustains its position through the T-7A Red Hawk program, competing for the largest Western military trainer contract. Pilatus Aircraft Ltd specializes in turboprop basic trainers, dominating the PC-21 niche with a glass cockpit standard that bridges civil and military flight schools.
A trainer aircraft is a fixed-wing platform designed for pilot instruction, typically featuring dual controls, enhanced stall characteristics, and ejection seats in military variants, with powerplants ranging from piston engines to afterburning turbofans depending on the training phase. Its primary purpose is to develop flight competencies from ab initio instruction through lead-in fighter training before operational aircraft assignment. Jet trainer configurations capture the highest value per unit within the product type dimension, reflecting the cost concentration in advanced systems with radar and weapons simulation. Glass cockpit technology leads the technology dimension as flight schools and air forces standardize on avionics that mirror operational fleet interfaces.
The FAA, EASA, and military airworthiness divisions of NATO member defense ministries collectively shape trainer certification requirements, with Part 23/CS-23 standards governing civil platforms and military type certification driving combat-relevant specifications. These frameworks determine avionics upgrade pathways, airframe life extension limits, and export licensing conditions that constrain fleet refresh timelines. Stakeholders must monitor how electric propulsion certification standards evolve, as this technology dimension could disrupt conventional and turbofan trainer segments if regulators establish clear airworthiness pathways for battery-powered instruction platforms.
Market Dynamics
The trainer aircraft market pivots on glass cockpit mandates from the FAA and EASA that force fleet-wide avionics refreshes, compressing procurement cycles for legacy platforms while accelerating next-generation trainer development.
Growth Catalysts
- FAA Part 23 Modernization:Updated certification standards for glass cockpit systems are compelling flight schools and military training commands to replace analog instrumentation fleets.
- Lead-in Fighter Training Demand:NATO air forces are expanding advanced jet training pipelines to bridge pilot shortages during frontline fighter fleet transitions.
- Synthetic Mission Systems:Embedded simulation technology is reducing live-flight training hours while maintaining operational readiness metrics.
Market Restraints
- Turbofan Engine Supply Concentration:A handful of specialized propulsion suppliers control afterburning trainer engine production, creating delivery bottlenecks for advanced jet programs.
- Military Type Certification Friction:Divergent airworthiness standards across NATO member defense ministries extend platform qualification timelines and raise non-recurring engineering costs.
- Civil-Defense Budget Competition:National fiscal pressures in key procurement markets are forcing trade-offs between trainer fleet expansion and operational combat aircraft acquisition.
Strategic Opportunities
- Electric Propulsion Certification Pathways:Emerging battery-powered trainer segments await regulatory clarity from the FAA and EASA on airworthiness standards for ab initio instruction platforms.
- Integrated Live-Virtual-Constructive Training:Convergence of physical aircraft with synthetic environments is opening service-based revenue models beyond hardware sales.
- Southeast Asian Fleet Expansion:Underpenetrated air forces in Indonesia, Vietnam, and Thailand are modernizing training infrastructure with Western and Russian platform evaluations underway.
Industry Challenges
- Glass Cockpit Integration Complexity:Retrofitting legacy airframes with digital avionics architectures demands specialized engineering talent that remains scarce across the aerospace supply base.
- Dual-Use Export Licensing Delays:ITAR and EU dual-use regulations create procurement uncertainty for trainer platforms with weapons simulation capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trainer Aircraft Market |
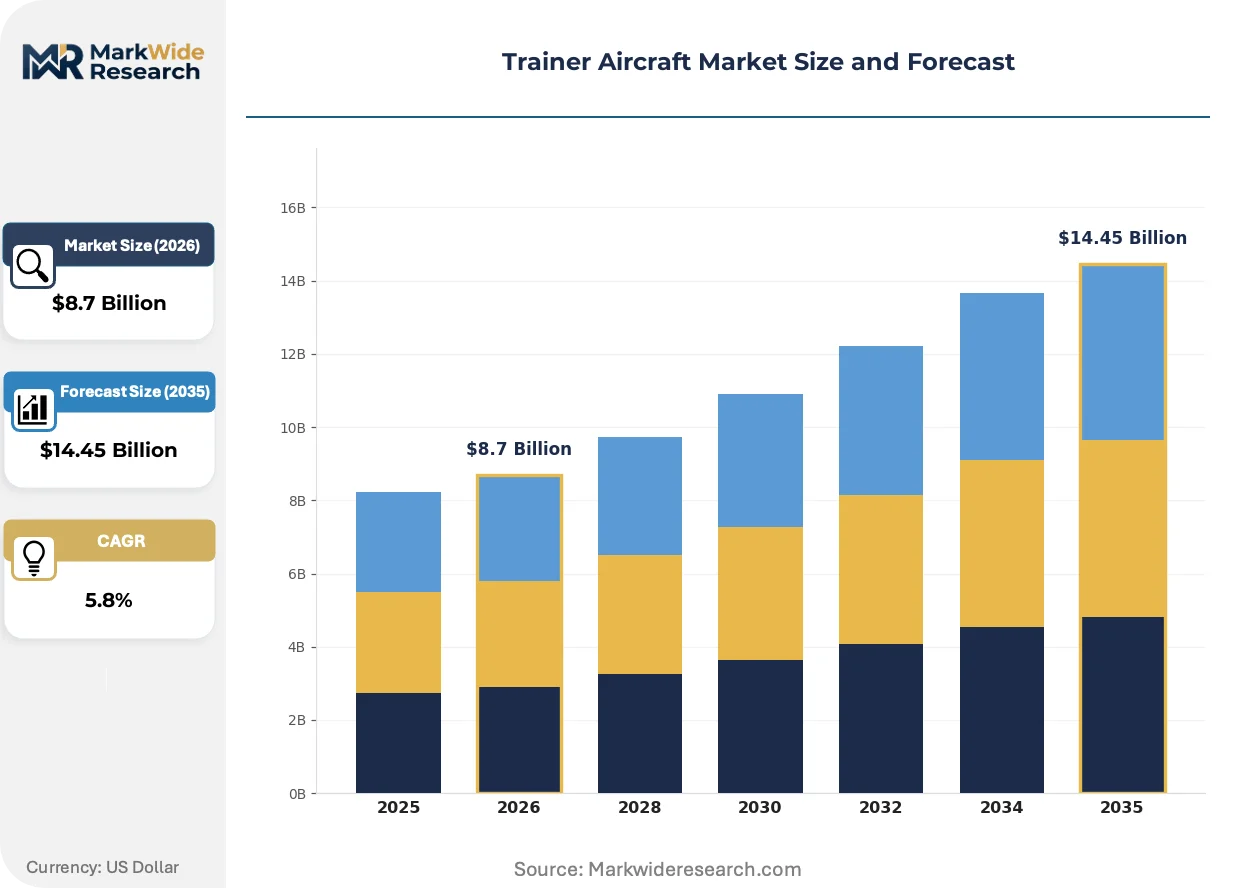
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Basic Trainer, Intermediate Trainer, Advanced Trainer, Jet Trainer End User: Military, Civil Aviation, Flight Schools, Private Owners Technology: Conventional, Glass Cockpit, Fly-by-Wire, Electric Usage: Pilot Training, Aircraft Familiarization, Aerobatics, Airshow Demonstrations |
| Companies Covered | Leonardo SpA, Pilatus Aircraft Ltd, The Boeing Company, Embraer SA, BAE Systems PLC, Textron Inc., Hindustan Aeronautics Ltd, Rostec, Airbus SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trainer Aircraft Market Strategic Shifts
Digital avionics architectures are compressing the traditional boundaries between basic, advanced, and lead-in fighter training phases, enabling platform consolidation and reshaping supplier value capture.
Embedded training systems is hybridizing physical aircraft with high-fidelity simulation environments. Military training commands across NATO are adopting these architectures to reduce live-flight hour costs while maintaining pilot proficiency. The technology is hybridizing hardware procurement models toward integrated system-of-systems contracts that bundle airframes with synthetic training infrastructure.
EASA's CS-23 certification framework for light aircraft is accelerating avionics modernization mandates across European flight schools. The regulation forces replacement of analog instrumentation with integrated digital displays by specified compliance deadlines. Basic trainer segments in Germany, France, and Italy are responding with accelerated fleet refresh programs that favor platforms with civil-military dual certification.
Performance-based training contracts are displacing traditional aircraft ownership models in several defense procurement frameworks. Air forces in Australia and Canada are piloting service-based arrangements where contractors provide training capacity rather than delivered hardware. This shift concentrates supplier risk while transferring fleet management complexity to original equipment manufacturers.
Trainer Aircraft Market Segmentation
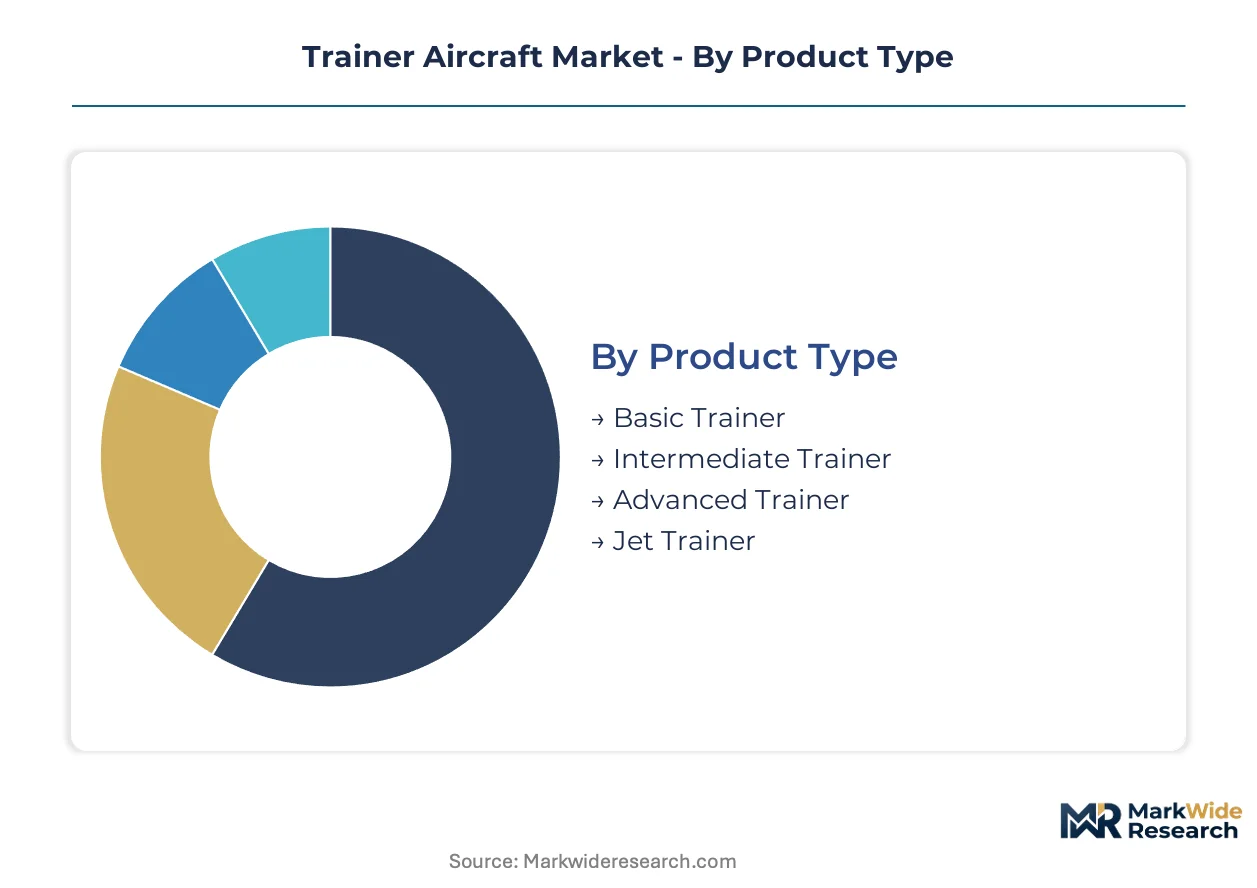
Trainer aircraft segmentation reveals how procurement priorities diverge across military training hierarchies and civil aviation pathways. Understanding these dimensional splits clarifies where platform investments concentrate and which technology transitions reshape fleet planning.
Product Type:
Cost tiers within trainer aircraft stratify sharply, with propulsion sophistication and avionics integration driving unit economics across the training pipeline.
- Jet Trainer:Afterburning turbofan platforms integrate radar simulation and weapons systems replication for lead-in fighter training. NATO air forces in the United States and United Kingdom are consolidating advanced phase procurement around these configurations as frontline fleets transition to fifth-generation fighters.
- Advanced Trainer:High-subsonic turbofan designs bridge basic instruction and operational conversion, typically featuring glass cockpit architectures matched to frontline fighter interfaces. Demand concentrates in European military procurement frameworks where the M-346 and Hawk platforms compete.
- Intermediate Trainer:Turboprop platforms with pressurized cabins and ejection seats serve military basic-advanced transition phases.
- Basic Trainer:Piston or turboprop platforms emphasize stall recovery, spin training, and fundamental instrument procedures.
Jet trainers command the established revenue base. The steepest expansion runs through advanced trainer platforms as air forces compress training phase transitions.
End User:
Customer type determines certification requirements, financing mechanisms, and fleet scale, with military procurement cycles dominating volume planning.
- Military:National air forces and naval aviation commands operate the largest consolidated fleets, with procurement tied to defense budget cycles and alliance standardization mandates. The United States Air Force T-7A program exemplifies multi-decade, multi-billion-dollar training system acquisitions that reshape supplier competitive positioning.
- Flight Schools:Commercial pilot certification academies operate high-utilization fleets governed by FAA Part 141 and EASA ATO standards, with glass cockpit mandates forcing accelerated refresh timelines.
- Civil Aviation:Corporate flight departments and airline training centers acquire platforms for type rating and recurrent training.
- Private Owners:Individual operators and aerobatic competitors purchase lower-complexity platforms for recreational or competitive use.
Military end users anchor fleet volumes. Flight schools are gaining share fastest as commercial pilot demand outpaces military pipeline expansion.
Technology:
Avionics maturity levels segment trainer platforms by pilot interface standardization and regulatory compliance burden.
- Glass Cockpit:Integrated digital flight displays with synthetic vision, moving maps, and engine monitoring replace analog instrumentation. FAA Part 23 modernization and EASA CS-23 mandates are compelling fleet-wide adoption across civil and military basic training segments.
- Conventional:Steam gauge instrumentation persists in legacy military fleets and cost-constrained flight schools, though regulatory sunset provisions are accelerating phase-out.
- Fly-by-Wire:Digital flight control systems replicate frontline fighter handling qualities, concentrating in advanced and jet trainer categories.
- Electric:Battery-powered propulsion awaits certification pathway clarity from the FAA and EASA for ab initio instruction platforms.
Glass cockpit technology dominates new procurement. Electric propulsion holds the steepest potential trajectory pending airworthiness standard finalization.
Usage:
Application purpose shapes platform specification, with mission system integration requirements varying across training objectives.
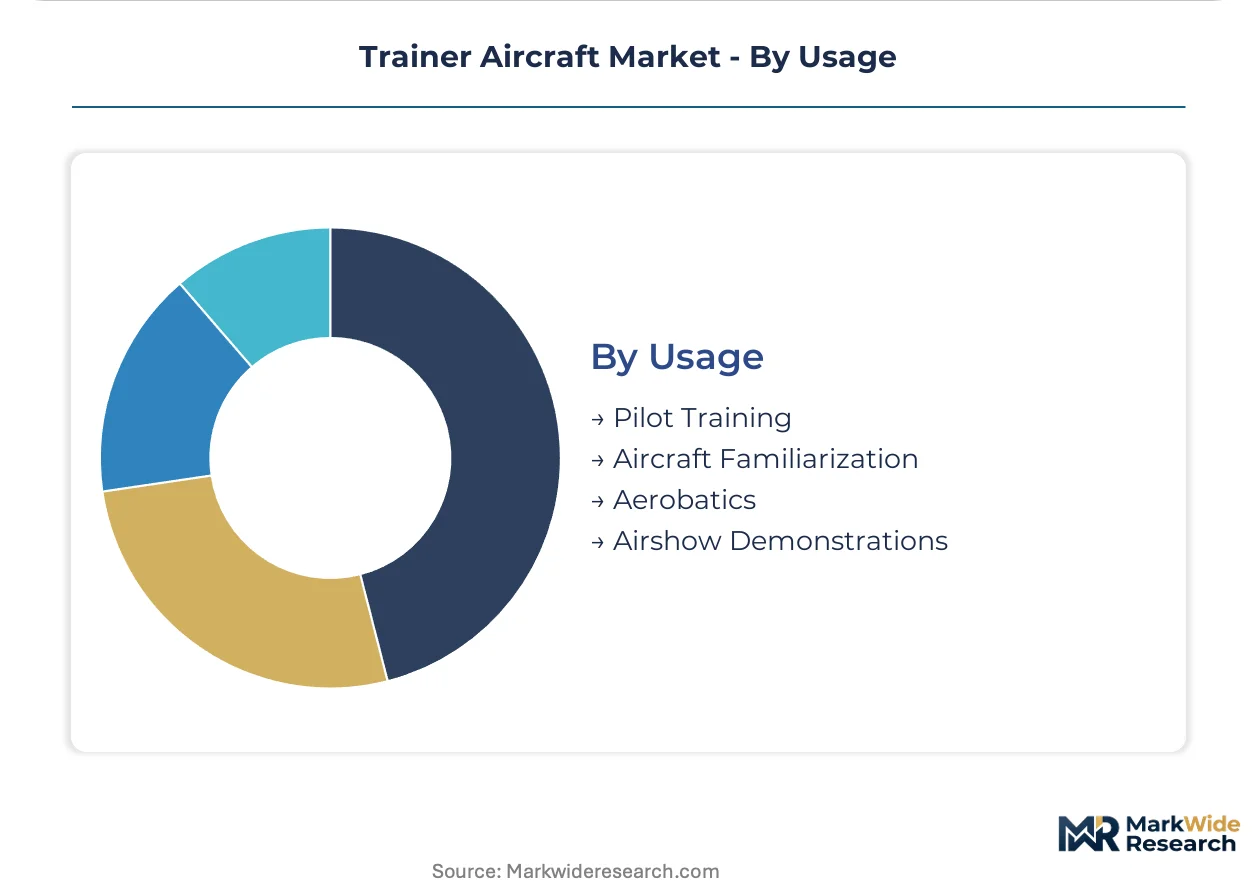
- Pilot Training:Structured curricula from ab initio through operational conversion constitute the core demand driver, with syllabus requirements dictating aircraft performance envelopes and dual-control configurations.
- Aircraft Familiarization:Type-specific transition training for experienced pilots moving between aircraft categories.
- Aerobatics:Maneuver-capable platforms with reinforced structures and inverted fuel systems serve competitive and military upset recovery programs.
- Airshow Demonstrations:High-visibility paint schemes and smoke systems equip military and civilian demonstration teams.
Pilot training applications command the established base. Aircraft familiarization usage is expanding most quickly as fleet modernization accelerates type conversion demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Military procurement offices and civil flight academies concentrate trainer aircraft demand in defense industrial hubs and aviation training corridors. National airworthiness mandates and fleet modernization timelines shape regional purchasing patterns.
United States
The US Air Force T-7A Red Hawk program drives the largest Western military trainer contract, with Boeing anchoring production in St. Louis, Missouri. FAA Part 23 modernization mandates accelerate glass cockpit refreshes across Part 141 flight schools. The Wichita, Kansas aerospace cluster hosts multiple training platform suppliers serving both military and civil segments.
Germany
Luftwaffe pilot training pipelines expand to bridge Eurofighter and FCAS fleet transitions, creating demand for advanced jet platforms. EASA CS-23 certification deadlines force analog-to-digital avionics conversions across German flight schools. The Munich aerospace corridor concentrates avionics integration capabilities for trainer cockpit modernization programs.
United Kingdom
Royal Air Force training command consolidates around the Hawk T2 platform for advanced phase instruction, with BAE Systems sustaining production lines. Military type certification friction with NATO allies extends platform qualification timelines for cross-border training agreements. The Brough and Warton industrial sites in Northern England anchor BAE's trainer manufacturing and systems integration operations.
Italy
Leonardo SpA leverages its M-346 platform to anchor European advanced jet training, with the Italian Air Force operating the type as a lead-in fighter trainer. EASA mandates on synthetic vision systems accelerate avionics upgrades across Italian military and civil training fleets. The Venegono Superiore facility near Milan serves as Leonardo's primary trainer design and final assembly center.
Australia
Royal Australian Air Force pilot training contracts shift toward service-based models where contractors provide training capacity rather than delivered hardware. Performance-based training procurement frameworks concentrate risk with original equipment manufacturers. The Williamtown defense precinct in New South Wales hosts integrated live-virtual-constructive training infrastructure development.
Trainer Aircraft Market Competitive Environment
Channel-controlling players compete with product-specialist players across segmented procurement frameworks. The vendor base stratifies between full-system integrators and component-focused suppliers. Three archetypes dominate: defense primes bundling airframes with synthetic training infrastructure, turboprop specialists serving civil-military crossover demand, and state-backed aerospace conglomerates with captive domestic markets. Competitive moves concentrate on strategic partnerships for embedded simulation technology and geographic expansion into underpenetrated Southeast Asian air forces.
Within the defense prime tier, The Boeing Company and BAE Systems PLC exemplify full-system integrators competing for multi-decade military training contracts. Leonardo SpA occupies a distinctive position bridging European advanced jet training requirements with integrated synthetic mission systems. Among turboprop specialists, Pilatus Aircraft Ltd represents the civil-military crossover archetype, with its PC-21 platform serving both NATO air forces and high-end flight academies requiring glass cockpit standardization.
| Leading Market Players |
|---|
| Leonardo SpA |
| Pilatus Aircraft Ltd |
| The Boeing Company |
| Embraer SA |
| BAE Systems PLC |
| Textron Inc. |
| Hindustan Aeronautics Ltd |
| Rostec |
| Airbus SE |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in afterburning turbofan engine production tilts pricing power toward specialized propulsion suppliers, compressing margins for airframe integrators while inflating long-term contract values for advanced jet trainers.
Pricing Analysis
Cost-plus contracts with labor and materials indexation dominate military trainer procurement, insulating suppliers from input volatility while capping upside. Pricing stratifies across advanced jet, intermediate turboprop, and basic trainer tiers, with glass cockpit certification grade driving differentiation within each band. Cost compression in basic trainer segments intensifies as flight schools face EASA CS-23 compliance deadlines. Military end users exhibit lowest price sensitivity due to mission-critical requirements and multi-decade fleet horizons.
Supply Chain Analysis
Upstream feedstock for titanium airframe structures and nickel-based superalloys draws from concentrated mining and metallurgy operations in the United States, Russia, and China. Specialized avionics components hinge on semiconductor fabrication in Taiwan and South Korea. Single-source vulnerability around afterburning turbofan engines creates procurement bottlenecks for advanced trainer programs. Distribution runs through defense prime contractors bundling airframes with synthetic training infrastructure under integrated system-of-systems contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Trainer aircraft procurement is shifting toward service-attach models where synthetic mission systems and live-virtual-constructive training infrastructure expand recurring revenue faster than hardware deliveries.
For Market Incumbents: Build switching-cost moats through embedded simulation technology that locks training commands into integrated platform ecosystems. Deepen backward integration into glass cockpit avionics to capture margin from regulatory-mandated fleet refreshes. Counter emerging electric propulsion entrants by accelerating FAA certification pathway capture for battery-powered ab initio platforms.
For New Entrants and Emerging Players: Establish a beachhead in Southeast Asian flight school markets where EASA-aligned certification demand outpaces local supply. Target Indonesian and Vietnamese military training commands evaluating Western platform alternatives. Lead with civil-military dual certification to bypass lengthy military type qualification timelines.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among synthetic training infrastructure providers bundling software subscriptions with hardware platforms. Five-to-ten year viability favors suppliers with captive positions in glass cockpit upgrade cycles. Monitor FAA Part 23 electric propulsion certification announcements as inflection indicators for battery-powered trainer segment viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Mission System Integration | Embeds Boeing and Leonardo platforms into NATO training commands through software-dependent recurring contracts. |
| Glass Cockpit Retrofit Program | Pilatus captures EASA CS-23 compliance-driven demand across German and Italian flight school fleets. |
| Electric Propulsion Certification Pathway | First-mover FAA approval for battery-powered ab initio platforms unlocks greenfield market creation. |
| Live-Virtual-Constructive Infrastructure Partnership | Australian service-based training contracts transfer fleet management risk to original equipment manufacturers. |
| Southeast Asian Distribution Expansion | Indonesian and Vietnamese air force evaluations create entry points for Western platform suppliers. |
Study Parameters
Initial hypotheses were tested against primary input from military procurement officers, flight school operations directors, avionics integration engineers, and defense prime contract managers and refined through secondary validation against FAA certification databases, EASA CS-23 regulatory filings, NATO standardization agreements, and defense budget appropriation documents. Bottom-up fleet inventory analysis was triangulated with top-down defense expenditure modeling.
Demand-supply balance across the projection horizon was assessed through military training pipeline capacity modeling and civil aviation pilot certification throughput analysis. Segmentation dimensions included product type, end user archetype, technology maturity level, and application purpose. CAGRs were derived from regression analysis of historical procurement cycles and projected fleet refresh timelines, incorporating synthetic training system adoption curves and regulatory compliance deadline clustering.
Stress conditions across defense budget volatility, turbofan engine delivery delays, and electric propulsion certification timeline slippage were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on NATO fleet standardization continuity and EASA mandate enforcement. Cross-checking against national defense white papers and flight school fleet renewal announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Simulation and Training
Military Training Aircraft Market
Simulation and Training
Simulators Market
Simulation and Training
Dynamic Flight Training Compartments Market
Simulation and Training
Police and Military Simulation Training Market
Simulation and Training
UAV Flight Training and Simulation Market
Simulation and Training
GNSS Simulators Market
Simulation and Training
Air Traffic Control Simulation and Training Market
Simulation and Training
Flight Simulation Training Device Market
Simulation and Training
Satellite Simulator Market
Simulation and Training
North America Simulator Windows and Simulator Skylights Market
Simulation and Training
Global Military Airborne Simulation and Training Market
Simulation and Training
North America Ship Bridge Simulators Market
Simulation and Training
Asia-Pacific Ship Bridge Simulators Market
Simulation and Training
Middle East and Africa Ship Bridge Simulators Market
Simulation and Training
Air Traffic Control Simulator and Training Market
Simulation and Training
Flight Simulator Market