
 Pilot Training Market | 2026-2036
Pilot Training Market Size, Share, and Industry Trends Forecast 2026-2036
Pilot Training Market Analytics
The EU Green Deal's sustainable aviation fuel mandates are repositioning pilot training curricula toward emissions-aware operational procedures. CAE Inc. leverages its integrated simulator manufacturing to control costs across training centers on three continents. Lufthansa Aviation Training GmbH anchors European regulatory compliance through its EASA-approved programs. FlightSafety International Inc. dominates the corporate and business aviation segment with specialized type-rating instruction.
Pilot training encompasses structured instruction, simulator-based proficiency development, and supervised flight experience designed to qualify candidates for specific aircraft type ratings and regulatory certifications. Full-flight simulators replicate cockpit environments with six-axis motion platforms and wraparound visual systems generating 200-degree fields of view. Simulator training commands the largest revenue share due to capital intensity and regulatory hour substitution allowances, while online modules represent the fastest-expanding format as airlines adopt distance learning for ground school theory. Certification type segmentation shows ATPL pathways generating premium pricing relative to PPL tracks, reflecting the multi-year commitment and airline sponsorship structures involved.
FAA Part 141 and EASA Part-FCL establish the foundational regulatory architecture governing curriculum hours, instructor qualifications, and examination protocols in the United States and Europe respectively. The Civil Aviation Authority of Singapore enforces similarly stringent standards that have positioned the city-state as a regional accreditation hub. ICAO's competency-based training and assessment framework is gradually displacing traditional hour-counting methodologies, requiring providers to restructure instructional design and invest in adaptive learning platforms. Stakeholders must evaluate which regulatory jurisdictions offer mutual recognition agreements that streamline cross-border pilot mobility before committing capital to new training infrastructure.
Market Dynamics
ICAO's competency-based training and assessment framework is restructuring instructional design across the pilot training industry, forcing providers to abandon hour-counting methodologies and invest in adaptive learning platforms that measure demonstrated proficiency rather than accumulated flight time.
Growth Catalysts
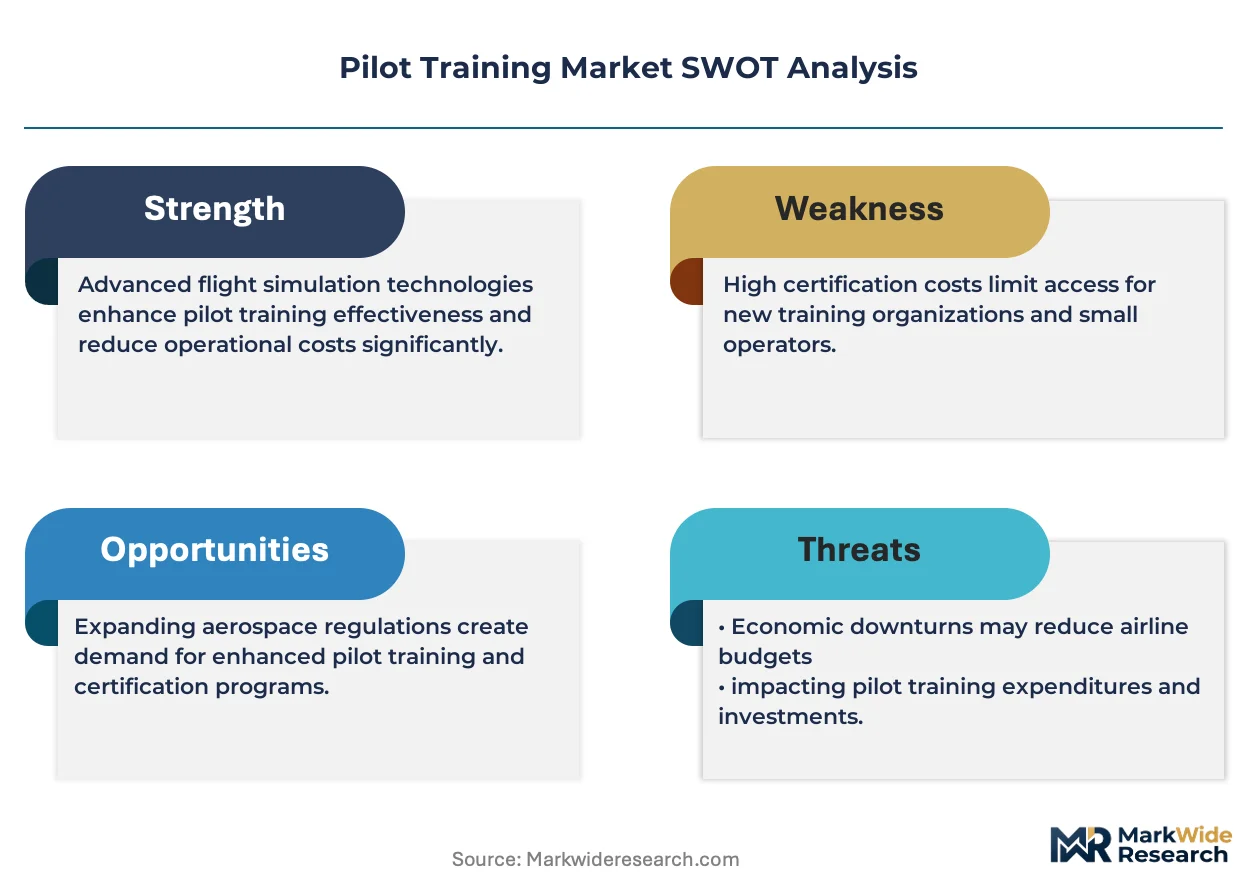
- FAA Part 141 Modernization:Updated certification requirements are accelerating simulator fleet replacement cycles among US training providers, creating equipment upgrade demand across the sector.
- Southeast Asian Fleet Expansion:Commercial carriers in Vietnam, Indonesia, and the Philippines are scaling cadet sponsorship programs to fill projected cockpit vacancies from aircraft deliveries.
- Virtual Reality Integration:Immersive headset-based procedural trainers are reducing initial operating costs for entry-level flight schools, expanding access to instrument familiarization modules.
Market Restraints
- Simulator Hardware Concentration:Full-flight motion platform manufacturing clusters in Canada and France create supply vulnerability for training centers in secondary markets.
- Jet Fuel Price Volatility:Actual flight hour costs fluctuate with aviation turbine fuel indices, compressing margins on live-aircraft training segments.
- Instructor Certification Bottlenecks:EASA Part-FCL examiner availability constraints in Eastern Europe limit training throughput regardless of simulator capacity.
Strategic Opportunities
- India's UDAN Regional Connectivity:Subsidized routes to tier-2 cities are generating first-officer demand from domestic carriers lacking established ab initio pipelines.
- Sustainable Aviation Fuel Mandates:EU Green Deal emissions protocols require emissions-aware operational training, creating curriculum differentiation opportunities for early adopters.
- Distance Learning Ground School:Asynchronous online theory modules are penetrating markets previously served only by residential programs, reducing geographic barriers to enrollment.
Industry Challenges
- Adaptive Learning Platform Integration:Legacy learning management systems at established academies resist seamless incorporation of competency-tracking algorithms.
- Examiner Standardization Delays:Mutual recognition agreement negotiations between CAAS, FAA, and EASA jurisdictions stall cross-border license conversion timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pilot Training Market |
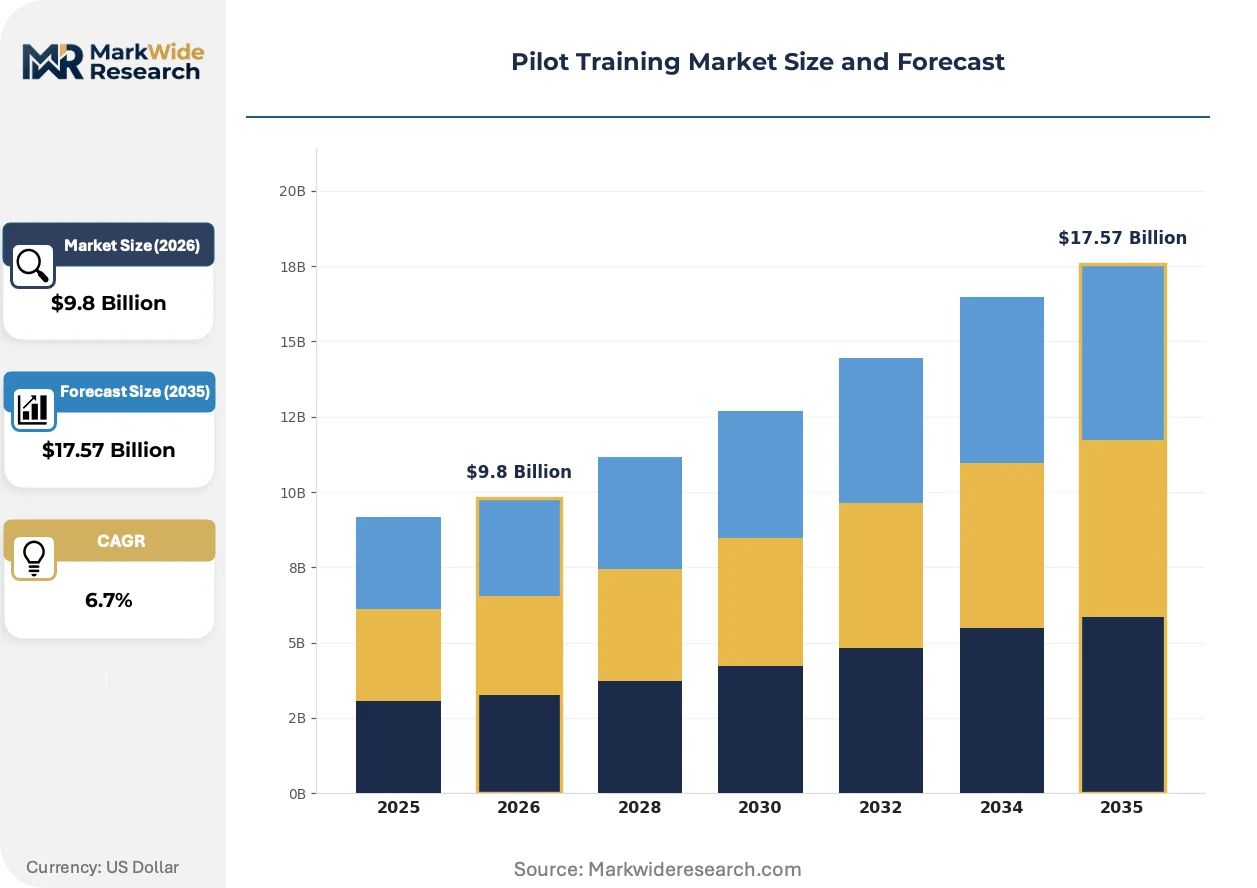
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.57 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Training Type: Simulator Training, Ground School, Flight Instruction, Online Modules Aircraft Type: Commercial Jets, Helicopters, Private Planes, Military Aircraft Experience Level: Beginner, Intermediate, Advanced, Professional Certification Type: PPL, CPL, ATPL, FRTOL |
| Companies Covered | FlightSafety International Inc., Epic Flight Academy Inc., The Boeing Company, Airbus Asia Training Centre Pte. Ltd., ATP Flight School Inc., CAE Inc., Lufthansa Aviation Training GmbH, Singapore Flying College Pte Ltd, L3Harris Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pilot Training Market Evolving Landscape
Training modality preferences are bifurcating between capital-intensive full-flight simulation and accessible virtual reality alternatives, with regulatory acceptance patterns determining which technologies achieve mainstream curriculum integration.
Extended reality headsets with haptic feedback gloves are overtaking traditional flat-screen procedural trainers for instrument scanning and emergency checklist drills. Regional flight schools in Australia and South Africa are adopting these systems to reduce initial capital outlays. The technology is overtaking legacy computer-based training modules by compressing equipment procurement cycles from years to months.
EASA's Part-FCL amendments incorporating upset prevention and recovery training mandates are extending simulator session durations and restructuring base curriculum sequences. Training providers must now allocate additional motion platform hours to stall and spin recovery scenarios. European ATPL programs are absorbing the regulatory burden through extended course timelines and adjusted pricing structures.
Airline-sponsored cadet contracts are displacing self-funded training pathways as the dominant enrollment mechanism for commercial certification tracks. Major carriers in Singapore and the United Arab Emirates are directly financing ab initio programs in exchange for multi-year employment commitments. This concentration of buyer power is most visible across the Asia-Pacific, where group training orders now determine simulator manufacturer production schedules.
Pilot Training Market Segmentation
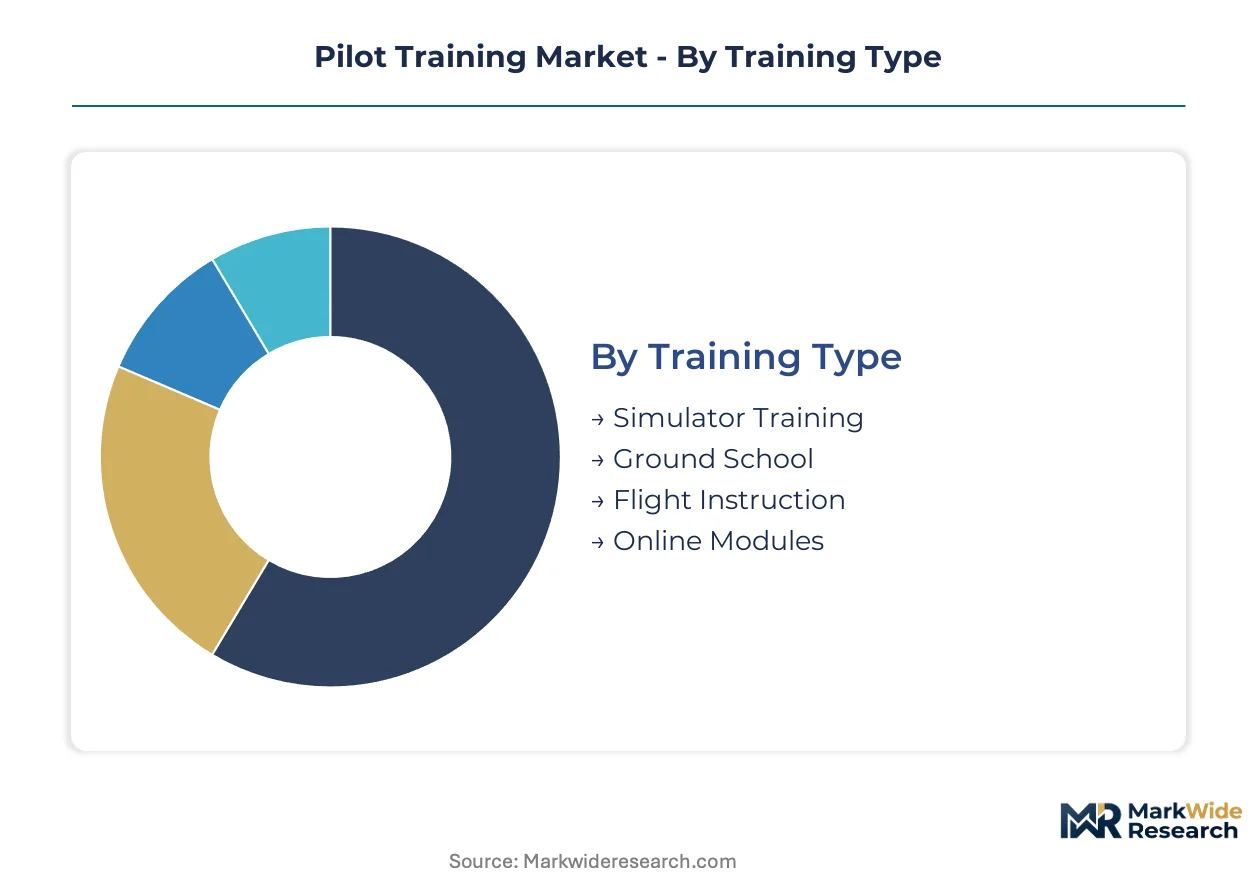
Segmentation in pilot training reveals how capital allocation, regulatory pathways, and technology adoption diverge across instructional formats and candidate profiles. Providers must align simulator investments, curriculum design, and pricing structures with distinct customer readiness levels and certification objectives.
Training Type:
Upgrade cycles and regulatory hour-substitution rules are redistributing capital across instructional modalities, with legacy providers modernizing fleets while entrants exploit lower-barrier formats.
- Simulator Training:Full-flight devices with six-axis motion platforms and 200-degree visual fields replicate cockpit environments for type-rating proficiency. Demand clusters with commercial carriers in Singapore and the United Arab Emirates, where CAE and Airbus Asia Training Centre serve regional airline group orders. Fleet replacement cycles are accelerating under FAA Part 141 modernization mandates.
- Ground School:Classroom-based theoretical instruction covering aerodynamics, meteorology, and air law remains mandatory for all certification pathways. European providers under EASA Part-FCL jurisdiction are extending course timelines to accommodate upset prevention and recovery training mandates.
- Flight Instruction:Supervised live-aircraft training delivers accumulated flight hours toward certificate eligibility. Jet fuel price volatility compresses margins on this segment regardless of geographic market.
- Online Modules:Asynchronous distance learning platforms deliver ground school theory through adaptive learning systems. Penetration is climbing fastest in markets previously restricted to residential programs.
Volume placements concentrate in Simulator Training; the faster expansion belongs to Online Modules.
Aircraft Type:
Platform-specific certification demand tracks directly to fleet delivery schedules and military procurement cycles across operator bases.
- Commercial Jets:Multi-crew pilot license pathways and type-rating instruction for narrow-body and wide-body aircraft dominate revenue concentration. Southeast Asian carriers in Vietnam, Indonesia, and the Philippines are scaling cadet sponsorship programs to match aircraft delivery pipelines.
- Helicopters:Rotary-wing instruction serves emergency medical services, offshore energy, and law enforcement operators. Training throughput is constrained by specialized instructor availability in secondary markets.
- Private Planes:Single-engine piston aircraft instruction supports PPL and instrument rating candidates. Regional flight schools in Australia and South Africa are adopting virtual reality headsets to reduce initial capital outlays.
- Military Aircraft:Government-contracted instruction follows defense procurement cycles and sovereign training requirements. National air forces retain captive training infrastructure in most jurisdictions.
Revenue gravity centers on Commercial Jets; Helicopter instruction is gaining share fastest among specialized operator segments.
Experience Level:
Curriculum sequencing and instructor specialization requirements create distinct margin profiles across candidate progression stages.
- Beginner:Ab initio instruction introduces fundamental stick-and-rudder skills and pre-solo certification. India's UDAN regional connectivity subsidies are generating first-officer demand from domestic carriers lacking established pipelines.
- Intermediate:Cross-country navigation, instrument rating foundations, and complex aircraft endorsement build operational competence. This stage absorbs the highest per-student instructor hour burden.
- Advanced:Multi-engine certification, commercial pilot preparation, and initial type-rating groundwork precede airline entry. EASA Part-FCL examiner availability constraints in Eastern Europe limit throughput at this transition point.
- Professional:Recurrent training, command upgrade preparation, and fleet transition instruction serve employed flight crew. Airline-sponsored contracts are displacing self-funded pathways as the dominant enrollment mechanism.
Enrollment volumes peak at Beginner levels; Professional segment value per trainee is climbing the fastest.
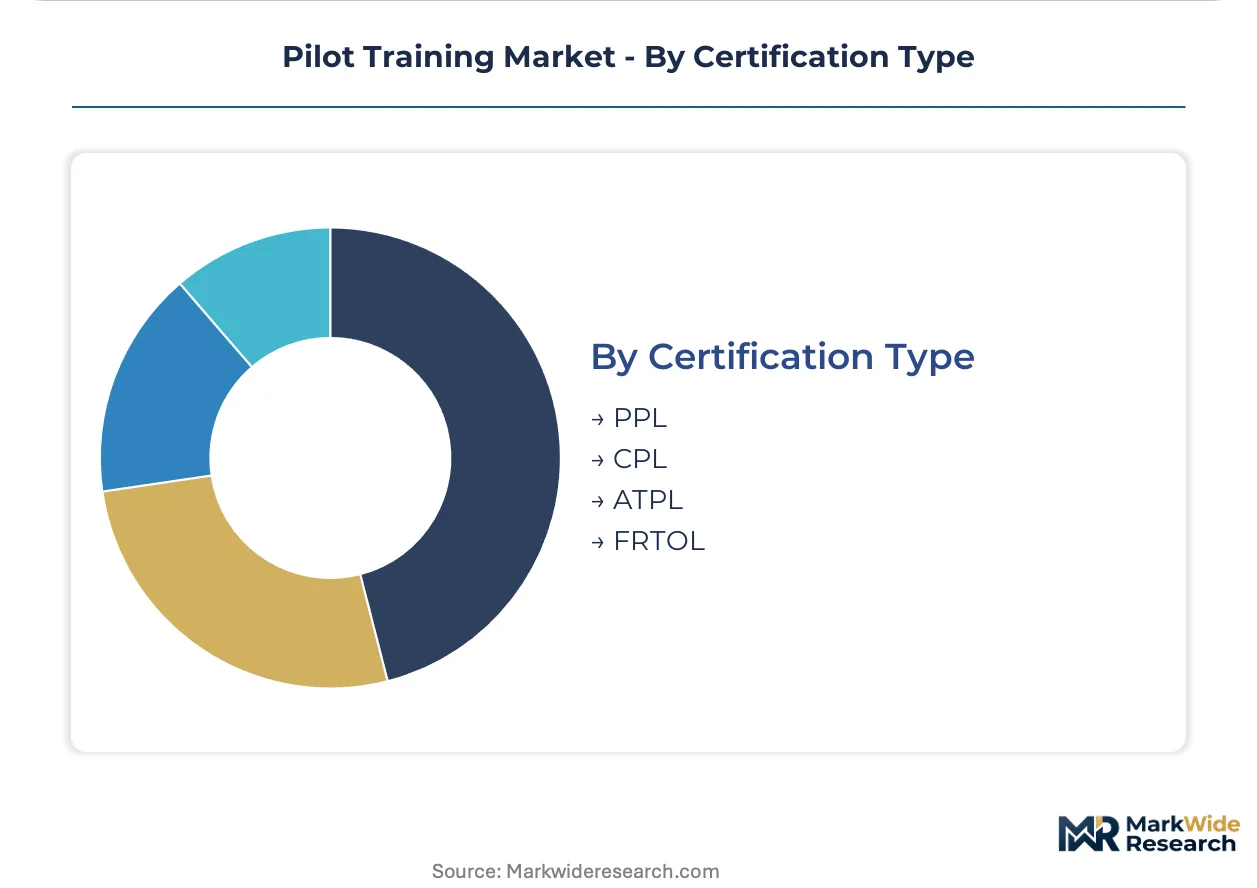
Certification Type:
Regulatory pathway selection determines curriculum duration, examination complexity, and sponsor financing structures.
- PPL:Private pilot license qualification permits non-commercial flight under visual flight rules. Self-funded candidates dominate this track in North American and European recreational aviation markets.
- CPL:Commercial pilot license enables remunerated flight operations with operational restrictions. Training providers price this intermediate pathway below ATPL tracks reflecting shorter commitment horizons.
- ATPL:Airline transport pilot license represents the terminal certification for multi-crew command. Singapore and United Arab Emirates carriers are directly financing ab initio programs in exchange for multi-year employment commitments, generating premium pricing structures.
- FRTOL:Flight radiotelephony operator license authorizes radio communication privileges in controlled airspace. This ancillary certification integrates into broader licensing curricula rather than standing alone.
Candidate volumes concentrate in PPL pathways; ATPL programs are expanding most quickly through airline sponsorship concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Simulator manufacturing concentrates in Canada and France, while training demand clusters in Singapore, the United Arab Emirates, and the United States where carrier fleet expansion drives cadet program scaling.
United States
FAA Part 141 modernization mandates are accelerating equipment replacement cycles among domestic training providers. The updated certification framework requires enhanced simulator fidelity standards and revised curriculum documentation protocols. FlightSafety International operates specialized facilities in Florida and Arizona serving corporate aviation type-rating demand.
Singapore
CAE and Airbus Asia Training Centre anchor Asia-Pacific commercial jet instruction from flagship campuses serving regional carrier group orders. The Civil Aviation Authority of Singapore enforces accreditation standards that position the city-state as a mutual recognition hub for cross-border license conversion. Changi Aviation Park clusters simulator bays, classroom infrastructure, and airline operations centers within integrated training precincts.
Germany
Lufthansa Aviation Training GmbH anchors European regulatory compliance through EASA-approved ATPL and type-rating programs. EASA Part-FCL amendments incorporating upset prevention and recovery training are extending simulator session durations across German academies. Frankfurt and Munich host the continent's densest concentrations of full-flight motion platforms serving Lufthansa Group and third-party carrier contracts.
United Arab Emirates
Emirates and Etihad cadet sponsorship programs are displacing self-funded training pathways through direct ab initio financing. The General Civil Aviation Authority maintains bilateral recognition agreements with EASA and FAA jurisdictions that streamline license conversion for expatriate flight crew. Dubai South integrates training campuses with maintenance facilities and airline headquarters within the aviation district.
India
UDAN regional connectivity subsidies are generating first-officer demand from domestic carriers lacking established ab initio pipelines. The Directorate General of Civil Aviation is expanding approved training organization capacity to address examiner availability constraints. Flight schools in Maharashtra and Karnataka are adopting virtual reality headsets to reduce initial capital outlays on procedural training equipment.
Pilot Training Market Competitive Landscape
The competitive structure tilts toward integrated simulator manufacturers with captive training networks. Consolidation around full-flight device production in Montreal and Toulouse creates supply-side leverage over independent academies. Three archetypes dominate: vertically integrated equipment-and-training hybrids, airline-captive facilities, and independent flight schools adopting lower-cost virtual reality formats. Capacity expansion and strategic partnerships with carrier cadet programs represent the primary competitive vectors.
Among North American specialists, FlightSafety International exemplifies the corporate aviation-focused archetype through its type-rating concentration. CAE represents the integrated manufacturer-operator model with simulator production feeding directly into global training center networks. L3Harris Technologies occupies a position spanning defense-contracted instruction and commercial pilot pathways. These three entities illustrate how capital intensity and regulatory relationships determine sustainable positioning across certification segments.
| Leading Market Players |
|---|
| FlightSafety International Inc. |
| Epic Flight Academy Inc. |
| The Boeing Company |
| Airbus Asia Training Centre Pte. Ltd. |
| ATP Flight School Inc. |
| CAE Inc. |
| Lufthansa Aviation Training GmbH |
| Singapore Flying College Pte Ltd |
| L3Harris Technologies Inc. |
| Others |
Value Network & Pricing Analysis
Captive integration into simulator manufacturing anchors both supply security and pricing power for training providers operating across three continents. CAE's in-house production of full-flight motion platforms insulates its training centers from equipment procurement cycles that strain independent academies, while airline-sponsored cadet contracts concentrate buyer leverage over pricing structures in Singapore and the United Arab Emirates.
Pricing Analysis
Cost-down pressure on self-funded PPL tracks accelerates because VR-based procedural trainers slash capital requirements for entry-level schools. Three-tier pricing structure across airline-sponsored, corporate-sponsored, and self-funded enrollment levels separates ATPL pathways from CPL and PPL tracks. Price differentiation rests on certification grade and simulator fidelity tier. Self-funded candidates in North American recreational aviation markets exhibit highest price sensitivity; Emirates and Etihad direct-financing programs show lowest.
Supply Chain Analysis
Domestic-content mandates in India's UDAN regional connectivity scheme are reshaping simulator procurement toward local assembly partnerships. Full-flight motion platform manufacturing clusters in Canada and France, with component sourcing from Germany and the United States. Raw material dependencies include aerospace-grade aluminum castings, high-fidelity visual projection systems, and precision hydraulic actuators. Single-source vulnerability concentrates in six-axis motion base production. Distribution runs through airline group training contracts and defense procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extended reality headsets are displacing legacy flat-screen procedural trainers across entry-level instruction, compressing equipment procurement cycles and democratizing access to instrument familiarization modules.
For Market Incumbents: Anchor fleet modernization programs to FAA Part 141 fidelity mandates before independent academies capture VR-enabled cost advantages. Deepen backward integration into adaptive learning platform development to defend against software-centric entrants. Prioritize EASA examiner certification investments in Eastern Europe where throughput constraints limit professional segment expansion. For New Entrants and Emerging Players: Begin with India's UDAN-subsidized regional connectivity corridors where domestic carriers lack established ab initio pipelines and examiner availability creates enrollment backlogs. Target helicopter instruction in secondary markets where specialized instructor scarcity protects margin structures. Pursue distance learning ground school partnerships with tier-2 city flight schools as the go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in vertical integration plays where simulator manufacturers acquire training network scale. Long-term viability favors entities controlling both motion platform production and airline cadet contract relationships. Watch EASA-FAA-CAAS mutual recognition agreement negotiations as the inflection signal for cross-border license conversion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Simulator Fleet Modernization | FAA Part 141 mandates force equipment replacement cycles across US training centers. |
| VR Procedural Trainer Deployment | Extended reality headsets reduce capital barriers for Australian and South African flight schools. |
| Airline Cadet Sponsorship Expansion | Singapore and UAE carriers finance ab initio programs in exchange for employment commitments. |
| Adaptive Learning Platform Integration | Competency-tracking algorithms replace hour-counting methodologies under ICAO frameworks. |
| EASA Examiner Capacity Buildout | Eastern European training throughput limits require examiner certification investment. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs combining primary interviews with flight school operators, airline training managers, simulator manufacturer product directors, and civil aviation authority certification leads. FAA Part 141 documentation, EASA Part-FCL amendment records, ICAO training circulars, and CAAS accreditation databases provided institutional validation. Bottom-up enrollment projections triangulated against top-down fleet delivery forecasts.
Granularity-level modeling distinguished training type, aircraft platform, experience tier, and certification pathway across the projection horizon. Simulator hour substitution rates, cadet sponsorship contract volumes, and examiner availability constraints fed segment-specific growth trajectories. CAGRs derived from equipment replacement cycles, regulatory mandate implementation timelines, and airline fleet expansion schedules.
Underlying measurement precision varies by segment; airline-sponsored ATPL pathways carry tighter precision than self-funded PPL enrollments. Forecasts reflect assumptions on mutual recognition agreement progress and VR regulatory acceptance timelines. ICAO competency framework adoption velocity and jet fuel price volatility present revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Simulation and Training
Live Laser-Based Training and Simulation Platforms Market
Simulation and Training
UAV Flight Training and Simulation Market
Simulation and Training
RADAR Simulator Market
Simulation and Training
Military Simulation Software Market
Simulation and Training
GNSS Simulators Market
Simulation and Training
Flight Simulator Market
Simulation and Training
Global Military Airborne Simulation and Training Market
Simulation and Training
North America Ship Bridge Simulators Market
Simulation and Training
Police and Military Simulation Training Market
Simulation and Training
Civil Aviation Simulator Market
Simulation and Training
Simulators Market
Simulation and Training
Global Ship Bridge Simulators Market
Simulation and Training
Helicopter Simulator Market
Simulation and Training
Air Traffic Control Simulator and Training Market
Simulation and Training
Asia-Pacific Civil Aviation Simulators Market
Simulation and Training
Flight Simulation Training Device Market