
 Air Traffic Control Simulation and Training Market | 2026-2036
Air Traffic Control Simulation and Training Market Size, Share, and Industry Trends Forecast 2026-2036
Air Traffic Control Simulation and Training Market Insights
Military aviation units are repositioning their training procurement toward synthetic environment simulation platforms that replicate contested airspace scenarios. Thales Group leverages its integrated defense-electronics heritage to anchor European military ATC training programs. Raytheon Technologies sustains its position through deep relationships with the FAA and US Department of Defense simulation contracts. Adacel Technologies Limited specializes in oceanic and procedural airspace training modules, competing aggressively in Asia-Pacific civilian markets.
Air Traffic Control Simulation and Training encompasses computer-generated environments that replicate radar displays, voice communication protocols, and multi-aircraft traffic scenarios for controller competency development. Systems integrate live weather data feeds, aircraft performance databases, and human-in-the-loop interfaces to achieve Federal Aviation Administration and Eurocontrol certification standards. Scenario-based simulation dominates procurement budgets among air navigation service providers seeking cost-effective recurrent training alternatives to live traffic exercises. Virtual reality training represents the fastest-expanding training method segment, though instructor-led formats retain margin concentration due to regulatory mandate persistence.
The FAA, Eurocontrol, and EASA collectively shape simulator certification requirements through joint safety management system directives and controller licensing frameworks. Military standards including NATO STANAG protocols further segment product development roadmaps for dual-use suppliers. Stakeholders must monitor evolving ICAO competency-based training mandates and their translation into national procurement specifications to anticipate simulator replacement cycles.
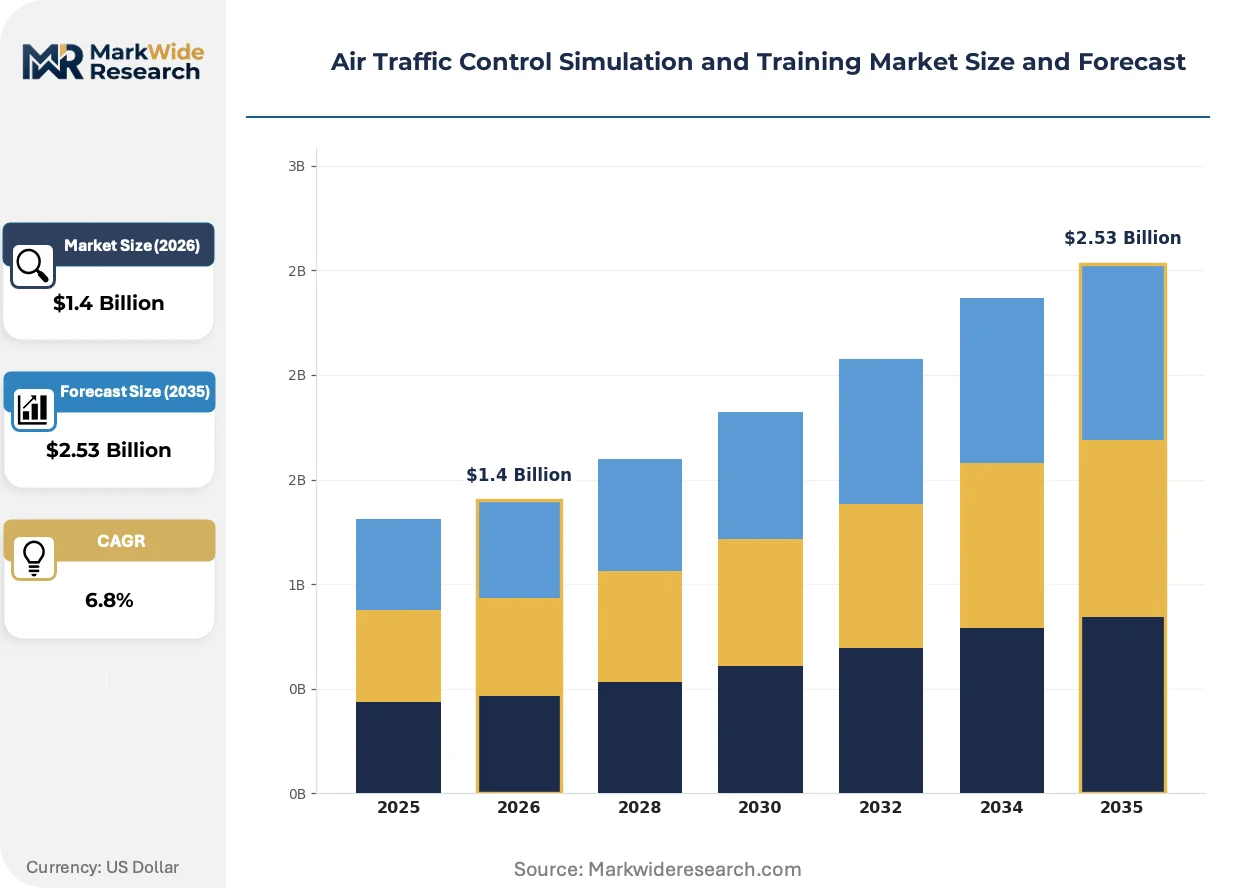
Market Dynamics
Air navigation service providers face mounting pressure to replace legacy radar-based training infrastructure with synthetic environment platforms that replicate NextGen and SESAR operational concepts. Procurement cycles compress as FAA and Eurocontrol certification deadlines force simultaneous simulator upgrades across multiple facility classes.
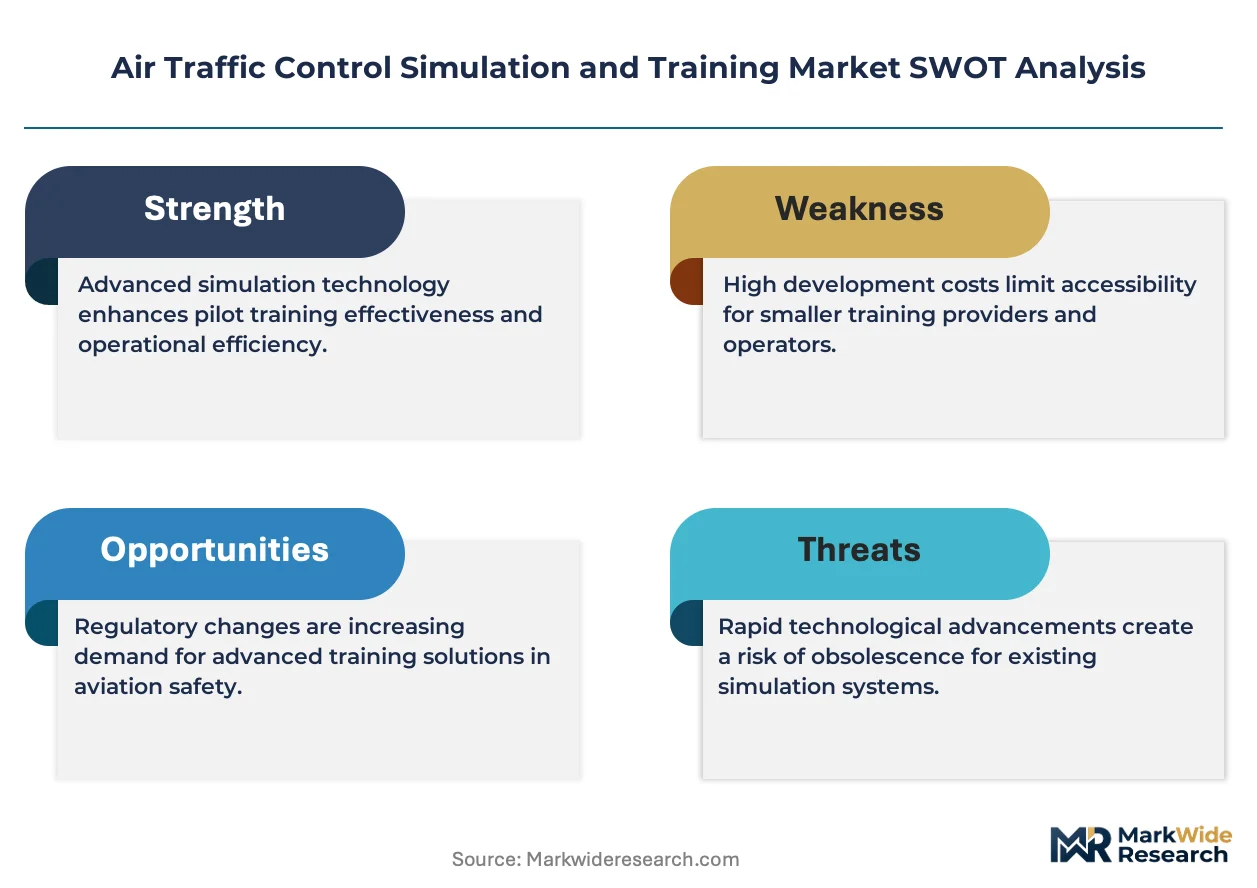
Growth Catalysts
- NextGen modernization mandates:FAA requirements for trajectory-based operations drive replacement of procedural training systems with 4D flight path simulation capabilities across US terminal radar approach control facilities.
- Contested airspace training:Military aviation units prioritize synthetic environments replicating electronic warfare scenarios and denied-GPS conditions for controller combat readiness certification.
- Oceanic procedural expansion:Growing North Atlantic and Pacific track density compels ANSPs in Australia and Singapore to invest in long-range surveillance and datalink simulation modules.
Market Restraints
- Specialized hardware dependency:High-fidelity voice communication and radar display replication require purpose-built input-output systems with limited supplier alternatives in Germany and France.
- Certification timeline rigidity:FAA JO 7110.65 and Eurocontrol controller licensing frameworks impose 18-24 month validation periods for new simulation platforms, freezing procurement decisions.
- Live traffic substitution ceiling:Regulatory minimums for human-in-the-loop hours prevent full displacement of on-the-job training, capping simulator utilization rates.
Strategic Opportunities
- Virtual reality training penetration:Head-mounted display systems for tower simulation remain underdeployed in civilian markets, offering first-mover positioning for immersive platform developers.
- Competency-based training frameworks:ICAO Doc 9995 implementation creates demand for adaptive simulation engines that adjust scenario complexity based on individual controller performance metrics.
- Remote training delivery:Cloud-hosted simulation instances enable distributed training architectures, reducing physical academy infrastructure requirements for ANSPs in Australia and Canada.
Industry Challenges
- Controller instructor scarcity:Retiring veteran controllers with simulation instructional qualifications outpace training pipeline replacement, constraining academy throughput.
- Multi-system integration complexity:Synthetic environment platforms must interface with live operational data feeds, weather systems, and aircraft performance databases, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Traffic Control Simulation and Training Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Simulation Type: Real-Time Simulation, Scenario-Based Simulation, Role-Playing Simulation, Synthetic Environment Simulation, Predictive Simulation Training Method: Instructor-Led Training, Computer-Based Training, Virtual Reality Training, Augmented Reality Training, Blended Learning Application Area: Air Traffic Management, Pilot Navigation, Airport Operations, Airspace Monitoring, Emergency Response End User Type: Air Navigation Service Providers, Airlines, Flight Schools, Military Aviation Units, Aviation Regulatory Agencies |
| Companies Covered | Thales Group, Raytheon Technologies, BAE Systems, Adacel Technologies Limited, EIZO Corporation, Frequentis, Leonardo, Saab, Indra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Traffic Control Simulation and Training Market Trends and Innovations
Simulation architecture is pivoting from discrete subsystem assemblies toward unified synthetic environments that merge radar, tower, and oceanic control scenarios. Vendors consolidate previously separate training product lines to capture cross-domain certification contracts.
Artificial intelligence-based traffic generation is unifying scenario development workflows by automating conflict creation and resolution path modeling. ANSP training academies in the United States and Germany adopt these platforms to reduce instructor scenario-building workload. The technology compresses curriculum development cycles from months to weeks while maintaining FAA and Eurocontrol certification alignment.
EU SESAR deployment timelines are accelerating simulator refresh mandates across European ANSPs, with specific emphasis on trajectory-based operations and remote tower simulation. Eurocontrol's common certification framework reduces national variance in procurement specifications. Civilian and military installations in France, Germany, and the Netherlands synchronize upgrade schedules to capture volume pricing from integrated platform suppliers.
Buyer concentration among centralized national training academies is compressing vendor sales cycles and intensifying pre-qualification requirements. ANSP procurement departments now mandate multi-year service commitments and software update guarantees as standard contract terms. This pattern concentrates contract awards with suppliers maintaining dedicated training support infrastructure in the United States, Germany, and Australia.
Air Traffic Control Simulation and Training Market Segmentation
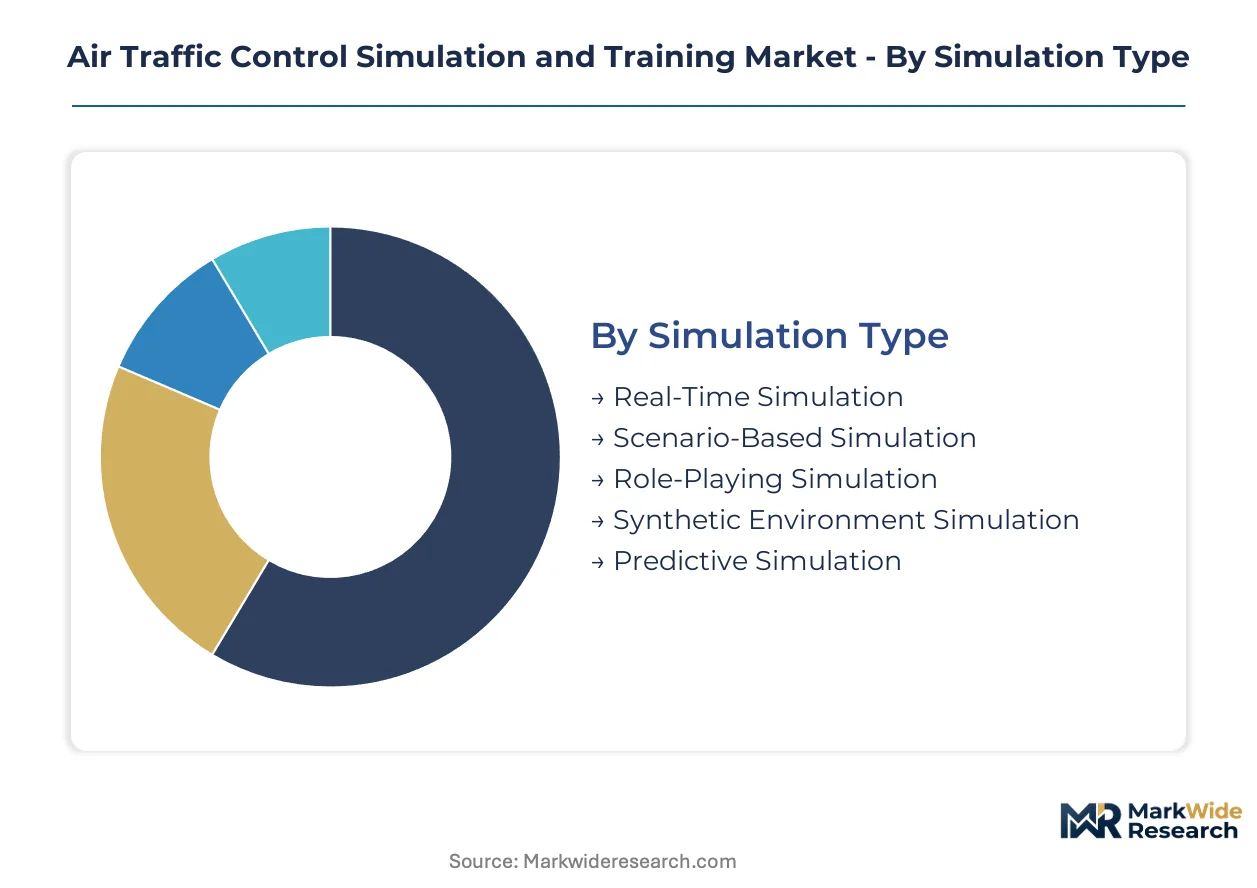
Segmentation in air traffic control simulation reveals how procurement priorities diverge between civilian ANSP academies and military aviation units. Each dimension—simulation architecture, delivery modality, operational domain, and buyer type—carries distinct certification requirements and technology refresh cycles that reshape vendor positioning.
Simulation Type:
Standalone simulation platforms operate independently for certification exercises, while embedded systems integrate directly with live operational infrastructure for on-the-job training.
- Scenario-Based Simulation:Pre-scripted traffic conflicts and weather disruptions replicate high-stress operational conditions for competency evaluation. FAA and Eurocontrol certification frameworks mandate scenario-based hours for controller licensing, concentrating demand among US and German ANSP training academies.
- Synthetic Environment Simulation:Unified digital replicas merge radar, tower, and oceanic control into seamless training environments. Military aviation units in Australia and the United States prioritize these platforms for contested airspace and electronic warfare readiness certification.
- Real-Time Simulation:Live traffic data feeds enable dynamic scenario adaptation during training sessions.
- Role-Playing Simulation:Multi-controller coordination exercises replicate team-based sector handoffs and emergency protocols.
- Predictive Simulation:AI-generated traffic forecasting models anticipate conflict scenarios before they materialize.
Scenario-based systems lead volumes today; synthetic environment platforms are gaining share fastest.
Training Method:
Cost tiering separates premium instructor-led formats from scalable self-paced modalities, with hybrid approaches capturing mid-budget deployments.
- Virtual Reality Training:Immersive head-mounted displays replicate tower visual environments with 360-degree field of view. ANSPs in Australia and Singapore deploy VR modules for cost-effective aerodrome control certification, though FAA validation timelines delay broader US adoption.
- Instructor-Led Training:Veteran controllers deliver scenario debriefs and performance assessments in physical academy settings. Regulatory mandates for human-in-the-loop hours preserve this format's margin concentration across European and North American training centers.
- Computer-Based Training:Self-paced modules cover procedural knowledge and regulatory updates.
- Augmented Reality Training:Overlay displays project traffic data onto physical tower windows or radar screens.
- Blended Learning:Hybrid schedules combine instructor sessions with computer-based self-study.
Instructor-led formats dominate revenue today; virtual reality is expanding most quickly.
Application Area:
Application scope determines integration complexity, with multi-domain platforms commanding premium pricing against single-purpose installations.
- Air Traffic Management:En-route and terminal radar approach control simulation replicates sector management, conflict resolution, and handoff protocols. ANSPs in Germany and the United States drive procurement for NextGen and SESAR-aligned trajectory-based operations training.
- Emergency Response:Hijacking, engine failure, and weather diversion scenarios test controller crisis management under time pressure. Military aviation units and civilian regulators in Australia mandate recurrent emergency simulation for license renewal.
- Pilot Navigation:Flight crew coordination exercises replicate pilot-controller communication protocols.
- Airport Operations:Ground movement and runway incursion prevention training for tower controllers.
- Airspace Monitoring:Long-range surveillance and oceanic procedural simulation for track management.
Air traffic management leads volumes today; emergency response is climbing the fastest.
End User Type:
Customer type dictates procurement scale and certification rigor, with national academies consolidating demand against fragmented airline and flight school purchases.
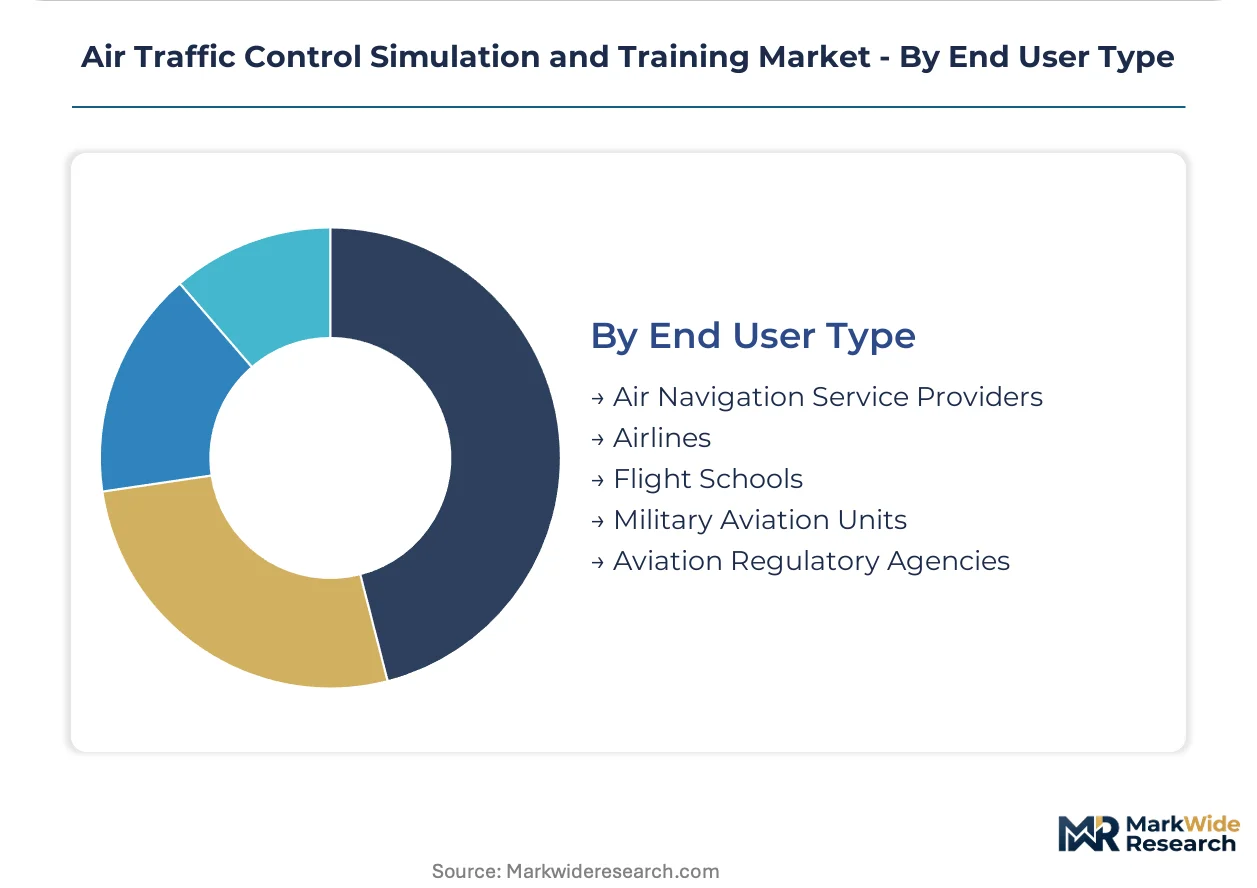
- Air Navigation Service Providers:Centralized national training academies operate multi-facility simulation networks for controller certification and recurrent training. FAA-mandated NextGen upgrades and Eurocontrol SESAR timelines compress procurement cycles across US, German, and Australian ANSPs.
- Military Aviation Units:Defense ministries procure synthetic environment platforms replicating contested airspace, electronic warfare, and denied-GPS conditions. NATO STANAG protocols and national combat readiness requirements drive specialized scenario development.
- Airlines:In-house training departments focus on pilot-controller coordination and company-specific procedures.
- Flight Schools:Entry-level tower and radar simulation for ab initio controller education.
- Aviation Regulatory Agencies:Oversight bodies operate reference simulation platforms for instructor certification and standardization.
Air navigation service providers dominate procurement today; military aviation units are expanding fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping procurement patterns as ANSPs migrate simulator investments toward jurisdictions with accelerated certification pathways. Cost-of-compliance gaps between FAA and Eurocontrol validation timelines are concentrating contract awards in markets offering streamlined approval frameworks.
United States
FAA NextGen modernization mandates and trajectory-based operations requirements are driving simulator replacements across terminal radar approach control facilities. The FAA JO 7110.65 certification framework imposes rigorous validation standards that favor incumbent suppliers with established compliance track records. Oklahoma City hosts the FAA Academy, which operates centralized training infrastructure serving domestic and international controller candidates.
Germany
EU SESAR deployment timelines and Eurocontrol's common certification framework are compressing procurement cycles for synthetic environment platforms. The country's national aviation regulator aligns with EASA controller licensing requirements, creating predictable procurement specifications for vendors. Langen and Munich house major DFS Deutsche Flugsicherung training academies coordinating multi-facility simulation networks.
Australia
Oceanic procedural expansion across North Pacific and Indian Ocean track systems is compelling investment in long-range surveillance simulation modules. Airservices Australia operates under ICAO competency-based training mandates that emphasize scenario-based certification hours. Melbourne and Brisbane training centers concentrate demand for oceanic and procedural airspace simulation capabilities.
France
Military-civilian dual-use procurement is accelerating through NATO STANAG protocol alignment and national combat readiness requirements. The country's aviation regulator maintains stringent simulator certification standards synchronized with Eurocontrol directives. Toulouse and Paris clusters integrate aerospace manufacturing heritage with advanced simulation development for controller training.
Singapore
Strategic positioning as a regional aviation hub is driving investment in tower and aerodrome control simulation for Southeast Asian controller certification. The Civil Aviation Authority of Singapore implements ICAO Doc 9995 competency frameworks for adaptive training delivery. Seletar and Changi training facilities serve as regional centers for ANSPs across Indonesia, Malaysia, and Thailand.
Air Traffic Control Simulation and Training Market Competitive Landscape
Platform consolidation dominates the current landscape as vendors merge previously discrete radar, tower, and oceanic simulation product lines. The supplier base concentrates among defense-electronics conglomerates with integrated training portfolios and specialized simulation pure-plays with domain-specific certification expertise. Two strategic archetypes prevail: integrated platform suppliers leveraging multi-domain contracts and niche specialists capturing single-domain certification mandates. M&A activity and multi-year service commitment requirements represent the dominant competitive moves reshaping vendor positioning.
Among integrated defense-electronics suppliers, Thales Group and Raytheon Technologies occupy positions anchored by deep relationships with military aviation units and civilian ANSPs respectively. Adacel Technologies Limited exemplifies the specialized pure-play archetype, concentrating procurement attention in Asia-Pacific oceanic and procedural airspace segments. These three entities represent the competitive spectrum from diversified conglomerate to focused specialist.
| Leading Market Players |
|---|
| Thales Group |
| Raytheon Technologies |
| BAE Systems |
| Adacel Technologies Limited |
| EIZO Corporation |
| Frequentis |
| Leonardo |
| Saab |
| Indra |
| Others |
Pricing and Supply Chain Analysis
Defense-electronics conglomerates with sovereign-backed financing anchor supply capacity in Germany and France, creating pricing discipline through multi-year service commitments that ANSP procurement departments now mandate as standard contract terms. This ownership pattern concentrates vendor pricing power while compressing sales cycles through pre-qualification requirements that lock out smaller competitors lacking dedicated training support infrastructure.
Pricing Analysis
Distributor margins in the United States and Germany absorb 15-25% of platform value before reaching ANSP academies, with direct-to-academy contracts commanding volume discounts for multi-facility simulation networks. Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified synthetic environment platforms from procedural training modules and computer-based self-study tools. Cost compression in mid-tier embedded systems is intensifying because Eurocontrol's common certification framework reduces national variance that previously supported geographic price differentiation. Military aviation units exhibit lowest price sensitivity due to NATO STANAG compliance mandates, while flight schools face acute budget constraints driving procurement toward economy-tier computer-based training modules.
Supply Chain Analysis
Single-source vulnerability sits with purpose-built voice communication and radar display replication hardware manufactured in Germany and France, where limited supplier alternatives constrain ANSP procurement flexibility. High-fidelity input-output systems draw from specialized semiconductor foundries in Taiwan, precision display panel production in South Korea, and custom aviation-grade enclosure fabrication in the United States. Tariff exposure on embedded computing components sourced from China is accelerating vendor migration toward alternative supply nodes in Mexico and Eastern Europe. Distribution runs through defense-electronics integrators with established FAA and Eurocontrol compliance track records, bypassing generalist IT channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Air Traffic Control Simulation and Training Market reads as a late-cycle quality story where procurement consolidation favors vendors with proven certification trajectories, justified by ANSPs shifting demand toward synthetic environment platforms that replicate NextGen trajectory-based operations and SESAR remote tower concepts.
For Market Incumbents: Extend platform consolidation strategies by merging previously discrete radar, tower, and oceanic simulation product lines into unified synthetic environments that capture cross-domain certification contracts. Invest in dedicated training support infrastructure within the United States, Germany, and Australia to satisfy multi-year service commitment mandates that procurement departments now require as standard terms. Vertical integration into AI-based traffic generation capabilities defends margin position against emerging pure-play specialists automating scenario development workflows. For New Entrants and Emerging Players: Virtual reality head-mounted display systems for tower simulation represent the most penetrable white-space target, with ANSPs in Australia and Singapore already deploying VR modules while FAA validation timelines delay broader US adoption. Cloud-hosted simulation instances enabling distributed training architectures offer second entry path for ANSPs in Canada and Australia seeking to reduce physical academy infrastructure requirements. Go-to-market positioning should emphasize accelerated ICAO Doc 9995 competency-based training compliance rather than competing on platform fidelity metrics. For Investors and Strategic Acquirers: Defense-electronics conglomerates with integrated training portfolios are the most active acquirer in this space, seeking specialized simulation pure-plays with domain-specific certification expertise in oceanic procedural or contested airspace scenarios. Long-term viability hinges on 5-10 year replacement cycles tied to FAA NextGen and EU SESAR deployment timelines rather than cyclical defense spending fluctuations. Watch for ICAO competency-based training mandate translation into national procurement specifications as the signal indicating simulator replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Consolidation | Unifies radar, tower, and oceanic domains to capture cross-domain ANSP certification contracts. |
| AI Traffic Generation Investment | Automates conflict scenario creation for FAA and Eurocontrol-aligned curriculum development. |
| Remote Training Infrastructure | Enables cloud-hosted simulation delivery reducing physical academy requirements for Airservices Australia. |
| Multi-Year Service Commitments | Satisfies procurement mandates from centralized national training academies in Germany and the United States. |
| Competency-Based Engine Development | Aligns simulation platforms with ICAO Doc 9995 adaptive training frameworks for license renewal. |
Research Methodology
Coverage spans the United States, Germany, Australia, France, and Singapore, with primary inputs from each market combining structured interviews with simulation training directors at ANSP academies, procurement officers at defense ministries, regulatory affairs leads at aviation authorities, and platform engineering heads at integrated suppliers. Secondary validation draws from FAA JO 7110.65 certification documentation, Eurocontrol controller licensing frameworks, ICAO Doc 9995 implementation guidelines, and ANSP capital expenditure disclosures. Bottom-up installation counts and top-down procurement budget analysis triangulate market sizing across civilian and military buyer segments.
Rate-of-change decomposition separates volume expansion from value-per-unit shifts as scenario-based simulation gives way to synthetic environment platforms and virtual reality training methods gain share against instructor-led formats. Segmentation dimensions modeled include simulation architecture type, training method modality, operational domain application, and end-user buyer category, with additional cross-cutting analysis of certification tier and service bundling intensity. CAGRs derive from facility-level procurement pipeline tracking and regulatory deadline alignment across the projection horizon, incorporating FAA NextGen modernization mandates and EU SESAR deployment timelines as demand timing inputs.
The model holds under steady regulatory certification timeline rigidity and sustained ANSP centralized academy procurement concentration; deviation in FAA or Eurocontrol validation acceleration, or fragmentation toward airline and flight school decentralized purchasing, would shift replacement cycle assumptions and vendor concentration metrics. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Simulation and Training
Military Simulation and Training Market
Simulation and Training
Civil Aviation Simulator Market
Simulation and Training
Live Laser-Based Training and Simulation Platforms Market
Simulation and Training
Military Simulation Software Market
Simulation and Training
Military Vehicles and Aircraft Simulations Market
Simulation and Training
Trainer Aircraft Market
Simulation and Training
Middle East and Africa Ship Bridge Simulators Market
Simulation and Training
Europe Flight Training and Simulation Market
Simulation and Training
GNSS Simulators Market
Simulation and Training
Flight Simulator Market
Simulation and Training
UAV Flight Training and Simulation Market
Simulation and Training
Flight Simulation Training Device Market
Simulation and Training
Military Simulation Virtual Training Market
Simulation and Training
Simulators Market
Simulation and Training
Helicopter Simulator Market
Simulation and Training
Military Aerospace Simulation and Training Market