
 Southeast Asia Business Jet Market | 2026-2036
Southeast Asia Business Jet Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Business Jet Market Analytics
Digital avionics integration with predictive maintenance platforms is reconfiguring how business jet fleets are managed across Southeast Asian operators. Bombardier Inc leverages its Global family connectivity suites to anchor premium long-range positioning in the region. Gulfstream Aerospace Corporation sustains technology leadership through advanced flight deck architectures and cabin management systems. Embraer SA competes aggressively in the light-to-midsize tier with cost-efficient airframes tailored to archipelago geography.
A business jet denotes a fixed-wing aircraft designed for private or corporate transport, typically featuring pressurized cabins, turbofan propulsion, and maximum takeoff weights below 100,000 pounds for runway-constrained Southeast Asian airports. These aircraft serve time-sensitive executives, government officials, and charter clients requiring point-to-point connectivity across fragmented island and mainland topographies. Light Jets occupy the volume tier due to lower acquisition costs and access to shorter runways at secondary Indonesian and Philippine airports. Charter Services command expanding share as asset-light operators avoid capital intensity while serving episodic demand from family offices and transient corporate users. Midsize Jets capture margin concentration by balancing range capability with operational economics on the Singapore-Jakarta and Bangkok-Hanoi corridors.
Indonesia's Directorate General of Civil Aviation, Malaysia's Civil Aviation Authority, and Singapore's Civil Aviation Authority enforce airworthiness and operational standards that shape fleet modernization timelines and import certification pathways. The Association of Southeast Asian Nations Single Aviation Market framework progressively liberalizes cross-border charter rights, altering base location strategies for fleet operators. Stakeholders must monitor sustainable aviation fuel infrastructure buildout at Seletar, Subang, and Halim Perdanakusuma airports to anticipate compliance cost trajectories and network planning decisions.
Market Dynamics
Sustainable aviation fuel mandates from ICAO's Carbon Offsetting and Reduction Scheme are forcing fleet operators across Indonesia, Malaysia, and Thailand to accelerate retrofit timelines and renegotiate fuel supply contracts at secondary airports.
Growth Catalysts
- Fractional Ownership Models:Ultra-high-net-worth individuals and family offices in Jakarta, Bangkok, and Singapore are expanding shared-asset structures to reduce capital intensity while maintaining schedule flexibility.
- ASEAN Single Aviation Market:Progressive liberalization of cross-border charter rights is altering base location strategies for operators seeking network efficiency across archipelago and mainland corridors.
- Predictive Maintenance Platforms:Digital avionics integration with AI-driven diagnostics is compressing aircraft downtime and extending maintenance intervals for regional fleet managers.
Market Restraints
- Sustainable Aviation Fuel Infrastructure Gaps:Limited SAF production capacity and distribution networks at Seletar, Subang, and Halim Perdanakusuma airports constrain compliance pathways and inflate operating costs.
- Runway-Constrained Airport Access:Maximum takeoff weight limitations below 100,000 pounds at secondary Indonesian and Philippine airports restrict aircraft selection and route economics.
- Import Certification Complexity:Divergent airworthiness standards between Indonesia's Directorate General of Civil Aviation, Malaysia's Civil Aviation Authority, and Singapore's Civil Aviation Authority fragment fleet standardization timelines.
Strategic Opportunities
- Philippine Secondary Airport Penetration:Light jet operators can capture unmet demand from mining executives and provincial government officials at Cebu, Davao, and Clark hubs with shorter runway infrastructure.
- Biofuel-Compatible Engine Retrofits:ICAO CORSIA compliance deadlines are creating aftermarket service revenue streams for maintenance providers capable of airframe modification and engine recertification.
- Charter Service Platform Digitization:Mobile-first booking interfaces and dynamic empty-leg optimization are displacing traditional broker networks among transient corporate users and family offices.
Industry Challenges
- Certified Aviation Maintenance Technician Scarcity:Indonesia, Malaysia, and Thailand face acute shortages of airframe and powerplant mechanics qualified on next-generation turbofan architectures and glass cockpit systems.
- Cross-Border Operational Permit Delays:Harmonization gaps between national civil aviation authorities extend flight authorization timelines for multi-country charter itineraries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Business Jet Market |
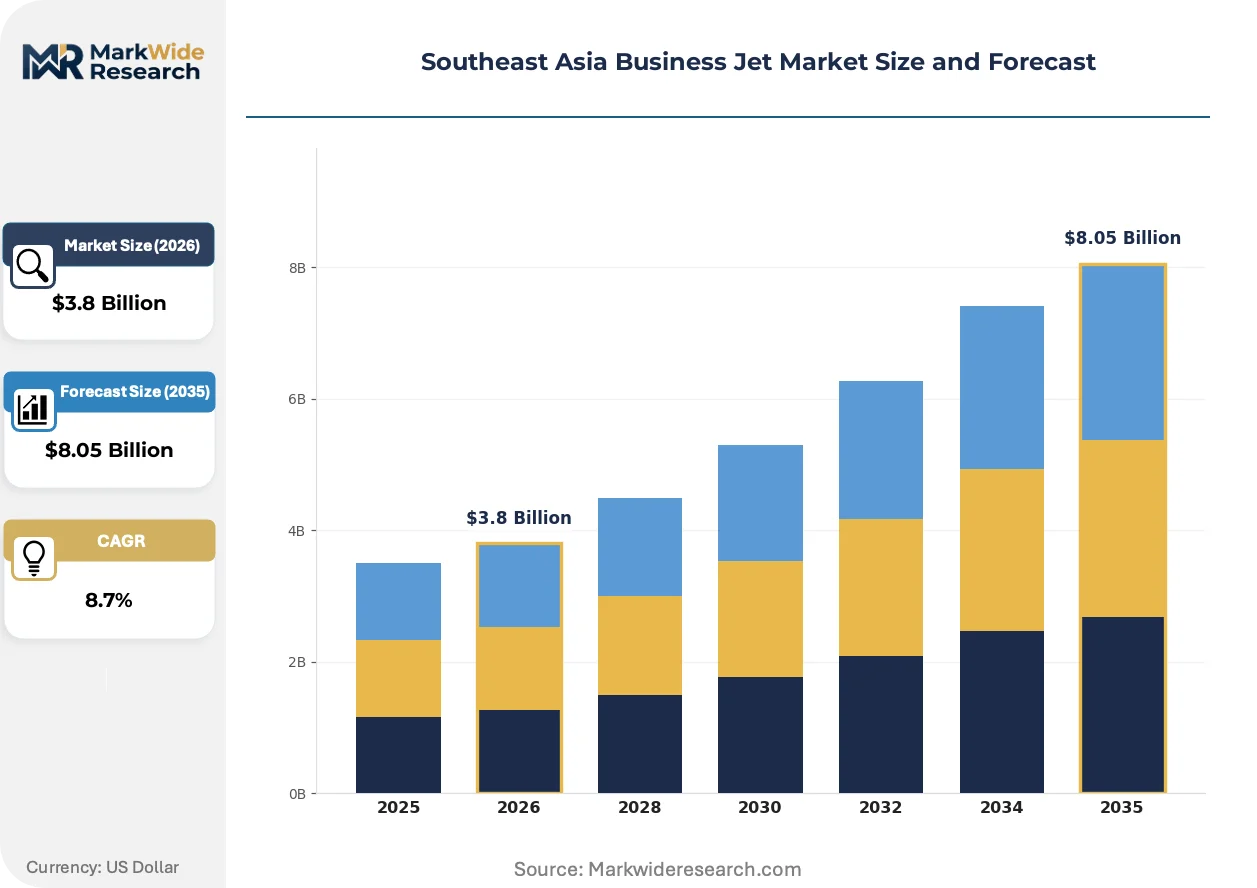
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Light Jets, Midsize Jets, Large Jets, Very Large Jets End User: Corporate, Government, Private, Charter Service Type: Fractional Ownership, Charter Services, Whole Aircraft Management, Jet Card Programs Fuel Type: Jet A, Jet A-1, Biofuels, Others |
| Companies Covered | Airbus SE, Bombardier Inc, Textron Inc, The Boeing Company, Honda Aircraft Company, Dassault Aviation SA, Embraer SA, Gulfstream Aerospace Corporation, General Dynamics Corporation, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Business Jet Market Evolving Landscape
Connectivity architecture and fuel propulsion systems are undergoing simultaneous transformation across Southeast Asian business aviation, compressing legacy operational models while opening new service categories.
Connected cabin management systems are hybridizing passenger experience expectations with ground-based digital services. Charter clients and corporate flight departments now demand seamless video conferencing, real-time data synchronization, and predictive concierge integration. This technology convergence is compressing differentiation timelines for operators still reliant on basic satellite communications.
Singapore's Civil Aviation Authority and Indonesia's Directorate General of Civil Aviation are tightening emissions monitoring protocols ahead of full ICAO CORSIA implementation. Operators must now document fuel burn coefficients and carbon offset purchases across international legs. Midsize jet fleets on the Singapore-Jakarta corridor face the steepest compliance cost trajectories as they balance range requirements with sustainability mandates.
Asset-light charter utilization is displacing traditional whole-aircraft ownership among family offices and mid-cap corporations. Episodic demand patterns favor pay-per-flight-hour structures over fixed depreciation burdens. Thailand's Bangkok-Don Mueang cluster and Indonesia's Surabaya secondary hub exhibit the most pronounced behavioral shifts, with transient users prioritizing schedule flexibility over asset control.
Southeast Asia Business Jet Market Segmentation
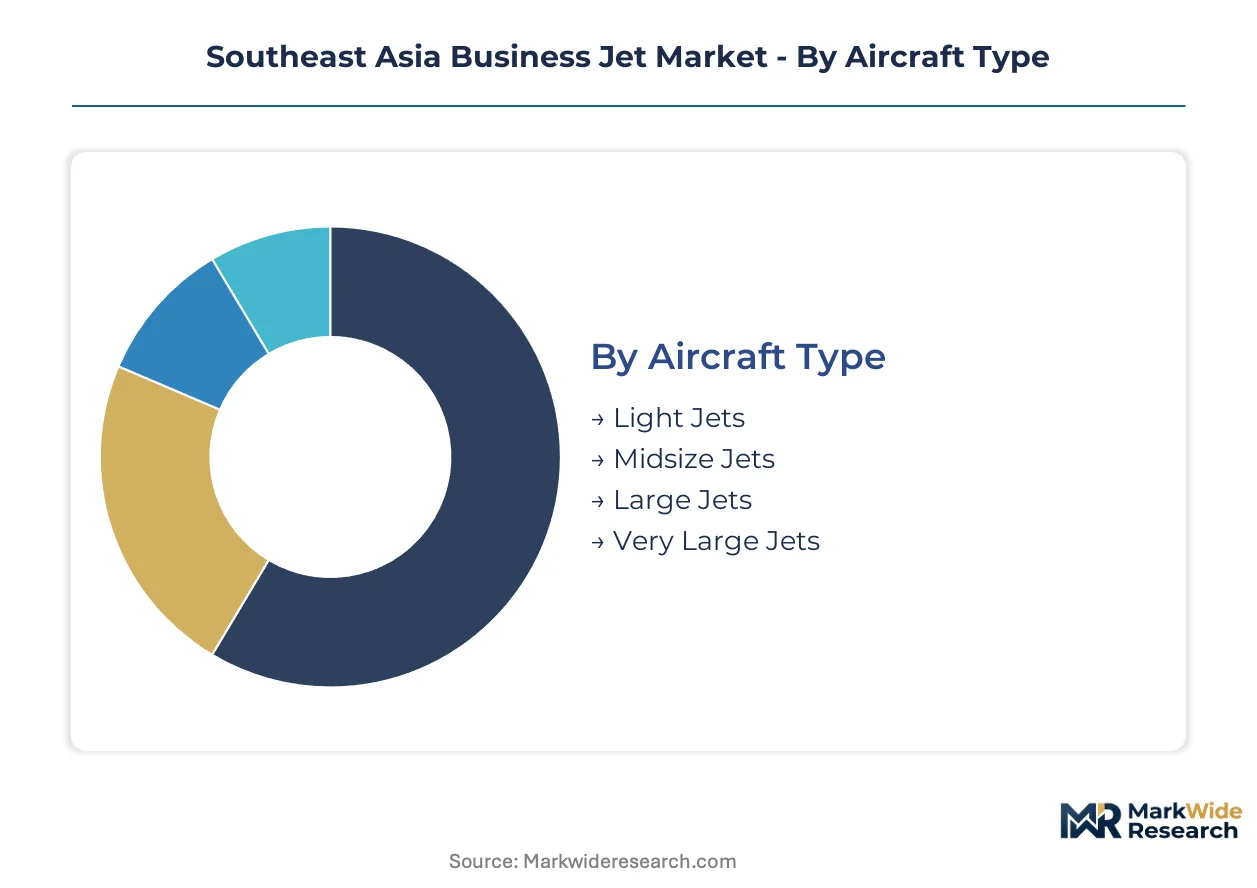
Segmentation in Southeast Asian business aviation reveals distinct operational economics across archipelago geography and regulatory fragmentation. Fleet managers and charter operators configure assets differently across Jakarta-Surabaya corridors versus Singapore-Seletar hubs based on runway constraints and fuel infrastructure maturity.
Aircraft Type:
After-sales service intensity varies dramatically across weight classes, with avionics retrofit cycles and engine overhaul intervals creating divergent revenue streams for maintenance providers.
- Light Jets:Maximum takeoff weights below 12,500 pounds enable access to secondary Indonesian and Philippine airports with sub-5,000-foot runways. Demand concentrates among mining executives and provincial government officials at Cebu, Davao, and Clark hubs where commercial service remains sparse.
- Midsize Jets:Pressurized cabins and 2,000-3,000 nautical mile range capability dominate the Singapore-Jakarta and Bangkok-Hanoi corridors. Corporate flight departments favor this tier for balancing operational economics against cabin productivity requirements.
- Large Jets:Transcontinental range suits inter-ASEAN missions requiring full standing headroom and lie-flat sleeping configurations. Indonesia's ultra-high-net-worth families deploy these aircraft for multi-leg itineraries across the archipelago.
- Very Large Jets:Ultra-long-range platforms serve head-of-state transport and sovereign wealth fund principals with customized cabin interiors.
Light Jets holds the largest share; momentum sits with Midsize Jets.
End User:
Procurement authority and flight-hour utilization patterns split sharply between asset owners and episodic consumers across the region's family office clusters.
- Corporate:Flight departments at Indonesian conglomerates and Singaporean multinational headquarters manage owned or managed fleets for executive time-sensitivity. These operators prioritize schedule control over capital efficiency.
- Private:Individual ultra-high-net-worth owners in Bangkok and Jakarta maintain whole-aircraft assets for personal and family mobility, often with dedicated flight crew employment.
- Government:State-owned enterprises and ministry transport units across Malaysia and Thailand operate specialized configurations for official delegation movement.
- Charter:Transient demand from mid-cap corporations and family offices without flight department infrastructure drives pay-per-use access at Seletar and Don Mueang clusters.
Corporate users dominate fleet ownership; Charter is expanding most quickly among asset-light demand profiles.
Service Type:
Capital deployment strategies range from full asset ownership to hour-based access contracts, reshaping operator business models across the region.
- Fractional Ownership:Shared-asset structures reduce capital intensity for Jakarta and Bangkok family offices while preserving schedule flexibility through guaranteed availability programs.
- Charter Services:On-demand access without depreciation burden attracts episodic users at Thailand's Bangkok-Don Mueang cluster and Indonesia's Surabaya secondary hub.
- Whole Aircraft Management:Third-party operators handle crewing, maintenance, and regulatory compliance for owners seeking operational outsourcing.
- Jet Card Programs:Pre-purchased hour blocks with fixed pricing appeal to corporate travel managers seeking budget predictability.
Charter Services commands expanding volume; Fractional Ownership shows steepest expansion trajectory among ultra-high-net-worth segments.
Fuel Type:
Compliance cost trajectories diverge based on ICAO CORSIA implementation timelines and local production capacity buildout.
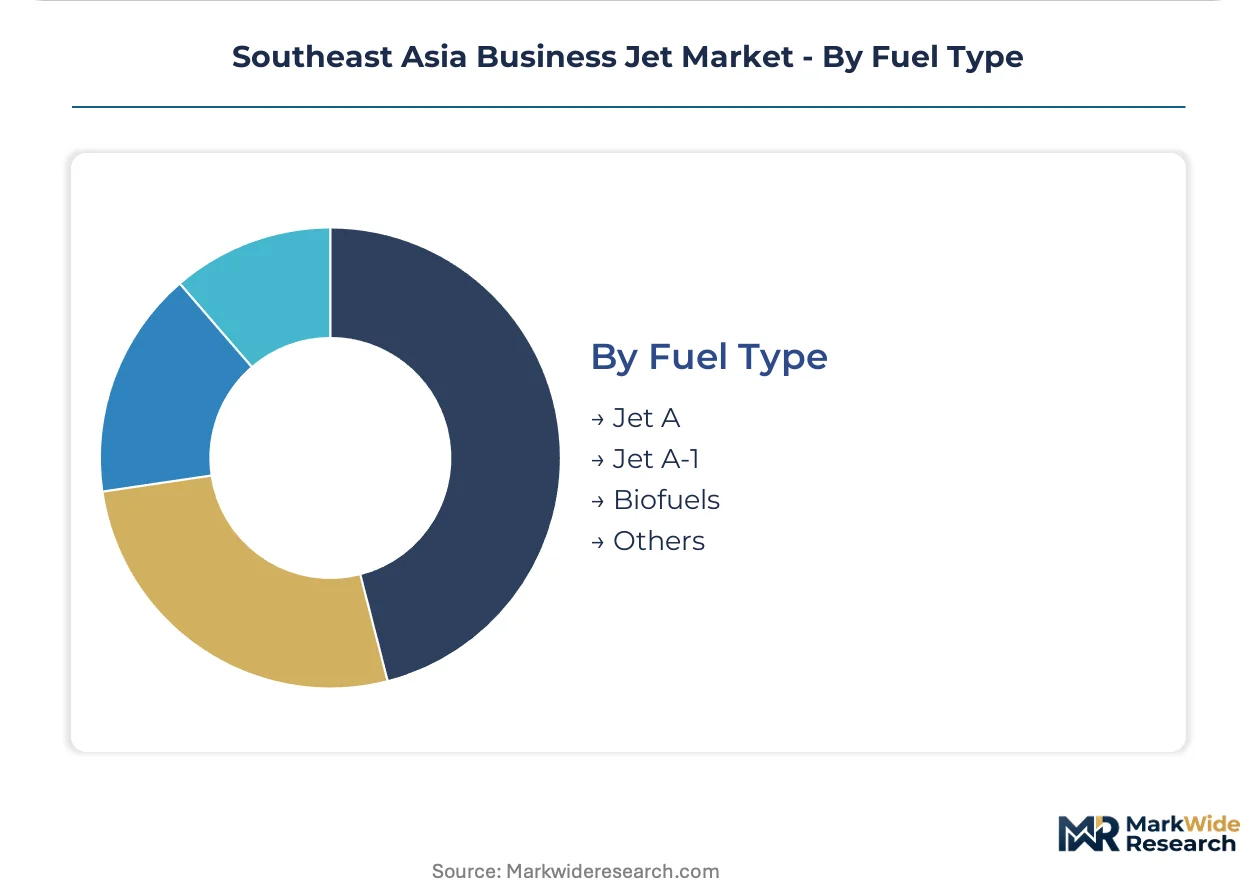
- Jet A:Standard kerosene-based turbine fuel dominates at established hubs with mature distribution infrastructure.
- Jet A-1:Lower freeze-point specification supports high-altitude operations and cold-weather routes across northern ASEAN corridors.
- Biofuels:Sustainable aviation fuel mandates from Indonesia's Directorate General of Civil Aviation and Singapore's Civil Aviation Authority are compelling retrofit investment and supply contract renegotiation.
- Others:Synthetic and emerging alternative formulations remain experimental at regional scale.
Jet A-1 retains operational dominance; Biofuels is gaining share fastest on regulatory compliance pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ultra-high-net-worth individuals and family offices concentrate in Indonesia, Singapore, and Thailand, driving fractional ownership and charter demand across archipelago corridors and mainland hubs. Jakarta-Surabaya connectivity, Singapore's Seletar Aviation Hub, and Bangkok-Don Mueang clusters anchor operational deployment for fleet operators.
Indonesia
Mining executives and provincial government officials generate sustained light jet demand at Cebu, Davao, and Clark hubs with sub-5,000-foot runways. Indonesia's Directorate General of Civil Aviation enforces airworthiness standards that shape import certification timelines and fleet modernization pathways. The Jakarta-Surabaya corridor concentrates corporate flight department activity, with secondary airport penetration expanding at Surabaya and Halim Perdanakusuma.
Singapore
Multinational headquarters and sovereign wealth fund principals anchor premium long-range jet utilization for inter-ASEAN missions. Singapore's Civil Aviation Authority mandates emissions monitoring protocols ahead of full ICAO CORSIA implementation, compelling fuel burn documentation. Seletar Aviation Hub functions as the region's primary maintenance and base location strategy node for cross-border charter operators.
Thailand
Transient corporate users and mid-cap corporations exhibit pronounced behavioral shifts toward asset-light charter structures at Bangkok-Don Mueang. Thailand's Civil Aviation Authority regulates operational standards that influence fleet configuration decisions for mixed-use operators. The Bangkok-Don Mueang cluster serves episodic demand from family offices prioritizing schedule flexibility over fixed depreciation burdens.
Malaysia
State-owned enterprises and ministry transport units operate specialized configurations for official delegation movement across peninsular and Borneo corridors. Malaysia's Civil Aviation Authority maintains divergent airworthiness standards that fragment regional fleet standardization timelines. Subang Airport anchors maintenance provider concentration, with aftermarket service revenue streams emerging from biofuel-compatible engine retrofit demand.
Philippines
Mining executives and provincial government officials at Cebu, Davao, and Clark hubs drive unmet light jet demand where commercial service remains sparse. The country's national civil aviation regulator shapes import certification complexity alongside Indonesian and Malaysian counterparts. Secondary airport penetration accelerates as operators exploit shorter runway infrastructure for archipelago point-to-point connectivity.
Southeast Asia Business Jet Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a consolidated structure where long-range platform manufacturers anchor premium positioning against cost-efficient airframe specialists. The vendor base stratifies into three archetypes: full-service OEMs with integrated aftermarket networks, regional specialists tailoring airframes to archipelago geography, and charter platform operators displacing traditional broker networks. Dominant competitive moves include strategic partnerships for sustainable aviation fuel supply contracts and portfolio diversification into fractional ownership program management.
Within the full-service OEM tier, Bombardier Inc and Gulfstream Aerospace Corporation exemplify channel-controlling players leveraging connectivity suites and flight deck architectures to anchor premium positioning. Embraer SA occupies a position as the cost-efficient airframe specialist competing aggressively in the light-to-midsize tier. These three manufacturers represent divergent strategic archetypes: Bombardier and Gulfstream emphasize technology leadership and cabin management integration, while Embraer targets operational economics for runway-constrained Southeast Asian airports.
| Leading Market Players |
|---|
| Airbus SE |
| Bombardier Inc |
| Textron Inc |
| The Boeing Company |
| Honda Aircraft Company |
| Dassault Aviation SA |
| Embraer SA |
| Gulfstream Aerospace Corporation |
| General Dynamics Corporation |
| Others |
Value Network & Pricing Analysis
Overcapacity at Seletar Aviation Hub is compressing charter hourly rates while simultaneously pressuring maintenance providers to absorb retrofit costs for ICAO CORSIA compliance, creating divergent margin trajectories across fleet operators and service vendors.
Pricing Analysis
Cost-plus contracts with Jet A-1 indexation dominate fuel provisioning agreements between Indonesian operators and Singapore-based suppliers. Three-tier pricing structure across premium long-range, standard midsize, and economy light jet segments reflects certification tier and after-sales service bundling. Pricing pressure stems from asset-light charter platforms undercutting traditional whole-aircraft ownership models. Mid-cap corporations exhibit highest price sensitivity, while sovereign wealth fund principals show minimal elasticity.
Supply Chain Analysis
Upstream feedstock for sustainable aviation fuel draws from Malaysian palm oil derivatives, Indonesian jatropha cultivation, and Singaporean waste-to-fuel processing facilities. Turbofan engines and avionics suites hinge on Japanese precision manufacturing, US flight control systems, and European cabin management components. Single-source vulnerability concentrates in glass cockpit system suppliers serving the archipelago's retrofit demand. Distribution runs through Seletar's integrated maintenance clusters and Jakarta's fragmented broker networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fractional ownership platforms and premium commercial aviation upgrades present substitution threats that incumbent business jet operators must navigate through service differentiation and regulatory compliance acceleration.
For Market Incumbents: Pre-empt charter platform displacement by securing exclusive SAF supply contracts at Halim Perdanakusuma and Subang airports while embedding predictive maintenance diagnostics into whole-aircraft management offerings. Backward integration into biofuel-compatible engine recertification capabilities defends margin position against emerging maintenance specialists. For New Entrants and Emerging Players: Philippine secondary airport penetration at Cebu, Davao, and Clark hubs offers the most penetrable white-space for light jet operators serving mining executives and provincial government officials. Mobile-first booking interfaces with dynamic empty-leg optimization provide a direct go-to-market angle against traditional broker networks. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across charter platform digitization as software-as-a-service models displace asset-heavy fleet ownership. Acquisition targets should demonstrate installed base access across Indonesia's Directorate General of Civil Aviation certification pathways. Monitor SAF infrastructure buildout timelines at Seletar as the inflection indicator for compliance cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Sustainable Aviation Fuel Supply Agreement | Secures CORSIA compliance pathways at Seletar and Halim Perdanakusuma airports ahead of mandate deadlines. |
| Predictive Maintenance Platform Integration | Compresses aircraft downtime for Indonesian fleet managers through AI-driven avionics diagnostics. |
| Secondary Airport Network Expansion | Captures unmet demand from Philippine mining executives at runway-constrained Cebu and Davao hubs. |
| Fractional Ownership Program Launch | Reduces capital intensity for Bangkok and Jakarta family offices while preserving schedule flexibility. |
| Biofuel-Compatible Engine Retrofit Service | Generates aftermarket revenue from ICAO CORSIA-driven airframe modification and recertification demand. |
Research Methodology
The analysis maps light jet, midsize jet, large jet, and very large jet segments, each validated through fleet managers at Indonesian conglomerates, charter brokers at Singapore's Seletar hub, maintenance directors at Malaysian MRO facilities, and regulatory affairs leads across ASEAN civil aviation authorities. Primary interview findings triangulate against Directorate General of Civil Aviation airworthiness filings, Singapore Civil Aviation Authority emissions protocols, customs import records for turbine aircraft, and ICAO CORSIA implementation documentation. Bottom-up aircraft deployment counts reconcile with top-down regional GDP and ultra-high-net-worth individual growth projections.
Assumption sets held fuel price volatility and regulatory implementation timelines fixed while varying fractional ownership adoption rates and SAF infrastructure buildout pace across the projection horizon. Segmentation dimensions include aircraft type, end user category, service model, and fuel specification tier alongside archipelago geography runway constraints. CAGRs derive from installed base evolution and replacement cycle analysis. Forecast inputs incorporate ASEAN Single Aviation Market liberalization trajectories and ICAO CORSIA compliance deadline enforcement intensity.
The forecast holds incumbent behavior within observed patterns; aggressive fleet modernization acceleration by sovereign wealth fund principals or sudden SAF subsidy withdrawals by Indonesian regulators would shift outcomes. Cross-checking against IATA regional traffic forecasts and Business Aviation Asia Pacific fleet registries is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aviation Market
Aircraft
Aircraft Aerostructures Market
Aircraft
Commercial Aircraft Aerostructures Market
Aircraft
Global Commercial Aircraft Disassembly Market
Aircraft
Special Mission Aircraft Market
Aircraft
Light and Very Light Jets Market
Aircraft
Asia-Pacific Light and Very Light Jets Market
Aircraft
America Freighter Aircraft Market
Aircraft
Latin America Commercial Aircraft Market
Aircraft
Aircraft Door Market
Aircraft
Asia-Pacific Turboprop Aircraft Market
Aircraft
Aircraft Windshield Wiper and Washer System Market
Aircraft
South Korea Aerospace and Defense Market
Aircraft
Zero-Emission Aircraft Market
Aircraft
US Aircraft Windshield Wiper and Washer System Market
Aircraft
Helicopter Flight Control Systems Market