
 Global Cocoa Ingredients Market | 2026-2036
Global Cocoa Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cocoa Ingredients Market Foresight
Multi-origin sourcing is recalibrating how cocoa processors secure bean supply across West Africa and Southeast Asia. Barry Callebaut leverages its integrated grinding network to control quality from bean to butter. Cargill anchors its position through direct farmer financing programs in origin countries. Olam International competes via sustainability certification coverage that spans multiple equatorial origins.
Cocoa ingredients comprise processed derivatives from fermented and dried Theobroma cacao beans, including powder with residual fat content of 10-12 percent, butter with triglyceride profiles dominated by palmitic-stearic-oleic arrangements, and liquor with particle sizes below 30 microns for industrial chocolate production. Cocoa butter commands premium positioning in confectionery applications where tempering stability and melt-point precision determine product quality. Cocoa powder generates volume throughput across bakery and beverage channels where cost efficiency outweighs fat-content requirements. The liquid form dominates industrial procurement for chocolate manufacturers operating continuous enrobing lines.
The FDA maintains identity standards for chocolate products under 21 CFR 163, while the EU enforces EUDR traceability mandates and F-Gas Regulation impacts processing equipment standards. EFSA evaluations of cadmium limits in cocoa products directly constrain sourcing from specific volcanic-soil origins. Stakeholders must monitor regulatory divergence between EU and US contaminant thresholds when configuring multi-market production strategies.
Market Dynamics
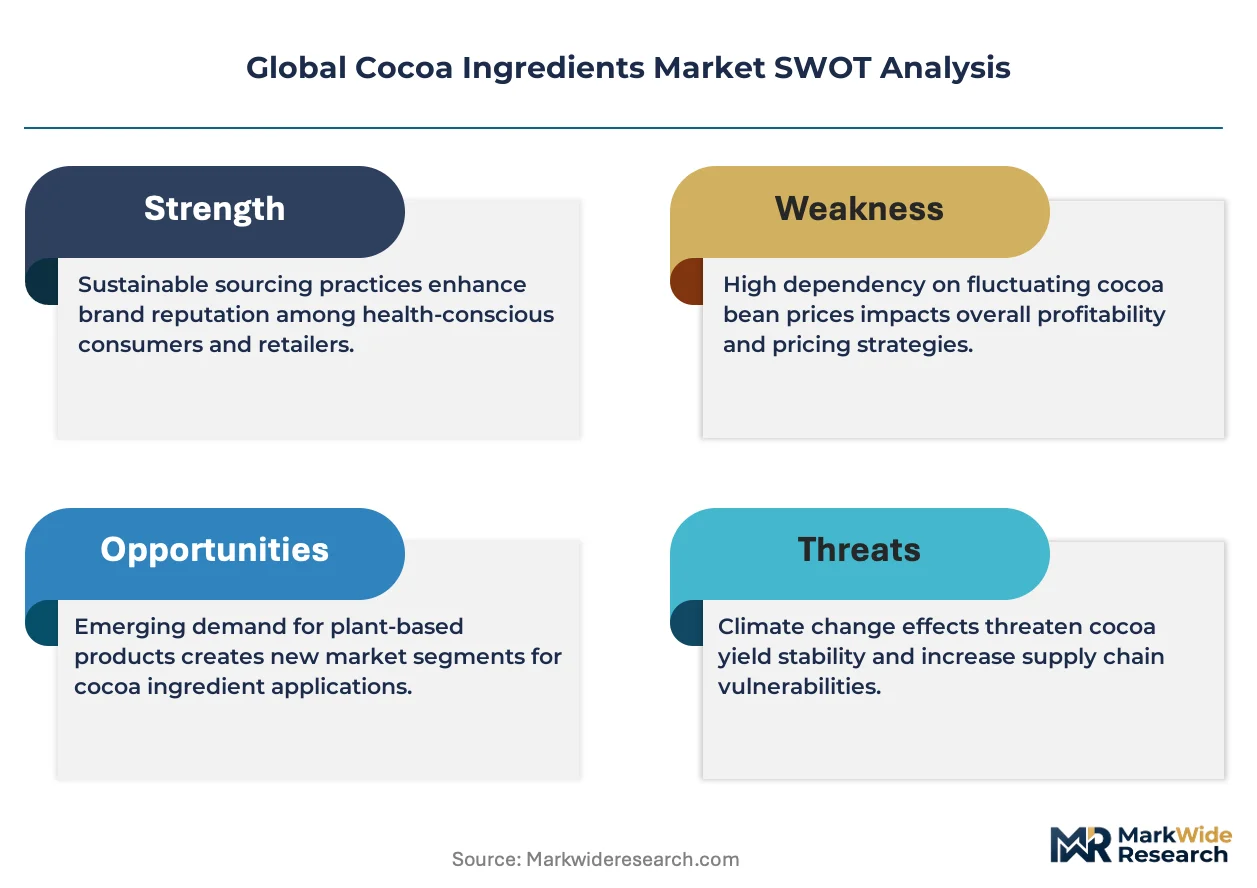
The EU Deforestation Regulation is compressing traceability timelines across cocoa supply chains while simultaneously elevating compliance costs for processors sourcing from West African origins. This regulatory pressure is forcing simultaneous investment in satellite monitoring infrastructure and farmer-facing digital verification systems.
Growth Catalysts
- Clean-label confectionery reformulation:Food manufacturers are eliminating synthetic emulsifiers in favor of cocoa butter's natural fat crystallization properties, expanding industrial demand for deodorized butter grades.
- EU Deforestation Regulation:Mandatory geolocation verification for all cocoa entering European processing facilities is accelerating adoption of farm-level digital traceability platforms.
- Bean-to-bar verticals:Specialty chocolate makers in North America and Western Europe are contracting directly for single-origin liquor with defined fermentation protocols, bypassing commodity exchanges.
Market Restraints
- Input cost volatility:Cocoa bean prices swing with West African precipitation patterns and port logistics disruptions, compressing processor margins on fixed-price butter contracts.
- Supply concentration risk:Over 60 percent of global bean output originates from Côte d'Ivoire and Ghana combined, creating systemic vulnerability to regional political instability or disease outbreaks.
- Cadmium accumulation:Volcanic soil chemistry in Latin American origins produces beans exceeding EFSA contamination thresholds, excluding entire origin countries from EU-bound supply.
Strategic Opportunities
- Indonesia and Vietnam expansion:Southeast Asian origins outside traditional West African supply zones offer cadmium-compliant beans with shorter shipping routes to Asian processing hubs.
- Plant-based dairy analogs:Cocoa butter's fat profile matches the crystallization requirements of vegan cheese and ice cream applications, opening formulation contracts with alternative protein brands.
- Carbon credit stacking:Agroforestry certification under Verra standards enables processors to monetize shade-grown cocoa carbon sequestration separately from commodity sales.
Industry Challenges
- Traceability systems integration:Merging farm-level geolocation data from multiple origin-country platforms into unified ERP systems requires custom API development and ongoing data validation.
- Grinding capacity reconfiguration:Existing European processing facilities require retrofitting for segregated handling of EUDR-compliant versus conventional bean streams, demanding significant capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cocoa Ingredients Market |
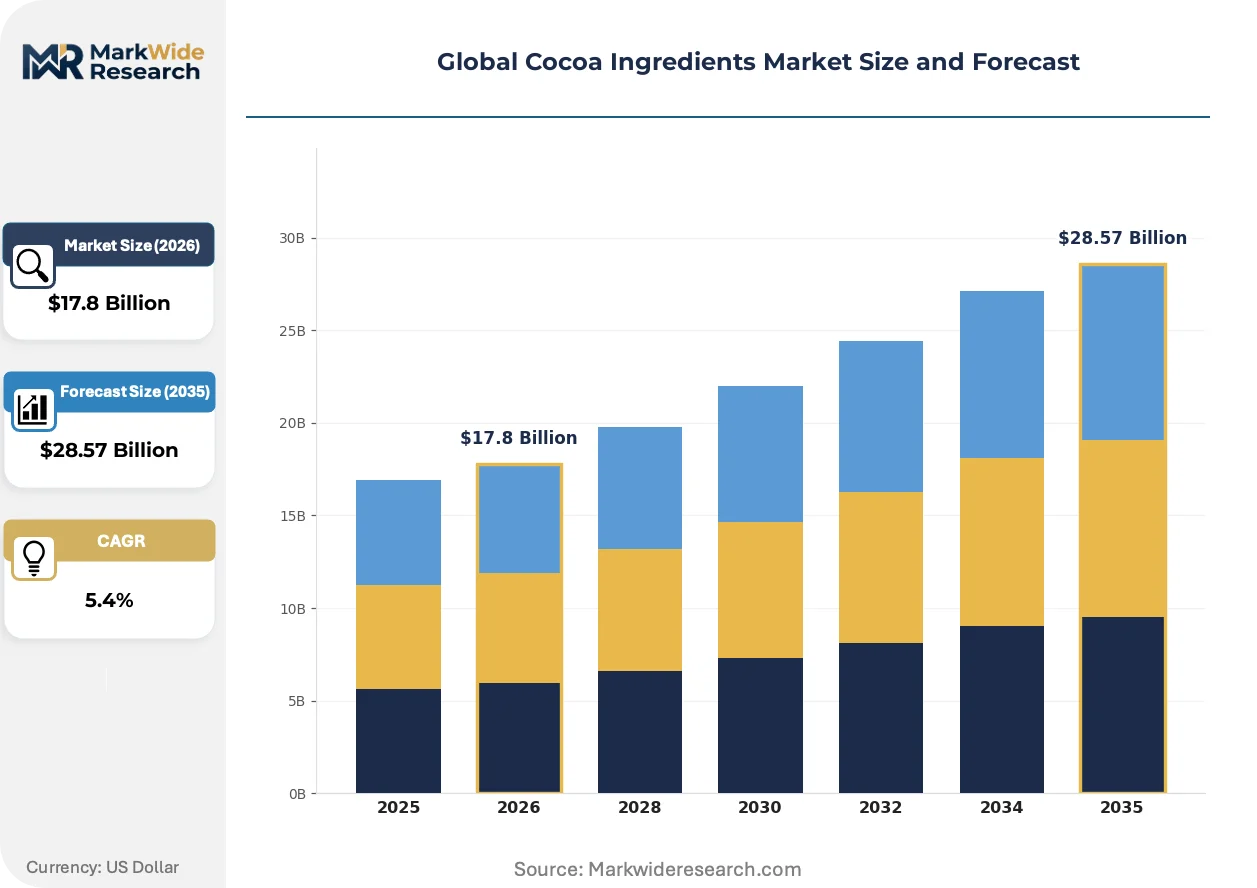
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $28.57 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cocoa Powder, Cocoa Butter, Cocoa Liquor, Cocoa Mass Application: Confectionery, Bakery, Beverages, Dairy Products, Personal Care End User: Food Manufacturers, Cosmetic Companies, Beverage Producers, Nutraceutical Firms Form: Liquid, Solid, Paste, Powdered |
| Companies Covered | Barry Callebaut, Cargill, Olam International, Archer Daniels Midland Company, Mars, Blommer Chocolate Company, Cocoa Processing Company, United Cocoa Processor, Guan Chong Berhad, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cocoa Ingredients Market Shifts & Advancements
Processing technology and regulatory compliance systems are converging to reshape how cocoa derivatives move from origin farms to finished confectionery. Three distinct vectors are reconfiguring competitive advantage across the value chain.
Precision fermentation for cocoa butter alternatives is expanding into commercial-scale production. Cellular agriculture startups in California and Singapore are cultivating yeast-derived triglycerides that replicate cocoa butter's polymorphic crystallization behavior. Industrial chocolate manufacturers in Germany and Switzerland are piloting these alternatives in compound coatings where tempering precision matters less than cost stability.
REACH authorization requirements for processing aids are tightening specifications for lecithin and other emulsifiers used in cocoa powder agglomeration. The European Chemicals Agency is requiring updated safety dossiers for phospholipid derivatives, forcing powder processors to reformulate instant beverage applications or switch to certified-clean-label alternatives. Swiss and Dutch grinding facilities are absorbing the bulk of compliance costs through dedicated regulatory affairs teams.
Confectionery brands are consolidating supplier relationships around integrated bean-to-ingredient providers capable of delivering simultaneous butter, liquor, and powder volumes under unified certification. This preference compression is marginalizing standalone cocoa powder traders and favoring processors with captive grinding networks across multiple origins. The shift is most pronounced among North American premium chocolate manufacturers seeking single-counterparty accountability for EUDR compliance.
Global Cocoa Ingredients Market Segmentation
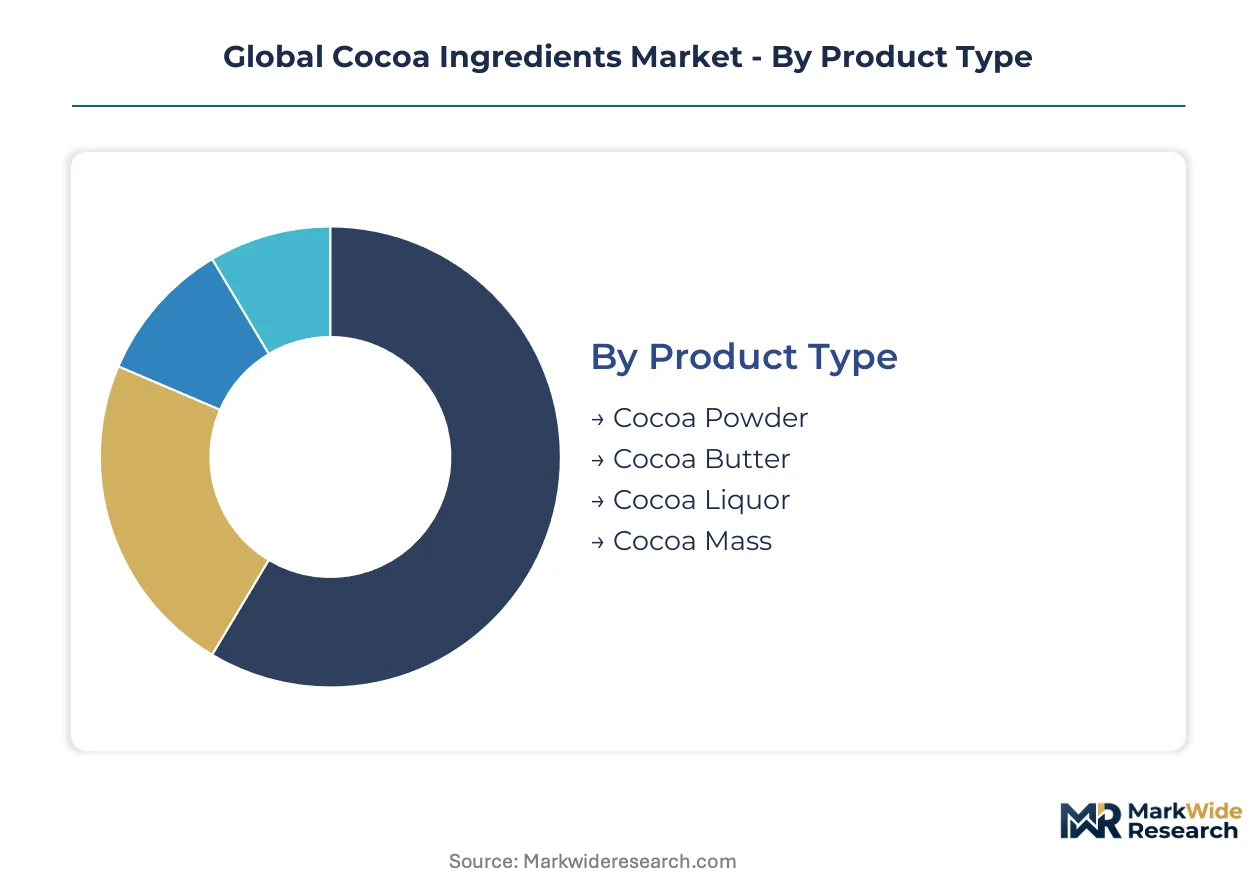
Cocoa ingredients demand fragments across multiple technical specifications and end-use requirements. Processors configure grinding lines differently depending on which product-application matrix commands their capacity.
Product Type:
Capital deployment varies sharply across grinding configurations, with butter extraction requiring the most sophisticated pressing infrastructure.
- Cocoa Butter:Deodorized triglyceride fractions with palmitic-stearic-oleic profiles dominate confectionery tempering applications. German and Swiss chocolate manufacturers contract for defined polymorphic stability grades, paying premiums for consistent melt-point precision that eliminates bloom defects in finished products.
- Cocoa Powder:Residual fat content of 10-12 percent after pressing determines baking and beverage suitability. North American bakery chains and instant drink mixers in Southeast Asia absorb volume throughput where cost efficiency outweighs fat-content specifications, though REACH authorization pressures on lecithin emulsifiers are forcing reformulation investments.
- Cocoa Liquor:Particle sizes below 30 microns serve industrial chocolate enrobing lines.
- Cocoa Mass:Unrefined whole-bean paste supplies bean-to-bar craft producers.
Cocoa butter absorbs the bulk of installed capacity; cocoa powder is expanding most quickly.
Application:
Customer procurement patterns separate commodity-scale buyers from specification-sensitive formulators.
- Confectionery:Tempering-stable butter grades with defined crystallization curves command premium positioning. Belgian and Italian praline houses specify single-origin liquor with fermentation protocol documentation, bypassing commodity exchanges for traceability compliance under EUDR mandates.
- Bakery:Cost-optimized powder grades with alkalized color profiles serve industrial cookie and cake manufacturers.
- Beverages:Agglomerated instant cocoa requires lecithin emulsification meeting EFSA safety dossier requirements.
- Dairy Products:Cocoa butter's fat crystallization properties match vegan ice cream and cheese analog formulation needs.
- Personal Care:Cosmetic-grade butter with heavy metal certification supplies skincare formulators.
Confectionery retains the dominant share of value throughput; dairy applications are climbing the fastest.
End User:
Scale and certification requirements divide procurement behavior across customer categories.
- Food Manufacturers:Integrated butter-liquor-powder contracts with unified EUDR certification dominate procurement. North American premium chocolate brands consolidate supplier relationships around single-counterparty accountability for geolocation verification.
- Cosmetic Companies:Heavy metal and microbiological specifications exceed food-grade requirements.
- Beverage Producers:Agglomeration performance and dispersibility determine powder sourcing.
- Nutraceutical Firms:Flavanol retention specifications constrain processing temperature profiles.
Food manufacturers command the largest contract volumes; nutraceutical firms are gaining share fastest.
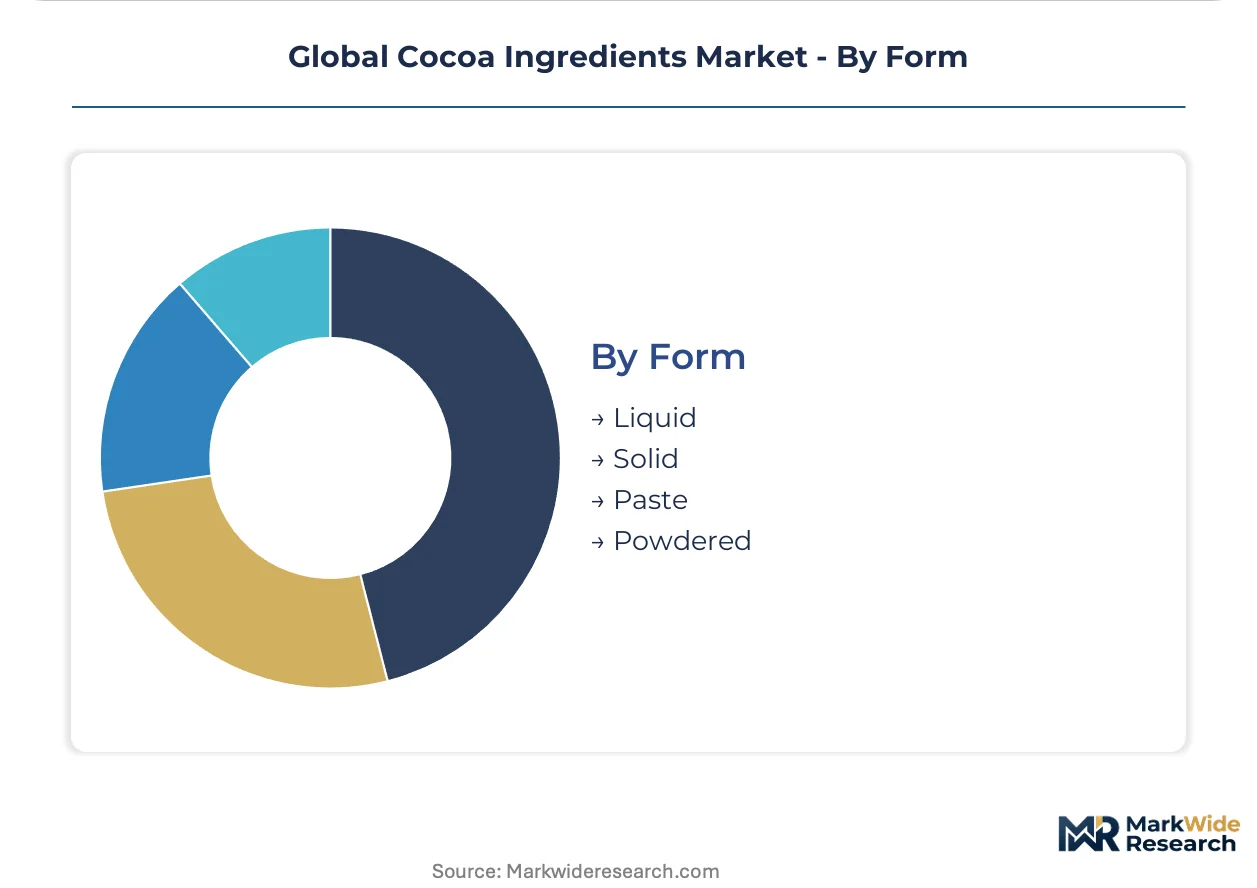
Form:
Physical state determines logistics infrastructure and handling equipment requirements.
- Liquid:Tanker-delivered liquor serves continuous enrobing lines at industrial chocolate plants. Rotterdam and Hamburg processing hubs maintain heated storage for just-in-time delivery to German confectionery manufacturers.
- Solid:Molded butter blocks require tempering equipment at destination facilities.
- Paste:Intermediate viscosity for specialty compound coatings.
- Powdered:Silo storage and pneumatic conveying systems serve high-volume bakery and beverage operations.
Liquid form dominates industrial procurement; powdered form is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chocolate manufacturers in Belgium, Switzerland, and Germany absorb the bulk of premium cocoa butter imports, while Asian processing hubs in Singapore and Malaysia redirect supply chains toward Southeast Asian bean origins to satisfy EUDR cadmium compliance requirements.
Germany
Industrial chocolate manufacturers in Cologne and Hamburg contract for defined polymorphic stability grades of deodorized cocoa butter. The F-Gas Regulation mandates equipment retrofits at processing facilities, compressing capital deployment timelines. The Hamburg-Rotterdam corridor maintains heated liquid liquor storage for just-in-time delivery to confectionery plants.
United States
North American premium chocolate brands consolidate supplier relationships around single-counterparty EUDR accountability. FDA identity standards under 21 CFR 163 govern chocolate product composition, creating regulatory divergence from EU thresholds. The Chicago and Pennsylvania industrial corridors host bean-to-bar craft producers contracting directly for single-origin liquor.
Switzerland
Swiss grinding facilities absorb compliance costs for REACH authorization requirements on lecithin emulsifiers through dedicated regulatory affairs teams. The Bern and Zurich clusters specialize in tempering-stable butter grades for praline houses specifying fermentation protocol documentation. Swissmedic oversight extends to cosmetic-grade butter with heavy metal certification for skincare formulators.
Indonesia
Southeast Asian bean origins offer cadmium-compliant supply with shorter shipping routes to Asian processing hubs. The country's national agricultural regulator enforces sustainability certification alignment with Verra agroforestry standards. Sulawesi and Sumatra farming cooperatives supply beans to Singapore grinding facilities serving Chinese confectionery demand.
Belgium
Belgian praline manufacturers specify single-origin liquor with documented fermentation protocols, bypassing commodity exchanges for EUDR traceability compliance. The ECHA safety dossier requirements for processing aids tighten emulsifier specifications in powder agglomeration. The Brussels-Antwerp industrial zone anchors EU-bound cocoa ingredient distribution.
Global Cocoa Ingredients Market Competitive Landscape
Capacity expansion dominates the current landscape as processors retrofit European facilities for segregated handling of EUDR-compliant versus conventional bean streams. The vendor base concentrates around integrated bean-to-ingredient providers with captive grinding networks across multiple origins. Three archetypes define competitive positioning: integrated grinders controlling quality from bean to butter, agricultural traders leveraging direct farmer financing programs, and sustainability certifiers spanning equatorial origins. M&A activity and geographic diversification into Southeast Asian supply zones constitute the dominant competitive moves.
Among integrated Swiss and Belgian processors, Barry Callebaut and Cargill exemplify the grinder archetype with multi-origin network control. Olam International occupies a position within the sustainability certification tier, representing the trader-certifier hybrid model. These three entities anchor the competitive structure through their respective dominance in quality control, agricultural finance, and certification coverage across West African and Southeast Asian origins.
| Leading Market Players |
|---|
| Barry Callebaut |
| Cargill |
| Olam International |
| Archer Daniels Midland Company |
| Mars |
| Blommer Chocolate Company |
| Cocoa Processing Company |
| United Cocoa Processor |
| Guan Chong Berhad |
| Others |
Supply & Pricing Matrix
EUDR-mandated geolocation verification is compressing procurement timelines and forcing processors to absorb satellite monitoring costs, which in turn stratifies pricing across compliant and non-compliant bean streams. The divergence between certified-origin premiums and conventional commodity benchmarks now reflects traceability infrastructure investment rather than quality differentials alone.
Pricing Analysis
Volume throughput concentrates in standard-grade cocoa powder for bakery and beverage channels, while margin capture sits with deodorized butter grades commanding tempering-stability premiums from Swiss and German chocolate manufacturers. Price differentiation separates EUDR-certified single-origin streams from bulk commodity grades, with fermentation-protocol documentation adding a further tier. Pricing pressure stems from fixed-price butter contracts exposed to bean futures volatility, squeezing processor margins when West African logistics disrupt. Industrial bakery chains exhibit the highest price sensitivity, whereas Belgian praline houses prioritize specification consistency over unit cost.
Supply Chain Analysis
Freight cost differentials between West African and Southeast Asian origins are redirecting procurement toward Indonesian and Vietnamese supply zones for Asian processing hubs. Geographic supply concentration centers on Côte d'Ivoire, Ghana, and Indonesia, with Ecuador and Cameroon serving secondary roles. Raw material dependencies rest on fermented bean quality, alkalization chemicals for powder processing, and lecithin emulsifiers facing REACH authorization pressures. Single-source vulnerability runs through the Abidjan-San Pedro corridor, where port congestion propagates delays to European grinding facilities. Distribution runs through Rotterdam and Hamburg liquid storage terminals for just-in-time delivery to German and Swiss confectionery plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Grinding capacity constraints in EUDR-compliant European facilities are propping ingredient pricing premiums, as retrofit timelines lag regulatory enforcement deadlines. Supply scarcity at origin—exacerbated by cadmium exclusions and traceability bottlenecks—sustains processor bargaining power despite downstream consolidation.
For Market Incumbents: Deploy satellite-verified farm mapping to lock origin-country supply relationships before competitor infrastructure deployment accelerates. Backward integration into Sulawesi and Sumatra farming cooperatives secures cadmium-compliant volumes outside West African concentration risk. Grinding capacity addition in Singapore and Malaysia captures Asian confectionery demand growth while shortening shipping routes to compliant beans.
For New Entrants and Emerging Players: EUDR in the European Union opens a window for digital traceability platform providers serving mid-tier processors lacking in-house geolocation systems. Target Indonesian farming cooperatives with bundled certification and financing packages, as national agricultural regulators align with Verra agroforestry standards. A go-to-market angle anchored in carbon credit stacking—monetizing shade-grown cocoa sequestration separately from commodity sales—differentiates against established grinders.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated bean-to-ingredient processors given EUDR compliance consolidation forcing customer procurement toward unified certification providers. Long-term viability favors archetypes with captive grinding networks spanning three or more origins and existing digital traceability infrastructure. The signal to watch is Belgian and German premium chocolate manufacturer RFP consolidation around single-counterparty accountability, which accelerates margin capture by integrated processors at the expense of standalone traders.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Retrofitting European facilities for segregated EUDR-compliant handling absorbs capital deployment timelines. |
| Backward Integration | Direct farmer financing programs in Côte d'Ivoire and Ghana anchor supply security for integrated grinders. |
| Long-term Supply Agreement | Fixed-price butter contracts with Swiss praline manufacturers lock in tempering-stability premium capture. |
| Sustainability Repositioning | Verra agroforestry certification enables carbon credit stacking revenue streams separate from commodity sales. |
| Geographic Expansion | Singapore and Malaysia grinding hubs redirect supply chains toward Indonesian cadmium-compliant bean origins. |
Research Methodology
Independent corroboration across grinding facility technical directors, cocoa procurement leads at European chocolate manufacturers, and sustainability certification officers underwrites the qualitative findings. Primary interviews with plant managers at Dutch and Swiss processing facilities, farmer cooperative administrators in West Africa and Southeast Asia, and regulatory affairs specialists at ECHA and FDA were cross-referenced against secondary validation from customs and trade data, SEC 10-K filings of listed processors, and EFSA safety dossier submissions. Bottom-up bean production estimates and top-down confectionery demand aggregation were triangulated to anchor volume assumptions.
The forecast window was anchored to historical reference periods spanning pre-pandemic baseline, disruption-adjusted trough, and recovery-phase reconfiguration to capture structural rather than cyclical shifts. Segmentation dimensions modeled include product type, application, and end-user category, with additional granularity on EUDR compliance status and certification tier. CAGRs were derived from regression analysis against cocoa bean price indices and confectionery production volumes. Industry-specific forecast inputs incorporated REACH authorization timelines for lecithin emulsifiers and F-Gas Regulation equipment retrofit schedules.
The model assumes a particular technology adoption path; alternative pathways for precision fermentation cocoa butter alternatives would alter the outlook if yeast-derived triglycerides achieve cost parity with conventional pressing. Forecasts reflect assumptions regarding EUDR enforcement consistency, West African precipitation patterns, and cadmium threshold stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Europe Dairy Ingredients Market
Ingredients
Broccoli Powder Market
Ingredients
Encapsulated Ingredients Market
Ingredients
Cultured Non-Fat Dairy Ingredients Market
Ingredients
Algae-Based Ingredients Market
Ingredients
Pine Needle Oil Market
Ingredients
Native Whey Protein Ingredients Market
Ingredients
Wheat Starch Derivative Market
Ingredients
Europe Whey Protein Ingredients Market
Ingredients
Organic Starch Market
Ingredients
Carotenoids Market
Ingredients
Europe Vanilla Beans and Extract Market
Ingredients
North America Phytosterols Market
Ingredients
Psyllium Products Market
Ingredients
Global Malt Ingredients Market
Ingredients
South America Plant Protein Ingredients Market