
 Global Bioactive Ingredients Market | 2026-2036
Global Bioactive Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bioactive Ingredients Market Foresight
Specialized fermentation technologists is unwinding capacity constraints across European and North American production hubs. BASF SE leverages its Ludwigshafen integrated complex to sustain captive supply of omega-3 fatty acids and carotenoids. dsm-firmenich anchors global peptide manufacturing through its Dutch biotechnology infrastructure, while Kerry Group plc competes on flavor-masked probiotic delivery systems for beverage applications.
Bioactive ingredients comprise physiologically active compounds—polyphenols, short-chain fatty acids, bioactive peptides, and carotenoids typically concentrated at 5-500 mg per serving—that modulate metabolic, immune, or cellular functions beyond basic nutrition. Industrial extraction employs solvent-free supercritical CO2, enzymatic hydrolysis, or precision fermentation to preserve structural integrity and bioavailability. Probiotics and prebiotics occupy the largest value pools due to entrenched consumer recognition and repeat purchase patterns in dietary supplements and functional foods. Phytochemicals and marine-derived peptides represent faster-expanding segments, propelled by clean-label preferences and emerging clinical validation in pharmaceutical formulations.
FDA GRAS self-affirmation and EFSA health claim assessments govern market access in the United States and European Union, while China's NMPA and SAMR enforce novel food ingredient registration for imported bioactives. These frameworks elevate barriers for unvalidated extracts and reward companies with dossier-ready clinical data packages. Stakeholders must monitor regulatory divergence between jurisdictions to optimize portfolio registration sequencing and avoid stranded development investments.
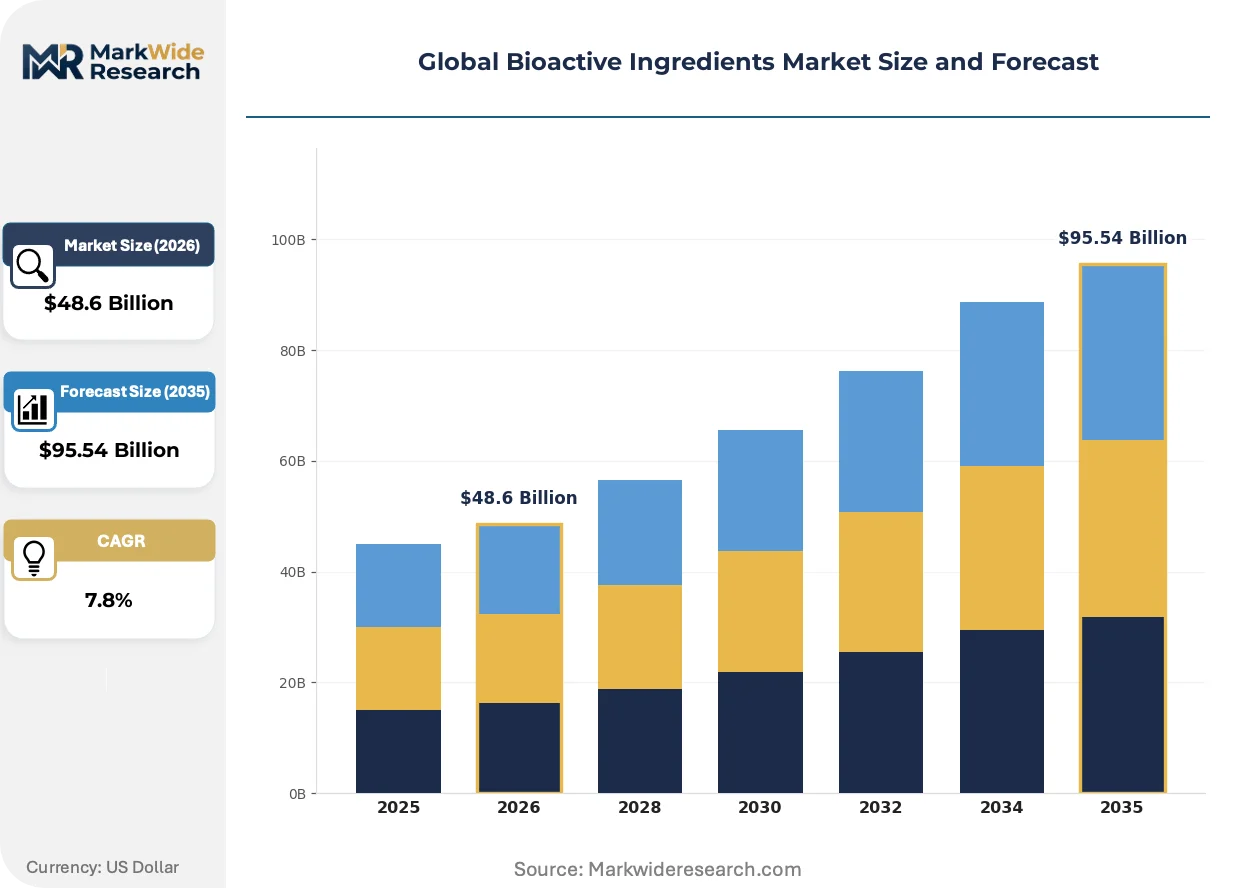
Market Dynamics
Fermentation capacity scarcity is compressing supply timelines for gut-health peptides and omega-3 concentrates, forcing nutraceutical formulators into long-term offtake agreements with biotechnology infrastructure operators.
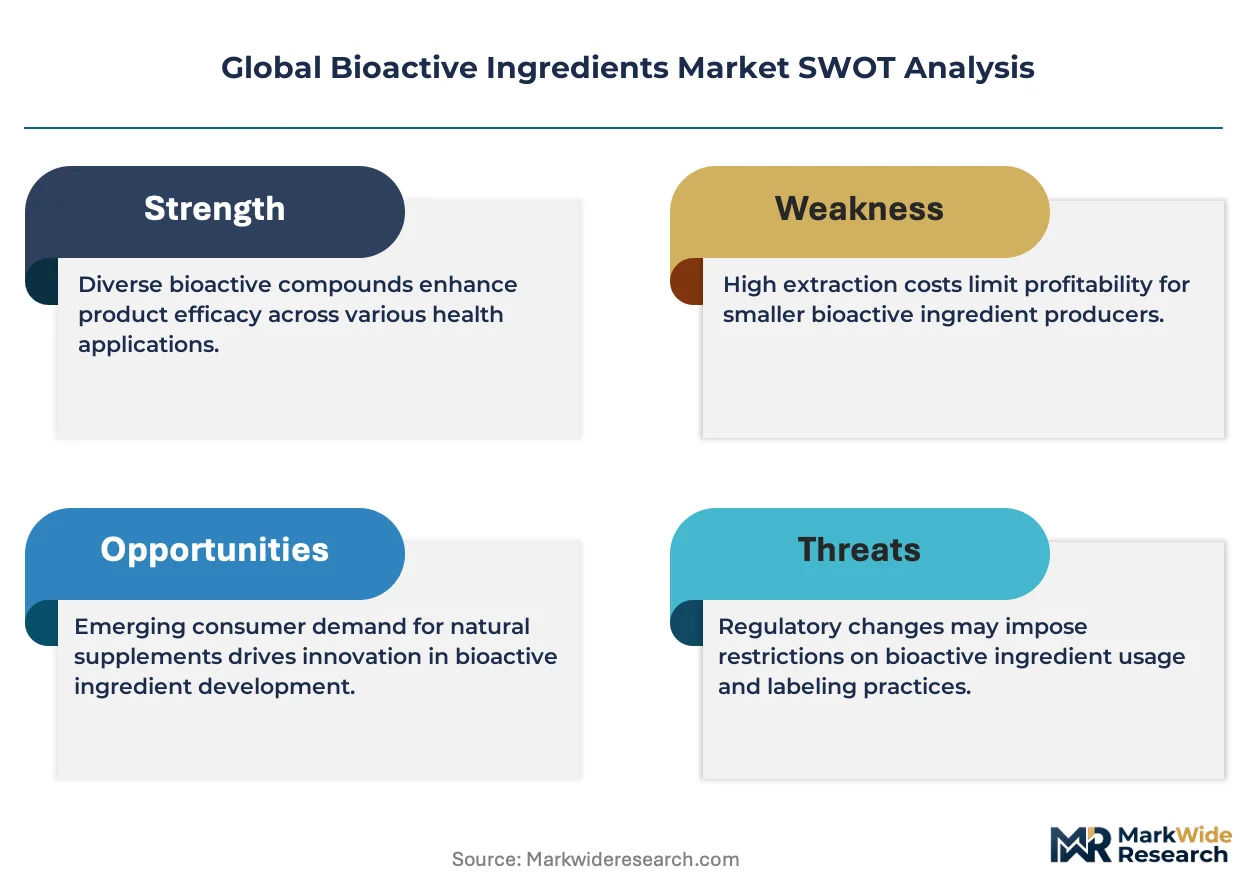
Growth Catalysts
- EFSA health claim substantiation:Dossier-ready clinical data packages unlock premium positioning for polyphenol and peptide suppliers in German and Dutch functional food channels.
- Precision fermentation scale-up:Dutch and Danish biotechnology clusters expand solvent-free carotenoid output to meet beverage industry clean-label procurement.
- China SAMR novel food registration:Import pathways for marine-derived bioactives tighten, rewarding early entrants with dossier completion capabilities.
Market Restraints
- Algal oil input volatility:Climate stress on open-pond cultivation in Chile and Australia compresses EPA/DHA raw material availability for omega-3 concentrates.
- Captive supply concentration:Ludwigshafen and Rotterdam harbor clusters control supercritical CO2 extraction capacity, elevating tolling costs for independent peptide processors.
- FDA GRAS notification backlog:Self-affirmation timelines extend for unvalidated botanical extracts, freezing market access for smaller phytochemical suppliers.
Strategic Opportunities
- Indian FSSAI functional food notification:Emerging regulatory clarity opens formulation partnerships for prebiotic fiber suppliers targeting urban supplement retail.
- Synbiotic convergence:Combined probiotic-prebiotic delivery systems capture pediatric and geriatric nutrition contracts previously split between separate ingredient vendors.
- Direct-to-brand e-procurement:Digital ingredient marketplaces displace traditional distributor markups for mid-sized German and Polish contract manufacturers.
Industry Challenges
- Precision fermentation talent scarcity:Strain engineering and downstream processing expertise concentrates in Leiden and Copenhagen, inflating compensation for qualified technologists.
- Clinical trial protocol standardization:Divergent EFSA, FDA, and NMPA biomarker requirements force redundant study designs, stretching R&D budgets for peptide health claim substantiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bioactive Ingredients Market |
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $95.54 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotics, Prebiotics, Enzymes, Antioxidants, Phytochemicals, Peptides Application: Dietary Supplements, Functional Foods, Animal Nutrition, Personal Care, Pharmaceutical Formulations, Beverages Source: Plant-Based, Marine-Derived, Microbial, Animal-Based, Synthetic, Fermented End User: Food Manufacturers, Nutraceutical Companies, Cosmetic Producers, Veterinary Services, Pharmaceutical Companies, Research Institutions |
| Companies Covered | Archer-Daniels-Midland Company, Cargill, Incorporated, BASF SE, dsm-firmenich, Kerry Group plc, Ingredion Incorporated, Ajinomoto Co., Inc., International Flavors & Fragrances Inc., Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bioactive Ingredients Market Shifts & Advancements
Biotechnology infrastructure is reshaping competitive boundaries between extraction-based and fermentation-derived supply, with regulatory data requirements accelerating consolidation around integrated manufacturing operators.
Precision fermentation for bioactive peptides is bifurcating supply economics. Strain-optimized short-chain fatty acid production preserves structural integrity without solvent residues. Pharmaceutical and infant nutrition formulators in Switzerland and the Netherlands are locking in five-year supply contracts at premium pricing. The technology is compressing traditional solvent extraction margins while enabling therapeutic-grade purity tiers previously unattainable at scale.
EU F-Gas Regulation phase-down is forcing refrigeration-dependent extraction facilities toward CO2 recapture systems. Supercritical CO2 processors in Germany and France face retrofit capex requirements or tolling fee increases. Marine peptide and carotenoid suppliers with existing closed-loop infrastructure capture volume from competitors facing compliance-driven downtime.
Clean-label certification is rotating procurement criteria toward blockchain-verified origin documentation. German and Austrian functional food manufacturers now require farm-to-fermenter traceability for polyphenol and prebiotic fiber inputs. Suppliers with integrated quality management systems displace commodity traders in premium formulation contracts, particularly for pediatric and sports nutrition applications.
Global Bioactive Ingredients Market Segmentation
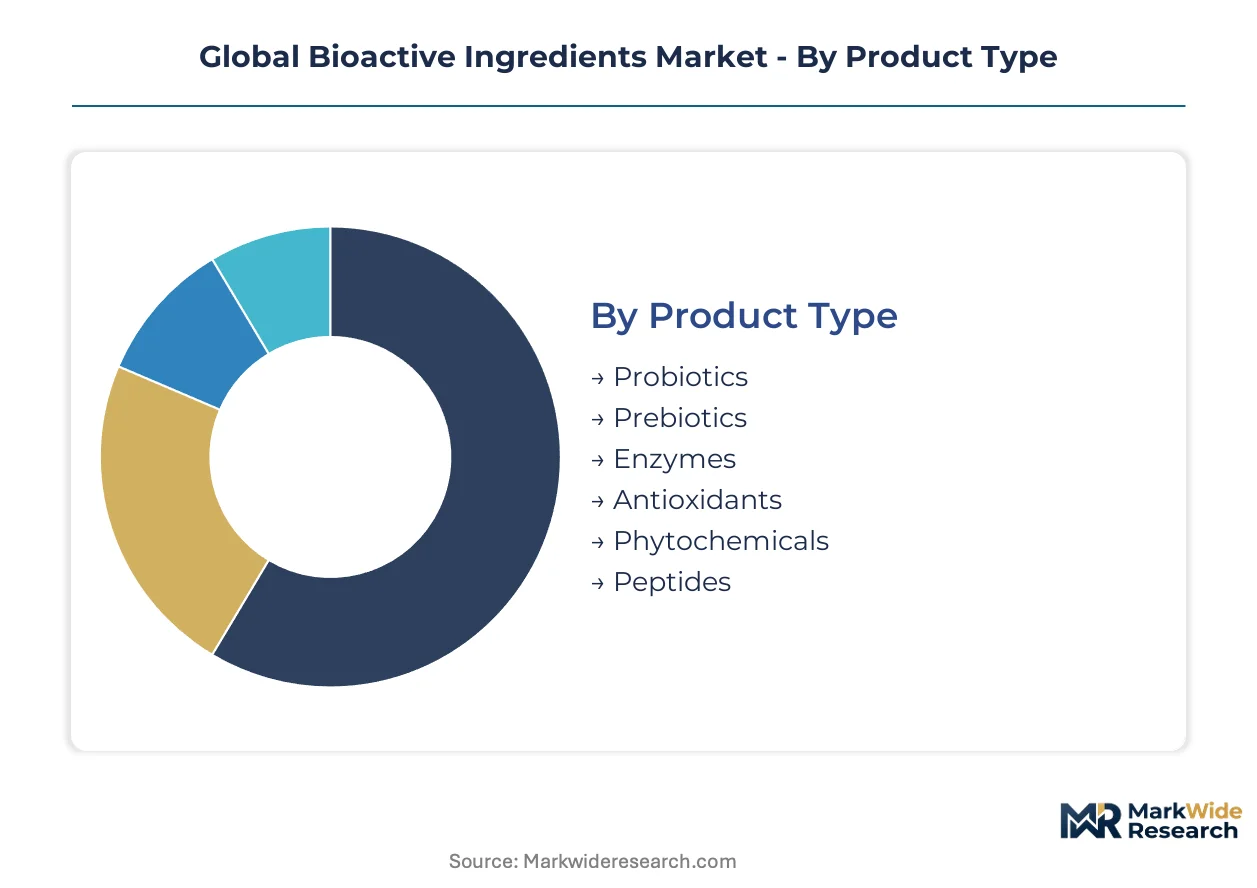
Segmentation in bioactive ingredients reveals where formulation economics and regulatory substantiation create divergent margin structures. Procurement patterns split between established gut-health platforms and emerging therapeutic-grade peptides, with source origin and end-user technical requirements determining pricing power.
Product Type:
Substitution pressure concentrates in mature categories where fermentation-derived alternatives displace traditional extraction methods, reshaping supplier economics across peptide and antioxidant segments.
- Probiotics:Live microbial cultures delivered at 10^6-10^11 CFU per serving dominate repeat-purchase supplement formulations. German and Dutch functional food manufacturers lock in multi-year supply contracts with strain-specific stability guarantees, while EFSA health claim substantiation requirements elevate barriers for generic suppliers.
- Peptides:Short-chain amino acid sequences (2-20 residues) produced via precision fermentation achieve therapeutic-grade purity without solvent residues. Swiss infant nutrition and pharmaceutical formulators in the Netherlands are securing five-year offtake agreements at premium pricing tiers, compressing margins for traditional enzymatic hydrolysis processors.
- Prebiotics:Non-digestible oligosaccharides and resistant starches.
- Enzymes:Catalytic proteins for digestive and processing applications.
- Antioxidants:Free-radical scavenging compounds including polyphenols and carotenoids.
- Phytochemicals:Plant-derived bioactive compounds with metabolic modulation properties.
Probiotics anchors the volume base while peptides gains share at the steepest rate.
Application:
Cost tier differentiation separates commodity beverage fortification from pharmaceutical-grade contract manufacturing, with regulatory dossier requirements determining market access economics.
- Dietary Supplements:Capsule, tablet, and powder delivery systems for direct consumer purchase. US and German retailers demand FDA GRAS self-affirmation or EFSA-compliant health claims, forcing smaller suppliers into tolling arrangements with integrated manufacturers.
- Pharmaceutical Formulations:Clinical-grade bioactives for drug delivery and therapeutic adjuvants. FDA IND-enabling studies and EMA quality documentation requirements concentrate procurement among Dutch and Swiss CDMOs with integrated fermentation and analytical capabilities.
- Functional Foods:Fortified conventional food products with physiological benefits.
- Animal Nutrition:Feed additives for livestock growth and health optimization.
- Personal Care:Topical bioactives for skin and hair applications.
- Beverages:Shelf-stable liquid delivery systems requiring flavor-masked probiotic stability.
Dietary supplements command the largest revenue pool while pharmaceutical formulations climb the fastest as clinical validation deepens.
Source:
Supply concentration around Dutch and Danish biotechnology clusters favors microbial and fermented origin materials, while marine-derived inputs face climate-driven availability constraints.
- Plant-Based:Polyphenols, fibers, and phytosterols extracted from botanical matrices. German and Austrian manufacturers now require blockchain-verified farm-to-fermenter traceability, displacing commodity traders in premium pediatric and sports nutrition contracts.
- Fermented:Precision fermentation-derived peptides, SCFAs, and carotenoids with solvent-free purity profiles. Strain engineering expertise concentrates in Leiden and Copenhagen, inflating compensation for qualified technologists and compressing timelines for capacity expansion.
- Marine-Derived:EPA/DHA concentrates and bioactive peptides from fish and algae.
- Microbial:Bacterial and fungal biomass for enzyme and metabolite production.
- Animal-Based:Collagen, chondroitin, and other tissue-derived compounds.
- Synthetic:Chemically synthesized bioactive molecules for cost-sensitive applications.
Plant-based sources retain the broadest formulation penetration while fermented origins expand most quickly on clean-label procurement demand.
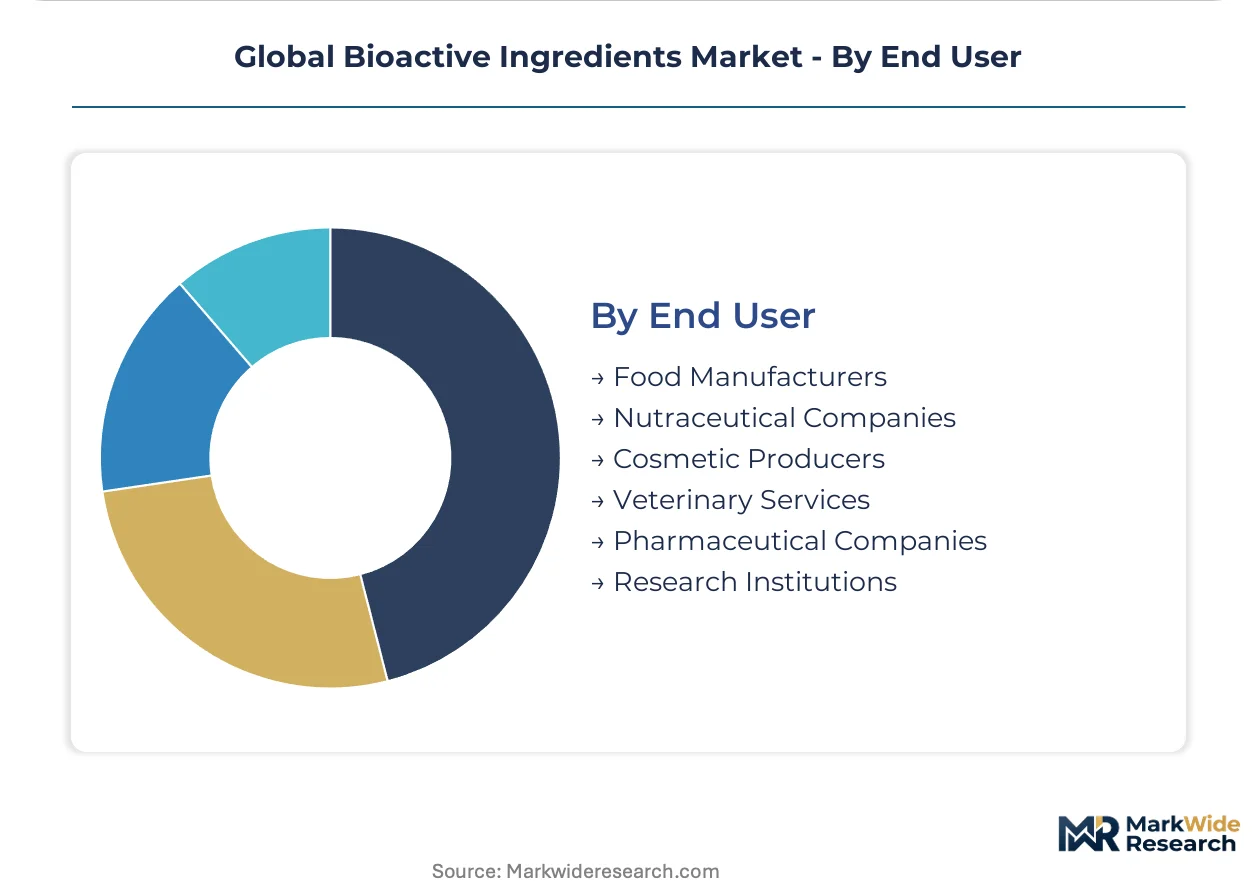
End User:
Customer type stratification separates toll-dependent mid-sized formulators from integrated multinationals with captive strain libraries and clinical trial infrastructure.
- Nutraceutical Companies:Brand owners and contract manufacturers assembling finished supplement and functional food products. Long-term offtake agreements with fermentation operators have become essential as gut-health peptide capacity scarcity compresses spot market availability.
- Pharmaceutical Companies:Drug developers incorporating bioactives as active pharmaceutical ingredients or excipients. Dossier-ready clinical data packages unlock premium positioning, with redundant EFSA, FDA, and NMPA study designs stretching R&D budgets for global registration.
- Food Manufacturers:Processed food and beverage producers seeking fortification ingredients.
- Cosmetic Producers:Personal care formulators targeting topical bioactive applications.
- Veterinary Services:Animal health product developers and feed compounders.
- Research Institutions:Academic and government laboratories conducting mechanistic and clinical studies.
Nutraceutical companies generate the highest transaction volume while pharmaceutical companies deliver the steepest margin expansion on therapeutic-grade requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates pharmaceutical-grade peptide procurement while the United States drives dietary supplement volumes; China and India diverge toward fermented bioactives for functional food fortification.
United States
FDA GRAS self-affirmation timelines extend for botanical extracts, freezing smaller suppliers while integrated manufacturers capture tolling demand. Dietary supplement brands in Utah and California lock in multi-year probiotic contracts with strain-specific stability guarantees. The FDA notification backlog rewards dossier-ready clinical data packages from established operators.
Germany
EFSA health claim substantiation requirements elevate barriers for generic polyphenol suppliers around Frankfurt and Hamburg. Precision fermentation capacity clusters in Ludwigshafen sustain captive omega-3 and carotenoid supply for Central European functional food manufacturers. BASF SE anchors supercritical CO2 extraction infrastructure that independent peptide processors access at elevated tolling rates.
China
NMPA and SAMR novel food registration tightens import pathways for marine-derived bioactives, rewarding early entrants with completed dossiers. Yangtze River Delta biotechnology parks expand precision fermentation scale-up for gut-health peptide production. Domestic formulators in Shanghai and Hangzhou secure five-year supply contracts at premium pricing for therapeutic-grade purity tiers.
India
FSSAI functional food notification clarity opens formulation partnerships for prebiotic fiber suppliers targeting urban supplement retail in Mumbai and Bangalore. Fermentation-derived bioactive capacity concentrates in Hyderabad and Pune as toll-dependent mid-sized formulators seek captive strain libraries. Indian nutraceutical companies expand procurement of fermented ingredients for pediatric nutrition applications.
Switzerland
Swissmedic quality documentation requirements concentrate pharmaceutical-grade bioactive procurement among Dutch and Swiss CDMOs with integrated capabilities. Infant nutrition formulators in Basel and Geneva lock in peptide supply contracts with therapeutic-grade purity specifications. The country's precision fermentation operators capture volume from competitors facing EU F-Gas Regulation compliance-driven downtime.
Global Bioactive Ingredients Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with fermentation capacity scarcity compressing supply timelines and forcing formulators into long-term offtake agreements. The vendor base separates between extraction-based processors and biotechnology infrastructure operators, with regulatory data requirements accelerating consolidation. Three archetypes dominate: integrated chemical conglomerates with captive supply chains, specialized fermentation technologists, and flavor-masked delivery system innovators. Competitive moves center on precision fermentation scale-up and supercritical CO2 extraction capacity expansion.
Among integrated chemical conglomerates, BASF SE and Evonik Industries AG occupy positions defined by Ludwigshafen and Marl harbor infrastructure that controls solvent-free extraction capacity. DSM-Firmenich represents the specialized fermentation technologist archetype through Dutch biotechnology infrastructure anchoring global peptide manufacturing. Kerry Group plc exemplifies the delivery system innovator tier, competing on probiotic stability solutions for beverage applications. These three companies illustrate how regulatory dossier capabilities and captive manufacturing infrastructure determine pricing power in a market where unvalidated extracts face stranded development investments.
| Leading Market Players |
|---|
| Archer-Daniels-Midland Company |
| Cargill, Incorporated |
| BASF SE |
| dsm-firmenich |
| Kerry Group plc |
| Ingredion Incorporated |
| Ajinomoto Co., Inc. |
| International Flavors & Fragrances Inc. |
| Evonik Industries AG |
| Others |
Supply & Pricing Matrix
EFSA health claim substantiation gates both supply qualification and price differentiation simultaneously, forcing peptide suppliers to embed clinical trial costs into long-term contract structures while generic botanical extractors compete on spot-market tolling fees. German functional food manufacturers now require dossier-ready documentation as a condition of procurement, compressing margins for unvalidated suppliers and concentrating pricing power among integrated fermentation operators.
Pricing Analysis
Long-term offtake agreements dominate therapeutic-grade peptide procurement, with Swiss infant nutrition formulators locking in five-year contracts at premium tiers while spot-market availability for gut-health bioactives tightens. Price differentiation separates fermentation-derived purity grades from solvent-extracted alternatives, with EFSA-compliant health claim packages commanding substantial premiums. Cost compression in traditional enzymatic hydrolysis is intensifying as precision fermentation scales, squeezing toll-dependent processors. Mid-sized Polish and German contract manufacturers exhibit highest price sensitivity, while pharmaceutical CDMOs prioritize supply security over unit economics.
Supply Chain Analysis
Rotterdam harbor supercritical CO2 extraction capacity acts as a chokepoint, with Ludwigshafen and Dutch biotechnology clusters controlling solvent-free carotenoid and omega-3 output that independent peptide processors access at elevated tolling rates. Raw material flows draw from Chilean and Australian algal cultivation for EPA/DHA concentrates, Leiden-Copenhagen strain engineering for fermented peptides, and Indian botanical matrices for polyphenol extraction. Single-source vulnerability concentrates in precision fermentation talent pools, where strain engineering expertise inflates compensation and extends capacity timelines. Distribution runs through integrated chemical conglomerates with captive supply chains, displacing commodity traders in premium formulation contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bioactive ingredients market is recovering from a cyclical trough driven by fermentation capacity scarcity, with supply timelines normalizing as Dutch and Danish biotechnology clusters expand solvent-free output.
For Market Incumbents: Compound defensive positioning through backward integration into strain libraries and clinical trial infrastructure, securing captive peptide manufacturing capacity before precision fermentation talent scarcity worsens. BASF SE and DSM-Firmenich archetypes should extend supercritical CO2 extraction tolling advantages by retrofitting EU F-Gas Regulation-compliant recapture systems, converting regulatory compliance downtime into volume capture from stranded competitors. For New Entrants and Emerging Players: Digital ingredient marketplace infrastructure represents a service-layer gap where incumbents under-serve mid-sized German and Polish contract manufacturers, creating entry pathways through direct-to-brand e-procurement platforms. Target Indian FSSAI functional food notification clarity as the most penetrable regulatory window, partnering with Hyderabad and Pune fermentation operators to supply prebiotic fiber formulations for urban Mumbai and Bangalore supplement retail. For Investors and Strategic Acquirers: China's SAMR novel food registration completion reshapes the acquisition landscape toward early entrants with dossier-ready marine-derived bioactive capabilities. Five-to-ten year viability favors integrated operators with simultaneous fermentation scale-up and regulatory affairs infrastructure, rather than pure-play extraction specialists. Monitor FDA GRAS notification backlog resolution as the signal indicating when smaller phytochemical suppliers regain market access and valuation multiples recover.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Dutch biotechnology clusters expand solvent-free carotenoid output to meet beverage industry clean-label procurement requirements. |
| EFSA Health Claim Dossier Completion | German functional food manufacturers lock in premium peptide suppliers with substantiated physiological benefit documentation. |
| EU F-Gas Regulation Retrofit | Supercritical CO2 processors in Germany and France capture volume from competitors facing compliance-driven downtime. |
| Blockchain-Verified Traceability Implementation | Austrian and German pediatric nutrition formulators displace commodity traders with farm-to-fermenter origin documentation. |
| Long-Term Offtake Agreement Structuring | Swiss infant nutrition CDMOs secure five-year peptide supply contracts at therapeutic-grade purity specifications. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with fermentation technologists, regulatory affairs directors at nutraceutical companies, functional food procurement managers, and precision fermentation strain engineers; alongside secondary validation through EFSA health claim registers, FDA GRAS notification databases, SAMR novel food filings, and customs trade data for algal oil and peptide concentrate flows. Bottom-up capacity modeling across Dutch, Danish, and German biotechnology clusters was triangulated against top-down demand estimates from dietary supplement and pharmaceutical formulation channels.
Across the analysis window, forecasts applied segment-level growth rates derived from procurement pattern analysis across probiotics, peptides, prebiotics, and phytochemicals, with additional modeling dimensions for source origin and end-user technical requirements. CAGRs were computed from normalized baseline values through iterative convergence of supply-side capacity expansion timelines and demand-side health claim substantiation progress. Industry-specific inputs included fermentation batch yield improvements, EFSA opinion publication velocity, and algal oil input cost trajectories.
Forecasts assume regulatory continuity in EFSA health claim assessments, FDA GRAS self-affirmation pathways, and China SAMR novel food registration protocols; material policy shifts in any jurisdiction would require re-modeling supply timelines and market access economics. Practitioners should keep alternative scenarios live as precision fermentation capacity expansion and climate stress on marine-derived inputs evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Antimicrobial (Enzymatic) Protein Hydrolysates Market
Ingredients
Cooking Coconut Milk Market
Ingredients
Waxy Maize Starch Market
Ingredients
Non-GMO Soya Market
Ingredients
France Protein Market
Ingredients
Italy Soy Protein Market
Ingredients
Egg White Powder Market
Ingredients
Food Grade Linseed Oil Market
Ingredients
Borage Oil Market
Ingredients
Soybean Oil Market
Ingredients
North America Fats and Oils Market
Ingredients
Europe Vanilla Beans and Extract Market
Ingredients
Fats and Oils Market
Ingredients
Carrot Fiber Market
Ingredients
Pea Fiber Market
Ingredients
Global Palm Kernel Oil and Coconut Oil Based Natural Fatty Acids Market