
 Global Autolyzed Yeast Extract Market | 2026-2036
Global Autolyzed Yeast Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Global Autolyzed Yeast Extract Market Analysis
The capital-intensity divergence between autolyzed yeast extract producers is unwinding as smaller operators struggle to match enzymatic hydrolysis investments. Lesaffre Group leverages captive fermentation capacity across multiple continents to sustain raw material security. Angel Yeast Co. Ltd. anchors its position through backward integration into molasses sourcing and strain development. Lallemand Inc. differentiates via specialized autolysis protocols that yield higher free amino nitrogen content for premium flavoring applications.
Autolyzed yeast extract comprises yeast cells enzymatically digested to release peptides, amino acids, nucleotides, and cell wall polysaccharides, typically achieving 40-60% protein content on a dry basis with savory umami intensity measured by equivalent monosodium glutamate comparison. Powder formulations dominate volume throughput due to extended shelf stability and ease of dry-blending into seasoning matrices, while liquid variants command margin premiums in beverage and fermentation-aid applications where rapid solubility reduces processing steps. The food industry segment leads absolute consumption as clean-label reformulation displaces synthetic flavor enhancers across savory product lines.
EFSA evaluates yeast-derived flavoring substances under Regulation (EC) No 1333/2008, while China's SAMR enforces GB standards for yeast extract labeling and compositional claims. FDA GRAS self-affirmation pathways govern US market entry, creating asynchronous compliance burdens for multinational suppliers. Stakeholders must monitor evolving nucleotide disclosure thresholds and fermentation substrate traceability mandates that will reshape procurement qualification criteria.
Market Dynamics
Enzymatic hydrolysis investment requirements are concentrating production capacity among operators with captive fermentation infrastructure, forcing smaller competitors toward toll-manufacturing arrangements or exit.
Growth Catalysts
- EFSA disclosure mandates:Clean-label reformulation requirements across Western Europe accelerate displacement of synthetic flavor enhancers in savory applications.
- Fermentation substrate traceability:Food manufacturers in China prioritize qualified yeast extract suppliers under SAMR tightening of GB labeling standards.
- Umami intensity benchmarking:Equivalent monosodium glutamate comparison protocols enable formulators to quantify clean-label replacement value.
Market Restraints
- Molasses price volatility:Sugar beet and cane supply fluctuations in Brazil and India transmit directly to yeast extract input costs.
- Nucleotide disclosure thresholds:Pending EFSA evaluations under Regulation (EC) No 1333/2008 create labeling uncertainty for savory product developers.
- Hydrolyzed vegetable protein substitution:Lower-cost umami alternatives capture share in economy-tier seasoning formulations.
Strategic Opportunities
- Beverage fermentation aids:Liquid yeast extract variants address rapid solubility requirements in craft brewing and alternative protein fermentation.
- East Asian procurement consolidation:China's SAMR enforcement of compositional claims creates qualification barriers favoring integrated suppliers.
- Cell culture media applications:Yeast-derived peptone and amino acid complexes penetrate pharmaceutical and cultivated meat nutrient formulations.
Industry Challenges
- Enzymatic hydrolysis expertise:Shortage of fermentation biochemists capable of optimizing autolysis protocols for free amino nitrogen targets constrains capacity expansion.
- GRAS self-affirmation complexity:FDA pathway documentation requirements for novel yeast strains extend US market entry timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Autolyzed Yeast Extract Market |
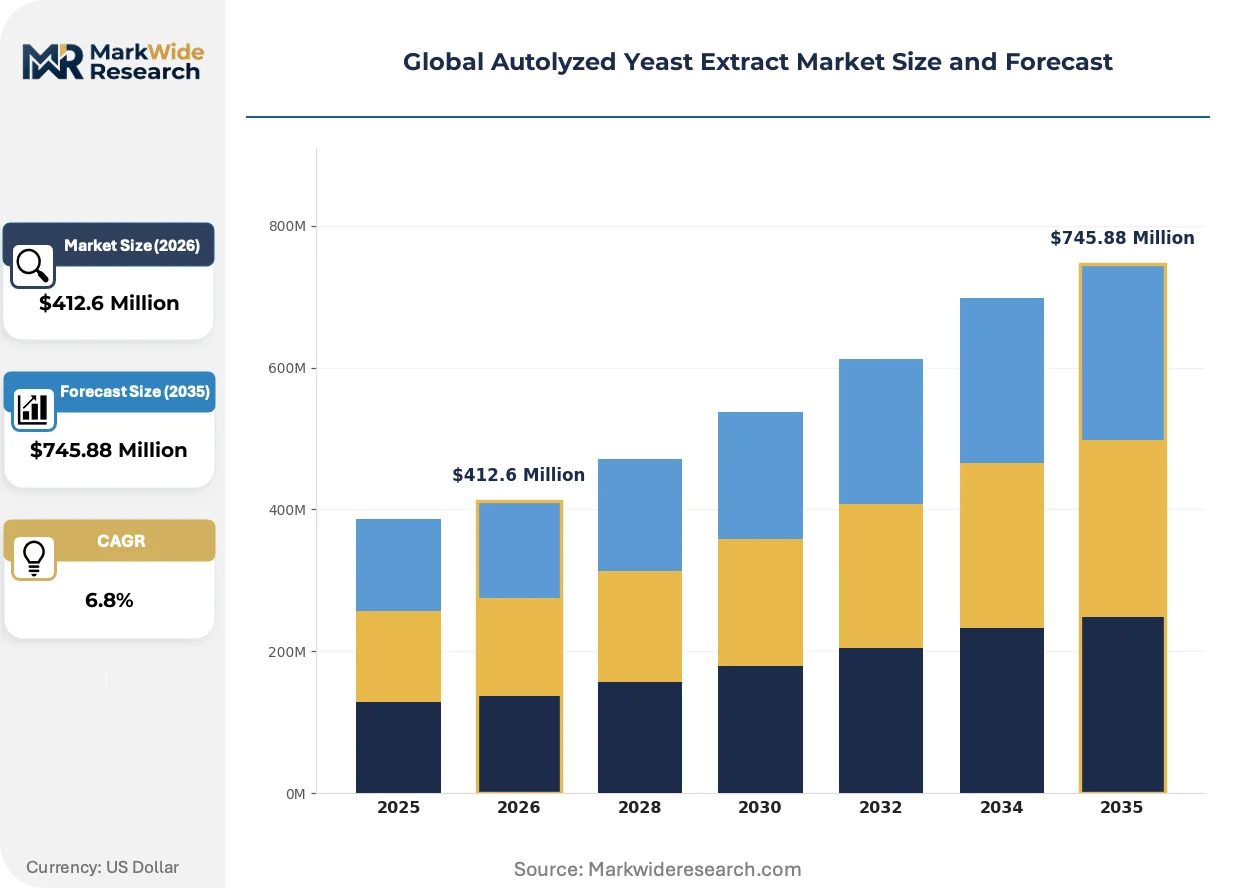
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Granular, Paste End User: Food Industry, Beverage Manufacturers, Animal Feed, Nutraceuticals Application: Flavoring Agent, Nutritional Supplement, Fermentation Aid, Seasoning Distribution Channel: Online Retailers, Supermarkets, Specialty Stores, Foodservice |
| Companies Covered | Lesaffre Group, Koninklijke DSM N.V., Angel Yeast Co. Ltd., Lallemand Inc., AB Mauri, Associated British Foods Plc, Leiber GmbH, Titan Biotech, Biorigin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Autolyzed Yeast Extract Market Emerging Trajectories
Process intensification and regulatory disclosure requirements are reshaping competitive differentiation away from commodity volume toward specialized autolysis protocols and substrate traceability systems.
Continuous enzymatic hydrolysis systems with real-time free amino nitrogen monitoring are displacing batch autolysis in high-throughput savory flavoring operations. Major seasoning manufacturers in Germany retrofit existing fermentation facilities to capture yield improvements and reduce lot-to-lot variability. This displacement compresses margins for operators dependent on static batch protocols without inline analytics.
EFSA's evolving evaluation of yeast-derived nucleotides under Regulation (EC) No 1333/2008 forces reformulation of disclosure thresholds across EU savory product portfolios. Food manufacturers pre-emptively adjust labeling to accommodate potential reclassification of 5'-ribonucleotide contributions. Premium positioning strategies now emphasize autolysis-derived umami rather than additive-equivalent claims.
Direct procurement relationships between end-use formulators and integrated yeast extract producers are consolidating specification-setting authority away from traditional distribution intermediaries. Large savory manufacturers in China negotiate captive supply arrangements with molasses-integrated producers to secure substrate traceability documentation. This channel compression is most visible in East Asian fermentation-aid procurement, where SAMR documentation requirements reward direct supplier relationships.
Global Autolyzed Yeast Extract Market Segmentation
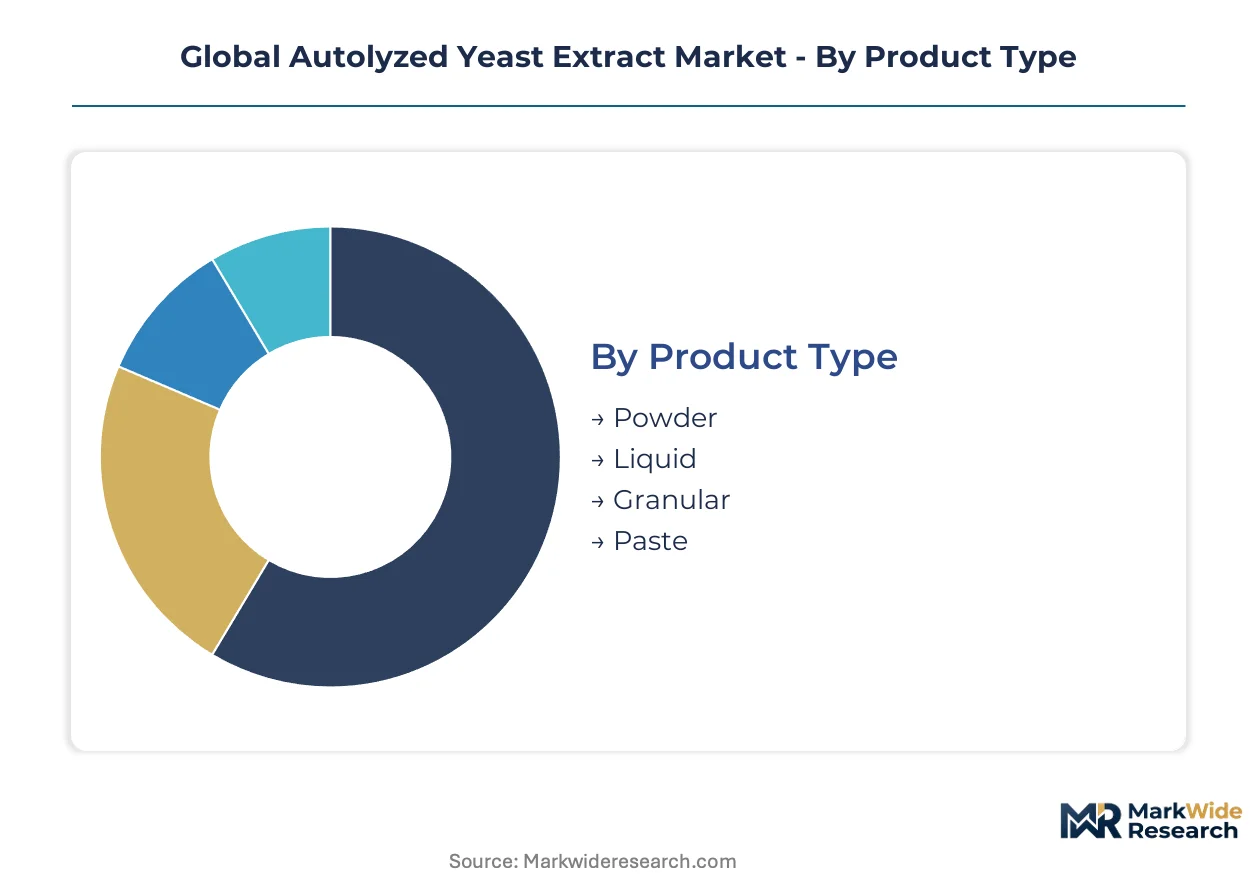
Segmentation in autolyzed yeast extract markets exposes where substitution pressure from hydrolyzed vegetable proteins and synthetic nucleotides concentrates. Formulators select formats and channels based on solubility requirements, labeling thresholds, and fermentation substrate traceability documentation.
Product Type:
Powder and liquid formats face divergent substitution threats from hydrolyzed vegetable proteins in economy-tier seasoning applications.
- Powder:Spray-dried extract achieves 40-60% protein content with extended shelf stability. Demand concentrates in German and Chinese savory seasoning manufacturing where dry-blending compatibility reduces processing steps.
- Liquid:Rapid solubility in aqueous systems commands margin premiums. Beverage manufacturers in craft brewing and alternative protein fermentation prioritize this format to eliminate reconstitution stages.
- Granular:Intermediate particle size suits table-top seasoning applications. Japanese and South Korean condiment producers specify this grade for controlled dissolution in instant soup bases.
- Paste:High-moisture concentrate serves wet sauce formulations. Brazilian and Mexican processed food manufacturers integrate paste variants into ready-meal flavor systems.
Powder anchors the volume base while liquid gains share at the steepest rate.
End User:
Cost-tier stratification separates integrated manufacturers from toll-dependent compounders across customer categories.
- Food Industry:Clean-label reformulation drives displacement of synthetic flavor enhancers in savory applications. EFSA disclosure mandates under Regulation (EC) No 1333/2008 accelerate procurement from qualified yeast extract suppliers with substrate traceability systems.
- Beverage Manufacturers:Liquid extract functions as fermentation aid and flavor precursor. Chinese craft brewers under SAMR enforcement prioritize direct supplier relationships for GB documentation compliance.
- Animal Feed:Palatability enhancement in pet food and livestock nutrition. Brazilian and Thai feed compounders specify yeast-derived alternatives to synthetic attractants.
- Nutraceuticals:Peptide and beta-glucan fractions for immune-modulation claims. US supplement manufacturers navigate FDA GRAS self-affirmation pathways for novel strain derivatives.
Food industry procurement dominates absolute volume while beverage manufacturers expand most quickly.
Application:
Application maturity determines where enzymatic hydrolysis investments concentrate versus where static batch protocols suffice.
- Flavoring Agent:Umami intensity benchmarking against monosodium glutamate equivalents enables quantified clean-label replacement. German and Italian savory manufacturers lead adoption of autolysis-derived alternatives.
- Nutritional Supplement:B-vitamin complexes and mineral chelates for fortified foods. Indian and Brazilian food fortification programs under FSSAI and ANVISA guidelines specify yeast-derived nutrient carriers.
- Fermentation Aid:Amino acid and peptide nitrogen sources for microbial culture media. Pharmaceutical and cultivated meat nutrient formulations in Singapore and Israel drive specification tightening.
- Seasoning:Direct incorporation into bouillon and sauce bases. Chinese and Japanese instant food manufacturers consolidate procurement through captive supply arrangements.
Flavoring agent applications anchor the volume base while fermentation aid gains share at the steepest rate.
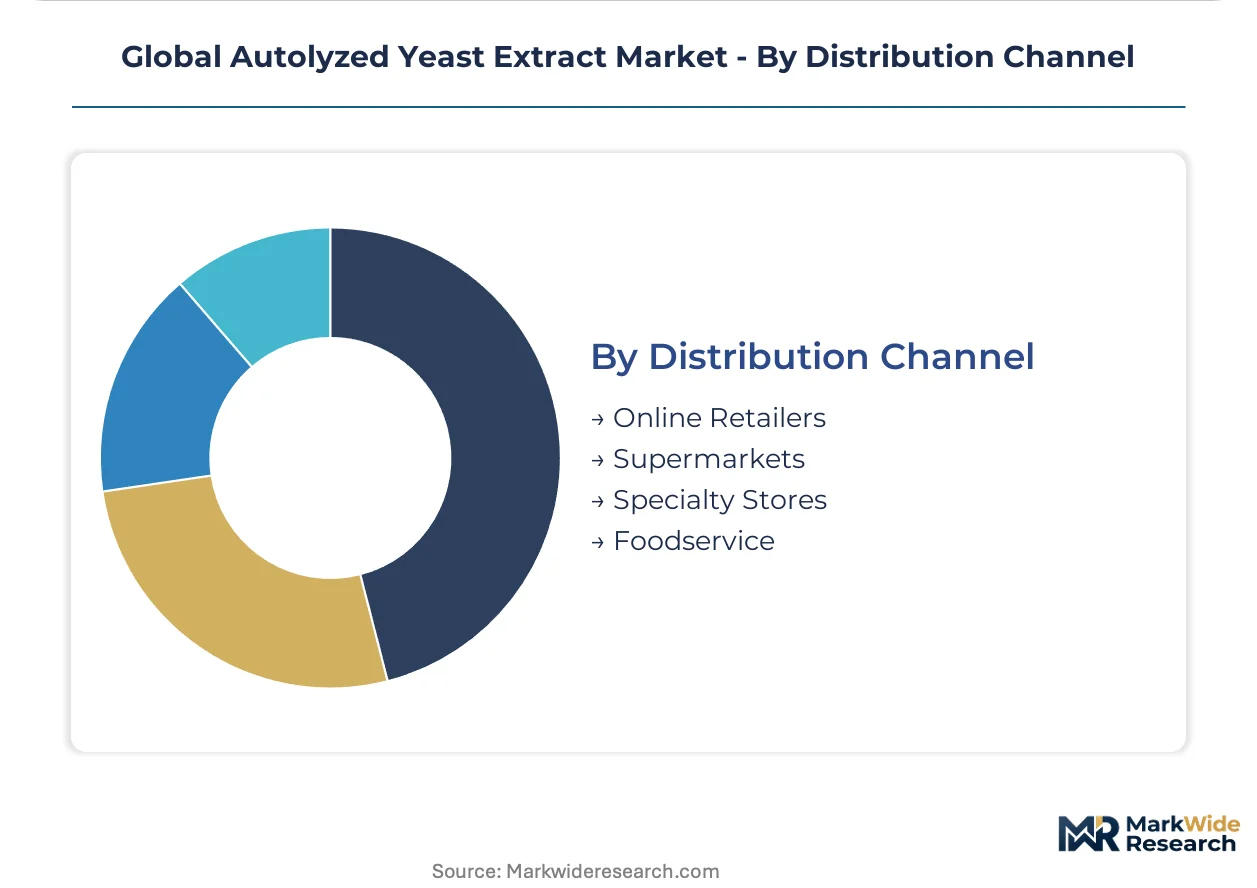
Distribution Channel:
Channel concentration reflects documentation requirements and lot-size economics across customer segments.
- Online Retailers:Small-lot procurement for artisanal and startup formulators. Direct-to-manufacturer platforms in China and India bypass traditional distribution markups.
- Supermarkets:Branded consumer yeast extract for home cooking. European retail chains emphasize clean-label positioning in private-label ranges.
- Specialty Stores:Technical-grade products for professional kitchens and small-scale food manufacturers. Japanese and South Korean culinary supply channels emphasize provenance documentation.
- Foodservice:Bulk supply to industrial kitchens and contract caterers. Brazilian and Mexican foodservice distributors consolidate volumes for seasoning blend manufacturers.
Foodservice anchors the volume base while online retailers gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and China demonstrate limited price elasticity as regulatory documentation requirements override cost considerations, while Brazilian and Indian compounders face acute substitution pressure from hydrolyzed vegetable proteins in economy-tier formulations.
Germany
EFSA disclosure mandates under Regulation (EC) No 1333/2008 compel savory manufacturers to source qualified autolyzed yeast extract with full substrate traceability. German seasoning producers in Lower Saxony retrofit fermentation facilities with continuous enzymatic hydrolysis systems to meet clean-label reformulation deadlines. The Cologne-Düsseldorf industrial corridor concentrates procurement authority among integrated seasoning compounders.
China
SAMR enforcement of GB standards for yeast extract labeling drives food manufacturers toward direct supplier relationships with molasses-integrated producers. The Yangtze River Delta anchors domestic fermentation capacity expansion as Angel Yeast Co. Ltd. consolidates backward integration into strain development. Shanghai-based craft brewers prioritize liquid extract procurement for rapid solubility in fermentation-aid applications.
United States
FDA GRAS self-affirmation pathways extend market entry timelines for novel yeast strain derivatives, favoring established suppliers with documentation expertise. US savory manufacturers navigate asynchronous compliance burdens relative to EU counterparts. The Midwest fermentation cluster around Illinois and Wisconsin attracts toll-manufacturing arrangements from smaller operators lacking captive infrastructure.
Brazil
Molasses price volatility from sugar cane supply fluctuations transmits directly to yeast extract input costs, squeezing margins for feed compounders and processed food manufacturers. ANVISA guidelines for yeast-derived nutrient carriers in food fortification programs create qualified supplier demand. São Paulo state concentrates pet food palatability enhancement procurement as compounders seek alternatives to synthetic attractants.
India
FSSAI food fortification programs specify yeast-derived nutrient carriers, opening procurement channels for B-vitamin complexes and mineral chelates. Indian seasoning manufacturers face acute substitution pressure from lower-cost hydrolyzed vegetable proteins in mass-market formulations. The Maharashtra-Gujarat industrial corridor attracts toll-manufacturing investment as smaller domestic operators lack enzymatic hydrolysis capabilities.
Global Autolyzed Yeast Extract Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier that relies on toll-manufacturing or narrow application focus. The integrated tier controls captive fermentation infrastructure across multiple continents, securing raw material security and substrate traceability documentation. Specialist operators differentiate through proprietary autolysis protocols or regional geographic concentration. Capacity expansion and strategic partnerships constitute the dominant competitive moves as enzymatic hydrolysis investment requirements concentrate production authority.
Within the integrated fermentation tier, Lesaffre Group and Angel Yeast Co. Ltd. exemplify archetypes of multi-continent captive capacity and backward integration into molasses sourcing respectively. Lallemand Inc. occupies a position emphasizing specialized autolysis protocols for premium flavoring applications. These three entities represent the structural divergence between scale-driven substrate security and protocol-driven quality differentiation that defines competitive positioning.
| Leading Market Players |
|---|
| Lesaffre Group |
| Koninklijke DSM N.V. |
| Angel Yeast Co. Ltd. |
| Lallemand Inc. |
| AB Mauri |
| Associated British Foods Plc |
| Leiber GmbH |
| Titan Biotech |
| Biorigin |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between German savory manufacturers and molasses-integrated yeast extract producers lock in both supply access and price visibility across EFSA-mandated reformulation cycles. These arrangements insulate qualified suppliers from spot-market molasses volatility while securing substrate traceability documentation demanded under tightening disclosure rules.
Pricing Analysis
After-sales service bundling with technical formulation support drives lifetime value for integrated yeast extract producers serving premium savory applications. Three-tier pricing structure across premium, standard, and economy levels separates autolysis-derived flavoring with full nucleotide disclosure from hydrolyzed vegetable protein alternatives. Cost compression in economy-tier seasoning compounds is intensifying because Brazilian and Indian manufacturers face acute substitution pressure from lower-cost umami sources. Food industry formulators in Germany and China demonstrate limited price sensitivity as regulatory documentation requirements override cost considerations.
Supply Chain Analysis
Molasses supply concentration in Brazil and India underwrites input cost volatility that transmits directly to yeast extract production economics. Fermentation substrate sourcing draws from sugar beet and cane processing clusters, with enzymatic hydrolysis equipment and specialized strain cultures as critical production inputs. Single-source vulnerability in molasses procurement exposes margin compression when climatic disruptions hit cane harvests. Distribution runs through direct procurement relationships between end-use formulators and integrated producers, consolidating specification-setting authority away from traditional intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of fermentation biochemists capable of optimizing autolysis protocols for free amino nitrogen targets constrains capacity expansion and rewards early capability investment. This talent gap shapes competitive durability across the projection horizon.
For Market Incumbents: Shield proprietary autolysis expertise through captive training programs and retention structures targeting EFSA-qualified strain development capabilities. Expand continuous enzymatic hydrolysis capacity in the Yangtze River Delta to capture SAMR-driven procurement consolidation. Deepen backward integration into molasses sourcing to secure substrate traceability documentation against pending nucleotide disclosure threshold revisions. For New Entrants and Emerging Players: FDA GRAS self-affirmation fast-tracks offer regulatory arbitrage for novel yeast strain derivatives targeting US nutraceutical applications. White-space concentration exists in cell culture media peptone supply for pharmaceutical and cultivated meat nutrient formulations, where specification tightening outpaces incumbent capacity addition. Lead with rapid-solubility liquid extract positioning in Chinese craft brewing to bypass established powder-format supply relationships. For Investors and Strategic Acquirers: Toll-dependent regional compounders lacking enzymatic hydrolysis infrastructure represent consolidation targets as capital-intensity divergence forces exit or captive arrangement. Long-term viability hinges on positioning within integrated fermentation tiers with multi-continent captive capacity and documented substrate traceability systems. Monitor EFSA nucleotide reclassification timelines as inflection indicators for savory reformulation demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Molasses Sourcing | Angel Yeast Co. Ltd. anchors raw material security through upstream control over fermentation substrates. |
| Continuous Enzymatic Hydrolysis Retrofit | German seasoning producers in Lower Saxony capture yield improvements and reduce lot-to-lot variability. |
| Direct Procurement Relationship Consolidation | Large savory manufacturers in China bypass distribution markups to secure SAMR documentation compliance. |
| Specialized Autolysis Protocol Development | Lallemand Inc. differentiates through higher free amino nitrogen content for premium flavoring applications. |
| Cell Culture Media Application Expansion | Yeast-derived peptone complexes penetrate pharmaceutical and cultivated meat nutrient formulations in Singapore. |
Methodological Framework
The analysis maps powder, liquid, granular, and paste format sub-sectors, each validated through fermentation biochemists, savory formulation technologists, and procurement directors at seasoning manufacturers. Primary interviews with plant managers at integrated yeast extract facilities, procurement leads at downstream food manufacturers, and regulatory affairs specialists across EFSA and SAMR jurisdictions combined with secondary validation from customs/trade data, SEC filings, and GB standard documentation. Bottom-up volume modeling and top-down value reconciliation triangulated outputs across the analysis window.
Consistency checks against external benchmarks validated projections for enzymatic hydrolysis capacity additions and clean-label reformulation penetration rates. Segmentation dimensions modeled include product format, end-user industry, application type, and distribution channel across regional production hubs. CAGRs were derived from trend extrapolation of EFSA disclosure mandate implementation timelines and SAMR enforcement intensity, with molasses price volatility and nucleotide reclassification risk as scenario inputs.
Decision-makers should treat outputs as directional under base assumptions of sustained regulatory tightening in Western Europe and East Asia; material deviation in enforcement timelines or molasses supply stability would warrant model refresh. Practitioners should keep alternative scenarios live as EFSA nucleotide evaluation conclusions and SAMR substrate traceability mandate scope evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Sugared Egg Yolk Market
Ingredients
Bouillon Market
Ingredients
Potato Protein Market
Ingredients
Ice Cream Ingredients Market
Ingredients
Global Hydrolyzed Wheat Protein Market
Ingredients
Moringa Ingredients Market
Ingredients
China Gelatin Market
Ingredients
India Bakery Ingredients Market
Ingredients
Olive Leaf Extract Market
Ingredients
Rapid-Set Gelatin Market
Ingredients
Fruit Powder Market
Ingredients
Global Pine Pollen Powder Market
Ingredients
Malted Barley Flour Market
Ingredients
North America Rice Protein Ingredients Market
Ingredients
Yeast Derivatives Market
Ingredients
Europe Dairy Ingredients Market