
 Europe Feed Prebiotics Market | 2026-2036
Europe Feed Prebiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Feed Prebiotics Market Foresight
Poultry feed formulation is consolidating its position as the dominant application channel across European livestock operations. BENEO GmbH leverages its Belgian chicory-root processing infrastructure to anchor supply of inulin-derived prebiotics for broiler integrators. Roquette Frères competes through its pea-starch fermentation platform, sustaining long-term contracts with French and Dutch compound feed manufacturers.
Europe Feed Prebiotics are non-digestible carbohydrate compounds, typically oligosaccharides or inulin extracted from chicory, beet, or legume sources, that selectively stimulate beneficial gut microbiota in monogastric and ruminant animals. These additives function by resisting upper-gastrointestinal enzymatic hydrolysis and undergoing colonic fermentation to produce short-chain fatty acids, thereby improving nutrient absorption and pathogen resistance. Oligosaccharides occupy the largest share of product-type value pools due to established manufacturing scale and documented efficacy in poultry trials. Powder and granular forms dominate physical formulation demand, though liquid applications are gaining traction in automated aquaculture feeding systems where precise dosing integration matters.
The EU Green Deal and Farm to Fork Strategy, enforced through EFSA feed additive authorization pathways, mandate measurable antibiotic reduction targets that directly expand prebiotic substitution demand. REACH compliance and CE marking requirements for feed materials further shape product registration costs and market access timelines for non-European suppliers. Stakeholders must monitor evolving EFSA opinions on novel prebiotic substrates and the Commission's pending revisions to feed hygiene regulations that could recalibrate manufacturing facility standards.
Market Dynamics
The EU Green Deal's Farm to Fork Strategy is compressing antibiotic reduction timelines, forcing livestock integrators to reallocate capital toward gut health additives that deliver measurable pathogen resistance without pharmaceutical residues.
Growth Catalysts
- Farm to Fork antibiotic mandates:Binding EU targets for antimicrobial reduction in poultry and swine operations are redirecting feed formulation budgets toward oligosaccharide-based alternatives.
- German industrial livestock corridor:Concentrated demand from vertically integrated broiler operations in Lower Saxony and North Rhine-Westphalia is anchoring volume commitments for chicory-root-derived inulin.
- Precision fermentation:Advances in enzymatic synthesis of galactooligosaccharides are lowering unit costs and expanding inclusion rates in compound feed manufacturing.
Market Restraints
- Chicory root supply concentration:Belgian and French agricultural processors control 70% of EU inulin extraction capacity, creating input vulnerability for non-integrated feed additive suppliers.
- EFSA authorization timelines:Novel substrate approvals under Regulation (EC) No 1831/2003 extend 18-24 months, freezing commercialization of emerging prebiotic candidates.
- Phytogenic substitution:Essential oil and plant extract blends are capturing budget share in swine applications where oligosaccharide efficacy documentation remains thinner.
Strategic Opportunities
- Polish poultry expansion:Rapid capacity buildout by integrators in Wielkopolska and Mazovia regions is outpacing local prebiotic supply infrastructure.
- Aquaculture liquid dosing:Automated recirculating systems in Norwegian salmon farming are creating demand for water-soluble prebiotic concentrates incompatible with powder handling.
- CE marking harmonization:Pending Commission revisions to feed hygiene regulations may streamline cross-border manufacturing facility approvals for multi-site producers.
Industry Challenges
- Microbiome assay standardization:Absence of validated in-vivo gut flora measurement protocols complicates efficacy claims for novel substrate developers seeking EFSA dossier approval.
- Legacy ERP integration:Automated dosing systems in modern feed mills require API connectivity that prebiotic suppliers with dated inventory platforms struggle to support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Feed Prebiotics Market |
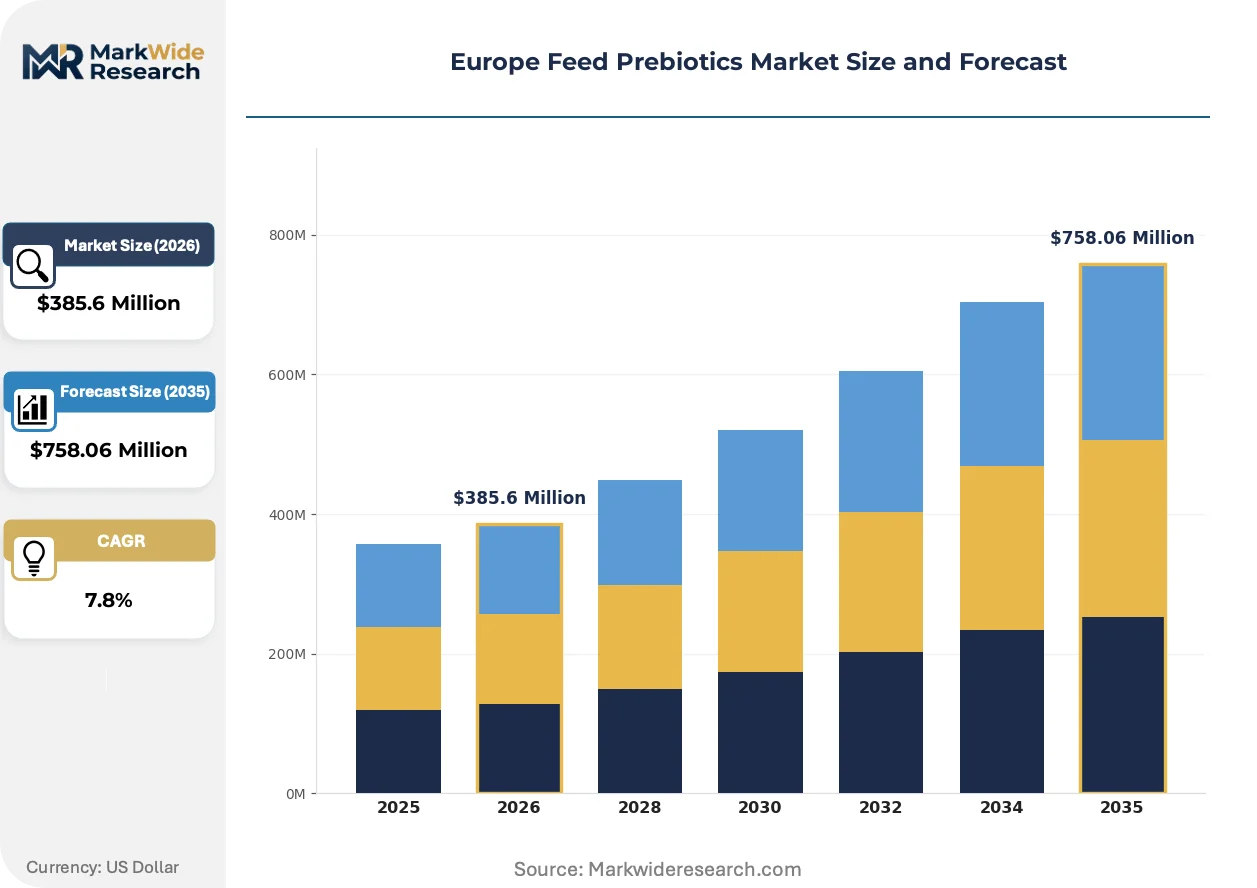
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $758.06 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oligosaccharides, Inulin, Fructo-oligosaccharides, Mannan-oligosaccharides Application: Poultry, Swine, Ruminants, Aquaculture Form: Powder, Granular, Liquid, Pelleted Distribution Channel: Online, Retail, Direct Sales, Distributors |
| Companies Covered | BENEO GmbH, Roquette Frères, Alltech, Inc., FrieslandCampina, Tate & Lyle, Cargill, Incorporated, COSUCRA, Kerry Group, Solvay, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Feed Prebiotics Market Shifts & Advancements
Fermentation-derived prebiotic substrates are displacing extraction-based manufacturing, while regulatory pressure on antibiotic residues is accelerating microbiome-targeted feed formulation across European livestock sectors.
Pea-starch fermentation platforms are expanding into commercial-scale oligosaccharide production, converting legume processing waste streams into functional feed additives. Dutch and French compound feed manufacturers are adopting these substrates at accelerating rates for layer and broiler rations. This technology is expanding into price-sensitive swine applications where chicory-root inulin premiums previously limited inclusion.
REACH compliance requirements for novel carbohydrate feed materials are tightening substance registration thresholds and extending safety data obligations to gut microbiome interaction studies. Industrial consequence includes elevated dossier preparation costs that favor incumbent suppliers with established toxicology portfolios. Poultry feed additive categories face the steepest compliance burden as EFSA prioritizes avian-specific metabolism data for authorization reviews.
Compound feed procurement is consolidating toward direct manufacturer relationships, bypassing traditional distributor networks for prebiotic sourcing. Large integrators in Germany and Spain are negotiating volume contracts that bundle technical support with substrate supply, displacing spot-market purchasing. This pattern is most visible in the broiler sector where margin compression demands feed cost predictability across 12-18 month production cycles.
Europe Feed Prebiotics Market Segmentation
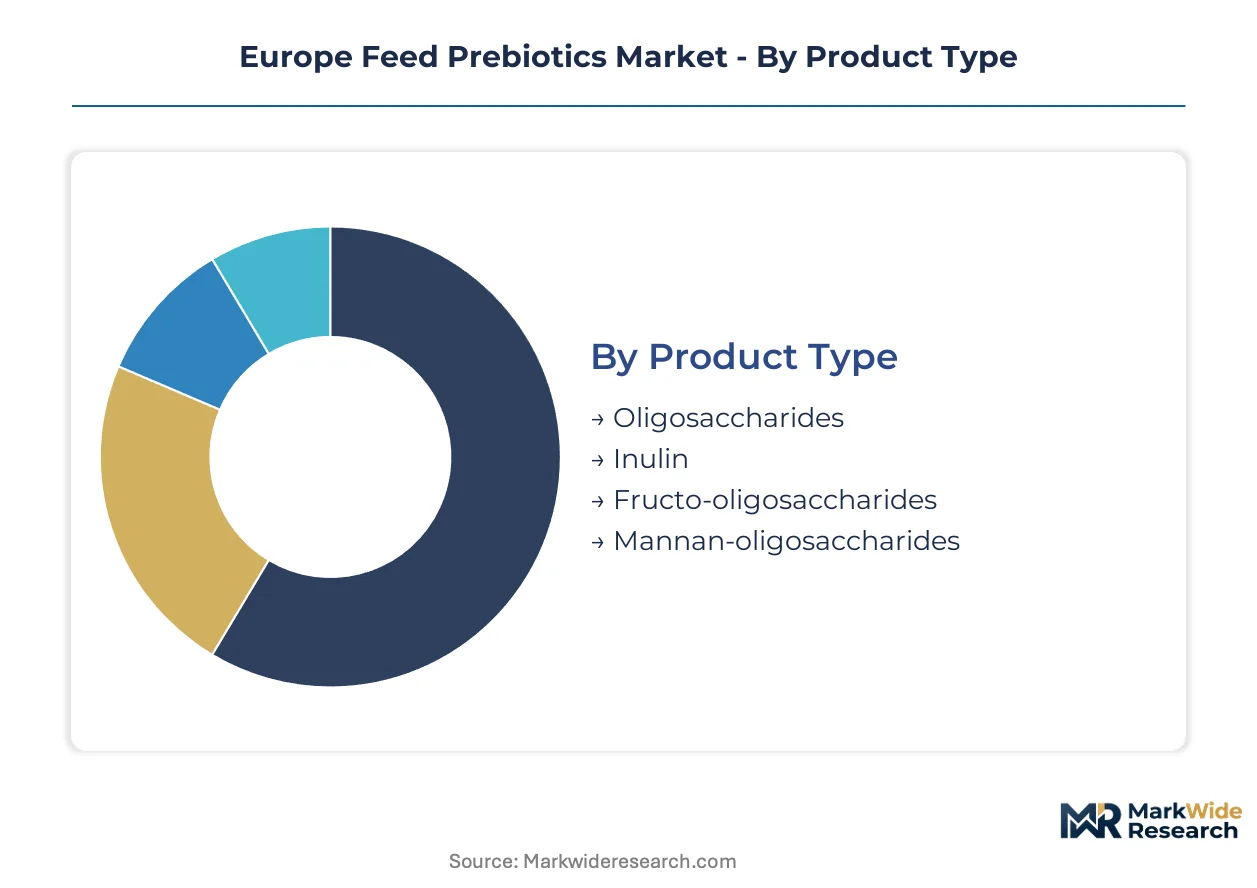
Prebiotic segmentation in European feed markets reflects divergent technical requirements across livestock species and formulation systems. Compound feed manufacturers select substrates based on digestive physiology, processing compatibility, and regulatory authorization status under EFSA pathways.
Product Type:
Integration depth varies sharply: oligosaccharides function as standalone additives with direct dosing protocols, while inulin requires embedding within compound feed matrices for thermal stability during pelleting.
- Oligosaccharides:Short-chain carbohydrate polymers resist upper-gastrointestinal enzymatic hydrolysis and undergo selective colonic fermentation. Demand concentrates in German broiler operations where integrators seek documented pathogen resistance without antibiotic residues. EFSA authorization timelines for novel oligosaccharide substrates extend dossier preparation cycles.
- Inulin:Long-chain fructan extracted primarily from chicory root delivers sustained short-chain fatty acid production through slower fermentation kinetics. Belgian and French agricultural processors anchor supply chains for layer and swine applications where gut microbiome modulation requires extended residence time. Chicory root supply concentration creates input vulnerability for non-integrated suppliers.
- Fructo-oligosaccharides:Partially hydrolyzed inulin fractions balance solubility with fermentation rate for automated dosing systems.
- Mannan-oligosaccharides:Yeast cell wall derivatives bind pathogenic bacteria in poultry intestinal tracts.
Volume placements concentrate in oligosaccharides; the faster expansion belongs to inulin as precision fermentation lowers extraction-dependent supply constraints.
Application:
Cost tier segmentation separates species by feed conversion economics: poultry and aquaculture command premium substrate pricing, while ruminant applications compete with forage-based alternatives on marginal cost.
- Poultry:Monogastric physiology maximizes prebiotic efficacy for pathogen exclusion and nutrient absorption enhancement. Spanish and Polish integrators drive volume through vertically integrated broiler operations subject to EU Green Deal antibiotic reduction mandates. EFSA prioritizes avian-specific metabolism data for authorization reviews, elevating compliance burden.
- Swine:Post-weaning gut flora establishment creates critical window for oligosaccharide intervention. Dutch and Danish sow operations anchor demand for fermentation-derived substrates that displace inulin price premiums in grower-finisher rations. Phytogenic essential oil blends capture budget share where oligosaccharide efficacy documentation remains thinner.
- Ruminants:Forestomach fermentation complicates direct microbiome targeting; prebiotics function primarily as rumen modulators.
- Aquaculture:Norwegian salmon farming creates demand for water-soluble concentrates compatible with automated recirculating system dosing.
Revenue concentration sits with poultry; aquaculture climbs the fastest as liquid formulation technology matures for marine species.
Form:
Customer type segmentation distinguishes between industrial compound feed mills requiring bulk powder handling and specialized aquaculture operations demanding precision liquid integration.
- Powder:Standard physical state for dry feed manufacturing with established metering and blending infrastructure. German and French compound feed manufacturers sustain long-term contracts for bulk oligosaccharide supply. Legacy ERP integration challenges constrain suppliers with dated inventory platforms.
- Granular:Agglomerated particles reduce dust generation and improve flowability in automated handling systems. Poultry feed mills in Lower Saxony prefer granular inulin for thermal stability during extrusion processes. REACH compliance requirements tighten substance registration thresholds for novel carbohydrate physical forms.
- Liquid:Water-soluble concentrates enable precise dosing in aquaculture recirculating systems.
- Pelleted:Pre-extruded substrate forms simplify inclusion in specialty feed rations.
Procurement volume clusters in powder; liquid applications gain share fastest as Norwegian salmon farming expands automated feeding infrastructure.
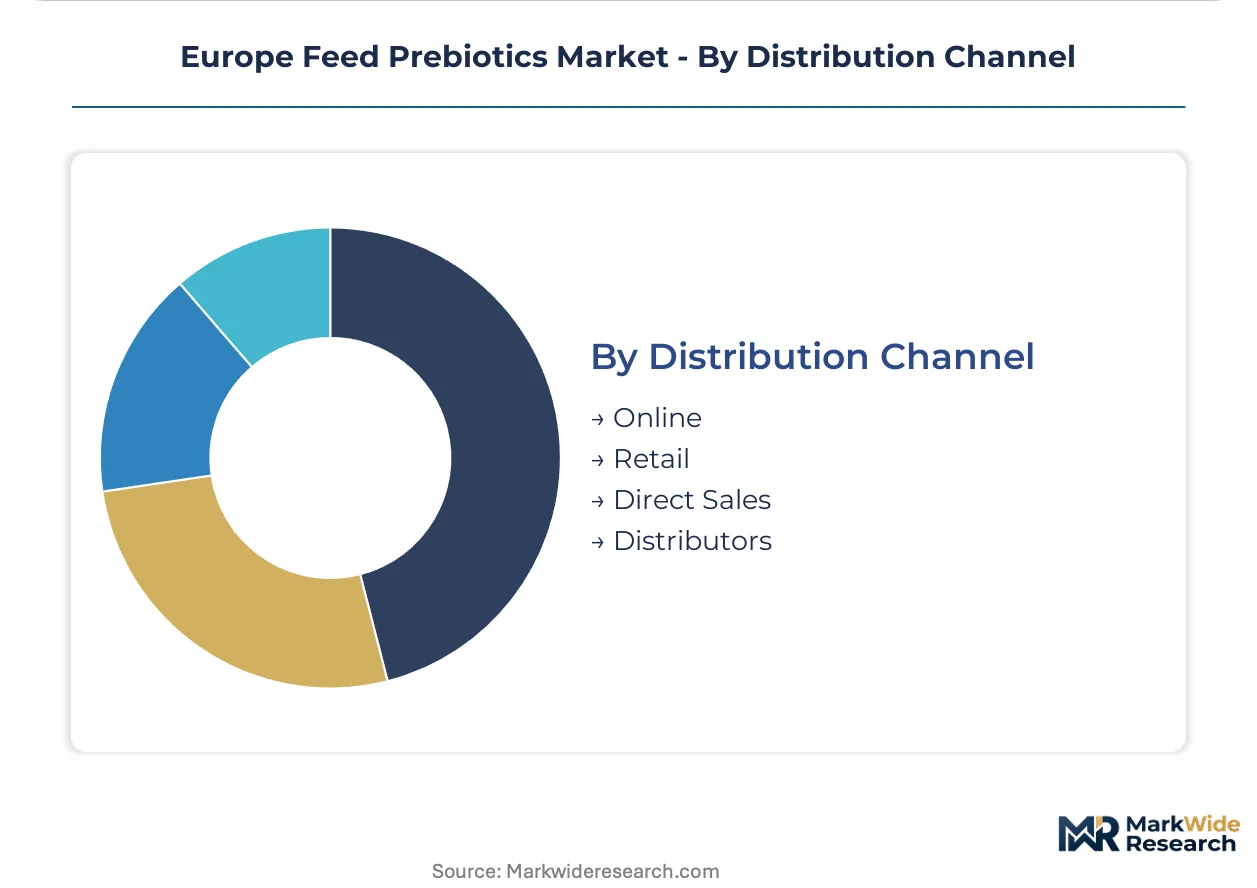
Distribution Channel:
Supply concentration shapes channel selection: direct manufacturer relationships displace distributor networks where compound feed procurement consolidates among large integrators.
- Direct Sales:Volume contracts bundling technical support with substrate supply anchor relationships with German and Spanish broiler integrators. Twelve-to-eighteen month production cycle predictability demands feed cost stability that spot-market purchasing cannot deliver. CE marking harmonization may streamline cross-border manufacturing facility approvals for multi-site producers.
- Distributors:Traditional networks retain relevance for smaller compound feed manufacturers lacking procurement scale for direct negotiation. Polish poultry expansion in Wielkopolska and Mazovia regions outpaces local prebiotic supply infrastructure, creating distributor intermediation opportunities. Margin compression across the broiler sector pressures distributor markup structures.
- Online:Digital procurement platforms serve specialty feed additive sourcing for smaller operations.
- Retail:Limited to hobby farming and smallholder livestock operations with minimal volume significance.
Contract value concentrates in direct sales; online channels expand most quickly as digital procurement platforms penetrate mid-tier compound feed manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lower Saxony's agricultural processing zones concentrate chicory-root extraction capacity and compound feed manufacturing infrastructure that anchors prebiotic supply chains across northwestern Europe.
Germany
Vertically integrated broiler operations in Lower Saxony and North Rhine-Westphalia drive oligosaccharide demand as EU Green Deal antibiotic mandates tighten. EFSA feed additive authorizations under Regulation (EC) No 1831/2003 shape product registration timelines for domestic suppliers. Industrial livestock corridors around Hanover and Münster sustain long-term volume contracts with chicory-root processors.
Spain
Catalonian and Aragonese poultry integrators expand prebiotic inclusion rates in response to Farm to Fork antimicrobial reduction targets. The Spanish Agency for Food Safety and Nutrition enforces feed hygiene standards that align with pending EU Commission revisions. Broiler production clusters in Lleida and Huesca provinces anchor demand for inulin-derived gut health additives.
Poland
Rapid capacity buildout by poultry integrators in Wielkopolska and Mazovia regions outpaces local prebiotic supply infrastructure. National veterinary inspectorate protocols implement EU antibiotic reduction mandates through feed formulation oversight. Poznań and Warsaw metropolitan areas concentrate compound feed manufacturing that sources oligosaccharides from western European suppliers.
Netherlands
Dutch layer and broiler operations adopt fermentation-derived substrates at accelerating rates for cost-sensitive rations. The Netherlands Food and Consumer Product Safety Authority coordinates with EFSA on novel prebiotic dossier reviews. Feed manufacturing corridors in Gelderland and North Brabant integrate pea-starch fermentation platforms into procurement portfolios.
France
Roquette Frères sustains long-term contracts with compound feed manufacturers through its pea-starch fermentation platform in northern production zones. ANSES feed safety evaluations parallel EFSA authorization pathways for novel substrates. Picardy and Hauts-de-France agricultural processing regions concentrate chicory-root and legume extraction capacity serving domestic and export markets.
Europe Feed Prebiotics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with extraction-based incumbents defending positions in poultry applications while fermentation platforms capture swine and layer rations. Market structure concentrates around Belgian and French agricultural processors controlling upstream chicory-root supply. Three archetypes dominate: integrated agricultural processors with captive raw material access, fermentation technology specialists converting legume waste streams, and diversified nutrition multinationals bundling prebiotics within broader feed additive portfolios. Competitive moves center on backward integration into chicory cultivation and precision fermentation capacity expansion.
Among Belgian agricultural processors, BENEO GmbH anchors supply of inulin-derived prebiotics through chicory-root processing infrastructure. Roquette Frères exemplifies the fermentation-specialist archetype with its pea-starch platform serving French and Dutch compound feed manufacturers. FrieslandCampina occupies a position within the dairy-derived prebiotic segment, leveraging whey processing streams for oligosaccharide production.
| Leading Market Players |
|---|
| BENEO GmbH |
| Roquette Frères |
| Alltech, Inc. |
| FrieslandCampina |
| Tate & Lyle |
| Cargill, Incorporated |
| COSUCRA |
| Kerry Group |
| Solvay |
| Others |
Supply & Pricing Matrix
Compound feed procurement consolidation among German and Spanish broiler integrators is forcing prebiotic suppliers to restructure fulfillment models, compressing spot-market margins while elevating contract premiums for guaranteed volume allocation.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as Polish poultry expansion outpaces regional chicory-root processing capacity. Pricing stratifies across premium, standard, and economy tiers, with EFSA-authorized substrates commanding certification premiums and fermentation-derived alternatives capturing share through volume discounts. Cost compression in standard-tier oligosaccharides is intensifying because Roquette Frères and BENEO GmbH are expanding pea-starch and chicory-root capacity respectively. Dutch layer operations exhibit highest price sensitivity, while German broiler integrators prioritize supply security over unit cost.
Supply Chain Analysis
CE marking and REACH substance registration requirements gate market access for non-European suppliers, extending facility qualification timelines. Chicory-root extraction concentrates in Belgium and France, while pea-starch fermentation platforms anchor in the Netherlands and northern France. Raw material dependencies center on chicory root cultivation, legume starch processing, and yeast cell wall derivatives. Single-source vulnerability persists in Belgian inulin extraction, where BENEO GmbH controls captive supply. Distribution runs through direct manufacturer relationships with large integrators, displacing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chicory-root supply concentration in Belgian and French agricultural processors props pricing power for extraction-based incumbents, constraining margin expansion for non-integrated competitors.
For Market Incumbents: Anticipate phytogenic substitution threats in swine applications by accelerating fermentation platform investments and securing long-term chicory cultivation contracts in Picardy and Hauts-de-France. EFSA authorization timeline extensions for novel substrates represent the priority defensive lever, requiring expanded toxicology dossier capabilities. For New Entrants and Emerging Players: Precision fermentation technology offers entry leverage into price-sensitive Dutch layer and Danish sow operations where chicory-root inulin premiums previously limited penetration. Polish poultry expansion in Wielkopolska and Mazovia presents the most penetrable geography, with automated aquaculture liquid dosing systems offering secondary white-space. Go-to-market positioning should emphasize API connectivity for feed mill ERP integration. For Investors and Strategic Acquirers: The window for entry favors fermentation technology specialists with pea-starch or enzymatic synthesis platforms over extraction-dependent incumbents. Long-term viability hinges on backward integration into raw material supply and regulatory dossier depth. Monitor EFSA opinions on novel prebiotic substrates as the inflection signal for authorization-driven competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chicory Cultivation | Captive raw material supply reduces Belgian processor dependency for non-integrated feed additive suppliers. |
| Precision Fermentation Capacity Expansion | Pea-starch platforms displace extraction costs and open price-sensitive swine and layer applications. |
| EFSA Dossier Investment | Accelerated novel substrate authorization timelines defend against phytogenic substitution in growth promoter replacement. |
| Aquaculture Liquid Formulation Development | Water-soluble concentrates align with Norwegian salmon farming automated recirculating system expansion. |
| Direct Integrator Contracting | Twelve-to-eighteen month volume commitments displace distributor markups and secure feed cost predictability. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across feed additive procurement managers, compound feed manufacturing directors, EFSA regulatory affairs specialists, and veterinary nutritionists. Bottom-up volume modeling triangulated against top-down market sizing from FEFAC production statistics, EFSA feed additive authorization databases, and national veterinary inspectorate protocols.
Reconciliation of production volume data, import-export flows, and integrator procurement disclosures shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, livestock application, physical formulation, and distribution channel, with CAGRs derived from time-series analysis of authorization trends and capacity expansion announcements. Feed conversion economics and antibiotic reduction mandate compliance timelines served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including potential EU Commission revisions to feed hygiene regulations and unforeseen phytogenic efficacy breakthroughs. Forecasts reflect documented assumptions regarding EFSA authorization timelines and chicory-root harvest yields. A model refresh is warranted upon material change in Farm to Fork Strategy implementation pace or novel fermentation substrate commercialization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Lipid Nutrition Market
Nutritional Supplements
Vitamin K2 Market
Nutritional Supplements
Aquatic Feed Supplement Market
Nutritional Supplements
Whey Protein Powder Market
Nutritional Supplements
North America Bovine Lactoferrin Market
Nutritional Supplements
Japan Whey Protein Market
Nutritional Supplements
Elderberry Supplements Market
Nutritional Supplements
Garlic Supplements Market
Nutritional Supplements
US Ketones Market
Nutritional Supplements
Omega 3 Supplements Market
Nutritional Supplements
Middle East and Africa Nutricosmetics Market
Nutritional Supplements
Oral Immunostimulant Market
Nutritional Supplements
Lion's Mane Market
Nutritional Supplements
Melatonin Supplements Market
Nutritional Supplements
Custom Supplement Formulation Service Market
Nutritional Supplements
Lactoferrin Products Market