
 Flavonoid Phytogenic Feed Additive Market | 2026-2036
Flavonoid Phytogenic Feed Additive Market Size, Share, and Industry Trends Forecast 2026-2036
Flavonoid Phytogenic Feed Additive Market Insights
European botanical extract producers is recalibrating capacity toward standardized flavonoid isolates for species-specific premixes. Cargill, Incorporated leverages its integrated oilseed processing network to secure quercetin-rich feedstock streams for captive additive production. BIOMIN Holding GmbH sustains its position through dedicated phytogenic research facilities in Austria focused on gut microbiome modulation. Phytobiotics Futterzusatzstoffe GmbH anchors its competitive stance in German-speaking markets through direct technical service teams embedded at feed mill operations.
Flavonoid phytogenic feed additives comprise polyphenolic compounds extracted from botanical sources such as citrus peel, grape seed, and Sophora japonica, standardized to specified quercetin, hesperidin, or rutin concentrations for antioxidant and anti-inflammatory function in animal nutrition. Powder formulations dominate commercial volumes due to blending compatibility with mineral premixes and extended shelf stability under controlled humidity, while liquid concentrates capture premium positioning in automated dosing systems for large aquaculture operations. Poultry applications lead segment value as integrators phase out zinc oxide and ionophore growth promoters across European and Southeast Asian supply chains.
The European Food Safety Authority evaluates novel flavonoid sources under Regulation 1831/2003, creating multi-year approval timelines that favor established suppliers with dedicated regulatory affairs capacity. The FDA Center for Veterinary Medicine maintains distinct Generally Recognized as Safe determinations for specific flavonoid preparations, producing divergent market access conditions between transatlantic jurisdictions. China's Ministry of Agriculture and Rural Affairs publishes permitted feed additive catalogs that restrict certain flavonoid extracts to domestically produced sources, shaping procurement strategies for multinational premix suppliers. Stakeholders must monitor evolving residue monitoring protocols in major importing countries, as maximum limits for botanical marker compounds in meat and aquaculture products remain under scientific review without harmonized international standards.
Market Dynamics
The European Union's Feed Additives Regulation 1831/2003 is compressing approval timelines for novel flavonoid compounds, forcing premix suppliers to consolidate regulatory affairs capacity while redirecting R&D spending toward established botanical sources with existing safety dossiers.
Growth Catalysts
- Antibiotic-free mandates:Poultry integrators in Southeast Asia are expanding flavonoid inclusion rates to replace ionophore growth promoters and zinc oxide in broiler feed formulations.
- EFSA evaluation frameworks:Standardized approval pathways for quercetin and hesperidin isolates are creating definable market access conditions for compliant suppliers with dedicated toxicology data packages.
- Aquaculture automation:Liquid concentrate formulations are capturing positioning in automated dosing systems for large-scale shrimp and salmon operations across coastal zones.
Market Restraints
- Citrus peel supply volatility:Weather-driven fluctuations in Mediterranean and Brazilian orange harvests are creating input cost instability for hesperidin extraction.
- Regulatory friction:China's Ministry of Agriculture and Rural Affairs restricts certain flavonoid extracts to domestically produced sources, fragmenting procurement strategies for multinational premix suppliers.
- Substitution pressure:Synthetic antioxidants and organic acid blends continue to compete on unit cost in price-sensitive feed segments.
Strategic Opportunities
- Underpenetrated aquaculture:Vietnamese and Indonesian shrimp producers represent white space for standardized rutin premixes targeting oxidative stress management in intensive pond systems.
- Regulatory tailwinds:The EU Green Deal's farm-to-fork strategy is accelerating botanical additive adoption through residue monitoring alignment and reduced chemical inputs targets.
- Species-specific premixes:Gut microbiome modulation research is enabling differentiated positioning for swine and ruminant applications beyond established poultry markets.
Industry Challenges
- Regulatory affairs talent scarcity:Multi-year EFSA approval timelines require specialized toxicologists and dossier preparation expertise that concentrates in established European suppliers.
- Standardization delays:Non-harmonized maximum residue limits for botanical marker compounds across major meat-importing jurisdictions are complicating export certification for integrated producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flavonoid Phytogenic Feed Additive Market |
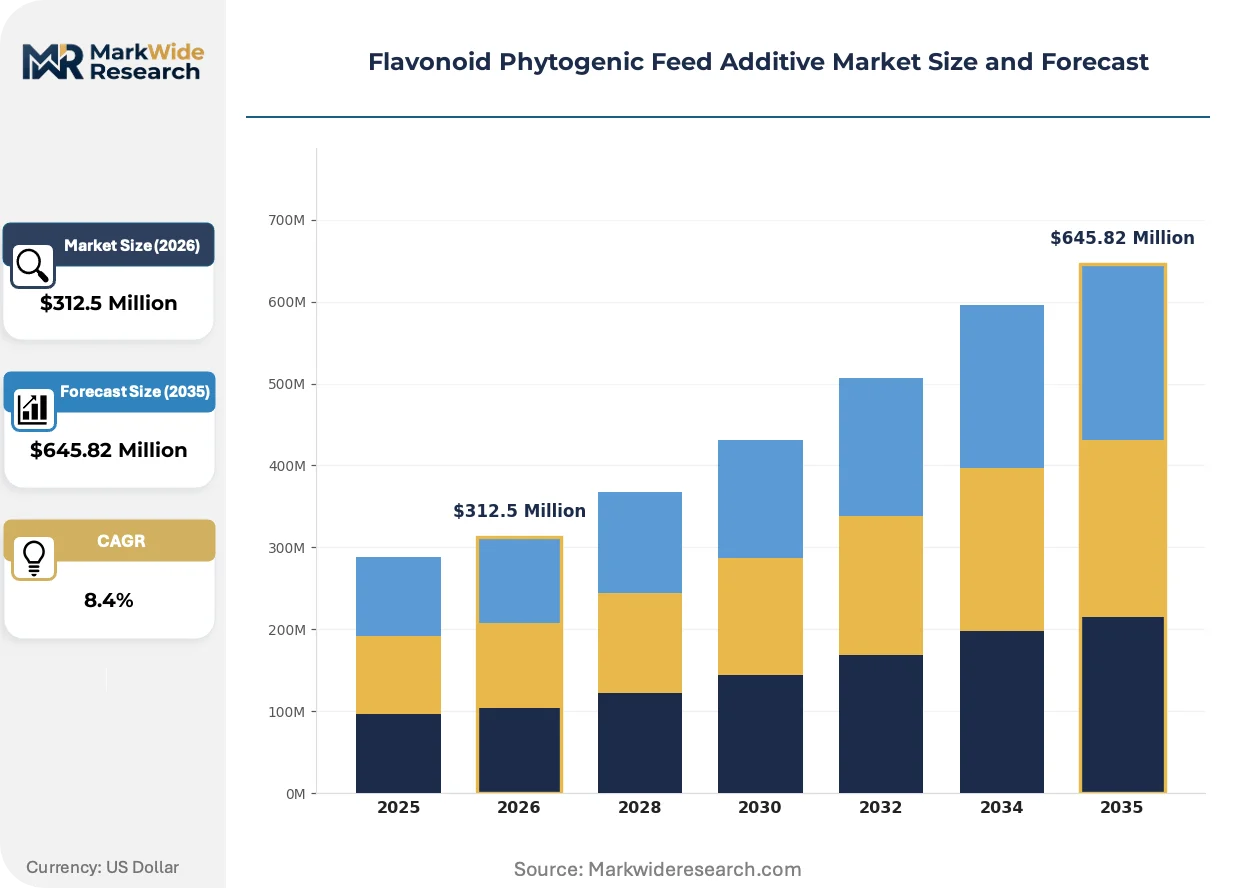
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $645.82 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granular, Concentrate Application: Poultry, Ruminants, Swine, Aquaculture End User: Farmers, Feed Manufacturers, Veterinarians, Distributors Distribution Channel: Online, Offline, Direct Sales, Retail |
| Companies Covered | Cargill, Incorporated, BIOMIN Holding GmbH, Bluestar Adisseo, Kemin Industries, Inc., DuPont, Phytobiotics Futterzusatzstoffe GmbH, Synthite Industries Ltd., Nor-Feed, MIAVIT Holding, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flavonoid Phytogenic Feed Additive Market Trends and Innovations
Bioprocessing advances and regulatory data requirements are reshaping how flavonoid isolates move from botanical extraction to species-specific premix formulation.
Microencapsulation technology is integrating lipid-based coating systems to protect quercetin and hesperidin from rumen degradation in dairy and beef cattle applications. North American and European ruminant nutritionists are adopting these protected forms at accelerating rates. The technology is integrating antioxidant delivery into precision feeding programs that were previously inaccessible to polyphenolic compounds.
EFSA's 2023 updated guidance on botanical additive characterization is requiring suppliers to standardize marker compound specifications and stability data across batch records. This industrial consequence is elevating capital requirements for analytical infrastructure and third-party validation. Poultry premix manufacturers serving EU export markets are responding by consolidating supplier bases toward vertically integrated extract producers with captive QC laboratories.
Integrated broiler operations in Brazil are consolidating procurement through mandated botanical premix specifications that bypass traditional distributor channels. Major processors are establishing direct technical partnerships with phytogenic suppliers, displacing independent feed mill formulators. This pattern is most visible in São Paulo and Paraná production clusters where contract farming density enables centralized additive specification.
Flavonoid Phytogenic Feed Additive Market Segmentation
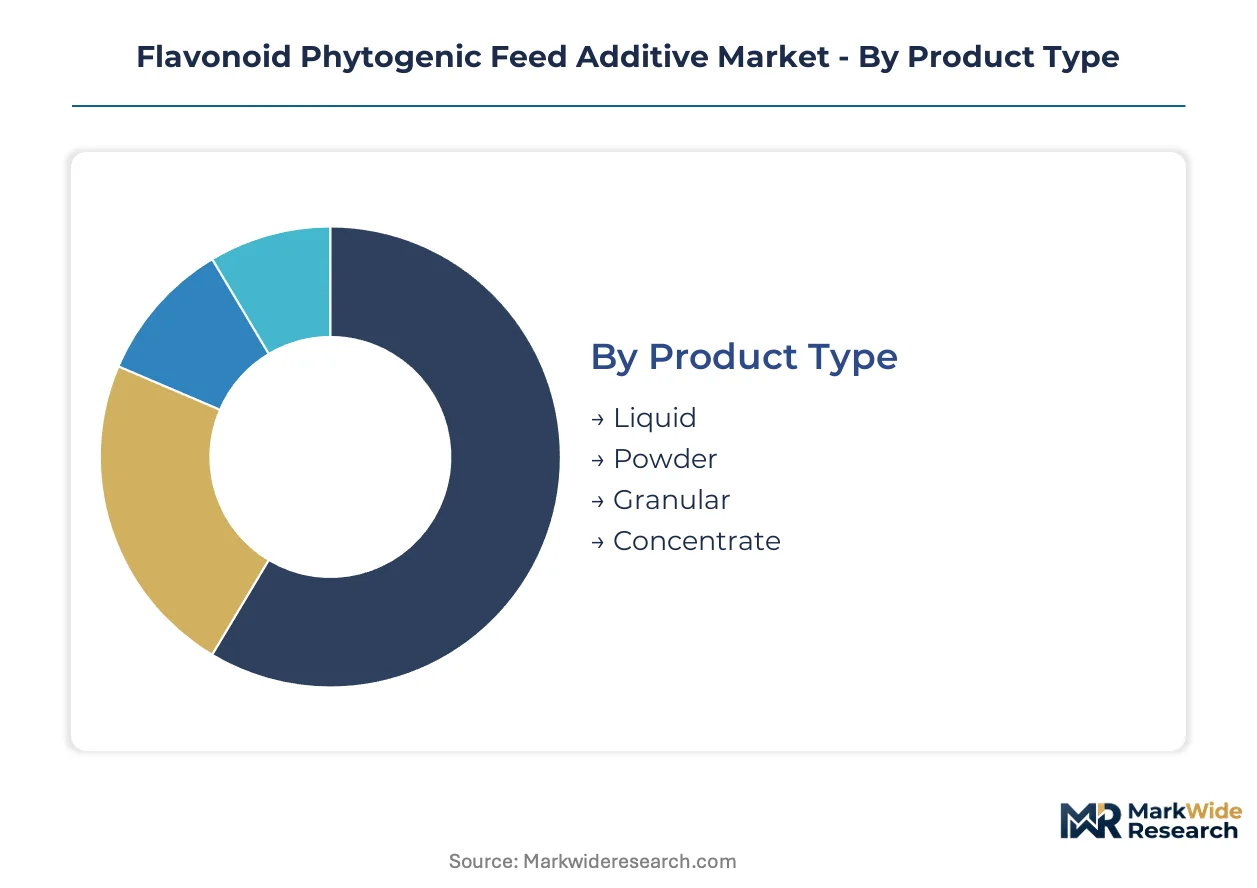
Flavonoid phytogenic feed additive purchasing decisions hinge on formulation compatibility, species-specific efficacy requirements, and regulatory compliance pathways. Understanding how these dimensions intersect enables suppliers to align production capacity with the most profitable demand concentrations.
Product Type:
Powder formulations dominate procurement volumes due to blending economics and mineral premix compatibility, while liquid concentrates command premium positioning in automated systems.
- Powder:Dry quercetin and hesperidin isolates blended with carriers for homogeneous distribution in mineral premixes. Southeast Asian poultry integrators specify powder grades for antibiotic-free broiler programs. Powder leads on scale; Concentrate leads on momentum.
- Liquid:Standardized flavonoid solutions in propylene glycol or water bases for automated dosing equipment. Large shrimp operations across Vietnamese coastal zones adopt liquid rutin formulations for pond-side application.
- Granular:Agglomerated particles with controlled release properties for ruminant applications. Brazilian feed manufacturers specify granular hesperidin for TMR stability.
- Concentrate:High-potency extracts requiring dilution before inclusion. Specialized aquaculture nutritionists in Indonesia source quercetin concentrates for custom premix formulation.
Powder leads on scale; Concentrate leads on momentum.
Application:
Species-specific gut health challenges and regulatory pressure on growth promoters determine flavonoid inclusion rates across livestock categories.
- Poultry:Broiler and layer operations utilize quercetin and hesperidin for antioxidant support and coccidiosis management alternatives. European integrators phasing out ionophores drive standardized premix demand.
- Ruminants:Microencapsulated rutin formulations protect polyphenols from rumen degradation while delivering post-ruminal antioxidant activity. North American dairy nutritionists adopt protected forms at accelerating rates.
- Swine:Post-weaning gut integrity applications utilize flavonoid blends for inflammatory modulation. German-speaking markets show concentrated demand for species-specific premixes.
- Aquaculture:Intensive shrimp and salmon operations employ liquid concentrates for oxidative stress management in high-density systems. Vietnamese and Indonesian producers represent expansion opportunities.
Poultry leads on scale; Aquaculture leads on momentum.
End User:
Technical service requirements and formulation expertise determine channel economics across buyer categories.
- Feed Manufacturers:Industrial compounders purchase bulk flavonoid isolates for captive premix production. Major Brazilian processors mandate standardized botanical specifications bypassing distributor channels.
- Farmers:Direct procurement concentrates in contract farming clusters with centralized additive programs. São Paulo broiler operations specify premixes through processor-negotiated supply agreements.
- Veterinarians:Prescription-oriented flavonoid applications for therapeutic gut health protocols. Austrian research facilities support veterinary recommendation networks.
- Distributors:Independent feed additive resellers face displacement as integrated operations consolidate procurement. Traditional channels retain relevance in fragmented livestock regions.
Feed Manufacturers lead on scale; Farmers lead on momentum.
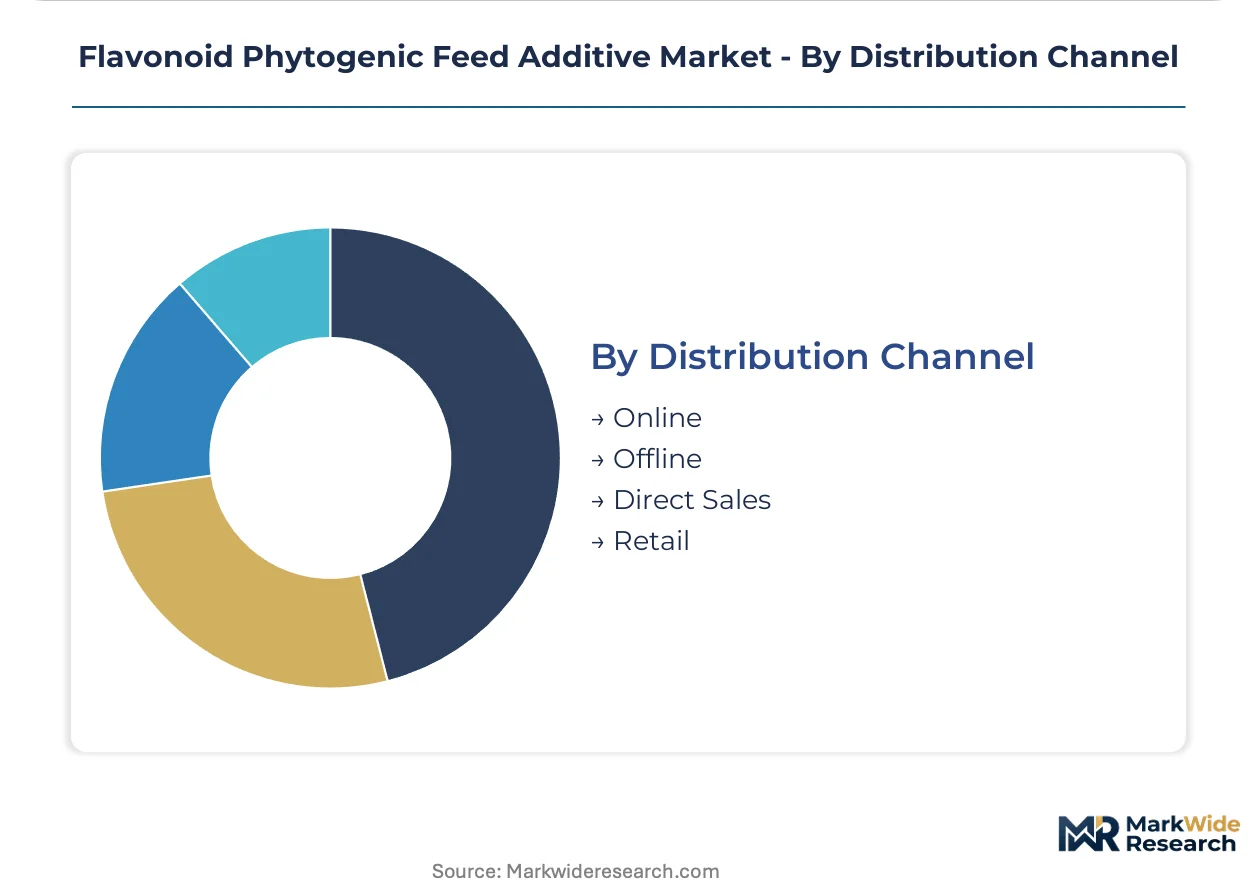
Distribution Channel:
Supply chain configuration reflects technical complexity, volume scale, and buyer sophistication across market tiers.
- Direct Sales:Technical partnerships between extract producers and integrated livestock operations. Cargill's captive oilseed processing secures quercetin feedstock for direct additive supply.
- Offline:Traditional distributor and feed mill relationships serving independent producers. German-speaking markets retain embedded technical service teams at mill operations.
- Online:Digital procurement platforms emerging for standardized commodity grades. Smaller aquaculture operations access liquid concentrates through specialized e-commerce channels.
- Retail:Limited presence for flavonoid additives due to formulation expertise requirements. Hobby farming segments in select European markets show minimal traction.
Direct Sales leads on scale; Online leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's integrated broiler processors mandate standardized botanical premix specifications at volumes exceeding Southeast Asian poultry integrators, while European extract producers recalibrate capacity toward species-specific isolates under tightening regulatory timelines.
Brazil
São Paulo and Paraná contract farming clusters drive concentrated demand for granular hesperidin formulations in TMR-stable premixes. ANVISA maintains distinct approval pathways for novel phytogenic compounds that lag behind EU EFSA timelines by 18-24 months. Major processors in the São Paulo production belt bypass independent distributors through direct technical partnerships with extract suppliers.
Germany
German-speaking markets concentrate demand for swine-specific flavonoid premixes targeting post-weaning gut integrity protocols. EFSA's updated 2023 botanical additive characterization guidance forces suppliers to standardize marker compound specifications across batch records. Phytobiotics Futterzusatzstoffe GmbH embeds technical service teams directly at feed mill operations throughout Bavaria and Lower Saxony.
United States
North American dairy nutritionists adopt microencapsulated rutin formulations at accelerating rates for post-ruminal antioxidant delivery. FDA Center for Veterinary Medicine maintains distinct GRAS determinations for specific flavonoid preparations that diverge from EU safety dossier requirements. Midwest compound feed manufacturers in Iowa and Illinois consolidate procurement toward vertically integrated extract producers with captive QC laboratories.
Vietnam
Intensive shrimp operations across Mekong Delta coastal zones represent underpenetrated white space for liquid rutin concentrates in automated pond-side dosing systems. The Ministry of Agriculture and Rural Affairs restricts certain flavonoid extracts to domestically produced sources, complicating multinational premix supplier entry. Vietnamese aquaculture clusters in Bà Rịa-Vũng Tàu province pilot standardized oxidative stress management protocols without ionophore alternatives.
China
Domestic feed additive catalogs limit procurement flexibility for multinational premix suppliers seeking quercetin-rich feedstock integration. The Ministry of Agriculture and Rural Affairs publishes permitted additive lists that favor captive production by state-aligned extract processors. Yangtze River Delta compounders source standardized hesperidin isolates through backward-integrated citrus processing networks in Jiangxi and Hunan provinces.
Flavonoid Phytogenic Feed Additive Market Competitive Landscape
European botanical extract producers anchor one tier; North American and Asian specialists hold differentiated positions through captive supply arrangements and technical service embedding. The vendor base stratifies across three structural tiers: vertically integrated agribusiness conglomerates with oilseed processing networks, dedicated phytogenic research houses with regulatory affairs capacity, and regional extract specialists serving domestic catalog restrictions. Two dominant competitive moves reshape positioning: direct technical partnerships that displace traditional distributor channels, and microencapsulation technology licensing for ruminant application expansion.
Within the integrated agribusiness tier, Cargill, Incorporated exemplifies backward integration into quercetin feedstock streams through captive oilseed processing assets. Among European research-focused specialists, BIOMIN Holding GmbH occupies a position defined by dedicated Austrian facilities targeting gut microbiome modulation, while Phytobiotics Futterzusatzstoffe GmbH anchors its stance through embedded technical service teams at German-speaking feed mill operations. These three entities represent distinct archetypes: commodity-scale feedstock security, research-driven species-specific formulation, and relationship-intensive regional market penetration.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| BIOMIN Holding GmbH |
| Bluestar Adisseo |
| Kemin Industries, Inc. |
| DuPont |
| Phytobiotics Futterzusatzstoffe GmbH |
| Synthite Industries Ltd. |
| Nor-Feed |
| MIAVIT Holding |
| Others |
Pricing and Supply Chain Analysis
Specialized toxicologists and dossier preparation experts concentrated in Austria and Germany command premium compensation that widens spreads between premium-certified and economy-grade flavonoid isolates. Labor-cost differentials between established European regulatory affairs hubs and emerging extraction centers in Brazil directly feed into tiered pricing structures across quercetin and hesperidin product lines.
Pricing Analysis
Capacity additions in Brazil are reshaping price floors for standardized hesperidin isolates as backward-integrated citrus processors expand captive extraction capabilities. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-compliant certified grades from catalog-restricted domestic Chinese sources and unstandardized commodity extracts. Cost compression in economy tiers is intensifying because Vietnamese and Indonesian aquaculture buyers prioritize unit economics over marker compound standardization. Contract farming clusters in São Paulo show least price sensitivity due to processor-mandated specifications, while independent Southeast Asian poultry integrators exhibit highest elasticity.
Supply Chain Analysis
Skilled analytical chemists and regulatory dossier specialists cluster disproportionately in Austria, Germany, and the Netherlands, creating workforce bottlenecks for quality control infrastructure expansion. Geographic supply concentration centers on Brazil for citrus-derived hesperidin, China for Sophora japonica quercetin, and Vietnam for emerging rutin extraction capacity. Raw material dependencies include Mediterranean and Brazilian orange peel harvests, oilseed processing byproduct streams, and aquaculture operation proximity for liquid concentrate delivery. Single-source vulnerability runs through EFSA-approved toxicology data packages concentrated in established European suppliers. Distribution runs through direct technical partnerships displacing traditional feed additive distributors in integrated broiler operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in flavonoid phytogenics rests on automation-driven cost reduction in liquid concentrate production and accelerated premium-tier adoption for microencapsulated ruminant formulations.
For Market Incumbents: Anticipate regulatory friction from China's Ministry of Agriculture and Rural Affairs catalog restrictions by securing dual-registered production assets in domestic Chinese extraction facilities. Consolidate supplier relationships toward vertically integrated oilseed processors with captive quercetin feedstock security. Prioritize EFSA dossier maintenance investments to defend against multi-year approval timeline compression for novel botanical sources. For New Entrants and Emerging Players: Capture Vietnamese and Indonesian shrimp aquaculture white space through automated pond-side dosing system partnerships offering liquid rutin concentrates with technical service embedding. Target species-specific swine premix demand in German-speaking markets where post-weaning gut integrity protocols concentrate purchasing decisions. Differentiate through microencapsulation technology licensing rather than commodity extract competition. For Investors and Strategic Acquirers: Integrated agribusiness conglomerates with oilseed processing networks are the most active acquirer in this space, seeking captive additive production capabilities. Long-term viability over the next decade hinges on regulatory affairs capacity concentration and species-specific formulation R&D depth. Monitor EFSA approval timeline compression and residue limit harmonization progress as inflection indicators for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Licensing | Enables post-ruminal antioxidant delivery for North American dairy nutritionists adopting protected rutin forms. |
| Backward Integration into Oilseed Processing | Cargill's captive quercetin feedstock streams demonstrate supply security for standardized isolate production. |
| Direct Technical Partnership Establishment | Brazilian processors bypass distributors through embedded supplier relationships in São Paulo contract farming clusters. |
| EFSA Dossier Consolidation Investment | Multi-year approval timelines favor established suppliers with dedicated toxicology data package capabilities. |
| Species-Specific Premix Formulation Expansion | BIOMIN's Austrian gut microbiome modulation facilities anchor differentiation beyond commodity poultry applications. |
Research Methodology
Direct dialogue with regulatory affairs directors at European extract producers, procurement leads at Brazilian integrated broiler processors, aquaculture nutritionists across Vietnamese coastal zones, and feed mill formulators in German-speaking markets grounded qualitative assessment. Secondary validation drew from EFSA botanical additive guidance documents, FDA Center for Veterinary Medicine GRAS determinations, Chinese Ministry of Agriculture feed additive catalogs, and customs trade data for citrus peel and flavonoid isolate flows. Bottom-up segment sizing triangulated against top-down market aggregation across powder, liquid, granular, and concentrate formulation categories.
Bottom-up modeling tracked species-specific inclusion rates by poultry, ruminant, swine, and aquaculture applications across the analysis window. Segmentation dimensions spanned product type, application, end user, and distribution channel with regional regulatory cluster overlays. CAGRs derived from weighted average growth trajectories incorporating antibiotic-free mandate acceleration, EFSA approval pathway standardization, and aquaculture automation penetration. Industry-specific inputs included ionophore growth promoter phase-out timelines and residue monitoring protocol evolution in major meat-importing jurisdictions.
Underlying measurement precision varies by segment; EFSA-compliant European markets carry tighter precision than fragmented Southeast Asian distributor channels. Forecasts reflect documented assumptions regarding regulatory timeline stability and citrus harvest yield patterns. Material deviation in China's catalog restriction enforcement or Brazilian processor consolidation pace warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Water Enhancer Market
Food Enhancers and Additives
Enriched Yeast Extract Market
Food Enhancers and Additives
France Water Enhancer Market
Food Enhancers and Additives
Emulsifier Enhancers Market
Food Enhancers and Additives
Kaempferol Market
Food Enhancers and Additives
Raising Agents Market
Food Enhancers and Additives
Feed Palatability Enhancers and Modifiers Market
Food Enhancers and Additives
Germany Food Flavor and Enhancer Market
Food Enhancers and Additives
Vegetable Shortening Market
Food Enhancers and Additives
Africa Water Enhancer Market
Food Enhancers and Additives
Germany Water Enhancer Market
Food Enhancers and Additives
Isoprenol Market
Food Enhancers and Additives
Instant Whipping Agents Market
Food Enhancers and Additives
Thaumatin Market
Food Enhancers and Additives
Asia-Pacific Food Flavor and Enhancer Market
Food Enhancers and Additives
Frying Shortening Market