
 Oral Immunostimulant Market | 2026-2036
Oral Immunostimulant Market Size, Share, and Industry Trends Forecast 2026-2036
Oral Immunostimulant Market Analytics
EU MDR is recalibrating the cost-of-entry calculus for oral immunostimulant manufacturers seeking CE-marked status in Europe. Bayer AG leverages its established pharmaceutical distribution network to sustain shelf presence across German pharmacy chains. Pfizer Inc. anchors its position through R&D intensity in respiratory immunostimulant formulations. Nestlé Health Science differentiates via product specialization in probiotic-driven gastrointestinal immune modulation.
Oral immunostimulants comprise biologically active compounds delivered through the gastrointestinal tract to modulate innate or adaptive immune responses, typically formulated as stabilized probiotic cultures, standardized herbal extracts, or enzymatic preparations with defined colony-forming unit counts or marker compound concentrations. These agents serve commercial and clinical purposes by reducing infection recurrence frequency or attenuating inflammatory pathways in chronic conditions. Probiotics dominate current revenue pools due to established consumer familiarity and pharmacy reimbursement pathways in European markets, while herbal extracts represent the fastest-growing category as clinicians seek alternatives to pharmaceutical immunosuppression. The homecare delivery channel is expanding structurally as post-acute protocols shift oral immunostimulant administration from hospital infusion centers to patient-controlled regimens.
FDA maintains oversight of oral immunostimulants marketed as dietary supplements through post-market adverse event monitoring and Good Manufacturing Practice inspections, while EMA influences European demand through its evolving stance on immune health claims under the Nutrition and Health Claims Regulation. India's CDSCO requires clinical trial data for probiotic formulations exceeding defined potency thresholds, constraining import pathways for non-domestic manufacturers. Stakeholders must monitor regulatory divergence between pharmaceutical-grade and food-supplement classification pathways, as this boundary determination will dictate which development programs require full clinical trial investment versus streamlined notification procedures.
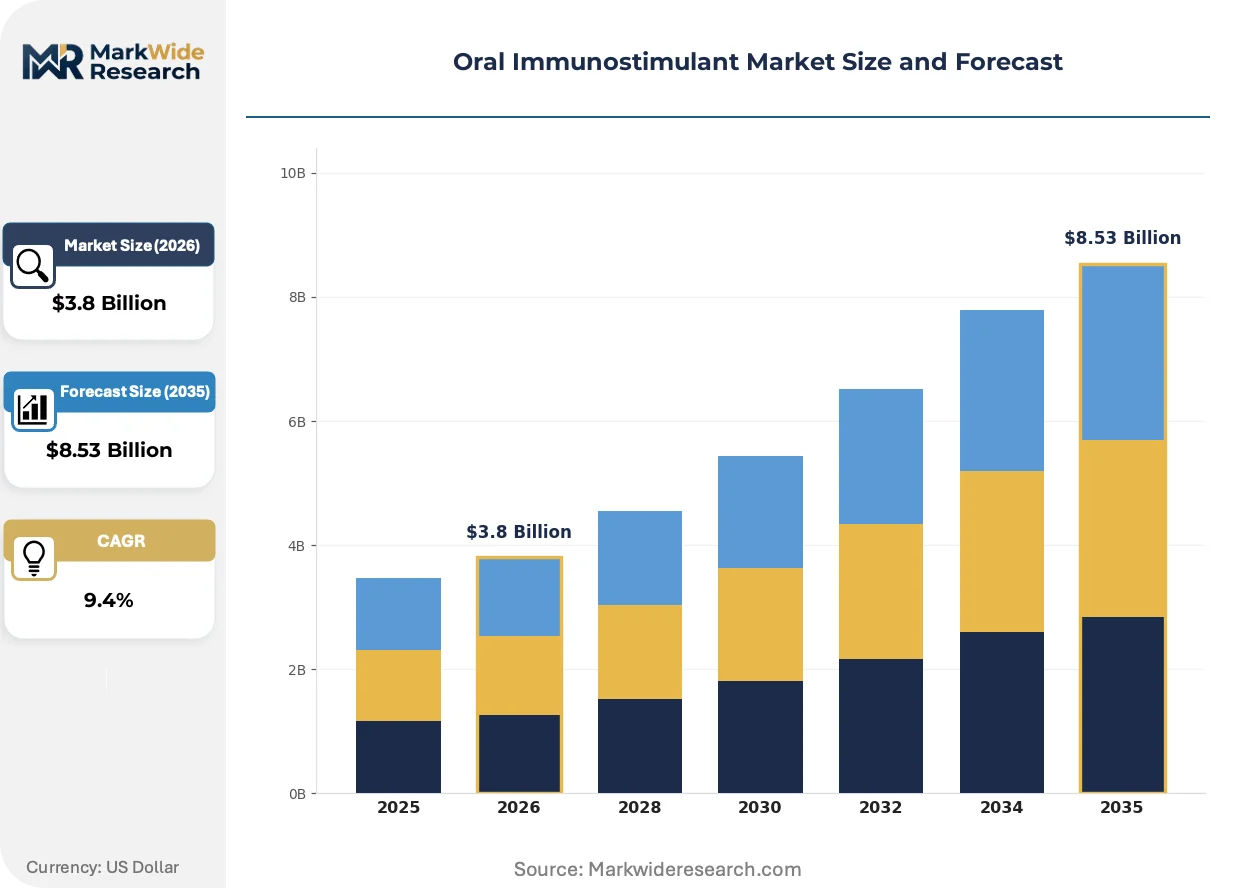
Market Dynamics
EU MDR clinical evidence requirements are compressing development timelines for CE-marked oral immunostimulants while simultaneously elevating barriers for nutraceutical entrants without pharmaceutical-grade trial infrastructure.
Growth Catalysts
- Post-acute protocol decentralization:Hospital outpatient departments are routing stable patients to homecare regimens, expanding addressable volume for patient-administered oral formulations.
- EMA immune health claim evolution:The Nutrition and Health Claims Regulation pathway is clarifying evidentiary standards for probiotic immunomodulation, reducing regulatory ambiguity for substantiated products.
- German pharmacy distribution depth:Structural reimbursement alignment between statutory health insurers and pharmacy-led probiotic dispensing has created replicable commercial infrastructure.
Market Restraints
- Live culture supply concentration:Industrial-scale probiotic fermentation capacity clusters with a limited set of European contract manufacturers, creating single-source vulnerability.
- Herbal extract standardization cost volatility:Marker compound quantification requires HPLC-MS infrastructure that mid-tier formulators cannot amortize across limited SKU counts.
- CDSCO potency threshold trials:India's requirement for clinical data on high-CFU probiotic formulations blocks direct import pathways for manufacturers lacking domestic trial partnerships.
Strategic Opportunities
- Respiratory indication expansion:Clinicians are prescribing oral immunostimulants for recurrent upper respiratory tract infection prophylaxis, opening a therapeutic category beyond gastrointestinal applications.
- Homecare channel infrastructure:Direct-to-patient delivery platforms are capturing post-discharge immunostimulant adherence monitoring, bypassing traditional pharmacy intermediation.
- PLI scheme localization:India's production-linked incentive framework for pharmaceutical manufacturing is attracting fermentation capacity investment to serve Asian market demand.
Industry Challenges
- Clinical immunology talent scarcity:Formulation science programs produce insufficient graduates with dual competency in microbiome characterization and GMP manufacturing.
- EU MDR technical documentation burden:CE-marked oral immunostimulants require systematic literature reviews and post-market surveillance systems that strain mid-cap regulatory affairs functions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oral Immunostimulant Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotics, Nutraceuticals, Herbal Extracts, Enzymes Therapy Area: Gastrointestinal Health, Respiratory Infections, Autoimmune Disorders, Allergy Management End User: Clinics, Hospitals, Pharmacies, Homecare Delivery Mode: Tablet, Powder, Liquid, Capsule |
| Companies Covered | Bayer AG, Pfizer Inc., Nestlé Health Science, GlaxoSmithKline plc, Novartis AG, Amgen Inc., Johnson & Johnson, Merck & Co., Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oral Immunostimulant Market Evolving Landscape
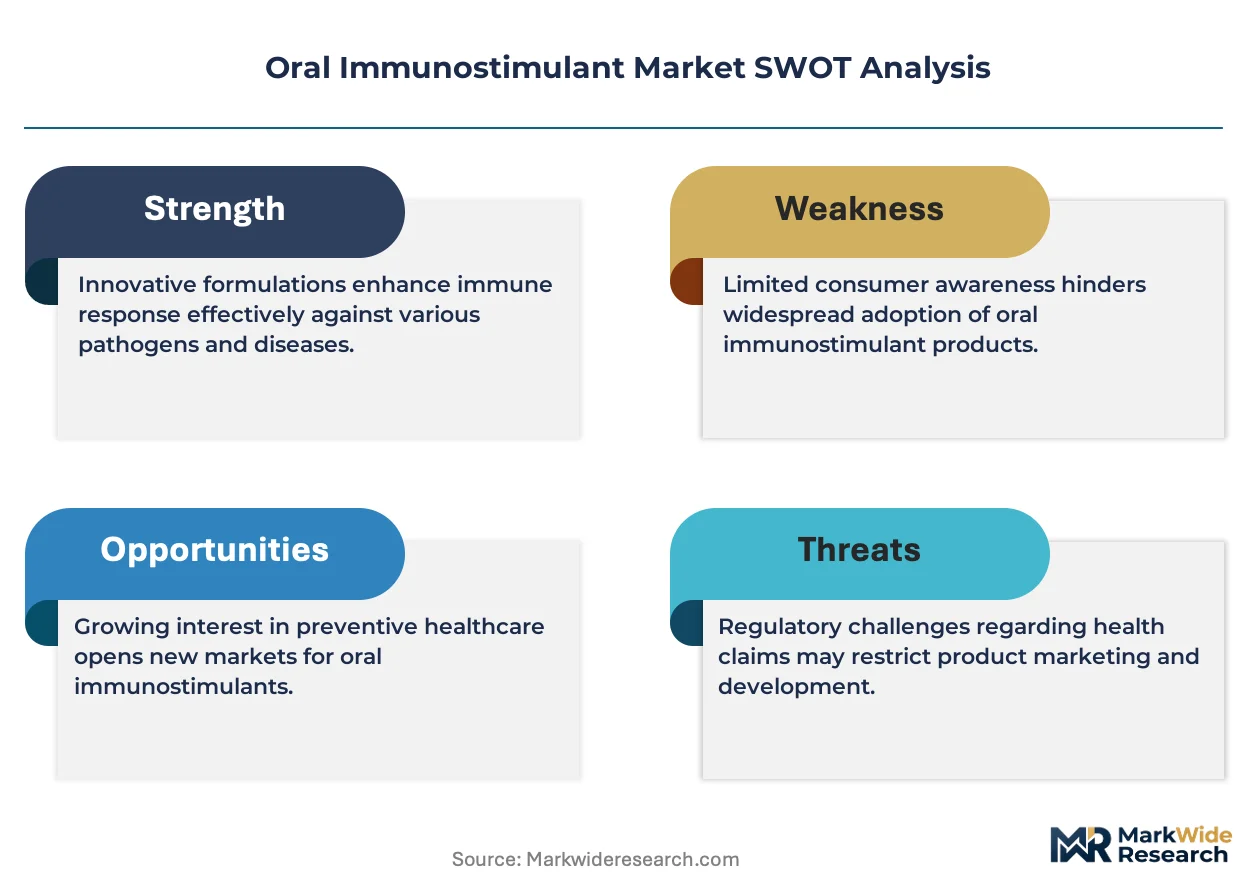
Live biotherapeutic product classification is blurring boundaries between pharmaceutical and food-supplement development pathways, forcing manufacturers to place parallel bets on regulatory strategies with divergent capital requirements.
Multi-strain probiotic consortia engineering is converging with CRISPR-guided metabolic pathway optimization to enhance short-chain fatty acid output. Academic medical centers in Germany and the Netherlands are adopting these next-generation formulations for irritable bowel syndrome with immune comorbidity. The technology is converging with pharmaceutical-grade manufacturing standards, compressing the historical separation between nutraceutical and prescription development pipelines.
EU MDR Article 10 clinical evidence requirements are extending to immune-modulating devices and borderline products, compelling manufacturers to generate randomized trial data for claims previously supported by observational studies. The regulation is forcing portfolio rationalization as smaller players exit categories where trial investment cannot be recovered. German notified bodies are experiencing backlog congestion, delaying CE-marked product launches by twelve to eighteen months.
Hospital procurement committees are unbundling oral immunostimulant selection from broad-spectrum antibiotic formulary decisions, creating separate evaluation tracks for immune-modulating agents. Pharmacy benefit managers in North American health systems are establishing distinct reimbursement tiers for evidence-grade probiotics versus commodity supplements. This pattern is most visible in integrated delivery networks where total cost-of-care contracts incentivize infection prevention over treatment.
Oral Immunostimulant Market Segmentation
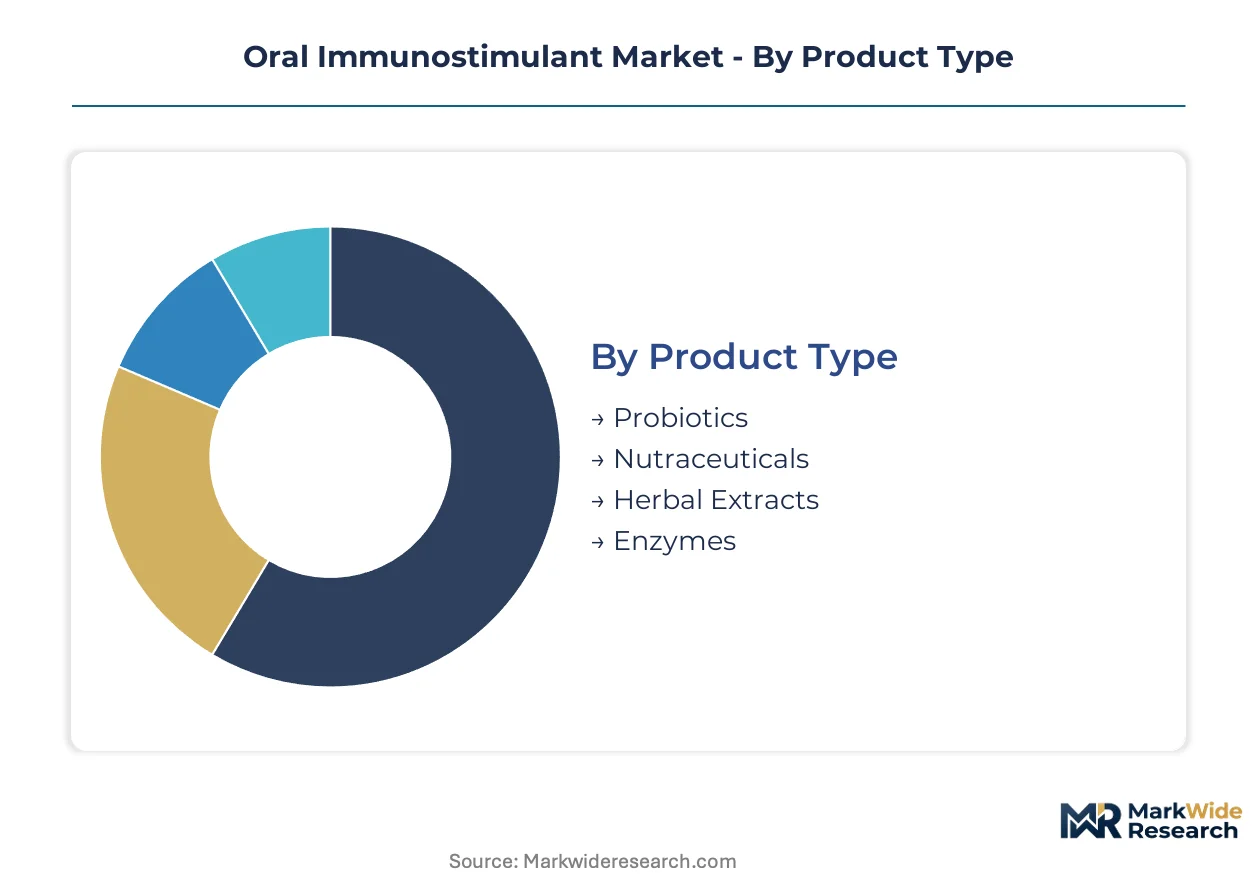
Segmentation in oral immunostimulants reveals divergent capital requirements across product categories. Probiotic fermentation infrastructure demands heavy fixed investment, while herbal extraction operates on more flexible asset bases.
Product Type:
Probiotic manufacturing ties up capital in bioreactor capacity and cold-chain logistics, whereas enzymatic production requires specialized purification systems with shorter depreciation cycles.
- Probiotics:Live bacterial cultures stabilized through lyophilization or microencapsulation, with defined colony-forming unit counts ensuring batch-to-batch consistency. Demand clusters in German pharmacy chains where statutory reimbursement creates predictable volume. Capital intensity peaks here due to multi-stage fermentation and stringent temperature controls.
- Nutraceuticals:Vitamin-mineral complexes and prebiotic fibers formulated for immune modulation through micronutrient repletion. Hospital outpatient departments in the Netherlands are standardizing these into post-surgical protocols. Manufacturing flexibility allows contract manufacturers to serve multiple therapeutic categories from shared blending lines.
- Herbal Extracts:Standardized botanical preparations with quantified marker compounds like polysaccharides or alkaloids. Echinacea and astragalus extracts lead prescription volumes in French phytotherapy practices.
- Enzymes:Proteolytic and fibrinolytic preparations targeting immune-inflammatory pathways through substrate modulation. Japanese functional food manufacturers dominate specialty enzyme supply.
Most installed capacity flows through Probiotics. Expansion is steepest in Herbal Extracts.
Therapy Area:
Application focus determines clinical trial burden and regulatory pathway selection, with gastrointestinal indications offering clearer biomarker endpoints than systemic immune modulation.
- Gastrointestinal Health:Irritable bowel syndrome with immune comorbidity and post-antibiotic dysbiosis represent the addressable population. Academic medical centers in Germany and the Netherlands are adopting multi-strain consortia for these indications. Microbiome characterization tools have sharpened trial design, reducing placebo response rates.
- Respiratory Infections:Recurrent upper respiratory tract infection prophylaxis in pediatric and elderly populations. Clinicians in Swiss primary care networks are prescribing oral immunostimulants as adjuncts to standard vaccination. Seasonal demand patterns create working capital challenges for manufacturers.
- Autoimmune Disorders:Adjunctive modulation of inflammatory pathways in rheumatoid arthritis and inflammatory bowel disease. EMA scrutiny of immune health claims has slowed commercialization in this category.
- Allergy Management:Desensitization support and mast cell stabilization for allergic rhinitis and atopic dermatitis. Austrian specialist clinics have integrated these into step-care algorithms.
Gastrointestinal Health commands the deepest clinical evidence base. Respiratory Infections are climbing the fastest as prophylactic prescribing expands.
End User:
Channel selection dictates packaging specifications, reimbursement complexity, and patient education requirements, with institutional procurement favoring unit-dose formats.
- Clinics:Specialist outpatient settings managing chronic immune conditions through repeat prescription models. German gastroenterology practices maintain standing orders for probiotic protocols. Inventory management systems here require just-in-time replenishment to preserve culture viability.
- Hospitals:Inpatient units and day-surgery centers administering perioperative immunostimulant regimens. Dutch hospital pharmacists are unbundling these from antibiotic stewardship programs. Formulary inclusion demands health technology assessment submissions.
- Pharmacies:Community and hospital outpatient dispensaries serving reimbursed prescription volumes. Structural alignment between German statutory insurers and pharmacy networks creates defensible distribution economics.
- Homecare:Direct-to-patient delivery platforms capturing post-discharge adherence monitoring. Post-acute protocol decentralization is routing stable patients away from infusion centers toward self-administered regimens.
Pharmacies handle the highest prescription volumes. Homecare is gaining share fastest as patient-controlled administration expands.
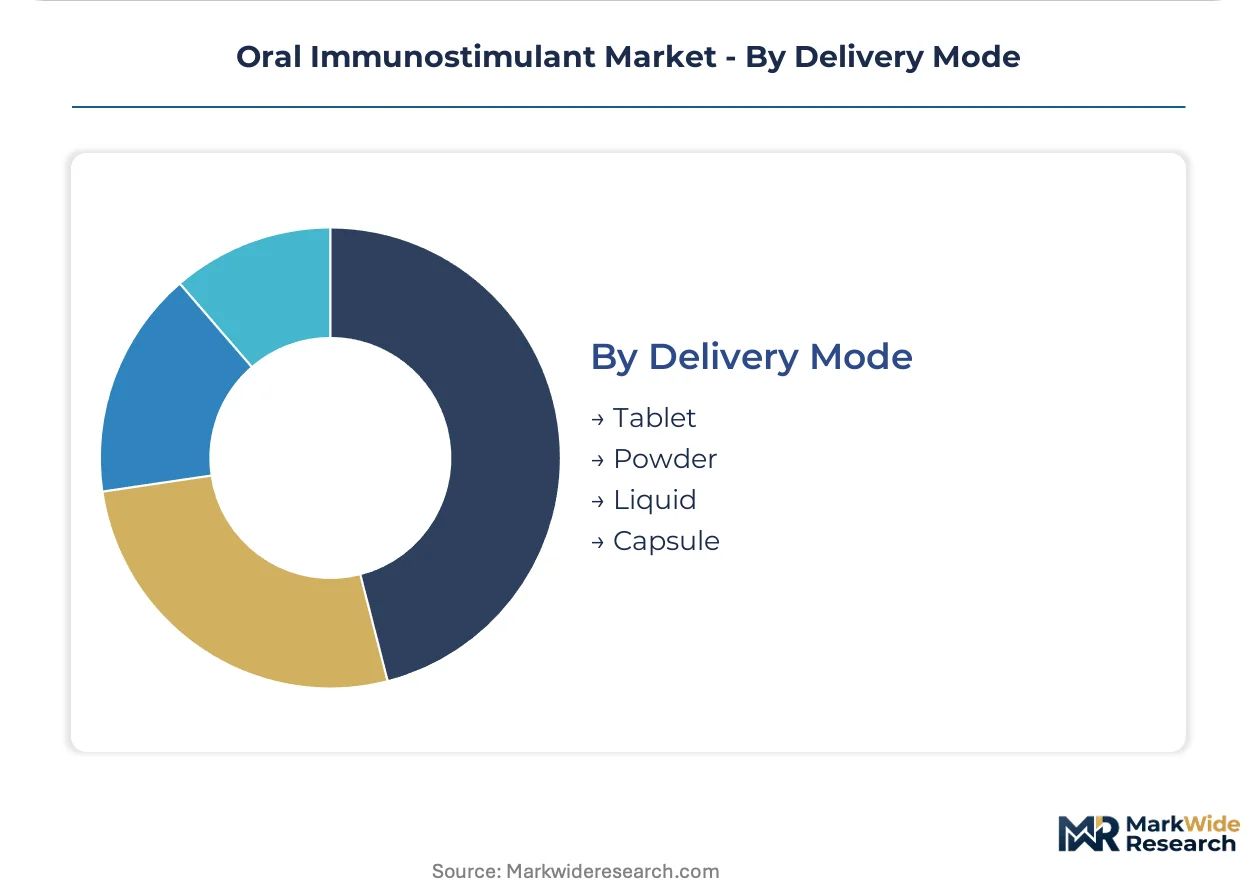
Delivery Mode:
Format engineering balances stability requirements against patient compliance, with moisture-sensitive live cultures demanding more sophisticated barrier packaging than enzymatic preparations.
- Tablet:Compressed formulations with enteric coatings protecting acid-labile ingredients through gastric transit. Pediatric and geriatric compliance favors this format in French and Italian markets. Tooling investments for bilayer or multilayer tablets raise capital thresholds.
- Powder:Sachet-dosed formulations enabling flexible titration and combination with food vehicles. Homecare channels prefer powders for patients with swallowing difficulties. Moisture barrier specifications are less stringent than for tablets.
- Liquid:Suspensions and emulsions offering rapid dissolution and dose precision. Short shelf lives constrain distribution radius to regional manufacturing.
- Capsule:Hard gelatin or HPMC shells containing powders, granules, or microencapsulated beads. Two-piece capsule filling lines offer faster changeover between SKUs than tablet presses.
Tablets absorb the largest share of manufacturing investment. Powders are expanding most quickly in direct-to-patient channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clinical immunology talent pools in Basel, Boston, and Bangalore anchor the geography of oral immunostimulant innovation. Manufacturing capacity clusters with European contract fermentation specialists. Regulatory divergence between pharmaceutical-grade and food-supplement pathways shapes investment location decisions.
Germany
Pharmacy-led distribution of probiotic immunostimulants achieves structural depth through statutory health insurer reimbursement alignment. The EU MDR framework tightens clinical evidence requirements for CE-marked immune-modulating products. Academic medical centers in Heidelberg and Munich adopt multi-strain consortia for irritable bowel syndrome with immune comorbidity.
United States
FDA post-market adverse event monitoring and GMP inspections govern dietary supplement pathway products while clinicians expand respiratory indication prescribing. Hospital procurement committees unbundle oral immunostimulant selection from antibiotic formulary decisions. Integrated delivery networks in Minnesota and California establish distinct reimbursement tiers for evidence-grade probiotics.
India
CDSCO clinical trial requirements for high-CFU probiotic formulations constrain import pathways and attract domestic fermentation investment under PLI scheme incentives. Post-acute protocol decentralization routes stable patients toward homecare self-administration. Manufacturing clusters in Hyderabad and Ahmedabad expand capacity to serve Asian market demand.
Netherlands
Hospital pharmacists standardize nutraceutical immunostimulants into post-surgical protocols with health technology assessment backing. EMA evolving stance on immune health claims under the Nutrition and Health Claims Regulation reduces regulatory ambiguity. Academic medical centers in Rotterdam and Utrecht pioneer microbiome characterization tools for trial design.
Switzerland
Swissmedic oversight of pharmaceutical-grade immunostimulants supports premium positioning for prescription formulations. Clinicians in Swiss primary care networks prescribe oral immunostimulants as adjuncts to standard vaccination for respiratory prophylaxis. Basel-based clinical immunology talent concentrates formulation science expertise with GMP manufacturing competency.
Oral Immunostimulant Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base separates into pharmaceutical majors with distribution infrastructure, consumer health divisions of food conglomerates, and mid-tier nutraceutical specialists. Three archetypes dominate: fermentation-capable probiotic manufacturers, herbal extraction specialists with HPLC-MS infrastructure, and enzymatic preparation formulators. Capacity expansion and portfolio diversification toward respiratory indications constitute the dominant competitive moves.
Within the pharmaceutical-major tier, Bayer AG and Pfizer Inc. occupy positions anchored by established distribution networks and R&D intensity. Nestlé Health Science exemplifies the consumer-health-division archetype, sitting within a broader nutrition conglomerate structure. These three entities represent divergent strategic postures: pharmaceutical-grade prescription development, consumer-facing functional food positioning, and hybrid clinic-to-pharmacy channel coverage.
| Leading Market Players |
|---|
| Bayer AG |
| Pfizer Inc. |
| Nestlé Health Science |
| GlaxoSmithKline plc |
| Novartis AG |
| Amgen Inc. |
| Johnson & Johnson |
| Merck & Co. |
| Abbott Laboratories |
| Others |
Value Network & Pricing Analysis
Live culture fermentation costs cascade through German pharmacy reimbursement tiers, with cold-chain logistics premiums separating pharmaceutical-grade probiotics from commodity supplements in downstream pricing.
Pricing Analysis
The bundled-vs-unbundled service split separates prescription-grade formulations with clinical support from over-the-counter alternatives. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with CE-marked products commanding reimbursement premiums. Cost compression in the standard tier intensifies because mid-tier formulators lack HPLC-MS infrastructure to amortize marker compound quantification. Hospital procurement committees exhibit lowest price sensitivity due to total cost-of-care contracting, while direct-to-consumer channels face acute sensitivity to per-dose positioning.
Supply Chain Analysis
Direct-to-pharmacy channels handle reimbursed prescription volumes in Germany, while homecare delivery platforms capture post-discharge adherence monitoring. Manufacturing capacity clusters in Germany, the Netherlands, and Denmark, with industrial-scale fermentation drawing from specialized European contract manufacturers. Raw material dependencies center on high-potency bacterial strains, pharmaceutical-grade excipients, and temperature-controlled packaging. Single-source vulnerability concentrates in live culture supply, where limited fermentation capacity creates bottleneck exposure. Distribution runs through pharmacy-led networks with statutory insurer alignment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR Article 10 clinical evidence requirements function as a regulatory compounder, elevating development costs and compressing viable participant pools as notified body backlogs extend launch timelines.
For Market Incumbents: To counter portfolio rationalization pressure from smaller players exiting CE-marked categories, anchor market position through backward integration into fermentation capacity and deepen vertical control over cold-chain logistics. Prioritize certification investment in multi-strain consortia with CRISPR-guided metabolic optimization to widen the evidence gap against commodity competitors. For New Entrants and Emerging Players: Launch via direct-to-patient delivery platforms in homecare channels where pharmacy intermediation remains underdeveloped. White-space targets cluster in respiratory indication expansion beyond gastrointestinal applications and in Indian domestic manufacturing under PLI scheme incentives. The penetrable segment is high-CFU probiotic formulations for post-acute protocol decentralization. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR technical documentation burdens strain mid-cap regulatory affairs functions beyond recovery capacity. Long-term viability favors acquisition targets with dual competency in microbiome characterization and GMP manufacturing, positioned at the live biotherapeutic product classification boundary. The inflection signal to watch is German notified body backlog resolution timing.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR compliance secures pharmacy reimbursement access across German statutory networks. |
| Respiratory Indication Expansion | Swiss primary care networks already prescribe for upper respiratory tract infection prophylaxis. |
| Backward Integration into Fermentation | Captive supply of live cultures mitigates single-source vulnerability in European contract manufacturing. |
| Homecare Channel Infrastructure | Direct-to-patient platforms bypass traditional pharmacy intermediation in post-discharge protocols. |
| PLI Scheme Localization | Indian production incentives attract fermentation capacity to serve Asian market demand under CDSCO pathways. |
Research Methodology
Direct dialogue with regulatory affairs leads, formulary directors at Dutch hospital pharmacists, German pharmacy chain procurement managers, and CDSCO filing specialists grounded qualitative findings in operational reality. Secondary validation drew from EMA submission databases, ClinicalTrials.gov immunomodulation protocols, German statutory insurer reimbursement schedules, and EU MDR notified body guidance documents. Bottom-up and top-down triangulation cross-checked manufacturer capacity disclosures against pharmacy dispensing volume records.
Bottom-up modeling segmented volume and value across product type, therapy area, end user channel, and delivery mode dimensions throughout the forecast period. CAGRs derived from segment-level growth rate synthesis anchored in reimbursement pathway expansion and protocol decentralization trends. Industry-specific inputs incorporated EU MDR implementation timelines, CDSCO potency threshold enforcement patterns, and German pharmacy distribution infrastructure maturity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under notified body backlog extension or CDSCO trial requirement tightening. Projections reflect assumptions regarding regulatory pathway stability and reimbursement alignment continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Activated Charcoal Supplement Market
Nutritional Supplements
Protein Powder Market
Nutritional Supplements
Global Docosahexaenoic Acid (DHA) Market
Nutritional Supplements
Australia Collagen Peptides Market
Nutritional Supplements
Global Reishi Mushroom Extracts Market
Nutritional Supplements
Sleep Gummies Market
Nutritional Supplements
Nutrient Dense Food Products Market
Nutritional Supplements
Lion's Mane Market
Nutritional Supplements
North America Collagen-Based Supplements Market
Nutritional Supplements
Hydrolyzed Whey Protein Market
Nutritional Supplements
Global Oncology Nutrition Market
Nutritional Supplements
South America Whey Protein Market
Nutritional Supplements
Isoleucine Market
Nutritional Supplements
Milk Thistle Market
Nutritional Supplements
North America Insoluble Dietary Fibers Market
Nutritional Supplements
Fatty Acid Supplements Market