
 US Ketones Market | 2026-2036
US Ketones Market Size, Share, and Industry Trends Forecast 2026-2036
US Ketones Market Intelligence
Direct-to-consumer exogenous ketone formulation is fragmenting across delivery modalities and purity grades. Perfect Keto leverages clean-label positioning and subscription commerce to sustain recurring revenue. H.V.M.N. Inc. anchors clinical credibility through peer-reviewed endurance studies. Ketologic competes on flavor engineering and price accessibility.
Ketones are organic compounds produced during fatty acid beta-oxidation, commercially synthesized as exogenous supplements in ester, salt, powder, and liquid forms with purity grades ranging from racemic mixtures to enantiomer-specific formulations. These compounds serve metabolic substrates for alternative fuel pathways in brain and muscle tissue, primarily targeting ketosis induction without dietary carbohydrate restriction. Ketone salts occupy the volume-leading position due to cost-efficient manufacturing and tolerable taste profiles, while ketone esters command premium positioning in elite athletic and research segments despite higher price points and gastrointestinal side effects. Online retail channels capture the fastest growth trajectory, driven by influencer marketing and personalized subscription models that bypass traditional brick-and-margin constraints.
FDA dietary supplement regulations under DSHEA, GRAS self-affirmation requirements, and FTC advertising substantiation standards collectively govern product claims, ingredient safety documentation, and marketing compliance. State-level health department oversight in California and Texas adds layer-specific labeling and manufacturing inspection protocols. Stakeholders must monitor evolving FDA enforcement priorities around structure-function claims and emerging NDI notification requirements for novel ketone analogs.
Market Dynamics
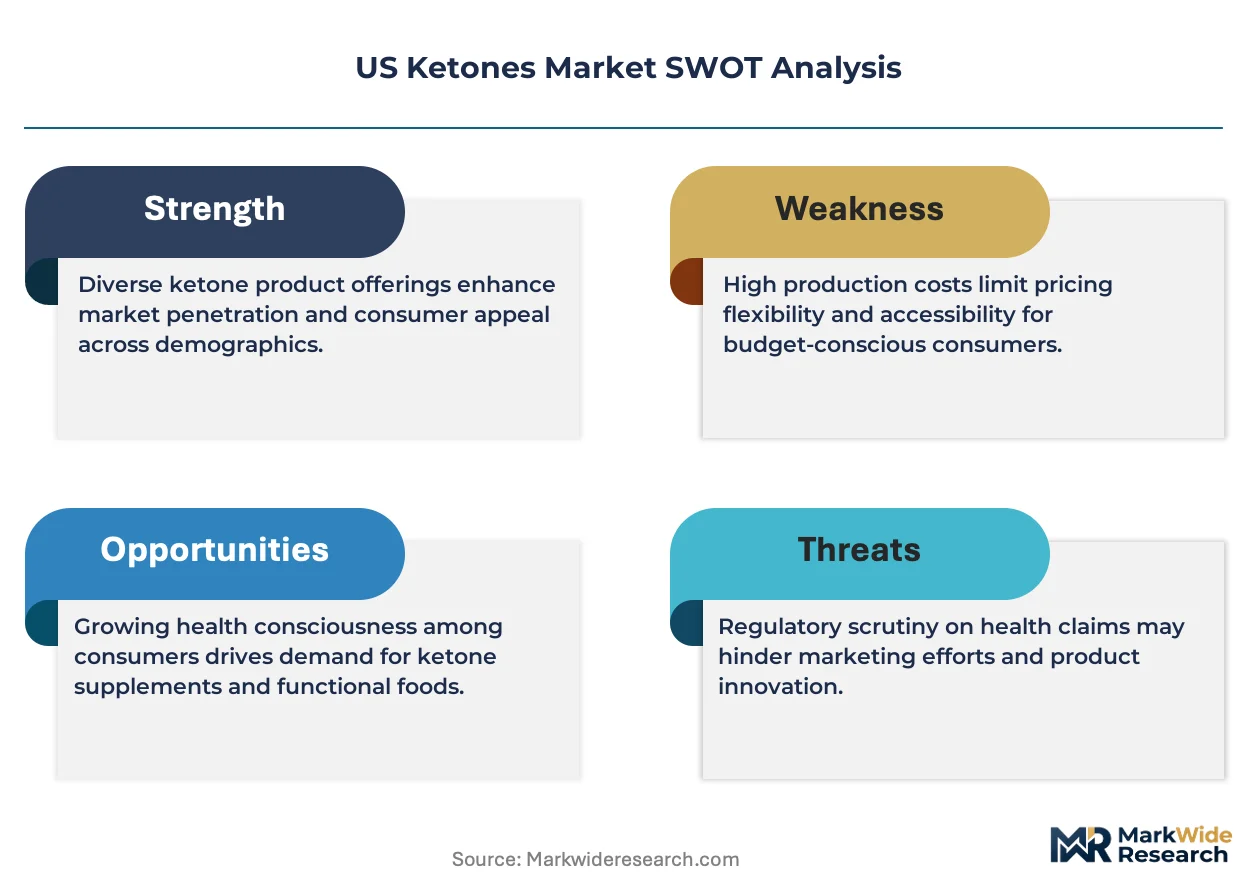
DSHEA dietary supplement enforcement is tightening around structure-function claims, forcing ketone brands to revalidate clinical substantiation or face FTC action. This regulatory pressure is compressing marketing margins while elevating formulation science as the primary competitive moat.
Growth Catalysts
- Metabolic health clinic expansion:Functional medicine practices in Texas and California are prescribing exogenous ketones for insulin sensitivity protocols, creating institutional demand pull.
- FDA GRAS self-affirmation pathway:Streamlined safety documentation allows novel ketone ester formulations to reach shelves faster than NDI notification routes.
- Endurance sports biochemistry:Marathon and ultra-running communities are adopting ketone esters for glycogen-sparing race strategies, validated through peer-reviewed exercise physiology studies.
Market Restraints
- Input cost volatility:Racemic D-BHB precursor chemicals face supply concentration from Chinese specialty chemical manufacturers, creating margin squeeze during trade friction periods.
- Gastrointestinal tolerability ceiling:Ketone esters at effective doses trigger nausea in 30-40% of naive users, limiting repeat purchase rates and word-of-mouth amplification.
- FTC advertising substantiation standards:Aggressive enforcement against cognitive enhancement claims forces brands to retreat from high-conversion messaging, reducing customer acquisition efficiency.
Strategic Opportunities
- Neurodegenerative adjunct therapy:Ketone salts as glucose-alternative brain fuel for early-stage Alzheimer's protocols represent an underpenetrated clinical channel requiring physician education investment.
- Subscription commerce infrastructure:Direct-to-consumer platforms with personalized dosing algorithms can capture recurring revenue streams currently dominated by Amazon third-party sellers.
- IRA metabolic health incentives:Preventive care tax credits for obesity-related interventions could expand HSA/FSA eligibility for prescription-grade ketone formulations.
Industry Challenges
- Enantiomeric purity verification:Laboratory capacity for distinguishing D-BHB from L-BHB is concentrated in academic centers, creating quality control bottlenecks for mid-tier manufacturers.
- Flavor masking R&D timelines:Bitter aftertaste engineering requires 18-24 month development cycles, delaying product refresh rates against faster-moving competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Ketones Market |
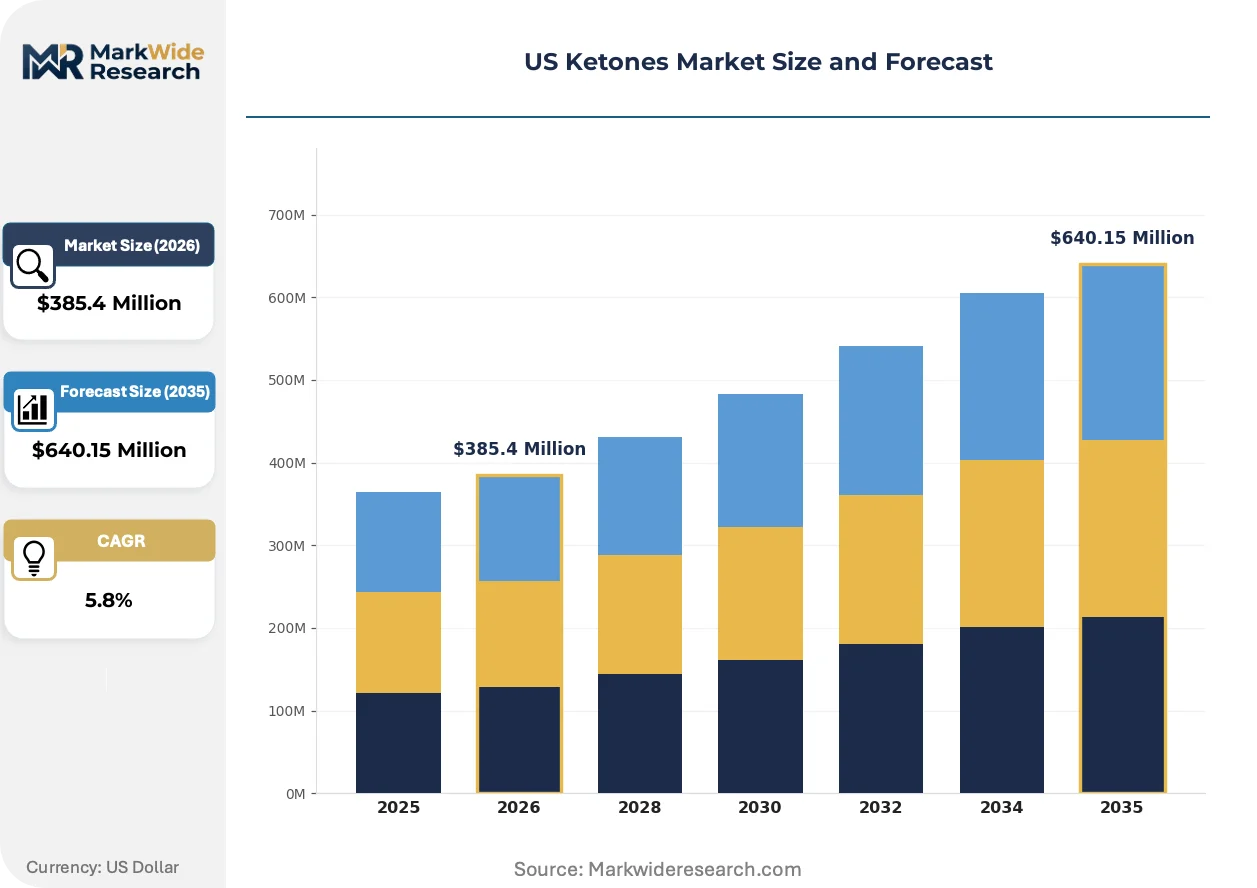
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ketone Esters, Ketone Salts, Ketone Powders, Liquid Ketones Delivery Mode: Pills, Powders, Beverages, Snacks End User: Health Enthusiasts, Athletes, Weight Loss Customers, Medical Patients Distribution Channel: Online Retail, Health Stores, Supermarkets, Pharmacies |
| Companies Covered | Perfect Keto, H.V.M.N. Inc., Ketologic, Pruvit Ventures, Inc., Ketoneaid Inc., Kegenix, BPI Sports, Zenwise Health, Compound Solution Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Ketones Market Strategic Shifts & Innovations
Clean-label positioning is displacing performance-only marketing as the primary purchase trigger. Formulators are racing to eliminate artificial sweeteners and synthetic colorants while maintaining palatability thresholds that prevent consumer abandonment.
Enantiomer-specific BHB synthesis is collapsing cost differentials between racemic mixtures and pure D-BHB isolates. Biocatalytic manufacturing platforms licensed from industrial enzyme suppliers are enabling mid-scale producers to achieve pharmaceutical-grade purity without multi-million-dollar chromatography infrastructure. Sports nutrition brands in California are adopting this technology fastest, compressing the premium positioning window for early ester specialists.
FTC guidance on cognitive health claims is tightening substantiation requirements for structure-function statements. Marketing teams must now secure randomized controlled trial data before deploying memory or focus benefit language, elevating clinical research budgets as a fixed cost of market participation. Ketone salt manufacturers targeting Texas functional medicine clinics are responding with physician-only distribution models that bypass direct-to-consumer claim restrictions.
Athlete procurement patterns are fragmenting across micro-influencer recommendation channels. TikTok and Instagram fitness creators with sub-100,000 followings are driving trial conversion more efficiently than legacy sponsorship deals with elite performers. This shift is most visible in Southern California, where CrossFit affiliate owners and obstacle course racing coaches function as de facto product gatekeepers for recreational endurance athletes.
US Ketones Market Segmentation
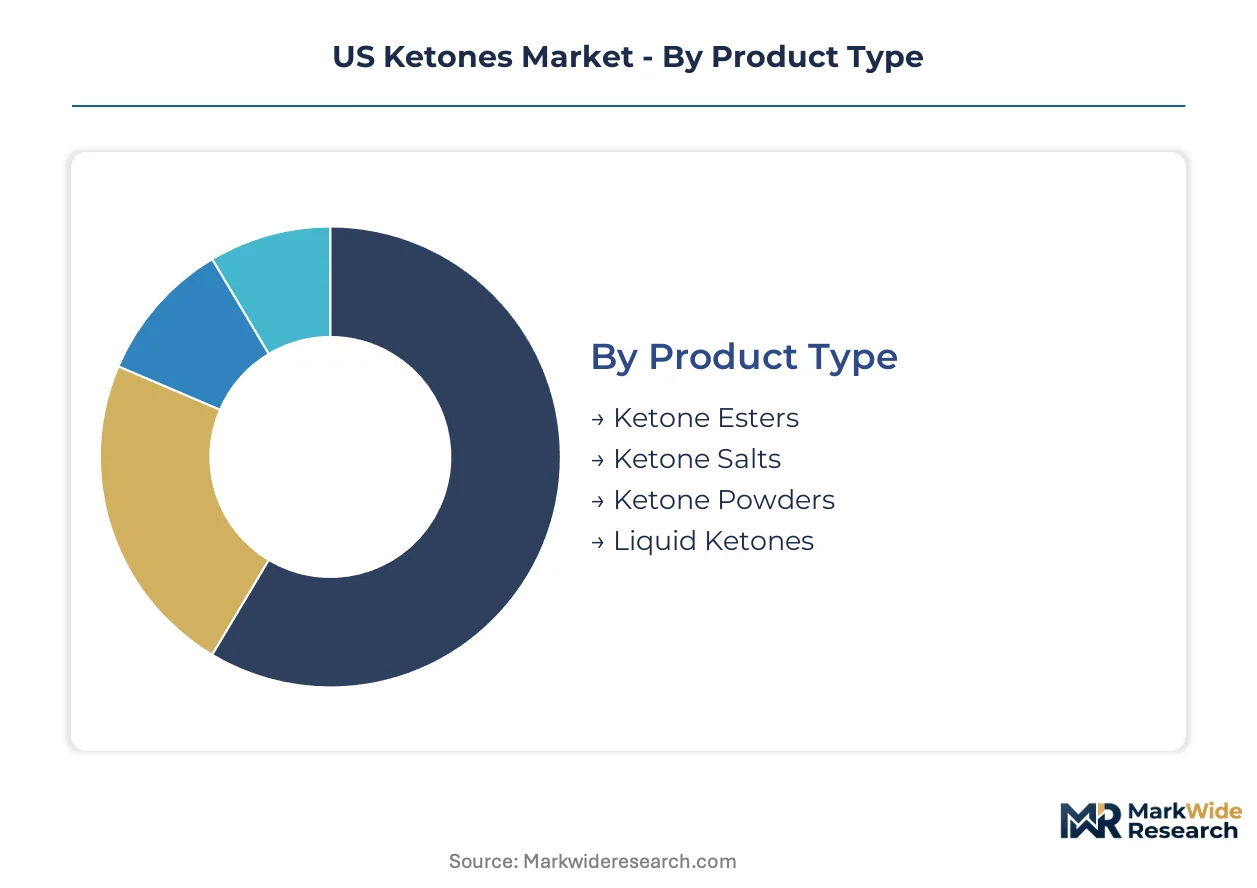
Segmentation in the US ketones market reveals divergent margin structures and purchase frequencies across product formats and buyer profiles. Manufacturers optimize inventory turns by matching formulation complexity to channel economics and end-use durability.
Product Type:
Ketone esters rotate through inventory fastest due to limited shelf stability, while ketone salts maintain the longest production-to-purchase cycles.
- Ketone Esters:Highly concentrated beta-hydroxybutyrate monoesters synthesized through chemical esterification deliver the highest ketone elevation per gram. Texas functional medicine clinics prescribe these for acute metabolic interventions, though gastrointestinal intolerance limits repeat purchase rates among naive users.
- Ketone Salts:BHB bound to mineral cations (sodium, calcium, magnesium, potassium) form the cost-efficient backbone of commercial availability. California sports nutrition brands dominate formulation innovation here, driven by endurance athlete demand for glycogen-sparing protocols.
- Ketone Powders:Spray-dried formulations enable flexible dosing and stackability with other supplements.
- Liquid Ketones:Ready-to-drink formats target convenience-seeking health enthusiasts in urban Texas markets.
Ketone salts anchor the volume base while ketone esters gain share at the steepest rate.
Delivery Mode:
Powder formats command the widest margin spreads across purity grades, while beverages compress margins through flavor R&D amortization.
- Pills:Encapsulated BHB salts and esters provide precise dosing for clinical protocols. Texas metabolic health clinics favor these for patient compliance tracking.
- Powders:Bulk BHB with flavor masking dominates direct-to-consumer subscription models. California-based brands engineer proprietary taste profiles to reduce churn.
- Beverages:Ready-to-drink ketone waters and performance shots target gym-adjacent impulse purchase. FDA GRAS self-affirmation requirements add regulatory lead time.
- Snacks:Ketone-infused bars and gummies represent the newest format entry with unproven repeat purchase patterns.
Powders generate the highest absolute contribution margin while beverages expand most quickly through convenience retail penetration.
End User:
Athlete segments refresh product trials seasonally, whereas medical patient adoption follows prescription renewal cycles.
- Athletes:Marathoners, triathletes, and CrossFit competitors in California drive premium ester adoption. Peer-reviewed exercise physiology studies from Stanford and UC Davis validate glycogen-sparing claims.
- Medical Patients:Early-stage Alzheimer's and epilepsy protocols under physician supervision create institutional demand pull. Texas functional medicine clinics lead prescriptive adoption.
- Health Enthusiasts:Biohacking consumers seeking cognitive enhancement populate online subscription cohorts.
- Weight Loss Customers:Keto diet adherents use exogenous ketones to accelerate ketosis induction without strict carbohydrate restriction.
Athletes sustain the largest absolute spend per capita while medical patients represent the stickiest retention cohort.
Distribution Channel:
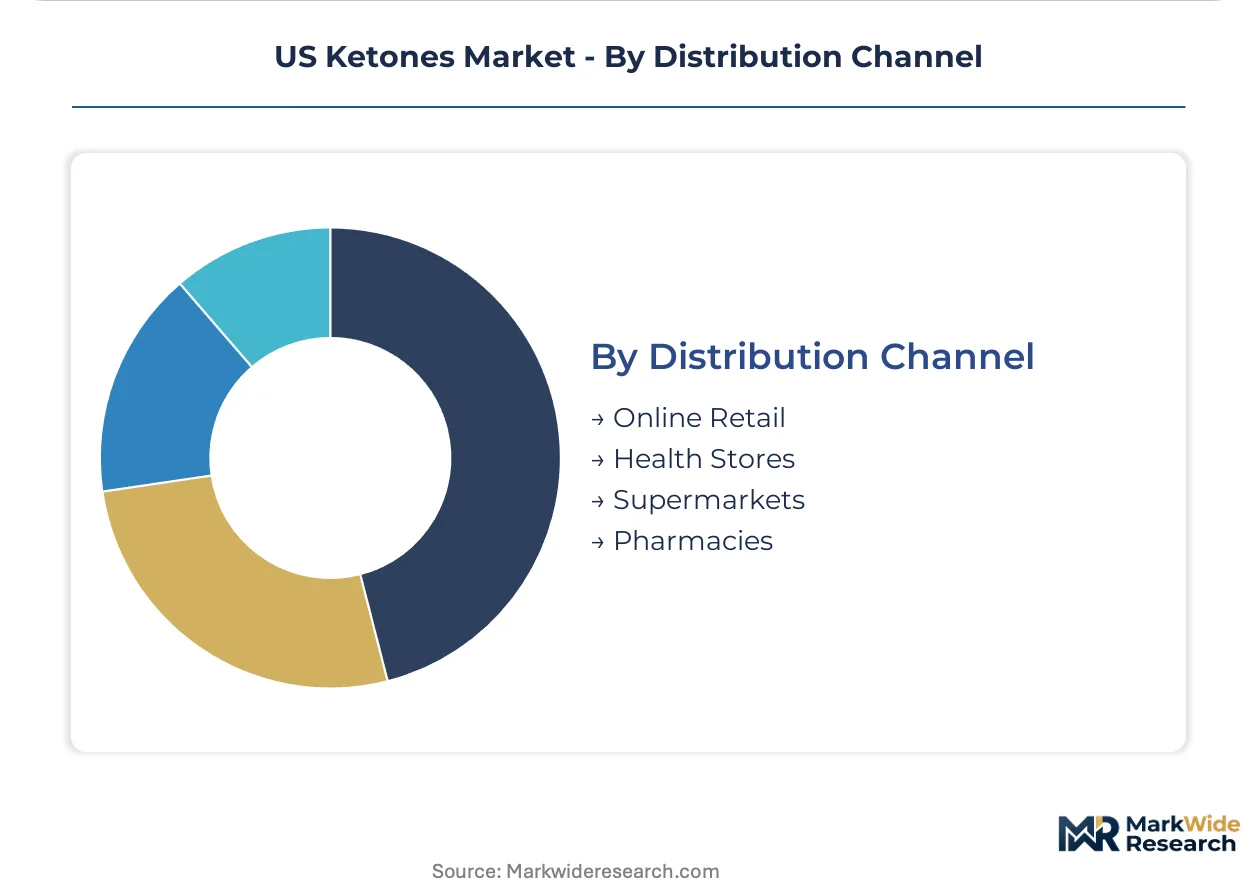
Online retail turns inventory fastest through algorithmic replenishment, while pharmacy channels impose the longest certification delays.
- Online Retail:Direct-to-consumer platforms and Amazon third-party sellers capture the majority of volume. Influencer marketing through TikTok and Instagram fitness creators drives trial conversion in Southern California.
- Health Stores:GNC, Vitamin Shoppe, and independent supplement retailers provide tactile evaluation for first-time buyers.
- Supermarkets:Mainstream grocery placement remains limited to powder formats in California and Texas metro areas.
- Pharmacies:CVS and Walgreens shelf access requires additional insurance reimbursement navigation for prescription-grade formulations.
Online retail commands the dominant volume position while health stores deliver the highest customer lifetime value through staff-assisted upselling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Elite endurance athletes and functional medicine practitioners concentrate in coastal and Sun Belt states, driving prescription-grade and sports-grade formulation demand. Texas metabolic health clinics and California sports nutrition brands anchor institutional procurement. FDA state-level enforcement variance creates compliance complexity across jurisdictions.
California
CrossFit affiliate networks and obstacle course racing communities in Southern California drive ketone ester trial through micro-influencer channels. State health department labeling inspections exceed federal minimums, adding compliance lead time for new market entrants. San Francisco Bay Area biocatalytic enzyme suppliers license pharmaceutical-grade BHB synthesis technology to mid-scale sports nutrition manufacturers.
Texas
Functional medicine practices in Austin and Dallas prescribe exogenous ketones for insulin sensitivity protocols, creating physician-directed demand pull. State medical board oversight of compounding pharmacy integration affects prescription-grade distribution pathways. Houston-area specialty chemical distributors warehouse racemic D-BHB precursors for regional formulation facilities.
Florida
Retiree populations seeking cognitive enhancement supplements populate direct-to-consumer subscription cohorts in Miami and Tampa metro areas. FTC advertising substantiation enforcement targets memory and focus claims in this jurisdiction with particular intensity. Orlando-area contract manufacturers blend flavor-masked ketone powders for private-label sports nutrition brands.
New York
Biohacking consumers in Manhattan and Brooklyn experiment with ketone esters for productivity optimization, sustaining premium pricing tolerance. State attorney general supplement testing programs impose additional quality verification burdens beyond FDA requirements. Long Island distribution centers serve Northeast corridor health store replenishment.
Colorado
Ultra-running communities in Boulder and Denver adopt ketone esters for high-altitude glycogen-sparing strategies. State public health department dietary supplement manufacturing inspections align with FDA Good Manufacturing Practice standards. Front Range ingredient suppliers specialize in mineral-cation BHB salt formulations for endurance athlete formulations.
US Ketones Market Key Industry Players
Channel-controlling players compete with product-specialist players across divergent margin structures. Direct-to-consumer subscription platforms and Amazon third-party sellers capture volume leadership, while clinical-credibility specialists defend premium positioning through peer-reviewed study investment. Three archetypes dominate: clean-label lifestyle brands, clinical-research anchors, and flavor-engineering value players. Competitive moves concentrate on biocatalytic manufacturing licensing and influencer marketing infrastructure acquisition.
Among clinical-credibility specialists, H.V.M.N. Inc. exemplifies the peer-reviewed study investment archetype. Perfect Keto and Ketologic occupy differentiated positions within the direct-to-consumer tier, with the former representing clean-label subscription commerce and the latter anchoring flavor-accessibility value positioning. These three companies illustrate how formulation science, marketing compliance, and channel control separate sustainable competitors from commodity suppliers.
| Leading Market Players |
|---|
| Perfect Keto |
| H.V.M.N. Inc. |
| Ketologic |
| Pruvit Ventures, Inc. |
| Ketoneaid Inc. |
| Kegenix |
| BPI Sports |
| Zenwise Health |
| Compound Solution Inc. |
| Others |
Cost & Logistics Intelligence
Port of Long Beach container freight rates from Chinese specialty chemical exporters transmit cost volatility directly into racemic D-BHB landed costs, compressing margin buffers for mid-tier manufacturers while amplifying price spreads between pharmaceutical-grade enantiomers and commodity salt formulations.
Pricing Analysis
Cost-plus contracts with Chinese precursor suppliers index to ethylene glycol spot markets, creating margin squeeze during petrochemical price spikes. Three-tier pricing structure across pharmaceutical-grade esters, sports-grade salts, and private-label powders separates certification-burdened clinical formulations from commodity fitness products. Pricing pressure stems from biocatalytic manufacturing licensing collapsing purity premiums faster than flavor R&D amortization. Weight loss customers exhibit highest price elasticity, while Texas functional medicine clinics absorb premium markups for prescription-grade encapsulation.
Supply Chain Analysis
Export control restrictions on dual-use biocatalytic enzyme technology limit US access to pharmaceutical-grade BHB synthesis platforms developed in German and Swiss industrial biotechnology clusters. Racemic precursor production concentrates in Chinese specialty chemical hubs, with mineral cation suppliers anchored in Utah and Michigan. Single-source vulnerability runs through Qingdao-area D-BHB manufacturers subject to tariff exposure. Distribution runs through Houston chemical distributors for regional formulation facilities, with direct-to-consumer platforms bypassing traditional wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US ketones market is exiting a regulatory enforcement trough as FDA structure-function claim clarity and FTC advertising substantiation standards stabilize, positioning compliant formulators for cyclical margin recovery.
For Market Incumbents: Harden clinical substantiation archives against FTC cognitive enhancement enforcement actions by commissioning randomized controlled trials for memory and focus claims. Secure backward integration into mineral-cation supply through captive agreements with Utah-based magnesium and potassium suppliers, insulating against input cost volatility from Chinese precursor concentration. For New Entrants and Emerging Players: Florida retiree populations seeking cognitive enhancement supplements represent the most penetrable geography, with Miami and Tampa metro areas showing subscription commerce infrastructure gaps relative to California and Texas saturation. Physician-only distribution models for Texas functional medicine clinics bypass direct-to-consumer claim restrictions while building prescriptive habit formation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biocatalytic manufacturing platforms with pharmaceutical-grade purity capabilities, as enzymatic synthesis collapses cost differentials between racemic and enantiomer-specific formulations. Acquisition targets should demonstrate FDA GRAS self-affirmation documentation and established subscription commerce cohorts with sub-15% monthly churn. Watch for IRA metabolic health incentive rulemaking expanding HSA/FSA eligibility as the signal for prescription-grade market inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Biocatalytic Manufacturing Licensing | Enzyme platform agreements from Bay Area suppliers enable pharmaceutical-grade purity without chromatography infrastructure. |
| Physician-Only Distribution Model | Texas functional medicine clinic networks bypass FTC direct-to-consumer claim restrictions for cognitive enhancement positioning. |
| Subscription Commerce Infrastructure | Algorithmic replenishment platforms capture recurring revenue currently dominated by Amazon third-party sellers. |
| GRAS Self-Affirmation Documentation | Streamlined FDA safety pathways accelerate novel ketone ester formulations to shelves faster than NDI routes. |
| Flavor Masking R&D Investment | Proprietary taste engineering reduces 18-24 month development cycles and prevents consumer abandonment from bitter aftertaste. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA GRAS notification databases, FTC advertising substantiation enforcement records, and customs import manifests for racemic D-BHB precursors. Primary interviews engaged formulation scientists at California sports nutrition brands, procurement directors at Texas metabolic health clinic networks, and regulatory affairs leads navigating structure-function claim compliance. Bottom-up demand modeling from subscription commerce platform data triangulates against top-down market sizing from import volume analysis.
Forecast inputs incorporate product type segmentation across esters, salts, powders, and liquids; delivery mode differentiation between pills, powders, beverages, and snacks; end-user stratification across athletes, medical patients, health enthusiasts, and weight loss customers; and distribution channel dynamics spanning online retail, health stores, supermarkets, and pharmacies. CAGRs derive from regression analysis of historical subscription cohort retention rates and prescription-grade formulation adoption curves across the projection horizon. Industry-specific inputs include biocatalytic manufacturing licensing velocity and IRA metabolic health incentive policy development.
The forecast holds incumbent behavior within observed patterns; aggressive moves by direct-to-consumer platforms with vertical integration into formulation manufacturing would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Algae Omega Market
Nutritional Supplements
Asia-Pacific Beta-Glucan Market
Nutritional Supplements
Marine Collagen Powder Market
Nutritional Supplements
Krill Oil Phospholipid Market
Nutritional Supplements
US Protein Supplements Market
Nutritional Supplements
Isoleucine Market
Nutritional Supplements
Pulse Products Market
Nutritional Supplements
China Collagen Peptides Market
Nutritional Supplements
Global Nutraceutical Market
Nutritional Supplements
Bypass Fat Supplement Market
Nutritional Supplements
Ketogenic Diet Food Market
Nutritional Supplements
South America Omega-3 Products Market
Nutritional Supplements
Global Vitamin Supplements Market
Nutritional Supplements
Fish Collagen Peptides Market
Nutritional Supplements
Tryptophan Market
Nutritional Supplements
Grass Fed Protein Market