
 Feed Prebiotics Market | 2026-2036
Feed Prebiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Feed Prebiotics Market Foresight
Market Context
Modular premix bundling is expanding as the dominant configuration pattern, allowing feed manufacturers to combine prebiotics with enzymes and organic acids in customizable ratios rather than purchasing standalone ingredients. Cargill Incorporated leverages its integrated supply chain from raw material sourcing to finished feed formulation, sustaining cost advantages across multiple geographies. DSM-Firmenich AG anchors its position through biotechnology leadership in fermentation-derived oligosaccharides, while Alltech Inc. differentiates via yeast-based prebiotic platforms and direct technical service to livestock operations.
Technical and Structural Dimensions
Feed prebiotics are non-digestible carbohydrate compounds, typically oligosaccharides with chain lengths of 2-20 monomer units, that selectively stimulate growth of beneficial gastrointestinal microbiota in monogastric and ruminant animals. Manufacturers produce these compounds through enzymatic hydrolysis of plant-derived substrates such as chicory root for inulin or microbial fermentation for galacto-oligosaccharides, with specifications targeting minimum 90% purity for commercial feed-grade applications. Fructo-oligosaccharides occupy the largest revenue pool due to established supply chains and broad species applicability, while mannan-oligosaccharides represent the fastest-growing product category driven by aquaculture expansion and ruminant gut health protocols. Poultry nutrition applications command premium positioning because integrators demand documented performance metrics for flock uniformity and feed conversion efficiency.
Regulatory Environment
The European Food Safety Authority evaluates novel prebiotic submissions under feed additive authorization procedures, while the FDA Center for Veterinary Medicine exercises oversight of direct-fed microbial and prebiotic claims in the United States. China's Ministry of Agriculture and Rural Affairs maintains a positive list approach for feed additive approval, creating divergent market access requirements that shape regional product portfolios. Brazil's MAPA and India's FSSAI have each tightened residue monitoring protocols, indirectly elevating prebiotic demand as producers seek performance alternatives to conventional growth promoters. Stakeholders must monitor evolving regulatory equivalence agreements between major exporting and importing jurisdictions to anticipate reformulation mandates and certification requirements.
Market Dynamics
Modular premix bundling is compressing standalone ingredient margins as feed manufacturers demand customizable enzyme-prebiotic-acid combinations rather than discrete inputs, forcing suppliers to reconfigure production lines for flexible batch sizing.
Growth Catalysts
- EU F-Gas Regulation:The European Union's F-Gas Regulation and Green Deal frameworks are mandating feed additive reformulation, accelerating prebiotic substitution for conventional growth promoters in member state poultry and swine operations.
- Poultry integrator documentation requirements:Integrated poultry producers in Brazil and Thailand now require documented flock uniformity and feed conversion metrics, pulling prebiotic inclusion into standard commercial formulations.
- Fermentation-derived oligosaccharides:Biotechnology advances in microbial fermentation for galacto-oligosaccharide production are lowering unit costs and expanding supply availability for aquaculture gut health protocols.
Market Restraints
- Chicory root supply concentration:Inulin production depends on chicory root sourcing concentrated in Belgium and the Netherlands, creating geographic vulnerability to weather-driven yield volatility.
- China positive list friction:China's Ministry of Agriculture and Rural Affairs maintains restrictive feed additive approval procedures, delaying market access for novel prebiotic submissions and fragmenting regional product portfolios.
- Enzyme-prebiotic substitution:Exogenous enzyme cocktails targeting similar gut health outcomes present direct performance competition, particularly in cost-sensitive swine nutrition segments.
Strategic Opportunities
- India FSSAI residue monitoring:India's Food Safety and Standards Authority has tightened antibiotic residue protocols, creating regulatory pull for prebiotic alternatives in dairy and poultry operations.
- Aquaculture expansion:Mannan-oligosaccharide applications in shrimp and finfish gut health represent underpenetrated species categories with limited established supplier presence.
- Direct technical service channels:Livestock operations in Vietnam and Indonesia lack technical support infrastructure, opening channel innovation for prebiotic suppliers combining product with on-farm microbiome assessment.
Industry Challenges
- Fermentation scale-up talent scarcity:Commercial-scale oligosaccharide production requires specialized biochemical engineering expertise that remains concentrated in European and North American research clusters.
- EFSA authorization timelines:European Food Safety Authority novel feed additive evaluations extend 18-24 months, compressing product development return horizons and requiring sustained regulatory affairs investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feed Prebiotics Market |
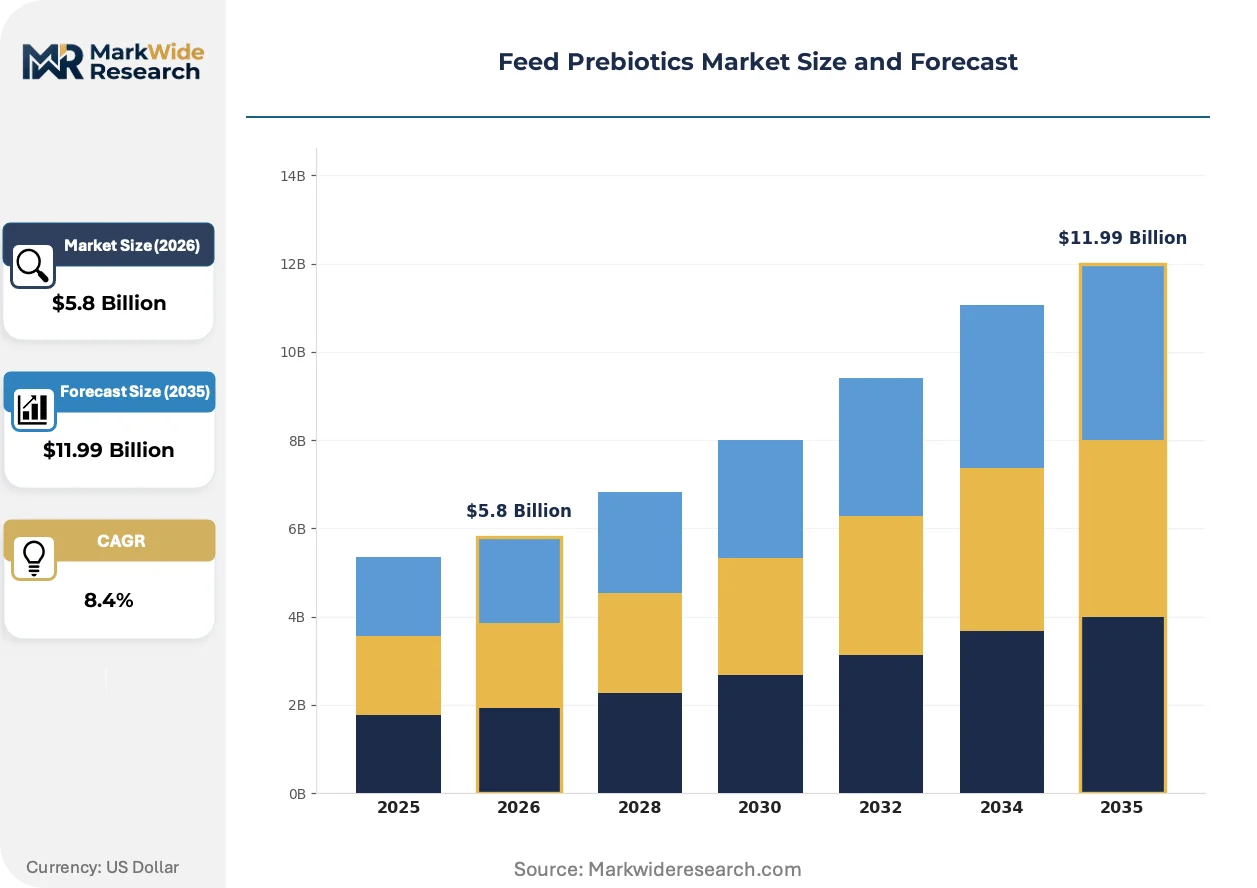
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.99 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inulin, Fructo-Oligosaccharides, Mannan-Oligosaccharides, Galacto-Oligosaccharides Application: Ruminant Nutrition, Swine Nutrition, Poultry Nutrition, Aquaculture Form: Powder, Granule, Liquid, Tablet End User: Feed Manufacturers, Livestock Farms, Aquaculture Facilities, Pet Food Producers |
| Companies Covered | ADM, Cargill Incorporated, DSM-Firmenich AG, Alltech Inc., Kemin Industries Inc., Ingredion Incorporated, Kerry Group, Land O'Lakes Inc., Novus International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feed Prebiotics Market Shifts & Advancements
Fermentation biotechnology and regulatory chemistry are converging to reshape how prebiotic compounds reach livestock operations, with production methods and approval pathways both undergoing structural revision.
Precision fermentation for galacto-oligosaccharide synthesis is overtaking traditional enzymatic hydrolysis as the dominant production architecture. Aquaculture nutrition specialists in Norway and Chile are adopting fermentation-derived mannan-oligosaccharides at accelerating rates. This technology is overtaking plant-extraction methods in premium feed-grade applications by enabling chain-length specificity and batch consistency that chicory-root processing cannot match.
The European Union's F-Gas Regulation is forcing refrigerant-dependent extraction facilities to retool thermal processes or relocate production. Feed additive manufacturers with captive fermentation capacity are absorbing volume from solvent-extraction dependent competitors. Poultry premix formulators in Germany, France, and Poland are most affected, accelerating qualification of fermentation-derived alternatives to maintain supply continuity.
Integrated poultry and swine operations are consolidating procurement authority at the headquarters level, displacing decentralized mill-level purchasing. Large Brazilian and Thai integrators now specify prebiotic inclusion rates and supplier qualifications centrally, compressing regional distributor roles. This concentration is most visible in Brazil's Mato Grosso and Paraná states, where three integrators control over sixty percent of commercial feed volume.
Feed Prebiotics Market Segmentation
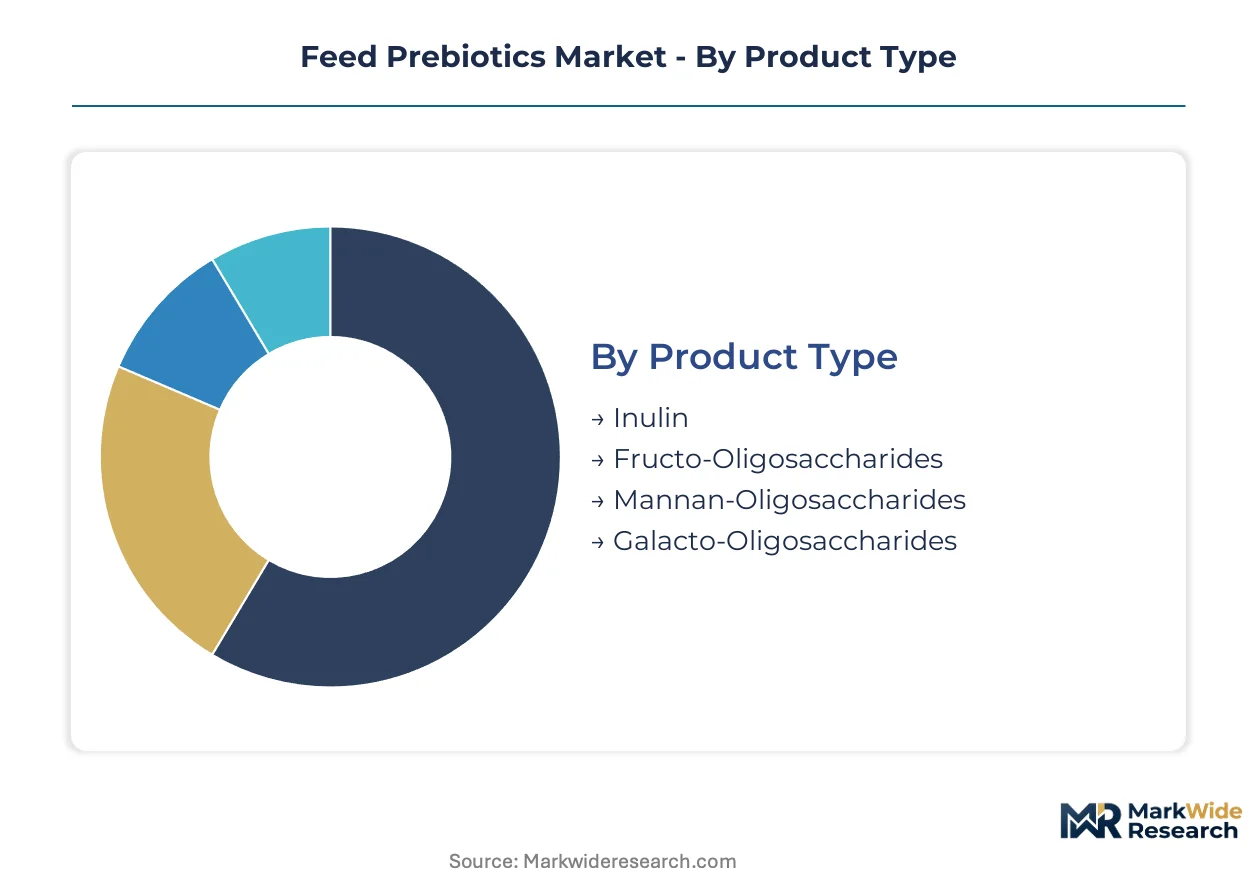
Prebiotic segmentation reveals how formulation choices cascade through supply chains. Product chemistry determines production economics, while application species dictate performance documentation requirements and regulatory exposure.
Product Type:
Integration depth varies sharply: fructo-oligosaccharides dominate standalone ingredient sales, while mannan-oligosaccharides embed increasingly in bundled aquaculture premixes.
- Fructo-Oligosaccharides:These 2-9 unit fructose chains derive primarily from chicory root enzymatic hydrolysis, commanding the largest revenue pool due to established supply chains and broad species applicability. Demand concentrates in German and Polish poultry premix formulations where integrators require documented flock uniformity metrics.
- Mannan-Oligosaccharides:Yeast cell wall extracts rich in mannan polymers stimulate beneficial gut microbiota in monogastric species. Norwegian and Chilean aquaculture operations are scaling inclusion rates fastest, driven by shrimp gut health protocols and finfish disease pressure.
- Inulin:Longer-chain fructan polysaccharides from chicory root support ruminant fiber fermentation and cecal health in horses.
- Galacto-Oligosaccharides:Fermentation-derived lactose oligomers target neonatal nutrition and precision gut modulation in premium swine operations.
Fructo-oligosaccharides lead volumes today; mannan-oligosaccharides is gaining share fastest.
Application:
Cost tier differentiation separates species categories: poultry commands premium positioning with mandatory performance documentation, while aquaculture operates at emerging-economy cost structures with faster adoption curves.
- Poultry Nutrition:Broiler and layer operations require prebiotics demonstrating measurable feed conversion ratio improvements and reduced pathogen shedding. Brazilian integrators in Mato Grosso and Paraná states now specify inclusion rates centrally, displacing mill-level procurement discretion.
- Aquaculture:Shrimp and finfish gut health protocols are expanding mannan-oligosaccharide demand fastest among all species categories. Chilean salmon producers and Vietnamese pangasius operations lack established supplier infrastructure, opening channel innovation opportunities.
- Swine Nutrition:Post-weaning diarrhea prevention drives galacto-oligosaccharide inclusion in nursery diets, though enzyme cocktails present direct performance competition in cost-sensitive segments.
- Ruminant Nutrition:Dairy and beef applications target rumen microbial efficiency and methane mitigation, with inulin and fructo-oligosaccharides supporting fiber digestibility.
Poultry nutrition captures premium margins; aquaculture climbs the fastest.
Form:
Volume concentration favors powder formats for feed mill integration, while liquid forms serve specialized aquaculture and pet food applications requiring precise dosing.
- Powder:Standard feed mill integration format enabling uniform distribution in mash and pelleted feeds. Powder dominates Brazilian and Thai commercial feed volumes.
- Liquid:Post-pelleting application and aquaculture feed coating require aqueous suspensions with stabilized oligosaccharide concentrations.
- Granule:Flowable formats reduce dust exposure and improve handling characteristics in automated dosing systems.
- Tablet:Compressed forms target pet food toppers and specialty livestock supplement segments with precise unit dosing.
Powder leads volumes today; liquid is gaining share fastest.
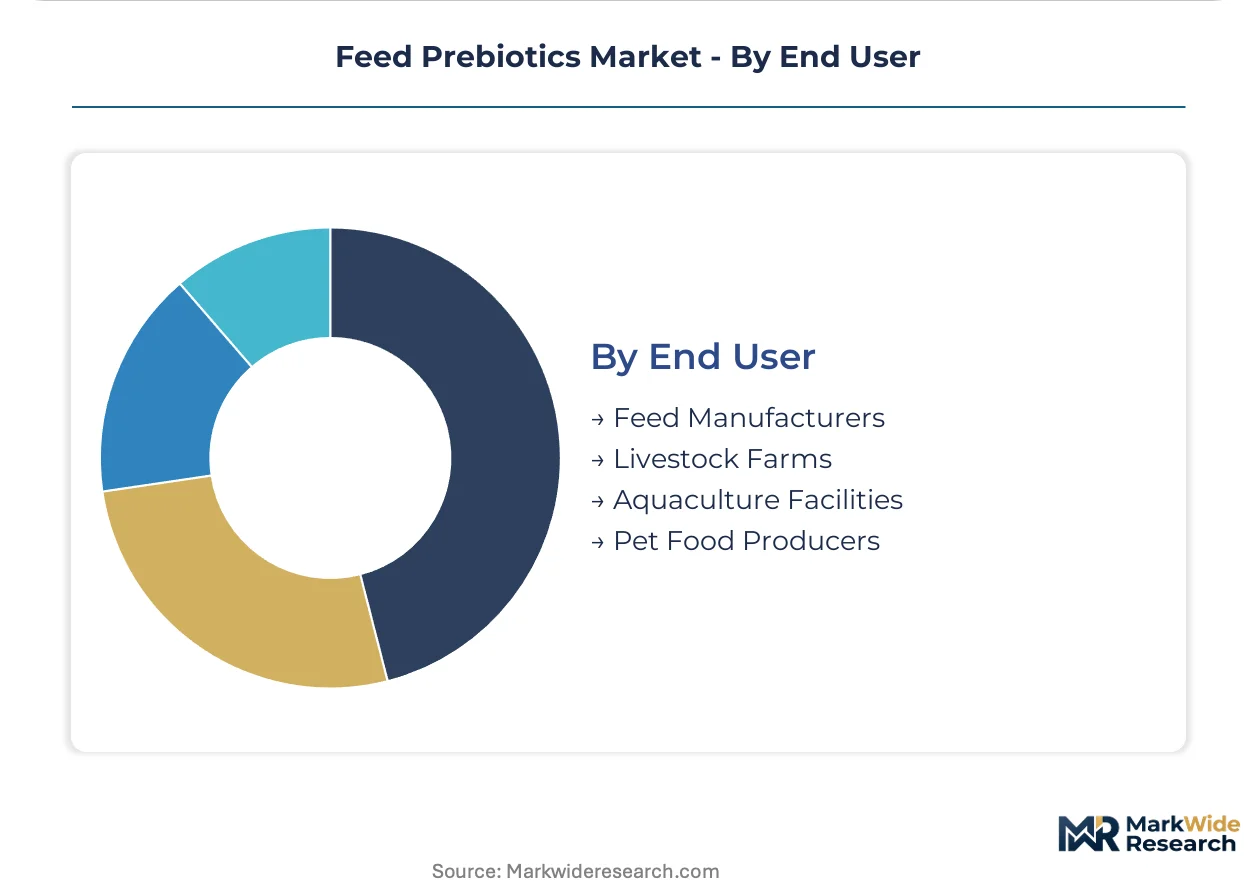
End User:
Customer type determines technical service intensity: feed manufacturers demand bulk consistency and formulation flexibility, while livestock farms require on-farm microbiome assessment support.
- Feed Manufacturers:Premix and complete feed producers specify prebiotic grades based on pelleting stability and compatibility with enzyme-acid bundles. German, French, and Polish formulators are most affected by EU F-Gas Regulation retooling requirements.
- Livestock Farms:Direct procurement concentrates in large integrated poultry and swine operations with captive feed mills, particularly in Brazil's Mato Grosso and Paraná states.
- Aquaculture Facilities:Norwegian salmon and Chilean producers adopt fermentation-derived mannan-oligosaccharides at accelerating rates for gut health protocols.
- Pet Food Producers:Premium and super-premium pet food brands incorporate prebiotics for digestive health positioning in North American and European markets.
Feed manufacturers lead volumes today; aquaculture facilities is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgium and the Netherlands pioneered commercial-scale chicory root processing for inulin extraction during the 1980s, establishing the feed prebiotics industry's original production corridor. This Benelux foundation seeded technical expertise that now spans fermentation biotechnology clusters across multiple continents. Today, regulatory chemistry and procurement consolidation reshape geographic competitive positioning.
Belgium
Chicory root cultivation and enzymatic hydrolysis capacity concentrate in the Flanders agricultural belt, supplying fructo-oligosaccharide feedstock to German and Polish premix formulators. EFSA feed additive authorization timelines of 18-24 months compress development returns for novel submissions from Belgian biotechnology developers. The Port of Antwerp handles bulk oligosaccharide exports to Brazilian integrators in Mato Grosso state.
Brazil
Integrated poultry and swine operations in Mato Grosso and Paraná states now specify prebiotic inclusion rates centrally, displacing mill-level procurement discretion that dominated prior decades. MAPA tightened antibiotic residue monitoring protocols, elevating prebiotic alternatives in commercial feed formulations. Three integrators control over sixty percent of commercial feed volume in these states, consolidating supplier qualification authority.
Germany
Poultry premix formulators in Lower Saxony and North Rhine-Westphalia face acute pressure from EU F-Gas Regulation retooling requirements for refrigerant-dependent extraction facilities. German integrators demand documented flock uniformity and feed conversion ratio metrics from prebiotic suppliers. The Cologne-Düsseldorf corridor hosts technical service operations supporting Central European livestock operations.
United States
The FDA Center for Veterinary Medicine exercises oversight of direct-fed microbial and prebiotic claims, creating distinct approval pathways from European frameworks. Corn Belt feed manufacturers bundle prebiotics with enzyme-acid combinations in modular premix configurations. Iowa and Illinois-based operations represent the densest concentration of commercial feed milling capacity adopting these bundled formulations.
China
The Ministry of Agriculture and Rural Affairs maintains a positive list approach for feed additive approval, fragmenting regional product portfolios and delaying market access for novel prebiotic submissions. Yangtze River Delta aquaculture operations scale mannan-oligosaccharide inclusion for shrimp gut health protocols. Shandong Province poultry integrators drive domestic fermentation capacity expansion for galacto-oligosaccharide production.
Feed Prebiotics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across documentation and technical service intensity, with poultry integrator requirements creating tier separation. The vendor base spans multinational agricultural conglomerates with captive fermentation capacity, specialized biotechnology developers, and regional distributors losing ground to centralized procurement. Three strategic archetypes dominate: integrated supply chain operators controlling raw material sourcing through finished feed formulation; fermentation technology specialists leveraging microbial synthesis platforms; and yeast-based prebiotic platforms combining product with direct technical service. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with modular premix bundling forcing production line reconfiguration for flexible batch sizing.
Within the integrated supply chain archetype, Cargill Incorporated exemplifies backward integration from chicory root sourcing through commercial feed formulation. DSM-Firmenich AG occupies a position among fermentation technology specialists, anchoring biotechnology leadership in microbial-derived oligosaccharides. Alltech Inc. represents the yeast-based platform model, combining technical service infrastructure with livestock operation support. These three companies illustrate how divergent production architectures—plant extraction, precision fermentation, and yeast cell wall processing—coexist under divergent margin structures and regulatory exposure profiles.
| Leading Market Players |
|---|
| ADM |
| Cargill Incorporated |
| DSM-Firmenich AG |
| Alltech Inc. |
| Kemin Industries Inc. |
| Ingredion Incorporated |
| Kerry Group |
| Land O'Lakes Inc. |
| Novus International Inc. |
| Others |
Supply & Pricing Matrix
Centralized procurement mandates from Brazilian poultry integrators in Mato Grosso and Paraná states are compressing distributor margins and forcing fermentation capacity investments that reshape cost structures across supplier tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates fermentation-derived galacto-oligosaccharides from chicory-root fructo-oligosaccharides and commodity inulin grades. Price differentiation rests on EFSA certification status and documented flock uniformity metrics for poultry integrators. Margins are tightening due to modular premix bundling demands from feed manufacturers. Standard-grade inulin faces acute price sensitivity from cost-sensitive swine nutrition segments, while premium fermentation-derived products command pricing power from aquaculture specialists in Norway and Chile.
Supply Chain Analysis
Domestic-content mandates in China's Ministry of Agriculture and Rural Affairs approvals are fragmenting regional product portfolios and compelling foreign suppliers to establish local fermentation partnerships. Raw material sourcing draws from chicory root cultivation in Belgium and the Netherlands, yeast cell wall processing in North American biotechnology clusters, and lactose feedstock for galacto-oligosaccharide production. Single-source vulnerability concentrates in chicory root supply from Benelux agricultural belts exposed to weather-driven yield volatility. Distribution runs through Antwerp bulk terminals for European exports and São Paulo logistics hubs for Brazilian integrator supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Feed Prebiotics Market functions as a regulatory compounder where EU F-Gas Regulation mandates are systematically displacing conventional growth promoters and elevating fermentation-derived alternatives.
For Market Incumbents: To counter enzyme-prebiotic substitution threats in cost-sensitive swine segments, incumbents must deepen backward integration into captive fermentation capacity and secure EFSA authorization pipelines for novel oligosaccharide submissions. Capacity addition in Brazilian Mato Grosso state addresses integrator consolidation patterns. For New Entrants and Emerging Players: India's FSSAI residue monitoring protocols open a window for prebiotic alternatives in dairy and poultry operations where technical service infrastructure remains underdeveloped. Vietnamese and Indonesian aquaculture facilities represent penetrable white-space targets combining product with on-farm microbiome assessment capabilities. For Investors and Strategic Acquirers: Asymmetric upside sits with fermentation technology specialists possessing commercial-scale biochemical engineering expertise and active EFSA submission pipelines. Long-term viability favors platforms with demonstrated pelleting stability in modular premix configurations. Watch for EFSA authorization timeline compression as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Captures volume from solvent-extraction competitors affected by EU F-Gas Regulation retooling requirements. |
| EFSA Authorization Investment | Compresses product development return horizons but secures premium positioning in German and Polish poultry premix markets. |
| Technical Service Channel Buildout | Addresses livestock operation support gaps in Vietnam and Indonesia where distributor roles are compressing. |
| Backward Integration into Yeast Processing | Secures mannan-oligosaccharide supply continuity for aquaculture gut health protocol expansion. |
| Modular Premix Partnership | Aligns production lines with feed manufacturer demands for customizable enzyme-prebiotic-acid combinations. |
Research Methodology
Coverage spans Benelux, Brazil, Germany, China, and the United States, with primary inputs from each region combining interviews with feed formulation directors, regulatory affairs specialists at biotechnology developers, procurement leads at Brazilian integrators, and technical service managers at premix manufacturers. Secondary validation draws from EFSA feed additive registers, FDA Center for Veterinary Medicine guidance documents, Brazil MAPA residue monitoring protocols, and customs trade data for oligosaccharide bulk movements. Bottom-up volume modeling triangulates against top-down expenditure estimates from integrated poultry and swine operations.
Rate-of-change decomposition isolates volume drivers by product chemistry, application species, and end-user procurement concentration across the analysis window. The modeling framework segments by fructo-oligosaccharide, mannan-oligosaccharide, inulin, and galacto-oligosaccharide product types; poultry, aquaculture, swine, and ruminant applications; and feed manufacturer versus livestock farm end-user channels. CAGRs derive from fitted growth curves incorporating documented flock uniformity metrics and feed conversion ratio improvements as performance validation inputs.
Revisions become necessary when EFSA authorization timelines extend beyond standard evaluation windows, when chicory root yields in Belgium and the Netherlands deviate from historical patterns, or when Chinese positive list approvals accelerate or restrict market access. Forecasts reflect assumptions about regulatory equivalence agreements and integrator procurement consolidation trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Postbiotic Supplements Market
Nutritional Supplements
Inflammation Supplements Market
Nutritional Supplements
Middle East and Africa Nutricosmetics Market
Nutritional Supplements
Grass-Fed Collagen Market
Nutritional Supplements
Phytoceramide Supplement Market
Nutritional Supplements
Water Soluble Vitamin and Mineral Feed Supplements Market
Nutritional Supplements
Multivitamin and Mineral Supplements Market
Nutritional Supplements
Chaga Mushroom Extract Market
Nutritional Supplements
Middle East Protein Market
Nutritional Supplements
Biotin Supplement Market
Nutritional Supplements
Vegan Collagen Protein Market
Nutritional Supplements
Vegan Protein Supplements Market
Nutritional Supplements
Bone Meal Supplement Market
Nutritional Supplements
Africa Beta Glucan Market
Nutritional Supplements
Global Proanthocyanidins Market
Nutritional Supplements
Sleep Gummies Market