
 Jackhammer Market | 2026-2036
Jackhammer Market Size, Share, and Industry Trends Forecast 2026-2036
Jackhammer Market Intelligence
Equipment rental networks is fragmenting as independent regional fleets challenge national distributors for construction contractor loyalty. Atlas Copco AB anchors its position through captive service centers in Nordic mining corridors. Hilti Corporation differentiates via direct-to-contractor subscription models that bundle tools, maintenance, and fleet tracking. Makita Corporation competes on battery-platform interoperability across its cordless demolition range.
A jackhammer is a percussive power tool that delivers repeated hammer blows through a chisel or pointed bit, typically generating impact energy from 15 to 70 joules depending on power source and piston diameter. Pneumatic variants dominate underground mining and tunneling where compressed air infrastructure exists, while electric models gain share in urban demolition constrained by emissions ordinances. Medium-size units occupy the largest volume tier across road maintenance and building renovation, whereas extra-large hydraulic breakers command the strongest margin pools in quarrying and primary rock excavation. The 11-15 HP power band represents the fastest-growing rating class as contractors seek single-machine versatility across multiple substrate hardnesses.
OSHA permissible exposure limits for noise and hand-arm vibration shape product design requirements in the United States, while CE marking under the EU Machinery Directive governs safety interlocks and electromagnetic compatibility for European access. EPA tiered emissions standards affect engine-driven portable compressor pairings that power pneumatic units in non-attainment zones. Stakeholders must monitor evolving battery energy density benchmarks and local silica dust regulations to calibrate R&D priorities and fleet replacement timing.
Market Dynamics
The jackhammer market is being restructured by the migration from pneumatic to electric powertrains in urban construction zones, where emissions ordinances and noise restrictions render compressed-air infrastructure economically unviable for new projects.
Growth Catalysts
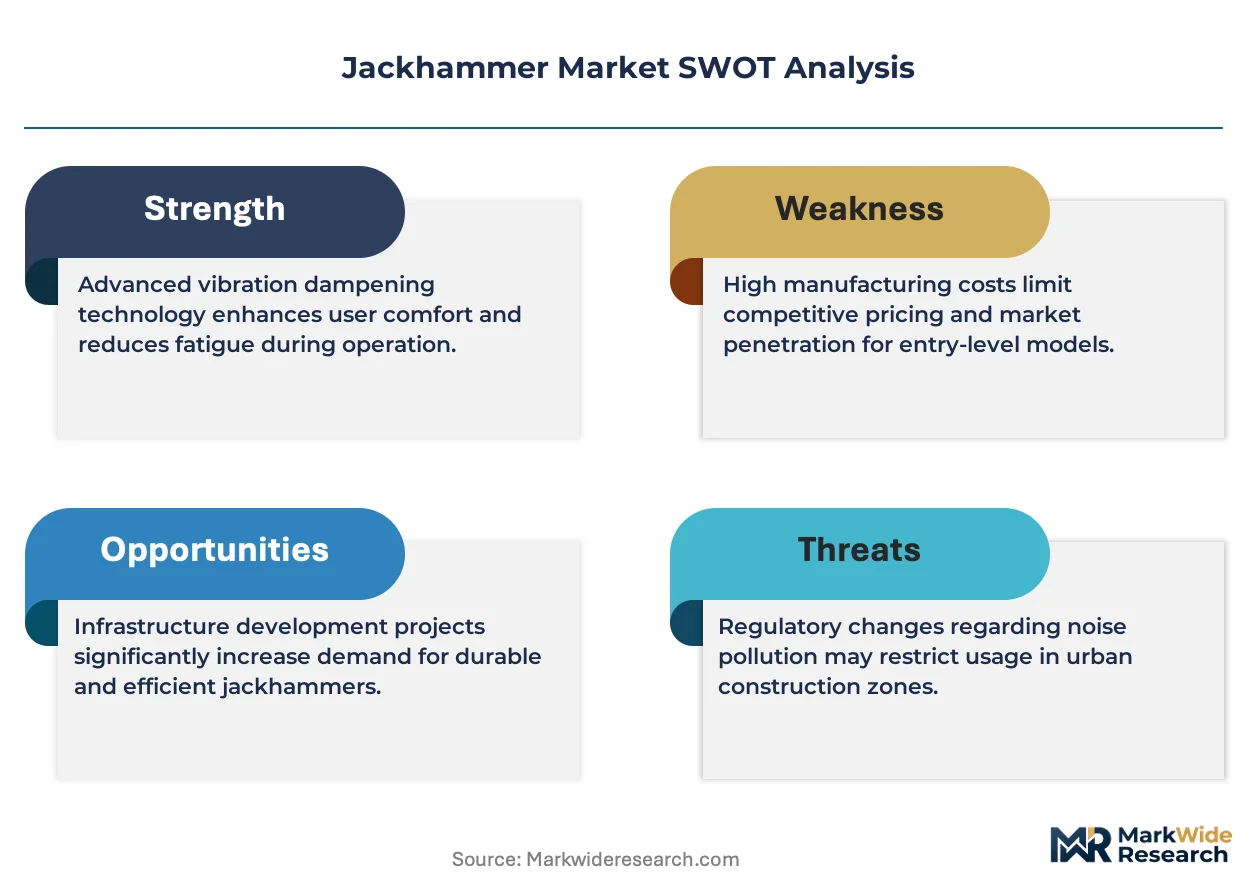
- OSHA noise exposure limits:Contractors in the United States face mandatory hearing conservation programs above 85 decibels, accelerating replacement of legacy pneumatic units with lower-decibel electric and hydraulic alternatives.
- Battery energy density benchmarks:Lithium-ion cell improvements enable cordless demolition tools to deliver impact energies previously restricted to corded or pneumatic systems, expanding viable use cases.
- Urban tunneling contractors:Infrastructure renewal cycles in Germany and China concentrate demand for medium-size electric breakers that navigate confined underground workspaces without ventilation constraints.
Market Restraints
- Neodymium magnet supply concentration:Rare-earth processing capacity clusters in China creates input cost volatility and geopolitical exposure for brushless motor production in cordless platforms.
- Pneumatic infrastructure lock-in:Mining operators with sunk capital in compressed-air networks face high switching costs that delay electric adoption despite operational advantages.
- Silica dust exposure standards:Strict enforcement of permissible exposure limits by OSHA and EU member state regulators adds compliance burden and equipment modification costs.
Strategic Opportunities
- EU Green Deal machinery retrofit incentives:Member state programs subsidize replacement of diesel-powered compressors with electric alternatives, creating pull-through demand for compatible breaker units.
- Building renovation vertical:Deep energy retrofit mandates across European residential stock expand demand for compact electric breakers in interior demolition where emissions and noise are prohibited.
- Tool-as-a-service platforms:Subscription models bundling maintenance, fleet tracking, and usage analytics penetrate contractor segments seeking to convert capital expenditure to operational expenditure.
Industry Challenges
- Vibration white finger certification:Compliance with ISO 5349 hand-arm vibration measurement protocols requires extensive testing cycles that extend product development timelines.
- Legacy fleet interoperability:Contractors operating mixed-vintage equipment face integration friction when connecting smart battery platforms to older tool bodies lacking communication chips.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Jackhammer Market |
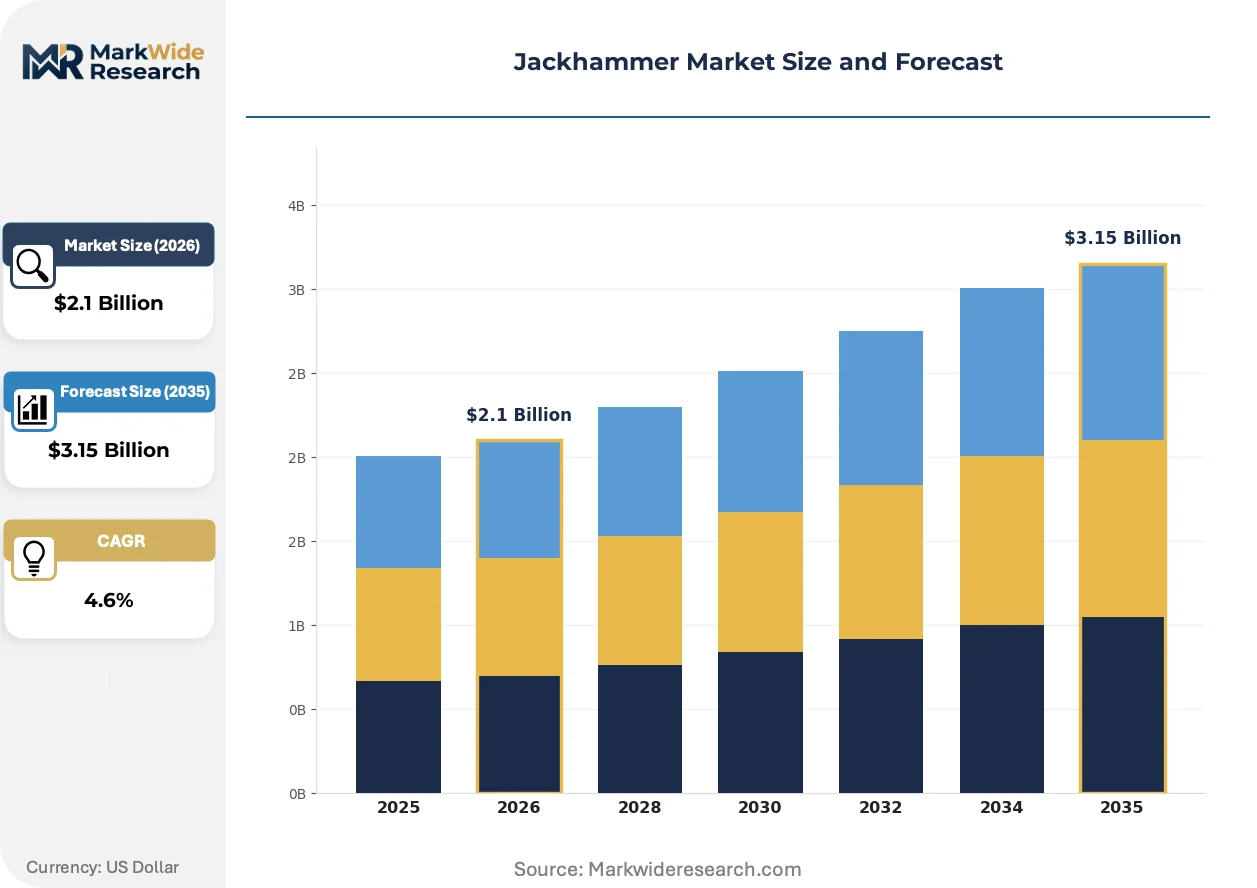
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pneumatic, Electric, Hydraulic, Demolition End User: Construction, Mining, Landscaping, Road Maintenance Size: Small, Medium, Large, Extra Large Power Rating: 1-5 HP, 6-10 HP, 11-15 HP, 16+ HP |
| Companies Covered | Robert Bosch GmbH, Chicago Pneumatic Tool Company LLC, Atlas Copco AB, Koki Holdings Co., Ltd., Einhell Germany AG, Hilti Corporation, Stanley Black & Decker, Inc., Wacker Neuson SE, Makita Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Jackhammer Market Strategic Shifts & Innovations
Electrification is compressing the traditional technology hierarchy in demolition equipment, while regulatory pressure on occupational health and environmental emissions forces simultaneous adaptation across powertrain, control, and safety systems.
Battery-platform standardization is collapsing the historical segmentation between professional and light-commercial tool tiers. Contractors now deploy interchangeable battery packs across rotary hammers, breakers, and cut-off saws from single manufacturers, reducing fleet complexity and spare parts inventory. This convergence pressures pure-play pneumatic specialists to develop electric competence or retreat to mining niches where compressed-air infrastructure remains entrenched.
CE marking under the EU Machinery Directive now mandates electromagnetic compatibility and safety interlocks that exceed prior voluntary standards. Manufacturers serving European access must redesign control electronics and mechanical brakes to satisfy notified body certification, adding engineering cost but creating regulatory moats against non-compliant imports. The construction equipment segment experiences the tightest compliance timelines as the directive's latest amendments take effect.
Rental channel consolidation is altering how contractors access demolition equipment. Independent regional fleets challenge national distributors by offering localized service response and flexible term structures, forcing incumbents to unbundle maintenance contracts and deploy telematics for utilization-based pricing. This pattern is most visible in German-speaking markets where Mittelstand construction firms prioritize proximity support over brand breadth.
Jackhammer Market Segmentation
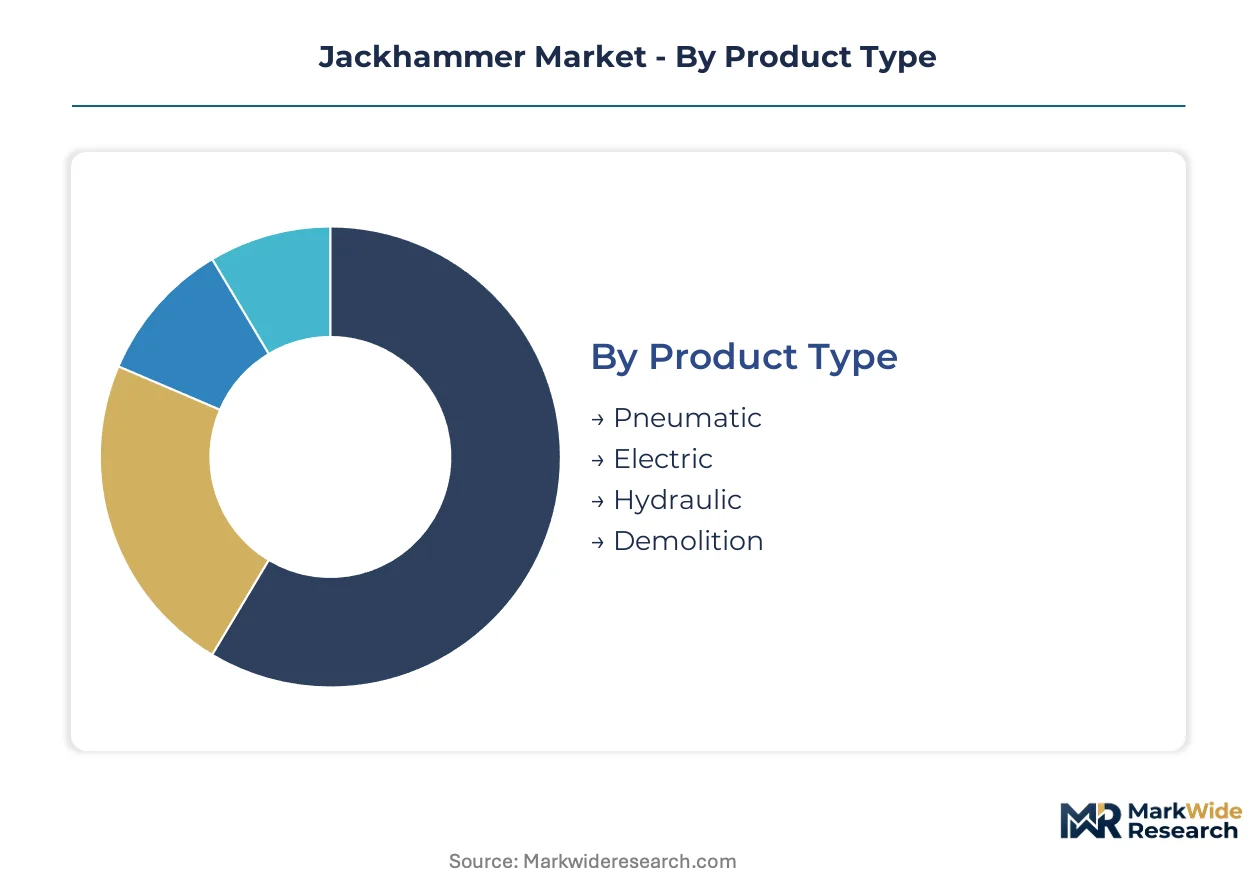
Powertrain diversity and application-specific demands fragment the jackhammer market into distinct procurement channels. Contractors select units based on substrate hardness, workspace ventilation constraints, and fleet interoperability requirements.
Product Type:
Mature pneumatic systems coexist with emerging electric platforms as urban emissions ordinances reshape contractor preferences.
- Electric:Brushless motor designs deliver 15-45 joule impact energy through lithium-ion power packs, eliminating exhaust ventilation in German tunneling projects and interior demolition sites. Battery-platform standardization across rotary hammers and breakers reduces contractor spare parts inventory. Electric variants retain volume leadership; hydraulic systems hold the steepest expansion curve in quarrying applications.
- Pneumatic:Compressed-air systems generate sustained impact through reciprocating piston mechanisms, dominating underground mining corridors in China where sunk infrastructure capital delays platform migration. OSHA noise exposure limits accelerate replacement timelines in United States construction zones.
- Hydraulic:Fluid-power breakers attach to carrier excavators for primary rock excavation, commanding premium positioning in Scandinavian quarrying operations.
- Demolition:Specialized long-reach configurations address vertical structure takedown in Japanese urban renewal districts.
Electric platforms capture urban replacement cycles; hydraulic attachments gain share in open-pit extraction.
End User:
Volume concentration varies sharply across project types, with infrastructure renewal driving equipment refresh timelines.
- Construction:General contractors deploy medium-size electric breakers for building renovation and structural modification, constrained by EU Machinery Directive electromagnetic compatibility mandates. Residential energy retrofit programs across France and Germany expand interior demolition demand. Construction retains volume leadership; road maintenance holds the steepest expansion curve.
- Mining:Underground operators in South Africa and Australia maintain pneumatic fleet dominance due to compressed-air infrastructure lock-in and ventilation system compatibility.
- Road Maintenance:Municipal agencies in the United States prioritize 11-15 HP electric units for asphalt cutting and concrete joint repair, responding to EPA non-attainment zone restrictions on diesel compressor pairings.
- Landscaping:Compact cordless systems address residential hardscape removal in suburban United States markets where noise ordinances prohibit pneumatic operation.
Construction absorbs the largest unit volumes; road maintenance agencies convert capital expenditure to operational expenditure through rental subscriptions.
Size:
Physical footprint determines workspace accessibility and substrate penetration capability across application tiers.
- Medium:20-35 kilogram units balance maneuverability with impact energy delivery, dominating German road maintenance and Chinese urban tunneling where confined workspaces restrict larger equipment. Medium-size configurations retain volume leadership; extra-large systems hold the steepest expansion curve.
- Extra Large:Excavator-mounted hydraulic breakers exceed 100 kilogram tool weight for primary rock fragmentation in Brazilian and Australian quarrying operations.
- Small:Single-operator cordless units address interior wall demolition and tile removal in European residential retrofit projects.
- Large:Stationary pneumatic rigs persist in Chinese coal mining vertical shafts where compressed-air infrastructure remains entrenched.
Medium-size units dominate contractor procurement; extra-large hydraulic attachments expand most quickly in extractive industries.
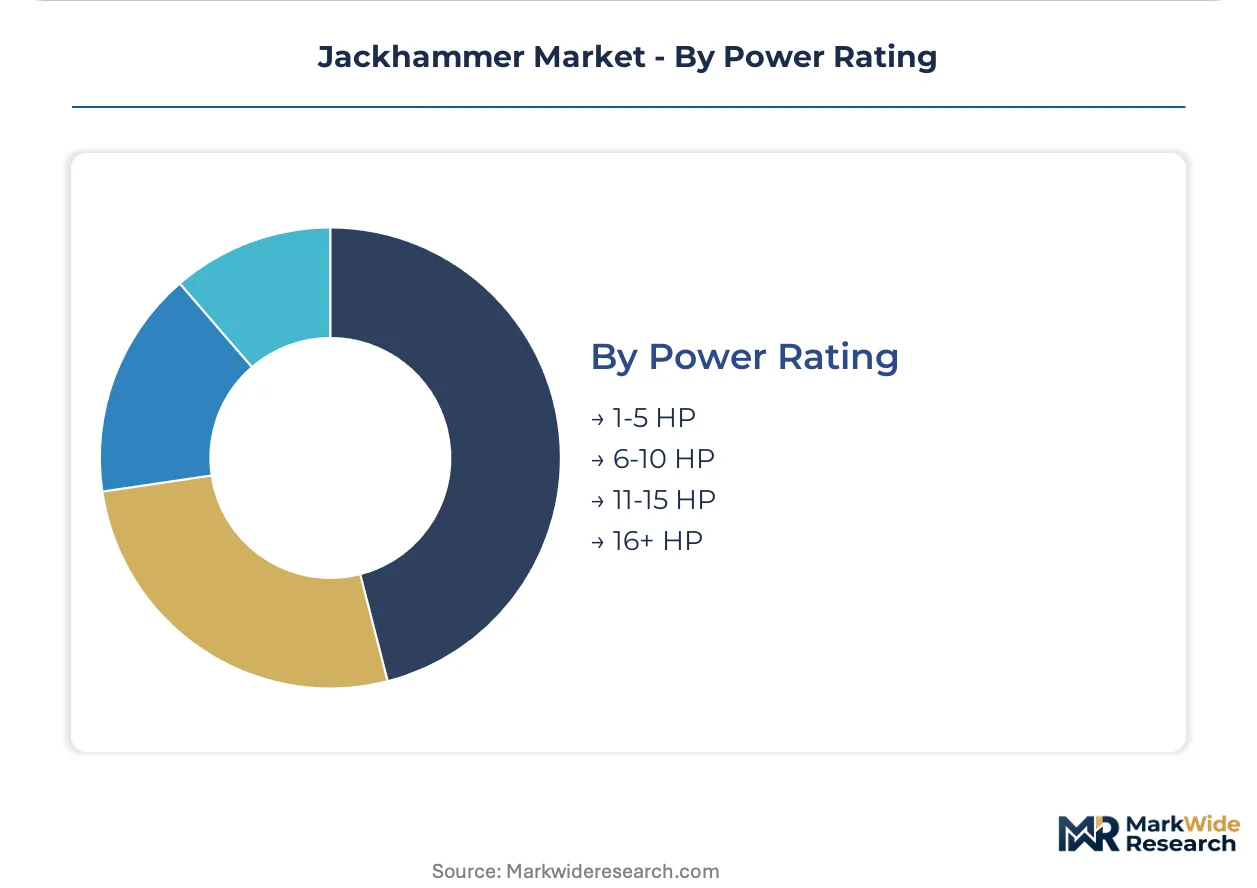
Power Rating:
Motor and engine specifications align with substrate hardness gradients and continuous duty cycle requirements.
- 11-15 HP:Mid-range power band enables single-machine versatility across reinforced concrete, asphalt, and sedimentary rock without platform switching. Contractors in the United States and Germany favor this rating for mixed-substrate road maintenance contracts. The 11-15 HP segment retains volume leadership; 16+ HP systems hold the steepest expansion curve.
- 16+ HP:High-displacement hydraulic power units address granite and basalt excavation in Nordic and Canadian quarrying operations.
- 1-5 HP:Compact electric motors serve light demolition and landscaping applications in Japanese residential districts.
- 6-10 HP:Entry-level professional tier bridges consumer and commercial use cases in emerging construction markets.
The 11-15 HP rating dominates fleet procurement; 16+ HP configurations climb the fastest in hard-rock extraction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA noise exposure limits in the United States anchor regulatory pressure across the dominant geography, while infrastructure renewal cycles in Germany and China concentrate replacement demand for electric and hydraulic variants.
United States
Municipal road maintenance agencies in California and Texas drive procurement of 11-15 HP electric units for asphalt cutting and concrete joint repair. EPA tiered emissions standards restrict diesel compressor pairings in non-attainment zones, accelerating electric adoption. The Pacific Northwest corridor hosts contractor fleets converting capital expenditure to operational expenditure through rental subscription platforms.
Germany
Urban tunneling contractors in the Ruhr region and Bavaria prioritize medium-size electric breakers for confined underground workspaces without ventilation constraints. EU Machinery Directive CE marking mandates electromagnetic compatibility and safety interlocks that exceed prior voluntary standards. The Mittelstand construction belt around Stuttgart and Munich favors proximity service response from independent regional rental fleets over national distributor breadth.
China
Underground mining operators in Shanxi and Inner Mongolia maintain pneumatic fleet dominance due to compressed-air infrastructure lock-in. The country's dual carbon goals pressure surface construction projects toward electric alternatives in Beijing-Tianjin-Hebei and Yangtze River Delta megacity clusters. Local rare-earth processing concentration for neodymium magnets creates input cost volatility for brushless motor production serving cordless platforms.
Australia
Quarrying operations in Western Australia and Queensland command extra-large hydraulic breakers for primary rock excavation in iron ore and coal extraction. The country's national occupational health regulator enforces hand-arm vibration measurement protocols that extend equipment certification timelines. Perth and Brisbane serve as distribution hubs for extractive industry equipment serving Pilbara and Bowen Basin mining corridors.
Brazil
Infrastructure investment programs in São Paulo and Minas Gerais expand demand for medium-size breakers in road maintenance and building renovation. ANVISA occupational health regulations align with ISO vibration standards, shaping product design requirements for imported equipment. The southeastern industrial triangle concentrates contractor procurement decisions for demolition equipment serving Latin American extractive projects.
Jackhammer Market Key Industry Players
Diversified industrial conglomerates and specialized power tool manufacturers split the market across distinct capability vectors. The vendor base clusters around three strategic archetypes: captive service network operators, battery-platform ecosystem builders, and pneumatic heritage specialists defending mining niches. Consolidation pressure intensifies as rental channel fragmentation forces incumbents to unbundle maintenance contracts and deploy telematics for utilization-based pricing. Geographic expansion and portfolio diversification represent the dominant competitive moves as players seek to offset regional demand cyclicality.
Among diversified industrial conglomerates, Robert Bosch GmbH and Stanley Black & Decker, Inc. occupy positions spanning professional and consumer tool tiers through multi-brand architectures. Atlas Copco AB anchors the pneumatic heritage specialist archetype with entrenched presence in Nordic and Australian mining corridors where compressed-air infrastructure delays platform migration. These three entities exemplify divergent responses to electrification pressure: conglomerates leverage battery-platform standardization across tool categories, while the pneumatic specialist defends margin pools in extractive applications where infrastructure lock-in persists.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Chicago Pneumatic Tool Company LLC |
| Atlas Copco AB |
| Koki Holdings Co., Ltd. |
| Einhell Germany AG |
| Hilti Corporation |
| Stanley Black & Decker, Inc. |
| Wacker Neuson SE |
| Makita Corporation |
| Others |
Cost & Logistics Intelligence
Shanxi Province's rare-earth processing corridors anchor global neodymium magnet supply for brushless motor production, translating concentrated upstream capacity into volatile input costs that compress margins across cordless jackhammer tiers. Contractors in Germany and the United States absorb these fluctuations through extended equipment replacement cycles or rental subscription conversions.
Pricing Analysis
Transatlantic price spreads of 15-25 percent separate European premium tiers from North American mid-market positioning, driven by CE marking compliance costs and localized service bundling. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales density, with ISO 5349 vibration certification commanding measurable premiums. Cost compression in economy cordless tiers is intensifying because lithium-ion cell price volatility feeds through to bill-of-materials pressure. Municipal road maintenance agencies exhibit highest price sensitivity, while mining operators with compressed-air infrastructure lock-in demonstrate lowest elasticity due to switching cost inertia.
Supply Chain Analysis
Supplier-financing facilities from Chinese battery cell manufacturers extend 90-120 day payment terms to tier-one power tool assemblers, easing working capital constraints but tethering procurement to geographic concentration. Manufacturing draws from China, Germany, and Japan for precision-machined piston assemblies, lithium-ion cells, and high-grade steel forgings respectively. Single-source vulnerability around rare-earth magnet processing creates tariff exposure and geopolitical risk concentration. Distribution runs through independent regional rental fleets in German-speaking markets and national distributor networks across North American construction corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery-platform standardization is collapsing historical segmentation between professional and light-commercial tiers, creating platform-economics dynamics where interoperability investments determine ecosystem lock-in and recurring revenue capture.
For Market Incumbents: Harden defensive positions by deepening captive service network density in Nordic and Australian mining corridors where pneumatic infrastructure delays electrification pressure. Prioritize backward integration into brushless motor production to offset neodymium magnet supply volatility from Chinese processors. Channel control through telematics-enabled utilization pricing will differentiate against independent rental fleet fragmentation. For New Entrants and Emerging Players: Pursue white-space penetration in European residential energy retrofit verticals where compact electric breakers face limited incumbent specialization. Target Brazilian road maintenance agencies converting capital expenditure to operational expenditure through flexible rental structures. A go-to-market angle bundling silica dust suppression compliance with equipment subscription addresses regulatory enforcement intensity. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors battery-platform ecosystem builders with demonstrated interoperability across rotary hammers, breakers, and cut-off saws. Long-term viability over a multi-year horizon rests on R&D amortization across cordless portfolios rather than pneumatic heritage defense. Acquisition targets should demonstrate telematics infrastructure and regional service density. The signal to watch is rental channel consolidation velocity in German-speaking markets as utilization-based pricing penetration indicates ecosystem maturity.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Standardization | Interoperability across breakers and rotary hammers reduces contractor spare parts inventory and deepens ecosystem lock-in. |
| Telematics-Enabled Rental Subscription | Usage analytics convert capital expenditure to operational expenditure for municipal road maintenance agencies. |
| CE Marking Compliance Investment | Electromagnetic compatibility certification creates regulatory moats against non-compliant imports in European access. |
| Silica Dust Suppression Integration | OSHA and EU enforcement of permissible exposure limits adds equipment modification revenue streams. |
| Independent Regional Fleet Expansion | Proximity service response captures Mittelstand contractor loyalty from national distributor breadth in Germany. |
Research Approach
Findings reconcile primary fieldwork against secondary review of customs trade records, SEC equipment manufacturer filings, and EU Machinery Directive notification databases. Primary interviews engaged maintenance directors at German tunneling contractors, aftermarket service heads at Nordic mining operators, and procurement leads at municipal road maintenance agencies across California and Texas. Secondary validation drew from OSHA enforcement data, EPA tiered emissions compliance records, and IEA infrastructure investment tracking. Bottom-up unit shipment modeling triangulates against top-down value estimates from rental channel revenue disclosures.
Forecast inputs span powertrain migration rates, infrastructure renewal cycle timing, and battery energy density improvement trajectories across the analysis window. Segmentation dimensions include product type, end user vertical, size classification, and power rating tier. CAGRs derive from regression analysis against historical replacement patterns and regulatory compliance deadline clustering. Industry-specific inputs incorporate neodymium magnet price volatility indices and silica dust enforcement intensity scoring.
Sensitivities concentrate around rare-earth supply disruption scenarios, accelerated EU Green Deal machinery retrofit subsidy expansion, and lithium-ion cell cost compression trajectories. Forecasts reflect documented assumptions regarding contractor fleet replacement elasticity and rental channel penetration ceilings. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Compact Excavator Market
Construction Equipment
Overhead Cranes Market
Construction Equipment
Hybrid Excavator Market
Construction Equipment
Manhole Housing Lifter Hook Market
Construction Equipment
Hammer Unions Market
Construction Equipment
Mill Pulverizer Market
Construction Equipment
Rotomolding Market
Construction Equipment
Piles Turner Market
Construction Equipment
Concrete Spreader Market
Construction Equipment
Bitumen Testing Equipment Market
Construction Equipment
Plasma Welding Machine Market
Construction Equipment
Latin America Heavy Construction Equipment Rental Market
Construction Equipment
Europe Excavator and Loaders Market
Construction Equipment
Concrete Chain Saw Market
Construction Equipment
Hexagonal Wire Netting Machine Market
Construction Equipment
Electric and Hybrid Construction Equipment Market