
 Escalator Cleaning Machine Market | 2026-2036
Escalator Cleaning Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Escalator Cleaning Machine Market Analysis
German engineering clusters is decoupling from generic floor-care manufacturing by building dedicated escalator-specific production lines. Kärcher leverages its pressure-wash heritage to dominate high-pressure cleaning configurations for transit systems. Nilfisk Group anchors European demand through specialized distribution to airport operators. Tennant Company competes in North America with autonomous-ready chassis designs that accommodate future robotic retrofit.
An escalator cleaning machine is a powered maintenance device engineered to remove debris, grease, and particulate accumulation from step treads, risers, and skirt panels without dismantling the escalator assembly; units typically operate at 1,500–3,000 RPM brush speeds with integrated vacuum recovery and solution injection systems to restore traction surfaces in continuous-duty commercial environments. Automatic cleaners lead volume due to labor-cost sensitivity among facility managers, while robotic cleaners represent the fastest-expanding margin pool as sensor costs decline and nighttime autonomous operation protocols mature. Chemical cleaning technology still occupies the largest installed base, though eco-friendly cleaning formulations are displacing solvent-based systems where wastewater discharge regulations have tightened.
The EU Machinery Directive and CE marking framework mandate emergency-stop integration and noise thresholds below 85 dB for equipment deployed in public spaces, directly shaping R&D priorities for European-market models. In the United States, OSHA walkway-surface standards and ADA slip-resistance requirements create compliance pull-through for certified cleaning protocols in commercial buildings and hospitals. Stakeholders must monitor how regional certification divergence between EPA Safer Choice formulations and REACH substance restrictions fragments product portfolios and service model economics.
Market Dynamics
The escalator cleaning machine market pivots on tightening wastewater discharge protocols that force solvent-based system obsolescence, compelling manufacturers to reformulate chemical recovery loops and redesign vacuum-sealed chassis architectures.
Growth Catalysts
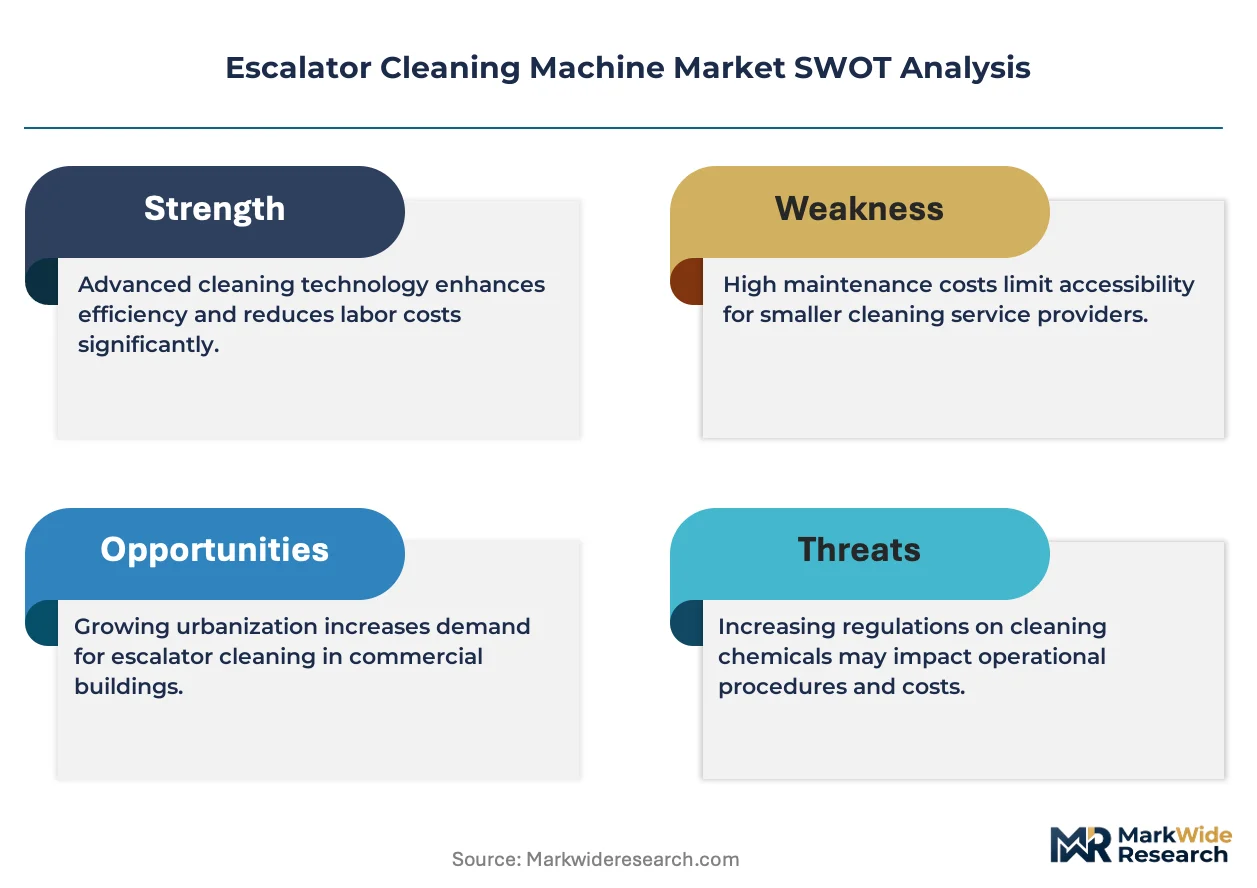
- EU Machinery Directive emergency-stop mandates:CE marking requirements for public-space noise thresholds below 85 dB accelerate replacement cycles in German and French transit authorities.
- Sensor cost deflation:Lidar and computer vision component prices enable autonomous-ready chassis retrofits for nighttime robotic operation in East Asian airports.
- East Asian high-rise density:Tokyo and Seoul metropolitan clusters sustain replacement demand as aging escalator fleets exceed 25-year service intervals.
Market Restraints
- Brush motor supply concentration:High-RPM brush assembly manufacturing clusters in southern China create single-source vulnerability for European OEMs.
- Stainless steel input volatility:Solution tank and chassis fabrication depends on nickel-price swings that compress margin predictability.
- REACH substance restrictions:ECHA candidate list expansions for solvent-based degreasers fragment formulation portfolios and extend R&D timelines.
Strategic Opportunities
- India metro buildouts:Delhi, Mumbai, and Bengaluru transit expansions create first-mover positioning for automated maintenance equipment tenders.
- EPA Safer Choice certification:Formulation compliance unlocks federal procurement preference in US hospital and government building contracts.
- Battery-electric convergence:Lithium-ion powerpack integration with autonomous navigation stacks enables cord-free operation in legacy infrastructure with limited outlet access.
Industry Challenges
- Electromechanical technician scarcity:Brush drive calibration and vacuum seal maintenance require specialized skills that outpace vocational training pipeline output.
- CE-MDR dual certification timelines:Parallel machinery and medical device directives for hospital-deployed units extend validation cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Escalator Cleaning Machine Market |
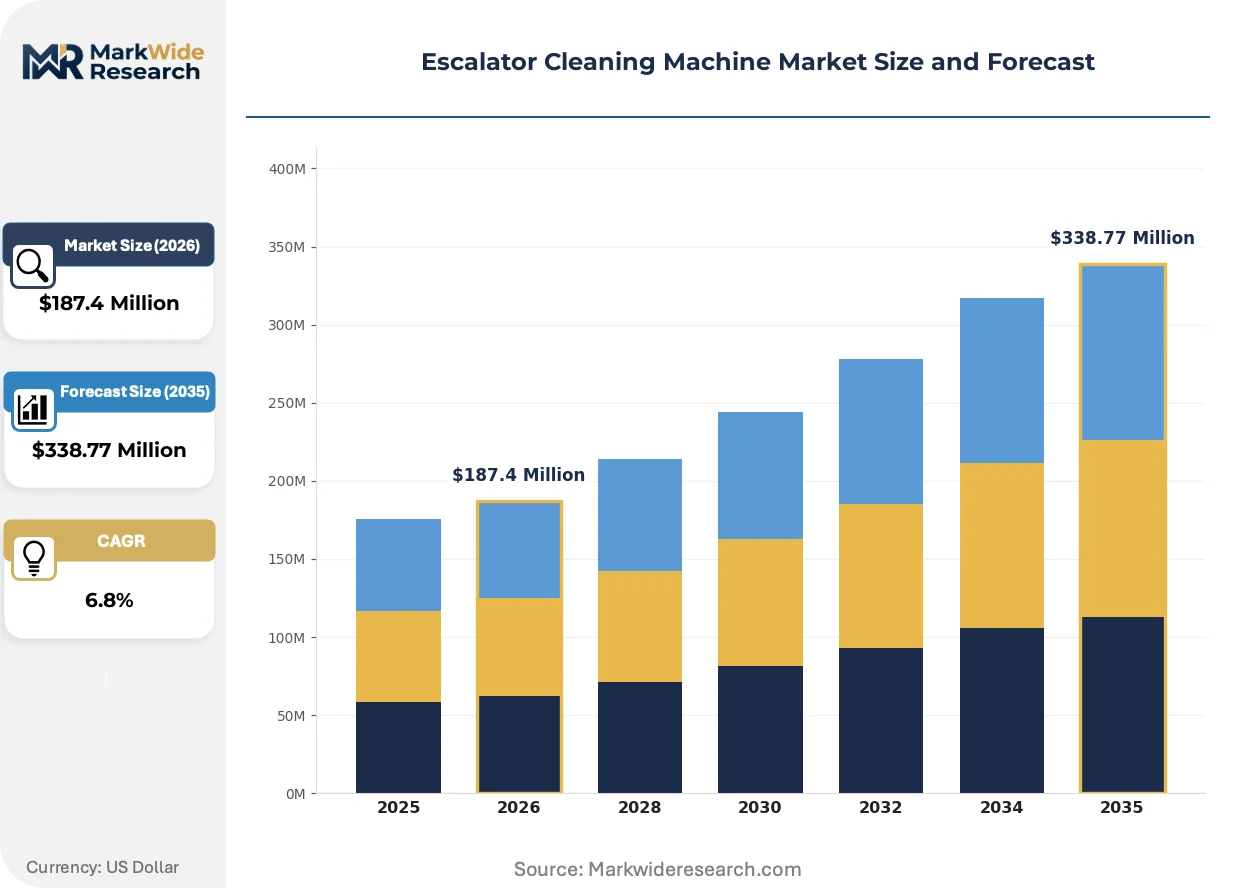
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Cleaners, Manual Cleaners, Robotic Cleaners, Hybrid Cleaners Deployment: On-site, Off-site, Mobile, Stationary End User: Commercial Buildings, Airports, Shopping Malls, Hospitals Technology: Steam Cleaning, Chemical Cleaning, High-pressure Cleaning, Eco-friendly Cleaning |
| Companies Covered | Kärcher, NITEC Solutions International, Fujitec Co., Ltd., Cleanfix Reinigungssysteme AG, Hako GmbH, Nilfisk Group, Tennant Company, Bortek Industries, Inc., Dulevo International S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Escalator Cleaning Machine Market Emerging Trajectories
Equipment architecture is fragmenting into interoperable subsystems that allow transit authorities to upgrade sensing, power, or recovery modules without full chassis replacement.
Brush-and-vacuum assemblies is modularizing into swappable cartridge formats that maintenance crews exchange in under four minutes. Frankfurt and Singapore airport operators pilot hot-swap protocols during 90-minute overnight service windows. This modularity compresses capital deployment by allowing incremental capability upgrades rather than full-unit procurement.
REACH substance restrictions are forcing solvent-based formulation obsolescence across EU member states. ECHA candidate list expansions now cover hydrofluoric acid derivatives previously standard in grease-cutting applications. German and Dutch manufacturers respond with enzyme-based alternatives that trade dwell time for discharge compliance.
Facility managers now unbundle equipment purchase from consumables supply and technical service, fragmenting vendor relationships that once ran through single-source distribution. This disintermediation pressures traditional dealers to reposition as certified service integrators. The shift is most visible in US commercial real estate, where property management platforms centralize procurement across multi-site portfolios.
Escalator Cleaning Machine Market Segmentation
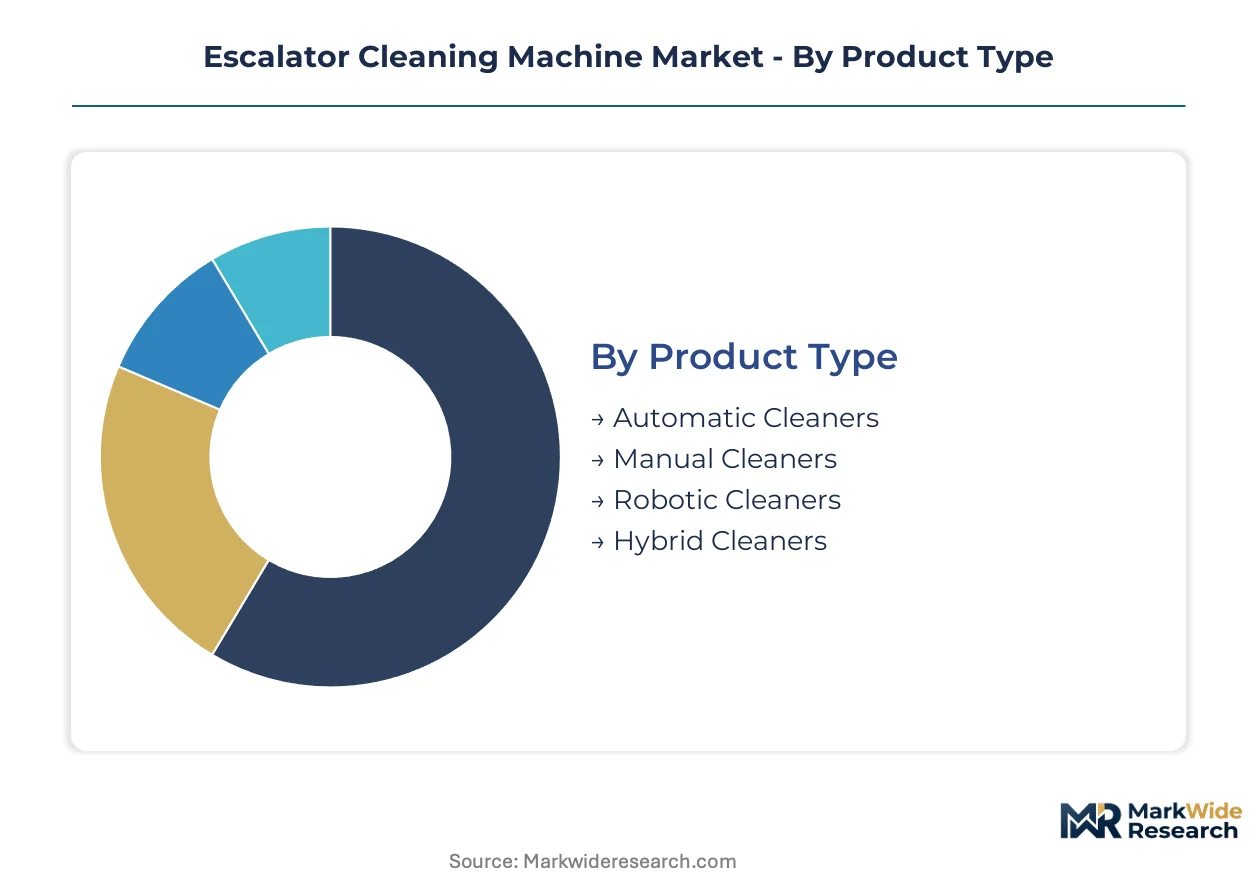
Escalator cleaning equipment procurement splits across operational models, deployment logistics, and regulatory compliance tiers that reshape vendor-customer contracting structures. Facility managers weigh capital outlay against labor substitution rates when matching machine specifications to duty-cycle intensity.
Product Type:
Capital intensity varies sharply across automation levels, with sensor-laden robotic platforms demanding three to four times the upfront investment of manual configurations.
- Automatic Cleaners:Programmable brush-and-vacuum systems operate at fixed 1,500–3,000 RPM speeds with integrated solution injection. German transit authorities in Berlin and Munich standardize on these units for overnight maintenance windows where technician staffing is constrained.
- Robotic Cleaners:Autonomous chassis incorporate lidar navigation and computer vision for unsupervised operation. Tokyo Metro and Seoul Metropolitan Subway are trialing nighttime deployment protocols that eliminate cord-tether limitations.
- Manual Cleaners:Hand-guided units with direct operator control suit low-traffic retail installations where capital budgets are restricted.
- Hybrid Cleaners:Convertible architectures switch between autonomous and manual modes for mixed-use facilities in Singapore's integrated transport hubs.
Automatic cleaners absorb the bulk of installed capacity; robotic cleaners are expanding most quickly.
Deployment:
Logistics infrastructure determines which operational model matches facility constraints, with power access and storage density driving selection.
- On-site:Permanent installation at single escalator banks requires dedicated utility hookups. Frankfurt Airport operates dedicated cleaning stations at each terminal cluster.
- Mobile:Battery-electric units with wheeled transport serve distributed retail portfolios. US property management platforms favor this model for multi-site coverage.
- Stationary:Fixed-base systems with centralized chemical recovery suit high-volume transit depots in Osaka and Nagoya.
- Off-site:Contracted service providers transport equipment between facilities, common in French hospital networks with centralized sterile processing departments.
Mobile deployment claims the largest operational footprint; on-site configurations are climbing the fastest as transit authorities internalize maintenance capabilities.
End User:
Regulatory exposure and liability thresholds segment demand by institutional risk tolerance.
- Airports:24-hour operational requirements and ADA slip-resistance mandates drive specification intensity. Amsterdam Schiphol and Dubai International specify CE-marked units with sub-85 dB noise thresholds.
- Hospitals:Infection control protocols and MDR compliance for medical-adjacent equipment elevate procurement scrutiny. Johns Hopkins and Mayo Clinic systems require EPA Safer Choice formulation compatibility.
- Commercial Buildings:Class A office towers in Chicago and Manhattan prioritize aesthetic maintenance with minimal service disruption.
- Shopping Malls:High-traffic retail environments in Mumbai and São Paulo balance cleaning frequency against tenant accessibility.
Airports command the highest specification tier; hospitals are gaining share fastest as healthcare infrastructure expands.
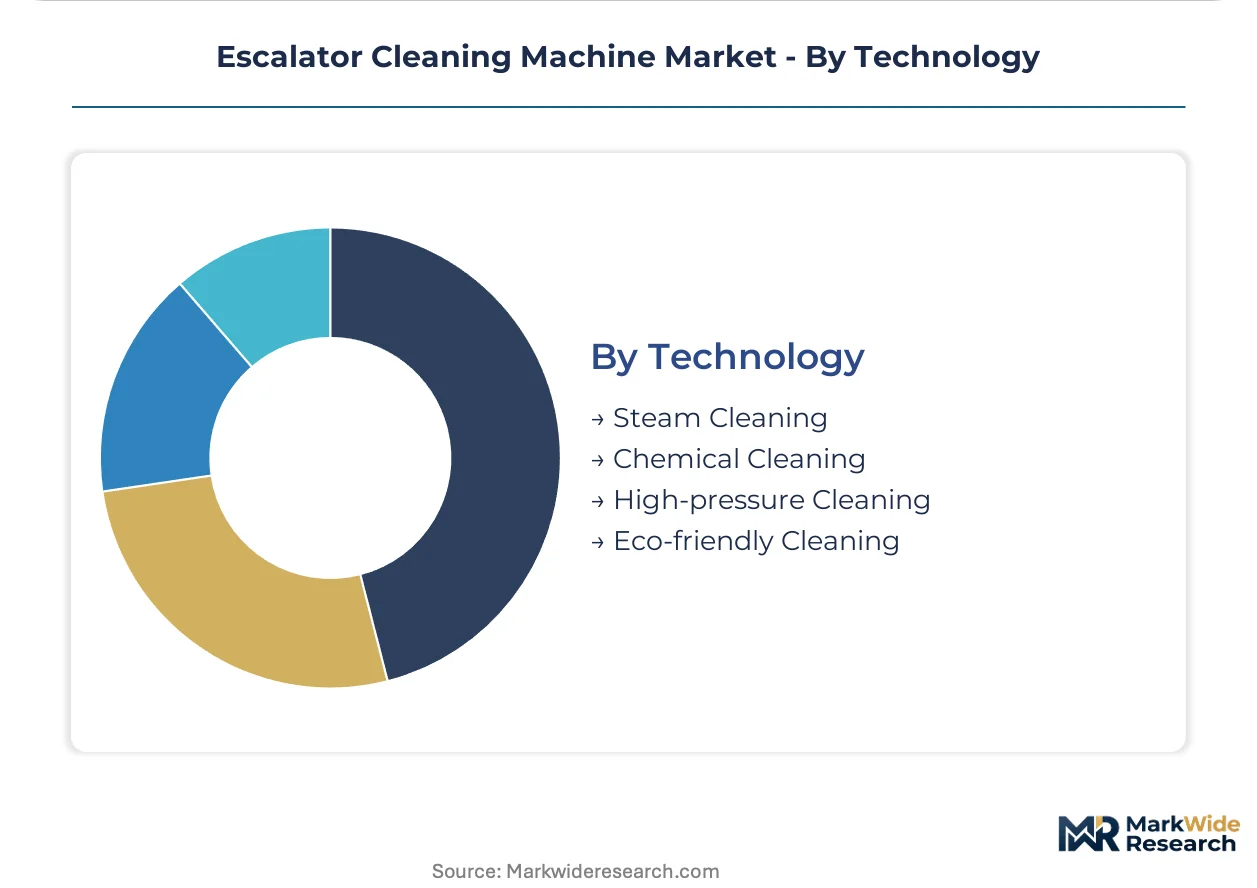
Technology:
Environmental compliance timelines are fragmenting technology adoption by geography.
- Chemical Cleaning:Solvent-based degreasers with hydrofluoric acid derivatives retain installed base dominance where REACH restrictions have not yet enforced reformulation.
- Eco-friendly Cleaning:Enzyme-based and bio-surfactant formulations achieve discharge compliance in Dutch and German jurisdictions with stringent wastewater protocols.
- Steam Cleaning:High-temperature vapor systems eliminate chemical residue concerns in Copenhagen and Stockholm municipal contracts.
- High-pressure Cleaning:Kärcher-derived pressure-wash architectures dominate transit system tenders in Düsseldorf and Hamburg.
Chemical cleaning retains the largest installed base; eco-friendly alternatives show the steepest expansion trajectory as ECHA candidate list restrictions proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brush motor manufacturing clusters in southern China supply the electromechanical core for equipment deployed across transit systems worldwide. Nickel-price volatility in stainless steel markets ripples through chassis fabrication costs for solution tank assemblies. Metropolitan density in East Asian commercial corridors sustains replacement cycles as aging escalator fleets exceed design service intervals.
Germany
Transit authorities in Berlin and Munich expand procurement of automated maintenance equipment for underground rail networks. The EU Machinery Directive mandates emergency-stop integration and noise thresholds below 85 dB for public-space deployment. Engineering clusters in Baden-Württemberg and North Rhine-Westphalia build dedicated escalator-specific production lines separate from generic floor-care manufacturing.
Japan
Tokyo Metro and Osaka Municipal Subway trial nighttime autonomous operation protocols for robotic cleaning chassis. METI standards for industrial equipment safety shape R&D priorities for sensor-integrated platforms. The Kansai and Chubu regions concentrate high-rise commercial density where aging escalator fleets create sustained equipment replacement demand.
United States
OSHA walkway-surface standards and ADA slip-resistance requirements pull through certified cleaning protocols in commercial buildings and hospitals. Property management platforms in Chicago and Manhattan centralize procurement across multi-site Class A office portfolios. The EPA Safer Choice formulation certification unlocks federal procurement preference for hospital and government building contracts.
India
Metro buildouts in Delhi, Mumbai, and Bengaluru create tender opportunities for automated maintenance equipment in new transit infrastructure. BIS certification requirements for imported machinery extend validation timelines for European and East Asian OEMs. The Delhi-NCR and Maharashtra clusters concentrate first-mover positioning as transit authorities internalize escalator maintenance capabilities.
Netherlands
Amsterdam Schiphol Airport specifies CE-marked units with sub-85 dB noise thresholds for 24-hour operational environments. REACH substance restrictions enforced by ECHA drive solvent-based formulation obsolescence and enzyme-based alternative adoption. The Randstad logistics hub supports mobile deployment models for distributed retail and healthcare facility portfolios.
Escalator Cleaning Machine Market Vendor Landscape
Global majors compete with regional champions across technology integration and service reach in the escalator cleaning machine market. The vendor base organizes into three tiers: diversified cleaning equipment conglomerates with pressure-wash heritage, specialized escalator-focused engineering houses, and autonomous-ready chassis developers positioning for robotic retrofit. Consolidation pressure favors players with captive distribution networks and formulation chemistry capabilities. Competitive moves center on modular subsystem interoperability and battery-electric powerpack integration for cord-free operation.
Within the diversified industrial cleaning tier, Kärcher leverages its pressure-wash heritage to anchor high-performance transit system configurations, while Nilfisk Group occupies a position in European airport operator distribution. Tennant Company represents the autonomous-ready chassis archetype with designs accommodating future robotic retrofit. Japanese engineering heritage manifests in Fujitec Co., Ltd., which exemplifies the specialized vertical-transportation-adjacent equipment category. These named entities illustrate how geographic origin and corporate structure correlate with strategic positioning across manual, automatic, and robotic automation levels.
| Leading Market Players |
|---|
| Kärcher |
| NITEC Solutions International |
| Fujitec Co., Ltd. |
| Cleanfix Reinigungssysteme AG |
| Hako GmbH |
| Nilfisk Group |
| Tennant Company |
| Bortek Industries, Inc. |
| Dulevo International S.p.A. |
| Others |
Supply Flow & Price Mechanics
Captive production of brush motor assemblies in southern China anchors supply positioning and pricing power for European OEMs facing REACH compliance costs. This geographic concentration forces tiered equipment sourcing strategies that separate premium autonomous chassis from economy manual configurations.
Pricing Analysis
Service bundling unbundling defines competitive positioning as facility managers separate equipment capital expenditure from consumables supply and technical maintenance contracts. Three-tier pricing structure across premium robotic, standard automatic, and economy manual levels reflects automation density and CE certification grade. Cost compression in the manual tier intensifies because of stainless steel input volatility and nickel-price swings in solution tank fabrication. Transit authorities in Germany and Japan show least price sensitivity due to regulatory mandates, while retail property managers in distributed US portfolios prioritize lowest capital outlay.
Supply Chain Analysis
Electromechanical technician scarcity in Baden-Württemberg and North Rhine-Westphalia constrains brush drive calibration capacity for European manufacturers. Brush motor manufacturing clusters in southern China and precision sensor fabrication in South Korea and Japan form the geographic supply core. Stainless steel sheet and lithium-ion powerpacks constitute critical raw material dependencies. Single-source vulnerability in high-RPM brush assembly sourcing creates structural risk. Distribution runs through specialized industrial cleaning equipment dealers repositioning as certified service integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The escalator cleaning machine market sits in a technology-transition phase as robotic autonomous platforms displace legacy manual configurations. Sensor cost deflation and nighttime operation protocols accelerate this substitution curve.
For Market Incumbents: Extend modular subsystem architectures to defend against pure-play autonomous entrants. Kärcher and Nilfisk Group should deepen backward integration into brush motor production to reduce southern China single-source exposure. CE-MDR dual certification investment creates switching costs for hospital procurement contracts. For New Entrants and Emerging Players: Airport service integrators represent the most penetrable channel partner type for robotic chassis penetration. Target Delhi, Mumbai, and Bengaluru metro buildouts where transit authorities lack legacy vendor relationships. Offer battery-electric mobile deployment as a first-mover wedge against cord-tethered incumbent fleets. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified cleaning equipment conglomerates seeking autonomous capability. Five-to-ten year viability favors specialized escalator-focused engineering houses with formulation chemistry captive supply. Watch ECHA candidate list expansion velocity as inflection indicator for solvent-based formulation obsolescence timing.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Subsystem Development | Frankfurt and Singapore airport pilots validate hot-swap cartridge architectures for 90-minute overnight windows. |
| Enzyme-Based Formulation Transition | REACH restrictions in Dutch and German jurisdictions force hydrofluoric acid derivative replacement. |
| Battery-Electric Powerpack Integration | Lithium-ion convergence enables cord-free operation in legacy infrastructure with limited outlet access. |
| Autonomous Navigation Stack Licensing | Tokyo Metro nighttime deployment protocols mature sensor-integrated platform adoption. |
| CE-MDR Dual Certification Pathway | Johns Hopkins and Mayo Clinic systems require EPA Safer Choice compatibility for hospital tenders. |
Methodological Framework
Multi-period observation of procurement tender awards, regulatory filing timelines, and sensor cost trajectories anchored the trend analysis, supplemented by interviews with facility maintenance directors, transit authority procurement officers, airport operations managers, and industrial equipment distributors. Secondary validation drew from EU Machinery Directive implementation records, ECHA candidate list updates, EPA Safer Choice certification databases, and customs trade data for brush motor and stainless steel imports. Bottom-up equipment shipment tracking and top-down transit infrastructure investment flows were triangulated for market sizing.
Input-output matrices modeled unit deployment across automation level, deployment logistics, end-user regulatory tier, and cleaning technology type throughout the forecast period. CAGRs were derived from segment-level replacement cycle analysis and infrastructure investment elasticity. Forecast inputs incorporated escalator fleet age distributions in East Asian metropolitan clusters and REACH substance restriction phase-in schedules.
Several conditions sit outside the modeled scope, including unannounced metro project cancellations, abrupt nickel price spikes exceeding historical volatility bands, and autonomous navigation regulatory reversals. Forecasts assume continued sensor cost deflation and stable EU-Asia trade lanes. Material deviation in ECHA candidate list expansion velocity or brush motor supply disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Grout Bags Market
Construction Equipment
Construction Power Rental Market
Construction Equipment
Stud Welding Guns Market
Construction Equipment
Extrusion Equipment Market
Construction Equipment
Winch Market
Construction Equipment
Rotary Dryers Market
Construction Equipment
Core Drill Automatic Feeding Machine Market
Construction Equipment
Case Erectors Market
Construction Equipment
Walform Machines Market
Construction Equipment
Hydraulic Press Machine Market
Construction Equipment
Wheeled Excavators Market
Construction Equipment
Concrete Demolition Professional Equipment Market
Construction Equipment
Press Brakes Market
Construction Equipment
Wood Chipping Machinery Market
Construction Equipment
Global Wheel Trenchers Market
Construction Equipment
Latin America Construction Equipment Market