
 Extrusion Equipment Market | 2026-2036
Extrusion Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Extrusion Equipment Market Analysis
Medical-grade and food-contact specification tiers is redrawing competitive boundaries in extrusion equipment. KraussMaffei Group leverages its integrated compounding-to-extrusion technology stack to anchor premium positioning across European pharmaceutical tubing lines. Milacron dominates large-diameter pipe extrusion systems through manufacturing scale and aftermarket parts density in North American infrastructure projects. The Japan Steel Works specializes in superalloy barrel and screw configurations that sustain extended production runs for fluoropolymer processors.
Extrusion equipment comprises machines that force thermoplastic, thermosetting, or metallic feedstock through a shaped die under controlled temperature and pressure, typically operating at barrel temperatures between 150°C and 400°C depending on polymer viscosity and shear requirements. Twin-screw extruders capture the fastest-expanding product type segment as compounders adopt co-rotating intermeshing designs for reactive extrusion and filler incorporation at higher throughput rates. Blown film extrusion technology leads value generation within the technology dimension, driven by multilayer barrier film demand for flexible food packaging where processors achieve precise gauge control across seven-layer configurations. Thermoplastics remain the dominant material category, though rubber extrusion lines serving automotive sealing profiles retain resilient margin pools due to specialized cold-feed screw geometries and longer replacement cycles.
FDA validation protocols for medical tubing and EU MDR traceability requirements are elevating equipment documentation and IQ/OQ/PQ commissioning standards, effectively filtering out lower-tier suppliers from regulated end-use segments. China's SAMR enforcement of GB standards for plastic pipe pressure ratings and Germany's KBA material certification for automotive fuel lines are tightening conformance obligations across export-oriented machinery builders. Stakeholders must monitor how dual carbon goals in China and EU Green Deal embodied-carbon tracking reshape capital equipment procurement criteria for energy efficiency and recyclability compatibility.
Market Dynamics
Automotive lightweighting mandates across Germany and China are compressing replacement cycles for single-screw systems while elevating specification thresholds for twin-screw configurations in filled-polymer compounding operations.
Growth Catalysts
- FDA validation protocols:Medical tubing processors in the United States face elevated IQ/OQ/PQ commissioning standards that filter lower-tier suppliers from regulated segments, concentrating procurement among validated equipment platforms.
- China's dual carbon goals:Energy efficiency benchmarks under MEE enforcement are accelerating capital replacement toward servo-driven extrusion lines with regenerative power recovery in the Yangtze River Delta manufacturing cluster.
- Fluoropolymer processing expansion:Semiconductor fabrication growth is driving demand for superalloy barrel configurations capable of sustaining extended production runs at elevated temperatures.
Market Restraints
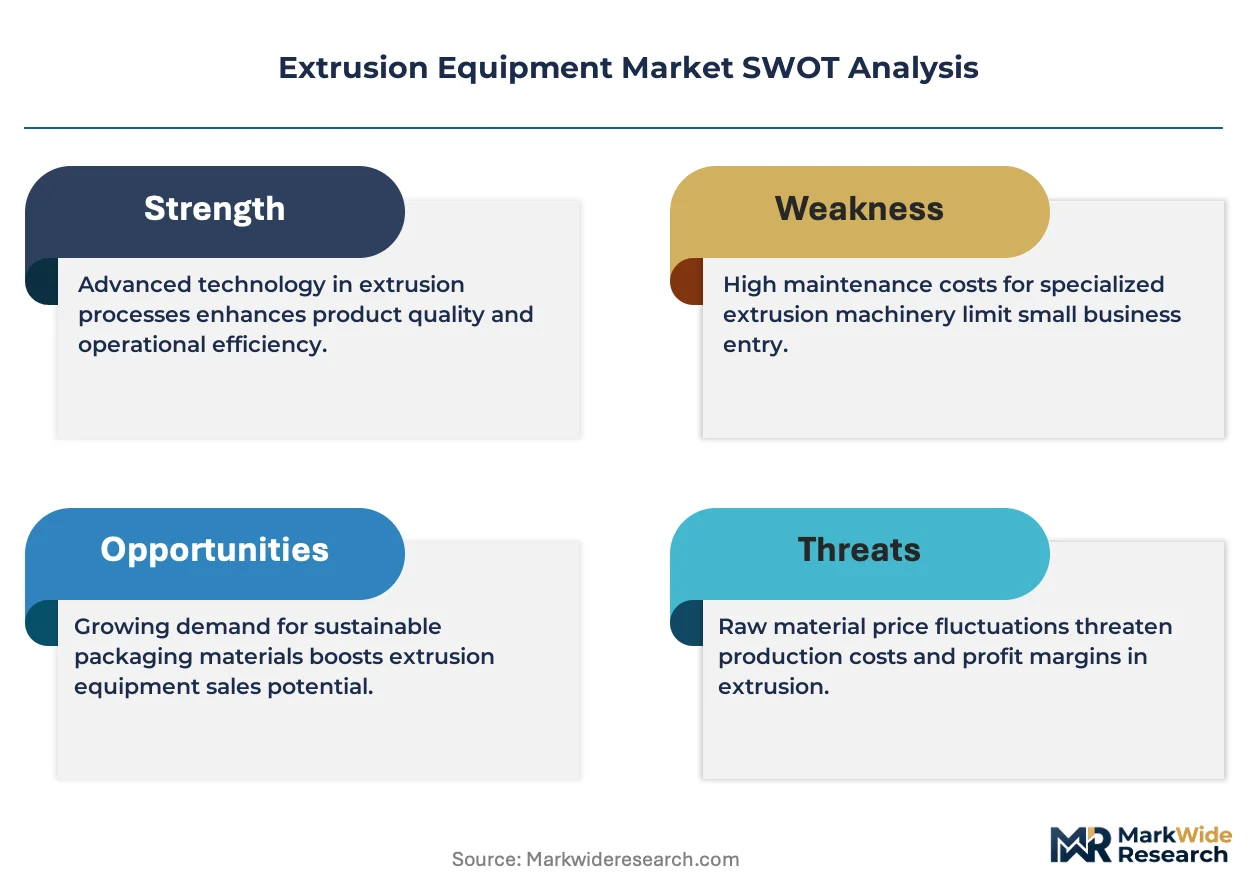
- Superalloy input volatility:Nickel and cobalt price fluctuations directly compress margin pools for specialized screw and barrel manufacturers serving high-temperature polymer segments.
- German KBA certification friction:Automotive fuel line material approvals create 18-24 month validation timelines that delay equipment commissioning and extend payback periods for Tier-2 suppliers.
- Substitution by additive manufacturing:Direct metal laser sintering is capturing low-volume, high-complexity profiles previously served by specialty extrusion in aerospace ducting applications.
Strategic Opportunities
- India's PLI scheme for specialty chemicals:Domestic compounding capacity expansion under production-linked incentives creates virgin demand territory for co-rotating twin-screw systems.
- EU Green Deal embodied-carbon tracking:Machinery procurement criteria are incorporating lifecycle carbon accounting, favoring equipment platforms with energy recovery and recyclability compatibility documentation.
- Reactive extrusion convergence:Integration of in-situ polymerization with direct shaping operations is opening process-intensification contracts for pharmaceutical and biodegradable resin processors.
Industry Challenges
- Control systems integration complexity:Legacy analog extrusion lines require complete electrical and software architecture replacement to achieve Industry 4.0 connectivity standards demanded by automotive OEMs.
- Multilayer die certification timelines:Seven-layer blown film equipment for barrier packaging faces extended validation periods under EU MDR traceability requirements and FSSAI food-contact migration testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Extrusion Equipment Market |
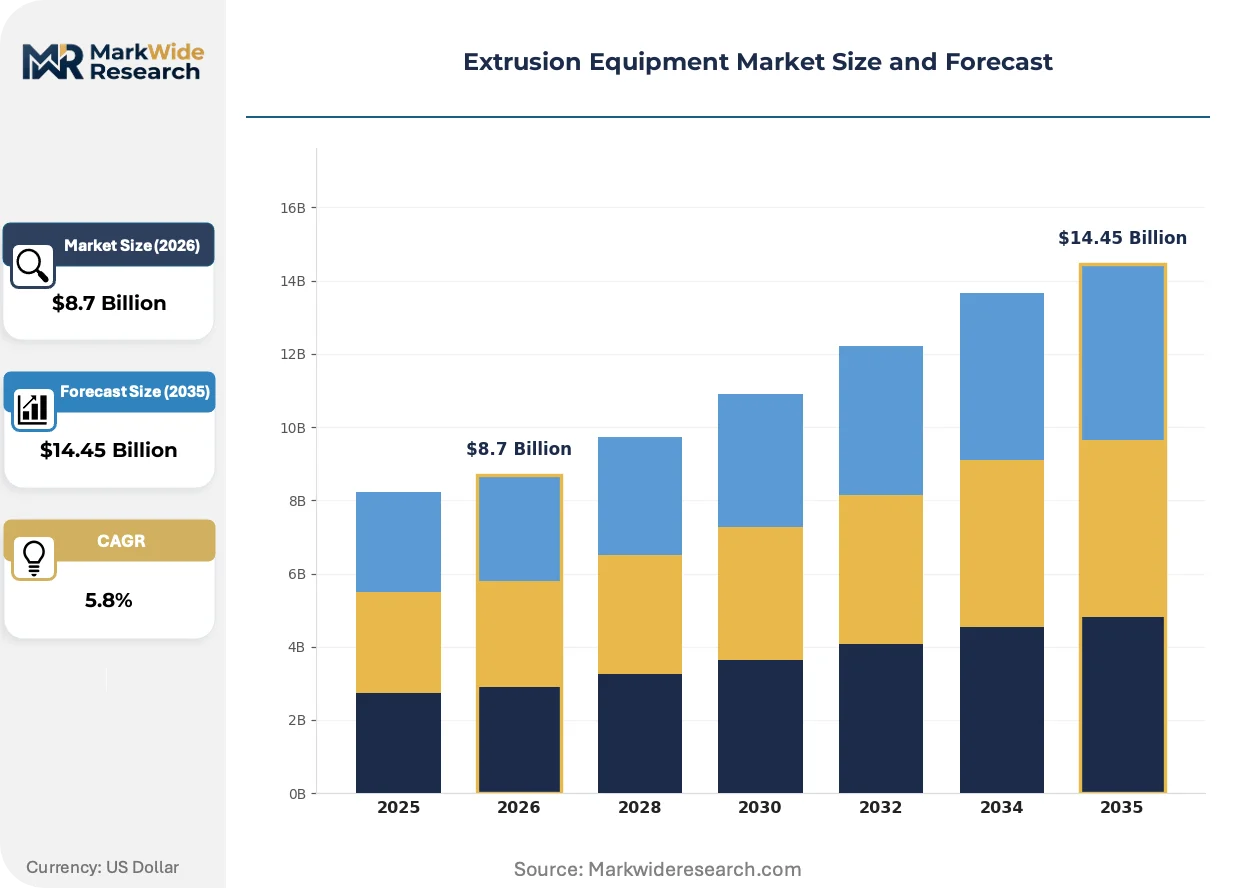
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Screw Extruders, Twin-Screw Extruders, Compact Extruders, Mini Extruders Technology: Conventional Extrusion, Reactive Extrusion, Blown Film Extrusion, Sheet Extrusion Material: Thermoplastics, Thermosetting Plastics, Rubber, Metals Application: Pipes, Films, Sheets, Automotive Components |
| Companies Covered | Milacron, Leistritz, Coperion, ENTEK, Cowell Extrusion Machinery, KraussMaffei Group, Battenfeld-Cincinnati, Graham Engineering, The Japan Steel Works, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Extrusion Equipment Market Emerging Trajectories
Digital twin deployment and inline rheological sensing are compressing process development cycles while elevating real-time quality assurance capabilities across medical and automotive specification tiers.
All-electric servo motor architectures are displacing hydraulic drive systems in precision medical tubing applications where processors demand sub-micron concentricity control at reduced energy intensity. German pharmaceutical tubing lines have adopted these platforms at accelerated replacement cycles. The shift is compressing aftermarket revenue pools for hydraulic component suppliers while elevating software and controls expertise as competitive differentiators.
EU MDR traceability mandates are forcing equipment builders to embed serialization and batch-record automation into medical-grade extrusion platforms. The regulation requires continuous data logging across temperature, pressure, and dimensional parameters with audit-ready documentation. European pharmaceutical tubing processors are prioritizing equipment with pre-validated software architectures to compress regulatory submission timelines.
Buyers are unbundling after-sales service contracts from initial equipment procurement, negotiating standalone performance-based maintenance agreements with third-party specialists. This fragmentation is disrupting traditional OEM service revenue models in North American infrastructure pipe segments. Large-diameter processors in Texas and Alberta are driving this shift, demanding uptime guarantees separate from capital equipment financing.
Extrusion Equipment Market Segmentation
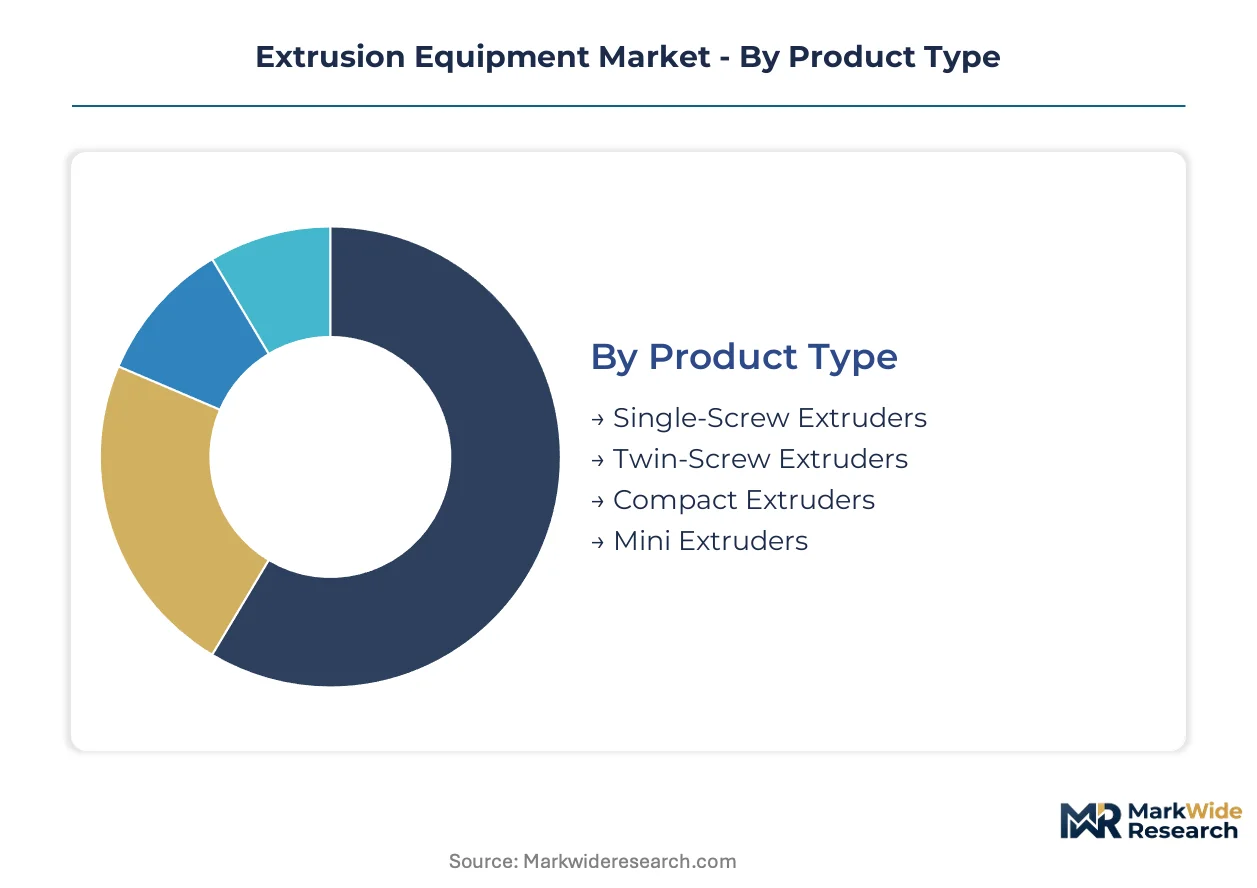
Extrusion equipment segmentation reveals how substitution pressures from additive manufacturing and alternative forming technologies concentrate risk in specific product configurations. Equipment buyers prioritize platforms that withstand process substitution while capturing specification premiums in regulated end-uses.
Product Type:
Twin-screw configurations face the strongest substitution pressure from continuous compounder alternatives, while single-screw systems confront obsolescence from direct additive manufacturing in low-complexity profiles.
- Single-Screw Extruders:These machines employ one rotating screw within a heated barrel to convey, melt, and pressurize polymer feedstock for continuous profile output. Demand concentrates in China's Yangtze River Delta for commodity pipe production where cost-per-ton efficiency outweighs flexibility requirements. German automotive lightweighting programs are compressing replacement cycles as processors retire aging hydraulic systems.
- Twin-Screw Extruders:Co-rotating intermeshing designs enable reactive extrusion, devolatilization, and high-filler incorporation at elevated throughput rates. Orders from China's SAMR-regulated pipe sector and EU pharmaceutical tubing lines are accelerating as compounders adopt these platforms for validated production. The FDA's IQ/OQ/PQ commissioning standards filter procurement toward established suppliers with documentation capabilities.
- Compact Extruders:Reduced-footprint systems serve laboratory-scale development and niche medical tubing trials where batch flexibility trumps throughput.
- Mini Extruders:Benchtop configurations support university research and polymer characterization workflows with minimal material consumption.
Single-screw extruders anchor the volume base while twin-screw extruders gain share at the steepest rate.
Technology:
Cost tier differentiation separates commodity processors from specification-tier buyers, with premium technology layers commanding validation documentation premiums.
- Blown Film Extrusion:Multilayer die systems achieve precise gauge control across seven-layer barrier configurations for flexible food packaging. FSSAI food-contact migration testing and EU MDR traceability requirements are extending validation timelines for equipment serving Indian and European pharmaceutical packaging lines.
- Reactive Extrusion:In-situ polymerization combined with direct shaping enables process intensification for biodegradable resin and pharmaceutical active incorporation. European compounders under EU Green Deal embodied-carbon tracking are adopting these platforms to compress energy intensity per kilogram of output.
- Conventional Extrusion:Standard single-stage melting and shaping dominates commodity pipe and profile production where capital efficiency determines procurement.
- Sheet Extrusion:Flat die and roll-stack configurations serve thermoforming feedstock for food trays and automotive interior panels.
Conventional extrusion holds the installed base while reactive extrusion climbs the fastest on sustainability-linked capital allocation.
Material:
Application-specific margin pools concentrate in material categories where processing difficulty creates equipment specification barriers.
- Thermoplastics:Meltable and reprocessable polymers dominate equipment utilization across packaging, construction, and consumer goods. China's dual carbon goals under MEE enforcement are accelerating servo-driven line adoption in the Yangtze River Delta for polyethylene and polypropylene pipe production.
- Rubber:Cold-feed screw geometries and specialized temperature profiles serve automotive sealing profiles and industrial hose applications. Germany's KBA material certification for fuel line components sustains resilient margin pools through extended replacement cycles and aftermarket parts density.
- Thermosetting Plastics:Crosslinking during processing requires specialized barrel cooling and screw designs for electrical insulation and composite matrices.
- Metals:Powder extrusion and continuous casting configurations serve aerospace and medical implant feedstock where superalloy barrel specifications sustain premium positioning.
Thermoplastics generate the volume foundation while rubber processing equipment sustains the most durable margin structure.
Application:
Customer type fragmentation separates infrastructure project buyers with uptime guarantees from specification-tier pharmaceutical and automotive processors.
- Films:Multilayer barrier and breathable film production commands the most sophisticated die and air-ring technology for food packaging and medical sterile barriers. EU MDR traceability mandates and FDA validation protocols are elevating equipment documentation requirements for European and North American pharmaceutical tubing processors.
- Pipes:Large-diameter pressure pipe systems for water infrastructure and oilfield gathering lines prioritize manufacturing scale and aftermarket parts availability. China's SAMR enforcement of GB standards for plastic pipe pressure ratings is tightening conformance obligations for export-oriented machinery builders.
- Sheets:Thermoforming feedstock and construction panels utilize calendering and roll-stack configurations with thickness uniformity specifications.
- Automotive Components:Underhood tubing, sealing systems, and interior trim demand material certifications from Germany's KBA and China's MIIT for fuel line and EV battery enclosure applications.
Pipes represent the largest installed base while films expand most quickly on flexible packaging specification upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment builders concentrate manufacturing capacity near polymer processing clusters to compress logistics costs and accelerate commissioning support. Germany's automotive lightweighting mandates and China's dual carbon enforcement are reshaping regional procurement patterns. The United States, Germany, China, Japan, and India represent the five dominant national markets for extrusion equipment investment.
United States
FDA validation protocols for medical tubing and large-diameter pipe infrastructure projects drive equipment procurement. The IRA's domestic content incentives are accelerating capital replacement in Texas and Alberta-focused oilfield gathering line systems. Houston anchors aftermarket parts density for North American infrastructure processors demanding uptime guarantees.
Germany
Automotive lightweighting programs and pharmaceutical tubing specification tiers elevate twin-screw system orders. KBA material certification for fuel line components creates 18-24 month validation timelines that filter procurement toward validated equipment platforms. Bavaria's machinery builders leverage integrated compounding-to-extrusion technology stacks for premium positioning.
China
Dual carbon goals under MEE enforcement accelerate servo-driven line adoption for energy efficiency benchmarks. SAMR's GB standards enforcement for plastic pipe pressure ratings tightens conformance obligations for export-oriented machinery builders. The Yangtze River Delta manufacturing cluster concentrates demand for polyethylene and polypropylene pipe production systems.
Japan
Semiconductor fabrication growth drives demand for superalloy barrel configurations in fluoropolymer processing. METI's industrial efficiency guidelines favor equipment platforms with regenerative power recovery and lifecycle carbon documentation. Nagoya-area precision manufacturers specialize in extended production run configurations for high-temperature polymer segments.
India
The PLI scheme for specialty chemicals creates virgin demand territory for co-rotating twin-screw systems in domestic compounding capacity expansion. FSSAI food-contact migration testing extends validation timelines for seven-layer blown film equipment serving pharmaceutical packaging lines. Maharashtra and Gujarat industrial corridors attract machinery investment from export-oriented compounders.
Extrusion Equipment Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. German and Japanese specialists anchor premium positioning through superalloy configurations and validated medical-grade platforms, while North American and Chinese fabricators compete on manufacturing scale and aftermarket density. Three archetypes dominate: integrated technology stack providers, scale-driven infrastructure specialists, and superalloy configuration experts. Consolidation pressure operates through M&A among mid-cap European compounder-equipment integrators, while geographic expansion drives Chinese builders into India's PLI-subsidized specialty chemicals sector.
Among German-integrated technology providers, KraussMaffei Group and Battenfeld-Cincinnati occupy positions exemplifying compounding-to-extrusion platform dominance. Milacron represents the scale-driven North American archetype for large-diameter pipe systems. The Japan Steel Works anchors the superalloy configuration specialist tier. These three names illustrate how geographic origin and corporate structure align with distinct competitive positioning vectors across medical, automotive, and infrastructure end-uses.
| Leading Market Players |
|---|
| Milacron |
| Leistritz |
| Coperion |
| ENTEK |
| Cowell Extrusion Machinery |
| KraussMaffei Group |
| Battenfeld-Cincinnati |
| Graham Engineering |
| The Japan Steel Works |
| Others |
Supply Flow & Price Mechanics
Capacity utilization rates above eighty percent at German and Japanese superalloy barrel manufacturers compress supply availability and elevate price floors for medical-grade extrusion platforms. Buyers face extended lead times for validated equipment configurations as these scale economies concentrate procurement leverage among integrated technology providers.
Pricing Analysis
FDA IQ/OQ/PQ validation protocols and EU MDR traceability mandates dictate the pricing tier structure across medical and pharmaceutical tubing equipment. Three-tier pricing structure across premium validated platforms, standard industrial configurations, and economy commodity systems separates procurement pools. Price differentiation hinges on certification documentation depth and aftermarket service bundling. Cost compression in standard pipe extrusion intensifies as Chinese manufacturers expand servo-driven line capacity. Infrastructure project buyers in North American oilfield gathering segments exhibit highest price sensitivity, while European pharmaceutical processors prioritize validation assurance over capital expenditure minimization.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for superalloy screw and barrel components sourced from Japanese specialty steel producers. Manufacturing concentration centers on Germany, China, and Japan for complete extrusion systems, with superalloy feedstock dependence on Japanese and Austrian metallurgical suppliers. Supply chain risk from nickel and cobalt price volatility in superalloy inputs compresses margin pools for high-temperature polymer equipment specialists. Distribution runs through OEM-direct channels for large infrastructure projects and specialized distributor networks for aftermarket parts and service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among multinational compounders and pharmaceutical processors with centralized procurement functions, compressing vendor margins and elevating specification requirements. This fragmentation among equipment purchasers intensifies competitive pressure on mid-tier suppliers lacking validated platform portfolios.
For Market Incumbents: Secure superalloy barrel supply agreements through backward integration into specialty metallurgy or long-term offtake contracts with Japanese steel producers. Defend against additive manufacturing substitution in aerospace ducting by accelerating reactive extrusion capability development for biodegradable resin processors. Certification investment in pre-validated FDA and EU MDR software architectures compresses regulatory submission timelines for pharmaceutical tubing buyers.
For New Entrants and Emerging Players: Anchor in India's PLI-subsidized specialty chemicals corridor, where domestic compounding capacity expansion creates virgin demand for co-rotating twin-screw systems without entrenched incumbent relationships. Target laboratory-scale and compact extruder segments serving university research and medical tubing trial applications, where batch flexibility requirements and lower capital thresholds reduce competitive barriers. Partner with European pharmaceutical packaging processors seeking seven-layer blown film equipment with embedded EU MDR traceability automation.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors superalloy configuration specialists with semiconductor fabrication exposure and integrated compounding-to-extrusion platform providers serving automotive lightweighting programs. Long-term viability over the next decade rests on equipment architectures compatible with dual carbon enforcement and embodied-carbon tracking requirements. Acquisition targets should demonstrate energy recovery system integration and recyclability compatibility documentation. Monitor MEE enforcement intensity in China's Yangtze River Delta as inflection indicator for servo-driven line replacement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Superalloy Supply | Captive supply of nickel-cobalt barrel components insulates margin pools from raw material volatility. |
| Pre-Validated Software Architecture Development | FDA IQ/OQ/PQ-ready platforms compress procurement cycles for European pharmaceutical tubing processors. |
| Servo-Drive System Manufacturing Scale-Up | Energy efficiency benchmarks under China's MEE enforcement accelerate capital replacement demand. |
| Reactive Extrusion Capability Investment | In-situ polymerization integration captures process-intensification contracts from biodegradable resin compounders. |
| Aftermarket Service Contract Unbundling | Performance-based maintenance agreements separate revenue streams from capital equipment financing in North American pipe segments. |
Methodological Framework
A standing panel of plant engineers at compounder facilities, procurement leads at automotive Tier 1 suppliers, aftermarket service heads at infrastructure pipe processors, and regulatory affairs specialists at pharmaceutical tubing manufacturers provided ongoing calibration. Primary interviews combined with secondary validation from SEC 10-K filings of listed machinery builders, customs and trade data on extrusion equipment imports, SAMR GB standards documentation, and EU MDR implementation guidance. Bottom-up equipment shipment tracking and top-down polymer processing capacity analysis enabled triangulation across independent data streams.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product type configuration, technology tier, material processing category, and end-use application intensity. CAGRs were derived from equipment replacement cycle analysis and capital expenditure elasticity to regulatory enforcement. Industry-specific forecast inputs incorporated KBA certification timeline data for automotive fuel line applications and MEE energy efficiency benchmark trajectories.
Material uncertainties — nickel and cobalt price volatility, KBA certification timeline extensions, additive manufacturing substitution rates in aerospace profiles — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory enforcement continuity and polymer processing capacity expansion plans. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Portable Chamfering Machines Market
Construction Equipment
Global Skid Steer Attachments Market
Construction Equipment
Construction Wearable Technology Market
Construction Equipment
Global Dragline Excavator Market
Construction Equipment
Global Construction Dumper Market
Construction Equipment
Jib Crane Market
Construction Equipment
Scaffold Technology Market
Construction Equipment
PU Casting Machine Market
Construction Equipment
Metal Machinery Market
Construction Equipment
Asia-Pacific Mobile Light Tower Market
Construction Equipment
Global Light Towers Market
Construction Equipment
Piling Machine Market
Construction Equipment
Global Tablet Press Machine Market
Construction Equipment
Trash Rack Cleaning Machine Market
Construction Equipment
Compressed Earth Block Machine Market
Construction Equipment
Compact Power Equipment Rental Market