
 Europe Enterprise Resource Planning (ERP) Software Market | 2026-2036
Europe Enterprise Resource Planning (ERP) Software Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Enterprise Resource Planning (ERP) Software Market Analytics
Market Context
The capability gap between hyperscale platform investments and mid-tier R&D budgets is reorganizing competitive tiers across European ERP. SAP leverages its decades-long installed base in industrial Germany to sustain renewal cycles among automotive and chemical conglomerates. Odoo competes on modular openness, anchoring its growth among Benelux SMEs that prioritize configurable deployment over monolithic suites.
Technical Definition and Segment Structure
Enterprise Resource Planning software integrates core business processes—finance, procurement, manufacturing, supply chain, human resources, and customer relations—through a unified database architecture with real-time transaction processing and role-based access controls. Cloud-based deployment leads European new-buy decisions as legacy on-premise estates face end-of-life pressure, while hybrid architectures capture regulated financial services firms requiring data sovereignty. Among end users, manufacturing generates the deepest module customization demand, whereas healthcare represents the fastest-growing vertical as NHS trusts and French hospital networks modernize procurement and patient billing workflows.
Regulatory Frame and Outlook
CSRD mandates from the European Commission and GDPR data-localization requirements shape product roadmaps, forcing vendors to architect EU-sovereign cloud instances and granular consent-audit trails. The EU AI Act adds algorithmic transparency obligations for ERP modules incorporating predictive analytics. Stakeholders must monitor how forthcoming sector-specific digital operational resilience standards redraw certification requirements for supply-chain and financial modules.
Market Dynamics
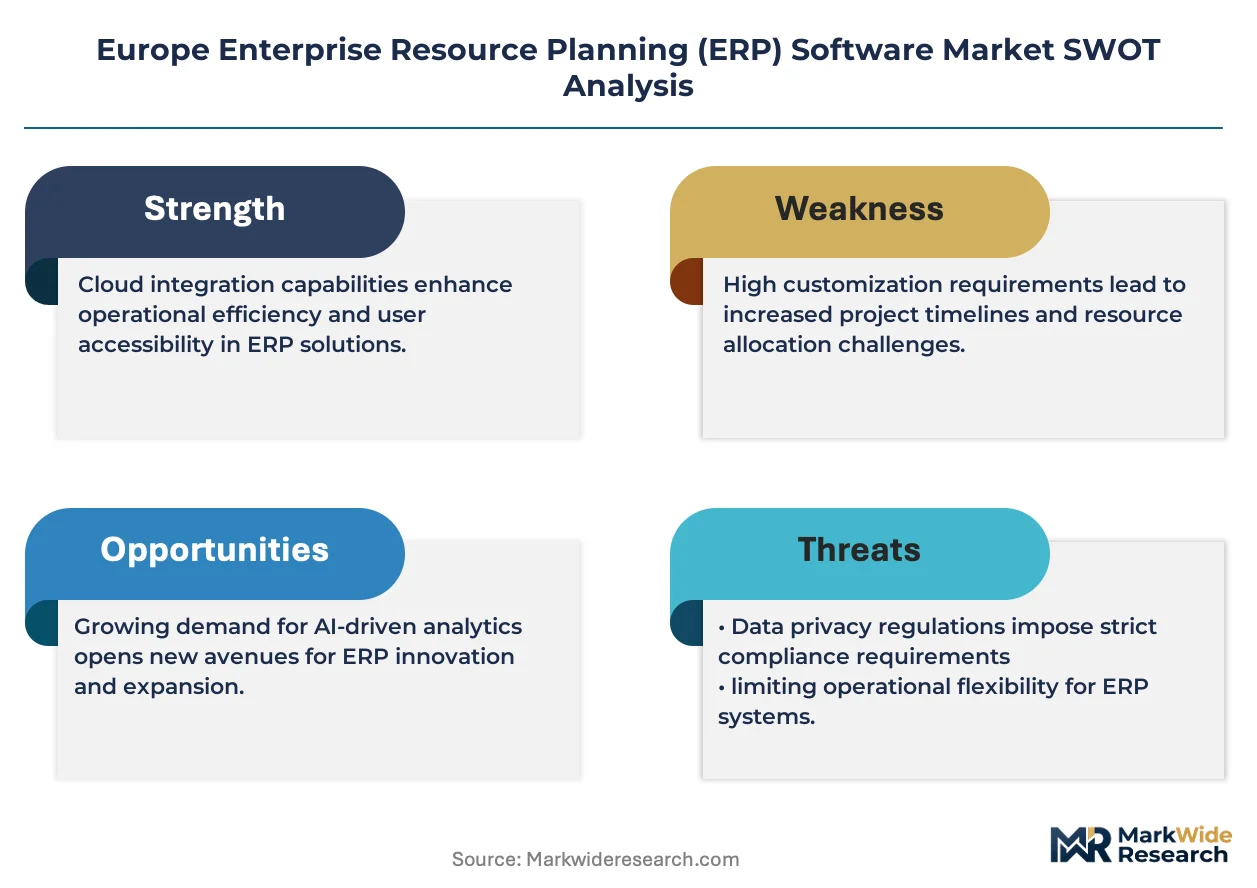
The CSRD disclosure regime and EU AI Act are forcing vendors to re-architect core modules for algorithmic transparency and sustainability reporting, compressing development cycles while elevating compliance costs.
Growth Catalysts
- CSRD Mandates:The European Commission's Corporate Sustainability Reporting Directive compels mid-cap enterprises to adopt ERP suites with embedded ESG data collection and audit-ready disclosure templates.
- Automotive Cloud Migration:German automotive OEMs are accelerating replacement of on-premise SAP estates with sovereign cloud instances to support real-time supply-chain visibility and battery traceability requirements.
- Healthcare Digitization:French hospital networks and NHS trusts are modernizing procurement and patient billing workflows, creating module customization demand for resource planning vendors.
Market Restraints
- Data Sovereignty Costs:GDPR localization requirements and EU AI Act algorithmic audit obligations force vendors to maintain separate cloud instances per member state, fragmenting infrastructure economics.
- Mid-Tier R&D Gap:Hyperscale platform investments by SAP and Oracle are widening the capability chasm, squeezing independent software vendors in Benelux and Nordic markets.
- Legacy Integration Friction:Decades of on-premise customization in German industrial conglomerates creates technical debt that slows cloud migration timelines and inflates professional services costs.
Strategic Opportunities
- Benelux SME Modularization:Belgian and Dutch mid-market manufacturers show appetite for composable ERP architectures that permit selective finance or supply-chain module deployment without full-suite commitment.
- AI-Act Compliance Services:Vendors can monetize algorithmic transparency tooling and bias-audit documentation as premium add-ons for predictive analytics modules in financial services.
- Healthcare Vertical Expansion:Netherlands-based hospital procurement networks represent underpenetrated demand for specialized inventory and vendor credentialing modules.
Industry Challenges
- Specialized Talent Scarcity:Vendors face acute shortages of consultants fluent in both legacy ABAP customization and modern API-first cloud architectures, particularly in Eastern European delivery centers.
- Certification Timeline Compression:EU AI Act conformity assessment procedures for high-risk predictive modules are creating bottlenecks that delay product releases and strain quality assurance teams.
- Multi-Instance Integration Complexity:Enterprises operating hybrid estates must reconcile real-time data flows between on-premise manufacturing execution systems and cloud-based financial cores, demanding costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Enterprise Resource Planning (ERP) Software Market |
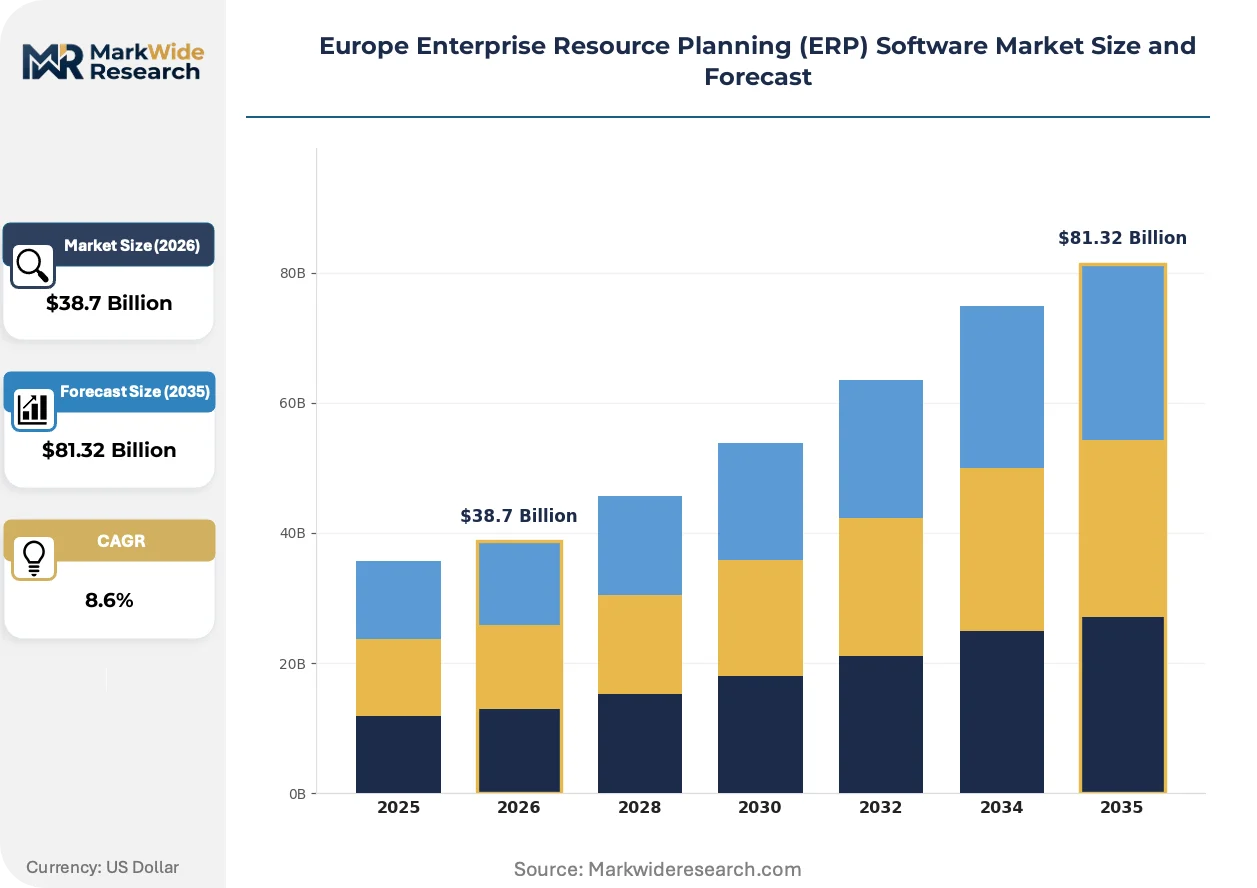
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $81.32 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Private Cloud End User: Manufacturing, Retail, Healthcare, Financial Services Solution: Accounting, Supply Chain Management, Human Resource Management, Customer Relationship Management Size: SMEs, Large Enterprises, Startups, Corporates |
| Companies Covered | Amadeus IT Group, Celonis, SAP, Infor, Nemetschek, Sage, Wolters Kluwer, Odoo, Dassault Systèmes, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Enterprise Resource Planning (ERP) Software Market Evolving Landscape
Agentic AI and embedded sustainability tooling are compressing the traditional ERP value chain, shifting competitive advantage toward vendors who can automate compliance workflows rather than merely record transactions.
API-first microservices architectures are supplanting monolithic suite deployments among European manufacturers seeking granular module substitution. German automotive suppliers are piloting composable finance and procurement components from niche vendors alongside legacy cores. This fragmentation is eroding single-vendor lock-in and elevating integration middleware to strategic importance.
The EU AI Act's risk-based classification system is mandating algorithmic impact assessments for ERP modules incorporating predictive workforce scheduling or credit scoring. Vendors must now embed explainability layers and human-in-the-loop overrides directly into workflow engines. Financial services firms in France and the Netherlands are prioritizing compliance-ready procurement to preempt regulatory enforcement.
Subscription-based consumption models are displacing perpetual license structures across mid-market buyers in Belgium and the Netherlands. CFOs favor operational expenditure treatment and embedded upgrade cycles over capital-intensive on-premise deployments. This preference shift favors cloud-native vendors with consumption-metering infrastructure over traditional incumbents with annuity maintenance revenue streams.
Europe Enterprise Resource Planning (ERP) Software Market Segmentation
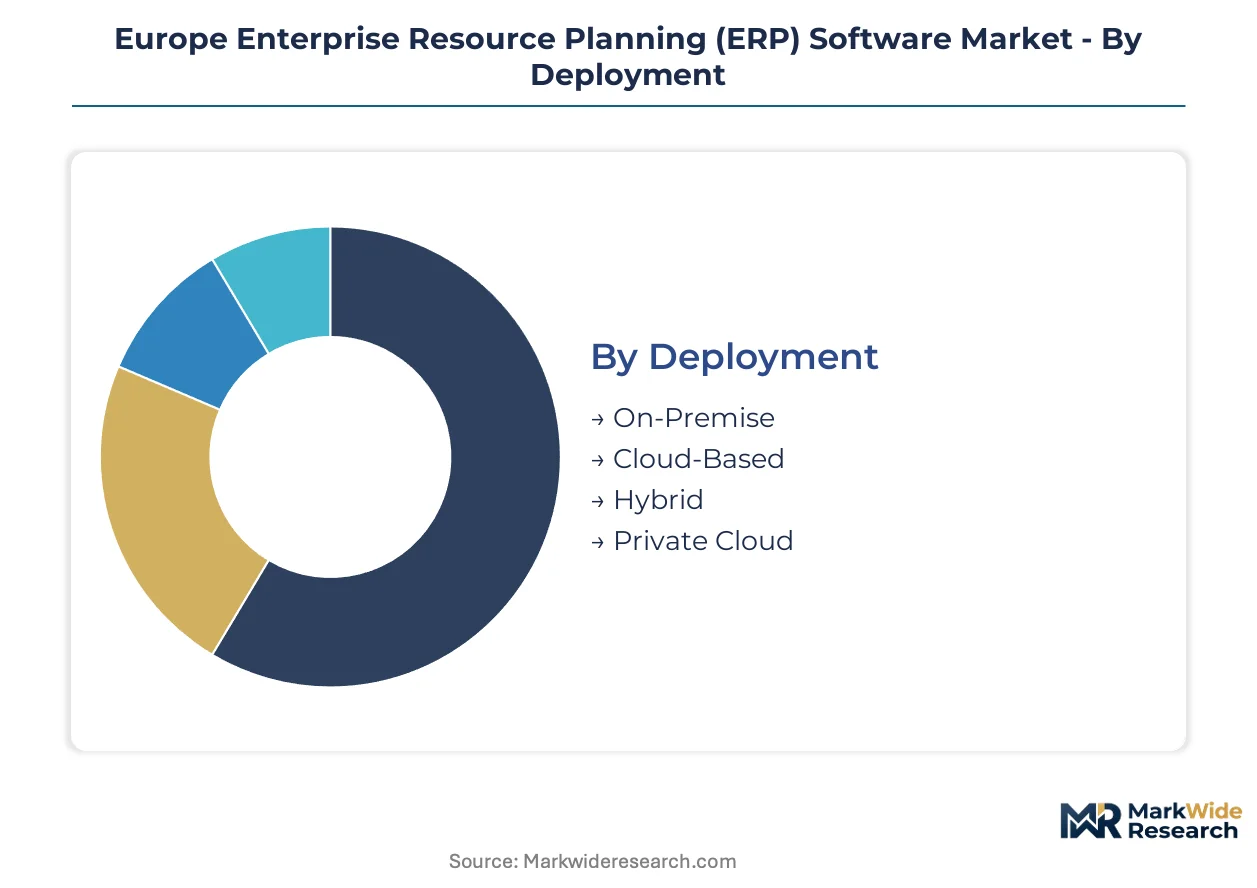
Deployment architecture determines vendor selection criteria and professional services intensity across European ERP procurement. End-user verticals impose distinct compliance and integration requirements that reshape module prioritization.
Deployment:
Channel mix varies sharply by deployment model, with cloud-based solutions flowing through hyperscaler marketplaces and hybrid architectures demanding systems integrator partnerships.
- On-Premise:Legacy infrastructure maintained within enterprise data centers with full hardware ownership and direct license management. German automotive conglomerates retain on-premise estates for manufacturing execution systems requiring sub-10-millisecond latency to shop-floor equipment.
- Cloud-Based:Multi-tenant SaaS delivery with automatic patch management and elastic compute scaling. French hospital networks and NHS trusts are migrating patient billing modules to sovereign cloud instances to satisfy GDPR localization mandates.
- Hybrid:Split architecture retaining sensitive financial data on-premise while extending supply-chain modules to cloud edge nodes. Regulated financial services firms in the Netherlands deploy hybrid stacks to reconcile real-time trading data with audit-trail sovereignty requirements.
- Private Cloud:Single-tenant dedicated infrastructure combining cloud operational models with physical isolation. Belgian defense contractors and German chemical processors specify private cloud for REACH-regulated substance tracking databases.
On-premise deployments dominate installed base. Cloud-based solutions are where expansion concentrates.
End User:
Application-specific requirements reshape implementation timelines and module customization depth across vertical segments.
- Manufacturing:Production planning, shop-floor data collection, and quality management integration with SCADA systems. German automotive suppliers generate the deepest module customization demand for battery traceability and circular economy compliance.
- Healthcare:Patient billing, procurement, and vendor credentialing with HIPAA-equivalent data handling. French hospital networks represent the steepest expansion trajectory as regional health authorities consolidate procurement platforms.
- Retail:Omnichannel inventory synchronization and loyalty program integration across franchise networks. Benelux fashion distributors prioritize real-time stock visibility across flagship and outlet channels.
- Financial Services:Risk-weighted asset calculation, anti-money laundering monitoring, and MiFID II transaction reporting. Dutch pension funds and French insurers drive demand for CSRD-ready sustainability disclosure modules.
Manufacturing commands the largest professional services attach rate. Healthcare is gaining share fastest among new-buy decisions.
Solution:
Customer type determines solution bundling preferences, with corporates demanding full-suite integration and SMEs selecting point modules.
- Accounting:General ledger, accounts payable automation, and tax engine localization for EU member-state variations. German Mittelstand firms prioritize accounting modules with embedded GoBD audit trail compliance.
- Supply Chain Management:Demand forecasting, procurement orchestration, and logistics visibility with supplier collaboration portals. Automotive OEMs in France and Germany specify SCM suites with battery passport traceability for EU Battery Regulation alignment.
- Human Resource Management:Payroll localization, skills matrices, and workforce scheduling with Works Council consultation workflows. Dutch and Belgian employers favor HRM modules supporting part-time and flexible contract prevalence.
- Customer Relationship Management:Opportunity management, service ticketing, and marketing automation with consent-audit trails. Financial services firms in the Netherlands embed CRM within MiFID II client communication archiving requirements.
Accounting modules dominate SME procurement. Supply chain management is where enterprise expansion concentrates.
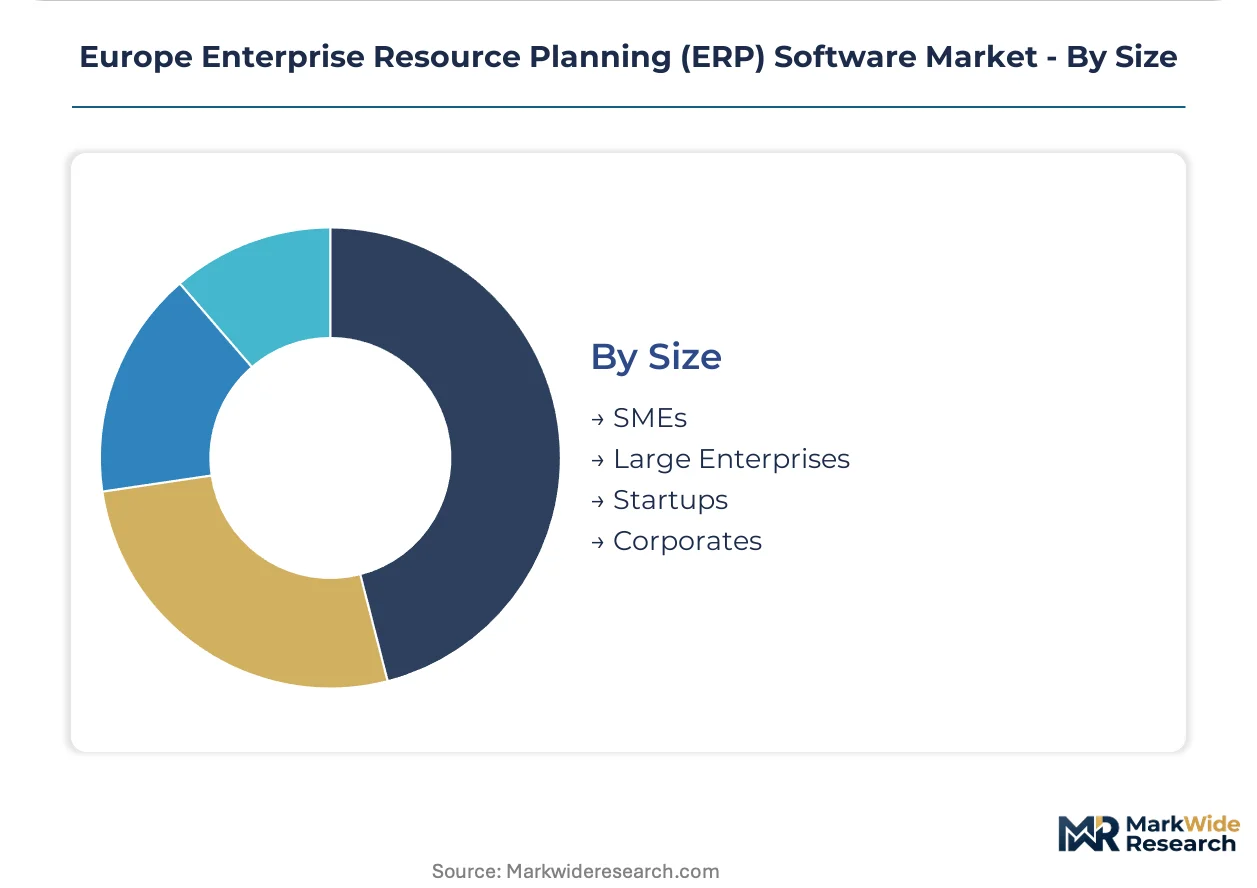
Size:
Volume concentration and margin profiles diverge across customer scale tiers, with large enterprises driving license value and SMEs expanding seat count.
- SMEs:Mid-market enterprises with 50-500 employees seeking rapid deployment without dedicated IT infrastructure. Belgian and Dutch manufacturers favor subscription pricing and pre-configured industry templates over customization.
- Large Enterprises:Complex organizations with multi-entity consolidation requirements and dedicated ERP centers of excellence. German chemical conglomerates sustain the highest per-customer professional services revenue through decade-long transformation programs.
- Startups:Venture-backed growth companies prioritizing API-first architectures and consumption-based scaling. Netherlands-based health tech startups select modular finance stacks that integrate with clinical trial management platforms.
- Corporates:Multi-national groups with shared service centers and standardized process templates across operating companies. French luxury goods houses deploy corporate ERP templates to harmonize subsidiary reporting for CSRD consolidation.
Large enterprises dominate annual contract value. SMEs represent the steepest seat-count expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial conglomerates command premium pricing for specialized manufacturing modules, while Benelux mid-market buyers extract volume discounts through modular procurement. This asymmetry reshapes vendor investment priorities across the continent.
Germany
Automotive OEMs and chemical processors drive demand for sovereign cloud instances with sub-10-millisecond latency to shop-floor equipment. The KBA enforces strict data localization for connected vehicle systems, compelling ERP vendors to maintain dedicated German cloud regions. Stuttgart and Munich anchor the densest concentration of SAP customization expertise, where battery traceability modules for EU Battery Regulation compliance command the highest professional services premiums.
France
French hospital networks and luxury goods houses generate contrasting procurement patterns for patient billing automation and CSRD consolidation templates. ANSM and CNIL jointly oversee health data handling requirements, creating dual compliance burdens for vendors serving the healthcare vertical. The Île-de-France region concentrates demand for financial services modules with embedded MiFID II transaction archiving, while Provence-Alpes-Côte d'Azur hosts specialized aerospace supply-chain implementations.
Netherlands
Dutch pension funds and insurers prioritize CSRD-ready sustainability disclosure modules with real-time carbon accounting integration. The Dutch Central Bank (DNB) mandates granular audit trails for risk-weighted asset calculations, shaping product roadmaps for financial services ERP suites. The Randstad corridor dominates procurement volume, where subscription-based consumption models have displaced perpetual licenses among mid-market buyers seeking operational expenditure treatment.
United Kingdom
NHS trusts modernizing procurement and patient billing workflows represent the steepest healthcare vertical expansion trajectory outside France. The UK Information Commissioner's Office enforces GDPR-equivalent data localization through post-Brexit adequacy decisions, forcing vendors to maintain separate British cloud instances. London's financial services cluster drives demand for anti-money laundering monitoring modules, while Midlands manufacturing bases seek hybrid architectures reconciling legacy on-premise estates with cloud edge nodes.
Belgium
Belgian defense contractors and pharmaceutical distributors specify private cloud deployments for REACH-regulated substance tracking and military procurement confidentiality. The Federal Agency for Medicines and Health Products (FAMHP) imposes serialization requirements that ripple through supply-chain module specifications. Flanders-based mid-market manufacturers favor composable ERP architectures permitting selective finance or procurement module deployment without full-suite commitment, compressing implementation timelines and professional services intensity.
Europe Enterprise Resource Planning (ERP) Software Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure across European ERP procurement. The market consolidates around three strategic positions: hyperscale platform vendors with decades-long installed bases, modular open-source specialists competing on configurability, and vertical-focused niche players serving regulated industries. Dominant competitive moves include M&A activity targeting AI-act compliance tooling and strategic partnerships with hyperscaler marketplaces to accelerate cloud migration services.
Within the hyperscale tier, SAP and Oracle anchor the premium segment through renewal cycles among German automotive and chemical conglomerates. Odoo exemplifies the modular openness archetype, occupying a position among Benelux SMEs that prioritize configurable deployment over monolithic suites. Sage sits within the mid-market accounting specialization tier, representing the subscription-based consumption preference shift among British and Dutch CFOs seeking operational expenditure treatment.
| Leading Market Players |
|---|
| Amadeus IT Group |
| Celonis |
| SAP |
| Infor |
| Nemetschek |
| Sage |
| Wolters Kluwer |
| Odoo |
| Dassault Systèmes |
| Others |
Value Network & Pricing Analysis
Ninety-day implementation timelines for mid-market ERP deployments compress vendor cash conversion cycles and concentrate pricing power among systems integrators with certified delivery capacity in Germany and the Netherlands. This lead-time discipline rewards vendors maintaining bench strength across ABAP and API-first skill sets, while penalizing boutique consultancies unable to staff multi-phase transformations.
Pricing Analysis
The customization-premium spread separates standard SaaS subscription tiers from configured-to-order implementations requiring legacy migration and regulatory module development. Subscription-based consumption models dominate mid-market procurement in Belgium and the Netherlands, while German automotive conglomerates absorb project-based pricing for sovereign cloud instances with embedded EU AI Act compliance tooling. Price differentiation hinges on certification level—GDPR-aligned data residency and CSRD audit-trail modules command substantial premiums—and vertical integration depth among implementation partners. Cost compression in the mid-tier SaaS segment intensifies as Odoo and Sage compete on seat-count economics, squeezing independent vendors unable to match hyperscaler infrastructure scale. CFOs at Dutch SMEs exhibit the highest price sensitivity, favoring operational expenditure treatment over capital-intensive on-premise commitments.
Supply Chain Analysis
Just-in-time delivery preferences dominate ERP procurement among Belgian and Dutch manufacturers seeking rapid module deployment without dedicated IT infrastructure buildout. Software supply chains draw from Ireland for EU-sovereign cloud hosting infrastructure, Germany for SAP customization expertise, and India for remote implementation delivery. Critical dependencies include hyperscaler compute capacity, certified consultant labor pools, and API middleware libraries. Single-source vulnerability concentrates in SAP's ABAP skill ecosystem, where decades of proprietary stack investment create captive supplier dynamics. Distribution runs through hyperscaler marketplaces for cloud-native solutions and systems integrator partnerships for hybrid architectures requiring on-premise integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive advantage toward vendors controlling interoperability standards and embedded compliance automation, as the EU AI Act and CSRD mandates elevate ecosystem orchestration above standalone functionality.
For Market Incumbents: Consolidate renewal cycles among German automotive and chemical conglomerates through sovereign cloud migration programs that embed battery traceability and circular economy compliance modules. Deepen vertical integration into AI-act conformity assessment tooling to preempt regulatory bottlenecks that delay product releases. Defend against modular open-source erosion in Benelux by pre-configuring industry templates that compress implementation timelines without sacrificing customization depth. For New Entrants and Emerging Players: Anchor in Netherlands-based hospital procurement networks, where NHS trust modernization and French hospital digitization create underpenetrated demand for specialized inventory and vendor credentialing modules. Target Belgian defense contractors and pharmaceutical distributors requiring private cloud deployments for REACH-regulated substance tracking. Lead with API-first microservices architectures that permit selective finance or supply-chain module deployment without full-suite commitment, matching Flanders-based manufacturer preferences for composable procurement. For Investors and Strategic Acquirers: Carve-out targets emerge from legacy systems integrators with dense ABAP customization expertise in Stuttgart and Munich, where battery traceability module development commands the highest professional services premiums. Long-term viability favors vendors with consumption-metering infrastructure and algorithmic transparency tooling that monetizes EU AI Act compliance as premium add-ons. Watch for inflection when AI-act conformity assessment bottlenecks trigger acquisition premiums for vendors with pre-certified predictive analytics modules.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architectures enable selective module substitution, eroding single-vendor lock-in across German automotive suppliers. |
| Strategic Partnership | Hyperscaler marketplace alliances accelerate cloud migration services for NHS trusts modernizing patient billing workflows. |
| Acquisition of Specialist Firm | AI-act compliance tooling targets address regulatory bottlenecks delaying predictive module releases in financial services. |
| Product Launch | Embedded sustainability tooling automates CSRD disclosure workflows, shifting competitive advantage beyond transaction recording. |
| Geographic Expansion | Benelux SME modularization captures subscription-based consumption preferences displacing perpetual licenses among Dutch CFOs. |
Research Methodology
Operator-level perspectives from ERP implementation directors, IT procurement officers at German automotive OEMs, cloud platform engineers, and systems integrator delivery leads anchored the qualitative base. Primary interviews combined with secondary validation from SEC filings of listed software vendors, hyperscaler capex disclosures, EU regulatory impact assessments, and hospital procurement database records. Bottom-up triangulation across deployment model adoption rates and top-down reconciliation against aggregate digital transformation budget flows established segment-level estimates.
Sensitivity analysis tested forecast robustness across alternative regulatory enforcement timelines and cloud migration acceleration scenarios. The analytical framework modeled deployment architecture, organization size, vertical industry, integration complexity, and regional adoption pattern across the analysis window. CAGRs derived from segment-level seat-count projections and average revenue per user trajectories, incorporating EU AI Act compliance cost pass-through assumptions and CSRD mandate implementation schedules as industry-specific inputs.
Material uncertainties—regulatory timeline slippage, hyperscaler infrastructure capacity constraints, and legacy skill pool attrition—sit outside the modeled envelope. Forecasts reflect assumptions about enforcement consistency and vendor certification velocity that could shift materially. Revision becomes warranted when AI-act conformity assessment backlogs exceed six-month clearance thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Storyboarding Software Market
Software & Services
Audit Management Software Market
Software & Services
Supplier Relationship Management Software Market
Software & Services
Quality and Lifecycle Management Software Market
Software & Services
Global PPC Software Market
Software & Services
Global Accreditation Management Software Market
Software & Services
Asia-Pacific IT Services Market
Software & Services
Software Release Management Tools Market
Software & Services
Computational Medicine and Drug Discovery Software Market
Software & Services
Global Legal Case Management Software Market
Software & Services
Global Disclosure Management Software Market
Software & Services
Application Platform As a Service Market
Software & Services
Applicant Tracking System (ATS) Market
Software & Services
Global Directory Software Market
Software & Services
Asia-Pacific Printing Software Market
Software & Services
Debt Collection Software Market