
 Asia-Pacific IT Services Market | 2026-2036
Asia-Pacific IT Services Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific IT Services Market Outlook
Enterprise procurement channels for IT services across the Asia-Pacific region is reconfiguring as multinational clients consolidate vendor relationships under outcome-based frameworks. Tata Consultancy Services Ltd. anchors extensive delivery networks across India and Southeast Asia with scale advantages in managed services. Infosys Ltd. differentiates through specialized cloud migration and AI consulting capabilities. Amazon Web Services, Inc. competes aggressively on public cloud infrastructure breadth, extending its data center footprint into Singapore, Japan, and Australia.
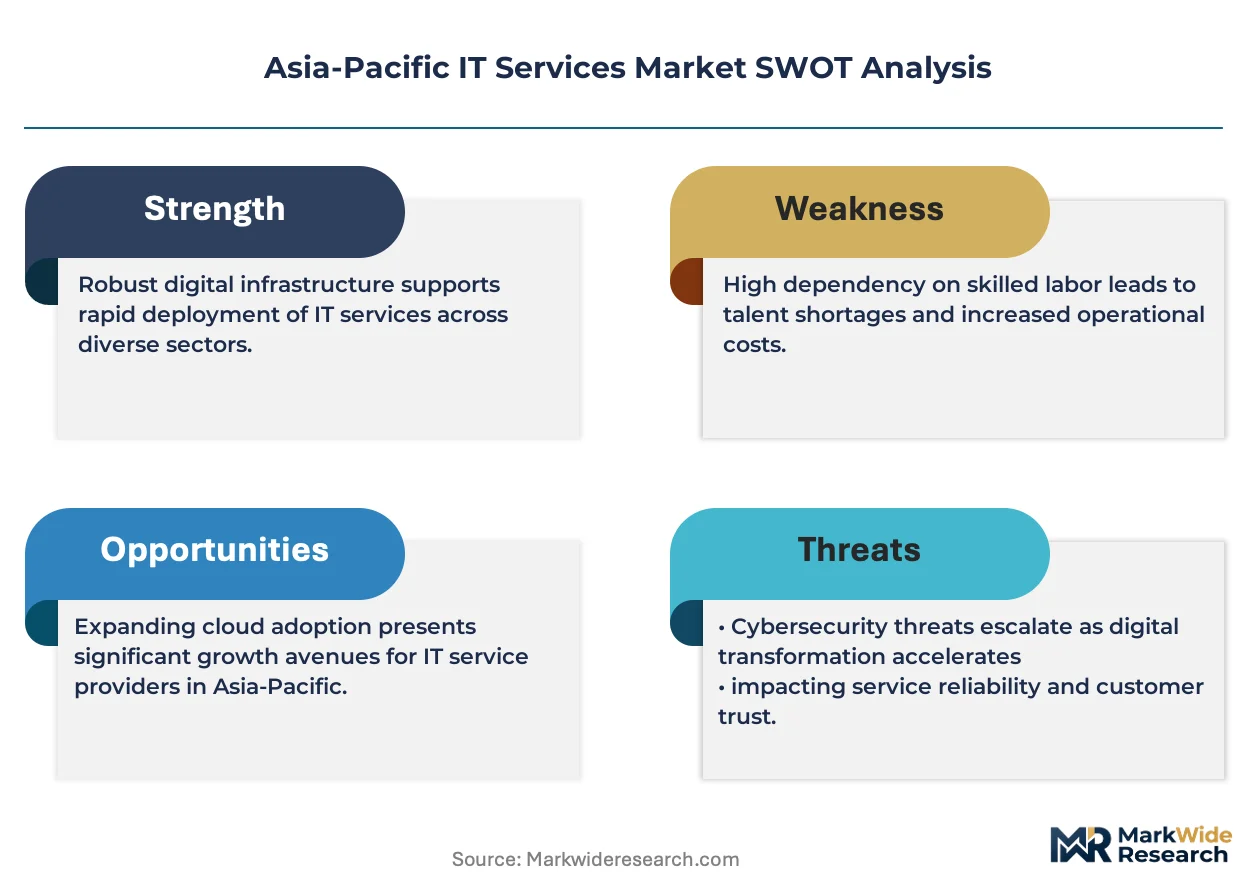
Asia-Pacific IT services encompass the design, development, integration, and management of software applications, infrastructure platforms, and digital business processes delivered through on-premises, cloud-native, or hybrid architectures with service-level agreements governing uptime, security compliance, and performance metrics. These services enable enterprises to optimize operational technology expenditure while accessing specialized capabilities in cybersecurity, data analytics, and enterprise resource planning. Cloud Services within the Service Type dimension leads current revenue contribution as enterprises accelerate workload migration, while Cybersecurity represents the fastest-growing margin pool amid escalating threat environments and regulatory mandates. The Deployment Model dimension shows Hybrid Cloud capturing disproportionate growth as regulated industries in finance and healthcare balance data sovereignty requirements with elasticity demands.
India's TRAI data localization guidelines, Japan's METI cybersecurity framework for critical infrastructure, and Singapore's MAS technology risk management requirements collectively elevate compliance complexity for cross-border service delivery. These regulatory layers shape vendor qualification criteria, data architecture decisions, and contract structuring across the region. Stakeholders must monitor evolving multi-jurisdiction compliance obligations as a primary determinant of competitive positioning and service portfolio design.
Market Dynamics
Hybrid cloud migration mandates from financial regulators across Southeast Asia are compressing traditional infrastructure refresh cycles while elevating compliance complexity for cross-border data flows. Enterprise buyers now prioritize vendors with demonstrated multi-jurisdiction certification portfolios over pure cost optimization.
Growth Catalysts
- India's PLI Scheme for IT Hardware:Manufacturing incentives attract component suppliers to Tamil Nadu and Karnataka, reducing import dependency for server and networking equipment used in domestic data centers.
- Japan's METI Cybersecurity Framework:Critical infrastructure operators must upgrade monitoring capabilities, creating sustained demand for managed security services and threat intelligence platforms.
- Banking Digital Transformation:Southeast Asian financial institutions accelerate core banking modernization to compete with neobanks, driving systems integration and API management spending.
Market Restraints
- Specialized Talent Scarcity:Cloud architecture and zero-trust security expertise concentrates in Bengaluru, Hyderabad, and Singapore, inflating compensation costs for tier-2 city delivery centers.
- Data Localization Requirements:India's TRAI guidelines and Vietnam's cybersecurity law fragment cloud infrastructure deployment, forcing redundant capacity investments across national boundaries.
- Legacy System Entrenchment:Japanese and Australian enterprises maintain decades-old mainframe dependencies, constraining cloud-native migration velocity and inflating integration timelines.
Strategic Opportunities
- Philippines BPO Technology Upgrade:Contact center operators seek AI-powered workforce management and real-time analytics, opening greenfield deployment for platform-as-a-service vendors.
- Indonesia's Sovereign Cloud Initiative:Government data classification requirements create demand for in-country hyperscale partnerships and certified managed services providers.
- AI-DevOps Convergence:Automated code generation and predictive incident management tools penetrate mid-market enterprises previously priced out of advanced analytics capabilities.
Industry Challenges
- Multi-Cloud Orchestration Complexity:Enterprises struggle to maintain consistent security postures across AWS, Azure, and Alibaba Cloud environments, requiring specialized platform engineering talent in short supply.
- Certification Timeline Compression:Singapore's MAS technology risk management updates and Australia's APRA CPS 234 revisions force annual control reassessments, consuming vendor compliance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific IT Services Market |
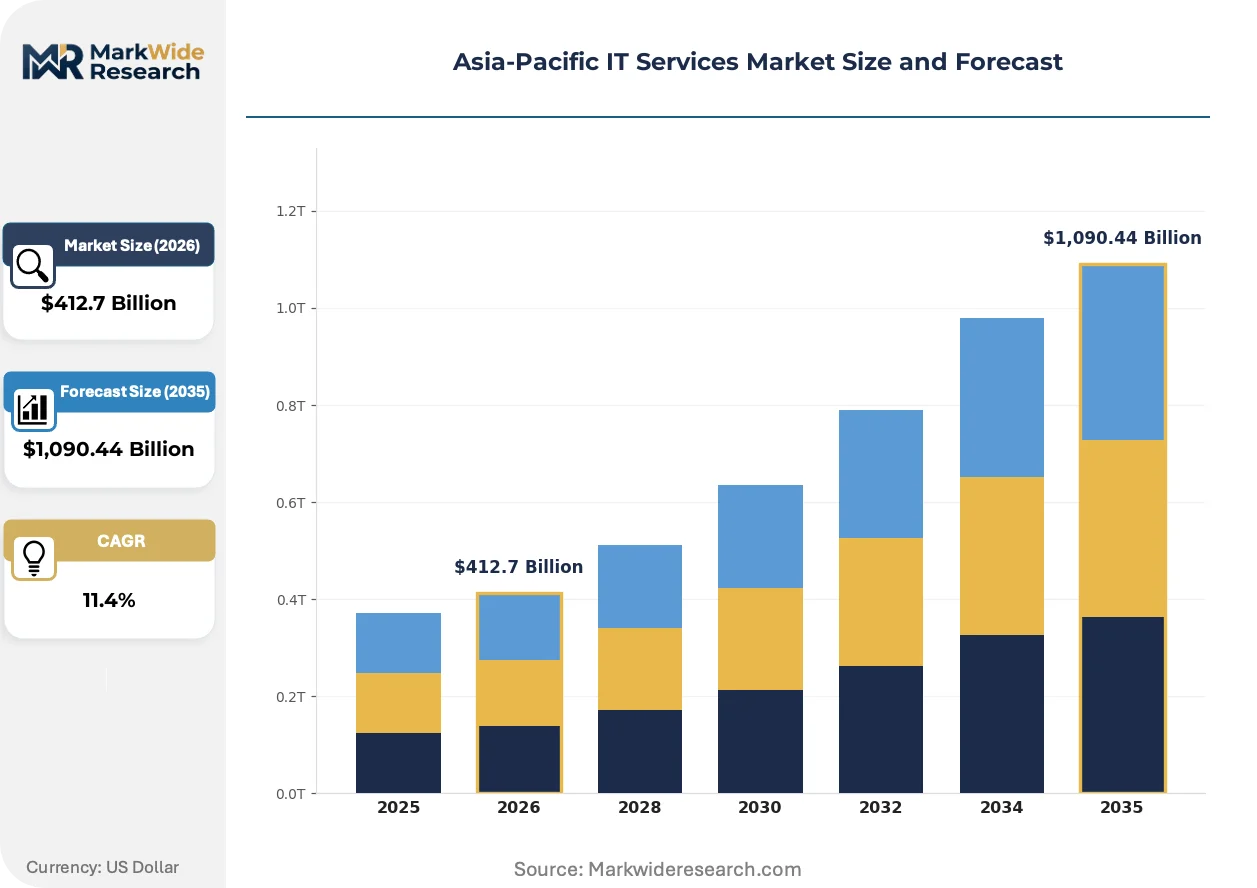
| Market Size in 2026 | $412.7 Billion |
| Market Size in 2035 | $1,090.44 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Managed Services, Cloud Services, Cybersecurity Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Industry Vertical: Healthcare, Retail, Manufacturing, Finance End User: Small Enterprises, Large Corporations, Government, Startups |
| Companies Covered | Accenture plc, Tata Consultancy Services Ltd., Infosys Ltd., Wipro Ltd., HCL Technologies Ltd., IBM Corporation, Microsoft, Amazon Web Services, Inc., Fujitsu Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific IT Services Market Strategic Shifts
Generative AI capabilities are embedding into service delivery workflows, compressing documentation and code generation timelines while forcing vendors to retrain delivery teams for prompt engineering and model fine-tuning disciplines.
Agentic AI systems that autonomously execute multi-step IT operations workflows are rendering obsolete traditional ticket-based support models. Large Australian banks and Singaporean insurers pilot these systems for incident remediation and patch management, collapsing mean-time-to-resolution metrics from hours to minutes and threatening established managed services pricing structures.
Singapore's MAS technology risk management guidelines now mandate independent validation of cloud control frameworks for systemically important financial institutions. Compliance officers must demonstrate continuous monitoring of third-party service providers, driving demand for automated audit trails and real-time control attestation platforms across ASEAN banking hubs.
Enterprise buyers now unbundle implementation services from software licensing, selecting specialized system integrators through competitive tender rather than defaulting to vendor professional services. Australian healthcare providers and Indian manufacturing conglomerates lead this pattern, fragmenting historically concentrated implementation revenue pools and elevating niche consultants with vertical-specific expertise.
Asia-Pacific IT Services Market Segmentation
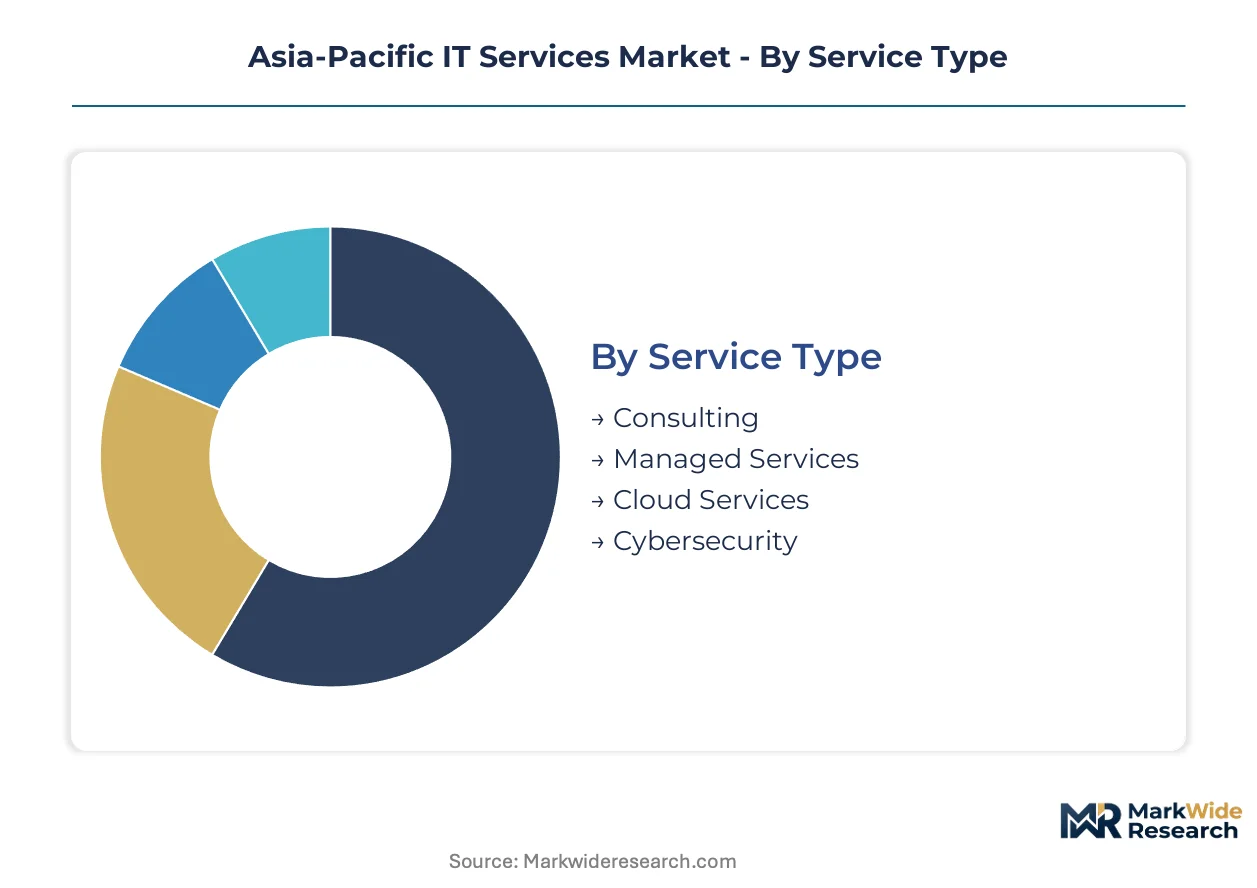
IT services procurement across Asia-Pacific follows distinct patterns shaped by regulatory mandates, data sovereignty requirements, and digital maturity gaps between financial hubs and emerging markets. Segment boundaries blur as hybrid architectures and multi-cloud strategies force vendors to recombine service offerings around customer outcomes rather than traditional technology categories.
Service Type:
Cost tier stratification determines vendor selection and contract structures, with premium advisory services commanding multiples over commoditized infrastructure management.
- Cloud Services:Workload migration, platform engineering, and cloud-native application development delivered across AWS, Azure, and Alibaba Cloud environments. Demand concentrates in Singapore's banking sector and India's technology corridors where RBI and TRAI guidelines mandate in-country data residency for payment systems.
- Cybersecurity:Managed detection and response, zero-trust architecture implementation, and threat intelligence platforms. Japanese financial institutions under METI framework requirements drive sustained spending on critical infrastructure protection and supply chain security validation.
- Managed Services:24/7 infrastructure monitoring, patch management, and service desk operations with defined SLAs.
- Consulting:Digital transformation roadmapping, enterprise architecture design, and change management advisory.
Cloud Services commands the established base. The steepest expansion runs through Cybersecurity.
Deployment Model:
Application sensitivity to data residency rules and latency requirements shapes infrastructure placement decisions across regulated and unregulated workloads.
- Hybrid Cloud:Orchestrated environments spanning on-premises data centers and public cloud regions with unified management planes. Australian healthcare providers and ASEAN banks balance APRA CPS 234 compliance requirements with elasticity for customer-facing applications.
- Public Cloud:Shared infrastructure services with pay-as-you-consume economics and global availability zones. Startups in Bengaluru and Sydney leverage hyperscale capacity for rapid scaling without capital commitment.
- Private Cloud:Dedicated single-tenant infrastructure with customized security controls.
- On-Premises:Legacy data center retention for mainframe-dependent workloads and air-gapped systems.
Hybrid Cloud anchors current deployment preferences. Public Cloud shows the strongest momentum among new workload allocation.
Industry Vertical:
Customer type differentiation separates complex multi-jurisdiction implementations from standardized packaged offerings.
- Finance:Core banking modernization, real-time payment infrastructure, and regulatory reporting platforms. Southeast Asian institutions compete with neobanks through API-first architectures and embedded finance partnerships.
- Healthcare:Electronic health record integration, telemedicine platforms, and clinical analytics. Australian providers unbundle implementation from software licensing to access specialized interoperability expertise.
- Manufacturing:Industrial IoT deployment, predictive maintenance systems, and supply chain visibility platforms.
- Retail:Omnichannel commerce, inventory optimization, and customer data platform implementation.
Finance maintains the largest contract values. Healthcare demonstrates the most rapid adoption acceleration.
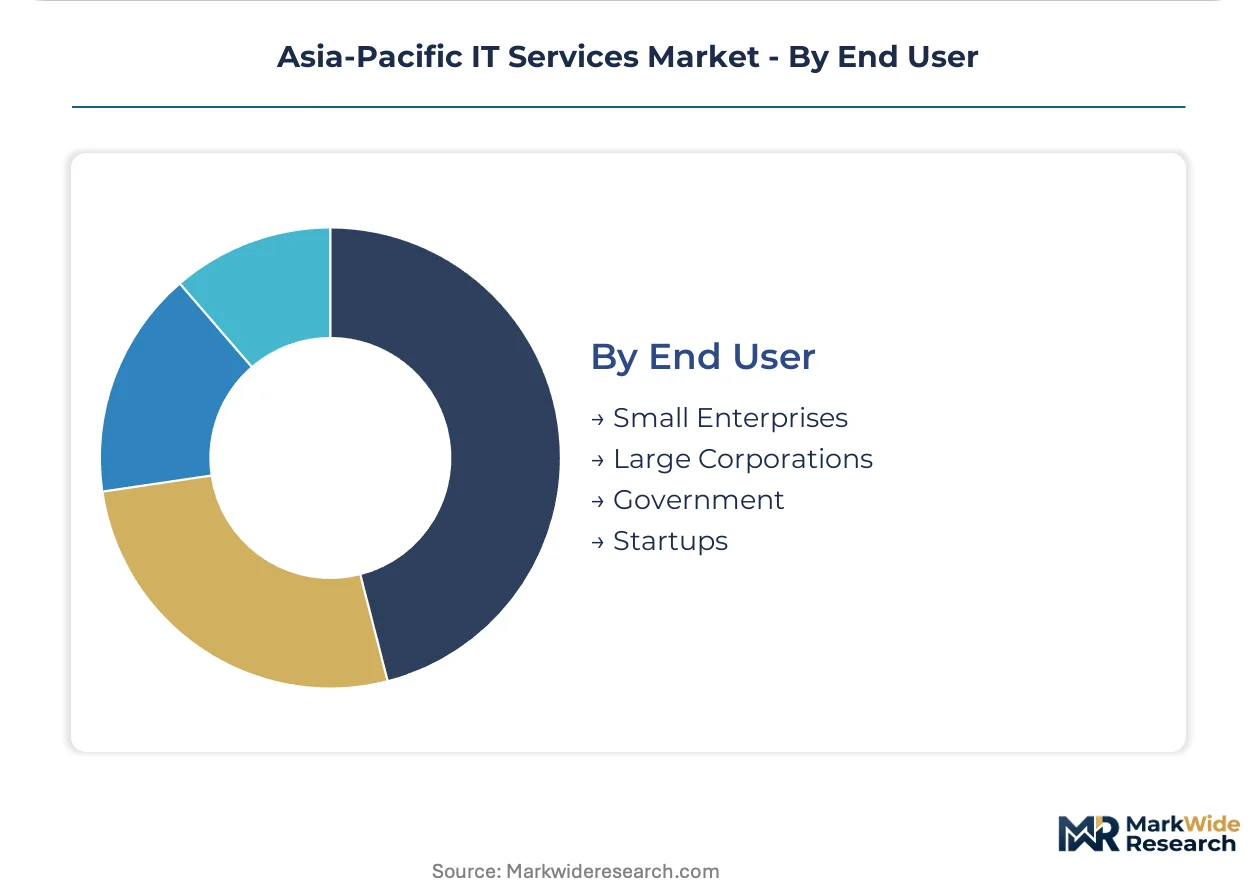
End User:
Volume concentration and procurement sophistication separate enterprise-scale transformation programs from transactional service relationships.
- Large Corporations:Multi-year outcome-based contracts with dedicated delivery teams and customized SLAs. Japanese conglomerates and Indian conglomerates drive complex ERP consolidation and cloud migration programs spanning multiple operating companies.
- Government:Sovereign cloud mandates, citizen service digitization, and critical infrastructure protection. Indonesia's data classification requirements and Singapore's Smart Nation initiatives create certified managed services demand.
- Small Enterprises:Standardized SaaS implementation and managed security packages with limited customization.
- Startups:Cloud-native development support and fractional CTO advisory on lean budgets.
Large Corporations dominate current revenue contribution. Government verticals show the sharpest budget expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's TRAI anchors the regulatory framework shaping data localization mandates across the region, while Japan's METI cybersecurity directives and Singapore's MAS technology risk requirements create layered compliance obligations for cross-border service delivery.
India
Banking and financial services institutions accelerate core banking modernization and cloud migration programs. The RBI and TRAI data localization guidelines mandate in-country data residency for payment systems and telecommunications. Technology corridors around Bengaluru and Hyderabad concentrate specialized talent pools and attract enterprise service delivery commitments from multinational clients.
Japan
Critical infrastructure operators under METI framework requirements drive sustained demand for managed security services and threat intelligence platforms. Decades-old mainframe dependencies in conglomerates constrain cloud-native migration velocity and inflate integration timelines. Tokyo and Osaka anchor delivery networks for enterprise ERP consolidation spanning multiple operating companies.
Singapore
Systemically important financial institutions face MAS technology risk management mandates requiring independent validation of cloud control frameworks. The Smart Nation initiative creates certified managed services demand for government data classification and citizen service digitization. Singapore hosts hyperscale data center expansions from AWS and Microsoft serving ASEAN banking hubs.
Australia
Healthcare providers unbundle implementation services from software licensing to access specialized interoperability expertise. APRA CPS 234 revisions force annual control reassessments, consuming vendor compliance resources. Sydney and Melbourne concentrate cloud-native development support for startups leveraging hyperscale capacity without capital commitment.
Indonesia
Government sovereign cloud initiatives create demand for in-country hyperscale partnerships and certified managed services providers. Data classification requirements fragment cloud infrastructure deployment, forcing redundant capacity investments. Jakarta anchors national delivery networks for platform-as-a-service vendors targeting mid-market enterprises.
Asia-Pacific IT Services Market Competitive Environment
Global systems integrators and India-headquartered IT services specialists split the market between outcome-based transformation contracts and scale-driven managed services delivery. The vendor base concentrates around three strategic archetypes: premium consulting firms with vertical-specific expertise, volume-oriented outsourcing providers with multi-city delivery networks, and hyperscale cloud platforms extending infrastructure services. Competitive positioning depends on multi-jurisdiction certification portfolios and demonstrated compliance automation capabilities. M&A activity targets niche cybersecurity consultancies, while strategic partnerships focus on sovereign cloud certifications.
Among India-based delivery specialists, Tata Consultancy Services Ltd., Infosys Ltd., and Wipro Ltd. exemplify the scale-driven archetype with extensive multi-city networks. These entities occupy positions balancing commoditized infrastructure management against premium advisory capabilities in cloud migration and AI consulting. Their geographic naming and corporate structures signal concentrated delivery footprints across Tamil Nadu, Karnataka, and Telangana, with client relationships spanning Southeast Asian financial institutions and Australian healthcare providers.
| Leading Market Players |
|---|
| Accenture plc |
| Tata Consultancy Services Ltd. |
| Infosys Ltd. |
| Wipro Ltd. |
| HCL Technologies Ltd. |
| IBM Corporation |
| Microsoft |
| Amazon Web Services, Inc. |
| Fujitsu Ltd. |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in zero-trust security talent across Bengaluru and Hyderabad compresses margin structures for mid-tier managed services contracts while forcing buyers toward outcome-based pricing models that transfer delivery risk to vendors.
Pricing Analysis
Rate spreads between Singapore and tier-2 Indian delivery centers now exceed three-to-one for equivalent cloud architecture certifications. Three-tier pricing structure across premium advisory, standard implementation, and economy-managed support segments dominates contract structures. Cost compression in economy tiers intensifies because hyperscale automation tools displace entry-level engineering hours. Small enterprises exhibit highest price sensitivity and gravitate toward standardized SaaS implementation packages with limited customization.
Supply Chain Analysis
Extended payment terms from ASEAN banking clients now stretch to ninety days, forcing mid-sized system integrators toward supply-chain finance facilities anchored by receivables. Delivery capacity concentrates in India, Singapore, and Japan. Specialized talent inputs draw from Bengaluru's cloud engineering pipeline, Hyderabad's cybersecurity academies, and Singapore's compliance certification networks. Single-source vulnerability runs through India's concentrated PLI scheme beneficiaries for server hardware. Distribution runs through direct enterprise sales teams and hyperscale marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as enterprise buyers unbundle implementation from software licensing, creating niches for vertical specialists with regulatory certification depth over generalist volume players.
For Market Incumbents: Insulate core banking relationships by embedding compliance automation tools that satisfy MAS and RBI audit trail mandates. Acquire niche cybersecurity consultancies with METI framework certifications to block emerging entrants from critical infrastructure accounts. Vertical integration into sovereign cloud infrastructure partnerships protects margin pools threatened by hyperscale direct engagement.
For New Entrants and Emerging Players: Establish a beachhead in Indonesia's government sovereign cloud initiative where certification requirements filter out unqualified competitors. Target mid-market Philippine BPO operators seeking AI-powered workforce management platforms with limited incumbent presence. Lead with platform-as-a-service offerings that bypass lengthy enterprise procurement cycles.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across sovereign cloud infrastructure deployments as data localization mandates multiply redundant capacity requirements. Five-to-ten-year viability favors vendors with demonstrated multi-jurisdiction certification portfolios over pure automation plays. Monitor TRAI guideline expansion into additional data categories as the signal for accelerated compliance spending inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | Indonesia's data classification requirements create captive demand for certified managed services providers. |
| AI-DevOps Platform Launch | Automated code generation tools penetrate mid-market enterprises previously priced out of advanced analytics. |
| Cybersecurity Consultancy Acquisition | METI framework compliance requirements sustain premium valuations for critical infrastructure protection specialists. |
| Hyperscale Partnership Expansion | AWS and Microsoft data center footprints in Singapore anchor ASEAN banking hub service delivery. |
| Vertical Talent Pipeline Development | Cloud architecture and zero-trust expertise scarcity in tier-2 cities inflates compensation costs for delivery centers. |
Study Parameters
A standing panel of CTOs, IT procurement officers, platform engineers, and integration specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from SEC filings, hyperscaler capex disclosures, RBI regulatory circulars, and MAS technology risk management guidelines. Bottom-up service line estimates and top-down macroeconomic triangulation anchored volume and value outputs.
Scenario-bracketing around regulatory implementation timelines and cloud adoption velocity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern. CAGRs derived from historical trajectory analysis and elasticity-adjusted demand curves. Forecast inputs incorporated PLI scheme capacity buildout schedules and banking digital transformation budget allocations.
Sensitivities concentrate around TRAI guideline expansion, METI framework enforcement intensity, and hyperscale pricing aggression. Forecasts reflect documented assumptions on regulatory implementation pace and talent pool expansion rates. Macroeconomic contraction, accelerated data localization mandates, or generative AI capability breakthroughs would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Automotive Customization Software Market
Software & Services
Global Reference Check Software Market
Software & Services
Screen and Video Capture Software Market
Software & Services
Mainframe Software Market
Software & Services
Sales Training Software Market
Software & Services
Landing Page Creation Software Market
Software & Services
Auto Software Market
Software & Services
North America Deck Design Software Market
Software & Services
Global Lead Capture Software Market
Software & Services
Blogger Outreach Software Market
Software & Services
Server Virtualization Software Market
Software & Services
Service Dispatch Software Market
Software & Services
Global Time Tracking Software Market
Software & Services
Global AB Testing Software Market
Software & Services
Global Virtualization Software Market
Software & Services
Global Building Information Modeling (BIM) Software Market