
 Global Disclosure Management Software Market | 2026-2036
Global Disclosure Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Disclosure Management Software Market Foresight
Modular bundling of compliance, reporting automation, and audit trail capabilities is broadening buyer choice in disclosure management platforms. Workiva leverages its cloud-native architecture to sustain leadership in financial reporting workflows. Oracle anchors enterprise-grade deployments through deep ERP integration. SAP competes by extending its S/4HANA ecosystem into regulatory filing automation.
Disclosure management software comprises platforms that collect, validate, and format structured financial and non-financial data for regulatory submissions and stakeholder communications, typically operating through XBRL tagging engines, workflow orchestration layers, and permission-based approval chains. Cloud-based deployment leads current adoption while hybrid configurations capture organizations transitioning from legacy on-premises systems. Reporting automation within the solution layer generates the fastest growth as ESG disclosure requirements multiply. Public companies and financial institutions represent the most concentrated end-user demand pools.
The SEC mandates XBRL formatting for U.S. filers while the EU Corporate Sustainability Reporting Directive imposes granular ESG disclosure standards across European registrants. The CSRD and SEC climate rules collectively expand addressable demand by forcing upgrade cycles from spreadsheet-based processes. Stakeholders must monitor how jurisdictional rule divergence shapes platform localization requirements and integration complexity.
Market Dynamics
XBRL mandate expansion and ESG disclosure granularity are compressing upgrade cycles from spreadsheet workflows into integrated cloud platforms, forcing procurement decisions around workflow automation depth rather than standalone formatting tools.
Growth Catalysts
- SEC Climate Disclosure Rules:U.S. public filers face expanded XBRL tagging requirements for emissions data, accelerating replacement of legacy desktop applications with orchestrated disclosure platforms.
- EU CSRD Phase-In:European registrants must report against European Sustainability Reporting Standards, creating demand for multi-framework validation engines that harmonize ESG metrics across jurisdictions.
- Cloud-Native Architecture:Financial institutions are migrating from on-premises XBRL processors to API-first platforms that embed directly into ERP reconciliation workflows.
Market Restraints
- Implementation Cost Concentration:Mid-cap issuers in Germany and France face six-figure deployment costs for CSRD-ready platforms, slowing adoption outside the largest registrants.
- Specialist Labor Scarcity:XBRL taxonomy expertise and ESG data engineering skills concentrate in London, New York, and Singapore, creating hiring bottlenecks for platform rollouts.
- Jurisdictional Fragmentation:Divergent SEC and EBA filing calendars force vendors to maintain parallel validation rule sets, inflating R&D overhead and platform pricing.
Strategic Opportunities
- India SEBI Mandate Expansion:Listed companies on Indian exchanges face tightening disclosure requirements for business responsibility reports, opening demand for localized XBRL platforms.
- AI-Assisted Validation Convergence:Natural language processing engines paired with robotic process automation are reducing manual tagging effort by tier-one audit firms.
- Embedded Finance Integration:Banking-as-a-service providers are white-labeling disclosure modules for fintech lenders seeking streamlined regulatory reporting.
Industry Challenges
- Multi-Taxonomy Mapping Complexity:Platforms must simultaneously support SEC, EBA, and SEBI XBRL taxonomies while maintaining audit trail integrity across frameworks.
- Legacy ERP Integration Friction:SAP and Oracle environments require custom connector development, extending implementation timelines and inflating professional services dependency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Disclosure Management Software Market |
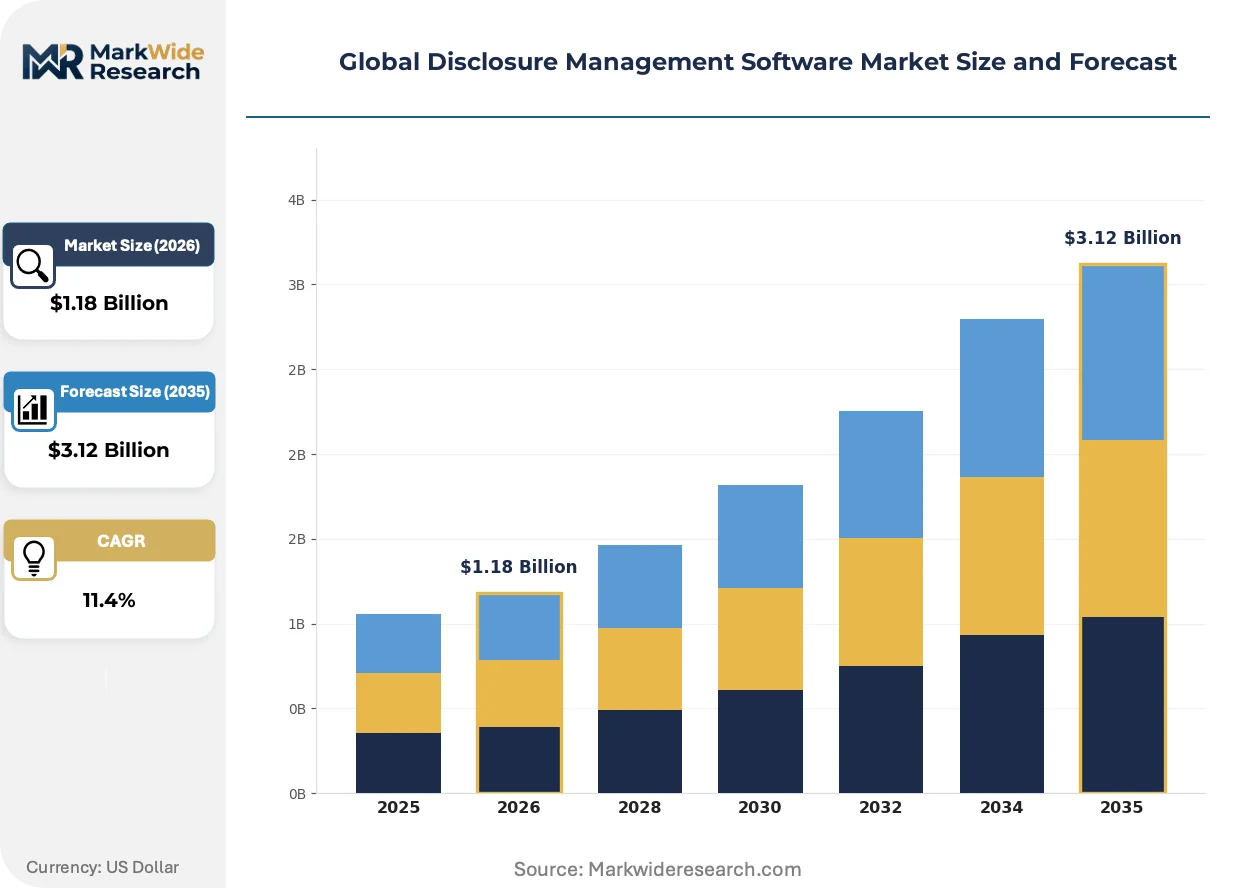
| Market Size in 2026 | $1.18 Billion |
| Market Size in 2035 | $3.12 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Software-as-a-Service Solution/Offering: Compliance Management, Reporting Automation, Data Integration, Audit Trail, Risk Management Application: Financial Reporting, Regulatory Filing, Investor Relations, Internal Controls, Investor Reporting End User: Financial Institutions, Insurance Firms, Accounting Firms, Public Companies, Government Agencies |
| Companies Covered | Insightsoftware, CCH Tagetik, Workiva, IRIS CARBON, DFIN ActiveDisclosure, Oracle, Prophix, Solvexia, SAP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Disclosure Management Software Market Shifts & Advancements
Generative AI and real-time data pipelines are dissolving the boundary between financial close processes and regulatory filing preparation, compressing disclosure production from weeks to days.
Natural language generation engines are absorbing the drafting burden for management discussion and analysis sections, enabling finance teams at U.S. multinationals to produce first-pass narratives in hours rather than days. Large language models trained on SEC comment letter patterns flag disclosure risks before submission. This capability is absorbing the traditional role of external counsel in pre-filing review cycles.
The EU Corporate Sustainability Reporting Directive imposes assurance requirements on ESG disclosures that previously operated on voluntary reporting standards. European filers must now secure limited assurance from statutory auditors on sustainability statements. Asset managers in Frankfurt and Paris are demanding platform vendors pre-integrate with auditor workpaper systems to streamline this verification layer.
Subscription pricing for disclosure software is displacing perpetual license models among North American mid-market issuers. Finance leaders in Boston and Chicago prioritize operating expense treatment and rapid scaling capacity over capitalized software ownership. Vendors are responding with seat-based tiers that expand contractually during peak filing windows without renegotiation.
Global Disclosure Management Software Market Segmentation
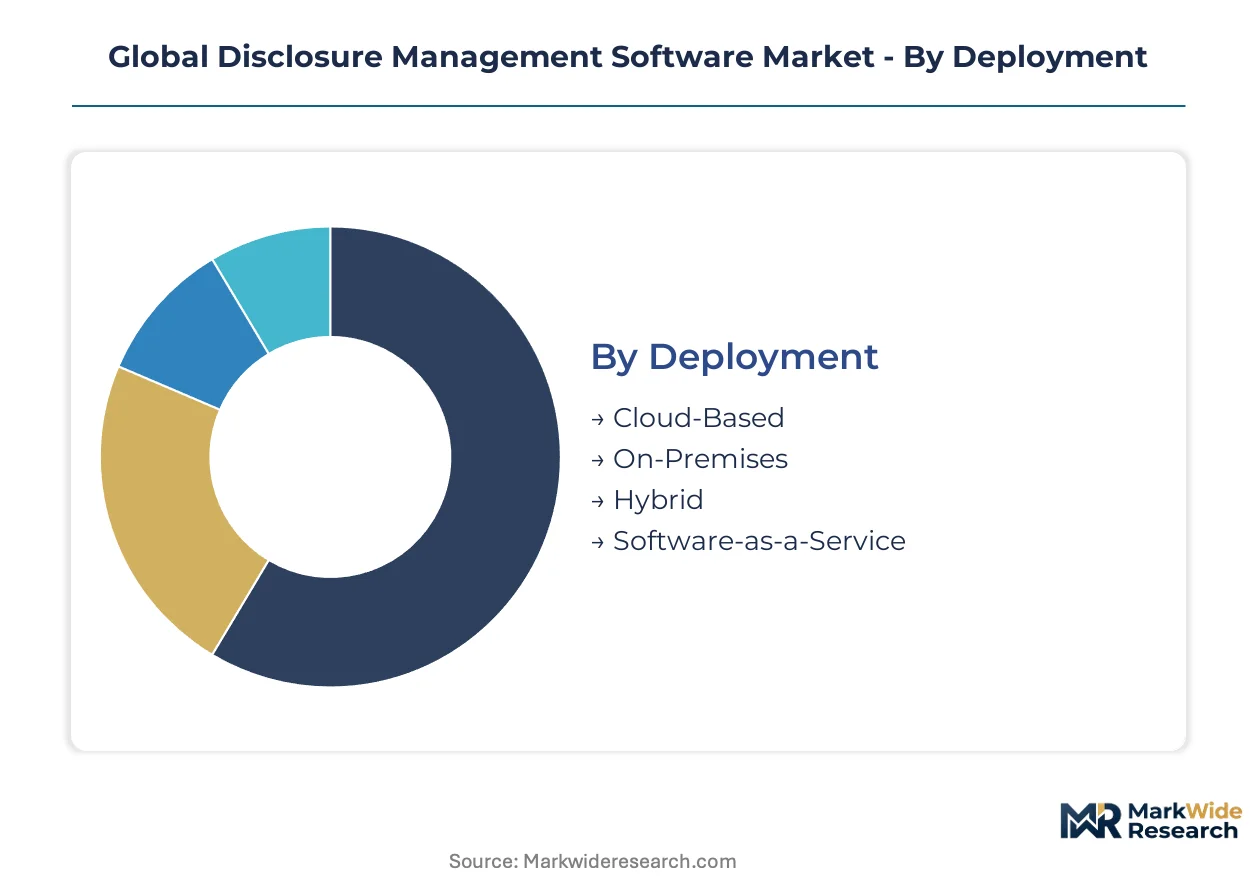
Segmentation in disclosure management software reveals how procurement priorities diverge across infrastructure maturity, regulatory exposure, and workflow complexity. Buyers select deployment modes and solution bundles based on ERP integration depth, XBRL mandate scope, and internal IT governance constraints.
Deployment:
Cloud infrastructure concentration among tier-one vendors is compressing implementation timelines and reshaping buyer procurement patterns.
- Cloud-Based:Multi-tenant architectures with API-first connectivity to ERP systems dominate new procurement among U.S. and German filers. Public companies in New York and Frankfurt prioritize these platforms for CSRD and SEC climate rule readiness.
- On-Premises:Legacy XBRL processors running behind corporate firewalls persist in Japanese and Swiss financial institutions with stringent data residency mandates. METI-regulated banks in Tokyo maintain these deployments for audit trail sovereignty.
- Hybrid:Split configurations anchor sensitive reconciliation data on-premises while pushing formatted filings to cloud validation engines. French insurance groups under ACPR supervision favor this model for ESG data segregation.
- Software-as-a-Service:Seat-based subscription tiers with elastic scaling during quarterly filing windows attract mid-cap issuers in India and Singapore. SEBI-registered companies in Mumbai adopt these for BRR disclosure automation.
Cloud-Based deployments absorb the bulk of installed capacity; Software-as-a-Service is expanding most quickly.
Solution/Offering:
Cost tier differentiation separates enterprise suites with full audit integration from modular point solutions targeting specific compliance gaps.
- Compliance Management:Rule engines mapping disclosure obligations across SEC, EBA, and SEBI taxonomies with automated gap analysis. U.S. multinationals with EU subsidiaries deploy these for CSRD-SEC dual reporting.
- Reporting Automation:XBRL tagging workflows with natural language generation for management discussion sections. Tier-one audit firms in London and New York deploy these to compress filing production cycles.
- Data Integration:ETL pipelines harmonizing ERP, ESG data warehouses, and sustainability rating platforms. German automotive suppliers use these for ESRS metric consolidation.
- Audit Trail:Immutable logging systems capturing approval chains and version history for statutory auditor review. French asset managers under AMF rules require pre-integration with these modules.
- Risk Management:Predictive analytics flagging disclosure inconsistencies against historical SEC comment letter patterns. U.S. registrants in Boston and Chicago deploy these for pre-submission risk scoring.
Reporting Automation captures the steepest expansion trajectory; Audit Trail modules command premium pricing in EU mandates.
Application:
Volume concentration in regulatory filing workflows is driving platform specialization toward XBRL validation and multi-framework submission.
- Financial Reporting:10-K and 20-F preparation with automated XBRL generation for U.S. GAAP and IFRS statements. Public companies in the United States anchor demand for these capabilities.
- Regulatory Filing:Direct submission portals connecting to EDGAR, ESMA registers, and SEBI portals with real-time validation feedback. EU registrants in Germany and France drive upgrade cycles here.
- Investor Relations:Earnings release automation and shareholder communication workflows with embedded ESG narrative generation. Indian listed companies expanding BRR disclosures adopt these modules.
- Internal Controls:SOX documentation and management certification workflows with deficiency tracking. U.S. mid-market issuers prioritize these for PCAOB audit efficiency.
- Investor Reporting:Limited partner communications and fund-level disclosure for private equity and asset managers. Firms in Singapore and London deploy these for AIFMD and Form PF alignment.
Regulatory Filing absorbs dominant procurement volume; Investor Relations applications are climbing the fastest as ESG disclosure broadens.
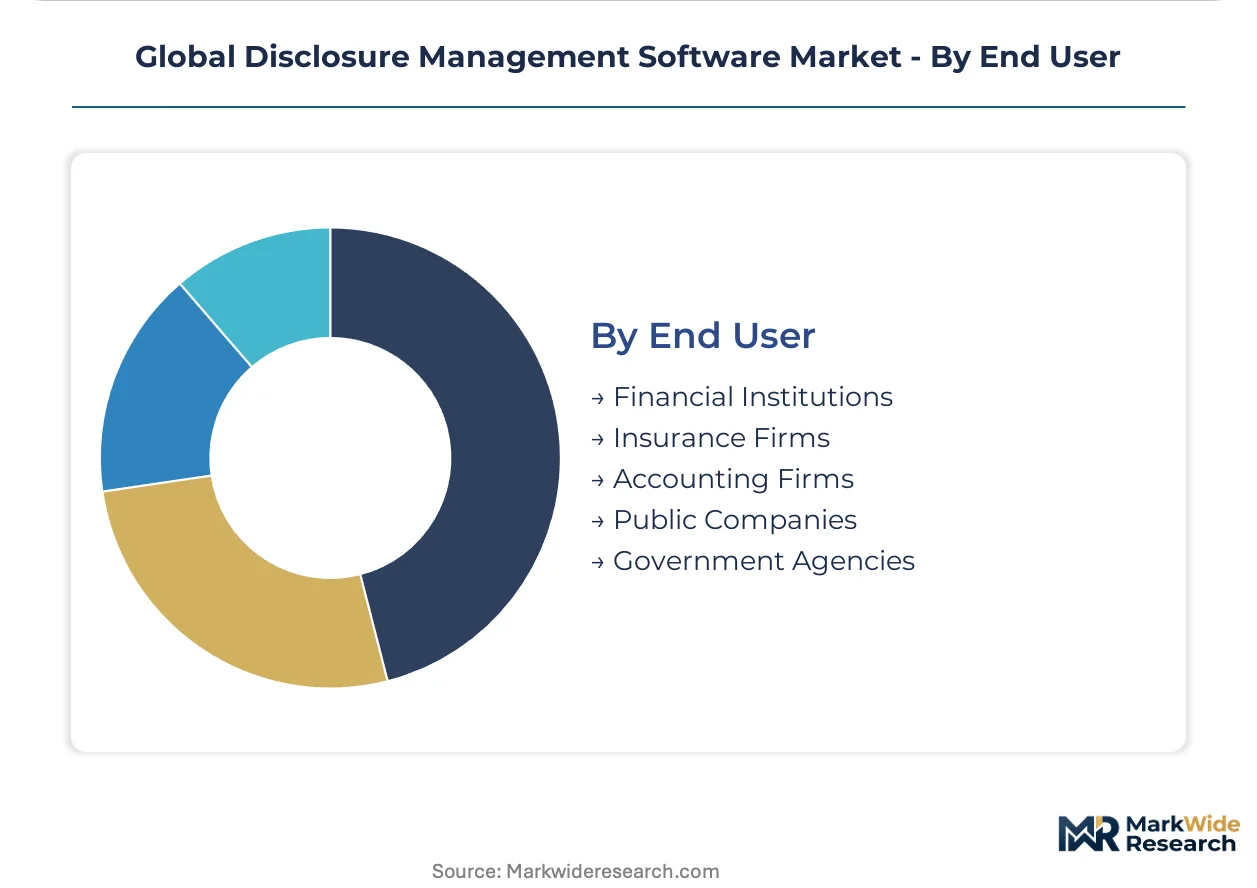
End User:
Customer type determines workflow complexity tolerance and integration depth requirements across the buyer base.
- Financial Institutions:Global systemically important banks with multi-jurisdictional filing obligations and real-time data reconciliation needs. Institutions in New York, London, and Zurich anchor enterprise platform demand.
- Insurance Firms:Solvency II and NAIC filing requirements with embedded actuarial data validation. European insurers under EIOPA supervision drive specialized module adoption.
- Accounting Firms:Audit-driven disclosure review and client co-development of filing workflows. The Big Four in London and New York deploy these for assurance service integration.
- Public Companies:SEC and CSRD registrants with quarterly and annual reporting cycles across multiple jurisdictions. U.S. and EU listed companies represent the core addressable market.
- Government Agencies:Sovereign wealth funds and public pension systems with transparency mandates and stakeholder reporting obligations. Agencies in Singapore and Norway adopt these for GRI-aligned disclosures.
Public Companies represent the largest installed base; Accounting Firms are gaining share fastest through audit service bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software development for disclosure management concentrates in the United States, Germany, and India, while consumption spreads across financial centers in London, Singapore, and New York where regulatory filing volumes are highest.
United States
SEC climate disclosure rules and XBRL mandate expansion drive procurement among S&P 500 filers in Manhattan and Chicago. The SEC mandates granular emissions data tagging for 10-K submissions, forcing upgrade cycles from desktop applications to cloud-native platforms. Boston-based asset managers are demanding API-first architectures that embed directly into ERP reconciliation workflows.
Germany
EU CSRD phase-in and ESRS reporting standards create concentrated demand among DAX-listed automotive and industrial conglomerates in Frankfurt and Munich. EBA filing requirements intersect with EIOPA supervision for insurers, generating specialized module adoption. Stuttgart-based automotive suppliers are deploying multi-framework validation engines to harmonize sustainability metrics across SEC and EU jurisdictions.
India
SEBI mandate expansion for business responsibility reports accelerates adoption among NSE-listed companies in Mumbai and Bangalore. The central bank's tightening disclosure requirements for financial institutions drive cloud migration among private sector banks. Hyderabad-based IT services exporters are white-labeling disclosure modules for fintech lenders seeking streamlined regulatory reporting.
United Kingdom
FCA alignment with ESMA standards and post-Brexit filing divergence create platform localization demand among FTSE 100 registrants in London and Edinburgh. The Big Four audit firms anchor enterprise platform deployment for assurance service integration. Canary Wharf-based asset managers require pre-integrated auditor workpaper systems for limited assurance on sustainability statements.
Japan
METI-regulated banks in Tokyo maintain hybrid deployments for audit trail sovereignty while migrating validation engines to cloud infrastructure. TSE-listed manufacturers in Osaka face dual reporting pressure from IFRS and Japanese GAAP convergence. Fukuoka-based regional banks are adopting seat-based subscription tiers for quarterly filing window elasticity.
Global Disclosure Management Software Market Competitive Landscape
The competitive structure tilts toward cloud-native specialists with deep ERP integration capabilities. Tier-one vendors with multi-tenant architectures command premium pricing among global systemically important banks, while modular point solution providers capture mid-market upgrade cycles from spreadsheet workflows. Two dominant archetypes emerge: enterprise suite vendors extending financial close platforms into regulatory automation, and vertical specialists concentrating on XBRL taxonomy engines. M&A activity concentrates on API-first startups with natural language generation capabilities, while incumbents defend position through strategic partnerships with tier-one audit firms.
Within the cloud-native specialist tier, Workiva and IRIS CARBON exemplify platform-first approaches that compress filing production cycles through workflow orchestration. Oracle anchors the enterprise suite segment with deep SAP and ERP integration for complex multi-jurisdictional filers. Among Germany-based configurators, CCH Tagetik occupies a position bridging compliance management with consolidation workflows for European CSRD readiness.
| Leading Market Players |
|---|
| Insightsoftware |
| CCH Tagetik |
| Workiva |
| IRIS CARBON |
| DFIN ActiveDisclosure |
| Oracle |
| Prophix |
| Solvexia |
| SAP |
| Others |
Supply & Pricing Matrix
Specialist labor costs in XBRL taxonomy engineering and ESG data architecture propagate downstream through tiered software pricing, with scarcity premiums in London and New York compressing margins for mid-market vendors while inflating enterprise suite valuations.
Pricing Analysis
Margin tightening in mid-cap SaaS tiers reflects the six-figure deployment costs CSRD mandates impose on German and French issuers outside the largest registrants. Three-tier pricing structure across premium, standard, and economy levels separates enterprise audit-integrated suites from modular point solutions and seat-based subscriptions. Pricing pressure intensifies in the mid-market as spreadsheet-to-cloud upgrade cycles compress procurement timelines. Financial institutions with multi-jurisdictional filing obligations exhibit lowest price sensitivity; SEBI-registered mid-caps in India demonstrate highest elasticity.
Supply Chain Analysis
XBRL taxonomy expertise scarcity in London, New York, and Singapore constrains platform rollout velocity for vendors serving EBA and SEC filing mandates. Software development concentrates in the United States, Germany, and India, with implementation services drawing from regional professional services networks in each jurisdiction. Supply chain risk centers on single-source vulnerability for specialized ESG data engineering talent and robotic process automation specialists. Distribution runs through direct enterprise sales teams for tier-one vendors, API marketplace integrations for cloud-native entrants, and audit firm partnerships for assurance-bundled deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Corporate Sustainability Reporting Directive transforms disclosure management into a cost-of-compliance arms race, erecting regulatory moats that favor vendors with pre-integrated auditor workpaper systems and multi-framework validation engines.
For Market Incumbents: Extend cloud-native architecture investments to embed generative AI validation layers that compress filing production cycles from weeks to days, neutralizing emerging API-first entrants. Deepen ERP integration partnerships with SAP and Oracle environments to capture legacy migration cycles. Prioritize pre-integration with statutory auditor systems for CSRD limited assurance workflows. For New Entrants and Emerging Players: API-first distribution channels offer the most penetrable route for fintech lenders and banking-as-a-service providers seeking white-labeled disclosure modules. Target SEBI-registered mid-caps in Mumbai and Bangalore where seat-based subscription tiers with elastic quarterly scaling remain underpenetrated. Lead with natural language generation capabilities for management discussion drafting to differentiate from incumbent workflow orchestration. For Investors and Strategic Acquirers: AI-assisted validation convergence is the leading indicator that natural language processing engines paired with robotic process automation will consolidate manual tagging market share. Long-term viability favors vendors with multi-tenant architectures and multi-taxonomy mapping capabilities spanning SEC, EBA, and SEBI jurisdictions. Monitor SEBI mandate expansion signals for Indian market inflection timing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first connectivity to SAP S/4HANA and Oracle ERP captures legacy migration demand in Frankfurt and Chicago. |
| Acquisition of Specialist Firm | Natural language generation startups absorb management discussion drafting burdens for tier-one audit firms. |
| Strategic Partnership | Pre-integration with Big Four auditor workpaper systems streamlines CSRD limited assurance verification layers. |
| Geographic Expansion | Localized XBRL platforms for SEBI business responsibility reports capture Mumbai and Bangalore upgrade cycles. |
| Product Launch | Generative AI validation engines flag SEC comment letter risks before submission, displacing external counsel review. |
Research Methodology
Document review covered SEC EDGAR filings, ESMA regulatory technical standards, SEBI circulars, and vendor SEC 10-K disclosures, complemented by interviews with CFOs at U.S. multinationals, ESG data controllers at German automotive suppliers, platform engineers at cloud-native vendors, and assurance partners at tier-one audit firms. Secondary validation drew from XBRL International taxonomy releases, CSRD implementation guidance, and ERP vendor integration documentation. Bottom-up deployment estimates triangulated against top-down regulatory mandate expansion projections.
Market sizing outputs reflect segment-level modeling across deployment mode, solution bundle, application workflow, and end-user archetype throughout the forecast period. CAGRs derived from regulatory mandate phase-in schedules, cloud migration velocity curves, and AI adoption penetration patterns in financial reporting workflows. Model inputs incorporated XBRL mandate expansion timelines, CSRD assurance requirement rollouts, and seat-based subscription displacement rates for perpetual licenses.
The model holds under stable regulatory implementation calendars; deviation in SEC climate rule litigation outcomes, CSRD phase-in delays, or ESG taxonomy standardization failures would shift upgrade cycle timing and vendor competitive positioning. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Worldwide Persuasive Content Management Software Market
Software & Services
Tech Support Services Market
Software & Services
Collaboration Software Market
Software & Services
Graphical User Interface (GUI) Design Software Market
Software & Services
Global Digital Signage Software Market
Software & Services
Global Offshore Software Development Market
Software & Services
Advanced Process Control Software Market
Software & Services
United States Donation Management Software Market
Software & Services
Ground Handling Software Market
Software & Services
Global Gamification Software Market
Software & Services
Data Center Backup and Recovery Software Market
Software & Services
Global Mobile Application Market
Software & Services
Global Audience Response Software Market
Software & Services
Embedded Software Market
Software & Services
Global Nosql Database Market
Software & Services
Global Inside Sales Software Market