
 Europe Anti-Money Laundering Software Market | 2026-2036
Europe Anti-Money Laundering Software Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Anti-Money Laundering Software Market Foresight
A persistent shortage of certified compliance engineers is unwinding implementation timelines across European financial institutions. Wolters Kluwer leverages its regulatory content backbone to sustain long-term client relationships in continental banking hubs. Featurespace Limited specializes in adaptive behavioral analytics, competing against legacy rule-based systems with machine-native detection architectures. SAP SE anchors enterprise-grade deployments through deep ERP integration, occupying the largest-account tier among multinational banks.
Europe Anti-Money Laundering Software encompasses transaction monitoring, customer due diligence, and suspicious activity reporting platforms engineered to detect, investigate, and document financial crime patterns across institutional payment flows. These systems deploy real-time behavioral analytics, rules engines, and AI classifiers to flag anomalous transactions for regulatory filing and internal risk review. Cloud-based solutions are capturing the fastest expansion as tier-two banks and cryptocurrency exchanges abandon capital-intensive on-premises infrastructure. Transaction Monitoring functionality leads absolute spending due to regulatory mandate density, while KYC Compliance modules are deepening margin pools through perpetual identity verification subscriptions. The Banking end-user segment dominates current procurement volumes, though Cryptocurrency sector demand is accelerating most sharply as virtual asset service providers face tightened registration requirements.
AMLA, GDPR, and the EU AI Act collectively reshape product architecture, mandating explainable algorithms, cross-border data governance, and centralized supervisory access across member states. National regulators in France, Germany, and Italy now require periodic model validation and audit trails that elevate software procurement standards above legacy check-box compliance. Stakeholders must weigh cloud sovereignty requirements against AI detection accuracy when selecting platform architectures for multi-jurisdictional deployment.
Market Dynamics
AMLA's centralized supervisory architecture is forcing European banks to replace fragmented national compliance stacks with unified cross-border platforms that satisfy pan-European audit standards.
Growth Catalysts
- EU AI Act:Mandates for explainable algorithmic decision-making are accelerating procurement of auditable machine learning transaction monitoring systems across French and German banking groups.
- Virtual Asset Service Providers:Cryptocurrency exchanges in the United Kingdom face tightened registration requirements under FCA guidelines, driving specialized AML software adoption.
- Real-time behavioral analytics:Adaptive machine-native detection architectures are capturing procurement budgets previously allocated to legacy rule-based screening engines.
Market Restraints
- Cloud sovereignty compliance:GDPR data localization requirements impose architectural constraints that fragment platform deployments across member state boundaries.
- Certified compliance engineer scarcity:Talent concentration in London and Frankfurt creates implementation bottlenecks for tier-two banks in peripheral markets.
- Legacy system integration costs:ERP anchoring by SAP SE in multinational banks creates switching friction that prolongs procurement cycles.
Strategic Opportunities
- Italian and Spanish tier-two banks:Underpenetrated markets present expansion targets for cloud-native platform vendors seeking share outside saturated London-Frankfurt-Paris corridors.
- Perpetual KYC subscriptions:Identity verification modules are deepening recurring revenue pools beyond one-time transaction monitoring licenses.
- Blockchain analytics convergence:Integration of on-chain transaction tracing with traditional fiat monitoring creates new product categories for virtual asset compliance.
Industry Challenges
- Cross-border model validation:National regulators in France, Germany, and Italy impose divergent audit trail standards that complicate single-platform deployment.
- Explainability engineering:EU AI Act requirements for interpretable algorithmic outputs demand specialized technical talent that remains scarce across continental Europe.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Anti-Money Laundering Software Market |
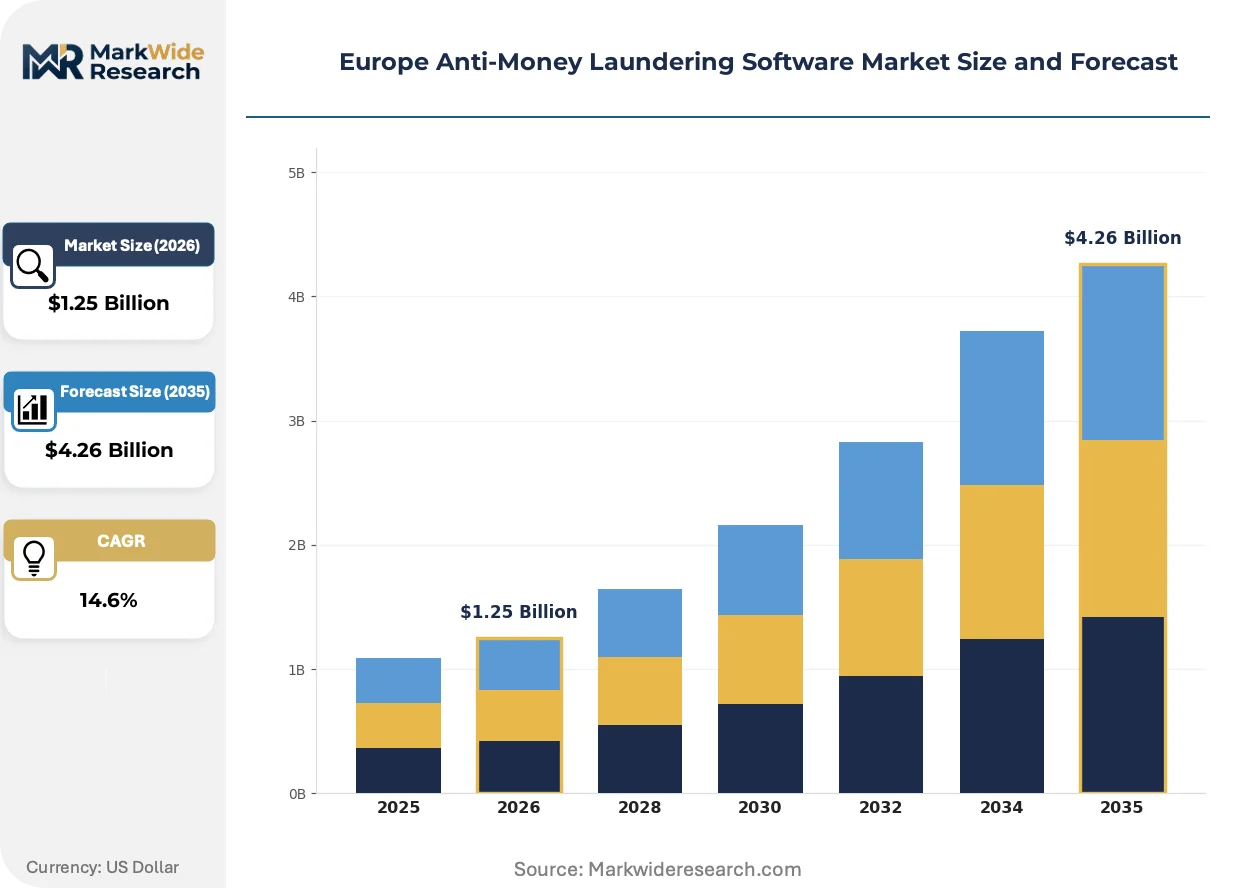
| Market Size in 2026 | $1.25 Billion |
| Market Size in 2035 | $4.26 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: On-premises, Cloud-based, Hybrid, Integrated End User Type: Banking, Insurance, Public Sector, Cryptocurrency Functionality: Transaction Monitoring, Risk Assessment, Reporting, KYC Compliance Deployment Model: Managed Service, Professional Service, Software as a Service, Others |
| Companies Covered | SAP SE, Wolters Kluwer, Comarch SA, Actico GmbH, Temenos, NICE Actimize, Featurespace Limited, Fiserv, BAE Systems, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Anti-Money Laundering Software Market Shifts & Advancements
Adaptive behavioral analytics is supplanting static rule engines as the dominant detection paradigm, compressing implementation timelines and reshaping vendor competitive positioning across European financial institutions.
Machine-native detection architectures leverage continuous model retraining against evolving transaction patterns. Tier-one banks in the United Kingdom and Germany are deploying these systems at scale, displacing legacy threshold-based alert generation. The technology is supplanting conventional compliance workflows by automating investigation prioritization and reducing false positive rates.
AMLA's establishment of a centralized EU supervisory authority mandates harmonized reporting standards across member states. Financial institutions must now maintain cross-border audit trails accessible to regulators in multiple jurisdictions. Banks with operations spanning France, Germany, and Italy are consolidating previously siloed national compliance functions into unified platforms.
Subscription-based pricing for perpetual customer due diligence is displacing perpetual license models for transaction monitoring modules. Fintechs and digital asset service providers in London's financial district are driving this transition, demanding operational expenditure treatment over capital-intensive procurement. The shift is most visible among cryptocurrency exchanges seeking to minimize upfront platform investments while maintaining regulatory coverage.
Europe Anti-Money Laundering Software Market Segmentation
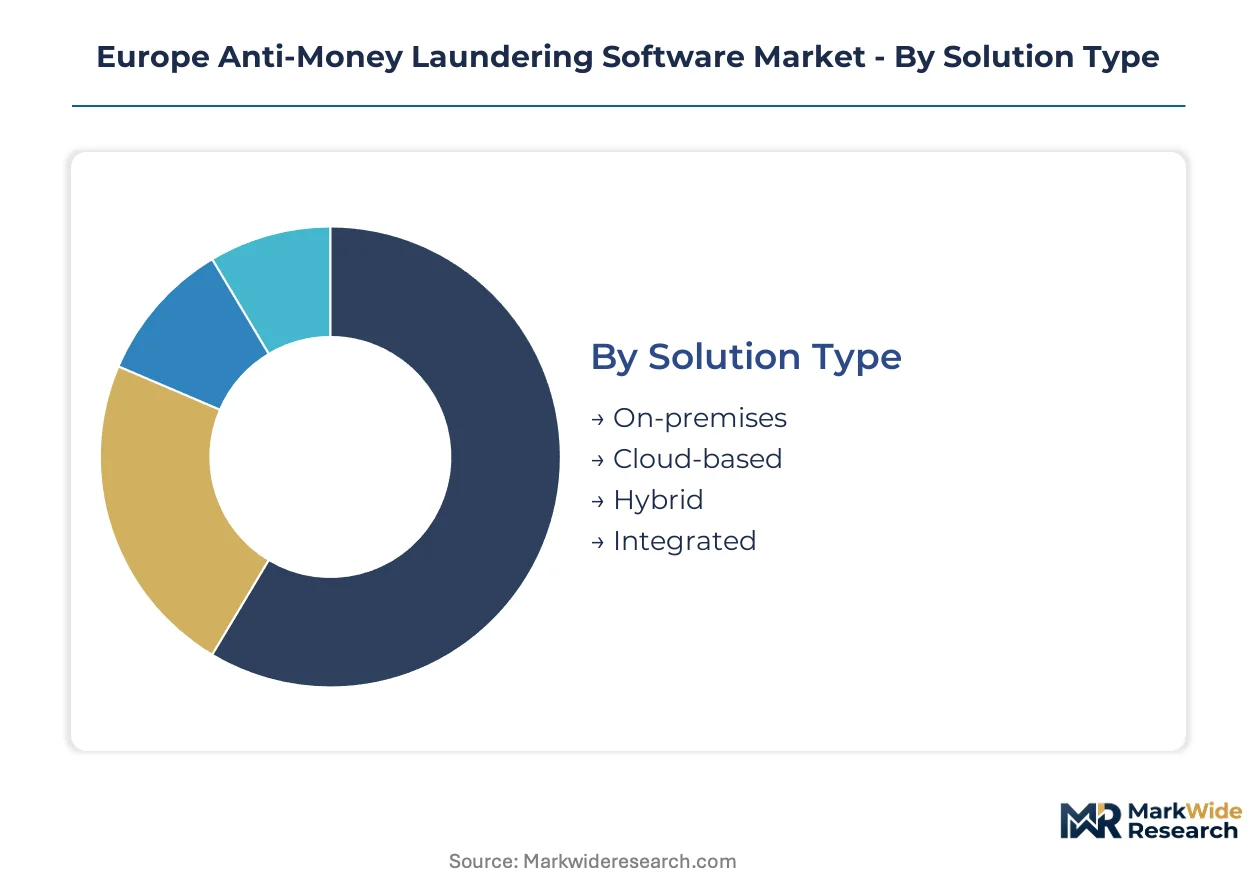
Segmentation in European AML software reveals how procurement priorities diverge across institutional risk profiles and regulatory maturity. Cloud-native architectures command premium pricing in fintech-heavy jurisdictions, while legacy banking groups prioritize integration depth over deployment speed.
Solution Type:
Margin pools concentrate in subscription-based delivery models that minimize client capital expenditure while ensuring recurring vendor revenue.
- Cloud-based:Multi-tenant architectures with auto-scaling compute resources serve tier-two banks and cryptocurrency exchanges in London and Frankfurt. Demand clusters among virtual asset service providers seeking rapid deployment without infrastructure capital. GDPR data sovereignty requirements impose regional instance mandates that elevate operational complexity.
- On-premises:Dedicated hardware installations within client data centers persist among German and French banking groups with legacy core banking dependencies. Procurement concentrates at institutions with restrictive data residency policies or classified transaction flows. Maintenance contracts and hardware refresh cycles sustain long-term vendor relationships.
- Hybrid:Split architectures route sensitive screening workloads on-site while leveraging cloud analytics for pattern detection. French mutual banks and Italian cooperative institutions favor this model for phased modernization.
- Integrated:Unified platforms embedding AML modules within broader risk management suites appeal to multinational banks with SAP SE or Oracle ERP anchors. Procurement cycles extend due to cross-functional stakeholder alignment requirements.
The dominant share belongs to Cloud-based deployments, while Hybrid solutions are gaining share fastest among mid-tier institutions navigating sovereignty constraints.
End User Type:
Application intensity varies sharply by sector regulatory exposure and transaction velocity.
- Banking:Universal banks in Germany, France, and the United Kingdom deploy comprehensive transaction monitoring across correspondent banking, trade finance, and retail payment streams. Wolters Kluwer and Featurespace Limited compete for tier-one procurement with divergent technical architectures. Implementation timelines stretch due to model validation requirements under national regulator mandates.
- Cryptocurrency:Virtual asset service providers face FCA registration deadlines in the United Kingdom and BaFin licensing in Germany. Specialized blockchain analytics integration distinguishes vendor offerings in this segment. Featurespace Limited's adaptive behavioral analytics capture procurement budgets from exchanges seeking machine-native detection.
- Insurance:Life and property-casualty carriers apply AML screening to premium financing, claims disbursement, and agency commission flows. Lower transaction volumes reduce platform sophistication requirements compared to banking.
- Public Sector:National financial intelligence units and tax authorities procure case management and cross-border information exchange infrastructure. Procurement concentrates in EU member states with AMLA direct supervisory relationships.
Banking retains the dominant procurement volume, though Cryptocurrency end users are expanding most quickly as registration deadlines tighten across European jurisdictions.
Functionality:
Recurring revenue depth distinguishes perpetual identity verification from one-time detection licensing.
- Transaction Monitoring:Real-time screening engines apply rule sets and machine learning classifiers to flag anomalous payment flows for investigation. German and British banks prioritize false positive reduction to contain operational investigation costs. Regulatory mandate density ensures this functionality captures the largest absolute spending.
- KYC Compliance:Perpetual customer due diligence platforms automate identity verification, beneficial ownership tracing, and risk rating updates throughout client relationships. London fintechs drive subscription pricing adoption to convert capital expenditure to operational treatment. Margin expansion potential exceeds transaction monitoring as verification frequency increases.
- Risk Assessment:Quantitative models score institutional and geographic exposure for portfolio-level compliance planning. Italian and Spanish banks apply these tools for AMLA-mandated risk factor documentation.
- Reporting:Automated suspicious activity report generation and regulatory filing workflows reduce manual documentation burden. Cross-border standardization under AMLA elevates platform requirements for multi-jurisdictional institutions.
Transaction Monitoring holds the dominant share, while KYC Compliance is climbing the fastest as subscription models displace perpetual licensing.
Deployment Model:
Customer type and internal capability determine service layering preferences.
- Software as a Service:Fully managed cloud delivery with vendor-operated infrastructure and continuous model updates. Cryptocurrency exchanges and neobanks in the United Kingdom favor this model for minimal IT overhead.
- Managed Service:Vendor-staffed investigation teams handle alert triage and case escalation on client behalf. Tier-two banks in peripheral markets procure these services to address certified compliance engineer scarcity.
- Professional Service:Implementation consulting, system integration, and model validation support for complex enterprise deployments. SAP SE anchors drive demand for specialized integration expertise.
- Others:Training programs, regulatory advisory, and audit preparation services complement core platform delivery.
Software as a Service commands the dominant procurement preference, while Managed Service is expanding most quickly among institutions confronting talent constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United Kingdom fintech clusters deploy cloud-native transaction monitoring for cryptocurrency exchanges, while German banking groups favor on-premises installations with deep ERP integration. French mutual banks pursue hybrid architectures to balance sovereignty requirements against analytics performance.
United Kingdom
London's fintech corridor drives SaaS procurement for virtual asset service providers facing FCA registration deadlines. The Economic Crime and Corporate Transparency Act mandates enhanced beneficial ownership disclosure, accelerating perpetual KYC platform adoption. Manchester and Edinburgh house tier-two banks modernizing compliance stacks through managed service partnerships.
Germany
BaFin licensing requirements for cryptocurrency custodians and payment institutions fuel specialized AML software procurement. The German Banking Act imposes stringent model validation standards that prolong enterprise implementation cycles. Frankfurt anchors continental Europe's largest banking concentration, where SAP SE-anchored ERP environments create substantial switching friction for alternative vendors.
France
Parisian banking groups consolidate previously siloed national compliance functions under AMLA-mandated cross-border audit standards. The French Monetary and Financial Code requires periodic algorithmic explainability documentation, elevating procurement criteria above legacy threshold-based systems. Lyon and Toulouse host emerging regtech clusters serving mutual banks with hybrid deployment preferences.
Italy
Milan's financial district presents underpenetrated expansion targets for cloud-native vendors seeking share outside saturated northern European corridors. The Italian Consolidated Banking Act imposes risk factor documentation requirements that deepen demand for quantitative assessment modules. Rome and Turin concentrate tier-two institutions confronting certified compliance engineer scarcity through managed service procurement.
Spain
Barcelona and Madrid fintech ecosystems drive subscription-based pricing adoption among neobanks seeking operational expenditure treatment. The Spanish Prevention of Money Laundering Regulations align with EU directives while permitting phased cloud migration timelines. Valencia hosts regional banking headquarters pursuing behavioral analytics upgrades to reduce false positive investigation burdens.
Europe Anti-Money Laundering Software Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational ERP anchors occupying the largest-account positions while adaptive analytics specialists capture fintech procurement. The market structure reflects divergent technical architectures: rule-based legacy platforms defend entrenched banking relationships as machine-native detection systems penetrate cryptocurrency and neobank segments. Two strategic archetypes dominate competitive positioning—enterprise integrators leveraging regulatory content backbones, and behavioral analytics pure-plays competing on implementation velocity. Consolidation pressure intensifies through technology licensing partnerships and vertical capability acquisitions.
Within the enterprise integration tier, SAP SE anchors multinational banking deployments through deep ERP coupling, while Wolters Kluwer sustains continental European relationships via regulatory content breadth. Featurespace Limited exemplifies the adaptive analytics archetype, occupying positions among United Kingdom cryptocurrency exchanges and tier-one banks seeking machine-native detection architectures.
| Leading Market Players |
|---|
| SAP SE |
| Wolters Kluwer |
| Comarch SA |
| Actico GmbH |
| Temenos |
| NICE Actimize |
| Featurespace Limited |
| Fiserv |
| BAE Systems |
| Others |
Supply & Pricing Matrix
Cloud-native SaaS delivery displacing on-premises perpetual licensing simultaneously redistributes vendor development costs across multi-tenant architectures and compresses procurement economics for tier-two banks and cryptocurrency exchanges. This substitution dynamic concentrates pricing power with vendors operating hyperscale infrastructure in Ireland and the Netherlands while fragmenting margin capture among legacy integrators maintaining German and French data center footprints.
Pricing Analysis
Subscription-based SaaS contracts dominate procurement, with three-tier pricing structure across premium, standard, and economy levels differentiating by model sophistication and investigation support depth. Price differentiation rests on explainability certification grade under EU AI Act standards and geographic data sovereignty compliance. Cost compression in standard tiers intensifies because feature parity across cloud-native entrants erodes legacy vendor premiums. Neobanks and virtual asset service providers exhibit highest price sensitivity; multinational banking groups anchored to SAP SE ERP environments demonstrate lowest.
Supply Chain Analysis
Implementation lead times stretch 8-14 months for enterprise deployments due to certified compliance engineer scarcity concentrated in London and Frankfurt. Software development capacity clusters in the United Kingdom, Germany, and Poland, with model training infrastructure drawing from Irish and Dutch hyperscale facilities. Single-source vulnerability permeates explainability engineering talent pools, constraining algorithmic audit documentation capacity. Distribution runs through direct enterprise sales teams for tier-one banking groups and channel partners serving mid-tier institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified compliance engineers capable of EU AI Act documentation represent the critical binding constraint across European financial institutions, elevating implementation risk and extending procurement cycles beyond historical baselines.
For Market Incumbents: Fortify regulatory content moats through accelerated EU AI Act certification pathways for machine learning transaction monitoring modules. Deepen vertical integration into explainability engineering talent pools via specialized training academies in Frankfurt and Paris to counter cloud-native entrants capturing cryptocurrency exchange procurement. Prioritize perpetual KYC subscription bundling to offset transaction monitoring license erosion. For New Entrants and Emerging Players: AMLA-mandated cross-border audit standardization creates immediate procurement windows at Italian and Spanish tier-two banks underserved by legacy vendor implementation capacity. Target Milan and Barcelona metropolitan banking clusters with managed service offerings that substitute vendor-staffed investigation teams for scarce certified compliance engineers. Pursue rapid FCA registration support packaging for United Kingdom virtual asset service providers facing enforcement deadlines. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed regtech specialists possessing EU AI Act-ready model documentation but constrained geographic footprint. Five-to-ten year viability hinges on adaptive behavioral analytics IP depth and regulatory relationship density across BaFin, FCA, and ACPR supervisory interfaces. Monitor AMLA centralized authority staffing levels as inflection indicator for harmonized procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Fast-Track | Explainable algorithmic documentation accelerates procurement at French and German banking groups. |
| Perpetual KYC Subscription Launch | Recurring revenue conversion captures London fintech operational expenditure preferences. |
| Blockchain Analytics Integration | On-chain tracing capability distinguishes vendor offerings for BaFin-licensed cryptocurrency custodians. |
| Managed Service Expansion | Vendor-staffed investigation teams address certified compliance engineer scarcity in Italian tier-two markets. |
| Hybrid Deployment Architecture | Split cloud-on-premise models satisfy GDPR sovereignty requirements for French mutual banks. |
Research Methodology
Cross-validation between primary interviews with compliance technology officers and secondary regulatory filing analysis anchors the qualitative findings. Stakeholder engagement encompassed chief risk officers at tier-one banks, regulatory affairs leads at virtual asset service providers, procurement directors at neobanks, and model validation specialists at national supervisory authorities. Secondary sources included AMLA implementation guidelines, BaFin circulars on cryptocurrency custody, FCA registration disclosure databases, and EU AI Act delegated act drafts. Bottom-up deployment sizing and top-down regulatory mandate intensity triangulation established segment boundaries.
Sensitivity analysis across cloud adoption velocity and certified engineer supply elasticity informs the projection framework. Segmentation dimensions modeled encompass deployment architecture, end-user regulatory exposure tier, functionality module mix, and cross-border operational complexity. CAGRs derive from regulatory deadline clustering and technology substitution curve fitting. Model inputs include FCA registration queue depth, AMLA supervisory staffing plans, and ERP anchor concentration at multinational banking groups.
Decision-makers should treat outputs as directional under sustained EU AI Act implementation timeline and AMLA centralized authority operationalization assumptions; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Smartphone Security Market
Security Software
Privileged Identity Management Market
Security Software
Cloud Identity and Access Management Software Market
Security Software
Data Privacy Software Market
Security Software
United States Lawful Interception Market
Security Software
Software Defined Perimeter (SDP) Market
Security Software
Anti-Money Laundering (AML) Software Solution Market
Security Software
Online Background Check Market
Security Software
Global Data Privacy Management Software Tools Market
Security Software
Managed Security Services Market
Security Software
Cloud File Security Software Market
Security Software
Privacy Management Software Market
Security Software
Security Information and Event Management Software Market
Security Software
Cloud Data Loss Prevention Solution Market
Security Software
Sound Masking Systems Market
Security Software
Software Assurance Market