
 Audit Management Software Market | 2026-2036
Audit Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Audit Management Software Market Analysis
Market Context
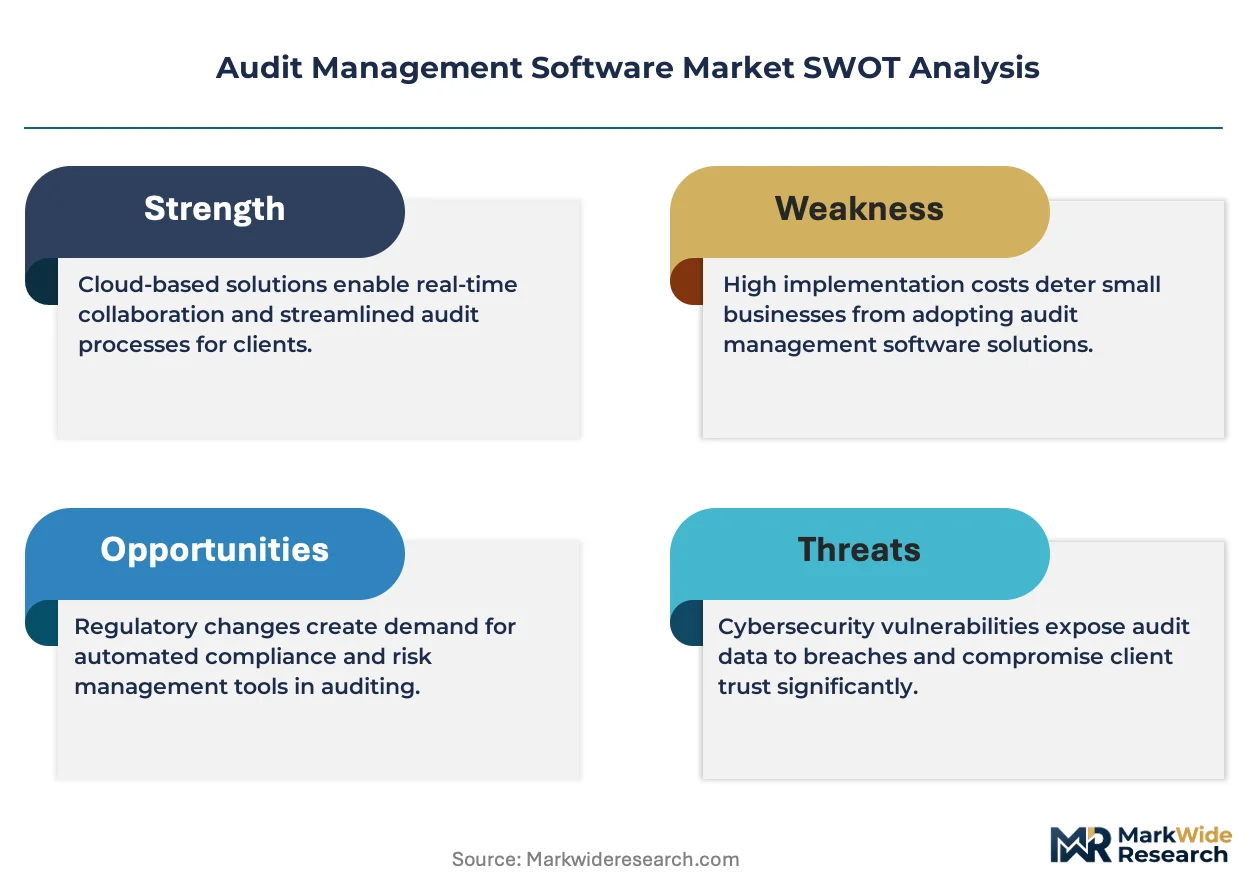
ISO 19011 certification for management system auditing is unwinding competitive barriers as enterprises demand vendor compliance with internationally recognized audit methodologies. Workiva leverages its cloud-native disclosure management heritage to anchor positions in regulated industries. Oracle competes through deep ERP integration that sustains captive demand among Fortune 500 accounts. AuditBoard differentiates via purpose-built risk and audit platforms that dominate mid-market and large-enterprise segments.
Technical Definition and Segment Structure
Audit management software comprises configurable platforms that automate planning, execution, documentation, and reporting of internal and external audits through workflow engines, risk scoring algorithms, and evidence repositories. These systems serve chief audit executives, compliance officers, and external auditors by reducing manual coordination overhead and standardizing assurance coverage across decentralized operations. Cloud-based deployment leads the product type landscape as enterprises abandon capital-intensive on-premises infrastructure, while SaaS delivery captures the fastest expansion by embedding continuous compliance monitoring into subscription economics. Among end users, financial institutions occupy the deepest margin pools due to layered regulatory scrutiny from multiple agencies, whereas healthcare providers represent an emerging growth vector as HIPAA enforcement tightens.
Regulatory Frame and Outlook
The SEC, EMA, and GDPR enforcement frameworks collectively shape product roadmaps by mandating immutable audit trails, real-time anomaly detection, and cross-border data governance capabilities. HIPAA and the EU AI Act further segment vendor specialization, as healthcare and algorithmic audit modules require distinct certification pathways. Stakeholders must monitor how convergence between financial disclosure rules and sustainability reporting standards reshapes feature prioritization across platform providers.
Market Dynamics
SEC disclosure mandates and the EU AI Act are compressing audit cycles while forcing platforms to embed real-time anomaly detection, reshaping vendor roadmaps toward continuous monitoring architectures.
Growth Catalysts
- HIPAA enforcement tightening:Healthcare providers in the United States face intensified OCR audits, driving demand for automated evidence repositories and risk-scoring modules.
- GDPR cross-border data governance:European enterprises require immutable audit trails for algorithmic decision-making, expanding addressable market for compliance platforms.
- Cloud-native workflow engines:SaaS delivery models embed continuous compliance monitoring into subscription economics, reducing capital barriers for mid-market adoption.
Market Restraints
- ISO 19011 certification costs:Vendor compliance with internationally recognized audit methodologies requires sustained investment in methodology training and third-party validation.
- ERP integration complexity:Deep system interoperability demands specialized engineering resources, concentrating implementation capacity among established providers.
- On-premises infrastructure drag:Enterprises with legacy data center investments face sunk-cost friction when migrating to cloud-based audit platforms.
Strategic Opportunities
- EU AI Act algorithmic accountability:European regulators mandate explainability documentation for automated systems, creating specialized module demand.
- Continuous control monitoring convergence:Integration of risk scoring algorithms with ERP transaction streams enables real-time assurance coverage.
- India BIS management system standards:Emerging market enterprises seek ISO-aligned audit platforms as manufacturing compliance requirements mature.
Industry Challenges
- Chief audit executive talent scarcity:Shortage of professionals versed in both assurance methodology and platform configuration slows enterprise deployment timelines.
- Multi-agency regulatory mapping:Financial institutions must reconcile overlapping SEC, Federal Reserve, and state-level examination protocols within single workflow engines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Audit Management Software Market |
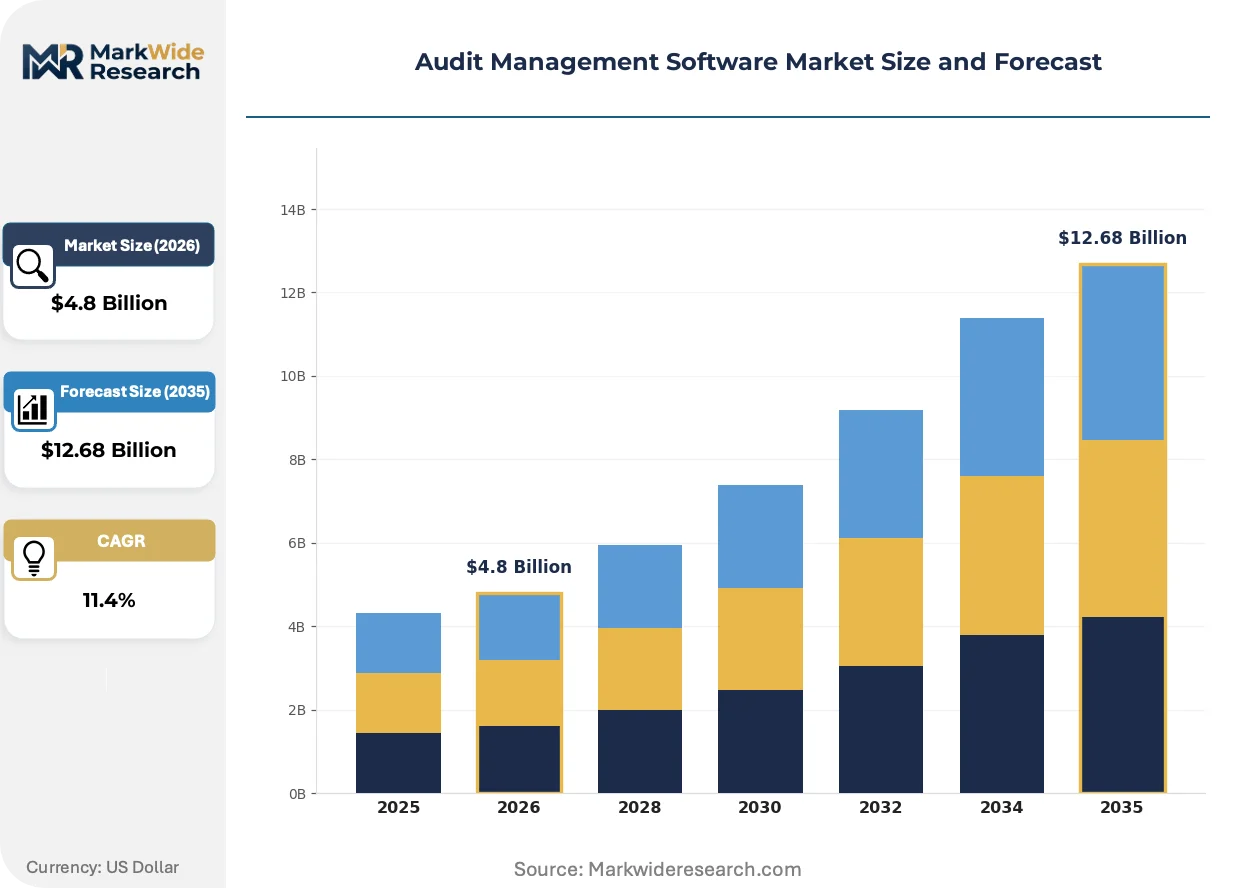
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premises, Hybrid, SaaS End User: Financial Institutions, IT Companies, Healthcare Providers, Government Agencies Deployment Model: Private Cloud, Public Cloud, Community Cloud, Dedicated Server Feature: Risk Management, Compliance Tracking, Workflow Automation, Reporting Tools |
| Companies Covered | Workiva, Oracle, AuditBoard, DataSnipper, Vanta, Diligent, SAP, Onspring, MetricStream, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Audit Management Software Market Emerging Trajectories
Artificial intelligence is compressing traditional audit sampling into continuous population analysis, while regulatory convergence between financial and sustainability disclosure standards forces platform unification.
Natural language processing engines are fragmenting manual documentation review by extracting control evidence directly from unstructured data sources. Large enterprises in financial services are deploying these tools across decentralized operations, compressing fieldwork timelines from weeks to days. This capability is fragmenting the traditional audit firm staffing model by reducing junior-level document examination hours.
The EU AI Act's risk-based classification system mandates algorithmic impact assessments for high-risk automated decision systems. European financial institutions and healthcare providers must document training data provenance and model performance metrics, forcing audit platforms to embed MLOps monitoring capabilities. Vendors are responding by certifying specialized healthcare and algorithmic audit modules through distinct regulatory pathways.
Subscription-based procurement is displacing perpetual license arrangements as enterprises prioritize operational expenditure flexibility. Mid-market buyers in the United States are consolidating vendor relationships around SaaS platforms that bundle continuous compliance monitoring with annual assurance workflows. This shift concentrates purchasing power among platforms demonstrating multi-tenant scalability and rapid feature deployment cycles.
Audit Management Software Market Segmentation
Audit management software segments reflect divergent procurement economics across regulated industries. Deployment preferences and feature prioritization vary sharply between financial institutions facing SEC mandates and healthcare providers navigating HIPAA enforcement.
Product Type:
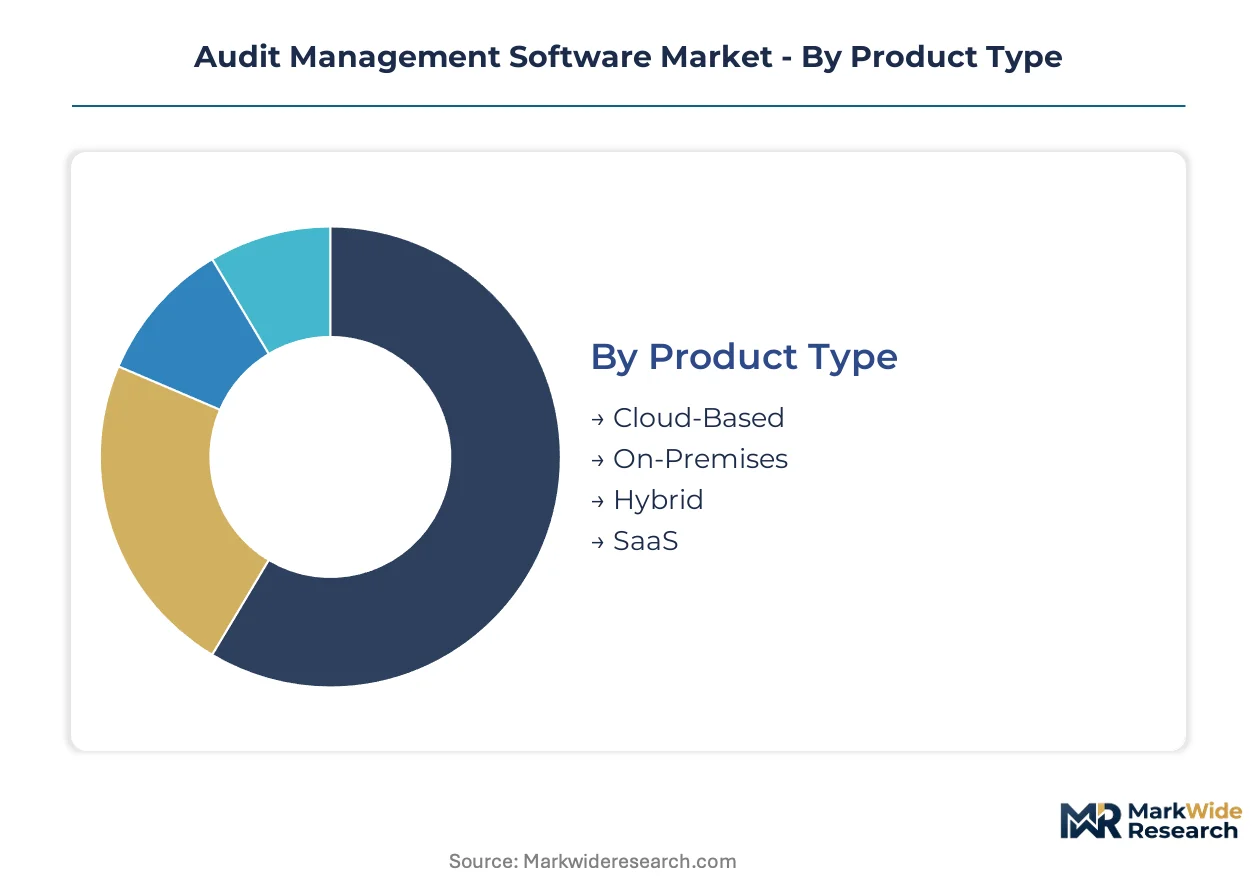
Channel mix splits sharply between capital-intensive perpetual licenses and recurring SaaS subscriptions, with migration patterns dicting vendor pricing power.
- Cloud-Based:Multi-tenant architectures enable continuous compliance monitoring without on-premises infrastructure overhead. Financial institutions in the United States favor these platforms as SEC disclosure mandates compress audit cycle timelines.
- SaaS:Subscription economics embed automated updates and regulatory content feeds directly into recurring fees. Healthcare providers expanding OCR audit readiness drive fastest adoption velocity among mid-market buyers.
- On-Premises:Legacy data center investments create sunk-cost friction for enterprises with stringent data residency requirements.
- Hybrid:Split deployments accommodate sensitive audit evidence on-premises while leveraging cloud analytics for risk scoring.
Cloud-Based platforms dominate installed base. SaaS delivery is where expansion concentrates.
End User:
Cost tiers stratify by regulatory layering intensity, with multi-agency oversight creating premium pricing tolerance.
- Financial Institutions:Banks and insurers operate under overlapping SEC, Federal Reserve, and state examination protocols requiring real-time anomaly detection. These buyers command deepest margin pools due to compliance failure costs.
- Healthcare Providers:Hospital systems and payers face intensified OCR audits under tightening HIPAA enforcement. Automated evidence repositories reduce manual documentation burden during surprise inspections.
- IT Companies:Technology vendors prioritize workflow automation for SOC 2 and ISO 27001 certification maintenance.
- Government Agencies:Public sector procurement favors FedRAMP-authorized platforms with immutable audit trail capabilities.
Financial Institutions anchor revenue concentration. Healthcare Providers are climbing the fastest as enforcement tightens.
Deployment Model:
Volume distribution tracks data sovereignty requirements and cross-border governance complexity.
- Private Cloud:Single-tenant isolation satisfies GDPR cross-border data transfer restrictions for European financial institutions. German and French regulators mandate enhanced control over algorithmic audit trails.
- Public Cloud:Shared infrastructure delivers cost efficiency for mid-market IT companies with standardized compliance needs.
- Community Cloud:Sector-specific instances serve healthcare consortiums sharing HIPAA-compliant audit frameworks.
- Dedicated Server:Physical isolation accommodates government agencies with classified audit evidence requirements.
Private Cloud holds largest share among regulated enterprises. Public Cloud is gaining share fastest as SaaS procurement displaces capital expenditure.
Feature:
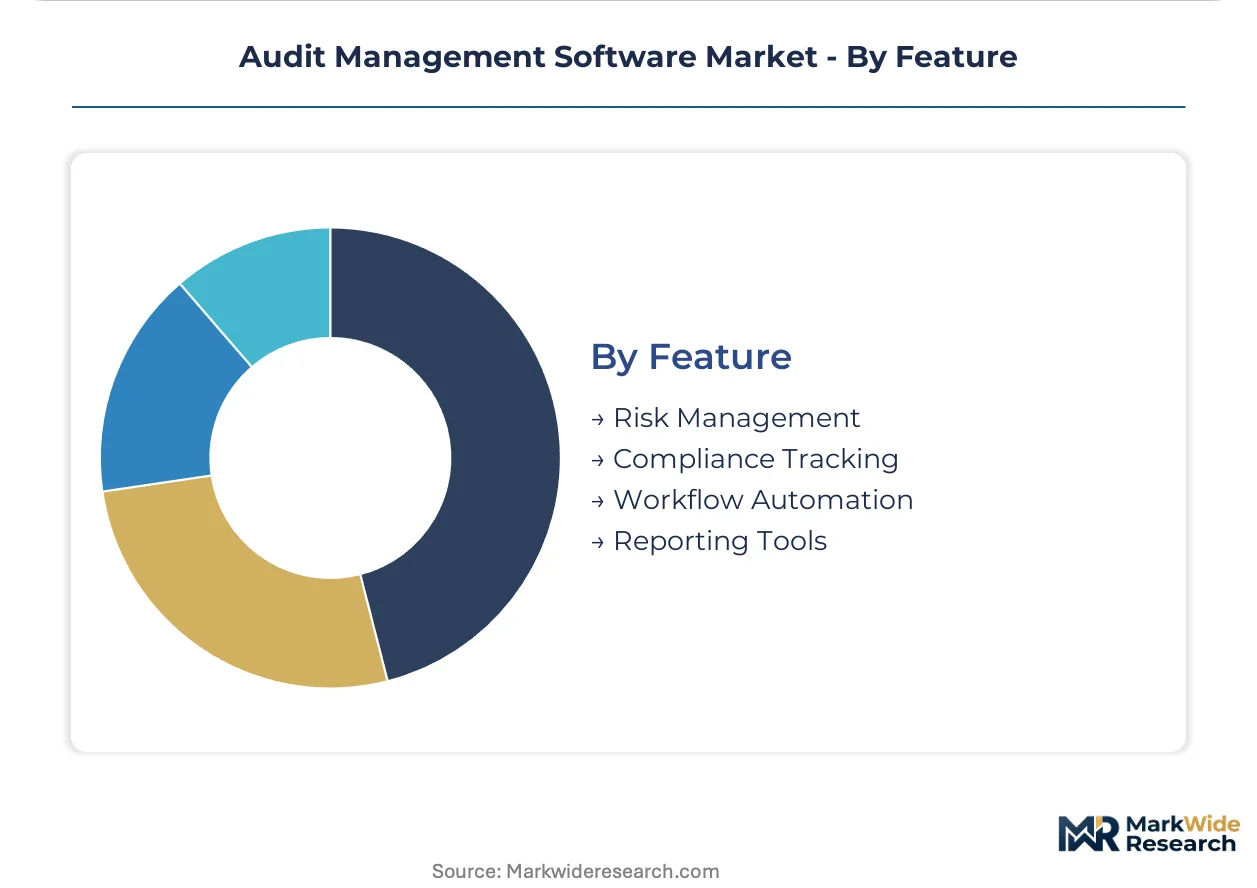
Application criticality determines module bundling strategies, with risk scoring commanding premium positioning.
- Risk Management:Algorithmic scoring engines prioritize audit resources based on control failure probability. EU AI Act mandates for high-risk automated systems expand addressable market for integrated risk-quantification tools.
- Compliance Tracking:Regulatory content libraries map control frameworks to SEC, GDPR, and HIPAA requirements automatically. Financial institutions consolidate multi-jurisdiction obligations within unified dashboards.
- Workflow Automation:Configurable engines reduce manual coordination between decentralized audit teams.
- Reporting Tools:Natural language generation compresses documentation timelines for external auditor handoff.
Risk Management modules command highest pricing. Compliance Tracking is where vendor R&D investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SEC disclosure mandates and HIPAA enforcement tightening are concentrating audit management software procurement in jurisdictions with layered regulatory oversight. Financial institutions and healthcare providers drive demand across markets with multi-agency examination protocols.
United States
Financial institutions in New York and Chicago deploy cloud-native platforms to compress audit cycles under overlapping SEC and Federal Reserve mandates. The Office for Civil Rights intensifies HIPAA audits, pushing hospital systems toward automated evidence repositories. Silicon Valley technology vendors prioritize SOC 2 workflow automation for certification maintenance.
Germany
Automotive and industrial conglomerates in Bavaria and Baden-Württemberg demand private cloud deployments to satisfy GDPR cross-border data transfer restrictions. The EU AI Act mandates algorithmic impact assessments for automated manufacturing systems. Frankfurt's financial services cluster drives adoption of integrated risk-scoring modules for real-time assurance.
United Kingdom
London-based banks and insurers reconcile multi-jurisdiction obligations within unified compliance dashboards as the Financial Conduct Authority tightens disclosure requirements. The UK Information Commissioner's Office enforces algorithmic accountability for automated credit decisions. Edinburgh's fintech cluster experiments with continuous control monitoring convergence.
India
IT services exporters in Bengaluru and Hyderabad seek ISO-aligned audit platforms as BIS management system standards mature for manufacturing compliance. The Reserve Bank of India mandates enhanced cybersecurity audits for payment system operators. Mumbai's financial institutions deploy risk management modules for multi-agency regulatory mapping.
Japan
Tokyo-based insurers and asset managers adopt workflow automation to address METI guidance on internal control standards for financial reporting. The Personal Information Protection Commission tightens audit trail requirements for cross-border data transfers. Osaka's manufacturing cluster integrates compliance tracking with JIS quality management certifications.
Audit Management Software Market Vendor Landscape
Player mix skews toward cloud-native specialists with disclosure management heritage and ERP-integrated incumbents with captive Fortune 500 demand. The market exhibits tiered concentration, with purpose-built risk platforms dominating mid-market segments while deep integration sustains positions among established providers. Three archetypes define competitive positioning: cloud-native workflow specialists, ERP-anchored incumbents, and compliance-focused challengers. Dominant competitive moves include portfolio diversification into algorithmic audit modules and strategic partnerships for MLOps monitoring capabilities.
Within the cloud-native specialist tier, Workiva leverages its disclosure management heritage to anchor positions in regulated industries, while AuditBoard exemplifies purpose-built risk platform differentiation for mid-market and large-enterprise segments. Oracle occupies a position among ERP-anchored incumbents competing through deep system integration that sustains captive demand.
| Leading Market Players |
|---|
| Workiva |
| Oracle |
| AuditBoard |
| DataSnipper |
| Vanta |
| Diligent |
| SAP |
| Onspring |
| MetricStream |
| Others |
Supply Flow & Price Mechanics
Cloud-native SaaS delivery displacing perpetual license models simultaneously redistributes vendor engineering resources toward multi-tenant architectures and compresses pricing premiums for on-premises customization. This substitution reshapes supply geography toward United States and Indian development centers while standardizing subscription economics across buyer tiers.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with ISO 19011-aligned platforms commanding subscription premiums from financial institutions facing SEC mandates. Three-tier pricing structure across premium, standard, and economy levels segments by integration depth and regulatory content library breadth. Cost compression in the mid-market tier intensifies because SaaS vendors bundle continuous compliance monitoring into base subscriptions. Healthcare providers exhibit highest price sensitivity due to constrained IT budgets, while multinational banks demonstrate lowest sensitivity given compliance failure costs.
Supply Chain Analysis
Just-in-time feature deployment through continuous integration pipelines dominates vendor development workflows, minimizing inventory of unreleased code modules. Engineering talent concentrates in the United States, India, and Ireland, with cloud infrastructure services drawing from Amazon Web Services, Microsoft Azure, and Google Cloud Platform. Single-source vulnerability in hyperscaler dependency creates concentration risk for multi-tenant platform availability. Distribution runs through direct enterprise sales teams supplemented by systems integrator partnerships for implementation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution by modular point solutions that unbundle workflow automation from comprehensive platforms, as mid-market buyers prioritize targeted functionality over integrated suites.
For Market Incumbents: Compound platform stickiness through deeper ERP integration that elevates switching costs for Fortune 500 accounts. Invest in MLOps monitoring certification to capture EU AI Act algorithmic audit demand before specialized challengers consolidate this module category. Channel control through exclusive systems integrator partnerships limits emerging vendor access to implementation capacity.
For New Entrants and Emerging Players: Mid-market healthcare providers underserved by complex enterprise platforms present immediate white-space opportunity. Target hospital systems with 500-2,000 beds lacking dedicated audit IT staff, offering pre-configured HIPAA content libraries with rapid deployment timelines. Go-to-market leverage through OCR compliance consultants who command trusted advisor status during surprise inspection preparation.
For Investors and Strategic Acquirers: Capital is best deployed toward cloud-native specialists with healthcare or algorithmic audit module certification and recurring revenue above subscription thresholds. Long-term viability hinges on continuous compliance monitoring convergence with ERP transaction streams. Watch for inflection when EU AI Act enforcement actions against high-risk automated systems exceed publicized thresholds, signaling accelerated algorithmic audit module procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Audit Module Certification | EU AI Act enforcement creates specialized demand for MLOps monitoring capabilities in Frankfurt and Paris financial clusters. |
| Healthcare Evidence Repository Expansion | OCR audit intensification drives automated documentation tools for hospital systems facing surprise HIPAA inspections. |
| ERP Native Integration Development | Deep Oracle and SAP interoperability sustains captive demand among Fortune 500 accounts with sunk system investments. |
| Continuous Control Monitoring Convergence | Real-time risk scoring integration with transaction streams compresses fieldwork timelines from weeks to days. |
| Private Cloud Deployment Architecture | GDPR cross-border data restrictions mandate single-tenant isolation for German and French financial institutions. |
Methodological Framework
A spread of perspectives from chief audit executives, compliance officers, platform engineers, and systems integrator partners converged on the working assumptions underlying this analysis. Primary interviews with these stakeholders combined with secondary validation against SEC disclosure filings, HIPAA enforcement action databases, EU regulatory guidance documents, and cloud vendor trust center documentation. Bottom-up deployment estimates and top-down regulatory mandate sizing were triangulated to establish market boundaries.
Segmentation dimensions modeled include deployment architecture, organization size tier, vertical regulatory intensity, integration complexity level, and regional adoption pattern across the analysis window. CAGRs were derived from regression analysis of historical procurement velocity against regulatory enforcement intensity indicators. Forecast inputs incorporated EU AI Act implementation timelines and OCR audit staffing expansion plans.
Forecasts assume regulatory continuity in SEC disclosure mandates, GDPR enforcement frameworks, and HIPAA audit protocols; material policy shifts would require re-modeling. Specific risks include algorithmic accountability standard divergence between EU and United States jurisdictions. Revision becomes warranted when multi-agency regulatory mapping complexity exceeds current workflow engine configuration capabilities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Neurodiverse Workforce Productivity Tools Market
Software & Services
Global Online Form Builder Software Market
Software & Services
Clustering Software Market
Software & Services
Sports League Management Software Market
Software & Services
Design Collaboration Software Market
Software & Services
Gym Management Software Market
Software & Services
Event Management Software Market
Software & Services
Global Software Composition Analysis Market
Software & Services
Professional Service Automation Market
Software & Services
File Analysis Software Market
Software & Services
Global Molecular Modeling Software for Chemistry Market
Software & Services
Inventory Management Software Market
Software & Services
Mobile Backend As a Service (Mbaas) Market
Software & Services
Global Electrical Computer-Aided Design (ECAD) Market
Software & Services
Live Chat Software Market
Software & Services
Global Customer Success Software Market