
 Global PPC Software Market | 2026-2036
Global PPC Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global PPC Software Market Foresight
Subscription-based SaaS pricing is rewriting competitive dynamics in pay-per-click software by lowering entry barriers for smaller advertisers. Google Ads leverages its search data monopoly to sustain dominance in keyword auction infrastructure. Microsoft Advertising anchors its position through Bing's integration with enterprise Microsoft 365 ecosystems. Criteo specializes in retargeting algorithms that compete for retail media budgets against Amazon Advertising's closed-loop commerce data.
Pay-per-click software comprises algorithmic platforms that automate bid placement, keyword discovery, and audience segmentation across search and display networks, typically processing millions of auction decisions per second through real-time bidding protocols. These systems serve advertisers seeking measurable return on ad spend through attribution-linked campaign execution. Cloud-based deployment leads segment adoption due to elastic scaling of auction processing capacity during peak retail events. Campaign automation represents the fastest-growing software type as machine learning reduces manual bid adjustment frequency. Analytics and reporting functions capture concentrated margin pools from enterprise clients demanding cross-channel attribution dashboards.
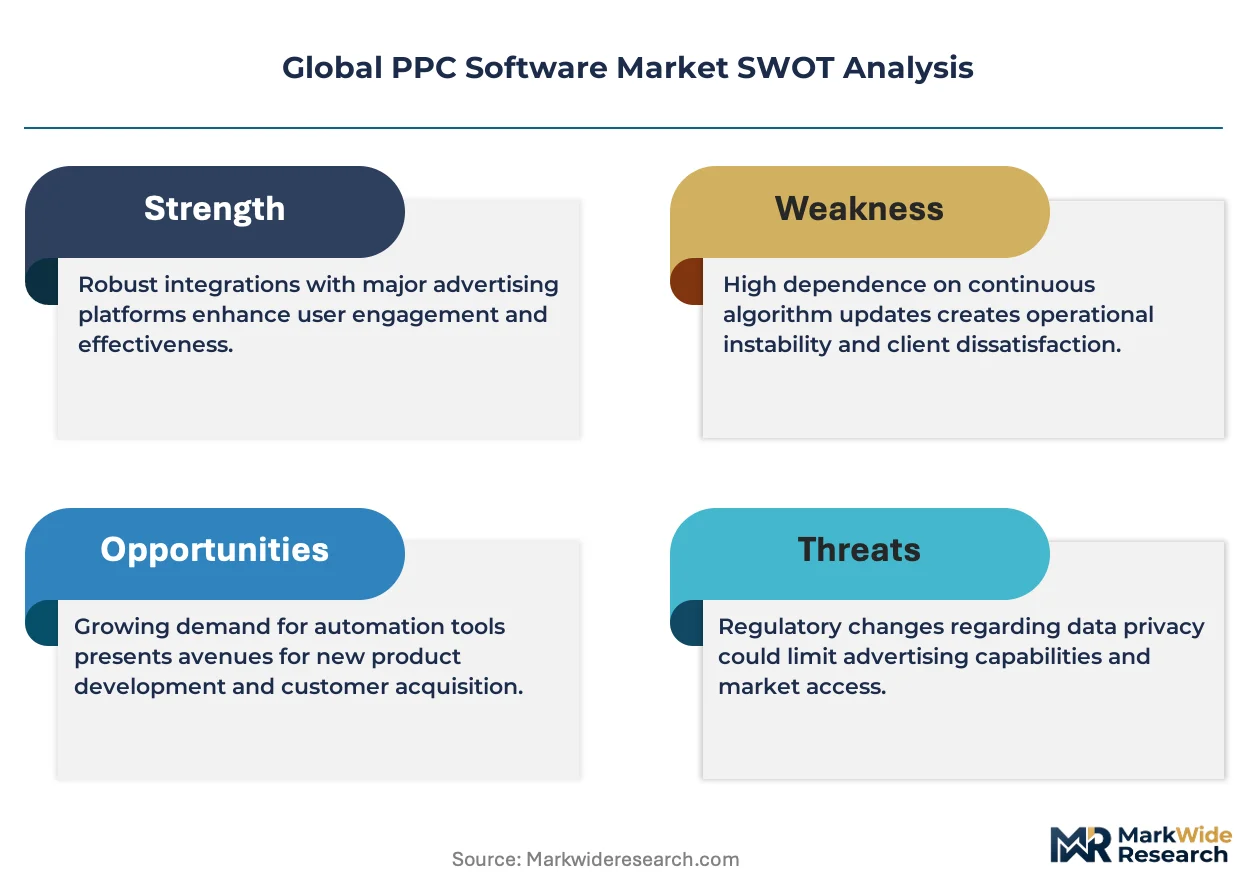
The EU AI Act imposes algorithmic transparency obligations on automated bidding systems deployed across European member states, compelling vendors to document decision logic for regulatory audits. The Federal Trade Commission in the United States scrutinizes opaque auction mechanics for potential anticompetitive effects in digital advertising markets. China's SAMR enforces data localization requirements that constrain cross-border bid data flows for platforms operating within its jurisdiction. Stakeholders must monitor divergence between algorithmic accountability regimes in Brussels and Washington to anticipate compliance architecture investments.
Market Dynamics
Algorithmic auction mechanics are concentrating competitive advantage among platforms with proprietary search data assets, while the EU AI Act forces disclosure of automated bidding logic that vendors previously treated as trade secrets.
Growth Catalysts
- Performance-based ad spending:E-commerce brands are reallocating fixed media budgets toward attribution-linked auction platforms that tie spend directly to conversion events.
- EU AI Act transparency mandates:Regulatory documentation requirements for automated decision systems are creating compliance service revenue streams for audit-ready bidding platforms.
- Elastic cloud infrastructure:Retail media networks during peak shopping events now scale auction processing capacity through serverless architectures.
Market Restraints
- Data localization barriers:China's SAMR enforces in-country bid data storage that fragments cross-border campaign orchestration for multinational advertisers.
- Search data concentration:Keyword auction infrastructure depends on proprietary query logs held by dominant search engines.
- Algorithmic opacity limits:Black-box machine learning models prevent advertisers from auditing why specific bid decisions occurred.
Strategic Opportunities
- Retail media expansion:Closed-loop commerce data from supermarket loyalty programs is enabling off-site sponsored product auctions outside Amazon's ecosystem.
- Connected TV convergence:Programmatic video ad platforms are integrating real-time bidding protocols from search into streaming inventory.
- India's digital ad tax incentives:Production-linked schemes for software exports are reducing effective platform development costs for vendors serving export markets.
Industry Challenges
- Cross-channel attribution engineering:Enterprises lack technical staff capable of stitching together identity graphs across walled garden platforms.
- Legacy API migration:Campaign management tools built on deprecated advertising platform interfaces face breaking changes without warning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global PPC Software Market |
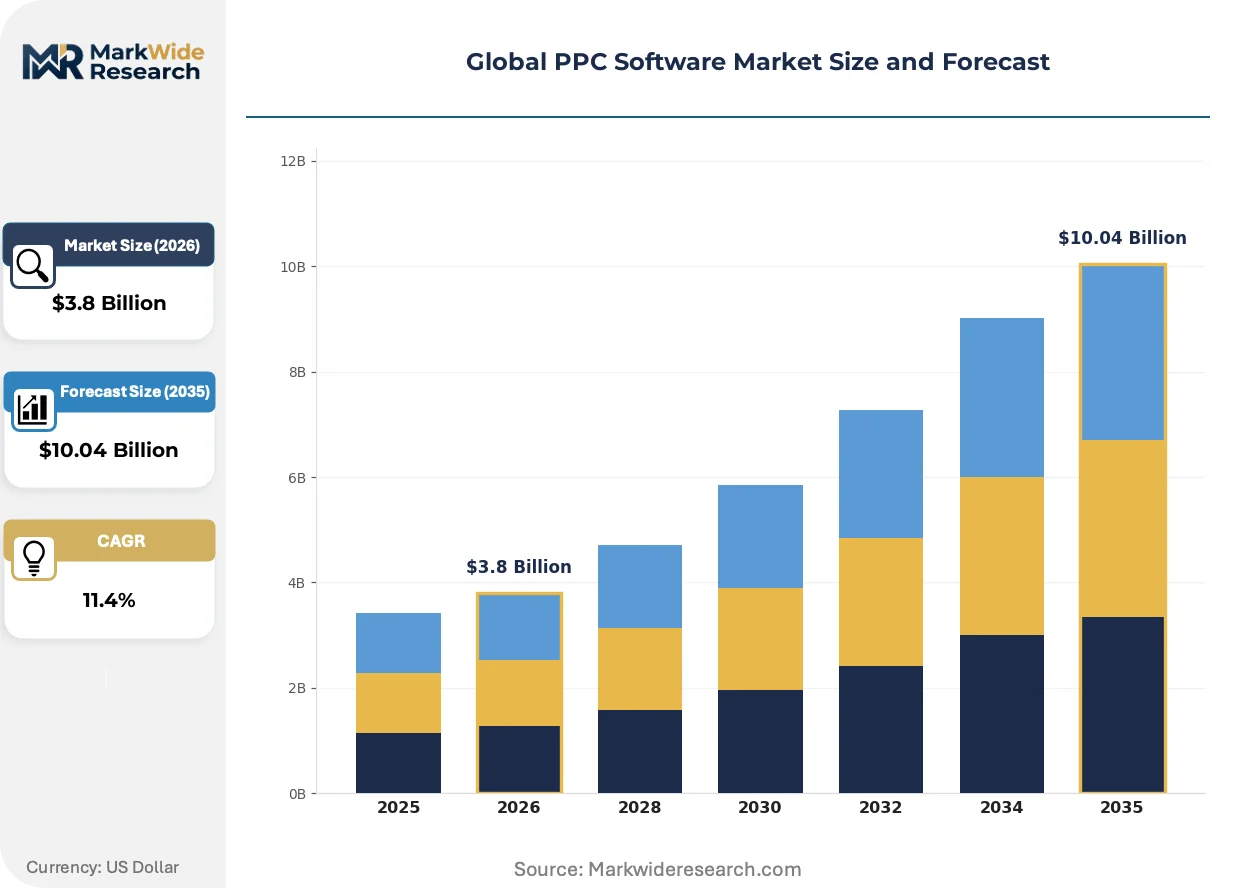
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Software Type: Bid Management, Keyword Research, Campaign Automation, Analytics & Reporting, Landing Page Optimization Deployment Mode: Cloud-Based, On-Premise, Hybrid, SaaS, Managed Services End User: Digital Agencies, E-Commerce Brands, Small & Medium Enterprises, Publishers, Affiliate Marketers Feature: Conversion Tracking, Competitor Analysis, Budget Management, Multi-Channel Management, Audience Targeting |
| Companies Covered | Meta Ads, AdRoll, Google Ads, Taboola, Criteo, Microsoft Advertising, LinkedIn Ads, Outbrain, Amazon Advertising, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global PPC Software Market Shifts & Advancements
Automation of creative optimization and auction participation is compressing the role of manual media buyers while expanding demand for machine learning operations specialists who can debug algorithmic performance drift.
First-price auction mechanics is migrating from header bidding in display advertising into search keyword auctions, altering how advertisers calculate marginal bid values. Mid-market agencies are retraining trading teams to model clearing price distributions rather than average position targets. This shift is compressing margin capture for intermediaries who previously arbitraged information asymmetries between buyers and inventory sources.
Brussels algorithmic accountability frameworks now require documentation of training data provenance and decision logic for automated bidding systems deployed across European member states. Vendors must maintain technical files subject to market surveillance authority inspection. Search advertising platforms serving EU-based advertisers are responding by segmenting European auction infrastructure from global systems to isolate compliance scope.
Agency remuneration structures are pivoting from percentage-of-spend commissions toward flat-fee optimization services as advertisers internalize auction platform access. Holding companies in Germany and the United Kingdom are unbundling media buying from strategic planning to retain margin as direct platform adoption accelerates. This restructuring is most visible among mid-sized e-commerce advertisers who previously relied on managed service layers for technical campaign execution.
Global PPC Software Market Segmentation
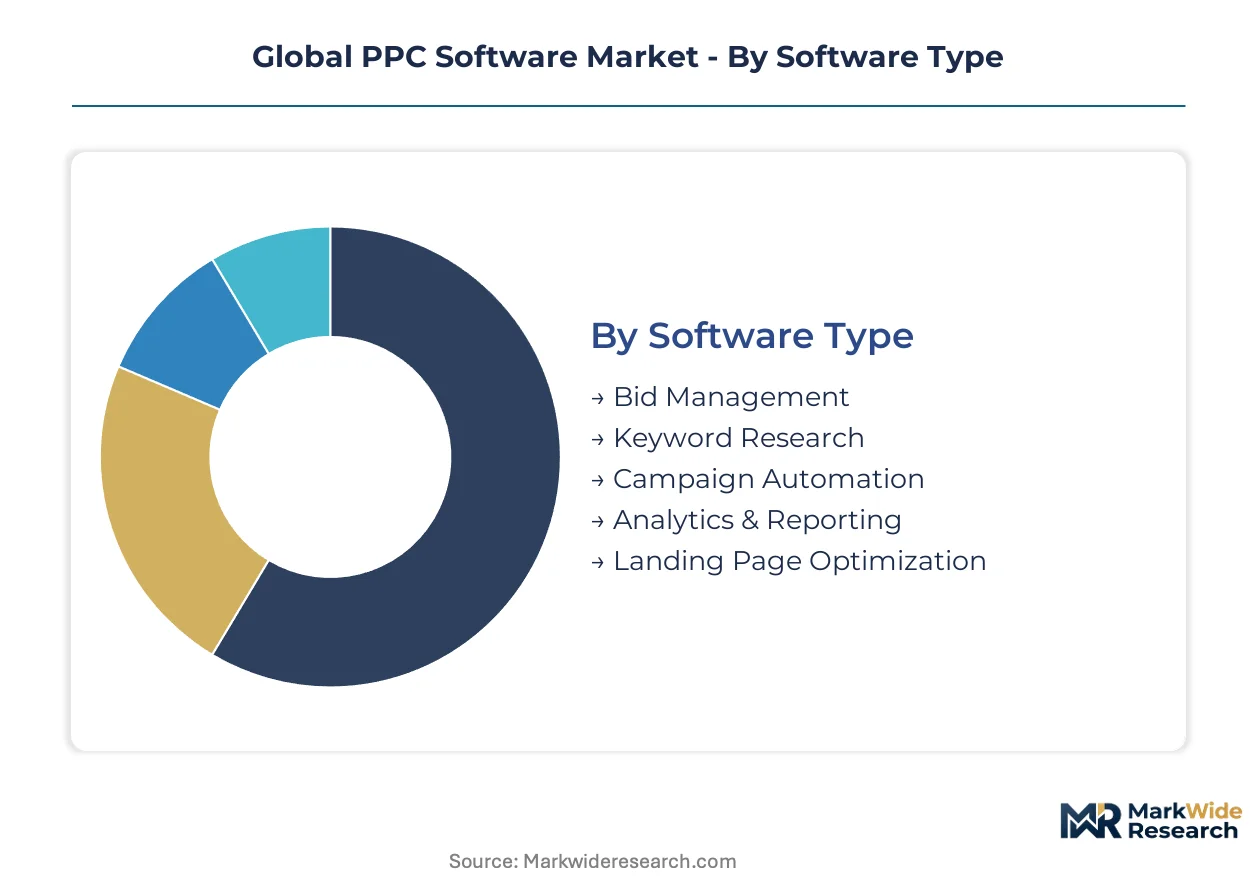
Segmentation in PPC software reveals how automation intensity varies across advertiser sophistication levels and infrastructure requirements. Deployment choices directly determine auction processing latency during high-volume retail events. Feature prioritization separates enterprise attribution demands from self-serve advertiser needs.
Software Type:
After-sales service intensity peaks with campaign automation platforms requiring continuous algorithm tuning and drift correction, while analytics modules demand quarterly business reviews for dashboard customization.
- Bid Management:Core auction participation engines execute real-time bid adjustments across search and display networks using predictive conversion models. Demand concentrates among mid-market e-commerce brands in the United States seeking margin protection during competitive keyword auctions.
- Campaign Automation:Machine learning systems reduce manual intervention frequency through automated budget pacing and creative rotation. E-commerce brands in Germany are expanding adoption fastest as EU AI Act documentation requirements favor vendors with audit-ready decision logs.
- Keyword Research:Query trend identification tools map search intent patterns to bidding opportunities.
- Analytics & Reporting:Cross-channel attribution dashboards serving enterprise procurement teams.
- Landing Page Optimization:Post-click experience testing integrated with quality score feedback loops.
By volume, bid management leads. By growth pace, campaign automation is ahead.
Deployment Mode:
Cost tier stratification separates elastic cloud consumption from fixed on-premise licensing, with hybrid architectures capturing mid-market advertisers balancing data sovereignty against processing scalability.
- Cloud-Based:Serverless auction processing architectures scale compute resources automatically during Black Friday and Prime Day traffic spikes. Digital agencies in India favor this model for production-linked incentive eligibility on software export revenues.
- SaaS:Subscription pricing lowers entry barriers for small advertisers through tiered feature access. Small and medium enterprises across multiple geographies are migrating fastest from perpetual licenses as platform APIs require continuous version compatibility.
- On-Premise:Dedicated infrastructure for financial services advertisers with internal compliance mandates.
- Hybrid:Split processing keeping bid data local while auction participation routes through cloud gateways.
- Managed Services:Vendor-operated campaign execution for advertisers lacking in-house trading expertise.
By volume, cloud-based deployments lead. By expansion trajectory, SaaS is climbing the fastest.
End User:
Customer type determines feature complexity requirements, with publishers needing supply-side auction tools distinct from demand-side advertiser platforms.
- Digital Agencies:Multi-client campaign orchestration platforms requiring consolidated billing and white-label reporting interfaces. Demand concentrates in the United Kingdom and Germany as holding companies unbundle media buying from strategic planning services.
- E-Commerce Brands:Direct-response focused tools tying every auction decision to attributable revenue events. These advertisers in India are expanding fastest through government digital infrastructure subsidies and export tax incentives.
- Small & Medium Enterprises:Simplified interfaces with automated recommendations replacing specialist trading knowledge.
- Publishers:Header bidding and private marketplace tools for inventory yield optimization.
- Affiliate Marketers:Commission-tracking integration with network attribution systems.
By volume, digital agencies lead. By growth pace, e-commerce brands are gaining share fastest.
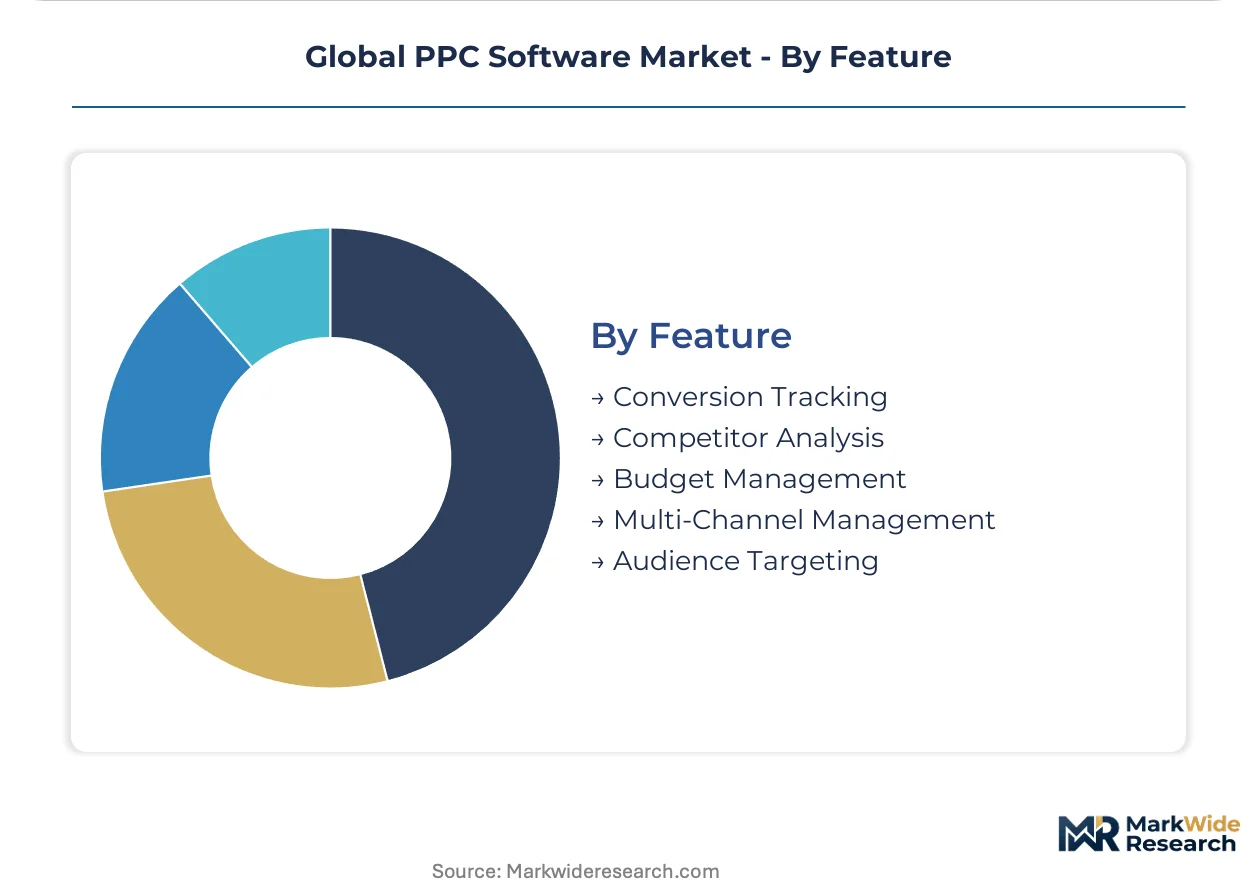
Feature:
Margin concentration follows feature sophistication, with multi-channel management commanding premium pricing from enterprises operating across walled garden platforms.
- Conversion Tracking:Attribution pipelines linking ad impressions to checkout events through pixel and server-side measurement. E-commerce brands in the United States demand this capability most intensely as performance-based spending replaces fixed media commitments.
- Audience Targeting:Identity graph construction for lookalike modeling and remarketing list management. Digital agencies in Germany are prioritizing this feature fastest ahead of EU AI Act enforcement on automated decision documentation.
- Competitor Analysis:Auction insight tools revealing rival bidding patterns and share of voice metrics.
- Budget Management:Automated pacing rules preventing overspend during high-traffic periods.
- Multi-Channel Management:Unified campaign execution across search, social, and retail media networks.
By volume, conversion tracking leads. By growth pace, audience targeting is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in PPC software tilt toward service outflows from the United States, United Kingdom, and India, while Germany and China balance domestic platform development against foreign vendor adoption. Net exporters leverage cloud infrastructure subsidies and software tax incentives to capture cross-border digital advertising spend.
United States
Enterprise advertisers in retail and financial services drive concentrated demand for cross-channel attribution dashboards. The FTC scrutinizes opaque auction mechanics for potential anticompetitive effects in digital advertising markets. Silicon Valley clusters anchor development of serverless auction processing architectures that scale automatically during peak retail events.
Germany
Mid-market e-commerce brands are unbundling media buying from strategic planning services, accelerating direct platform adoption. The EU AI Act imposes algorithmic transparency obligations on automated bidding systems deployed across European member states. Berlin and Munich host holding companies restructuring agency remuneration toward flat-fee optimization services.
India
Government digital infrastructure subsidies and export tax incentives are reducing effective platform development costs for vendors serving overseas markets. The PLI scheme for software exports rewards cloud-based deployment models favored by digital agencies. Bangalore and Hyderabad clusters concentrate campaign automation engineering talent for global SaaS delivery.
China
SAMR enforces data localization requirements that constrain cross-border bid data flows for multinational advertisers operating within its jurisdiction. Domestic retail media networks leverage closed-loop commerce data from supermarket loyalty programs for off-site sponsored product auctions. Shanghai and Shenzhen anchor development of proprietary auction infrastructure isolated from global systems.
United Kingdom
Digital agencies serving multi-client portfolios demand consolidated billing and white-label reporting interfaces. GDPR compliance architectures influence feature development for audience targeting and identity graph construction. London concentrates demand for analytics and reporting functions from enterprise procurement teams seeking cross-channel attribution dashboards.
Global PPC Software Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in auction mechanics and attribution pipelines. Search advertising infrastructure concentrates among data-rich incumbents with proprietary query logs, while mid-tier vendors fragment across retargeting algorithms and retail media tools. Two strategic archetypes dominate: closed-loop commerce platforms leveraging first-party transaction data, and independent software vendors selling audit-ready automation to compliance-conscious advertisers. Competitive moves center on geographic segmentation of auction infrastructure to isolate regulatory scope, and unbundling of agency services to capture margin from direct advertiser platform adoption.
Within the search infrastructure archetype, Google Ads and Microsoft Advertising occupy positions defined by data access and enterprise ecosystem integration. Criteo exemplifies the retargeting specialist tier competing for retail media budgets. These three entities represent contrasting strategic postures: query-log dependence, productivity-suite anchoring, and algorithmic specialization respectively.
| Leading Market Players |
|---|
| Meta Ads |
| AdRoll |
| Google Ads |
| Taboola |
| Criteo |
| Microsoft Advertising |
| LinkedIn Ads |
| Outbrain |
| Amazon Advertising |
| Others |
Supply & Pricing Matrix
Overcapacity in cloud auction processing infrastructure across India and the United States compresses margins for SaaS vendors while simultaneously enabling aggressive tiered pricing for mid-market advertisers seeking elastic compute during peak retail events.
Pricing Analysis
Small and medium enterprises anchor subscription-based SaaS pricing as the dominant model, with three-tier pricing structure across premium, standard, and economy levels differentiating by feature depth and API call volume. Price differentiation rests on audit-readiness certification for EU AI Act compliance and cloud scalability guarantees during traffic spikes. Cost compression in the economy tier intensifies because Indian digital agencies exploit production-linked incentives to undercut global competitors. E-commerce brands show least price sensitivity for campaign automation modules, while affiliate marketers demand lowest entry points.
Supply Chain Analysis
Extended payment terms from hyperscaler cloud providers anchor working capital structures for PPC software vendors, enabling deferred infrastructure costs until advertiser subscription revenue materializes. Engineering talent concentrates in India, the United States, and Germany, with machine learning operations specialists commanding premium compensation. Raw material dependencies include GPU compute clusters, proprietary search query licensing, and identity graph data partnerships. Single-source vulnerability sits with Google Ads auction API access, which dominates keyword auction infrastructure. Distribution runs through direct SaaS portals and digital agency channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Performance-based ad spending migration represents an early-cycle expansion story, with e-commerce brands internalizing auction platform access faster than historical managed-service adoption curves predicted.
For Market Incumbents: Harden algorithmic audit trails to preempt EU AI Act enforcement actions against opaque bidding models. Fortify data localization architectures in China to satisfy SAMR requirements without fragmenting global campaign orchestration. Prioritize certification investment for algorithmic transparency documentation.
For New Entrants and Emerging Players: Establish a beachhead in retail media automation outside Amazon's closed-loop ecosystem, where supermarket loyalty program data enables off-site sponsored product auctions. Target Germany's mid-market e-commerce segment, where unbundling of agency services creates direct platform adoption appetite. Lead with flat-fee optimization positioning against percentage-of-spend incumbents.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among campaign automation vendors serving EU-regulated advertisers, where compliance documentation requirements create sticky switching costs. Five-to-ten year viability favors platforms with proprietary identity graph assets or search data partnerships. Watch for FTC antitrust action against opaque auction mechanics as an inflection signal for regulatory-forced transparency investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Audit Trail Investment | EU AI Act documentation requirements create compliance moats for audit-ready vendors serving European advertisers. |
| Retail Media Platform Integration | Supermarket loyalty program data partnerships unlock off-site sponsored product auctions beyond Amazon's ecosystem. |
| Cloud Infrastructure Geographic Segmentation | Isolating European auction processing from global systems limits regulatory compliance scope and audit exposure. |
| Agency Service Unbundling | Separating media buying from strategic planning captures margin from direct advertiser platform adoption in Germany and the United Kingdom. |
| Machine Learning Operations Talent Acquisition | MLops specialists command premium compensation for debugging algorithmic performance drift in automated bidding systems. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with PPC platform product managers, digital agency trading directors, e-commerce marketing executives, and cloud infrastructure procurement officers. Secondary validation drew from SEC filings of advertising technology vendors, EU regulatory documentation databases, hyperscaler capex disclosures, and customs records of software export flows. Bottom-up triangulation across advertiser spend patterns and top-down reconciliation against aggregate digital advertising market estimates anchored value projections.
Calibration against historical adoption curves for marketing automation software informed growth trajectory assumptions across the projection horizon. Segmentation dimensions modeled include deployment architecture, organization size tier, vertical industry, integration complexity with walled garden platforms, and regional regulatory cluster. CAGRs were derived from slope analysis of comparable software category maturation patterns, with inputs from cloud infrastructure capacity expansion timelines and retail media network auction volume growth.
Sensitivities concentrate around EU AI Act enforcement timing, FTC antitrust action against opaque auction mechanics, and China's SAMR data localization expansion. Forecasts reflect documented assumptions regarding performance-based budget migration velocity and cloud infrastructure cost curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
United States IT Services Market
Software & Services
Cursor Reviewer Market
Software & Services
Movie Editing Software Market
Software & Services
Know Your Customer Software Market
Software & Services
Global Furniture Manufacturing Software Market
Software & Services
Embroidery Design Software Market
Software & Services
Global Rapid Application Development Market
Software & Services
Backend-As-A-Service Market
Software & Services
Exercise and Weight Loss Apps Market
Software & Services
Ad Creation Software Market
Software & Services
Software Testing Company Market
Software & Services
Software-Defined Machine Market
Software & Services
LTFS Copy Software Market
Software & Services
Contract Lifecycle Management (CLM) Solution Market
Software & Services
Braking Systems Software Market
Software & Services
Global Digital Experience Management Software Market