
 Global Legal Case Management Software Market | 2026-2036
Global Legal Case Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Legal Case Management Software Market Foresight
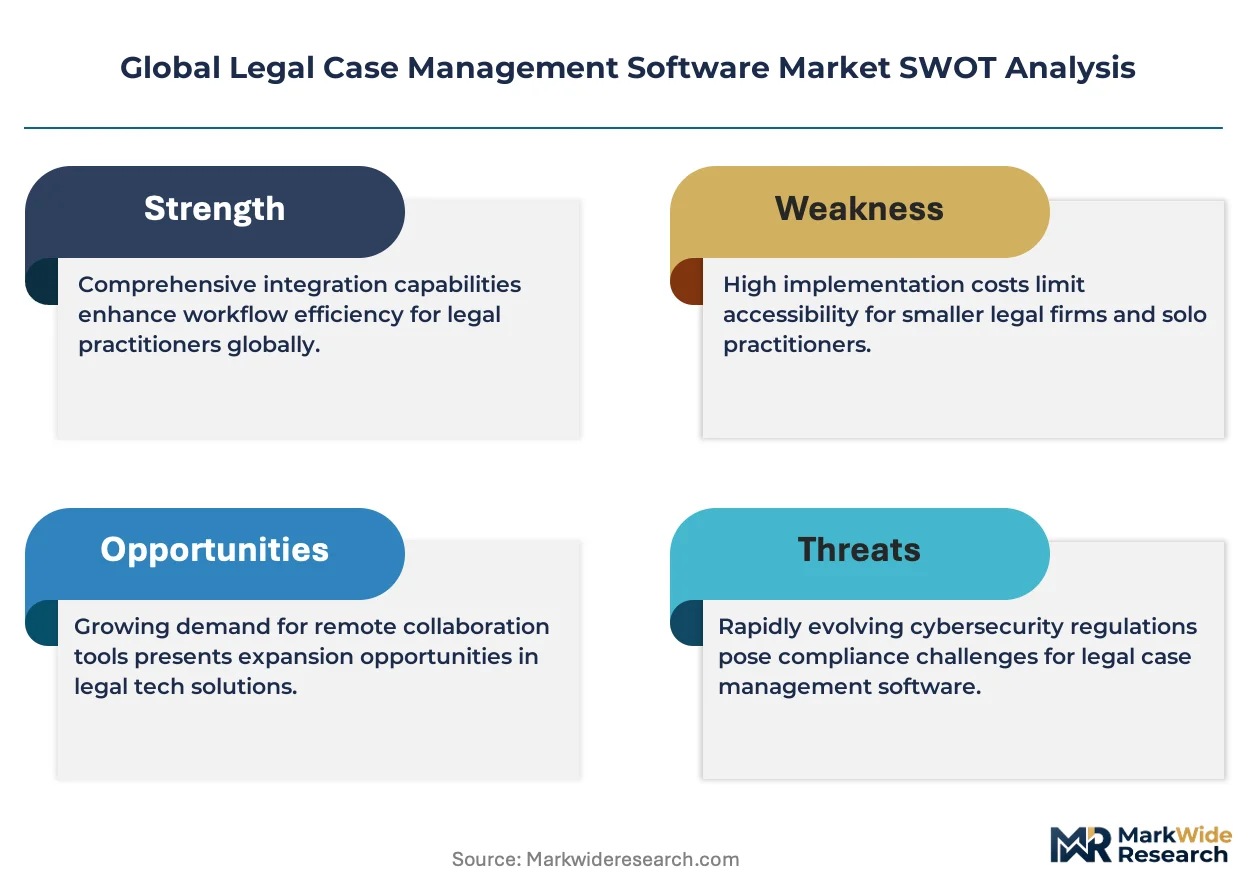
Buyer concentration among mid-sized law firms is rebalancing toward corporate legal departments and government agencies seeking centralized matter oversight. Clio leverages its cloud-native architecture to dominate solo and small-firm segments across North America. Thomson Reuters anchors enterprise-grade deployments through integrated research and compliance modules. Smokeball competes on workflow automation depth for plaintiff-focused practices in Australia and the United Kingdom.
Legal case management software orchestrates matter lifecycle operations through structured databases, automated calendaring, and rules-based deadline compliance tied to court-specific procedural requirements. These systems reduce malpractice exposure while enabling real-time collaboration between attorneys, clients, and external counsel. Cloud-based deployment leads solution offering penetration due to lower capital barriers and automatic regulatory update propagation, while on-premises installations retain footholds where data residency statutes restrict cross-border hosting. Document management and workflow automation capture the largest margin pools as law firms prioritize efficiency over standalone time-tracking tools. Litigation management and contract lifecycle management represent the fastest-expanding use cases as regulatory enforcement intensifies across financial services and healthcare sectors.
The EU AI Act and GDPR constrain automated decision-making in European legal tech deployments, compelling vendors to engineer human-in-the-loop validation architectures. The SEC and FDA in the United States drive demand for audit-ready compliance management trails within corporate counsel platforms. Stakeholders must monitor evolving data localization requirements across Brazil, China, and Saudi Arabia as these jurisdictions draft sector-specific legal tech governance frameworks that will determine market access terms for international software providers.
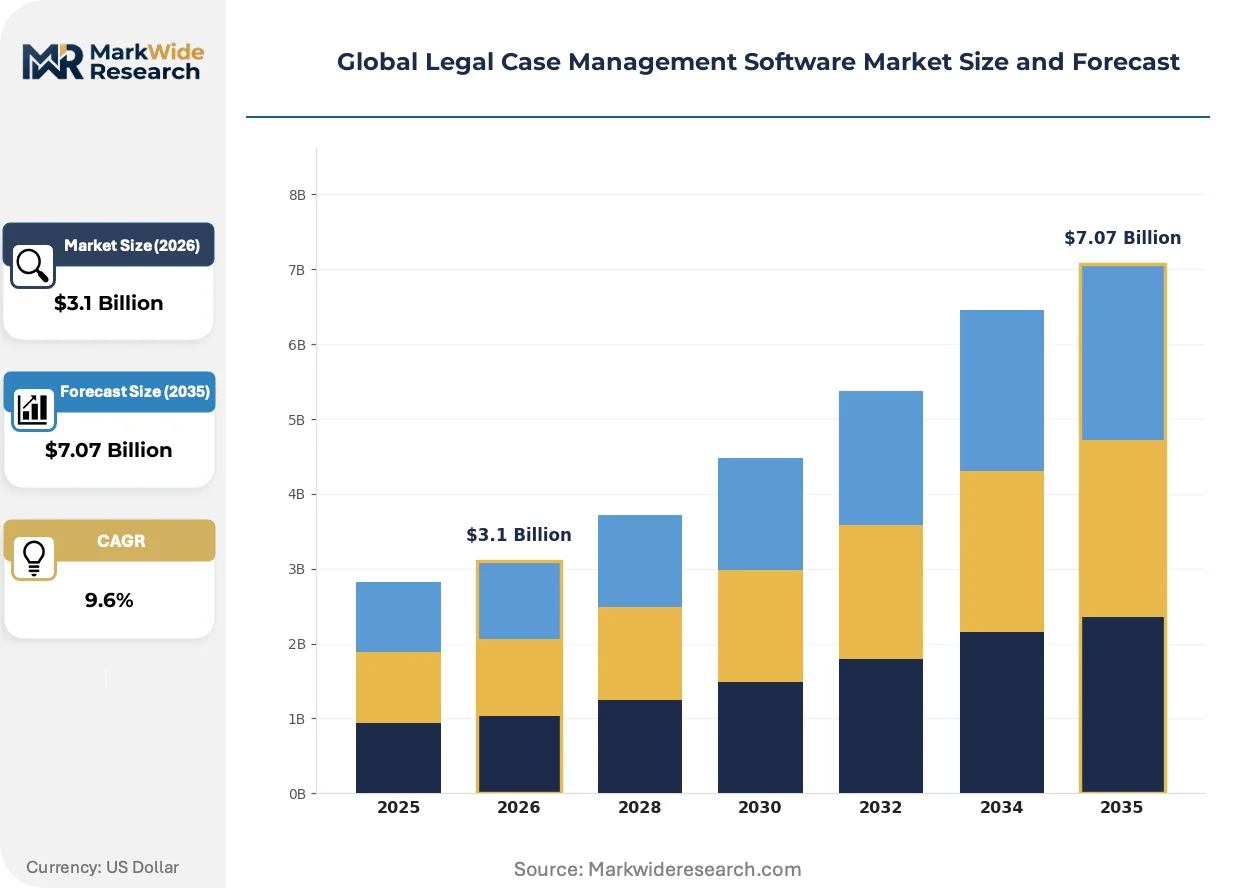
Market Dynamics
Cloud-native architectures are compressing deployment cycles while data sovereignty mandates in Germany, Singapore, and Brazil force vendors to re-engineer hosting infrastructure for jurisdictional compliance.
Growth Catalysts
- SEC audit-trail mandates:Corporate legal departments in the United States must maintain immutable compliance records, driving platform upgrades for litigation management and contract lifecycle oversight.
- Healthcare sector enforcement:FDA oversight of promotional materials and adverse event reporting compels pharmaceutical legal teams to automate matter tracking and deadline compliance.
- Generative AI integration:Natural language processing tools are accelerating document review and contract analysis, reducing attorney hours on routine discovery tasks.
Market Restraints
- Cross-border data friction:China's data localization statutes and Saudi Arabia's emerging cloud governance frameworks block SaaS providers from serving multinational clients through centralized hosting.
- Legacy system entrenchment:Large law firms face switching costs exceeding eighteen months for full data migration from on-premises matter management databases.
- Specialized talent scarcity:Vendors struggle to hire legal engineers who combine domain expertise with cloud architecture skills, inflating implementation timelines.
Strategic Opportunities
- India's digital court initiative:The country's e-Courts project creates demand for case filing automation and virtual hearing integration among domestic litigation practices.
- Convergence of CLM and matter management:Contract lifecycle platforms are absorbing dispute resolution workflows, opening cross-sell paths for vendors with existing corporate relationships.
- Outcome-based pricing models:Subscription tiers tied to matter outcomes rather than seat counts are penetrating mid-market corporate legal departments seeking cost predictability.
Industry Challenges
- GDPR Article 22 compliance:European deployments require human-in-the-loop validation for any automated case prioritization or document classification, complicating AI feature roadmaps.
- Multi-jurisdictional certification lag:Vendors must secure separate approvals from Germany's KBA-equivalent data authorities and France's CNIL before launching unified EU platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Legal Case Management Software Market |
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $7.07 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS, Hosted Solution Offering: Document Management, Workflow Automation, Time Tracking, Billing Management, Client Collaboration Use Case: Litigation Management, Contract Lifecycle Management, Intellectual Property, Compliance Management, Case Research End User: Legal Firms, Corporate Counsels, Government Agencies, Legal Process Outsourcing, Solo Practitioners |
| Companies Covered | Clio, Smokeball, MyCase, PracticePanther, Filevine, CosmoLex, AbacusLaw, Actionstep, Thomson Reuters, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Legal Case Management Software Market Shifts & Advancements
Artificial intelligence is rewriting workflow automation while regulatory fragmentation forces architectural compromises. Vendors now compete on inference speed and explainability rather than feature breadth alone.
Large language models are expanding into contract analysis and deposition preparation, with corporate legal departments in the United States adopting these tools fastest. Mid-sized firms lag due to confidentiality concerns, creating a bifurcation between early adopters and risk-averse holdouts. The technology is expanding into predictive matter budgeting, compressing the advantage of traditional hourly billing models.
The EU AI Act's risk classification system subjects legal tech automation to conformity assessments when supporting judicial decision-making. Vendors must document training data provenance and algorithmic transparency for high-risk deployments. German legal departments are responding by demanding on-premise inference to limit third-party data exposure.
Corporate procurement teams now mandate API-first architecture and pre-built connectors to existing ERP systems, displacing standalone platforms. Law firms serving financial services clients face the strictest integration requirements, with SOC 2 Type II certification becoming table stakes. Australia and the United Kingdom show the fastest procurement cycle compression, with average vendor selection timelines falling below ninety days.
Global Legal Case Management Software Market Segmentation
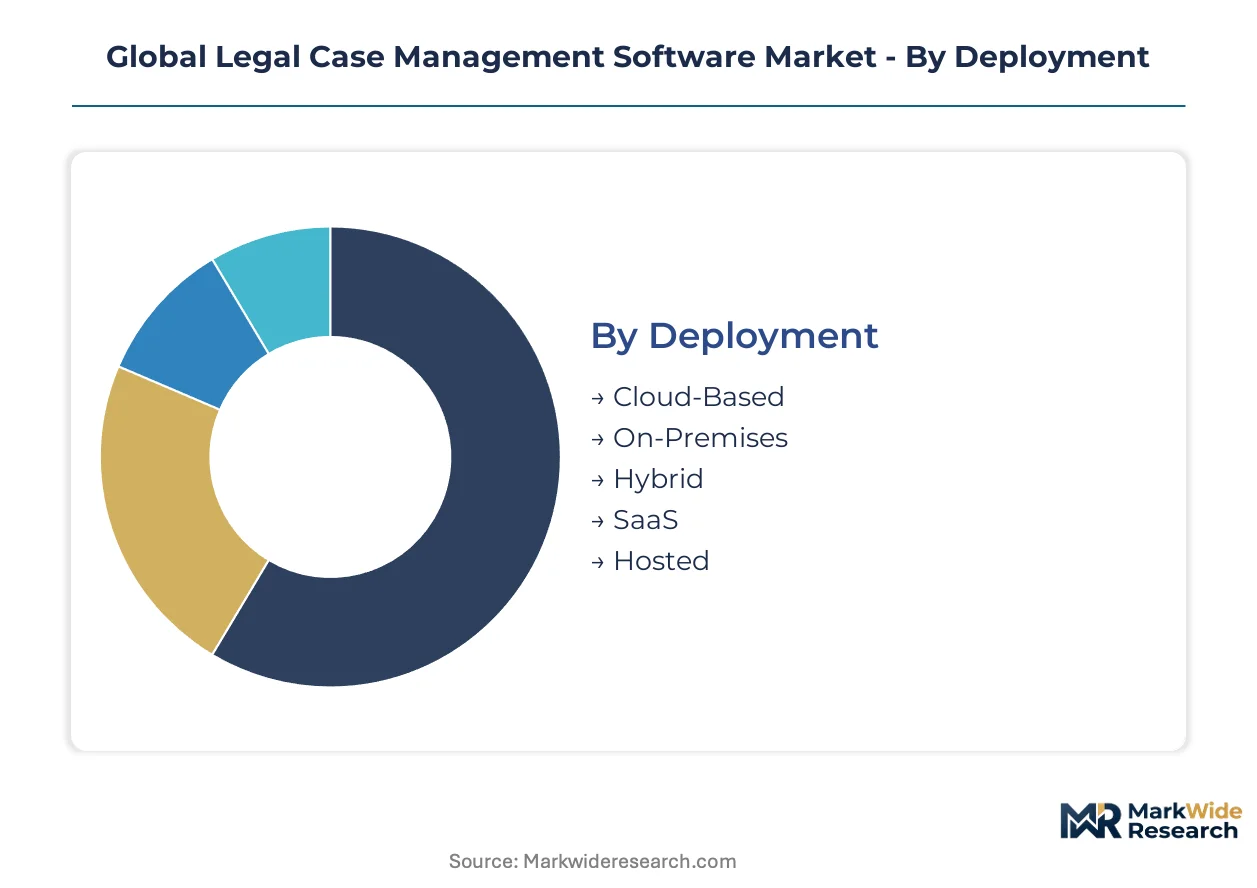
Segmentation reveals how procurement priorities diverge between capital-constrained solo practitioners and compliance-heavy corporate legal departments. Deployment models and solution architectures must align with jurisdictional data residency mandates and matter complexity tiers.
Deployment:
Capital intensity peaks with on-premises infrastructure requiring dedicated server farms and in-house IT staffing.
- Cloud-Based:Multi-tenant architectures eliminate hardware procurement and shift expenditure to operational budgets. Corporate legal departments in the United States and United Kingdom favor this model for automatic security patching and elastic scaling during discovery surges.
- On-Premises:Self-hosted deployments demand significant upfront capital for servers, cooling systems, and perpetual license fees. Germany's KBA-equivalent data authorities and Saudi Arabia's emerging cloud governance frameworks compel this choice where cross-border hosting faces statutory prohibition.
- Hybrid:Split architectures isolate sensitive client matter on local servers while pushing routine calendaring to cloud nodes. Australian financial services legal teams adopt this configuration to satisfy APRA oversight while retaining collaboration flexibility.
- SaaS:Subscription delivery abstracts all infrastructure management to vendors, compressing procurement cycles below ninety days in the United Kingdom and Australia. Solo practitioners and small plaintiff firms gravitate here for predictable monthly outlays.
- Hosted:Single-tenant private cloud deployments offer dedicated instances without capital ownership burdens. Singapore's data sovereignty requirements and Brazil's sector-specific localization statutes drive demand among multinational corporate counsel.
Most installed capacity flows through Cloud-Based deployments. Expansion is steepest in Hosted configurations as data localization statutes proliferate.
Solution Offering:
Margin concentration follows workflow automation depth rather than commoditized time-tracking utilities.
- Document Management:Version-controlled repositories with OCR indexing and privilege tagging form the technical backbone of matter organization. Litigation practices in the United States prioritize these systems to manage discovery volumes running into terabytes.
- Workflow Automation:Rules engines orchestrate deadline compliance against court-specific procedural rules, integrating directly with e-filing portals. Plaintiff-focused practices in Australia and the United Kingdom deploy these tools to reduce malpractice exposure on limitation dates.
- Time Tracking:Mobile-enabled capture tools record billable activity against matter codes with automatic narrative generation. Solo practitioners rely on lightweight implementations while enterprise legal departments demand ERP integration.
- Billing Management:LEDES-compliant invoice generation and alternative fee arrangement modeling support complex pricing structures. Mid-sized firms serving insurance defense panels require these capabilities for claims compliance.
- Client Collaboration:Secure portals enable document exchange and status visibility without email vulnerability. Corporate counsels mandate these interfaces to demonstrate transparency to internal business stakeholders.
Revenue pools concentrate in Workflow Automation and Document Management. Client Collaboration tools are gaining share fastest as corporate procurement teams mandate external-facing transparency.
Use Case:
Application complexity scales with regulatory enforcement intensity across financial services and healthcare verticals.
- Litigation Management:End-to-end matter lifecycle platforms integrate docketing, document production, and trial preparation workflows. SEC audit-trail mandates and FDA oversight of pharmaceutical promotional materials drive corporate legal department investment in the United States.
- Contract Lifecycle Management:Repository, negotiation, and obligation management tools now absorbing dispute resolution modules. Convergence with matter management creates cross-sell opportunities for vendors with existing corporate relationships.
- Intellectual Property:Docketing systems tracking prosecution deadlines across multiple patent offices with annuity payment integration. Technology sector legal teams in the United States and Germany deploy specialized implementations.
- Compliance Management:Regulatory change tracking and policy attestation workflows with board-ready reporting dashboards. Healthcare sector enforcement and EU AI Act conformity assessments elevate procurement priority.
- Case Research:Knowledge management platforms organizing prior work product and judicial analytics. Large law firms maintain these investments despite generative AI displacement pressure on standalone research tools.
Current deployments concentrate in Litigation Management. Contract Lifecycle Management is climbing the fastest as platforms converge with broader legal operations infrastructure.
End User:
Procurement authority is shifting from traditional law firm IT committees to corporate legal operations functions.
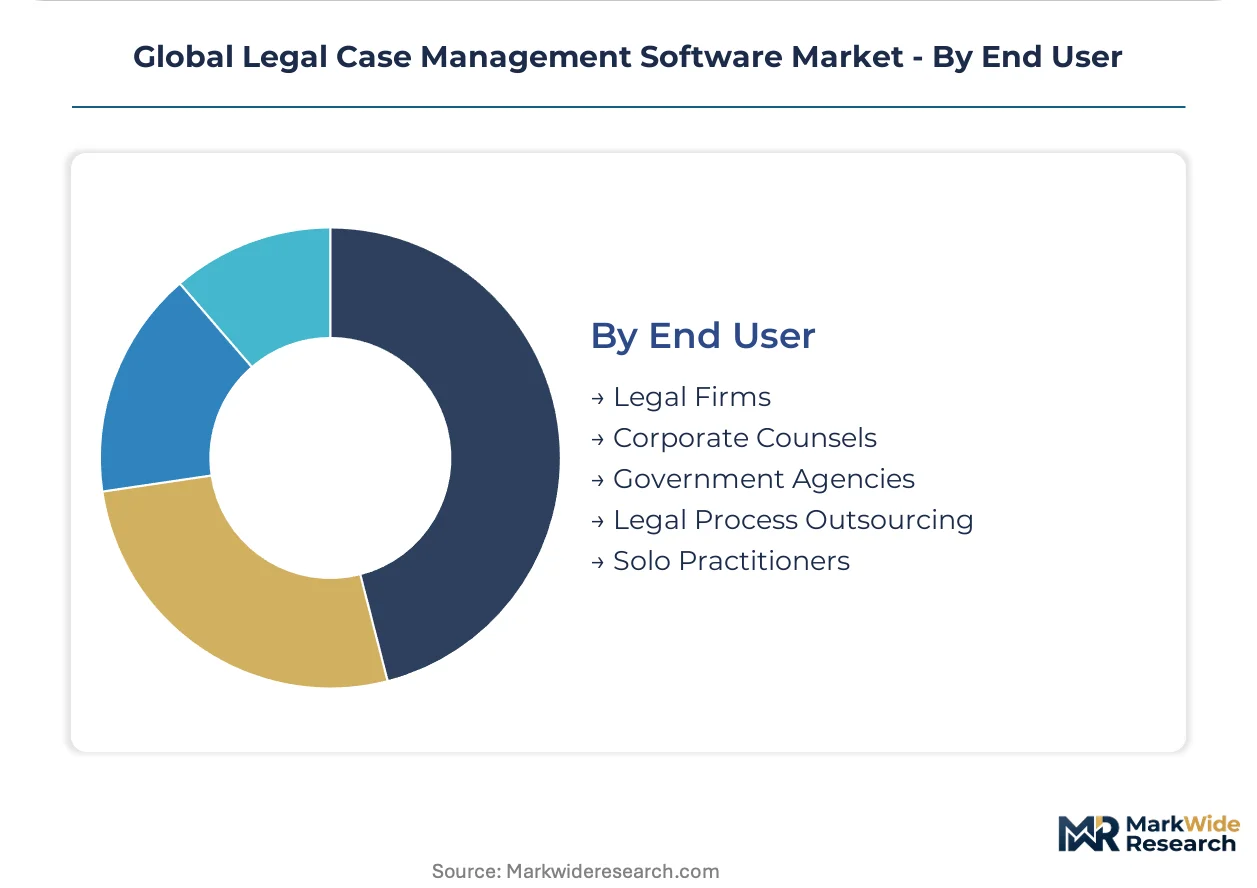
- Legal Firms:Partnership-governed technology decisions favor proven solutions with established peer references. Large firms face eighteen-month switching costs for legacy database migrations.
- Corporate Counsels:Centralized legal operations teams mandate API-first architecture and pre-built ERP connectors. SOC 2 Type II certification has become non-negotiable for financial services sector engagements.
- Government Agencies:Public procurement frameworks and security clearance requirements extend sales cycles. India's e-Courts project and similar digital court initiatives are creating demand for case filing automation.
- Legal Process Outsourcing:Volume-driven providers prioritize document review and contract abstraction tools with throughput metrics. Cost-per-matter pricing models dominate vendor selection.
- Solo Practitioners:Price-sensitive buyers favor cloud-native solutions with minimal configuration overhead. Clio dominates this segment across North America through mobile-first design and bar association partnerships.
Seat concentration remains with Legal Firms. Corporate Counsels are expanding procurement fastest as in-house legal operations mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Legal engineers cluster in the United States, the United Kingdom, and Australia, anchoring platform development while data sovereignty mandates in Germany and Singapore force infrastructure localization.
United States
Corporate legal departments in New York and Washington D.C. drive procurement for SEC audit-trail compliance and FDA-regulated healthcare enforcement. The SEC mandates immutable litigation records, compelling platform upgrades. Silicon Valley vendors cluster in San Francisco and Palo Alto, shipping cloud-native architectures to mid-market firms.
United Kingdom
London-based financial services legal teams demand SOC 2 Type II certification and API-first ERP integration. The Solicitors Regulation Authority enforces strict professional indemnity protocols. The City of London and Canary Wharf concentrate compliance-heavy deployments among multinational corporate counsel.
Germany
Munich and Frankfurt legal departments prioritize on-premise inference to satisfy GDPR Article 22 human-in-the-loop requirements. The KBA-equivalent data authorities enforce strict cross-border hosting prohibitions. Baden-Württemberg automotive legal teams deploy localized matter management for supply chain dispute resolution.
Australia
Sydney and Melbourne plaintiff firms automate workflow compliance against court-specific procedural rules. APRA oversight compels hybrid architectures among financial services legal teams. Brisbane and Perth practices adopt cloud calendaring while isolating sensitive client matter locally.
Singapore
Marina Bay corporate counsel mandate hosted single-tenant deployments to satisfy data sovereignty requirements. The Personal Data Protection Commission enforces strict localization for cross-border matter hosting. Raffles Place legal operations teams consolidate regional APAC dispute resolution through centralized platforms.
Global Legal Case Management Software Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across deployment tiers. The market structures around three strategic archetypes: cloud-native disruptors serving solo practitioners, integrated research-platform vendors anchoring enterprise accounts, and workflow automation specialists penetrating plaintiff-focused practices. Dominant competitive moves include geographic infrastructure localization for data sovereignty compliance and generative AI feature integration for document acceleration.
Within the cloud-native tier, Clio and Smokeball exemplify divergent specialization paths. Clio anchors North American small-firm penetration through mobile-first design. Smokeball occupies a position among Australia and United Kingdom plaintiff practices prioritizing deadline automation depth. Thomson Reuters sits within the enterprise tier, representing integrated research and compliance module bundling for corporate legal departments.
| Leading Market Players |
|---|
| Clio |
| Smokeball |
| MyCase |
| PracticePanther |
| Filevine |
| CosmoLex |
| AbacusLaw |
| Actionstep |
| Thomson Reuters |
| Others |
Supply & Pricing Matrix
Legal engineering talent clusters in the United States, the United Kingdom, and Australia, with labor-cost differentials between San Francisco and Bangalore widening pricing-tier spreads across deployment models. Cloud-native vendors absorb premium engineering salaries into per-seat subscriptions while offshore development centers enable aggressive entry-level pricing for solo practitioner tiers.
Pricing Analysis
Bundled research-and-compliance modules command enterprise premiums against unbundled workflow-automation tools serving mid-market firms. Three-tier pricing structure across premium, standard, and economy levels separates SOC 2 Type II-certified platforms from basic calendaring utilities. Pricing pressure stems from open-source document management alternatives compressing margins in the economy tier. Corporate legal departments show lowest price sensitivity due to compliance mandate urgency, while solo practitioners migrate aggressively toward freemium entry points.
Supply Chain Analysis
Returns and refurbishment flows remain minimal in pure software delivery, though data center hardware refresh cycles create secondary markets for decommissioned server infrastructure. Supply concentrates in the United States for hyperscale cloud compute, Ireland and Singapore for regional data residency compliance, and India for engineering talent pipelines. Raw material dependencies span semiconductor fabrication capacity, rare earth elements for storage arrays, and fiber optic cable infrastructure. Single-source vulnerability sits with Taiwan-based chip fabrication for AI inference accelerators. Distribution runs through direct vendor sales teams for enterprise accounts and bar association partnerships for small-firm penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as corporate procurement teams mandate API-first architecture and pre-built ERP connectors, shifting demand decisively toward premium specifications. Compliance-heavy deployments now dominate vendor selection criteria over standalone feature breadth.
For Market Incumbents: Deepen vertical integration into specialized legal engineering talent pipelines through university partnerships and certification academies. Defend margin position by accelerating generative AI feature roadmaps before open-source alternatives commoditize document review workflows. Prioritize Germany and Singapore infrastructure localization to preempt data sovereignty mandates from locking out multinational accounts. For New Entrants and Emerging Players: The mid-market price-point gap between Thomson Reuters enterprise bundles and Clio small-firm tiers offers white-space opportunity for workflow automation specialists. Target Australia's plaintiff-focused practices and India's e-Courts digitization initiative where incumbent presence remains thin. Pursue channel partnerships with legal process outsourcing providers to secure volume-driven reference accounts without direct enterprise sales infrastructure. For Investors and Strategic Acquirers: Corporate legal operations functions are the most active acquirer in this space, consolidating point solutions into integrated platforms. Five-to-ten year viability favors vendors with existing ERP connector libraries and compliance certification depth over pure-play AI feature startups. Monitor FDA and SEC enforcement intensity as the inflection indicator for healthcare and financial services vertical expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Geographic Infrastructure Localization | Hosted deployments in Germany satisfy KBA-equivalent data authorities and unlock enterprise procurement. |
| Generative AI Feature Integration | Natural language processing tools accelerate SEC audit-trail document review for corporate legal departments. |
| API-First Architecture Development | Pre-built ERP connectors satisfy corporate procurement mandates and displace standalone platforms. |
| Compliance Certification Investment | SOC 2 Type II attestation becomes non-negotiable for financial services sector engagements in London. |
| Outcome-Based Pricing Pilots | Matter-outcome subscriptions penetrate cost-predictability-seeking mid-market corporate legal departments. |
Research Methodology
Bottom-up corporate legal department and law firm modeling reconciled against top-down vendor revenue tracking forms the analytical core of this study. Primary interviews with legal operations directors, CIOs at mid-sized firms, compliance officers, and bar association technology committees combined with secondary validation from SEC filings, FDA enforcement action databases, and legal technology procurement records. Triangulation across deployment model adoption curves and matter management platform implementations anchored segmentation splits.
Historical trendline analysis of cloud migration patterns and regulatory enforcement intensity informed projection mechanics across the analysis window. Segmentation dimensions modeled include deployment architecture, organization size tier, vertical industry, integration complexity level, and regional data residency requirement. CAGRs derived from elasticity-adjusted adoption curves and replacement cycle compression in jurisdictions with emerging localization statutes. Forecast inputs incorporated EU AI Act conformity assessment timelines and India's e-Courts project phase milestones.
Caveats apply where GDPR Article 22 enforcement interpretations or China's data localization statute expansions could materially shift the outlook. Practitioners should monitor FDA promotional material enforcement actions and SEC whistleblower program expansion for early signals of compliance management platform demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Advanced Mobile UX Design Services Market
Software & Services
Specification Management Software Market
Software & Services
Global Spa and Salon Software Market
Software & Services
Packaged Software Market
Software & Services
Global Online Survey Software Market
Software & Services
Real Estate Software Market
Software & Services
Audio and Video Editing Software Market
Software & Services
Global Application Platform Market
Software & Services
Global Ad Server Software Market
Software & Services
Global AB Testing Software Market
Software & Services
Collaborative Applications Market
Software & Services
Global Time and Attendance Management Software Market
Software & Services
Computer Backup Software Market
Software & Services
Global Recruiting Software Market
Software & Services
Global Data Entry Software Market
Software & Services
Global Open API Market