
 Application Platform As a Service Market | 2026-2036
Application Platform As a Service Market Size, Share, and Industry Trends Forecast 2026-2036
Application Platform As a Service Market Analysis
Consumption-based leasing and asset-light infrastructure financing is reshaping competitive dynamics in the Application Platform As a Service space. Microsoft leverages its captive enterprise channel to sustain hybrid cloud momentum across regulated workloads. Google anchors its position through container-native development environments that compete with legacy virtual machine architectures. IBM Corporation differentiates via managed mainframe-to-cloud integration services that occupy niche but high-retention accounts.
Application Platform As a Service delivers a cloud-native runtime environment with pre-integrated middleware, database services, and DevOps tooling that eliminates infrastructure provisioning overhead for software teams. The stack typically exposes RESTful APIs, auto-scaling thresholds, and CI/CD pipeline hooks that let developers deploy code without managing underlying servers or network topology. Public cloud deployments lead volume but hybrid cloud architectures capture expanding margin pools as enterprises straddle on-premises compliance requirements with elastic public capacity. Managed services within the service type dimension sustain higher renewal rates than pure self-service development platforms because operational accountability shifts to the vendor.
FDA scrutiny of cloud-hosted clinical trial systems, EU GDPR data-localization mandates, and China's GB standards for cross-border data flows collectively shape architectural decisions across healthcare and finance deployments. The SEC's cybersecurity disclosure rules for publicly traded firms further tighten vendor selection criteria around audit trails and encryption standards. Stakeholders must weigh sovereign data requirements against platform interoperability before committing to single-provider ecosystems.
Market Dynamics
Container-native architectures and serverless computing are compressing infrastructure abstraction layers, forcing vendors to compete on developer experience rather than raw compute provisioning. GDPR data-localization mandates and sector-specific residency rules in healthcare and finance are fragmenting deployment patterns toward sovereign cloud instances.
Growth Catalysts
- GDPR Data Residency Mandates:European enterprises must maintain patient records and financial transactions within jurisdictional boundaries, driving demand for managed hybrid platforms that automate compliance tagging and geo-fencing.
- DevOps Toolchain Consolidation:Platform engineering teams seek unified control planes that embed CI/CD, observability, and policy-as-code into a single consumption layer, reducing toolchain sprawl.
- China's GB Standards for Cross-Border Flows:Multinational corporations operating in mainland China require localized PaaS instances with SAMR-certified encryption modules, creating captive demand for compliant infrastructure.
Market Restraints
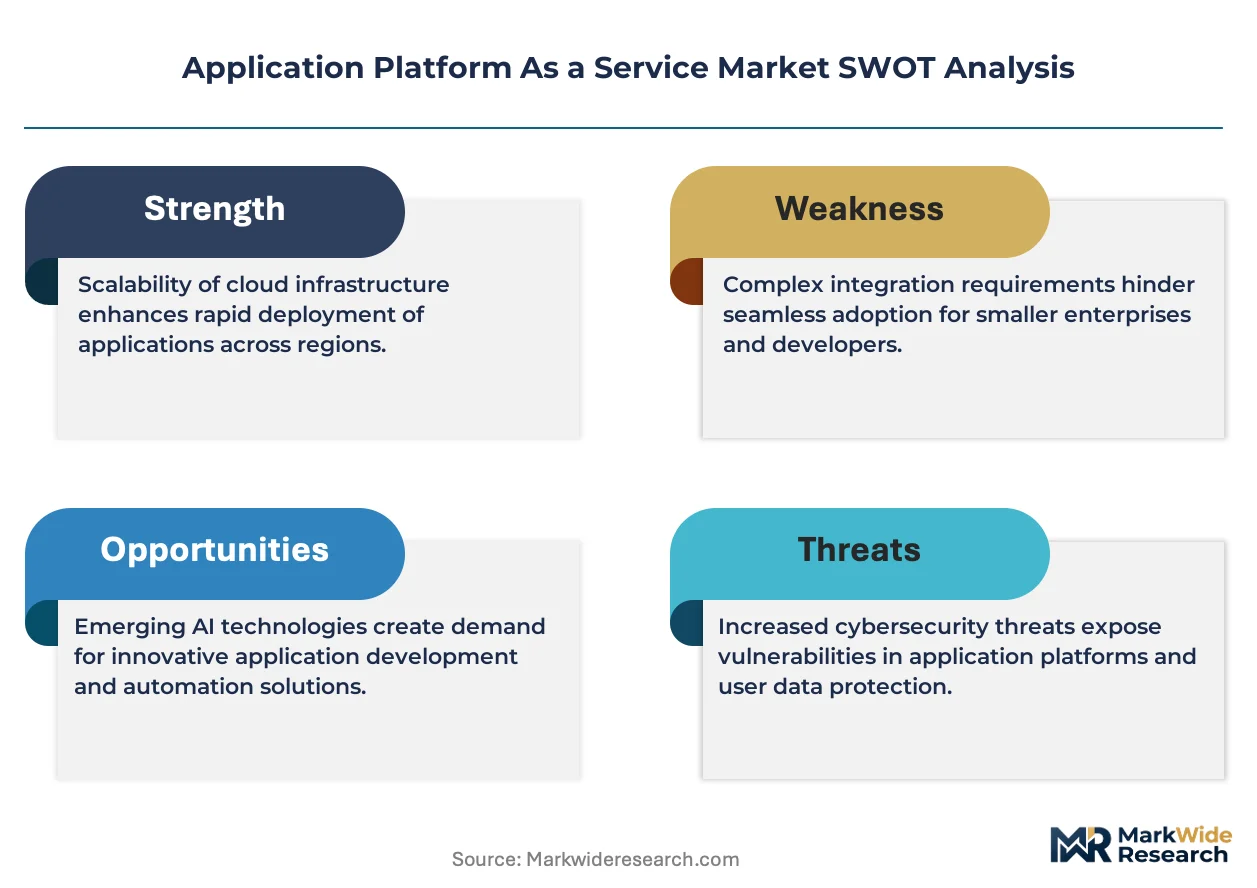
- Compute Cost Volatility:Spot instance pricing fluctuations and energy cost spikes in European data centers compress margins for workload-intensive analytics platforms.
- Concentrated Hyperscaler Dependency:Three cloud providers control the underlying infrastructure stack, creating single-point-of-failure risk for platform vendors without multi-cloud abstraction layers.
- Latency Constraints at the Edge:Real-time industrial control systems require sub-10 millisecond response times that centralized cloud regions cannot consistently deliver.
Strategic Opportunities
- India's PLI Scheme for Data Centers:Domestic infrastructure incentives position Indian metros as alternative hosting locations for Asia-Pacific workloads seeking cost arbitrage.
- AI Inference Workload Specialization:GPU-optimized platform tiers that abstract NVIDIA and AMD accelerator provisioning attract machine learning engineering teams.
- Embedded Finance Integration:Banking-as-a-service APIs layered onto retail and logistics platforms create net-new PaaS consumption from non-technology verticals.
Industry Challenges
- Platform Engineering Talent Scarcity:Shortage of engineers proficient in Kubernetes, Terraform, and policy-as-code tooling delays enterprise migration timelines.
- Legacy Mainframe Integration Complexity:COBOL and assembler workloads in insurance and government require costly middleware bridges to cloud-native runtimes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Application Platform As a Service Market |
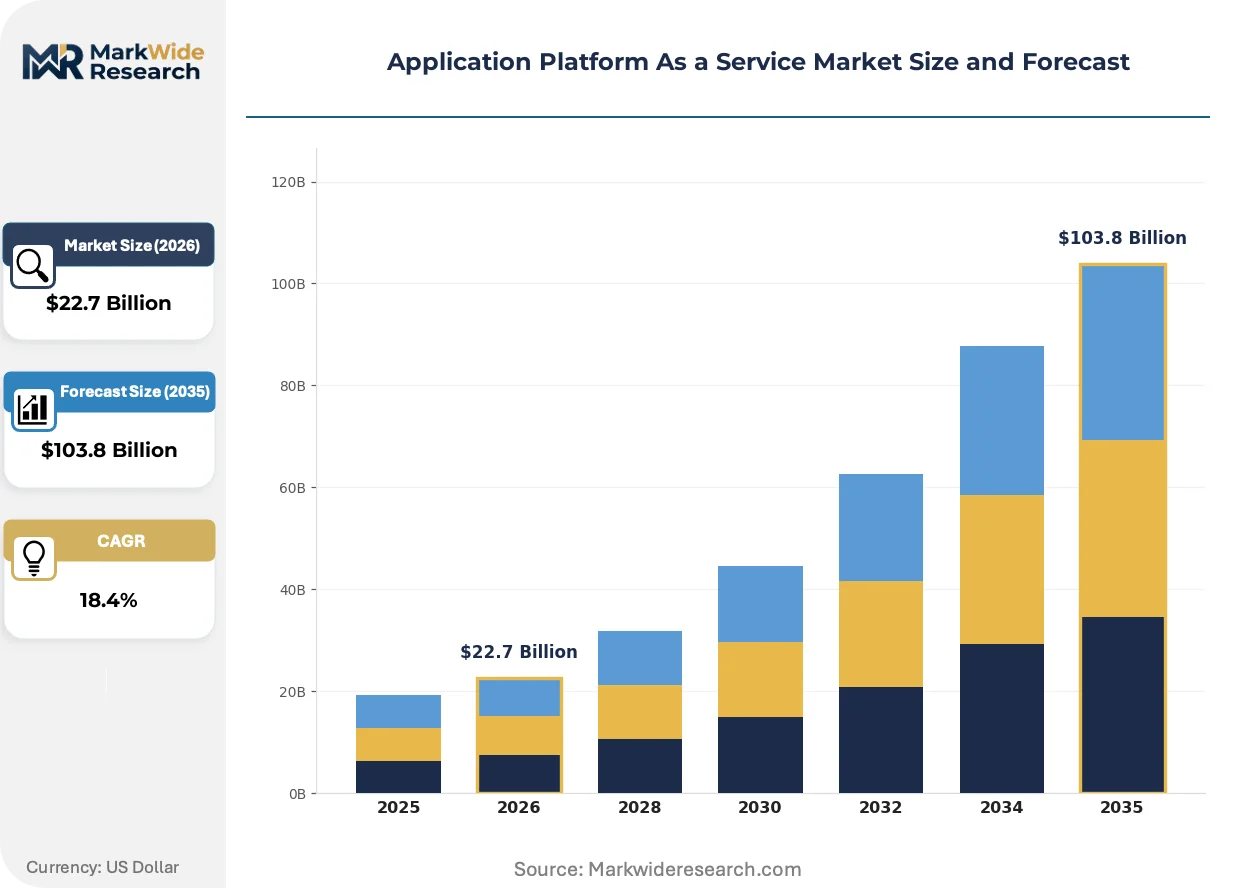
| Market Size in 2026 | $22.7 Billion |
| Market Size in 2035 | $103.8 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: Managed Services, Integration Services, Application Development, Support Services End User: SMEs, Large Enterprises, Government Agencies, Educational Institutions Industry Vertical: Healthcare, Finance, Retail, Telecommunications |
| Companies Covered | Amazon Web Services, Inc., Microsoft, Google, IBM Corporation, Salesforce, inc., SAP SE, Alibaba Cloud, Oracle Corporation, ServiceNow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Application Platform As a Service Market Emerging Trajectories
Abstraction layers are collapsing traditional distinctions between infrastructure and application code, embedding operational concerns directly into software delivery pipelines. Vendors now compete on the depth of their managed service catalogs rather than raw compute specifications.
WebAssembly runtime modules are virtualizing the boundary between compiled binaries and execution environments. Financial services firms embed Wasm components into payment processing workflows for sandboxed, near-native performance without container overhead. This architecture is virtualizing the traditional JVM and .NET CLR dominance in enterprise middleware, compressing startup latency from seconds to milliseconds.
The EU AI Act's risk-classification framework imposes documentation and audit requirements on high-risk automated decision systems. Healthcare providers deploying clinical risk-scoring algorithms must maintain model provenance logs and human-in-the-loop validation checkpoints. European hospital systems are responding by selecting PaaS vendors with pre-certified MDR-compliant audit trails rather than building compliance stacks in-house.
Consumption-based billing granularity has shifted from monthly reserved instances to per-second metered execution. Enterprise procurement functions now negotiate committed use discounts against actual workload telemetry rather than forecasted capacity. This behavioral pivot is most pronounced in North American SaaS companies optimizing burn rates, where engineering teams directly track infrastructure spend against feature-level revenue attribution.
Application Platform As a Service Market Segmentation
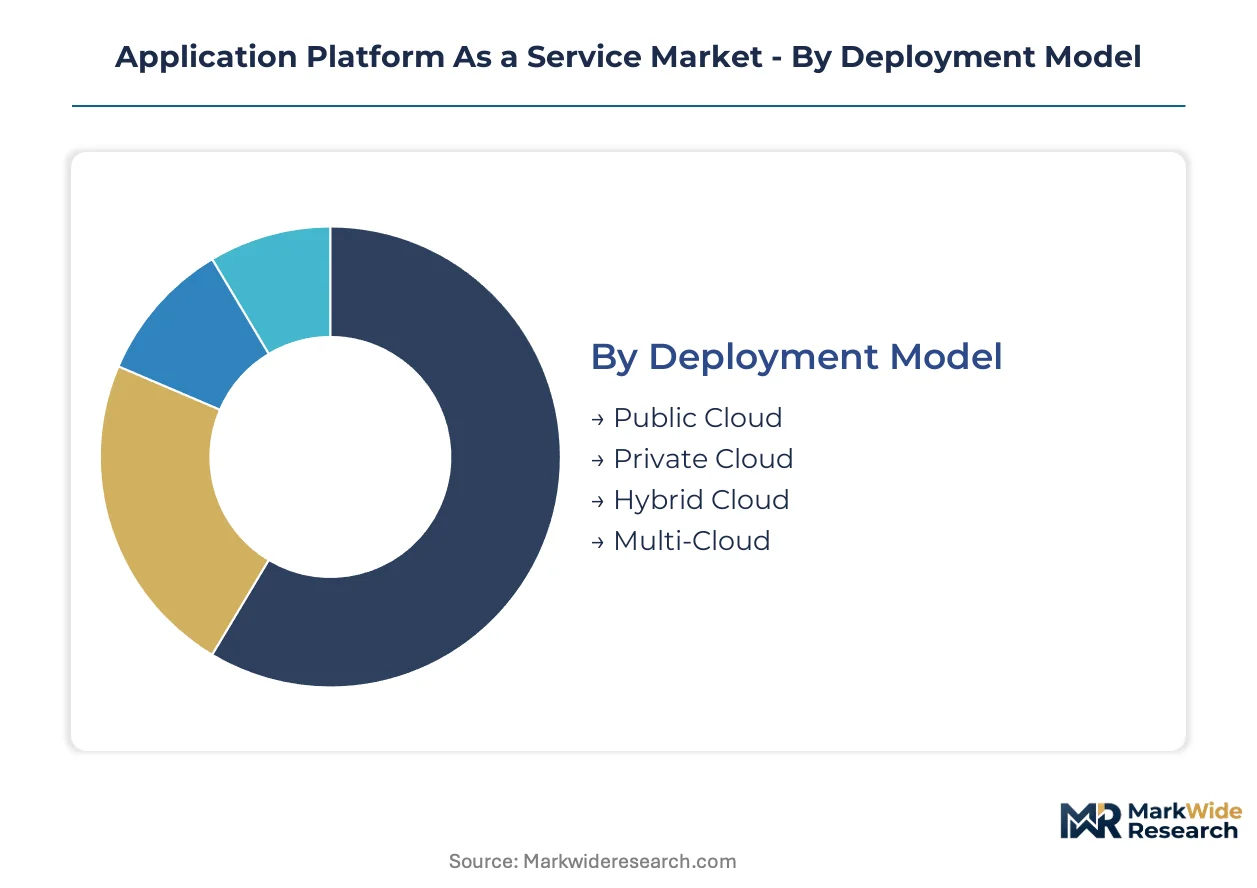
Segmentation in Application Platform As a Service reveals how procurement patterns split across infrastructure sovereignty requirements and operational accountability models. Buyers select deployment architectures based on data residency mandates, while service type choices reflect internal platform engineering maturity.
Deployment Model:
Mature hyperscaler regions anchor public cloud volume, while emerging sovereign infrastructure requirements accelerate hybrid and multi-cloud adoption curves.
- Public Cloud:Shared infrastructure pools deliver elastic compute with zero capital commitment. Demand concentrates among North American SaaS startups optimizing burn rates through consumption-based billing and auto-scaling thresholds.
- Private Cloud:Dedicated single-tenant environments isolate workloads on proprietary hardware stacks. European healthcare providers and German automotive suppliers deploy private instances to satisfy GDPR Article 44 data-localization mandates and industry-specific audit requirements.
- Hybrid Cloud:Unified control planes orchestrate workloads across on-premises and public capacity. Financial services firms in Singapore and Sydney use hybrid architectures to retain transaction ledgers locally while bursting analytics to public regions.
- Multi-Cloud:Abstraction layers distribute applications across two or more hyperscaler ecosystems. Procurement teams at Fortune 500 industrials negotiate committed use discounts by maintaining workload portability and avoiding vendor lock-in.
Public Cloud retains volume leadership; Multi-Cloud holds the steepest expansion curve.
Service Type:
Cost-tier stratification separates premium managed offerings from self-service development platforms with minimal operational handholding.
- Managed Services:Vendors assume full operational accountability for runtime patching, capacity scaling, and incident response. Large enterprises in regulated sectors—healthcare, defense contracting, critical infrastructure—pay premium rates to shift compliance liability and reduce platform engineering headcount.
- Integration Services:Pre-built connectors and API orchestration tools stitch disparate SaaS applications and legacy systems. Manufacturing conglomerates in Japan and South Korea consume integration services to link ERP, MES, and IoT telemetry without building custom middleware.
- Application Development:Low-code environments and container-native build pipelines accelerate software delivery. Mid-market technology companies and digital-native startups select development-focused tiers to compress time-to-market for customer-facing features.
- Support Services:Tiered technical assistance programs range from community forums to dedicated customer success managers. Government agencies and educational institutions prioritize support packages with guaranteed response SLAs over raw platform capabilities.
Managed Services commands the premium pricing tier; Integration Services is gaining share fastest among industrial verticals.
End User:
Customer-type differentiation maps procurement sophistication against internal technical capabilities and regulatory exposure.
- SMEs:Resource-constrained organizations prioritize turnkey platforms with minimal configuration overhead. Regional software vendors and professional services firms in Brazil and Mexico select SME-tier offerings to avoid hiring dedicated DevOps personnel.
- Large Enterprises:Complex organizational structures demand customizable policy engines, SSO integration, and granular cost allocation. Multinational banks and pharmaceutical manufacturers negotiate enterprise agreements with private pricing and dedicated infrastructure reservations.
- Government Agencies:Sovereign cloud mandates and classified workload requirements drive specialized procurement vehicles. National healthcare systems and defense departments in France, Canada, and Australia require FedRAMP, IRAP, or equivalent certification frameworks.
- Educational Institutions:Budget cycles and grant-funded research projects shape seasonal consumption patterns. University research computing centers leverage educational discounts for GPU-intensive machine learning workloads and genomic sequencing pipelines.
Large Enterprises dominates contract value; Government Agencies is climbing the fastest on sovereign infrastructure investments.
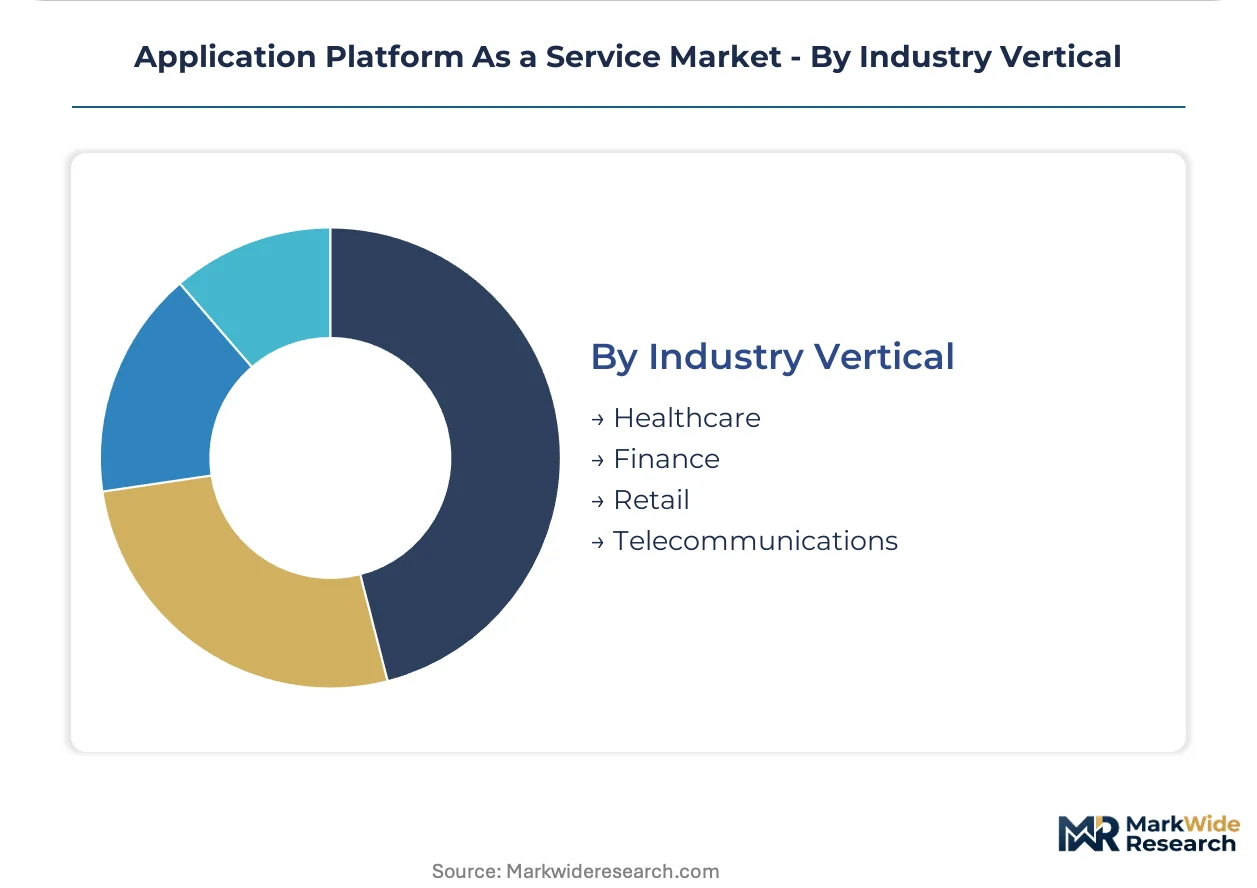
Industry Vertical:
Application-specific requirements fragment platform selection across audit intensity, latency sensitivity, and data gravity patterns.
- Healthcare:HIPAA, GDPR, and FDA 21 CFR Part 11 compliance frameworks govern clinical data handling. Hospital systems and medical device manufacturers in the United States and Germany select platforms with pre-certified audit trails and business associate agreements.
- Finance:Real-time transaction processing and algorithmic trading demand sub-millisecond latency with deterministic performance. Investment banks and payment processors in London, New York, and Zurich co-locate platform workloads in exchange-adjacent data centers.
- Retail:Seasonal demand spikes and omnichannel inventory synchronization drive elastic capacity requirements. E-commerce platforms and grocery chains deploy event-driven architectures to handle Black Friday and holiday shopping surges without overprovisioning baseline infrastructure.
- Telecommunications:Network function virtualization and edge computing integration reshape carrier infrastructure strategies. Mobile operators in India and Indonesia modernize core network elements using cloud-native platforms to reduce proprietary hardware dependency.
Finance retains the highest per-customer spend; Healthcare is expanding most quickly on regulatory-compliant platform investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for data centers is redirecting Asia-Pacific workload flows toward domestic infrastructure, while GDPR enforcement in Europe and SEC cybersecurity rules in the United States reshape vendor selection criteria across regulated industries.
United States
SEC disclosure rules for publicly traded firms tighten audit trail requirements for cloud-hosted financial systems. FDA scrutiny of clinical trial platforms drives healthcare providers toward FedRAMP-certified environments. Silicon Valley and Seattle metro areas concentrate SaaS engineering teams optimizing burn rates through per-second billing granularity.
Germany
GDPR Article 44 data-localization mandates force automotive and industrial conglomerates to retain transaction records within jurisdictional boundaries. The country's national data protection regulator enforces strict cross-border transfer protocols. Stuttgart and Munich industrial clusters deploy private cloud instances to satisfy sector-specific audit requirements for manufacturing telemetry.
India
PLI scheme incentives for domestic data center infrastructure attract multinational corporations seeking cost arbitrage for Asia-Pacific workloads. The central bank's data localization directives require financial institutions to maintain core banking records onshore. Mumbai and Bangalore technology corridors host captive development centers consuming managed integration services for ERP modernization.
Singapore
Monetary Authority of Singapore guidelines for cloud risk management shape financial services procurement frameworks. The city-state's position as a regional hub concentrates trading infrastructure requiring sub-millisecond latency. Marina Bay and Changi Business Park data centers co-locate platform workloads for Southeast Asian banking operations.
United Kingdom
Financial Conduct Authority operational resilience rules mandate recovery time objectives for critical third-party services. NHS Digital requirements for patient data handling drive hospital system migrations toward IRAP-aligned platforms. London's Square Mile and Canary Wharf clusters host investment banks deploying hybrid architectures for algorithmic trading compliance.
Application Platform As a Service Market Vendor Landscape
On the supply side, the industry is consolidating around hyperscaler ecosystems with captive infrastructure stacks, while specialized vendors occupy niche integration and compliance segments. Three strategic archetypes dominate: full-stack cloud providers with enterprise distribution networks, container-native platform specialists, and legacy system integration houses bridging mainframe-to-cloud migrations. Competitive intensity manifests through strategic partnerships with systems integrators and portfolio diversification into sovereign cloud instances.
Among hyperscaler-based platform vendors, Amazon Web Services, Microsoft, and Google exemplify the scale-driven archetype, each anchoring distinct competitive vectors through enterprise channel depth, developer tooling integration, and container-native runtime environments respectively. IBM Corporation occupies a position within the legacy integration tier, representing vendors that monetize high-retention mainframe modernization contracts. These four entities collectively illustrate how market structure stratifies between volume-leader ecosystems and specialized compliance-focused service layers.
| Leading Market Players |
|---|
| Amazon Web Services, Inc. |
| Microsoft |
| IBM Corporation |
| Salesforce, inc. |
| SAP SE |
| Alibaba Cloud |
| Oracle Corporation |
| ServiceNow |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific fiber routes from Singapore to Los Angeles anchor cost dynamics for hyperscaler infrastructure delivery, concentrating supply-side pricing power among three cloud providers while forcing downstream platform vendors to differentiate through certification-grade service tiers rather than raw compute arbitrage.
Pricing Analysis
Certification level (FedRAMP/ISO 27001/GDPR-compliant) creates the primary spread between platform tiers, with sovereign cloud instances commanding premium rates over standard public deployments. Subscription-based SaaS licensing dominates, though consumption-based per-second metering gains traction among North American SaaS startups optimizing burn rates. Price differentiation rests on audit trail depth and data residency guarantees, with healthcare and finance segments showing lowest price sensitivity due to compliance liability concerns. Cost compression in standard-tier offerings intensifies as hyperscaler spot pricing volatility feeds through to managed platform margins.
Supply Chain Analysis
Upstream silicon supply from Taiwan, South Korea, and the United States feeds GPU and accelerator provisioning for AI-optimized platform tiers. NVIDIA and AMD chip allocations, high-bandwidth memory modules, and custom ASIC development anchor raw material dependencies. Single-source vulnerability concentrates in advanced node semiconductor fabrication, where geopolitical export controls threaten supply continuity. Distribution runs through hyperscaler-owned data center footprints and specialized colocation partners in financial and healthcare regulatory jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Application Platform As a Service sits in early-cycle expansion as sovereign data mandates force architectural redesigns across European and Asia-Pacific enterprises, creating captive demand for compliant hybrid infrastructure that outpaces pure self-service platform growth.
For Market Incumbents: Harden multi-cloud abstraction layers against hyperscaler lock-in risk while deepening FedRAMP and GDPR pre-certification investments to capture regulated workload migrations. Consolidate channel partnerships with systems integrators specializing in mainframe-to-cloud modernization to defend high-retention enterprise accounts against container-native specialists. For New Entrants and Emerging Players: Mid-market manufacturing conglomerates in Japan and South Korea represent the most penetrable entry point, where ERP-MES integration gaps outstrip internal platform engineering capabilities. Government agency sovereign cloud mandates in France, Canada, and Australia offer second-tier white space with shorter procurement cycles than Fortune 500 enterprises. Lead with API-first integration services rather than full-stack runtime competition to bypass hyperscaler infrastructure scale disadvantages. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates spinning captive IT services units with pre-existing manufacturing telemetry integration expertise. Long-term viability hinges on compliance automation differentiation rather than commodity compute abstraction. Monitor GDPR enforcement variance across EU member states as the inflection signal for sovereign cloud demand acceleration versus standard public platform growth.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | FedRAMP and GDPR pre-certification captures healthcare and finance procurement cycles ahead of compliance deadlines. |
| Container-Native Platform Integration | Kubernetes abstraction layers displace legacy VM architectures among DevOps teams seeking CI/CD pipeline consolidation. |
| Strategic Partnership with Systems Integrators | IBM and Accenture channel relationships unlock mainframe modernization budgets in insurance and government verticals. |
| Acquisition of Compliance Automation Specialist | MDR audit trail and EU AI Act documentation tooling addresses European hospital system procurement requirements. |
| Geographic Expansion to Indian Metro Markets | Mumbai and Bangalore data center presence leverages PLI scheme incentives for Asia-Pacific cost arbitrage. |
Methodological Framework
A spread of perspectives from platform engineering directors, cloud procurement officers, compliance auditors, and systems integration architects converged on the working assumptions through structured primary interviews, validated against hyperscaler capex disclosures, SEC 10-K infrastructure segment filings, EU regulatory enforcement notices, and healthcare GPO contract databases. Bottom-up deployment model sizing triangulated against top-down enterprise IT spend allocation surveys across the analysis window.
Demand-supply balance modeling segmented the market by deployment architecture, service type accountability model, end-user procurement sophistication, and industry vertical compliance intensity across the projection horizon. CAGRs derived from elasticity-adjusted adoption curves incorporating sovereign data mandate enforcement timelines and DevOps toolchain consolidation rates. GPU-accelerated tier penetration and per-second billing granularity adoption served as industry-specific forecast calibration inputs.
Practitioners should monitor regulatory enforcement variance, hyperscaler spot pricing volatility, and WebAssembly runtime maturity for early signals of forecast deviation. Material shifts in EU AI Act implementation timelines or semiconductor export control scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Output Management Software Market
Software & Services
Global Storm Tracking Apps Market
Software & Services
Load Balancing Software Market
Software & Services
RFP Software Market
Software & Services
Data Conversion Services Market
Software & Services
Global Digital Adoption Platform Software Market
Software & Services
Online Paint Editor App Market
Software & Services
Salon Booking Software Market
Software & Services
Kennel Management Software Market
Software & Services
Global Audit Software Market
Software & Services
Automotive Dealership Software Market
Software & Services
Global Web Scraper Software Market
Software & Services
Sales Training and Onboarding Software Market
Software & Services
Global VR Game Engine Software Market
Software & Services
Optical Coatings Design Software Market
Software & Services
Virtual Studio Software Market