
 Global Directory Software Market | 2026-2036
Global Directory Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Directory Software Market Foresight
Enterprise buyers with complex multi-cloud footprints is collapsing the traditional on-premises directory model toward federated architectures. Brilliant Directories leverages its vertical specialization in membership-based organizations to sustain recurring revenue streams. eDirectory anchors its position through geographic dominance in North American small-business segments. AlphaPlex differentiates via API-first infrastructure that integrates with legacy identity stacks.
Directory software comprises systems that store, organize, and authenticate user identity attributes across networked environments, typically operating through LDAP or SCIM protocols with real-time synchronization intervals under 500 milliseconds to enable unified resource access. Cloud-based deployment leads current investment flows as organizations retire datacenter-bound infrastructure, while identity management solutions capture the deepest margin pools due to privileged access governance requirements. Single sign-on functionality is accelerating fastest among solution types as workforce friction reduction becomes a board-level priority.
FDA 21 CFR Part 11 requirements for healthcare identity traceability, EU GDPR data residency mandates enforced by national DPAs, and ISO/IEC 27001 certification standards collectively elevate compliance-driven procurement specifications. HIPAA security rule audits in the United States further tighten vendor qualification thresholds for directory platforms handling protected health information. Stakeholders must monitor how zero-trust architecture mandates from the U.S. federal government reshape deployment specifications and certification requirements.
Market Dynamics
Enterprise migration from on-premises LDAP servers to cloud-native identity fabrics is compressing deployment cycles and forcing incumbent vendors to rearchitect synchronization engines for sub-100-millisecond latency thresholds.
Growth Catalysts
- EU AI Act compliance mandates:Healthcare and financial services organizations across Germany, France, and the Netherlands are procuring auditable directory platforms to satisfy algorithmic transparency requirements for automated access decisions.
- Federated identity protocols:SCIM 2.0 and OIDC standards are enabling cross-organizational trust frameworks that eliminate redundant credential stores in multi-tenant SaaS environments.
- Zero-trust architecture mandates:U.S. federal agencies under OMB guidance are decommissioning perimeter-based authentication, driving continuous verification engine procurement.
Market Restraints
- Legacy system integration costs:Mainframe-era identity repositories in U.S. healthcare and government sectors require custom middleware development that extends implementation timelines by 8-14 months.
- Data residency enforcement:China's Personal Information Protection Law and Russia's data localization rules fragment cloud directory architectures, forcing redundant regional infrastructure deployment.
- Skilled identity architect scarcity:Deep expertise in hybrid Active Directory/Azure AD synchronization commands 40-60% salary premiums in London, Singapore, and New York labor markets.
Strategic Opportunities
- Brazilian enterprise digitization:ANVISA's electronic health record interoperability rules are creating first-mover advantages for directory vendors establishing local data centers in São Paulo state.
- API-first platform convergence:Directory services bundled with privileged access management and secrets vaulting are capturing expanded security budgets from CISO organizations.
- Edge computing identity nodes:Manufacturing facilities in Japan's Aichi prefecture and Germany's Baden-Württemberg region are deploying localized authentication to support autonomous robotics fleets.
Industry Challenges
- Cross-border key escrow complexity:Organizations operating across U.S., EU, and Chinese jurisdictions face conflicting cryptographic export controls and sovereign access demands that complicate global single sign-on deployments.
- Biometric template standardization gaps:Inconsistent ISO/IEC 19795 implementations between NIST-certified and BIS-compliant systems force redundant enrollment workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Directory Software Market |
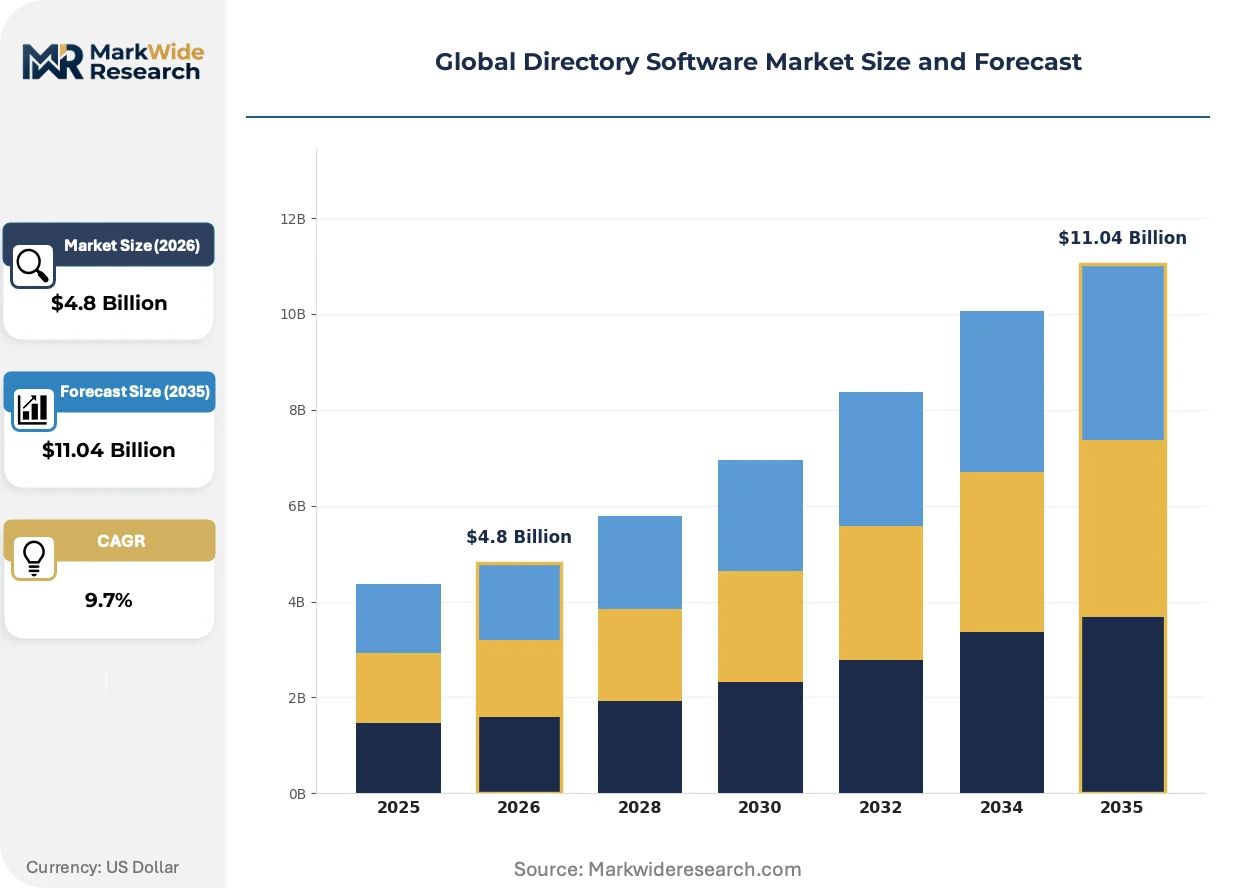
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Private Cloud, Public Cloud Solution Type: Identity Management, Access Management, User Provisioning, Directory Synchronization, Single Sign-On Use Case: Employee Directory, Customer Registry, Partner Portal, Supplier Management, Alumni Networks End User Industry: Information Technology, Telecommunications, Education, Government Agencies, Financial Services |
| Companies Covered | Brilliant Directories, eDirectory, AlphaPlex, CridioStudio, Templatic, Ideal Directories, GoClixy, Lisfinity, Business Directory Plugin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Directory Software Market Shifts & Advancements
Decentralized identity architectures and machine-to-machine authentication protocols are redrawing competitive boundaries between traditional directory vendors and emerging blockchain-based credential providers.
Serverless directory functions delivered through edge container orchestration are miniaturizing authentication latency for IoT device fleets. Automotive manufacturers in Stuttgart and industrial automation suppliers in Osaka are deploying these lightweight agents at plant-floor gateways. The technology is miniaturizing hardware requirements for directory nodes, enabling authentication directly on programmable logic controllers without dedicated identity servers.
GDPR Article 32 security-of-processing requirements are compelling European directory operators to implement encryption-by-default for all attribute stores. German data protection authorities in Hamburg and Bavaria have issued binding guidance that treats directory synchronization logs as personal data subject to erasure requests. Healthcare networks in Denmark and Sweden are responding by deploying immutable audit trails with cryptographic separation between operational and compliance data planes.
Subscription-based consumption models for identity verification API calls are displacing perpetual license arrangements in mid-market buyer segments. Value-added resellers in Australia's New South Wales and Victoria states are bundling directory services with managed detection and response offerings. This bundling concentrates purchasing authority with MSSP procurement teams rather than traditional IT infrastructure buyers, compressing vendor direct-sales engagement cycles by half.
Global Directory Software Market Segmentation
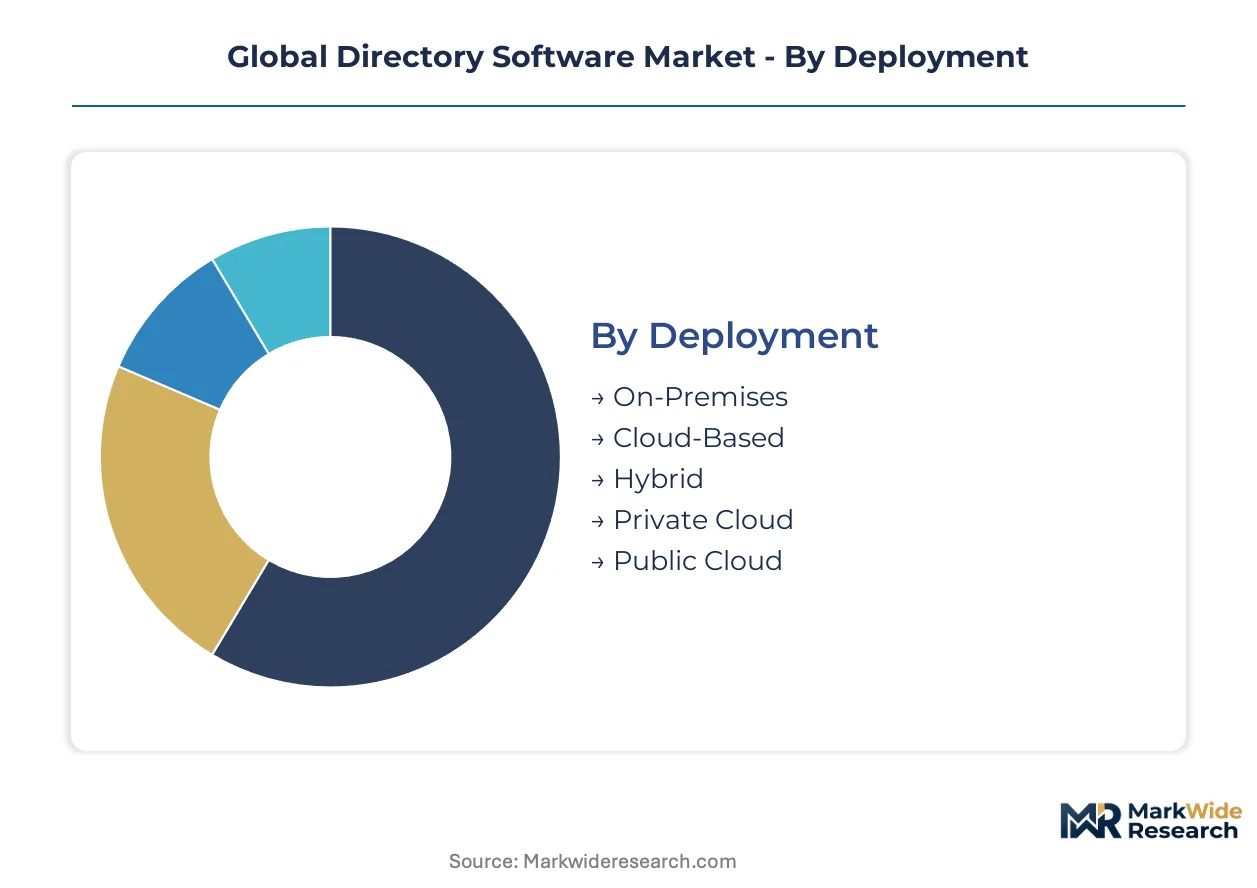
Directory software segmentation reveals how procurement authority is fragmenting across infrastructure buyers, security teams, and line-of-business owners. Each axis exposes different margin pools and competitive entry points for vendors repositioning around cloud-native delivery models.
Deployment:
Margin concentration sits with hybrid architectures that preserve legacy LDAP investments while enabling cloud scalability.
- On-Premises:Traditional datacenter deployments using Microsoft Active Directory or OpenLDAP with dedicated hardware maintenance contracts. Financial services institutions in Frankfurt and Singapore retain these configurations for SWIFT messaging compliance and sovereign data requirements.
- Cloud-Based:Fully managed SaaS directory services with API-driven provisioning and automatic patch management. Healthcare networks in Denmark and Sweden are migrating here to satisfy GDPR Article 32 encryption mandates without capital expenditure cycles.
- Hybrid:Synchronized on-premises and cloud identity stores with real-time attribute replication. German automotive manufacturers in Stuttgart and Munich favor this model for plant-floor autonomy combined with corporate cloud access.
- Private Cloud:Single-tenant directory instances hosted in dedicated virtual environments. Defense contractors in the United States and France deploy these for ITAR and EUCC certification compliance.
- Public Cloud:Multi-tenant directory services from hyperscale providers with consumption-based pricing. Brazilian enterprises in São Paulo state are adopting these for ANVISA health record interoperability deadlines.
On-Premises holds installed capacity. Cloud-Based is rotating up the share rankings.
Solution Type:
Volume leadership belongs to identity management suites bundling provisioning, governance, and analytics into consolidated procurement vehicles.
- Identity Management:Core directory platforms storing user attributes, group memberships, and authentication credentials with LDAP or SCIM protocol support. Telecommunications operators in South Korea and Japan deploy these for subscriber identity federation across MVNO partnerships.
- Access Management:Policy engines governing resource authorization through role-based or attribute-based controls. U.S. federal agencies under OMB zero-trust mandates are expanding procurement here for continuous verification workflows.
- User Provisioning:Automated lifecycle management for account creation, modification, and deactivation across target systems. Higher education institutions in the United Kingdom and Australia use these to manage transient student populations.
- Directory Synchronization:Real-time replication engines maintaining attribute consistency across heterogeneous identity stores. Manufacturing conglomerates in Germany's Baden-Württemberg region deploy these for ERP-HR system alignment.
- Single Sign-On:Authentication brokers eliminating redundant credential prompts across application portfolios. Professional services firms in London and New York are climbing the fastest here as workforce friction reduction becomes a board priority.
Identity Management dominates current bookings. Single Sign-On is expanding most quickly among new deployments.
Use Case:
Customer registries command pricing premiums due to consent management complexity and regulatory audit requirements.
- Employee Directory:Internal workforce identity systems integrating with HRIS, payroll, and productivity suites. Government agencies in Canada and Australia maintain these for public sector workforce administration.
- Customer Registry:External identity platforms supporting registration, preference management, and marketing consent tracking. Retail banking networks in Spain and Italy are investing here for PSD2 strong customer authentication compliance.
- Partner Portal:B2B identity frameworks enabling secure collaboration with distributors, resellers, and joint venture entities. Industrial automation suppliers in Osaka use these for supply chain partner onboarding.
- Supplier Management:Vendor identity systems governing procurement system access and purchase order authorization. Automotive OEMs in Stuttgart and Wolfsburg deploy these for tiered supplier network security.
- Alumni Networks:Community identity platforms maintaining engagement with former employees or students. Universities in the United States and United Kingdom operate these for fundraising and career services access.
Employee Directory retains the largest installed base. Customer Registry is gaining share fastest as digital engagement investments accelerate.
End User Industry:
Financial services generates the deepest security budgets due to fraud prevention and regulatory examination intensity.
- Information Technology:Technology vendors using directory infrastructure for internal workforce management and customer-facing SaaS authentication. Cloud software providers in Ireland and the Netherlands are scaling these for multi-tenant platform security.
- Telecommunications:Carriers managing subscriber identities, device authentication, and roaming partner federation. Mobile network operators in India and Brazil deploy these for national identity linkage requirements.
- Education:Universities and K-12 systems governing student, faculty, and researcher access to learning management systems. Research institutions in Switzerland and Sweden use these for cross-border collaboration platform access.
- Government Agencies:Public sector entities implementing citizen identity, civil servant administration, and inter-agency trust frameworks. Federal departments in the United States and Germany are climbing the fastest here for zero-trust architecture compliance.
- Financial Services:Banks, insurers, and payment processors managing customer identity, employee access, and regulatory reporting. Institutions in Singapore and the United Arab Emirates invest here for central bank cybersecurity examination readiness.
Information Technology holds current deployment volume. Government Agencies is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Submarine cable landing stations in Portugal and Spain anchor Europe's data sovereignty infrastructure for directory software deployments. These fiber-optic entry points enable GDPR-compliant cross-border synchronization between continental identity fabrics and transatlantic cloud regions. The physical layer determines where vendors locate certificate authority nodes and encryption key escrow facilities.
United States
Federal zero-trust mandates from OMB are accelerating procurement of continuous verification engines across civilian agencies. HIPAA security rule audits tighten vendor qualification thresholds for platforms handling protected health information. Healthcare networks in Boston and Nashville are deploying hybrid architectures to satisfy both federal and state-level data residency requirements.
Germany
Enterprise digitization and stringent data sovereignty rules drive hybrid deployment adoption across automotive and industrial sectors. EU AI Act compliance mandates require auditable access management platforms for automated decision systems. Manufacturers in Stuttgart and Munich favor synchronized on-premises and cloud identity stores for plant-floor autonomy combined with corporate cloud access.
China
Personal Information Protection Law enforcement fragments cloud directory architectures and forces redundant regional infrastructure deployment. National data localization rules require domestic certificate authorities for identity verification workflows. Technology clusters in Beijing and Shenzhen are developing sovereign identity stacks that operate independently of global federation protocols.
Brazil
ANVISA electronic health record interoperability rules create first-mover advantages for vendors establishing local data centers in São Paulo state. National identity linkage requirements for mobile network operators expand addressable demand for subscriber federation platforms. Financial institutions in Rio de Janeiro are climbing fastest for central bank cybersecurity examination readiness.
Japan
Manufacturing facilities in Aichi prefecture deploy localized authentication nodes to support autonomous robotics fleets. METI industrial security guidelines mandate sub-100-millisecond latency for machine-to-machine identity verification. Automotive suppliers in Osaka and Nagoya are miniaturizing directory hardware requirements to enable authentication directly on programmable logic controllers.
Global Directory Software Market Competitive Landscape
Listed leaders compete with private specialists across deployment architecture preferences, creating a tiered competitive structure. The vendor base clusters around three strategic archetypes: vertical specialists serving membership-based organizations, geographic incumbents with regional channel density, and API-first infrastructure providers integrating with legacy identity stacks. Dominant competitive moves include portfolio diversification into adjacent identity governance categories and geographic expansion through local data center establishment.
Within the vertical specialization tier, Brilliant Directories and eDirectory occupy distinct positioning. Brilliant Directories exemplifies the membership-focused archetype through its recurring revenue model tailored to association and chamber-of-commerce deployments. eDirectory anchors the small-business geographic dominance pattern, particularly across North American metropolitan markets. AlphaPlex represents the API-first infrastructure approach, targeting enterprise buyers requiring seamless integration with heterogeneous legacy identity stacks. These three patterns illustrate how competitive differentiation in directory software increasingly depends on integration depth and vertical workflow alignment rather than raw feature breadth.
| Leading Market Players |
|---|
| Brilliant Directories |
| eDirectory |
| AlphaPlex |
| CridioStudio |
| Templatic |
| Ideal Directories |
| GoClixy |
| Lisfinity |
| Business Directory Plugin |
| Others |
Supply & Pricing Matrix
ISO/IEC 27001 certification gates vendor qualification and simultaneously stratifies pricing tiers across deployment models, compressing margins for uncertified entrants while enabling premium capture by accredited providers serving regulated healthcare and financial verticals.
Pricing Analysis
Volume-discount tiering structures dominate SaaS directory procurement, with annual committed use tiers separating enterprise multi-tenant deployments from mid-market single-tenant instances. Pricing stratifies across premium, standard, and economy tiers driven by API call volume thresholds and geographic data residency guarantees. Cost compression in the standard tier intensifies as hyperscale providers bundle directory services with broader identity suites. Mid-market buyers exhibit highest price sensitivity, while federal agencies and defense contractors demonstrate lowest elasticity due to compliance-driven vendor lock-in.
Supply Chain Analysis
Just-in-time provisioning of cloud identity infrastructure dominates procurement patterns, though strategic stockpiling of on-premises hardware persists among German automotive manufacturers and U.S. defense contractors facing sovereign access requirements. Supply concentrates in the United States, Germany, and Ireland for hyperscale directory nodes, with component dependencies spanning cryptographic hardware security modules, edge container orchestration platforms, and cross-border fiber connectivity. Single-source vulnerability in submarine cable landing stations between Portugal and Spain elevates synchronization latency risks. Distribution runs through value-added resellers in Australia's New South Wales and Victoria, and direct hyperscaler marketplaces for enterprise self-service procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-based decentralized identity architectures threaten traditional directory incumbents with disintermediation, forcing established vendors to defend substitution risk through API ecosystem lock-in and compliance certification moats.
For Market Incumbents: Secure hybrid deployment dominance by deepening Active Directory/Azure AD synchronization capabilities and acquiring edge authentication specialists serving manufacturing robotics fleets. Certify against EU AI Act algorithmic transparency requirements before 2026 enforcement deadlines to maintain German automotive and healthcare procurement access. Backward integration into hardware security module manufacturing reduces cryptographic component cost exposure. For New Entrants and Emerging Players: Differentiate on serverless edge container orchestration for sub-100-millisecond latency in Japan's Aichi prefecture and Germany's Baden-Württemberg manufacturing corridors. Target Brazilian enterprise digitization around ANVISA health record interoperability deadlines as the most penetrable geography. Pursue managed security service provider bundling in Australia to bypass compressed direct-sales cycles. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across API-first infrastructure segments as containerization miniaturizes hardware requirements. Long-term viability favors platforms with vertical workflow alignment in membership-based organizations and association management. Monitor U.S. federal zero-trust mandate procurement velocity as the signal to watch for continuous verification engine demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | SCIM 2.0 and OIDC protocol support enables seamless legacy identity stack assimilation. |
| Geographic Expansion | São Paulo data center establishment captures ANVISA electronic health record interoperability deadlines. |
| Product Launch | Serverless directory functions miniaturize authentication latency for IoT device fleets. |
| Strategic Partnership | MSSP bundling in New South Wales concentrates purchasing authority with security teams. |
| Acquisition of Specialist Firm | Edge authentication specialists deepen manufacturing robotics fleet penetration in Stuttgart. |
Research Methodology
Operator-level perspectives from CTOs, IT procurement officers, platform engineers, and channel partners anchored the qualitative base. Primary interviews combined with secondary validation from SEC filings, hyperscaler capex disclosures, App Annie integration metrics, and hospital procurement databases. Bottom-up deployment counts across on-premises, cloud-based, hybrid, private cloud, and public cloud segments triangulated against top-down identity management suite revenue estimates.
Sensitivity analysis tested forecast robustness across the projection horizon by varying federal zero-trust mandate adoption velocity and EU AI Act enforcement timing. Segmentation dimensions modeled include deployment architecture, solution type, use case, and end-user industry vertical. CAGRs derived from logistic diffusion curves fitted to historical cloud migration patterns and regulatory compliance investment cycles. Industry-specific inputs encompassed OMB guidance implementation rates and GDPR Article 32 encryption mandate adoption curves.
Material uncertainties — sovereign data localization rule expansion, biometric template standardization fragmentation, and cross-border key escrow jurisdictional conflict — sit outside the modeled envelope. Forecasts reflect assumptions about SCIM 2.0 protocol adoption and hybrid synchronization latency thresholds. Revision becomes warranted when federal zero-trust procurement velocity crosses 40% agency penetration thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Continuous Testing Market
Software & Services
Board Portal Market
Software & Services
Computer Backup Software Market
Software & Services
Business Rules Management System Market
Software & Services
Global Cloud Accounting Technology Market
Software & Services
Global Corporate Wellness Software Market
Software & Services
Supplier Relationship Management Software Market
Software & Services
Employee Engagement Solutions Market
Software & Services
Global Data Recovery Software Market
Software & Services
Enterprise Performance Management (EPM) Software Market
Software & Services
Europe Digital Signage Software Market
Software & Services
Metal Fabrication Software Market
Software & Services
Kennel Management Software Market
Software & Services
Europe Workforce Management Software Market
Software & Services
Subscription Management Software Market
Software & Services
Cursor Reviewer Market