
 Supplier Relationship Management Software Market | 2026-2036
Supplier Relationship Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Supplier Relationship Management Software Market Analysis
The supplier relationship management software market is rebalancing between premium enterprise suites and commodity procurement tools as buyers split between deep integration needs and quick-deployment requirements. SAP Ariba leverages its embedded ERP connectivity to dominate complex manufacturing procurement workflows. Coupa differentiates through spend analytics that anchor corporate finance transformation programs. Ivalua specializes in multi-tier supplier visibility for automotive and aerospace value chains.
Supplier relationship management software encompasses cloud-based, on-premise, and hybrid deployment architectures that centralize contract management, supplier evaluation, performance tracking, and risk assessment across procurement organizations. The technology typically integrates via API layers with ERP and financial systems to enforce compliance rules, automate scorecarding, and flag supply disruptions before they cascade. Cloud-based deployment leads absolute revenue contribution due to faster implementation cycles and lower total cost of ownership for mid-market adopters. Supplier evaluation and risk management solutions represent the fastest-expanding solution segments as enterprises prioritize resilience over pure cost optimization following recent supply chain shocks.
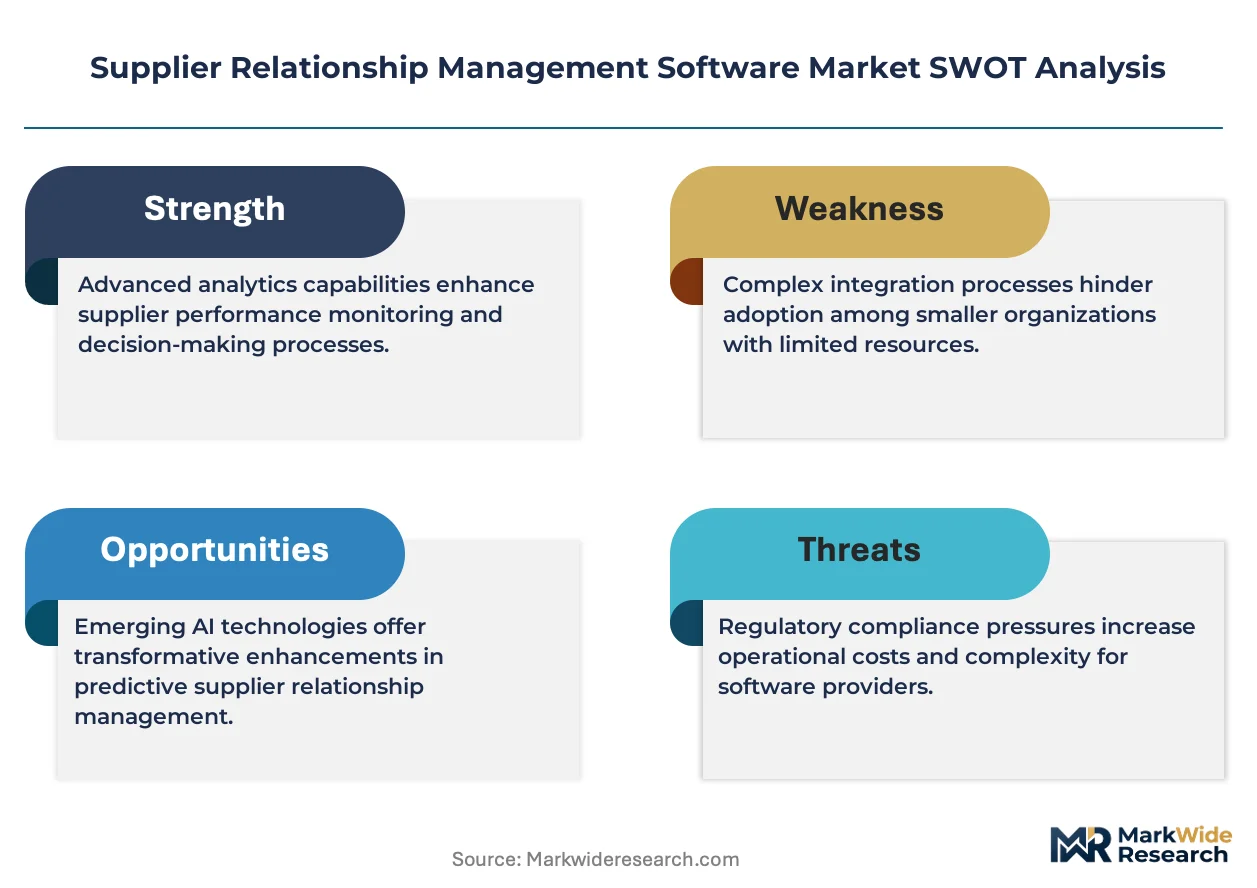
FDA quality system regulations, EU GDPR data handling requirements, and ISO 9001 supplier quality standards collectively shape product design priorities and market access conditions for vendors serving regulated industries. The EU AI Act imposes new documentation burdens on automated supplier scoring algorithms that process vendor financial and compliance data. Stakeholders must monitor how procurement teams weigh algorithmic transparency mandates against the operational efficiency gains of black-box risk models.
Market Dynamics
The EU AI Act's documentation mandates for automated vendor scoring algorithms are forcing procurement teams to rebuild risk assessment workflows around explainable decision logic rather than black-box efficiency gains.
Growth Catalysts
- Automotive supply chain digitization:Germany's automotive corridor is driving demand for multi-tier supplier visibility tools that map sub-tier dependencies across complex manufacturing networks.
- Cloud migration acceleration:Mid-market procurement organizations are abandoning on-premise legacy systems for API-first SaaS architectures that reduce implementation cycles from months to weeks.
- EU AI Act compliance infrastructure:Automated vendor risk scoring systems require new audit trails and algorithmic transparency modules, creating replacement demand for non-compliant legacy tools.
Market Restraints
- Data sovereignty fragmentation:Cross-border supplier data flows face conflicting requirements under GDPR, China's PIPL, and emerging national data localization laws.
- ERP integration complexity:Custom API development for legacy SAP and Oracle environments consumes 40-60% of implementation budgets and extends project timelines.
- Specialized talent scarcity:Procurement technology teams lack sufficient expertise in both supply chain operations and machine learning model governance.
Strategic Opportunities
- Carbon accounting convergence:Supplier relationship management platforms are expanding into Scope 3 emissions tracking as CSRD mandates require supply chain climate disclosures.
- Small supplier financial inclusion:Embedded working capital financing and dynamic discounting tools unlock new revenue streams from previously unbanked tier-2 and tier-3 vendors.
- India manufacturing expansion:Production-linked incentive schemes are attracting automotive and electronics manufacturers seeking alternative supply bases to China.
Industry Challenges
- Multi-tier data verification:Sub-supplier self-reported ESG and financial metrics lack standardized validation mechanisms, undermining risk model reliability.
- Algorithmic bias remediation:Procurement teams struggle to detect and correct discriminatory patterns in automated vendor scoring that may disadvantage minority-owned suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Supplier Relationship Management Software Market |
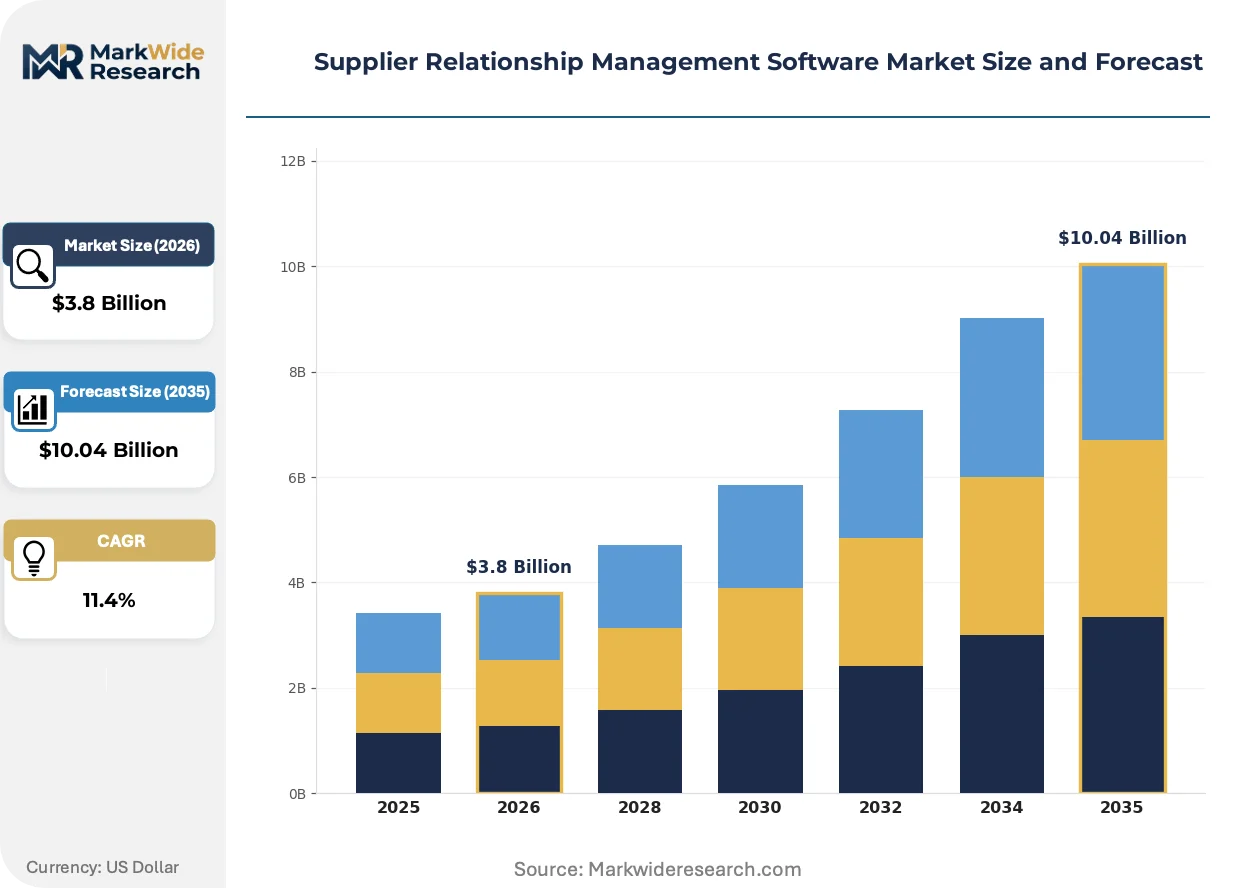
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, SaaS Industry Vertical: Manufacturing, Retail, Healthcare, Automotive Solution: Contract Management, Supplier Evaluation, Performance Management, Risk Management End User: SMEs, Large Enterprises, Government Agencies, Non-Profits |
| Companies Covered | Zapro, Jaggaer, SAP Ariba, Spendflo, Kodiak Hub, Coupa, Ivalua, VendorJot, GEP SMART, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Supplier Relationship Management Software Market Emerging Trajectories
Artificial intelligence is penetrating supplier risk assessment at the expense of static scorecarding methods, while regulatory pressure and procurement operating model changes are reshaping how organizations evaluate and manage vendor relationships.
Generative AI copilots for contract analysis and supplier negotiation preparation are expanding into procurement workflows at mid-market and enterprise organizations. Automotive and aerospace manufacturers with complex multi-tier supply chains are adopting these tools fastest. The technology is expanding into routine procurement tasks previously handled by category managers, compressing headcount growth plans for strategic sourcing functions.
The EU AI Act's risk-based classification system for automated decision-making tools imposes documentation and human oversight requirements on vendor scoring algorithms. Procurement software vendors must now build explainability layers that expose model logic to auditors and affected suppliers. Financial services and public sector procurement teams in Germany, France, and the Netherlands are most affected, with many pausing AI deployments until compliance frameworks stabilize.
Continuous monitoring subscriptions are displacing periodic supplier audits as the dominant risk management model. Manufacturing buyers now expect real-time financial health alerts and ESG incident detection rather than annual assessments. This shift is most visible in Germany's automotive supply base and among US medical device manufacturers subject to FDA quality system regulations requiring ongoing supplier controls.
Supplier Relationship Management Software Market Segmentation
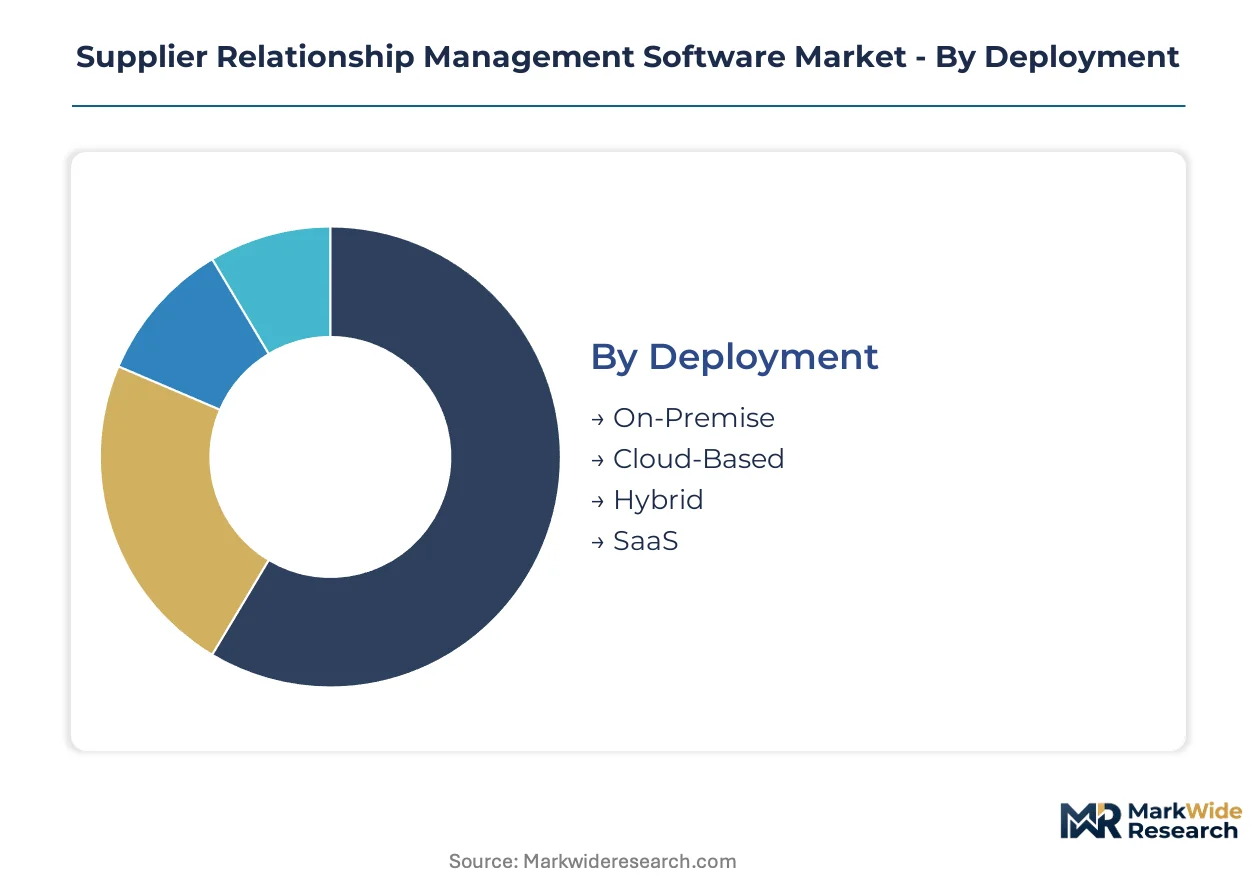
Deployment architecture and solution specialization dictate how procurement teams balance implementation speed against integration depth. Industry vertical concentration and end-user scale further fragment vendor targeting strategies across this expanding market.
Deployment:
Supply concentration among cloud-native vendors is reshaping procurement infrastructure procurement timelines and total cost structures.
- Cloud-Based:Multi-tenant SaaS architectures eliminate server maintenance overhead and compress implementation cycles. Manufacturing procurement teams in Germany's automotive corridor favor these platforms for rapid supplier onboarding without IT infrastructure delays.
- SaaS:Subscription licensing with API-first integration layers connects directly to ERP systems. Mid-market retailers expanding supplier networks choose this model for predictable operational expenditure and automatic feature updates.
- On-Premise:Licensed software running on customer-managed servers serves defense contractors and government agencies with strict data sovereignty mandates.
- Hybrid:Split configurations keep sensitive supplier financial data on-premise while routing transactional workflows through cloud interfaces.
Today's leader: Cloud-Based. Tomorrow's challenger: SaaS.
Industry Vertical:
Procurement sophistication varies sharply by sector regulatory burden and supply chain complexity.
- Automotive:Multi-tier supplier visibility requirements dominate platform selection. OEMs and tier-1 manufacturers in Germany, Japan, and the US deploy these tools to map sub-supplier dependencies across thousands of component sources.
- Manufacturing:FDA quality system regulations and ISO 9001 standards shape feature roadmaps for supplier audit automation and corrective action tracking.
- Healthcare:Medical device manufacturers prioritize FDA-compliant supplier qualification workflows and adverse event monitoring integration.
- Retail:Fast-moving consumer goods buyers emphasize supplier scorecards for on-time delivery and ethical sourcing verification.
Automotive commands premium pricing. Manufacturing delivers volume scale.
Solution:
Functional module selection reflects whether buyers prioritize cost control, risk mitigation, or strategic supplier development.
- Risk Management:Real-time financial health monitoring and ESG incident detection replace periodic audits. EU AI Act compliance requirements now mandate explainable algorithms for automated vendor scoring, driving replacement demand.
- Supplier Evaluation:Dynamic scorecarding with KPI dashboards tracks delivery performance, quality metrics, and innovation contribution. Aerospace manufacturers use these capabilities for source selection in long-cycle procurement programs.
- Contract Management:Clause libraries, automated renewal alerts, and obligation tracking reduce legal review bottlenecks.
- Performance Management:Continuous improvement workflows align supplier capabilities with buyer operational requirements.
Risk Management is climbing the fastest. Supplier Evaluation holds installed base dominance.
End User:
Organizational scale determines implementation approach and feature utilization depth.
- Large Enterprises:Global procurement organizations require multi-entity deployment with consolidated spend analytics. These buyers drive demand for advanced AI features and custom integration development.
- SMEs:Mid-market manufacturers and professional services firms adopt templated configurations with rapid deployment. Cloud-based solutions with pre-built ERP connectors serve this segment.
- Government Agencies:Public procurement bodies prioritize audit trails, competitive bidding compliance, and domestic supplier preference tracking.
- Non-Profits:Development organizations and humanitarian agencies use donor-funded implementations with simplified supplier due diligence.
Large Enterprises anchor vendor revenue. SMEs represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement technology talent clusters in Germany, the United States, and India anchor software development and implementation capacity for supplier relationship management platforms.
Germany
Automotive OEMs and tier-1 manufacturers drive demand for multi-tier supplier visibility tools. The EU AI Act mandates explainable algorithms for automated vendor scoring, forcing procurement teams to rebuild risk assessment workflows. Stuttgart and Munich host concentrated deployment activity among manufacturers mapping complex sub-supplier networks.
United States
Medical device manufacturers and aerospace contractors prioritize FDA-compliant supplier qualification systems. Cloud migration accelerates as mid-market procurement organizations abandon legacy on-premise installations. Boston and Seattle metropolitan areas concentrate healthcare and technology sector adoption respectively.
China
Electronics and automotive manufacturers seek supply chain resilience tools amid production-linked incentive competition with India. The Personal Information Protection Law restricts cross-border supplier data flows, complicating multinational deployment architectures. Shenzhen and Shanghai manufacturing clusters drive localized platform customization requirements.
India
Production-linked incentive schemes attract automotive and electronics manufacturers seeking alternative supply bases, expanding procurement technology demand. Software development talent in Bangalore and Hyderabad supports platform engineering for global vendors. Domestic mid-market manufacturers adopt cloud-based solutions for rapid supplier onboarding without heavy IT infrastructure investment.
United Kingdom
Financial services procurement teams in London pause AI deployments pending EU AI Act compliance framework stabilization. Retail and professional services sectors drive SaaS adoption for spend analytics and contract management. The Midlands manufacturing corridor generates demand for supplier performance tracking aligned with ISO 9001 quality standards.
Supplier Relationship Management Software Market Vendor Landscape
Capital-heavy enterprise suite producers compete with asset-light cloud-native specialists for procurement technology budgets. The market structure concentrates around three tiers: embedded ERP platforms, best-of-breed SaaS applications, and vertical specialists serving automotive and aerospace value chains. Dominant competitive moves include API-first architecture development to compress implementation timelines and strategic partnerships with financial services providers to embed working capital solutions.
Within the embedded ERP tier, SAP Ariba and Coupa occupy positions anchoring complex manufacturing procurement workflows. Ivalua represents the vertical specialist archetype focused on multi-tier supplier visibility. These three companies exemplify how competitive positioning splits between deep integration requirements and rapid-deployment demands across automotive, healthcare, and industrial manufacturing segments.
| Leading Market Players |
|---|
| Zapro |
| Jaggaer |
| SAP Ariba |
| Spendflo |
| Kodiak Hub |
| Coupa |
| Ivalua |
| VendorJot |
| GEP SMART |
| Others |
Supply Flow & Price Mechanics
Enterprise-commodity bifurcation in supplier relationship management software splits procurement teams between deep ERP-integrated suites and rapid-deployment SaaS tools, with this divergence manifesting in both subscription pricing ladders and cloud infrastructure sourcing strategies. Premium vendors command annual recurring revenue multiples by anchoring to SAP and Oracle ecosystems, while API-first specialists compress implementation timelines through multi-tenant architectures hosted on hyperscaler platforms in Germany, the United States, and India.
Pricing Analysis
Bundled implementation services versus unbundled software licensing defines the dominant pricing split across deployment models. SaaS subscription tiers separate enterprise-grade API connectivity from mid-market templated configurations, with ISO 27001 certification and EU AI Act compliance modules carrying material premiums. Pricing pressure stems from cloud-native entrants undercutting legacy on-premise vendors on total cost of ownership, compressing margins for installation-heavy implementation models. Mid-market manufacturers exhibit highest price sensitivity, prioritizing predictable operational expenditure over capital-intensive customization, while automotive OEMs accept premium positioning for multi-tier supplier visibility capabilities.
Supply Chain Analysis
Cloud infrastructure supply rests on hyperscaler data center concentration in the United States, Germany, and India, with compute and storage capacity expansion tethered to regional energy availability and data localization mandates. Software development talent draws from Bangalore, Hyderabad, and Munich engineering clusters, while API integration layers depend on ERP vendor cooperation from SAP and Oracle ecosystems. Single-source vulnerability concentrates in hyperscaler dependency for mid-market SaaS deployments, with regulatory restrictions under China's PIPL and EU GDPR fragmenting cross-border data routing. Distribution runs through direct enterprise sales organizations, systems integrator partnerships, and cloud marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supplier relationship management software investment logic functions as a geographic-arbitrage play, with development cost differentials between Indian engineering hubs and German implementation markets creating margin expansion opportunities for vendors optimizing delivery location.
For Market Incumbents: Extend API-first architecture development to compress implementation timelines below six weeks, neutralizing cloud-native challenger speed advantages. Acquire specialized compliance modules addressing EU AI Act algorithmic transparency requirements, defending position against modular best-of-breed entrants. Vertical integration into embedded working capital financing creates sticky revenue streams from tier-2 and tier-3 supplier networks.
For New Entrants and Emerging Players: Mid-market automotive suppliers in India's production-linked incentive corridors represent an underserved buyer archetype with limited procurement technology penetration. Target this segment through pre-configured supplier evaluation templates aligned with ISO 9001 and BIS quality standards, bypassing complex custom integration requirements. Channel partnerships with Indian systems integrators accelerate market access without direct enterprise sales infrastructure.
For Investors and Strategic Acquirers: Consolidation pressure builds where vertical specialists with automotive multi-tier visibility capabilities face standalone sustainability challenges against platform breadth. Long-term viability favors vendors bridging procurement workflows with carbon accounting and Scope 3 disclosure automation under CSRD mandates. Acquisition target archetypes include compliance-focused explainability layer developers and India-based engineering talent pools. Watch EU AI Act enforcement calibration as inflection indicator for algorithmic risk scoring replacement demand.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Architecture Development | Compresses implementation cycles from months to weeks for German automotive procurement teams. |
| EU AI Act Compliance Module Launch | Captures replacement demand from non-compliant legacy risk scoring installations in France and Netherlands. |
| Embedded Working Capital Financing | Unlocks revenue from previously unbanked tier-2 suppliers in India's manufacturing expansion corridors. |
| Carbon Accounting Platform Integration | Aligns with CSRD Scope 3 disclosure mandates affecting European automotive supply chains. |
| India Engineering Talent Acquisition | Reduces development costs for cloud-native features targeting mid-market SaaS expansion. |
Methodological Framework
Direct dialogue with procurement technology executives, ERP integration specialists, automotive supply chain managers, and regulatory compliance officers grounded qualitative findings, validated against SEC filings of publicly traded vendors, EU AI Act implementation guidance documents, and hyperscaler cloud infrastructure disclosure reports. Bottom-up sizing of deployment model segments and top-down cross-check against aggregate procurement software expenditure estimates ensured triangulation integrity.
Segment-level projections across cloud, SaaS, on-premise, and hybrid deployment architectures, combined with automotive, manufacturing, healthcare, and retail vertical splits, generated value estimates across the analysis window. CAGRs derived from regression analysis of historical adoption curves and forward-looking procurement digitization intensity indicators, with EU regulatory compliance timelines and India's production-linked incentive scheme uptake serving as key forecast inputs.
Inputs from vendor financial disclosures and regulatory implementation schedules were available through the study window; gaps in private mid-market SaaS vendor operating metrics introduce uncertainty bands around SME segment growth trajectories. Forecasts reflect documented assumptions regarding ERP migration velocity and AI compliance enforcement timing. Regulatory calibration shifts in Germany's KBA automotive oversight and India's BIS software standards represent triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Open Source Bug Tracking Tool Market
Software & Services
Global Integration Software Market
Software & Services
3D Animation Production Software Market
Software & Services
Account-Based Direct Mail Software Market
Software & Services
Global UIUX Software Market
Software & Services
Lighting Control Software Market
Software & Services
Survey and Feedback Management Software Market
Software & Services
Procurement Software Market
Software & Services
Home Fitness App Market
Software & Services
PAC Programming Software Market
Software & Services
Global Local SEO Software Market
Software & Services
Patent Management Software Market
Software & Services
Advanced Mobile UX Design Services Market
Software & Services
Europe CMMS Software Market
Software & Services
School Timetable Software Market
Software & Services
Global App Store Optimization Tools Software Market