
 Europe Embedded Insurance Market | 2026-2036
Europe Embedded Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Embedded Insurance Market Insights
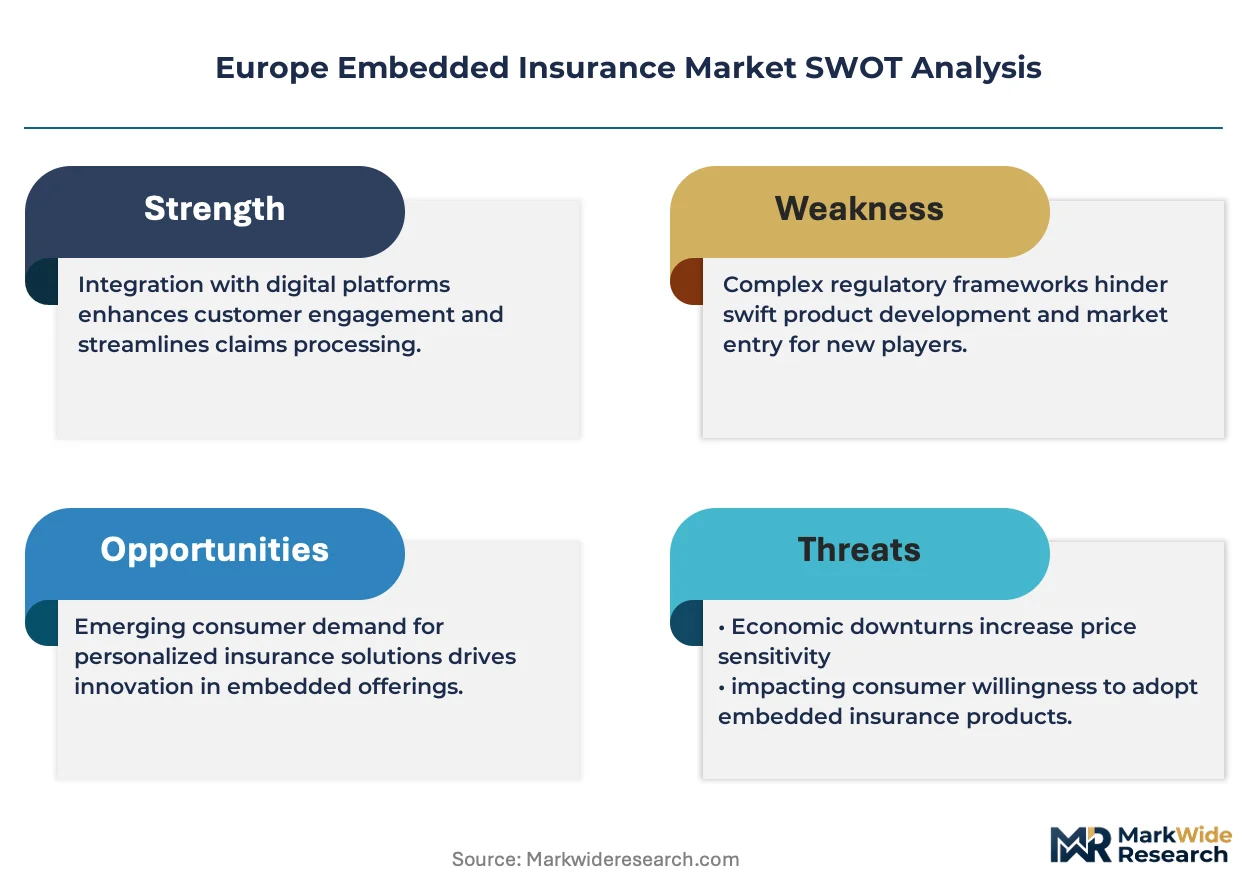
The EU Green Deal is rebalancing risk assessment frameworks across European underwriters, compelling carriers to embed climate exposure metrics into product design. Allianz Partners leverages its pan-European automotive partnerships to sustain embedded coverage distribution at vehicle point-of-sale. Zurich Insurance Group anchors commercial lines through broker-integrated APIs, while Qover specializes in modular API-first architectures that let digital platforms white-label policies.
Embedded insurance refers to the integration of risk coverage into non-insurance transactions, typically via application programming interfaces that trigger policy issuance upon purchase events without redirecting customers to separate enrollment flows. Health Insurance and Auto Insurance represent the most penetrated product lines, with the former benefiting from employer wellness platform integrations and the latter from connected vehicle telematics. AI and Cloud Computing drive the fastest technology expansion, as real-time data processing enables dynamic pricing and instant claims settlement.
The European Insurance and Occupational Pensions Authority (EIOPA) and national regulators such as BaFin in Germany and the Autorité de Contrôle Prudentiel et de Résolution (ACPR) in France enforce strict conduct-of-business rules that govern embedded product transparency and customer disclosure. The EU AI Act adds algorithmic accountability requirements for automated underwriting decisions, forcing technology providers to build explainability layers into their platforms. Stakeholders must monitor how EIOPA's developing digital insurance guidance harmonizes with divergent national implementation timelines.
Market Dynamics
The EU AI Act is forcing embedded insurance platforms to rebuild their algorithmic underwriting stacks with mandatory explainability layers, while the EU Green Deal compels carriers to weave climate exposure metrics into product design.
Growth Catalysts
- API-first distribution:Real-time policy issuance via application programming interfaces eliminates enrollment friction at digital point-of-sale, accelerating merchant adoption across European e-commerce platforms.
- EIOPA digital guidance:Harmonized conduct-of-business rules across member states reduce regulatory fragmentation for cross-border embedded product deployment.
- Connected vehicle telematics:Auto manufacturers in Germany leverage sensor data streams to trigger usage-based coverage at vehicle point-of-sale without manual underwriting.
Market Restraints
- Algorithmic compliance costs:The EU AI Act mandates documented human oversight for automated underwriting decisions, forcing technology providers to absorb expensive explainability engineering.
- Legacy core system fragility:Established carriers operate on decades-old policy administration platforms that resist real-time API integration without multimillion-euro modernization.
- Data localization requirements:Divergent national implementations of GDPR across France, Germany, and Italy complicate centralized cloud architectures for pan-European distribution.
Strategic Opportunities
- Employer wellness platform integration:Health coverage embedded into corporate SaaS benefits administration remains underpenetrated in Spain and Italy relative to Nordic markets.
- CSRD-driven risk disclosure:The Corporate Sustainability Reporting Directive creates mandatory demand for climate risk transfer products among mid-cap European enterprises.
- Telematics-parametric convergence:Real-time sensor data combined with automated claims triggers enables instant settlement for agricultural and logistics coverage without loss adjustment.
Industry Challenges
- Actuarial-technical translation gap:Product teams struggle to convert traditional rating factors into machine-learning features that satisfy BaFin model governance requirements.
- Multi-jurisdiction licensing complexity:Passporting rules under Solvency II create operational overhead when embedded partners operate across EEA member states with divergent consumer protection enforcement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Embedded Insurance Market |
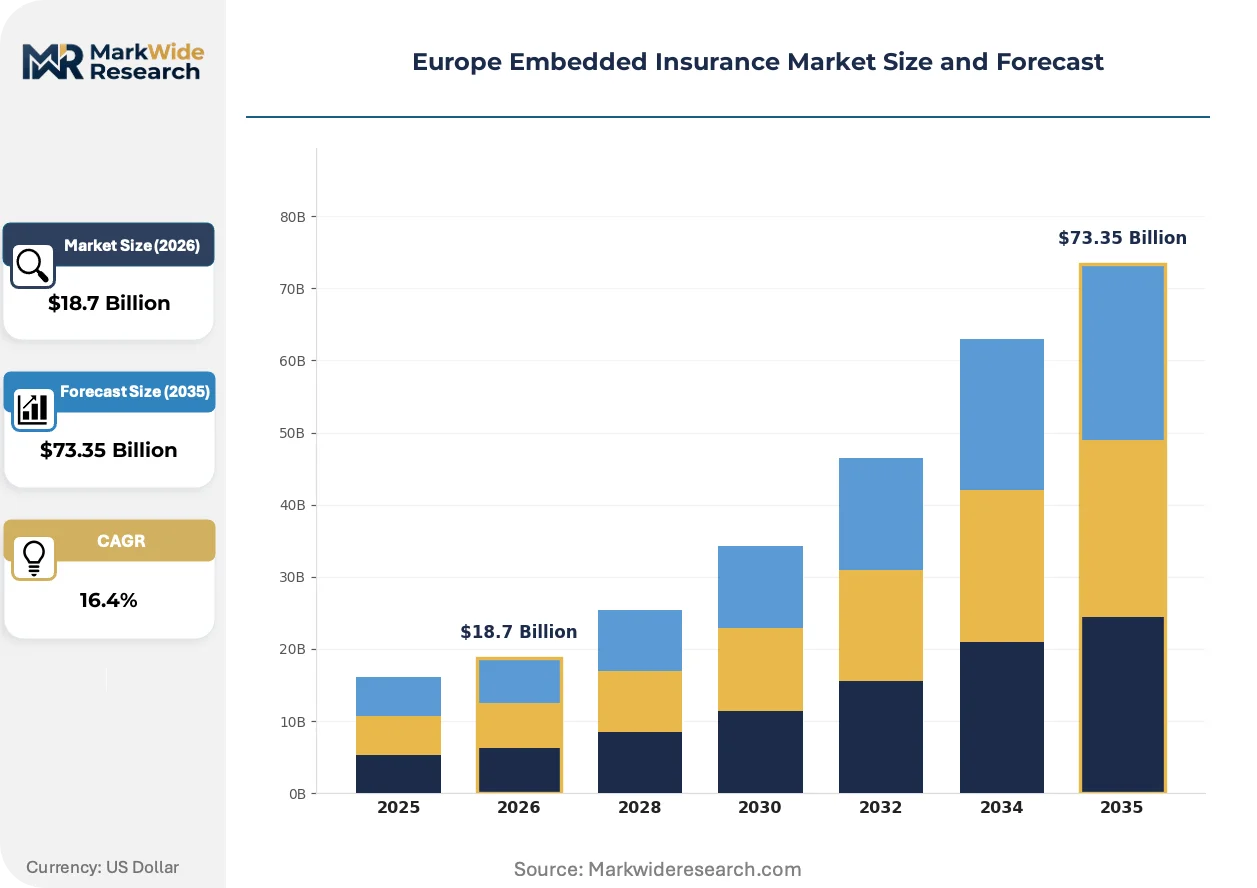
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Auto Insurance, Health Insurance, Travel Insurance, Home Insurance Technology: Blockchain, AI, Cloud Computing, IoT End User: Consumers, Small Business, Corporates, Startups Distribution Channel: Online Platforms, Mobile Applications, Brokers, Direct Sales |
| Companies Covered | Allianz Partners, AXA Partners, Qover, Cover Genius, Zurich Insurance Group, bolttech, Bsurance, Wefox Holding AG, Zego, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Embedded Insurance Market Trends and Innovations
Real-time data infrastructure is compressing the policy lifecycle from weeks to seconds, while regulatory pressure on algorithmic transparency is reshaping how technology stacks get architected.
Cloud-native core platforms are integrating event-driven microservices that trigger policy issuance upon purchase transactions without redirecting customers to separate enrollment flows. German insurtech infrastructure providers deploy these architectures most aggressively. The structural consequence is collapsing distribution costs and enabling white-label coverage for non-insurance merchants.
The EU AI Act mandates documented human oversight and technical documentation for automated underwriting decisions classified as high-risk AI systems. Carriers must maintain audit trails of algorithmic logic that EIOPA and national regulators can inspect. Commercial lines with complex risk assessments face the steepest compliance engineering burden.
Corporate buyers now expect coverage to surface within software they already use rather than through broker-mediated annual renewal cycles. HR platforms and fleet management systems are becoming the primary distribution channel for health and auto coverage. This pattern is most advanced in Germany's B2B SaaS ecosystem.
Europe Embedded Insurance Market Segmentation
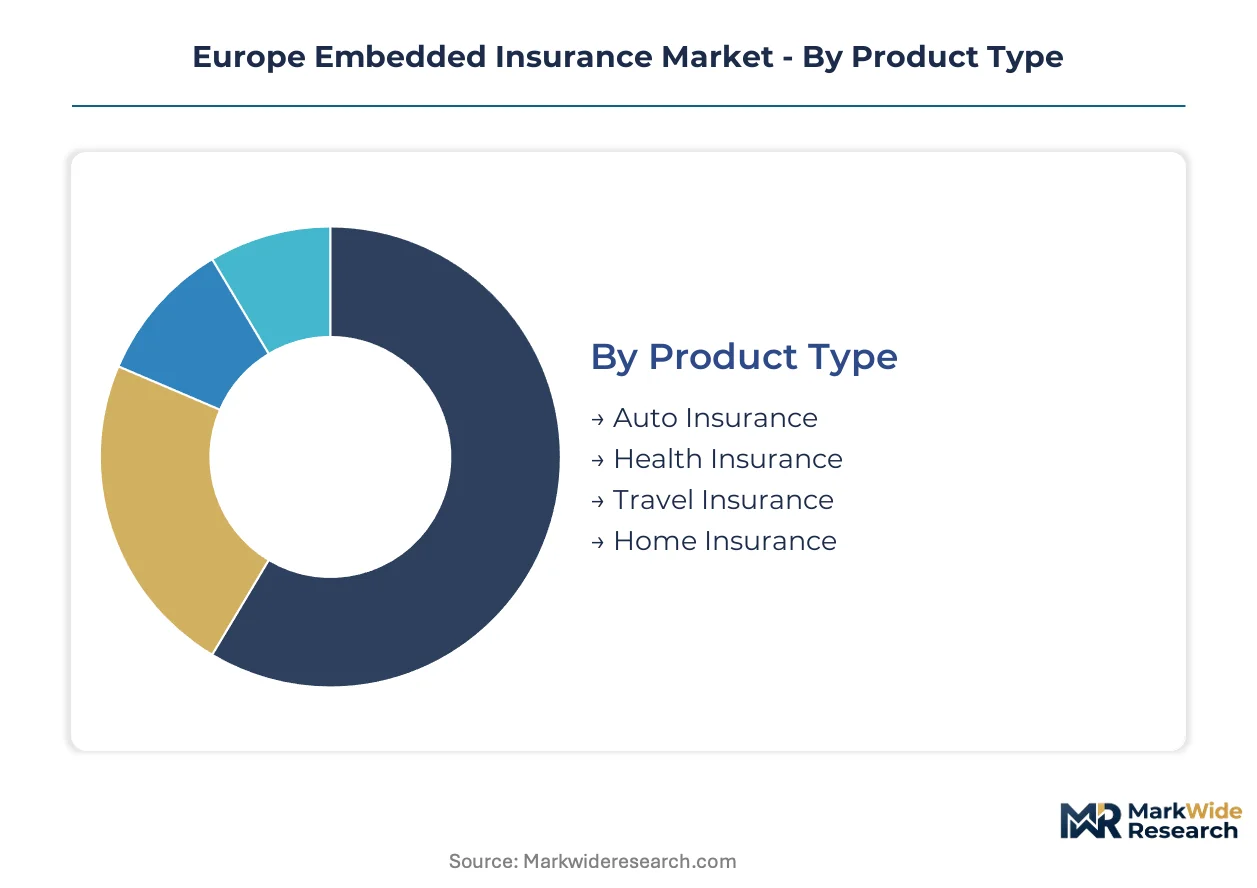
Embedded insurance architectures demand precise segment alignment between risk product design and distribution technology. Each category reveals distinct margin profiles and regulatory exposure across European jurisdictions.
Product Type:
Standardization dominates basic motor and travel coverage, while health and home products require deeper customization to match national regulatory frameworks.
- Auto Insurance:Connected vehicle telematics enable usage-based pricing triggered at point-of-sale through manufacturer APIs. German automotive partnerships concentrate demand here, driven by fleet electrification mandates under the EU Green Deal.
- Health Insurance:Modular coverage components integrate into employer wellness platforms and HR SaaS systems. Nordic markets lead adoption, though Spain and Italy show expansion potential as corporate benefits administration digitizes.
- Travel Insurance:Real-time policy issuance activates upon booking confirmation without separate enrollment flows.
- Home Insurance:Smart home sensor data enables parametric triggers for weather-related claims settlement.
Leading the category by volume: Auto Insurance. Growing fastest: Health Insurance.
Technology:
Cost tier separation runs from capital-intensive legacy modernization to lightweight API deployment, with cloud infrastructure anchoring mid-market scalability.
- AI:Machine learning models automate underwriting decisions and dynamic pricing adjustments. The EU AI Act imposes explainability requirements that force architecture rebuilds, particularly for high-risk automated assessments in commercial lines.
- Cloud Computing:Event-driven microservices architectures enable real-time policy issuance without customer redirection. German insurtech infrastructure providers deploy these most aggressively, collapsing distribution costs for white-label merchant solutions.
- Blockchain:Distributed ledgers support parametric claims automation and fraud-resistant record-keeping.
- IoT:Sensor networks feed continuous risk data streams from vehicles, homes, and industrial equipment.
Leading the category by deployment scale: Cloud Computing. Expanding most quickly: AI.
End User:
Customer type determines integration complexity, from frictionless consumer checkout to bespoke corporate risk structuring.
- Corporates:Mid-cap enterprises under CSRD disclosure mandates drive demand for climate risk transfer products integrated into procurement and fleet management systems. Broker-integrated APIs from established carriers anchor this segment.
- Small Business:Digital-native merchants seek turnkey coverage bundles for e-commerce liability and cyber exposure.
- Consumers:Individual purchasers expect invisible coverage activation at digital point-of-sale.
- Startups:Early-stage companies prioritize flexible, pay-as-you-grow policy structures without long-term commitments.
Leading the category by policy value: Corporates. Steepest expansion trajectory: Small Business.
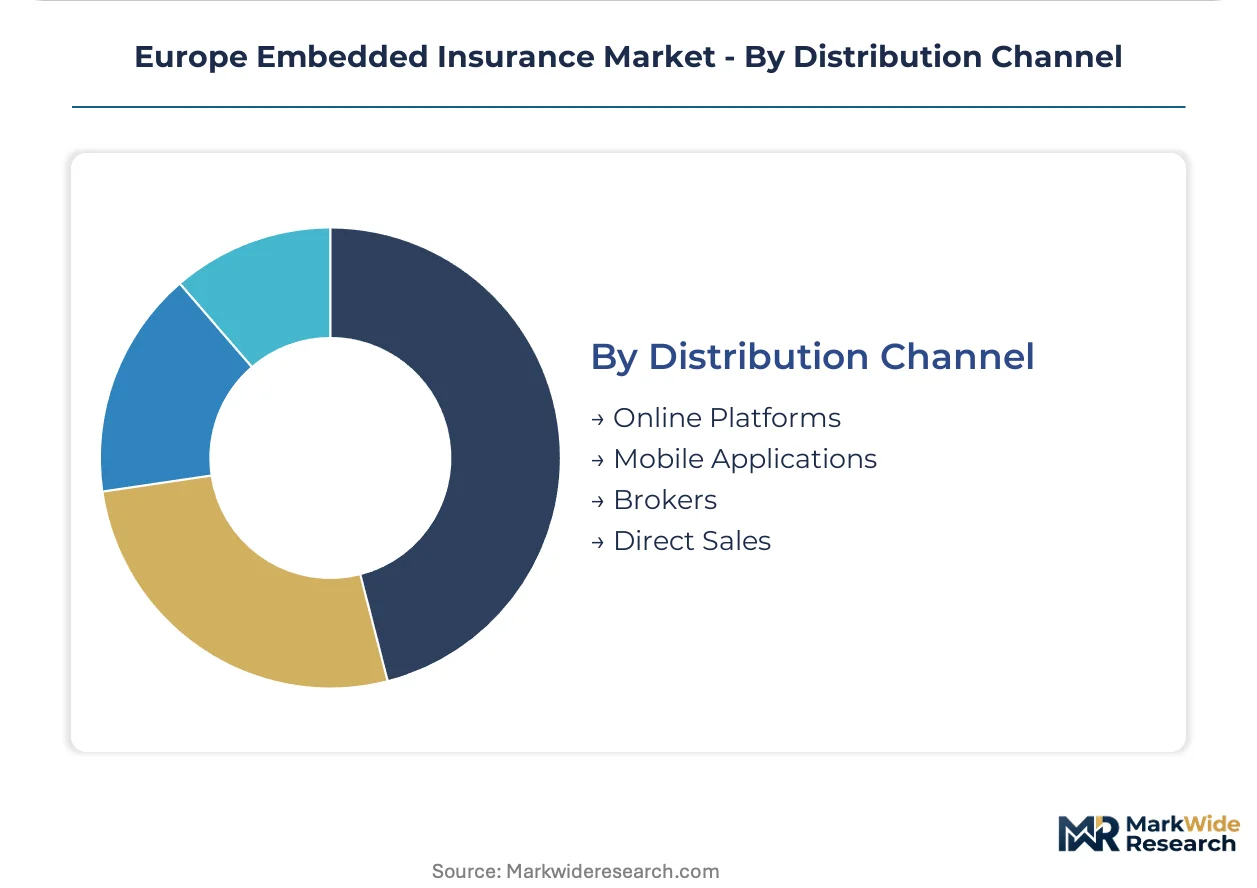
Distribution Channel:
Maturity gradient separates established broker networks from emerging platform-native distribution, with mobile interfaces capturing younger demographics.
- Online Platforms:E-commerce checkout integration eliminates enrollment friction through embedded APIs. Merchant adoption accelerates as real-time issuance technology matures, particularly across German and French digital retail ecosystems.
- Mobile Applications:Native app experiences enable contextual coverage offers based on transaction type and location data.
- Brokers:Traditional intermediaries retain strength in complex commercial lines requiring human advisory.
- Direct Sales:Carrier-owned channels persist for established customer relationships and renewal retention.
Leading the category by transaction volume: Online Platforms. Gaining share fastest: Mobile Applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Berlin anchors European insurtech infrastructure development, hosting dense clusters of API-first platform providers that serve cross-border embedded distribution networks spanning the continent.
Germany
Automotive OEMs and fleet management SaaS providers drive embedded auto insurance demand through connected vehicle telematics integrations. BaFin enforces strict model governance requirements for algorithmic underwriting systems. Munich and Frankfurt host established carrier technology centers where legacy modernization programs accelerate API deployment.
United Kingdom
Fintech ecosystems and employer benefits platforms concentrate health insurance embedding opportunities across London and Manchester. The Financial Conduct Authority maintains conduct-of-business rules governing digital distribution transparency. Lloyd's of London syndicates experiment with parametric coverage structures for logistics and agriculture applications.
France
E-commerce merchant adoption surges through Paris-based retail technology platforms seeking checkout-integrated coverage bundles. The Autorité de Contrôle Prudentiel et de Résolution supervises embedded product disclosure standards. Lyon hosts emerging insurtech infrastructure providers specializing in modular policy architectures.
Netherlands
Logistics and shipping platforms drive demand for cargo and transit coverage embedded into supply chain management software. The Dutch Authority for the Financial Markets coordinates with EIOPA on digital insurance guidance implementation. Amsterdam's fintech corridor attracts API-first distributors targeting SME commercial lines.
Italy
Corporate benefits digitization lags Nordic benchmarks, creating expansion headroom for health coverage embedded into HR platforms. IVASS national regulations govern consumer protection in digital distribution channels. Milan's financial services cluster incubates partnerships between traditional carriers and retail technology providers.
Europe Embedded Insurance Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology sophistication and regulatory compliance depth, with API-native specialists commanding valuation multiples above legacy-dependent distributors. Market structure tilts toward consolidation at the infrastructure layer while fragmenting across vertical application endpoints. Three archetypes dominate: pan-European carrier technology divisions, standalone insurtech infrastructure providers, and vertical-specialized program administrators. Competitive moves concentrate on strategic API partnership networks and regulatory technology investments that accelerate market access across member states.
Within the carrier technology tier, Allianz Partners and Zurich Insurance Group occupy positions anchored by automotive and commercial line distribution relationships. Among standalone infrastructure specialists, Qover exemplifies modular architecture approaches that enable white-label deployment across merchant platforms. AXA Partners represents the program administrator archetype, sitting within cross-border partnership networks that leverage group-scale regulatory capabilities.
| Leading Market Players |
|---|
| Allianz Partners |
| AXA Partners |
| Qover |
| Cover Genius |
| Zurich Insurance Group |
| bolttech |
| Bsurance |
| Wefox Holding AG |
| Zego |
| Others |
Pricing and Supply Chain Analysis
Corporate procurement teams in Germany and France now mandate API-native infrastructure with embedded explainability layers, forcing carriers to absorb compliance engineering costs that compress margins at the technology tier while sustaining premium capture at the product tier.
Pricing Analysis
Outcome-linked pricing for parametric coverage anchors value capture in agricultural and logistics applications. Three-tier pricing structure across premium, standard, and economy levels separates white-label merchant solutions from direct carrier offerings. Cost compression in the mid-market intensifies because legacy core modernization absorbs capital that could fund competitive positioning. Small business digital merchants exhibit highest price sensitivity; corporate risk managers under CSRD mandates show lowest.
Supply Chain Analysis
Single-source vulnerability sits with German insurtech infrastructure providers dominating event-driven microservices architecture. Technology development concentrates in Germany, cloud hosting draws from Ireland and the Netherlands, and underwriting capacity rests on London and Zurich. Regulatory fragmentation across BaFin, ACPR, and IVASS implementations creates compliance chokepoints. Distribution runs through API-first platform partnerships rather than traditional broker networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compliance engineering capacity constrains carrier technology divisions, propping pricing power for modular infrastructure specialists who have pre-built explainability layers.
For Market Incumbents: Deploy regulatory technology investments to accelerate passporting across EEA member states. Consolidate fragmented API partnership networks through exclusive platform integrations. Counter emerging standalone insurtech infrastructure providers by absorbing their white-label merchant relationships. For New Entrants and Emerging Players: Embedded health coverage within Spanish and Italian corporate benefits administration offers the most penetrable white-space target. Pursue employer wellness platform integrations as the primary go-to-market angle. Target mid-cap enterprises seeking climate risk transfer products under CSRD disclosure mandates. For Investors and Strategic Acquirers: Re-rating potential sits with modular API-first infrastructure specialists given EU AI Act compliance catalysts. Position acquisitions for five-to-ten year digital distribution consolidation. Monitor EIOPA digital insurance guidance harmonization progress as the key inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Real-time policy issuance via embedded microservices collapses distribution friction for merchant partners. |
| Explainability Layer Development | Pre-built algorithmic audit trails satisfy BaFin model governance and accelerate EEA market access. |
| White-Label Partnership Expansion | Modular architecture deployment across French and German e-commerce platforms captures checkout-embedded demand. |
| Legacy Core Modernization | Cloud-native policy administration enables event-driven architectures without multimillion-euro replacement cycles. |
| Cross-Border Regulatory Passporting | Harmonized Solvency II implementations reduce operational overhead for pan-European embedded distribution. |
Research Methodology
Document review covered EIOPA digital insurance guidance, BaFin circulars on algorithmic underwriting, and carrier technology disclosures, complemented by interviews with insurtech CTOs, carrier digital distribution heads, and merchant platform integration specialists. Secondary sources included EU AI Act technical documentation, CSRD implementation frameworks, and national regulator conduct-of-business rules. Bottom-up merchant adoption estimates triangulated against top-down carrier technology spending allocations.
Segment-level value outputs across product type, technology deployment, and end-user categories were generated through structured modeling. The analytical framework incorporated API transaction volumes, policy issuance velocity, and platform integration density throughout the forecast period. CAGRs derived from regression against historical insurtech funding cycles and regulatory implementation timelines.
Inputs from EIOPA consultation papers and national regulator draft guidance were available through the study window; gaps in real-time merchant transaction data introduce uncertainty bands around platform adoption velocity. Forecasts reflect documented assumptions on regulatory harmonization speed and legacy carrier modernization capacity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Norway Property and Casualty Insurance Market
Insurance
Insurance BPO Services Market
Insurance
Europe Car Insurance Market
Insurance
Europe Online Insurance Market
Insurance
Financial Protection Market
Insurance
Boiler Insurance Market
Insurance
Marine Crew Insurance Market
Insurance
Digital Innovation in Insurance Market
Insurance
Saudi Arabia Travel Insurance Market
Insurance
Asia-Pacific Travel Insurance Market
Insurance
Canada Parametric Insurance Market
Insurance
United Kingdom Parametric Insurance Market
Insurance
Income Protection Insurance Market
Insurance
Drone Insurance Market
Insurance
Cargo Insurance Market
Insurance
UK Electronic Gadgets Insurance Market