
 Asia-Pacific Travel Insurance Market | 2026-2036
Asia-Pacific Travel Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Travel Insurance Market Analytics
Multi-source distribution is recalibrating how Asia-Pacific travel insurance reaches end buyers. Allianz SE leverages its bancassurance partnerships across Thailand and Indonesia to sustain premium flow at the point of sale. Ping An Insurance anchors its regional position through embedded offerings on Chinese outbound booking platforms. Tokio Marine Holdings competes via specialized coverage for senior travelers, a segment it dominates in its home market.
Asia-Pacific travel insurance constitutes short-term risk transfer instruments covering medical emergencies, trip interruption, and personal liability for cross-border travelers, typically underwritten through annual contracts or per-trip policies with 30-180 day coverage windows. Its primary commercial purpose is to absorb volatile healthcare costs and non-recoverable travel expenditures that fall outside standard health or property policies. Annual multitrip products lead the product type dimension by premium volume, while backpacker coverage generates the fastest policy growth among younger demographics. Online platforms now capture the dominant share of new policy issuance, though insurance brokers retain margin concentration in complex corporate accounts.
APRA in Australia, Japan's Financial Services Agency, and China's National Financial Regulatory Administration each impose distinct capital reserve and disclosure requirements on travel underwriters operating within their jurisdictions. These frameworks elevate barriers for new entrants while compelling incumbents to localize product architecture and claims infrastructure. Stakeholders must monitor how fragmented regulatory evolution across the region affects cross-border policy portability and reinsurance structuring.
Market Dynamics
Post-pandemic outbound travel normalization across Asia-Pacific is compressing policy distribution timelines, forcing underwriters to embed real-time underwriting engines directly into airline and hospitality booking flows.
Growth Catalysts
- Silver Demographics:Japan's aging outbound traveler base is accelerating demand for specialized medical evacuation and chronic condition coverage extensions.
- APRA Capital Frameworks:Stricter solvency requirements for Australian travel underwriters are filtering out thinly capitalized competitors, consolidating premium flow toward established carriers.
- Embedded Distribution:Chinese outbound booking platforms are integrating policy issuance at checkout, collapsing the traditional broker-mediated purchase cycle.
Market Restraints
- Healthcare Cost Volatility:Medical inflation in Southeast Asian destination markets is eroding loss ratios on standard emergency coverage products.
- Reinsurance Concentration:Catastrophe capacity for pandemic-related trip cancellation aggregates with a limited pool of Singapore-based reinsurers.
- Regulatory Fragmentation:Divergent disclosure requirements between Japan's Financial Services Agency and China's National Financial Regulatory Administration complicate cross-border policy portability.
Strategic Opportunities
- Indonesia Digital Infrastructure:Underpenetrated domestic travel segments present white space for micro-duration policies triggered by ride-hailing and intercity bus bookings.
- Climate Event Coverage:Parametric triggers for typhoon-related trip disruption are converging with satellite-based weather monitoring to enable instant claims settlement.
- India Outbound Expansion:RBI liberalization of foreign exchange allowances for leisure travel is expanding addressable premium pools for international medical coverage.
Industry Challenges
- Actuarial Talent Scarcity:Shortage of professionals with combined travel risk and health underwriting expertise constrains product innovation velocity.
- Legacy System Integration:Incumbent carriers face friction embedding API-first policy issuance into third-party distribution platforms without core system replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Travel Insurance Market |
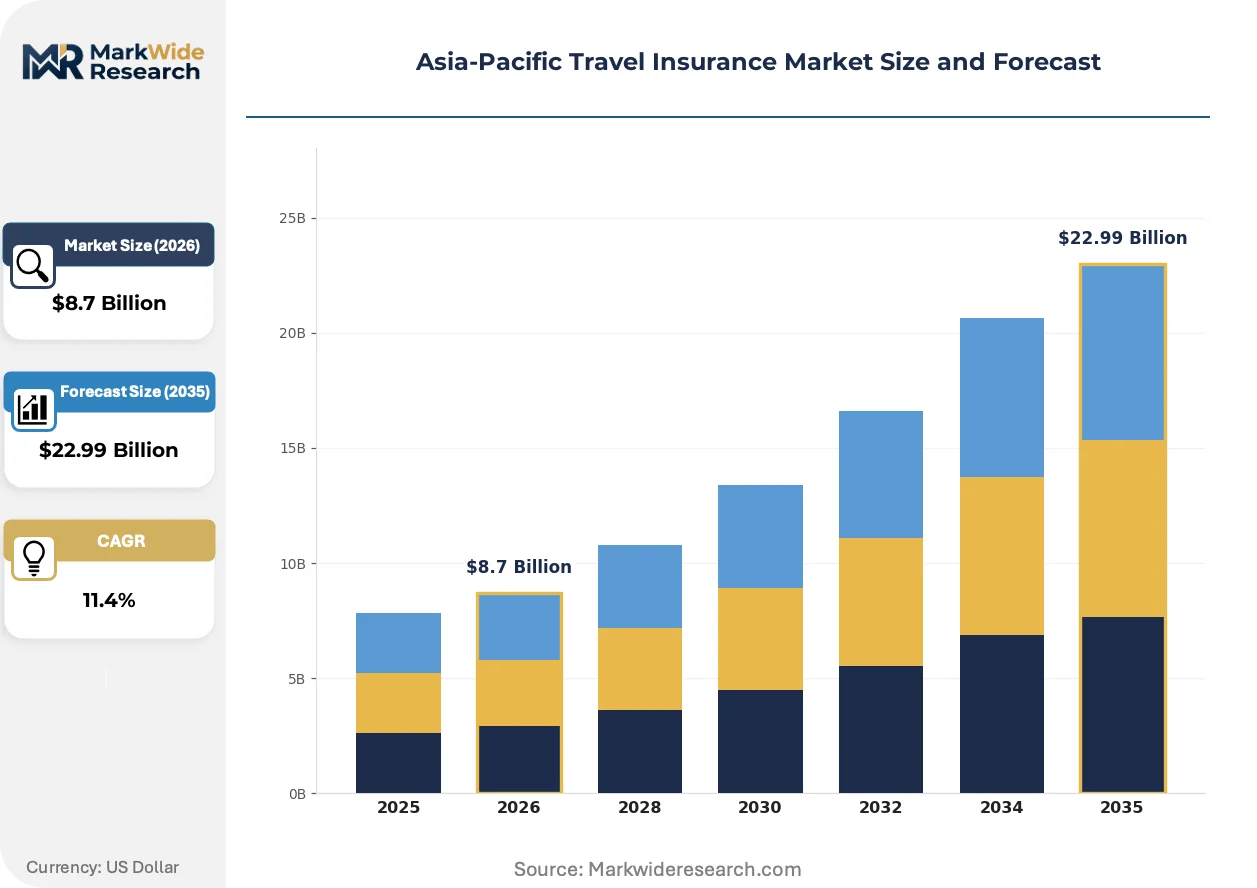
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Trip, Annual Multitrip, Backpacker, Business Travel Customer Type: Individual Travelers, Families, Corporate Clients, Students Distribution Channel: Direct Sales, Online Platforms, Travel Agencies, Insurance Brokers Coverage Type: Medical Expenses, Trip Cancellation, Lost Baggage, Personal Liability |
| Companies Covered | American International Group, Inc., QBE Insurance Group Limited, Allianz SE, Assicurazioni Generali S.p.A., Tokio Marine Holdings, Inc., AXA S.A., Chubb Limited, Ping An Insurance (Group) Co. of China Ltd, Zurich Insurance Group AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Travel Insurance Market Evolving Landscape
Real-time data streams from traveler devices and booking platforms are dissolving the traditional temporal gap between risk assessment and policy activation, compressing underwriting cycles from days to milliseconds.
Parametric claim settlement engines is absorbing the friction of manual documentation review for standard trip interruption events. Low-cost carriers across Thailand and Vietnam are adopting these triggers for mass-market policies. This compression is absorbing administrative overhead that previously consumed 15-20% of gross written premium.
Japan's Financial Services Agency disclosure mandates for policy wording transparency are forcing simplification of coverage exclusions. Australian underwriters operating in Japan must now localize product summaries to meet these standards. Senior traveler segments are responding with higher conversion rates on simplified annual multitrip products.
Direct-to-consumer platforms are disintermediating traditional insurance brokers for standard leisure policies. Corporate travel managers in Singapore and Hong Kong are consolidating procurement through specialized SaaS platforms that embed coverage comparison. This channel rotation is most visible in SME accounts previously served by generalist intermediaries.
Asia-Pacific Travel Insurance Market Segmentation
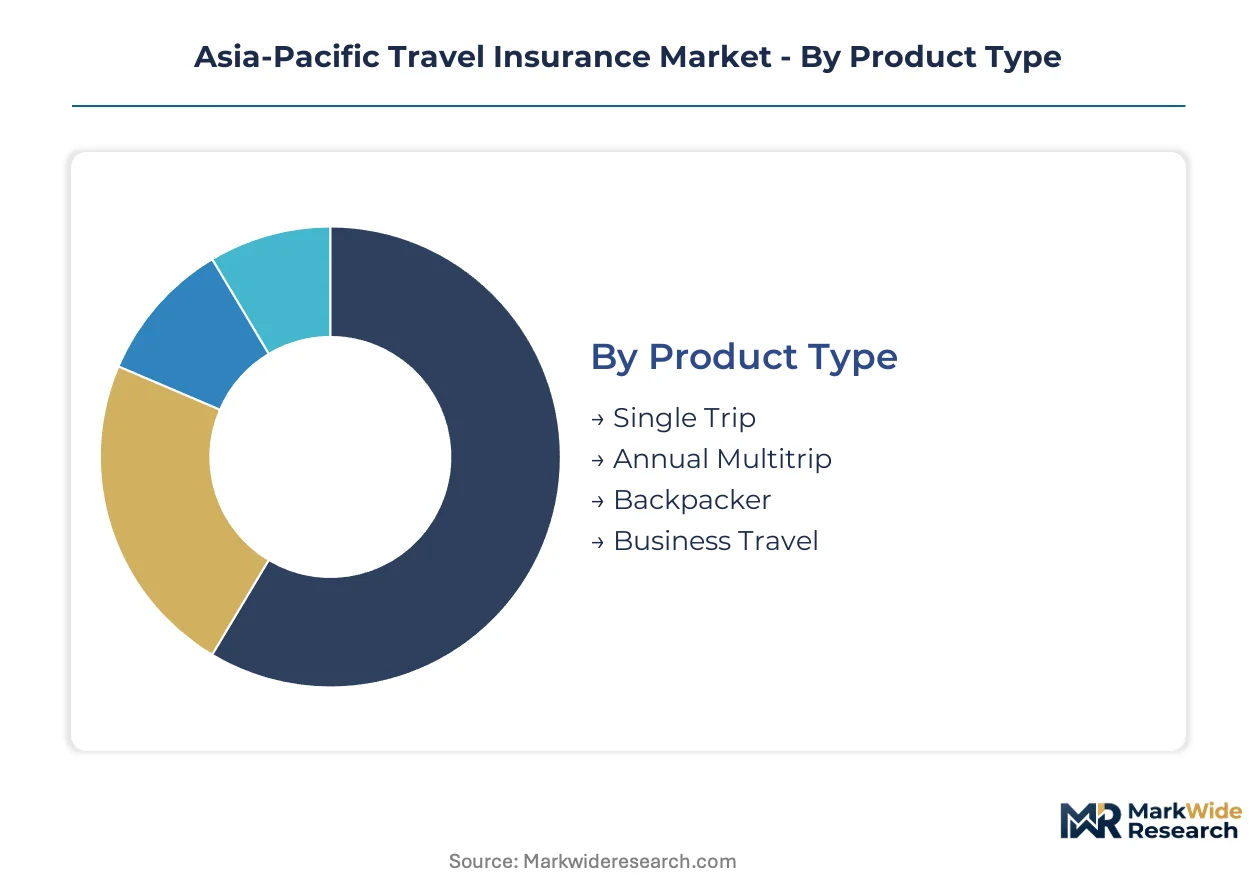
Asia-Pacific travel insurance segmentation reveals divergent profitability profiles across policy structures and buyer categories. Annual multitrip products concentrate premium volume while single-trip policies dominate policy count, creating distinct operational requirements for underwriters across the region.
Product Type:
Annual multitrip products generate the highest premium density per active policyholder, while single-trip coverage accounts for the greatest transaction frequency across distribution channels.
- Annual Multitrip:Bundled coverage for unlimited journeys within a 12-month window, typically capped at 90 days per trip. Corporate procurement in Singapore and Hong Kong drives bulk uptake as employers standardize protection for frequent flyers. APRA's capital adequacy requirements favor established carriers with balance sheet depth to underwrite these renewable portfolios.
- Single Trip:Per-journey protection activated for specific departure and return dates, spanning 30-180 day windows. Leisure travelers from Japan and South Korea purchasing through online platforms represent the core demand pool. Medical inflation in Southeast Asian destinations is compressing margins on standard emergency coverage within this segment.
- Backpacker:Extended-duration policies for travelers under 35 undertaking multi-destination itineraries. Australia's working holiday visa schemes and Indonesia's digital nomad permits are expanding addressable pools for specialized underwriters.
- Business Travel:Corporate-negotiated coverage incorporating trip cancellation, equipment protection, and evacuation services. Post-pandemic resumption of regional headquarters rotation in Thailand and Vietnam is rebuilding group policy volumes.
Mature deployment sits with Annual Multitrip products. Newer deployment is concentrated in Backpacker coverage gaining share fastest among younger demographics.
Customer Type:
Corporate clients command the highest average policy values, while individual travelers represent the deepest addressable base across price-sensitive and premium tiers.
- Individual Travelers:Solo policyholders purchasing through direct-to-consumer platforms or travel agency attachments. Japan's aging outbound demographic is accelerating demand for specialized medical evacuation extensions within this category.
- Families:Multi-traveler policies bundling dependent coverage under primary policyholder terms. Group pricing dynamics in Australia and New Zealand favor family plan uptake during school holiday peak seasons.
- Corporate Clients:Employer-sponsored group arrangements covering business travel and expatriate medical needs. Southeast Asian headquarters expansion is driving procurement consolidation through specialized SaaS platforms in Singapore.
- Students:Educational exchange and overseas study protection, typically mandated by host institutions. India's RBI liberalization of foreign exchange allowances is expanding outbound student volumes requiring international medical coverage.
Established penetration sits with Individual Travelers. Accelerating deployment is concentrated in Corporate Clients as regional business travel normalizes.
Distribution Channel:
Online platforms capture dominant new policy issuance velocity, while insurance brokers retain margin concentration in complex multi-jurisdictional accounts.
- Direct Sales:Carrier-owned channels including telephone centers and proprietary websites. Australian underwriters leverage direct relationships to bypass aggregator commissions on renewal business.
- Online Platforms:Comparison engines and embedded checkout integrations on booking sites. Chinese outbound travel platforms are collapsing traditional broker-mediated purchase cycles through policy issuance at checkout.
- Travel Agencies:Traditional intermediaries attaching coverage to package tour sales. Thailand and Vietnam agencies maintain relevance for mass-market leisure segments less comfortable with digital purchase.
- Insurance Brokers:Specialized intermediaries advising on corporate programs and high-net-worth individual coverage. Complex accounts across multiple Asia-Pacific jurisdictions sustain broker relevance despite platform disintermediation.
Legacy strength sits with Insurance Brokers. Platform migration is concentrating fastest in Online Platforms as real-time underwriting engines embed into airline and hospitality booking flows.
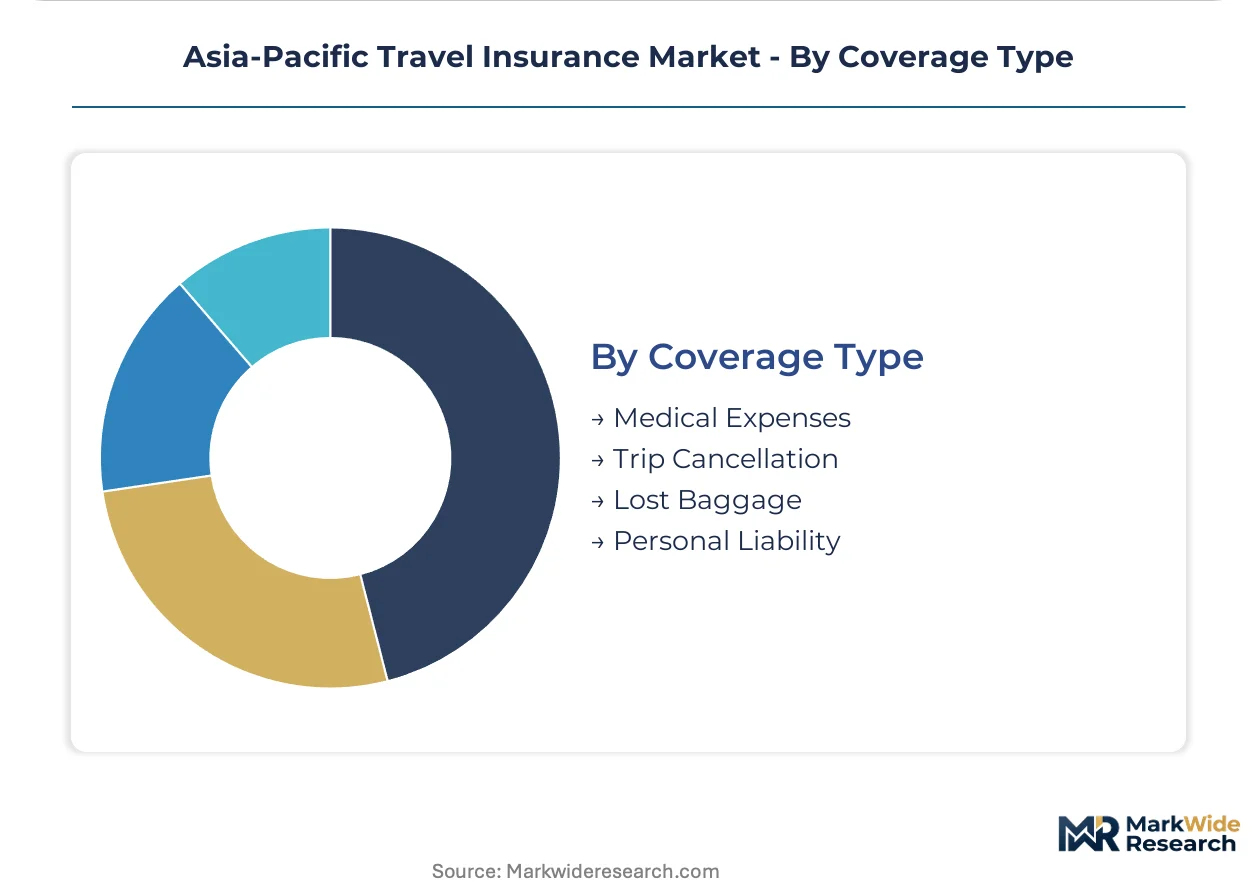
Coverage Type:
Medical expenses protection commands the highest claim frequency, while trip cancellation coverage carries the greatest severity variance for underwriters.
- Medical Expenses:Emergency treatment, hospitalization, and evacuation cost absorption outside home jurisdiction. Japan's aging outbound traveler base is accelerating specialized chronic condition coverage extensions within this category.
- Trip Cancellation:Reimbursement for non-recoverable prepaid travel costs due to covered events. Pandemic-related aggregates concentrate with a limited pool of Singapore-based reinsurers, constraining capacity.
- Lost Baggage:Personal effects and luggage replacement protection, typically sub-limited per item. Low-cost carrier adoption across Thailand and Vietnam drives attachment to mass-market policies.
- Personal Liability:Third-party injury or property damage protection during travel. Corporate travel managers in Hong Kong increasingly mandate this coverage for senior executive itineraries.
Standard deployment sits with Medical Expenses coverage. Parametric innovation is expanding fastest in Trip Cancellation as satellite-based weather monitoring enables instant claims settlement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo's outbound tourism recovery anchors premium flow across the Asia-Pacific travel insurance market. Singapore's reinsurance concentration shapes catastrophe capacity for trip cancellation aggregates. Sydney's APRA-regulated underwriters enforce capital adequacy standards that filter regional competition.
Japan
Japan's aging outbound traveler base accelerates specialized medical evacuation and chronic condition coverage extensions. The Financial Services Agency mandates simplified policy wording transparency, forcing product localization for foreign underwriters. Tokyo-based carriers dominate annual multitrip products for senior demographics.
Australia
APRA's stricter solvency requirements for travel underwriters filter thinly capitalized competitors toward established carriers. Sydney and Melbourne insurance clusters concentrate premium flow for renewable corporate portfolios. Direct sales channels bypass aggregator commissions on renewal business.
China
Outbound booking platforms embed policy issuance at checkout, collapsing traditional broker-mediated purchase cycles. The National Financial Regulatory Administration imposes distinct capital reserve requirements complicating cross-border policy portability. Shanghai and Beijing digital infrastructure anchors real-time underwriting engine deployment.
Singapore
Regional headquarters expansion drives procurement consolidation through specialized SaaS platforms for corporate travel managers. A limited pool of Singapore-based reinsurers concentrates catastrophe capacity for pandemic-related trip cancellation. The city-state's regulatory framework elevates barriers for new entrants.
Thailand
Low-cost carrier adoption drives parametric trigger attachment for mass-market policies across Bangkok and Phuket travel corridors. Bancassurance partnerships sustain premium flow at the point of sale for leisure segments. Post-pandemic business travel resumption rebuilds group policy volumes for corporate clients.
Asia-Pacific Travel Insurance Market Competitive Landscape
Embedded distribution partnerships dominate the current landscape, displacing traditional broker-mediated channels. The vendor base clusters around three archetypes: multinational conglomerates with bancassurance networks, domestic champions leveraging platform integrations, and specialized underwriters targeting demographic niches. Geographic expansion and technology licensing represent the primary competitive vectors as carriers localize product architecture across fragmented regulatory jurisdictions.
Within the multinational tier, Allianz SE and AXA S.A. exemplify carriers with established bancassurance partnerships across Southeast Asian markets. Tokio Marine Holdings occupies a position as a specialized underwriter anchored in senior traveler segments. Ping An Insurance represents the domestic champion archetype through embedded offerings on Chinese outbound booking platforms.
| Leading Market Players |
|---|
| American International Group, Inc. |
| QBE Insurance Group Limited |
| Allianz SE |
| Assicurazioni Generali S.p.A. |
| Tokio Marine Holdings, Inc. |
| AXA S.A. |
| Chubb Limited |
| Ping An Insurance (Group) Co. of China Ltd |
| Zurich Insurance Group AG |
| Others |
Value Network & Pricing Analysis
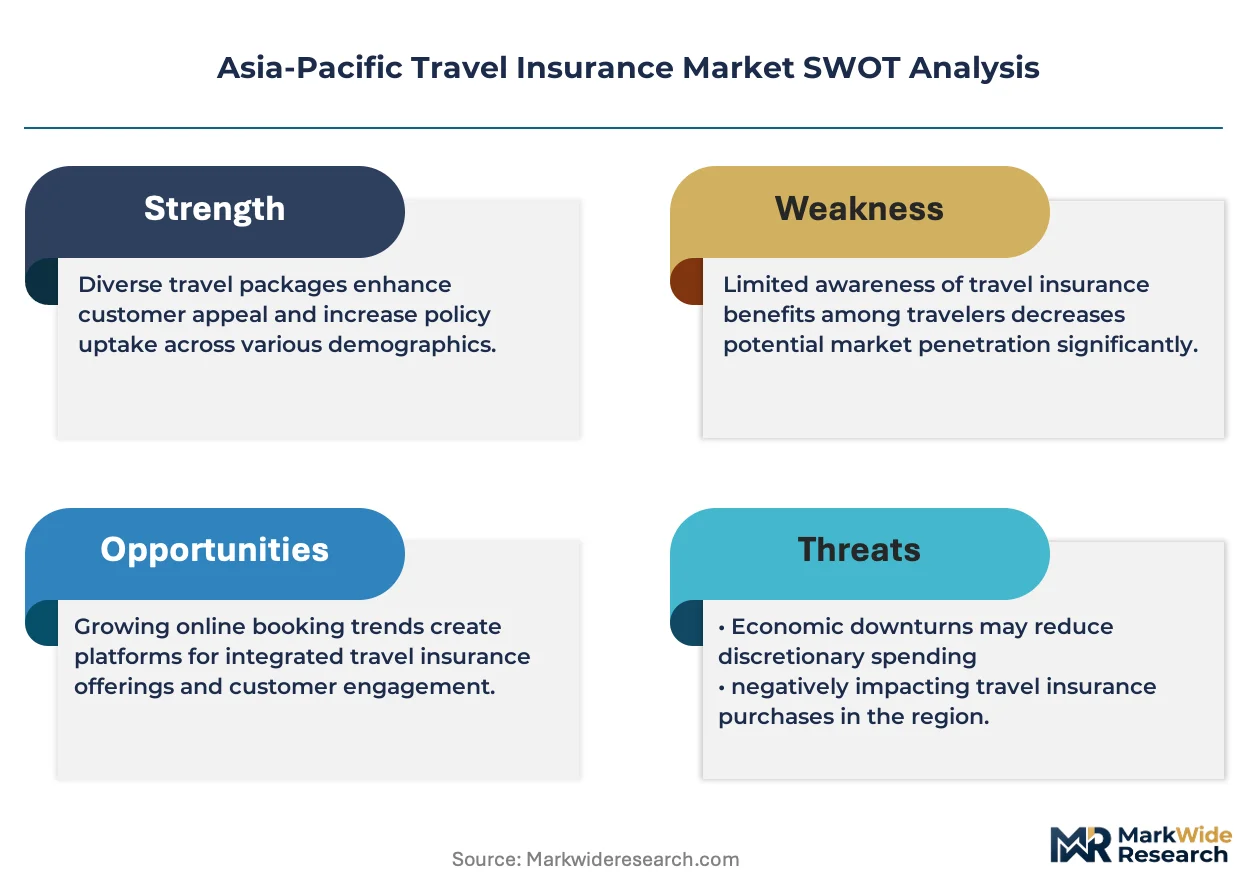
Horizontal integration across reinsurance and distribution layers anchors both supply positioning and pricing power for Asia-Pacific travel underwriters. Carriers with captive reinsurance arrangements in Singapore command superior rate-setting leverage against thinly capitalized competitors facing APRA solvency constraints.
Pricing Analysis
Warranty-style medical evacuation bundling separates premium tiers from stripped-down emergency-only coverage. Three-tier pricing structure across premium, standard, and economy levels tracks customer age bands and trip duration complexity. Cost compression in economy tiers intensifies because Southeast Asian medical inflation erodes loss ratios. Backpacker segments exhibit highest price sensitivity while corporate procurement in Singapore shows lowest elasticity due to duty-of-care mandates.
Supply Chain Analysis
Direct-to-carrier digital channels handle individual traveler volume while broker-mediated structures manage corporate account complexity. Reinsurance capacity concentrates in Singapore, Australia, and Japan. Claims processing infrastructure draws from India, Philippines, and Malaysia. Single-source vulnerability sits with Singapore-based catastrophe capacity for pandemic-related trip cancellation. Distribution runs through embedded checkout integrations on Chinese outbound platforms and Thai bancassurance networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reinsurance capacity scarcity props pricing power across the Asia-Pacific travel insurance market. Singapore's limited catastrophe pool for trip cancellation aggregates creates structural supply constraints.
For Market Incumbents: Deepen vertical integration into reinsurance structures to secure catastrophe capacity before Singapore capacity tightens further. Expand parametric claims settlement capabilities to absorb administrative overhead that competitors cannot match. Lock in multi-year corporate contracts in Thailand and Vietnam before regional headquarters rotation completes. For New Entrants and Emerging Players: Digital nomad visa holders in Indonesia represent an underserved buyer archetype with minimal incumbent presence. White space exists in micro-duration policies triggered by ride-hailing and intercity bus bookings. Climate event coverage with satellite-based parametric triggers offers differentiation in typhoon-exposed markets. Go-to-market through direct API integration with Indonesian super-app platforms bypasses established broker relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to multinational carriers seeking Asia-Pacific platform scale. Long-term viability hinges on regulatory license portability across Japan's Financial Services Agency and China's National Financial Regulatory Administration boundaries. Acquisition targets should demonstrate embedded distribution partnerships with outbound travel platforms. Watch for APRA capital adequacy enforcement as inflection indicator for Australian competitor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Claims Engine Deployment | Satellite-based weather monitoring enables instant settlement for typhoon-related trip disruption across Thai and Vietnamese low-cost carrier partnerships. |
| Embedded Distribution Partnership | API integration with Chinese outbound booking platforms collapses traditional broker-mediated purchase cycles at point of sale. |
| Reinsurance Capacity Lock-in | Multi-year catastrophe treaties with Singapore-based reinsurers secure trip cancellation aggregate protection before capacity tightens. |
| Senior Traveler Product Localization | Simplified policy wording meets Japan's Financial Services Agency transparency mandates while capturing aging outbound demographic conversion. |
| Corporate SaaS Platform Integration | Specialized procurement platforms in Singapore and Hong Kong embed coverage comparison for SME accounts previously served by generalist intermediaries. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Asia-Pacific travel insurance analysis. Primary interviews with underwriters, reinsurance brokers, corporate travel managers, and platform integration specialists combined with APRA solvency disclosures, Japan Financial Services Agency policy wordings, and Chinese outbound travel platform transaction data. Bottom-up policy issuance modeling triangulated against top-down premium flow estimates across the analysis window.
Granularity-level modeling tracked product type, customer segment, distribution channel, and coverage category dimensions at country level. Annual multitrip and single-trip policy structures were modeled separately with distinct loss ratio assumptions. CAGRs derived from time-series regression across the projection horizon incorporating outbound travel recovery trajectories, medical inflation differentials, and regulatory capital requirement phase-ins.
Revisions become necessary when pandemic-related trip cancellation aggregates exceed Singapore reinsurer capacity, APRA tightens solvency ratios, or China's National Financial Regulatory Administration restricts cross-border policy portability. Forecasts reflect assumptions about outbound tourism normalization velocity and medical cost trajectories in Southeast Asian destinations. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
India Travel Insurance Market
Insurance
Peer to Peer Insurance Market
Insurance
Germany Travel Insurance Market
Insurance
Crop Insurance Market
Insurance
Compulsory Third Party (CTP) Insurance Market
Insurance
Europe Road Assistance Insurance Market
Insurance
Engineering Insurance Market
Insurance
Financial Guarantee Market
Insurance
Saudi Arabia Property and Casualty Insurance Market
Insurance
US Travel Insurance Market
Insurance
Saudi Arabia Health & Medical Insurance Market
Insurance
Netherlands Property and Casualty Insurance Market
Insurance
AI in Insurance Market
Insurance
Europe Travel Insurance Market
Insurance
Europe Bancassurance Market
Insurance
Global Fine Art Insurance Market