
 Marine Crew Insurance Market | 2026-2036
Marine Crew Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Crew Insurance Market Analysis
Claims management revenue is tilting toward medical repatriation and disability settlements as crew welfare liabilities escalate. Gard leverages its Oslo-based mutual structure to sustain competitive pricing for ocean-going fleets. Chubb anchors its position through specialized offshore energy crew programs. Allianz competes via digital claims platforms that reduce settlement cycles for international seafarers.
Marine crew insurance provides financial protection against injury, illness, death, and repatriation expenses for seafarers, with policies typically incorporating war-risk exclusions and jurisdictional clauses tied to flag-state requirements. Coverage type segments show medical expenses and repatriation costs commanding premium attention as port-state control inspections intensify under MLC protocols. Distribution channel dynamics reveal brokers dominating placement for deep-sea fleets while online platforms gain traction among yacht and small-craft operators seeking rapid quote turnaround.
The International Labour Organization's Maritime Labour Convention shapes minimum coverage mandates, while flag-state regulators such as the UK's Maritime and Coastguard Agency and Panama's Merchant Marine Directorate enforce compliance through vessel inspection regimes. The EU's Insurance Distribution Directive affects how London-based brokers and underwriters market policies across member states. Stakeholders must monitor emerging mental health coverage requirements and evolving definitions of shipowner liability as crew welfare standards tighten.
Market Dynamics
The International Maritime Organization's Maritime Labour Convention enforcement is compressing compliance timelines for shipowners, forcing rapid upgrades to crew protection packages as port-state control inspections intensify across major flag registries.
Growth Catalysts
- MLC 2006 Certification Mandates:Flag registries in Panama and Liberia now require documented crew insurance certificates before vessel registration renewal, expanding policy placement volumes.
- Offshore Energy Expansion:North Sea and Gulf of Mexico drilling contractors are extending coverage to specialist technicians aboard dynamic positioning vessels.
- Telemedicine Integration:Satellite-connected diagnostic tools aboard container fleets are reducing emergency evacuation costs and lowering claims severity for underwriters.
Market Restraints
- Medical Cost Inflation:Hospital charges in Singapore and Dubai—primary repatriation hubs—are rising faster than premium adjustments can absorb.
- Mutual Club Concentration:The thirteen-member International Group of P&I Clubs controls liability coverage for ninety percent of ocean-going tonnage, limiting price competition.
- War Risk Exclusions:Standard policies exclude Red Sea and Black Sea routes, forcing shipowners to purchase separate riders at volatile rates.
Strategic Opportunities
- Mental Health Coverage Gaps:Post-traumatic stress and isolation-related claims are emerging as unmet needs among long-haul container crews.
- Digital Broker Platforms:Online placement systems are penetrating the yacht and small-craft segment previously served by traditional intermediaries.
- EU Green Deal Alignment:Crew insurance products bundled with environmental compliance services can capture ESG-focused shipowner budgets.
Industry Challenges
- Claims Adjudication Expertise:Underwriters lack sufficient maritime medical specialists to assess complex disability settlements across multiple jurisdictions.
- Legacy System Integration:Established P&I clubs struggle to connect paper-based membership records with automated claims processing platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Crew Insurance Market |
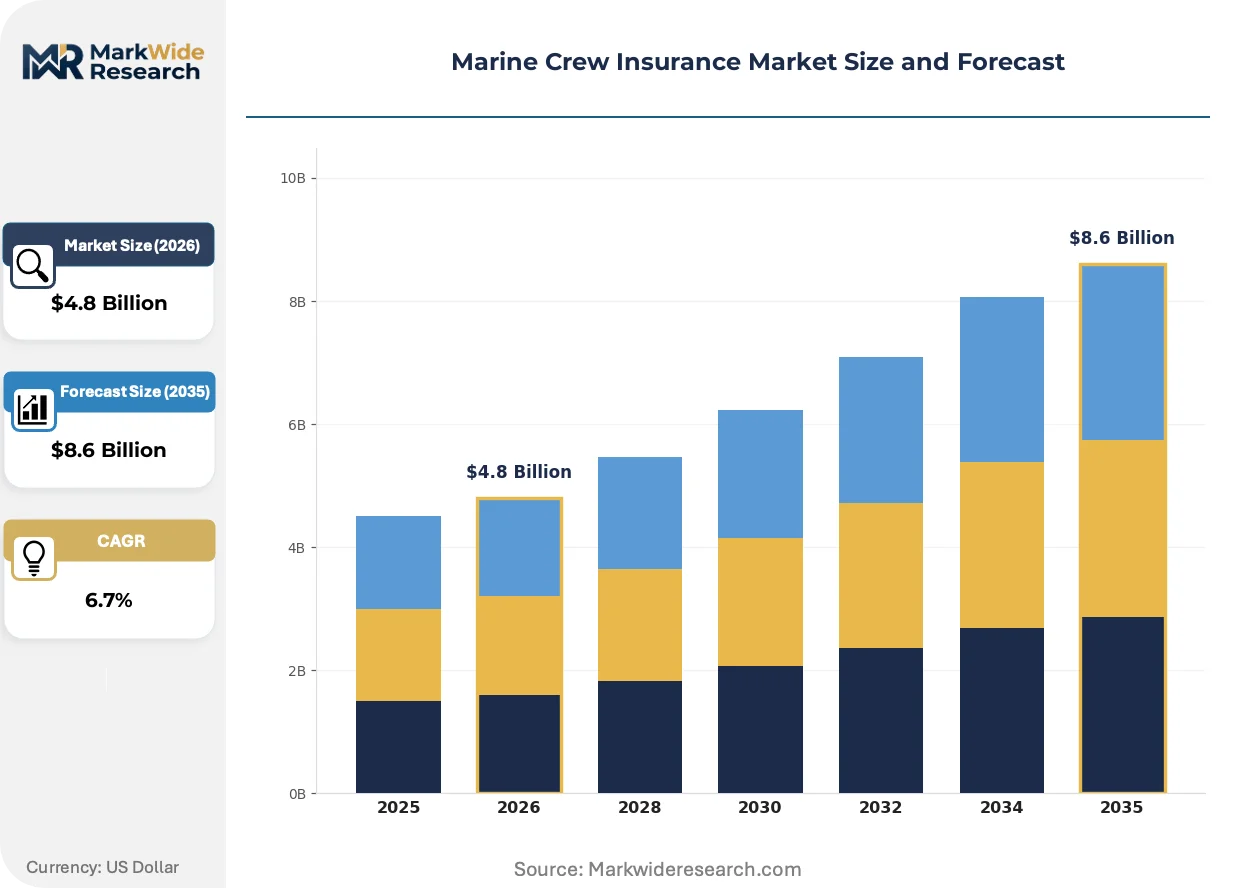
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: Medical Expenses, Liability Coverage, Accidental Death, Repatriation Costs Underwriting Criteria: Experience Level, Crew Size, Vessel Type, Employment Contract Type Policy Duration: Short-Term, Long-Term, Annual, Temporary Distribution Channel: Brokers, Direct Sales, Online Platforms, Insurers |
| Companies Covered | Chubb, Superyacht Insurance Group, Gard, Progressive, Global Marine Insurance Agency, China P&I Club, Marsh, Nationwide, Allianz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Crew Insurance Market Emerging Trajectories
Artificial intelligence and satellite connectivity are compressing claims settlement cycles while regulatory mandates expand coverage definitions beyond traditional injury and illness parameters.
Blockchain-enabled smart contracts are digitizing policy verification for port-state control inspectors. The Marshall Islands and Bahamas maritime administrations now accept cryptographic certificates during vessel inspections. This compression of documentation friction is digitizing compliance workflows and reducing detention risks for shipowners.
The EU's Insurance Distribution Directive is tightening cross-border marketing rules for London-based brokers placing coverage with German and Greek shipowners. Underwriters must now maintain licensed branches in each member state where policies are sold. Mediterranean and Baltic fleet operators are responding by consolidating placements with EU-domiciled intermediaries.
Shipowners are unbundling medical repatriation from standard P&I coverage and purchasing standalone policies through specialized aviation brokers. This behavior shift is most visible among Asian container lines operating ultra-large vessels with four-thousand-plus crew rotations annually. Dedicated air ambulance contracts now compete with traditional marine underwriters for the same risk pool.
Marine Crew Insurance Market Segmentation
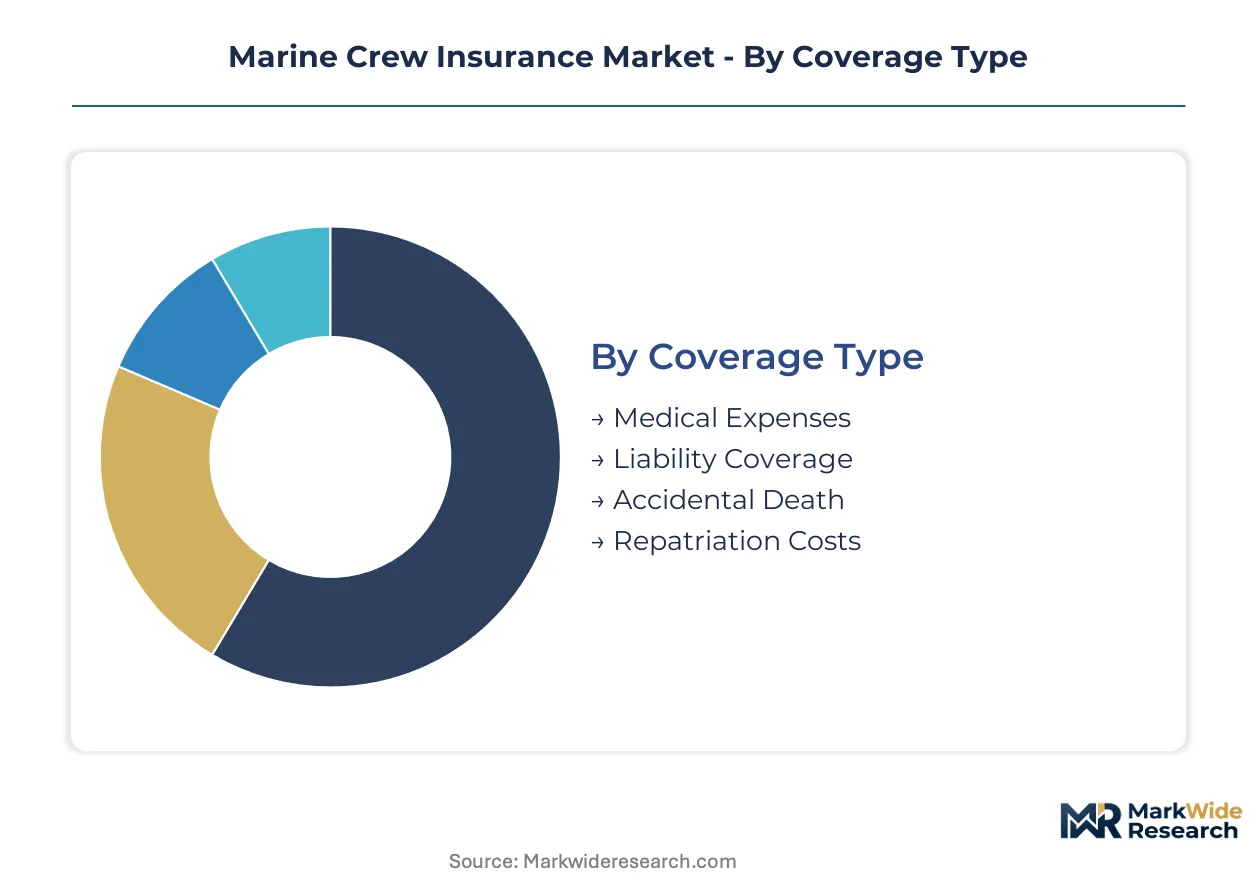
Marine crew insurance segmentation reveals how policy structures align with vessel operational profiles and regulatory compliance pathways. Underwriters calibrate pricing and coverage depth through distinct lenses that reflect maritime risk assessment conventions.
Coverage Type:
After-sales service intensity varies sharply across coverage categories, with medical and repatriation claims demanding 24/7 emergency response infrastructure while liability coverage relies on slower legal adjudication cycles.
- Medical Expenses:Policies reimburse hospitalization, surgery, and pharmaceutical costs for illness or injury occurring during service periods. Demand concentrates among Singapore-flagged container fleets where port-state control inspections under MLC protocols mandate documented medical coverage. Crew welfare liability escalation is compressing settlement timelines.
- Repatriation Costs:Coverage spans emergency medical evacuation, mortal remains transport, and family accompaniment expenses. Asian container lines operating ultra-large vessels with high crew rotation volumes are unbundling this from standard P&I coverage and purchasing standalone aviation broker contracts. Satellite-connected diagnostic tools are reducing emergency evacuation frequency.
- Liability Coverage:Protects shipowners against crew claims for workplace injury, negligence, or contractual disputes under maritime labor conventions.
- Accidental Death:Provides lump-sum benefits to designated beneficiaries when crew members perish from covered perils during employment.
By volume, medical expenses leads. By growth pace, repatriation costs is expanding most quickly.
Underwriting Criteria:
Cost tier differentiation shapes premium calculation methodologies, with high-experience master mariners commanding favorable rates versus entry-level ratings on volatile routes.
- Vessel Type:Dynamic positioning offshore energy vessels, ultra-large container ships, and chemical tankers each carry distinct risk profiles affecting premium structures. North Sea and Gulf of Mexico drilling contractors are extending coverage to specialist technicians aboard DP vessels.
- Crew Size:Aggregate exposure scales non-linearly with headcount, with four-thousand-plus crew rotation vessels requiring dedicated claims management infrastructure. Singapore and Dubai hospital charge inflation is outstripping premium adjustment capacity for large crews.
- Experience Level:Master mariners and licensed officers receive preferential terms versus entry-level ratings.
- Employment Contract Type:Permanent, fixed-term, and casual arrangements trigger varying coverage activation rules.
By volume, vessel type leads. By margin contribution, crew size is climbing the fastest.
Policy Duration:
Application flexibility distinguishes short-cycle placements for project-specific voyages from multi-year fleet programs that lock in rate stability.
- Annual:Standard renewal cycles align with vessel registration and classification society survey schedules. Flag registries in Panama and Liberia now require documented crew insurance certificates before registration renewal, expanding annual placement volumes.
- Long-Term:Multi-year agreements stabilize budgeting for shipowners with predictable trading patterns. Established P&I clubs leverage mutual structures to sustain competitive pricing for ocean-going fleets under extended terms.
- Short-Term:Covers single voyages or temporary crew assignments.
- Temporary:Addresses gap coverage during vessel lay-up or ownership transfer periods.
By volume, annual leads. By placement velocity, long-term is gaining share fastest.
Distribution Channel:
Customer type fragmentation separates deep-sea fleet procurement through intermediaries from small-craft operators seeking direct digital access.
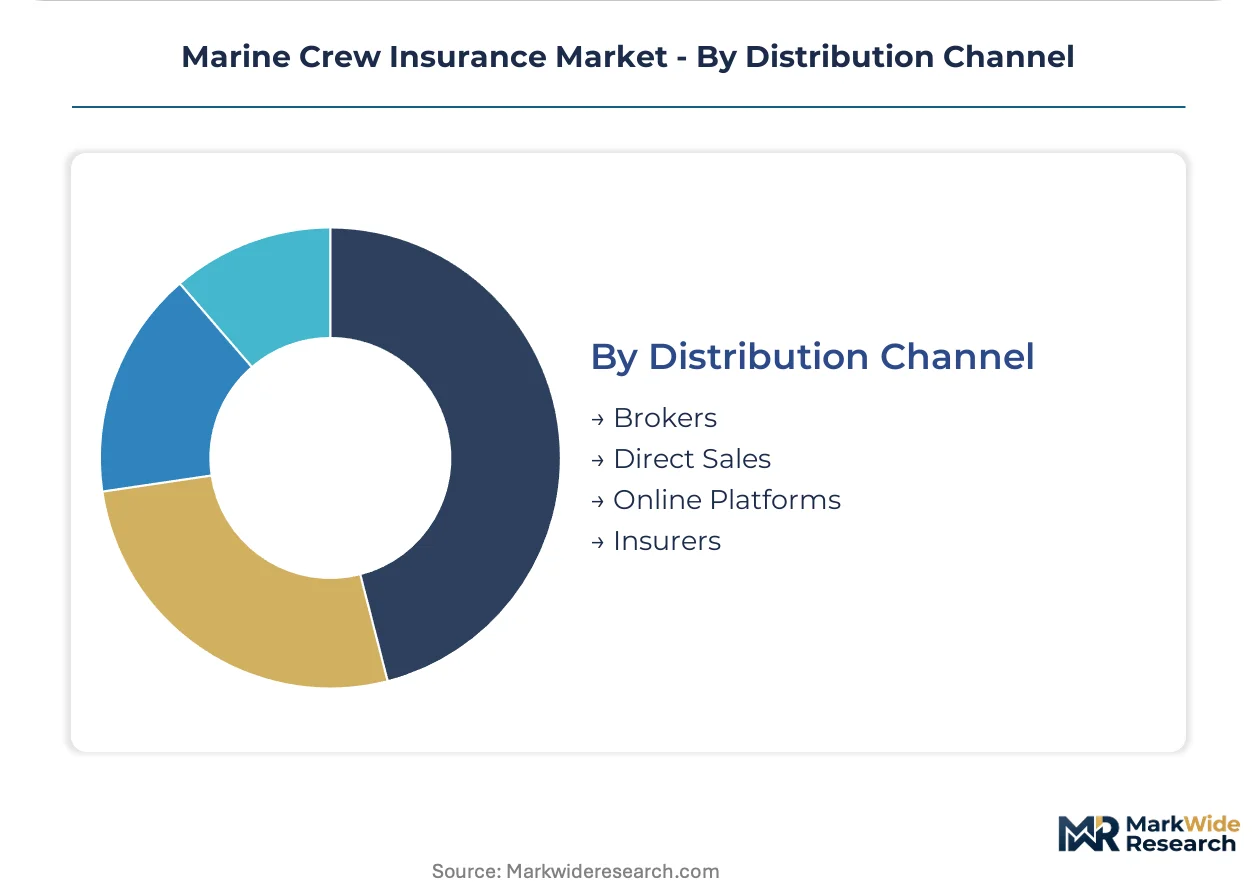
- Brokers:Traditional intermediaries dominate placement for deep-sea fleets, leveraging relationships with London and Singapore underwriters. The EU's Insurance Distribution Directive is tightening cross-border marketing rules for London-based brokers placing coverage with German and Greek shipowners.
- Online Platforms:Digital placement systems are penetrating the yacht and small-craft segment previously served by traditional intermediaries, offering rapid quote turnaround. Mediterranean and Baltic fleet operators are consolidating placements with EU-domiciled intermediaries.
- Direct Sales:Shipowners with captive insurance capabilities or large fleets negotiate directly with underwriters.
- Insurers:P&I clubs and commercial underwriters maintain direct relationships with select large accounts.
By volume, brokers leads. By channel shift velocity, online platforms shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shipowners in Panama and Liberia exhibit the highest price elasticity, driving mutual club competition, while Singapore-based operators absorb premium increases with minimal volume attrition. European flag registries enforce stricter coverage mandates that compress underwriting margins. Asian container lines prioritize claims settlement speed over rate negotiation.
Singapore
Port-state control inspections under MLC protocols drive documented medical coverage requirements for container fleets. The Monetary Authority of Singapore coordinates with the Maritime and Port Authority to enforce crew welfare liability standards. The Singapore marine insurance hub concentrates P&I clubs and commercial underwriters competing on claims response infrastructure.
Norway
North Sea offshore energy expansion extends coverage demand for dynamic positioning vessel technicians. The Norwegian Maritime Authority enforces strict crew protection certification for vessel registration. Oslo anchors Gard's mutual structure serving ocean-going fleets with competitive pricing through extended terms.
United Kingdom
London-based brokers face tightened cross-border marketing rules under the EU's Insurance Distribution Directive. The Maritime and Coastguard Agency enforces MLC compliance through vessel inspection regimes. The City of London insurance cluster sees Mediterranean and Baltic fleet operators consolidating placements with EU-domiciled intermediaries.
United States
Gulf of Mexico drilling contractors expand specialist technician coverage aboard offshore energy vessels. The Coast Guard enforces flag-state requirements tied to crew insurance documentation. Houston and New Orleans marine insurance operations serve energy sector demand with dedicated offshore energy crew programs.
Germany
Greek and German shipowners drive demand for digital claims platforms reducing settlement cycles. The Federal Financial Supervisory Authority implements EU Insurance Distribution Directive requirements for policy marketing. Hamburg's marine insurance brokers adapt to licensed branch requirements for cross-border coverage placement.
Marine Crew Insurance Market Vendor Landscape
Mutual clubs and commercial underwriters split the market between liability-focused collective structures and profit-oriented specialized programs. The thirteen-member International Group of P&I Clubs controls ninety percent of ocean-going tonnage, creating a concentrated liability tier alongside fragmented commercial underwriters. Three archetypes dominate: mutual P&I clubs leveraging collective pricing power, global commercial insurers bundling crew coverage with broader marine portfolios, and specialized brokers unbundling repatriation for aviation contract placement. Competitive moves center on telemedicine integration to compress claims severity and digital platform deployment to accelerate quote turnaround.
Among mutual structures, Gard exemplifies the Oslo-based collective model sustaining competitive pricing through member retention. Chubb anchors the commercial tier with specialized offshore energy crew programs targeting drilling contractor demand. Allianz occupies a position emphasizing digital claims infrastructure for international seafarer settlement acceleration. These three represent the archetype spectrum from mutual collective through commercial specialization to technology-enabled service differentiation.
| Leading Market Players |
|---|
| Chubb |
| Superyacht Insurance Group |
| Gard |
| Progressive |
| Global Marine Insurance Agency |
| China P&I Club |
| Marsh |
| Nationwide |
| Allianz |
| Others |
Supply Flow & Price Mechanics
Singapore-Dubai repatriation corridor cost inflation feeds directly into premium pricing tiers and pushes shipowners toward unbundled aviation broker contracts. The thirteen-member International Group of P&I Clubs concentrates liability coverage pricing power while commercial underwriters compete on claims response speed.
Pricing Analysis
Claims management revenue drives lifetime value across medical repatriation and disability settlement tiers. Three-tier pricing structure across premium, standard, and economy levels separates mutual club members from commercial program buyers and direct-placement yacht operators. Price differentiation rests on crew size scale and telemedicine integration depth. Cost compression in medical expense coverage is intensifying because Singapore and Dubai hospital charges outpace premium adjustment capacity. Asian container lines with four-thousand-plus crew rotations show highest price sensitivity, while offshore energy drilling contractors absorb increases with minimal volume attrition.
Supply Chain Analysis
Export-control regimes on satellite-connected diagnostic technology limit telemedicine platform flows into certain flag registries. Underwriting capacity concentrates in the United Kingdom, Singapore, and Norway. Raw material inputs include aviation broker networks, maritime medical specialist labor, and satellite bandwidth for remote diagnostics. Single-source vulnerability sits with the thirteen-member International Group controlling ninety percent of ocean-going tonnage liability coverage. Distribution runs through London and Singapore broker clusters for deep-sea fleets, with online platforms penetrating yacht and small-craft segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine crew insurance functions as a service-attach opportunity where claims management and medical repatriation revenue layers expand faster than base liability coverage. Recurring premium streams from multi-year fleet programs now outpace single-voyage placements.
For Market Incumbents: Entrench mutual club positioning through telemedicine integration that compresses claims severity and accelerates settlement cycles. Invest in licensed EU branch infrastructure to defend against Insurance Distribution Directive compliance pressure from London-based competitors. Channel control over aviation broker relationships protects against unbundling behavior among Asian container lines.
For New Entrants and Emerging Players: Mental health coverage gaps among long-haul container crews represent the most penetrable entry point for specialized programs. Digital broker platforms serving yacht and small-craft operators offer rapid quote turnaround unavailable through traditional intermediaries. Partner with satellite diagnostic providers to embed telemedicine into policy bundles.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified marine insurers with neglected crew protection divisions. Long-term viability hinges on regulatory compliance service bundling as MLC enforcement tightens across flag registries. Monitor port-state control inspection data as an inflection indicator for policy placement volume shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Telemedicine Platform Integration | Satellite-connected diagnostic tools reduce emergency evacuation costs for underwriters serving container fleets. |
| EU Licensed Branch Expansion | London-based brokers establish compliant presence to serve German and Greek shipowners under Insurance Distribution Directive rules. |
| Mental Health Coverage Program Launch | Post-traumatic stress and isolation-related policies address unmet needs among long-haul seafarers. |
| Aviation Broker Partnership | Standalone repatriation contracts compete with traditional P&I coverage for Asian container line risk pools. |
| Blockchain Certificate Deployment | Marshall Islands and Bahamas maritime administrations accept cryptographic policy verification during vessel inspections. |
Methodological Framework
Initial hypotheses were tested against primary input from marine underwriters, P&I club claims managers, shipowner procurement officers, and aviation broker specialists and refined through secondary validation. Primary research combined structured interviews with secondary analysis of International Maritime Organization MLC compliance reports, flag registry documentation requirements, and Lloyd's List marine insurance transaction data. Bottom-up policy placement volume estimates triangulated against top-down market sizing from premium pool analysis.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include coverage type, vessel category, crew size tier, policy duration, and distribution channel. CAGRs were derived from regression analysis of historical placement volumes and forward assessment of regulatory compliance drivers. Industry-specific forecast inputs incorporated port-state control inspection frequency projections and telemedicine adoption curves among container fleet operators.
Practitioners should monitor MLC enforcement intensity and mental health coverage mandate expansion for early signals. Forecasts reflect assumptions about mutual club pricing discipline and medical cost inflation trajectories. Material shifts in International Group coverage terms or Singapore-Dubai hospital charge escalation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Online Insurance Market
Insurance
Japan Parametric Insurance Market
Insurance
China Group Health Insurance Market
Insurance
South Korea Liability Insurance Market
Insurance
Singapore Property and Casualty Insurance Market
Insurance
Business Income Insurance Market
Insurance
Europe Health Insurance Market
Insurance
North America Liability Insurance Market
Insurance
Asia-Pacific Family Floater Health Insurance Market
Insurance
North America Family Floater Health Insurance Market
Insurance
Norway Property and Casualty Insurance Market
Insurance
IoT Insurance Market
Insurance
Djibouti Insurance Market
Insurance
Canada House Insurance Market
Insurance
Disability Insurance Market
Insurance
Europe Road Assistance Insurance Market