
 Cargo Insurance Market | 2026-2036
Cargo Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Cargo Insurance Market Analysis
EU Green Deal compliance is broadening the cost-of-entry calculus for cargo underwriters operating in European trade lanes. Allianz Commercial leverages proprietary climate-risk modeling to differentiate marine coverage offerings. Lloyd's of London anchors specialty cargo underwriting through its syndicated market structure. AXA SA competes across multimodal segments with integrated supply-chain risk services.
Cargo insurance is a contract of indemnity covering physical loss or damage to goods during transit, with policies specifying valuation methods, general average clauses, and Institute Cargo Clauses A/B/C as technical parameters. All Risk coverage dominates premium pools due to comprehensive protection against external perils, while Named Perils retains share among commodity shippers with predictable loss profiles. Ocean Freight generates the largest absolute premium volume given vessel capacity and voyage duration, though Air Freight commands higher rate-on-line multiples per unit value.
EMA guidelines on pharmaceutical distribution integrity, EU F-Gas Regulation affecting refrigerated container standards, and ISO 28000 supply-chain security certifications collectively reshape coverage requirements and underwriting criteria. Lloyd's of London, EMA, and ISO standards intersect where temperature-controlled biologics transit through multiple regulatory jurisdictions. Stakeholders must monitor how sustainability disclosure mandates reconfigure risk transfer structures between shippers and carriers.
Market Dynamics
Pharmaceutical cold-chain logistics are forcing cargo underwriters to rebuild risk models around temperature excursions and biologic degradation, as EMA distribution integrity guidelines harden coverage requirements for temperature-sensitive shipments across European trade lanes.
Growth Catalysts
- EU Corporate Sustainability Reporting Directive:Mandatory supply-chain risk disclosure is compelling shippers to purchase documented cargo coverage, expanding the addressable premium pool.
- Biologics manufacturing:Cell and gene therapies require strict cold-chain custody, creating specialized coverage demand with rate-on-line multiples above standard freight.
- Hamburg port infrastructure:Continental Europe's largest container throughput anchors German demand concentration, with multimodal connectivity extending coverage requirements inland.
Market Restraints
- Refrigerant input volatility:EU F-Gas Regulation phase-down schedules are compressing hydrofluorocarbon availability, raising reefer container operating costs and claims severity.
- Marine hull capacity concentration:Lloyd's of London syndicates and Bermuda reinsurers control disproportionate catastrophe exposure, creating systemic pricing pressure after major vessel casualties.
- Valuation methodology rigidity:Institute Cargo Clauses A/B/C standardization limits product differentiation, compressing margin for non-specialist underwriters.
Strategic Opportunities
- Indian pharmaceutical exports:CDSCO-regulated manufacturing hubs in Hyderabad and Ahmedabad are expanding temperature-controlled shipments to Europe and North America, creating underpenetrated premium pools.
- Parametric coverage models:IoT sensor integration with blockchain verification enables automated claims settlement for verified temperature breaches.
- ISO 28000 certification mandates:Supply-chain security standards are becoming procurement prerequisites, bundling insurance with compliance services.
Industry Challenges
- Climate risk modeling talent scarcity:Catastrophe modelers with marine and temperature-logistics expertise command premium compensation, constraining mid-market underwriter expansion.
- Legacy policy administration systems:Mainframe-based rating engines struggle to integrate real-time sensor data, delaying parametric product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cargo Insurance Market |
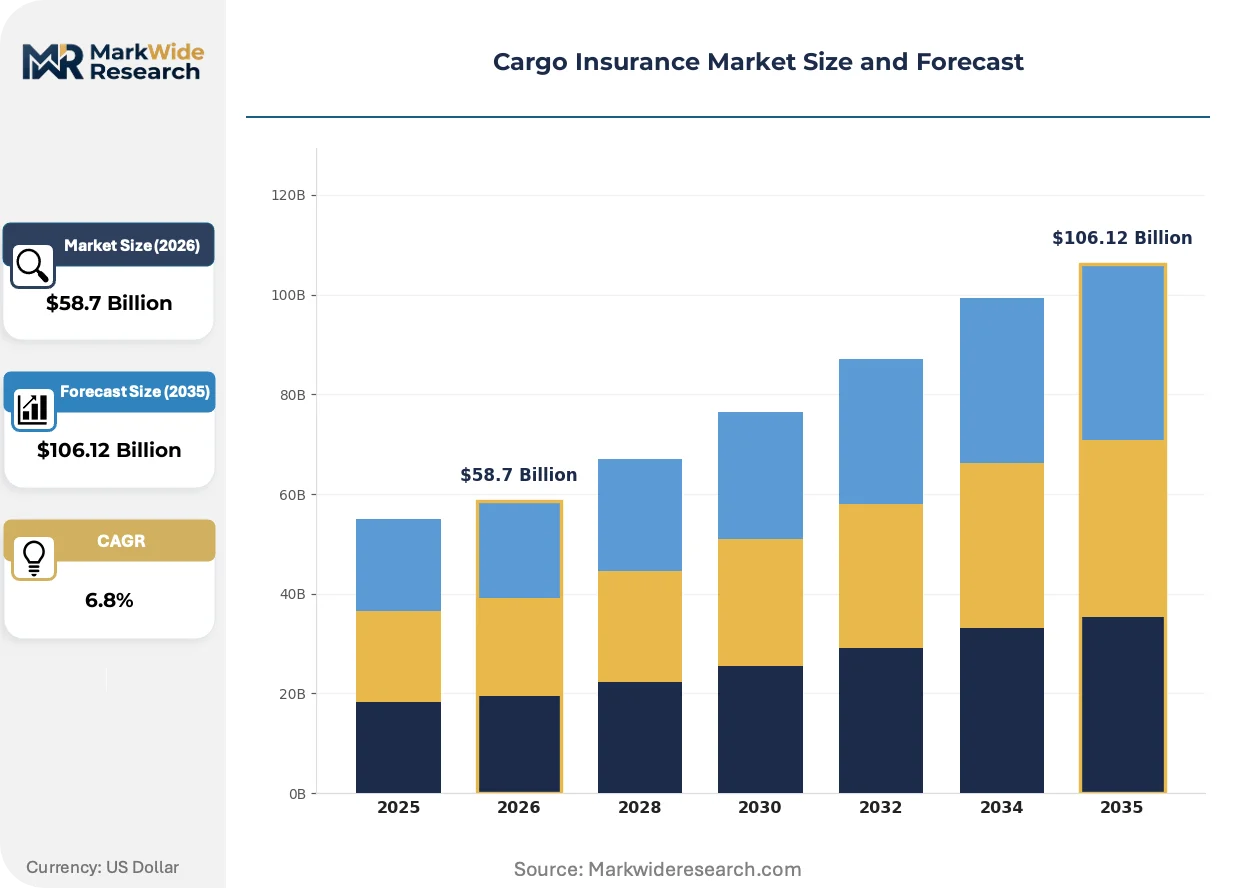
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $106.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: All Risk, Total Loss, Named Perils, Freight Insurance Transport Mode: Air Freight, Ocean Freight, Rail Transport, Road Transport Policy Type: Single Shipment, Annual Policy, Open Cover, Specific Policy Insurer Type: Insurers, Brokers, Underwriters, Reinsurers |
| Companies Covered | American International Group Inc., Allianz Commercial, AXA SA, The Hartford, Progressive, Generali, The Phoenix, Liberty Mutual, Lloyd's of London, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cargo Insurance Market Emerging Trajectories
Digital risk transfer mechanisms are displacing paper-based documentation and manual claims processes, as sensor networks and distributed ledger technology compress the information asymmetry between shippers, carriers, and underwriters.
Blockchain-enabled smart contracts are expanding into marine cargo documentation, creating immutable bills of lading and automated general average adjustments. German pharmaceutical distributors and Dutch perishables traders are piloting these systems for Rotterdam-Hamburg corridor shipments. This distributed architecture is expanding into traditional documentary credit structures, reducing fraud exposure and accelerating settlement timelines for contested claims.
EU F-Gas Regulation is mandating phased hydrofluorocarbon reductions through 2030, forcing refrigerated container operators to retrofit equipment with natural refrigerant alternatives. Underwriters must recalibrate mechanical breakdown and spoilage rates for unproven cooling systems. Temperature-controlled biologics transiting through Antwerp and Bremerhaven face the steepest coverage repricing as fleet retrofits lag regulatory deadlines.
Shippers are consolidating insurance procurement through integrated supply-chain risk platforms rather than standalone annual policies. German automotive manufacturers and French luxury goods houses are leading this transition, embedding coverage within logistics provider contracts. This bundling is most advanced in Rhine-Alpine corridor trade lanes, where single-source accountability reduces coverage gaps between modal handoffs.
Cargo Insurance Market Segmentation
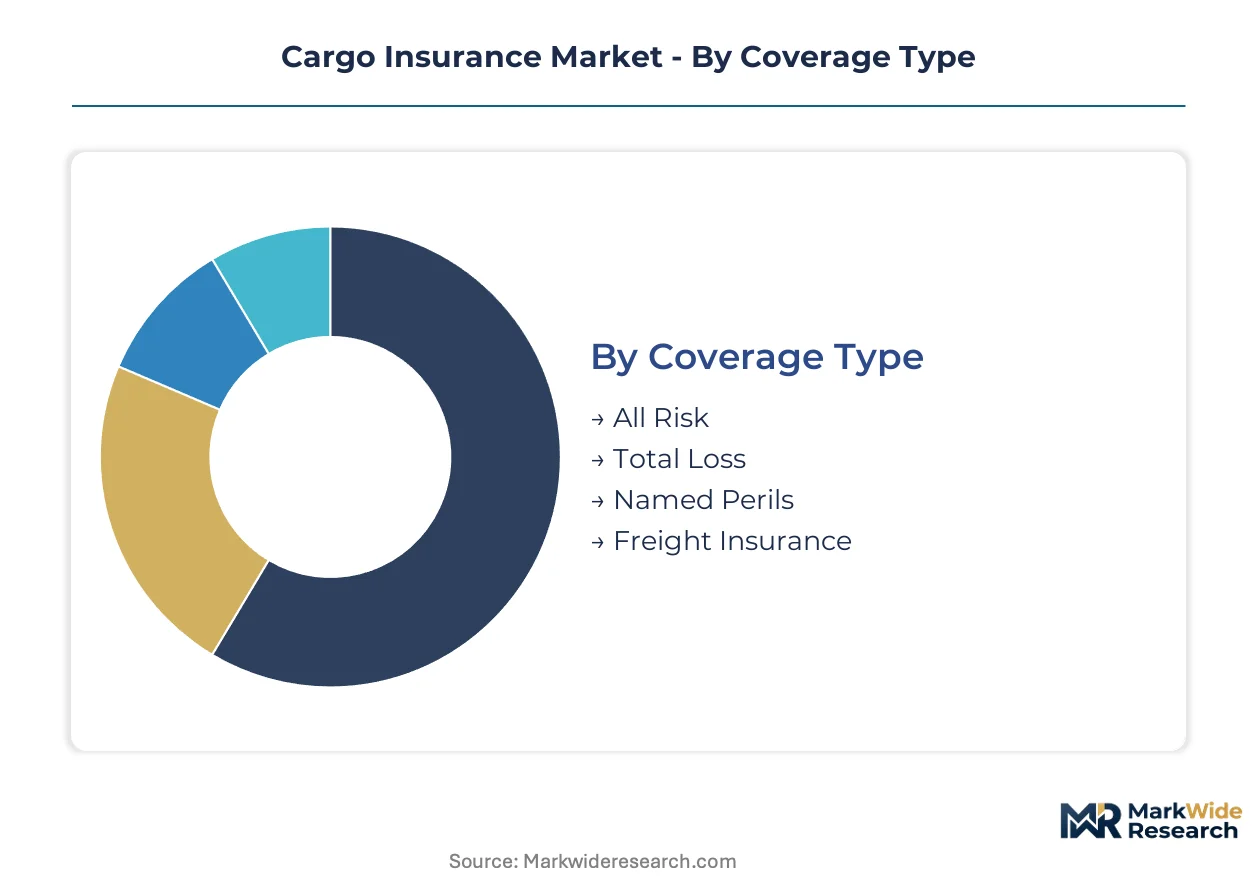
Cargo insurance segmentation reveals how coverage design maps to supply-chain risk profiles, with certification requirements from EMA, ISO, and Lloyd's syndicates governing which policy structures apply to which cargo categories. Underwriters calibrate pricing and capacity allocation across these dimensions based on loss history, regulatory exposure, and sensor-verifiable custody chains.
Coverage Type:
EMA distribution integrity guidelines and ISO 28000 security certifications determine which coverage tiers pharmaceutical and high-value shippers must maintain across European trade lanes.
- All Risk:Comprehensive protection against external perils including theft, water damage, and contamination. Hamburg pharmaceutical distributors and Dutch perishables traders default to this tier for Rotterdam-Hamburg corridor shipments where EMA cold-chain mandates apply.
- Named Perils:Specified-cause coverage with predictable loss profiles and lower premiums. Commodity shippers moving bulk agricultural products through Bremerhaven favor this structure where cargo value density justifies limited protection.
- Total Loss:Catastrophe-only coverage triggered by complete cargo destruction. German automotive manufacturers occasionally layer this atop primary policies for Rhine-Alpine corridor transit.
- Freight Insurance:Carrier liability extension protecting against contractual gaps between shipper and hauler policies. French luxury goods houses embed this within logistics provider contracts for multimodal handoffs.
Leading the category by volume: All Risk. Growing fastest: Named Perils as commodity shippers optimize cost exposure.
Transport Mode:
Modal selection directly determines which regulatory jurisdictions apply, with EU F-Gas Regulation governing reefer containers and FAA standards governing temperature-controlled air cargo.
- Ocean Freight:Vessel capacity and extended voyage duration generate the largest absolute premium volume. Hamburg port infrastructure anchors German demand, though F-Gas retrofit lag at Antwerp and Bremerhaven is forcing coverage repricing for temperature-controlled biologics.
- Air Freight:Higher rate-on-line multiples per unit value reflect compressed transit times and stringent IATA temperature protocols. Cell and gene therapy shipments from Hyderabad and Ahmedabad to Europe command specialized cold-chain premiums.
- Rail Transport:Eurasian corridor growth through the Rhine-Alpine axis is expanding coverage requirements for China-Europe block trains. German automotive manufacturers favor this mode for inland multimodal connectivity.
- Road Transport:Last-mile and cross-border European haulage governed by EU driving hour regulations and CMR convention liability limits. French and German fleet operators bundle this with logistics contracts.
Volume concentrates in Ocean Freight. Air Freight claims the steepest expansion trajectory driven by biologics manufacturing.
Policy Type:
Procurement patterns distinguish transactional shippers from integrated supply-chain operators, with CSRD disclosure mandates favoring documented annual structures over ad hoc arrangements.
- Annual Policy:Consolidated coverage for high-frequency shippers with predictable cargo flows. German automotive manufacturers and French luxury goods houses have shifted toward this structure to satisfy EU Corporate Sustainability Reporting Directive risk documentation requirements.
- Single Shipment:Event-specific coverage for irregular or project cargo movements. Indian pharmaceutical exporters use this for trial shipments to European regulators before establishing recurring lanes.
- Open Cover:Declaratory facility allowing automatic coverage for shipments below agreed value thresholds. Dutch perishables traders leverage this for Rotterdam-hubbed reefer volumes.
- Specific Policy:Tailored terms for unique cargo categories or exceptional voyages. Lloyd's syndicates specialize in this structure for specialty risks outside standard Institute Cargo Clauses.
Annual Policy dominates premium pools. Open Cover is gaining share fastest among integrated logistics platforms.
Insurer Type:
Market function specialization reflects capital intensity and risk distribution requirements, with Lloyd's syndicated structure enabling catastrophe exposure that standalone insurers cannot retain.
- Underwriters:Risk originators setting terms, pricing, and capacity allocation. Allianz Commercial deploys proprietary climate-risk modeling here to differentiate marine offerings.
- Brokers:Intermediaries matching shipper risk profiles with appropriate capacity. German pharmaceutical distributors rely on broker expertise to navigate EMA-ISO-Lloyd's intersection requirements.
- Insurers:Balance-sheet carriers retaining primary risk. AXA SA competes across multimodal segments with integrated supply-chain risk services.
- Reinsurers:Catastrophe capacity providers absorbing peak exposures. Bermuda markets and Lloyd's syndicates control disproportionate marine hull concentration.
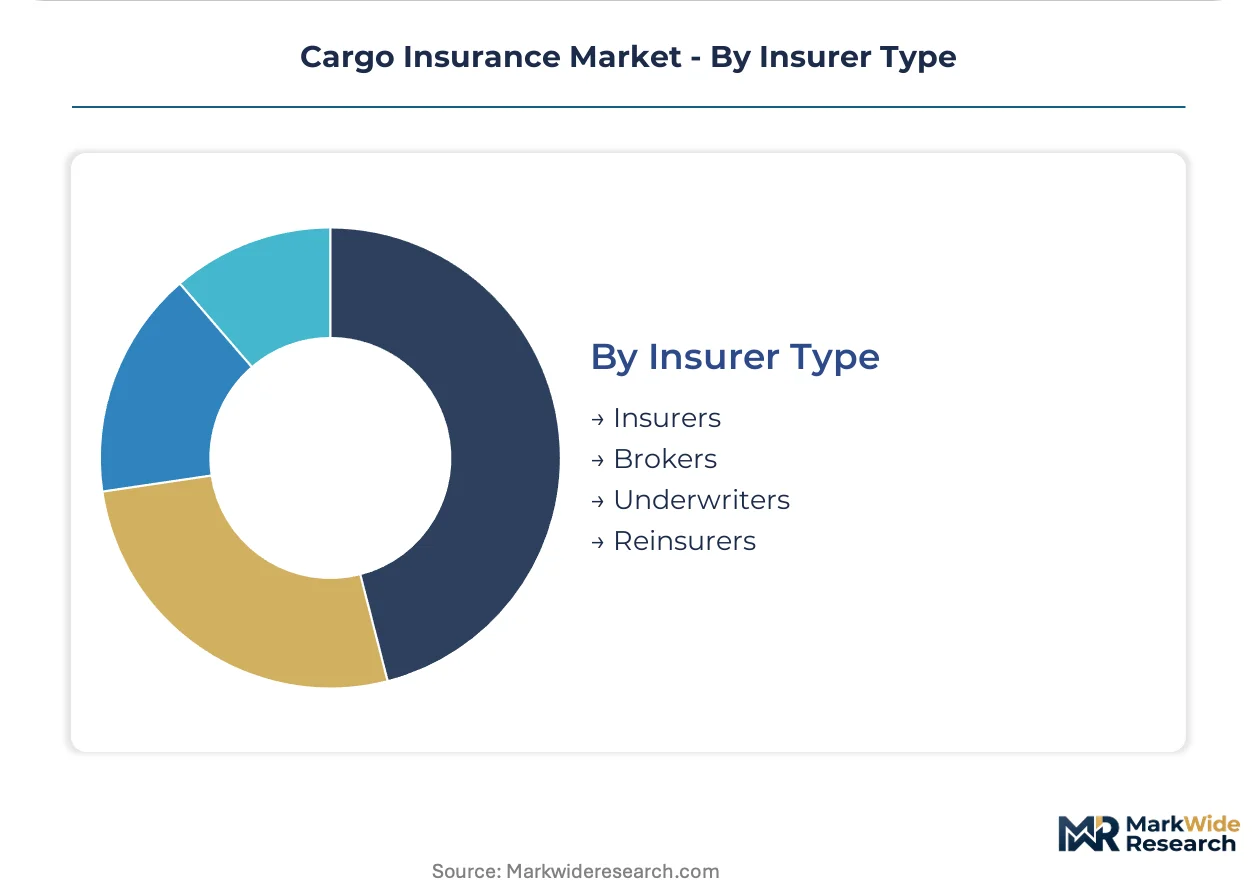
Underwriters lead by premium volume. Brokers are expanding most quickly as procurement consolidates through integrated platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Hamburg and Rotterdam concentrate cargo insurance demand through bonded warehousing incentives and streamlined customs processing for temperature-sensitive pharmaceuticals.
Germany
Hamburg's port infrastructure anchors continental European premium volume, with multimodal connectivity extending coverage requirements inland. The EU Corporate Sustainability Reporting Directive compels German automotive manufacturers and pharmaceutical distributors to document supply-chain risk exposure through verified annual policies. Rhine-Alpine corridor logistics platforms bundle insurance with haulage contracts, consolidating procurement around integrated risk services.
United States
Pharmaceutical cold-chain logistics between Hyderabad and Newark generate specialized coverage demand for cell and gene therapies requiring strict temperature custody. FDA distribution integrity guidelines harden underwriting criteria for biologic shipments transiting through major air hubs. Chicago's intermodal terminals and Los Angeles-Long Beach port complex anchor premium concentration for multimodal agricultural and automotive cargo.
India
CDSCO-regulated manufacturing hubs in Hyderabad and Ahmedabad are expanding temperature-controlled pharmaceutical exports to Europe and North America, creating underpenetrated premium pools. The country's central pharmaceutical regulator mandates distribution integrity documentation for biologic shipments, compelling exporters to secure documented cargo coverage. Gujarat's Special Economic Zones and Maharashtra's logistics corridors concentrate cold-chain infrastructure investment.
Netherlands
Rotterdam's port throughput and perishables trading infrastructure generate substantial reefer container premium volume. EU F-Gas Regulation phase-down schedules are forcing refrigerated fleet retrofits, raising mechanical breakdown and spoilage coverage rates. Dutch traders leverage Open Cover declaratory facilities for high-frequency reefer volumes hubbed through the Rotterdam-Hamburg corridor.
United Kingdom
Lloyd's of London syndicates anchor specialty cargo underwriting through their distributed market structure, enabling catastrophe exposure retention that standalone insurers cannot match. The UK's departure from EU regulatory alignment has created dual-track compliance requirements for cross-channel shipments. London-based brokers navigate EMA-ISO-Lloyd's intersection requirements for pharmaceutical distributors seeking coverage for continental European transit.
Cargo Insurance Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across multimodal segments, with market structure tiering between balance-sheet carriers, syndicated capacity providers, and intermediary brokers. Consolidation concentrates among underwriters deploying proprietary climate-risk modeling and integrated supply-chain risk platforms. Three archetypes dominate: global multi-line insurers with logistics capabilities, Lloyd's syndicated specialists in catastrophe-exposed marine hull, and technology-enabled brokers consolidating procurement through digital platforms. Competitive moves center on parametric product launches leveraging IoT sensor integration and strategic bundling of compliance services with coverage.
Among the named carriers in this study, Allianz Commercial and AXA SA represent the diversified multi-line archetype with integrated supply-chain risk services, while Lloyd's of London exemplifies the syndicated specialist structure enabling complex or catastrophe-exposed risks outside standard Institute Cargo Clauses. These three anchors illustrate how geographic origin and organizational structure shape competitive positioning: German and French balance-sheet carriers compete on service integration, while the London market retains franchise value in specialty and non-standard risks.
| Leading Market Players |
|---|
| American International Group Inc. |
| Allianz Commercial |
| AXA SA |
| The Hartford |
| Progressive |
| Generali |
| The Phoenix |
| Liberty Mutual |
| Lloyd's of London |
| Others |
Supply Flow & Price Mechanics
EU Corporate Sustainability Reporting Directive disclosure mandates are compelling German automotive manufacturers and pharmaceutical distributors to consolidate procurement through integrated logistics platforms, forcing underwriters to bundle compliance documentation with coverage and compressing margins for standalone annual policies.
Pricing Analysis
Expedited coverage activation for temperature-sensitive biologics commands premium rate-on-line multiples, while spot-market single-shipment policies for commodity bulk cargo trade at discounted multiples. Three-tier pricing structure across premium, standard, and economy levels stratifies by EMA cold-chain certification grade and ISO 28000 security compliance tier. Pricing pressure stems from refrigerant input volatility under EU F-Gas Regulation phase-down schedules. Commodity agricultural shippers exhibit highest price sensitivity; cell and gene therapy manufacturers show lowest sensitivity due to irreplaceable cargo value density.
Supply Chain Analysis
ISO 28000 certification and EMA distribution integrity qualification gate access to premium-tier pharmaceutical coverage, filtering out non-compliant logistics providers. Supply concentrates in Germany, the Netherlands, and the United Kingdom for European underwriting capacity, with Bermuda reinsurers providing catastrophe peak exposure. Raw material dependencies include hydrofluorocarbon refrigerants, marine hull steel, and IoT sensor hardware. Single-source vulnerability concentrates in Lloyd's of London syndicates for catastrophe marine hull. Distribution runs through Rotterdam-Hamburg corridor logistics platforms bundling coverage with haulage contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Catastrophe marine hull capacity concentration among Lloyd's syndicates and Bermuda reinsurers props pricing power, constraining supply expansion and preserving underwriting margins across European trade lanes.
For Market Incumbents: Extend proprietary climate-risk modeling capabilities into parametric IoT-verified products before mid-market competitors close capability gaps. Defend position by embedding coverage within Rhine-Alpine corridor logistics platforms where German automotive manufacturers consolidate procurement. Acquire sensor-data integration talent to accelerate automated claims settlement for temperature breach verification. For New Entrants and Emerging Players: Indian pharmaceutical exporters from Hyderabad and Ahmedabad represent an underserved buyer archetype requiring documented cold-chain coverage for CDSCO-regulated biologic shipments to European regulators. Target this segment with single-shipment policies graduating to annual structures upon regulatory approval of recurring lanes. Partner with Dutch perishables traders piloting blockchain-enabled smart contracts for Rotterdam-hubbed reefer volumes. For Investors and Strategic Acquirers: The window for entry favors technology-enabled brokers consolidating procurement through digital platforms before incumbent underwriters retrofit legacy mainframe systems. Long-term viability hinges on parametric product deployment capability across the analysis window. Monitor IoT sensor integration velocity as inflection indicator for automated claims settlement adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Coverage Launch | IoT sensor integration enables automated settlement for EMA-verified temperature breaches. |
| Compliance Service Bundling | CSRD documentation requirements embed insurance within German automotive logistics contracts. |
| Refrigerant Fleet Retrofit | EU F-Gas Regulation phase-down forces reefer container coverage repricing at Antwerp and Bremerhaven. |
| Blockchain Documentation Pilot | Rotterdam-Hamburg corridor shipments test immutable bills of lading for Dutch perishables traders. |
| Climate-Risk Modeling Investment | Allianz Commercial deploys proprietary capabilities to differentiate marine coverage offerings. |
Methodological Framework
Trade databases, regulatory filings with EMA and CDSCO, and Institute Cargo Clauses documentation formed the secondary backbone, cross-referenced with primary interviews with cargo underwriters, marine brokers, pharmaceutical supply chain directors, and refrigerated fleet operators. Bottom-up and top-down triangulation validated premium volume estimates across modal segments and coverage tiers.
Bottom-up shipment-value modeling aggregated individual trade lane exposures, while top-down macroeconomic calibration anchored aggregate premium pools across the projection horizon. Segmentation dimensions included coverage type, transport mode, policy structure, and insurer function, with CAGRs derived from loss ratio trends and capacity deployment patterns. Forecast inputs incorporated EMA distribution integrity guideline evolution and EU F-Gas Regulation compliance cost trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to marine hull catastrophe frequency and refrigerant technology substitution rates. Model outputs reflect assumptions around sensor adoption curves and blockchain documentation penetration. A model refresh is warranted upon material change in EMA cold-chain mandate enforcement or Lloyd's of London syndicate capacity deployment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Insurance Protection Products Market
Insurance
United States Insurance Brokerage Market
Insurance
B2B2C Insurance Market
Insurance
South Korea Liability Insurance Market
Insurance
US Extended Warranty Market
Insurance
Global Boats and Yacht Insurance Market
Insurance
Norway Property and Casualty Insurance Market
Insurance
Compulsory Third Party (CTP) Insurance Market
Insurance
Auto Compulsory Insurance Market
Insurance
Africa Insurance Market
Insurance
Canada Cyber (Liability) Insurance Market
Insurance
US Insurance Third-Party Administrator Market
Insurance
Aerial Imaging in Insurance Service Market
Insurance
China Property and Casualty Insurance Market
Insurance
Aerospace Insurance Market
Insurance
Canada Health and Medical Insurance Market