
 Drone Insurance Market | 2026-2036
Drone Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Drone Insurance Market Insights
Buyer concentration across commercial drone fleets is rebalancing as enterprise operators consolidate coverage under single master policies rather than insuring individual units. SkyWatch.AI leverages real-time flight telemetry to price risk dynamically per mission. Allianz Global Corporate & Specialty anchors large-account underwriting for energy and utility infrastructure clients with complex fleet exposures. Coverdrone specializes in recreational-to-commercial transitional policies across European jurisdictions.
Drone insurance constitutes a specialized risk-transfer instrument covering physical damage to unmanned aerial vehicles, third-party bodily injury, and payload loss during flight operations, with underwriting grounded in flight-hour logs, pilot certification tiers, and geofencing compliance data. Its primary commercial purpose is to indemnify operators against aviation liability and equipment replacement costs in regulated airspace. Liability Coverage commands the largest premium pool due to catastrophic third-party exposure, while Payload Insurance captures expanding margin as sensor and LiDAR equipment values escalate. Infrastructure Inspection and Agricultural Surveillance dominate application-based demand, with Delivery Services representing the steepest trajectory as urban beyond-visual-line-of-sight frameworks mature.
The FAA's Part 107 certification requirements and remote ID rulemaking shape US underwriting criteria, while EASA's open and specific category classifications under EU Regulation 2019/947 standardize European policy boundaries. The EU AI Act and emerging algorithmic accountability frameworks will soon extend to autonomous flight systems, complicating liability attribution between operators and software vendors. Stakeholders must monitor how jurisdiction-specific airspace integration timelines alter territorial coverage exclusions and premium adequacy.
Market Dynamics
Enterprise fleet operators are consolidating coverage under master policies while telemetry-driven pricing compresses traditional actuarial models, forcing underwriters to rebuild risk assessment around real-time flight data rather than static pilot certifications.
Growth Catalysts
- Remote ID mandates:The FAA's remote identification requirements generate compliance-driven policy renewals as operators expand fleets to meet surveillance and delivery contract volumes.
- Last-mile logistics:E-commerce fulfillment networks in Germany and the Netherlands are scaling drone delivery pilots, creating fleet-level liability exposures that demand structured coverage.
- Sensor payload escalation:LiDAR and thermal imaging equipment values exceeding $75,000 per unit drive standalone payload insurance attachments to standard hull policies.
Market Restraints
- Pilot certification bottlenecks:FAA Part 107 recurrent testing requirements restrict eligible operator pools, limiting addressable premium volume in commercial segments.
- Actuarial data scarcity:Limited historical loss data for beyond-visual-line-of-sight operations forces conservative pricing that deters price-sensitive agricultural buyers.
- Geofencing enforcement gaps:Inconsistent airspace restriction implementation across municipal jurisdictions complicates territorial coverage exclusions.
Strategic Opportunities
- Autonomous flight convergence:AI-powered navigation systems intersecting with 5G network slicing create parametric insurance triggers based on connection quality metrics.
- India agricultural penetration:Crop-spraying drone adoption under the PLI scheme opens specialized coverage for monsoon-season equipment exposure.
- Embedded distribution:Drone-as-a-service platforms in France and Spain are integrating insurance into hourly rental rates, capturing transient operators.
Industry Challenges
- Claims adjudication complexity:Software-hardware liability attribution in autonomous incidents requires new forensic capabilities that most underwriters lack.
- Cross-border coverage fragmentation:EASA open category recognition does not transfer to Swiss or Norwegian airspace, forcing multi-jurisdictional policy stacking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drone Insurance Market |
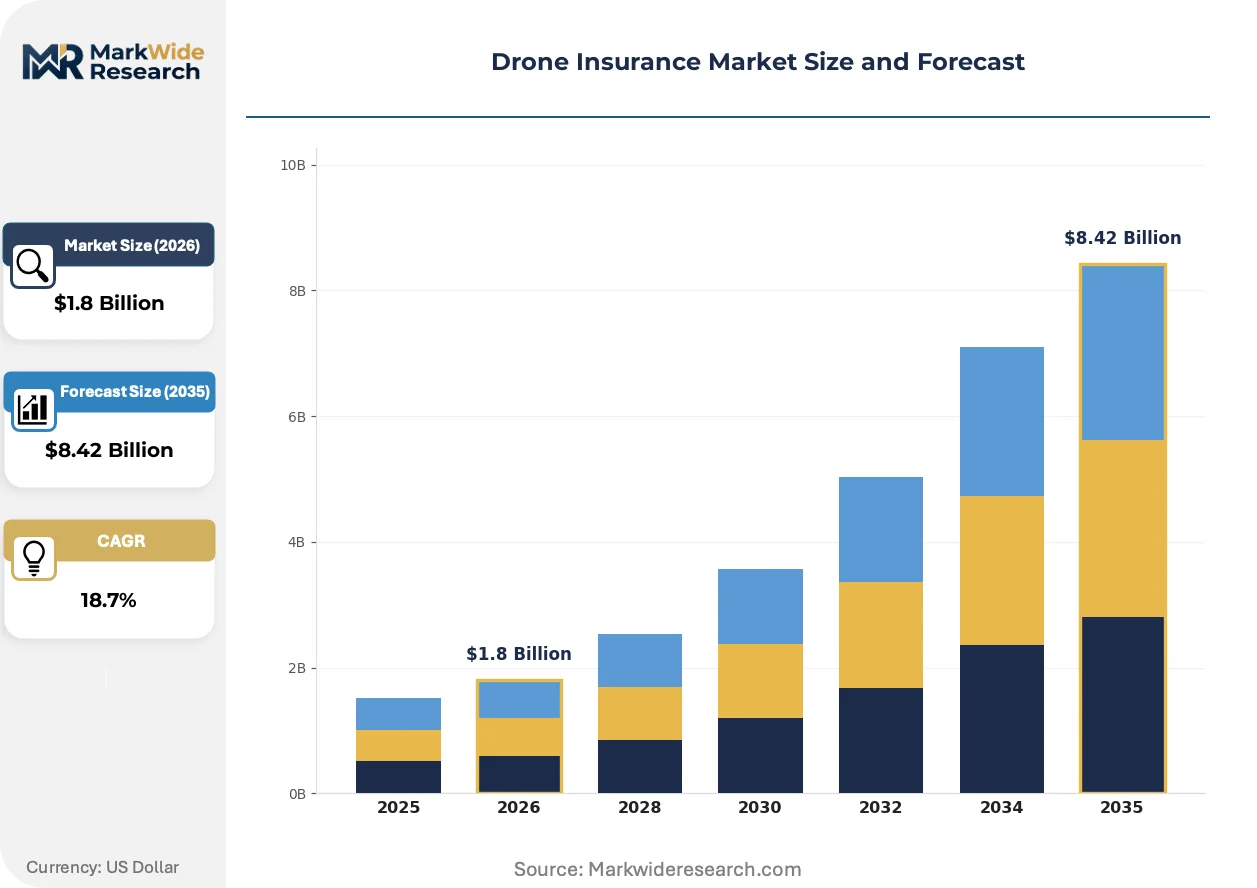
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Insurance Product Type: Liability Coverage, Hull Coverage, Payload Insurance, Third-Party Liability, Personal Injury Protection, Cargo Insurance Application: Aerial Photography, Agricultural Surveillance, Infrastructure Inspection, Public Safety Operations, Delivery Services, Surveying Drone Type: Fixed Wing, Rotary Wing, Hybrid, Micro Drones, Nano Drones, Tactical Drones End User: Commercial Operators, Government Agencies, Emergency Responders, Research Institutions, Entertainment Companies, Training Providers |
| Companies Covered | SkyWatch.AI, Flock, Moonrock Insurance, Avion Insurance, AIG US, Coverdrone, Allianz Global Corporate & Specialty, Aligned, Global Aerospace Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drone Insurance Market Trends and Innovations
Telematics infrastructure is displacing retrospective risk assessment with continuous flight monitoring, compressing the information asymmetry between operators and underwriters while enabling usage-based premium structures.
Blockchain-verified flight logs are integrating with smart contract architectures to automate claims settlement when telemetry confirms hard landings or geofence breaches. Agricultural cooperatives in Australia and energy inspectors in Texas are piloting these systems, reducing loss adjustment expenses and accelerating indemnity timelines for equipment replacement.
EASA's specific category operational authorizations under EU Regulation 2019/947 are mandating third-party liability minimums that exceed standard commercial general liability limits. Infrastructure operators in Poland and Sweden are restructuring coverage to meet these floors, while insurers develop modular endorsements for cross-border fleet deployments.
Enterprise procurement departments are consolidating vendor relationships, pressuring insurers to bundle hull, liability, and payload coverage into single annual contracts with fleet-wide deductibles. This concentration is most pronounced among utility inspection contractors in California and mining surveyors in Western Australia, who trade premium volume for streamlined certificate management.
Drone Insurance Market Segmentation
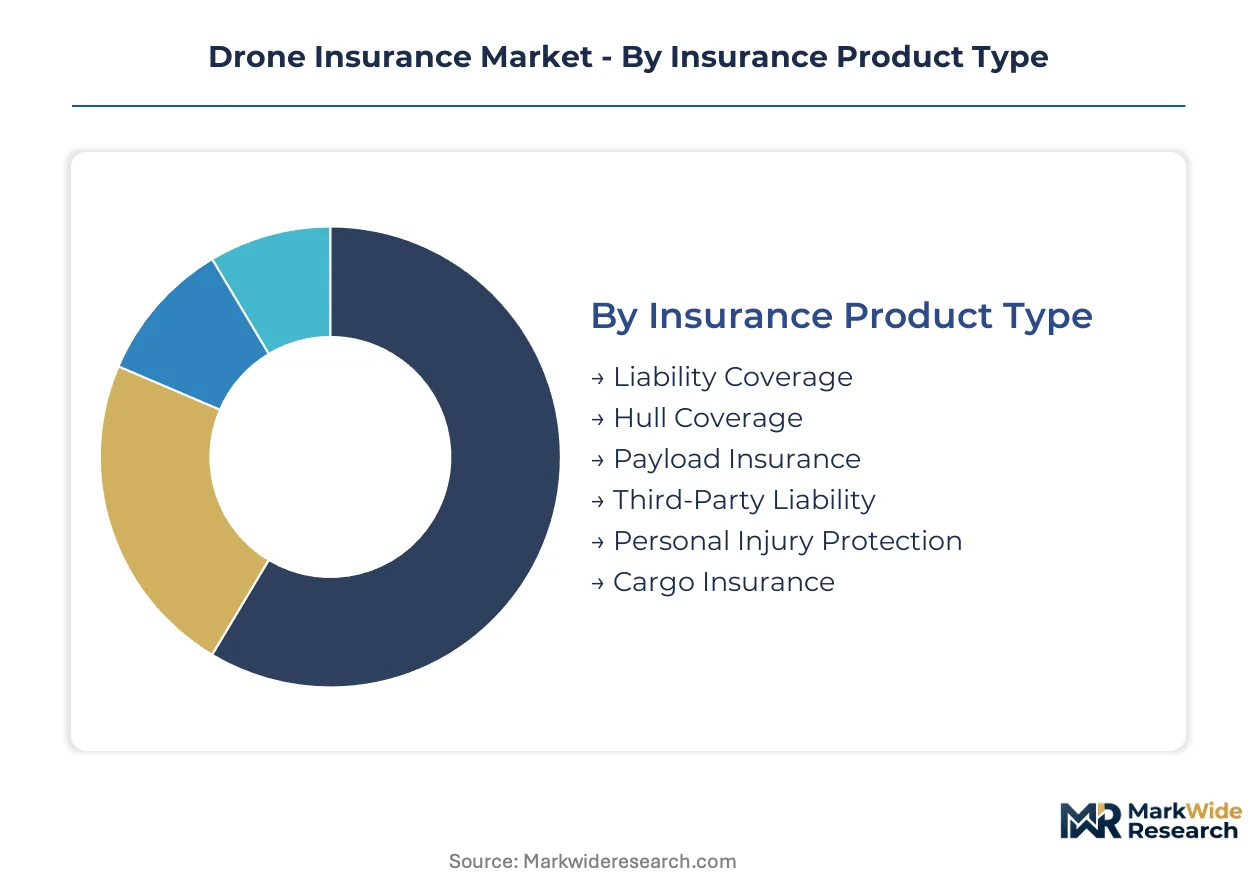
Drone insurance products must align coverage structures with distinct operational risk profiles. Each segmentation axis—product design, mission application, aircraft specification, and buyer category—creates divergent underwriting requirements and pricing methodologies.
Insurance Product Type:
Product architecture determines premium allocation across physical damage, liability exposure, and specialized equipment loss.
- Liability Coverage:Indemnifies operators against third-party bodily injury and property damage claims arising from flight operations. Demand concentrates among commercial delivery fleets in the United States where urban beyond-visual-line-of-sight operations generate catastrophic exposure scenarios.
- Hull Coverage:Protects against physical damage to the airframe, propulsion systems, and avionics. Agricultural cooperatives in Australia and energy inspectors in Texas drive attachment rates as equipment replacement costs escalate.
- Payload Insurance:Covers sensor arrays, LiDAR units, and thermal imaging equipment. Research institutions deploying high-value scientific instrumentation represent the core buyer segment.
- Third-Party Liability:Extends protection to ground personnel and bystanders outside the operator's direct control. Public safety operations in municipal jurisdictions require elevated limits.
- Personal Injury Protection:Addresses pilot and crew medical expenses from ground incidents during pre-flight preparation. Training providers incorporate this coverage into student rental packages.
- Cargo Insurance:Indemnifies against loss of transported goods during aerial delivery. E-commerce fulfillment networks in Germany and the Netherlands are scaling pilots that demand structured coverage.
Mature deployment sits with Liability Coverage. Newer deployment is concentrated in Payload Insurance.
Application:
Mission type dictates frequency, airspace complexity, and value-at-risk parameters.
- Aerial Photography:Covers commercial imaging for real estate, media production, and marketing content. Entertainment companies in California and New York generate recurring premium volume through project-based policies.
- Agricultural Surveillance:Encompasses crop health monitoring, irrigation mapping, and yield prediction flights. Operators in India's wheat belt and Australia's Murray-Darling basin are expanding fleet sizes under the PLI scheme and drought mitigation programs.
- Infrastructure Inspection:Addresses power line, pipeline, and bridge assessment missions. Utility contractors in Texas and mining surveyors in Western Australia consolidate coverage under master policies with fleet-wide deductibles.
- Public Safety Operations:Supports search-and-rescue, firefighting overwatch, and disaster response. Emergency responders in Florida and California face unique night-flight authorization requirements.
- Delivery Services:Covers last-mile logistics for medical supplies, retail goods, and food services. This segment is gaining share fastest as urban air mobility frameworks mature in the Netherlands and Germany.
- Surveying:Encompasses topographic mapping, construction progress monitoring, and cadastral boundary verification. Engineering firms in Poland and Sweden restructure coverage to meet EASA specific category liability minimums.
Mature deployment sits with Infrastructure Inspection. Newer deployment is concentrated in Delivery Services.
Drone Type:
Airframe configuration determines flight endurance, payload capacity, and crash severity profiles.
- Fixed Wing:Long-endurance platforms optimized for corridor mapping and agricultural surveys. Energy infrastructure clients in Australia and the United States anchor underwriting volume for high-value fixed-wing fleets.
- Rotary Wing:Multirotor systems dominating close-quarters inspection and precision payload delivery. Commercial operators in last-mile logistics represent the expanding buyer segment.
- Hybrid:Combines vertical takeoff capability with efficient forward flight. Surveying contractors in Norway and Switzerland deploy these platforms for mountainous terrain access.
- Micro Drones:Sub-250g platforms operating under simplified regulatory thresholds. Recreational-to-commercial transitional operators in European jurisdictions drive policy volume.
- Nano Drones:Indoor inspection systems for confined space assessment. Industrial facility managers in Germany pilot these for tank and vessel examination.
- Tactical Drones:Military-grade platforms adapted for civilian emergency response. Government agencies in the United States require specialized coverage for sensitive mission profiles.
Mature deployment sits with Rotary Wing. Newer deployment is concentrated in Hybrid configurations.
End User:
Buyer organizational structure determines procurement methodology and policy administration complexity.
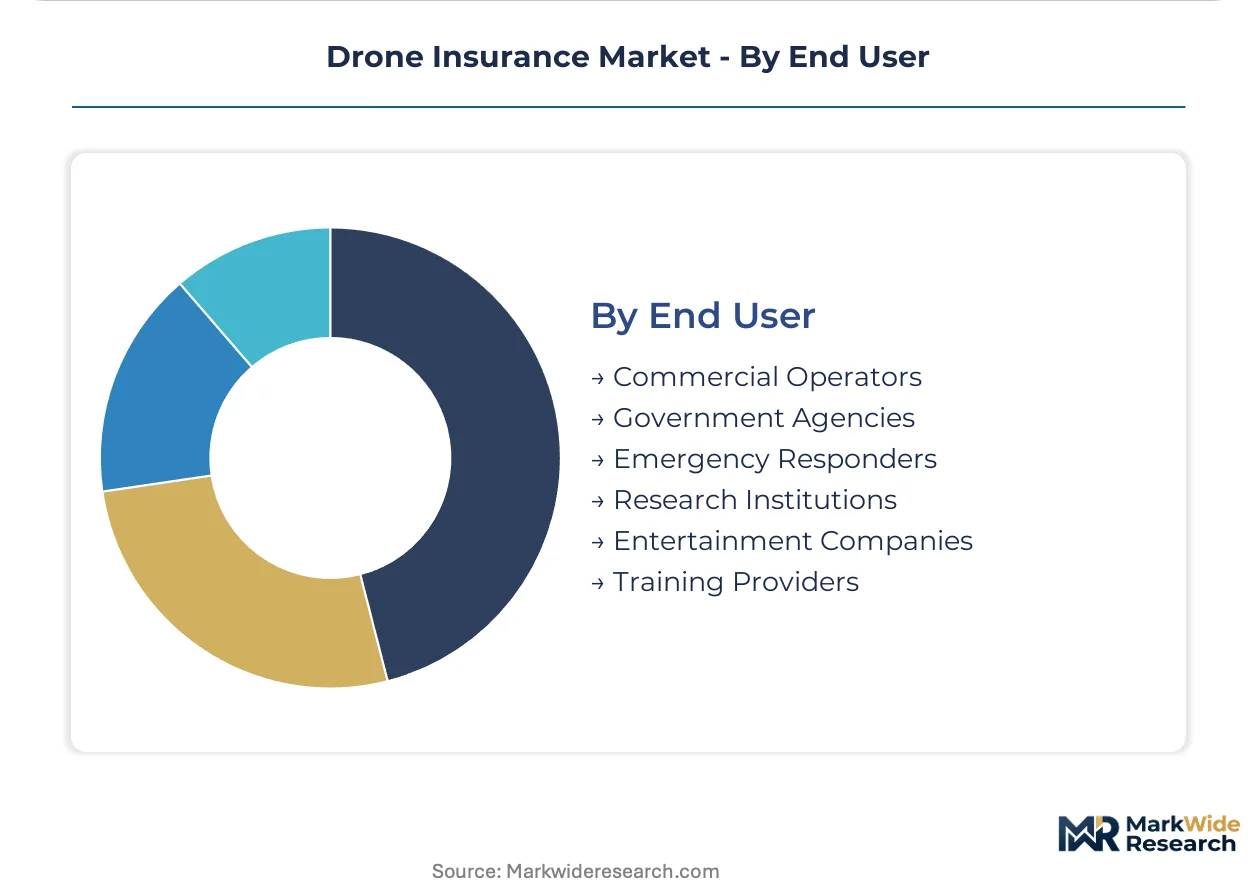
- Commercial Operators:Enterprise fleet managers consolidating coverage under single master policies. Utility inspection contractors in California trade premium volume for streamlined certificate management.
- Government Agencies:Federal, state, and municipal departments with sovereign immunity considerations. FAA Part 107 recurrent testing mandates reshape actuarial models for agency pilot pools.
- Emergency Responders:Fire departments, police aviation units, and disaster management authorities. Night-flight authorization and thermal payload integration create specialized coverage requirements.
- Research Institutions:Universities and scientific organizations deploying experimental sensor configurations. High-value LiDAR and hyperspectral equipment exceeding $75,000 per unit drives standalone payload attachments.
- Entertainment Companies:Film studios, event producers, and content creation agencies. Project-based policies align with production scheduling in Los Angeles and New York.
- Training Providers:Flight schools and certification centers with student-operated equipment exposure. Embedded insurance in hourly rental rates captures transient operator risk in France and Spain.
Mature deployment sits with Commercial Operators. Newer deployment is concentrated in Research Institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's telemetry infrastructure anchors North American underwriting innovation, while European regulatory harmonization and Asian agricultural mechanization create divergent premium formation environments across three continents.
United States
Commercial delivery fleets and utility infrastructure contractors drive premium concentration. FAA Part 107 recurrent testing mandates and remote ID rulemaking tighten underwriting standards. Texas energy corridor operators consolidate coverage under master policies with fleet-wide deductibles.
Germany
E-commerce fulfillment networks and industrial inspection services scale drone operations. EASA open and specific category classifications under EU Regulation 2019/947 standardize policy boundaries. Bavarian logistics clusters pilot embedded insurance in hourly rental rates.
India
Crop-spraying cooperatives expand fleet sizes under the PLI scheme. BIS certification requirements and monsoon-season equipment exposure create specialized coverage demand. Punjab and Haryana agricultural belts anchor premium growth for hull and payload policies.
Australia
Mining surveyors and drought mitigation programs drive fixed-wing fleet deployment. TGA-equivalent aviation safety frameworks govern commercial operations. Western Australia resource corridors consolidate vendor relationships for streamlined certificate management.
United Kingdom
Recreational-to-commercial transitional operators and entertainment production companies generate project-based policy volume. CAA operational authorizations align with EASA specific category liability minimums. London media clusters demand elevated limits for urban beyond-visual-line-of-sight filming.
Drone Insurance Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue telemetry-driven dynamic pricing and embedded distribution partnerships. The market structure bifurcates between legacy aviation underwriters with fleet-scale capacity and insurtech platforms leveraging real-time flight data. Strategic archetypes include telematics-native pricing engines, master policy consolidators for enterprise fleets, and jurisdictional specialists navigating European regulatory fragmentation. Dominant competitive moves center on API integrations with drone-as-a-service platforms and parametric smart contract development for automated claims settlement.
Among telemetry-native specialists, SkyWatch.AI exemplifies the algorithmic pricing archetype, while Coverdrone occupies a position within European jurisdictional specialization. Allianz Global Corporate & Specialty anchors the large-account underwriting tier for energy and utility infrastructure clients with complex fleet exposures.
| Leading Market Players |
|---|
| SkyWatch.AI |
| Flock |
| Moonrock Insurance |
| Avion Insurance |
| AIG US |
| Coverdrone |
| Allianz Global Corporate & Specialty |
| Aligned |
| Global Aerospace Inc |
| Others |
Pricing and Supply Chain Analysis
Actuarial talent concentration in London and Zurich sustains premium-rate differentials between telemetry-native underwriters and legacy aviation carriers, with labor-cost arbitrage in Eastern European analytics hubs compressing spreads on economy-tier policies.
Pricing Analysis
Volume concentrates in standard-tier annual policies while margin accrues to dynamic-per-mission coverage. Price differentiation hinges on pilot-certification tier and real-time telemetry integration. Cost compression in agricultural segments is intensifying because conservative BVLOS actuarial assumptions deter price-sensitive cooperatives. Fleet operators with master policies demonstrate lowest price sensitivity; recreational transitional buyers exhibit highest elasticity.
Supply Chain Analysis
Workforce availability constraints in Ireland and Poland limit capacity for claims-adjustment automation engineering. Underwriting infrastructure draws from cloud-computing resources in Germany, proprietary telemetry platforms in Israel, and legacy reinsurance capacity in Bermuda. Single-source vulnerability sits with FAA certification data feeds. Distribution runs through broker networks for enterprise accounts and API integrations for embedded drone-as-a-service partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where FAA Part 107 recurrent testing mandates erect regulatory moats favoring incumbents with established pilot-verification infrastructure.
For Market Incumbents: To counter telemetry-native pricing erosion from SkyWatch.AI and Flock, legacy carriers must acquire real-time flight-data capabilities or partner with UTM platform providers. Channel control through exclusive arrangements with major drone manufacturers represents the critical defensive lever. Certification investment in EASA specific-category authorization expands addressable premium pools. For New Entrants and Emerging Players: The premium-to-economy price-point gap in agricultural coverage offers white-space entry for parametric products tied to seasonal flight-hour bands. India's PLI-subsidized crop-spraying cooperatives represent the most penetrable segment. Embedded distribution through drone rental platforms in France and Spain provides the essential go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with telematics-native underwriters given remote-ID mandate acceleration across multiple jurisdictions. Long-term viability favors platforms with proprietary flight-risk algorithms and API-first distribution architectures. The inflection signal to watch is BVLOS regulatory framework finalization in urban air mobility corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Telemetry Platform Acquisition | Real-time flight-data integration enables dynamic-per-mission pricing competitive with SkyWatch.AI. |
| EASA Specific-Category Authorization | EU Regulation 2019/947 compliance unlocks infrastructure-insurance premiums in Poland and Sweden. |
| Embedded Insurance API Development | Drone-as-a-service platform partnerships in Germany and Spain capture transient operator volume. |
| Parametric Smart Contract Deployment | Blockchain-verified flight logs automate claims settlement for Australian agricultural cooperatives. |
| Master Policy Consolidation Program | Fleet-wide deductible structures secure multi-year contracts with California utility contractors. |
Research Methodology
Independent corroboration across underwriter pricing desks, UTM platform engineers, and regulatory affairs specialists at aviation authorities underwrites the qualitative findings. Primary interviews with chief underwriting officers, actuarial modelers, drone fleet managers, and EASA compliance consultants combined with secondary validation from FAA regulatory filings, EASA operational authorization databases, and insurance regulatory disclosures. Bottom-up premium volume estimates triangulated against top-down addressable fleet projections.
Rate-of-change decomposition across liability coverage, hull protection, and payload insurance segments structured the analytical framework. Segmentation dimensions modeled include insurance product architecture, mission application type, drone airframe configuration, and buyer organizational category. CAGRs derived from regression analysis against flight-hour growth trajectories and regulatory compliance timeline acceleration. Forecast inputs incorporated remote-ID mandate implementation schedules and BVLOS framework maturation curves.
Inputs from aviation regulatory databases and insurance premium filings were available through the study window; gaps in historical BVLOS loss data introduce uncertainty bands around agricultural segment pricing assumptions. Forecasts reflect documented assumptions regarding airspace integration timelines and fleet operator consolidation patterns. Material deviation in FAA remote-ID enforcement intensity or EASA specific-category authorization velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
New Zealand Property and Casualty Insurance Market
Insurance
US Long-Term Care Private Insurance Market
Insurance
Data Analytics in Insurance Market
Insurance
Norway Property and Casualty Insurance Market
Insurance
Musical Instrument Insurance Market
Insurance
Germany Car Insurance Market
Insurance
Canada Health and Medical Insurance Market
Insurance
UK Electronic Gadgets Insurance Market
Insurance
Insurance Third Party Administrators Market
Insurance
Spain Group Health Insurance Market
Insurance
Digital Insurance Market
Insurance
Property Insurance Market
Insurance
Asia-Pacific EV Insurance Market
Insurance
AI in Insurance Market
Insurance
Finland Cyber (Liability) Insurance Market
Insurance
US Travel Insurance Market