
 Global Extra Corporeal Membrane Oxygenation (ECMO) System Market | 2026-2036
Global Extra Corporeal Membrane Oxygenation (ECMO) System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Extra Corporeal Membrane Oxygenation (ECMO) System Market Foresight
Hospital procurement of ECMO systems is rebalancing from dispersed critical care units toward centralized cardiovascular ICUs and dedicated ECMO centers. Getinge AB dominates the oxygenator and pump segment through its CardioHelp system, leveraging integrated transport capabilities that sustain high-acuity patient mobility. Medtronic anchors the North American installed base with established perfusion technology platforms, while LivaNova PLC differentiates through specialized pediatric and neonatal circuit designs that command premium positioning in children's hospitals.
Extra Corporeal Membrane Oxygenation (ECMO) systems are life-support devices that oxygenate blood outside the body through a membrane oxygenator, typically achieving gas exchange rates of 100-400 mL/min depending on membrane surface area and blood flow configuration. These systems serve patients with refractory cardiac or respiratory failure when conventional mechanical ventilation or pharmacologic support proves insufficient. Venoarterial ECMO occupies the largest revenue share due to its dual cardiac and pulmonary support function in post-cardiotomy and cardiac arrest scenarios, while portable ECMO represents the fastest-growing configuration as transport-capable systems enable inter-hospital patient transfers and field deployment. Biocompatible circuitry technology is displacing conventional PVC tubing as heparin-coated and phosphorylcholine-treated surfaces reduce thrombogenicity and extend safe perfusion durations.
FDA 510(k) clearance pathways and EMA Medical Device Regulation (MDR) conformity assessments shape product development timelines and market access requirements for ECMO manufacturers across the United States and European Union. Japan's PMDA enforces distinct clinical evidence standards for long-term circulatory support devices that create additional regulatory layers for entrants targeting that market. Stakeholders must monitor evolving reimbursement frameworks for extracorporeal life support procedures, as coverage decisions by national health technology assessment bodies will determine adoption velocity in publicly funded healthcare systems.
Market Dynamics
Hospital procurement patterns for ECMO systems are consolidating around centralized cardiovascular ICUs, driven by the clinical complexity of extracorporeal support and the need for specialized perfusionist staffing. This structural reconfiguration favors vendors with integrated transport capabilities and remote monitoring platforms.
Growth Catalysts
- Refractory Respiratory Failure Prevalence:Post-pandemic recognition of ECMO efficacy in severe ARDS has expanded institutional protocols beyond traditional cardiac surgery departments into medical ICU settings.
- FDA 510(k) Pathway Modernization:Streamlined clearance routes for predicate oxygenator designs accelerate product iteration cycles for membrane surface area and gas exchange efficiency improvements.
- Japan PMDA Center Designation Program:Government-certified ECMO centers receive preferential reimbursement and equipment subsidies, concentrating demand in tertiary facilities with established extracorporeal life support programs.
Market Restraints
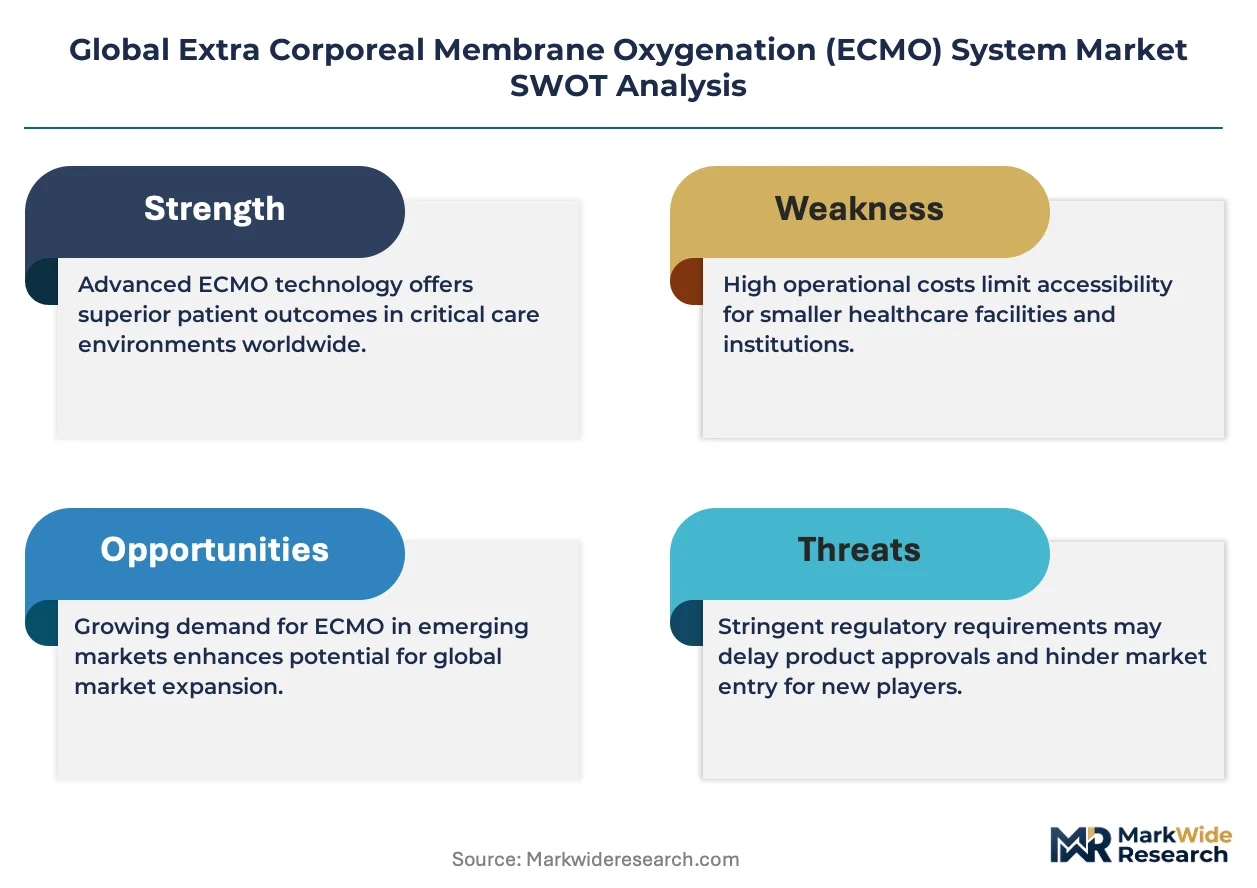
- Silicone Membrane Input Concentration:Three Japanese and German suppliers control microporous silicone sheet production for long-term oxygenators, creating vulnerability to polymer supply disruptions.
- EMA MDR Clinical Evidence Burden:Extended perfusion duration claims now require prospective registry data, extending conformity assessment timelines by 18-24 months for novel circuit designs.
- Specialized Perfusionist Labor Scarcity:Certification requirements limit trained operator availability, capping institutional expansion regardless of capital equipment procurement budgets.
Strategic Opportunities
- Brazil ANVISA Expedited Review:Priority regulatory channel for life-support devices creates first-mover positioning in Latin America's largest healthcare market with underdeveloped ECMO infrastructure.
- Phosphorylcholine-Heparin Hybrid Coatings:Convergence of two biocompatibility approaches enables anticoagulant-free short-term support, opening procedural applications in interventional cardiology suites.
- Mobile Stroke Unit Integration:Prehospital ECMO deployment for refractory cardiac arrest represents an emerging application channel with distinct procurement pathways through emergency medical services agencies.
Industry Challenges
- ISO 10993-4 Hemocompatibility Testing:Extended thrombogenicity validation protocols for novel membrane materials compress development timelines and inflate preclinical study costs.
- Legacy Perfusion Console Interoperability:Proprietary communication protocols between pump controllers and patient monitoring systems force costly middleware development for multi-vendor installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Extra Corporeal Membrane Oxygenation (ECMO) System Market |
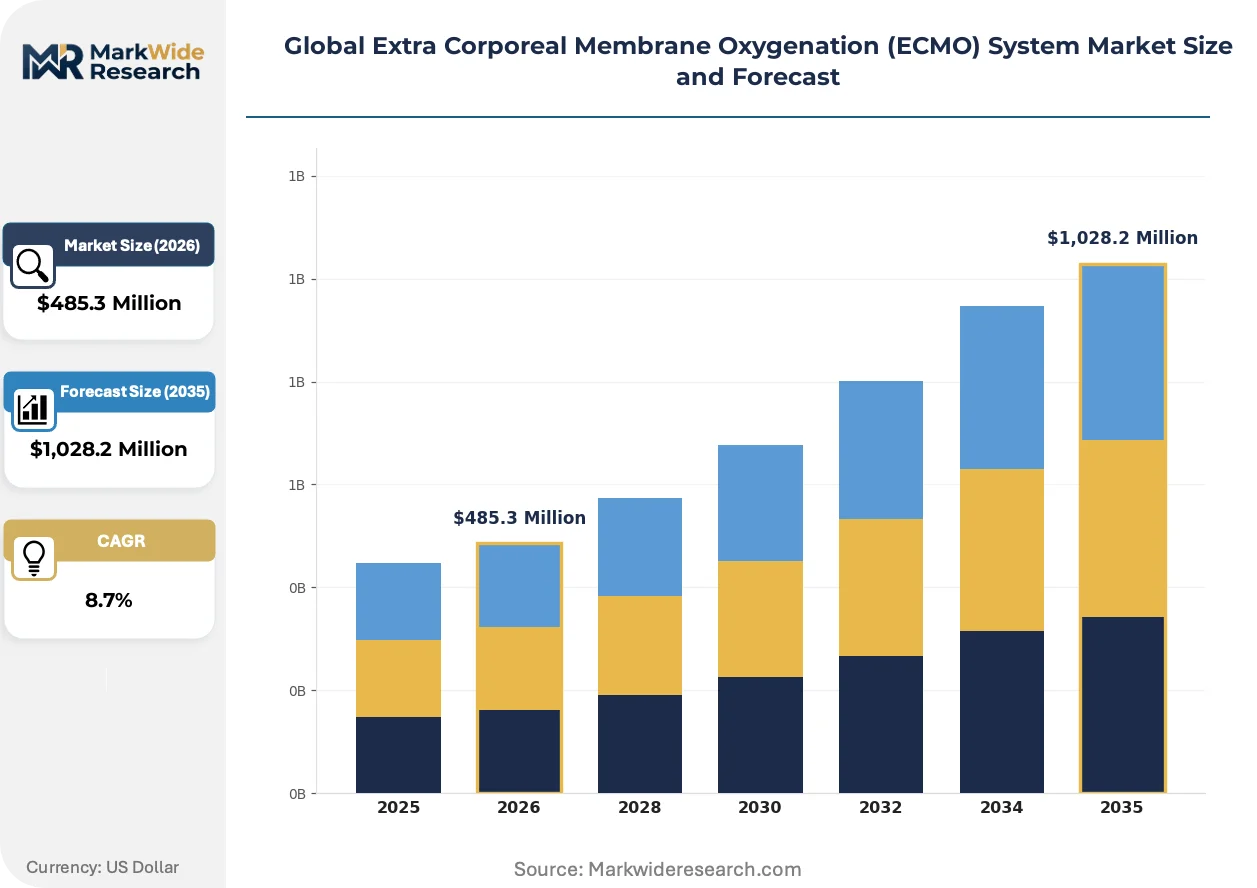
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $1,028.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Venoarterial ECMO, Venovenous ECMO, Portable ECMO, Modular ECMO Technology: Integrated Pump Oxygenators, Centrally Supported Systems, Wearable ECMO, Biocompatible Circuitry Application: Respiratory Failure, Cardiac Arrest Support, Bridge to Transplant, Postoperative Support, Neonatal Care End User: Cardiovascular ICUs, Pediatric Facilities, Specialized Clinics, Critical Care Units |
| Companies Covered | Getinge AB, Medtronic, LivaNova PLC, Terumo Corporation, Fresenius Medical Care AG & Co. KGaA, Abbott Laboratories, MicroPort Scientific Corporation, EUROSETS, Nipro Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Extra Corporeal Membrane Oxygenation (ECMO) System Market Shifts & Advancements
Membrane oxygenator technology is advancing through surface chemistry innovations and modular circuit architectures that reduce priming volume and heparin dependency. These developments are compressing the boundary between short-term cardiopulmonary bypass and prolonged extracorporeal support.
Magnetically levitated centrifugal pump technology is absorbing market share from roller pump designs in new installations. Pediatric and neonatal ECMO programs in Germany and the United States are adopting these systems at twice the rate of general critical care units. The technology is absorbing thrombus formation risk through elimination of mechanical bearings, enabling longer safe perfusion durations without circuit exchange.
EMA Medical Device Regulation biocompatibility standards are tightening material traceability requirements for oxygenator membranes used beyond 14 days. Manufacturers must now submit supply chain documentation for all polymer additives and surface treatments. Long-duration venovenous configurations for bridge-to-transplant applications face the most significant compliance burden, with several products undergoing supplemental MDR conformity reviews.
Service contracting structures are unbundling from capital equipment sales as hospital purchasing departments seek operational expenditure treatment for ECMO programs. Third-party perfusion service providers in Japan and the United States are capturing circuit management and on-call staffing responsibilities previously bundled with device procurement. This shift is most pronounced in mid-sized community hospitals establishing ECMO capabilities without dedicated in-house perfusion teams.
Global Extra Corporeal Membrane Oxygenation (ECMO) System Market Segmentation
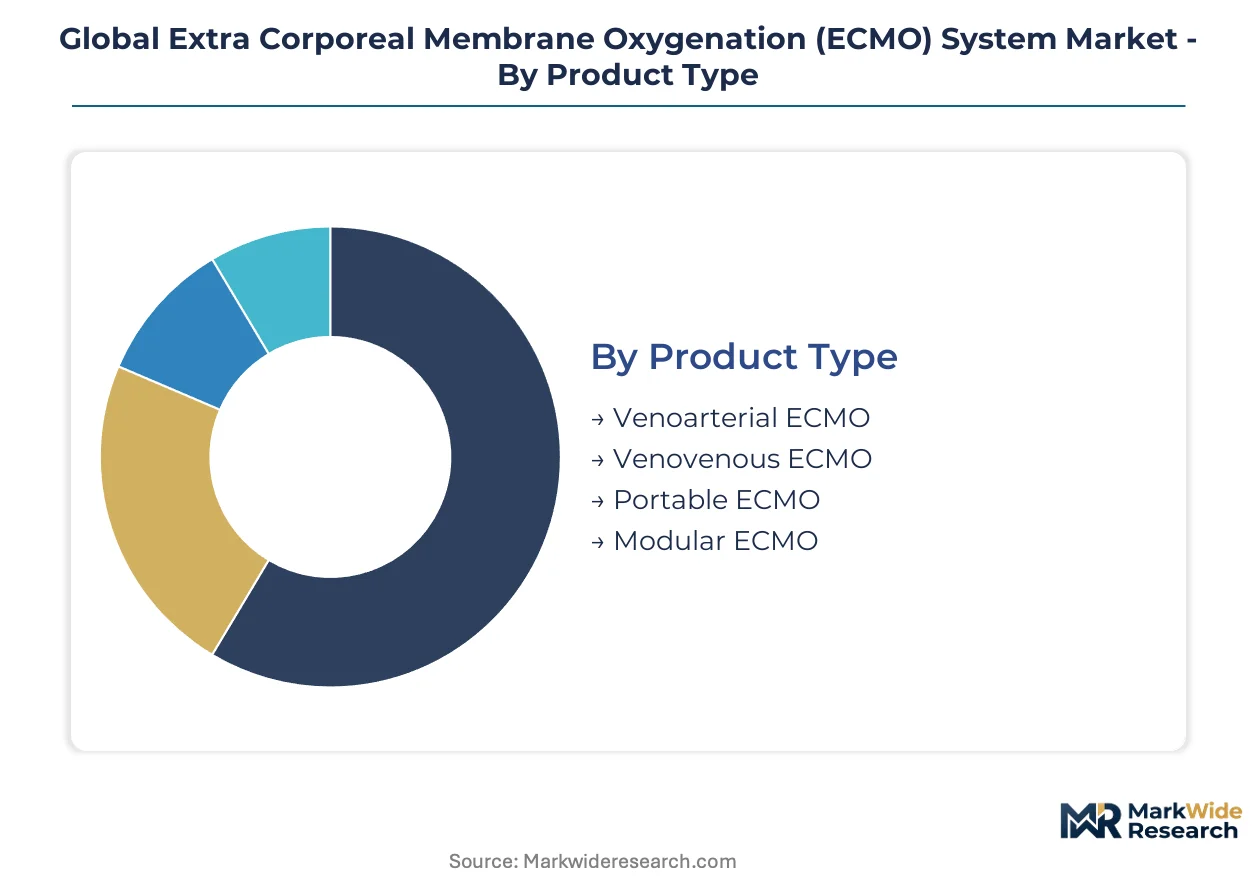
ECMO system procurement varies sharply by clinical setting and support duration, with configuration choices directly determining staffing requirements, anticoagulation protocols, and facility reimbursement eligibility. Understanding segment boundaries helps vendors align product roadmaps with the specific evidence thresholds and operator training demands of each use case.
Product Type:
Upgrade cycles in this category track the expansion of dedicated ECMO center networks, with hospitals replacing legacy consoles to gain transport compatibility and remote monitoring capabilities.
- Venoarterial ECMO:Dual cardiac and pulmonary support configuration employing femoral or central cannulation strategies to maintain systemic perfusion during cardiogenic shock or post-cardiotomy failure. Demand concentrates in Germany and the United States where cardiovascular surgery volumes and ECPR protocols drive installed base expansion. The configuration commands premium positioning due to perfusionist staffing requirements and higher complication management complexity.
- Venovenous ECMO:Isolated respiratory support circuit routing deoxygenated blood from femoral or jugular access through the oxygenator and returning to the right atrium, preserving native cardiac output. Japanese tertiary centers and US academic medical centers lead adoption for severe ARDS bridging, with PMDA center designation programs accelerating procurement in Tokyo and Osaka hospital networks.
- Portable ECMO:Compact pump-oxygenator units designed for inter-hospital transport and prehospital deployment, typically under 15 kg total system weight.
- Modular ECMO:Configurable circuit architectures allowing rapid conversion between venovenous and venoarterial modes or integration with ventricular assist devices.
Venoarterial ECMO leads volumes today; portable ECMO is gaining share fastest.
Technology:
Technology selection in new installations increasingly favors systems that reduce heparin dependency and enable longer safe perfusion durations without circuit exchange.
- Integrated Pump Oxygenators:Combined centrifugal pump and membrane oxygenator units with shared housing and reduced priming volume, typically 200-400 mL. Pediatric facilities in the United States and Germany favor these systems for neonatal applications where circuit volume relative to patient blood volume is critical. Surface coating technologies including phosphorylcholine and heparin bonding dominate procurement specifications.
- Centrally Supported Systems:Traditional console-based configurations with separate roller or centrifugal pumps and standalone oxygenators, common in established cardiac surgery departments.
- Wearable ECMO:Miniaturized ambulatory systems enabling patient mobilization during prolonged support, currently limited to investigational and bridge-to-transplant protocols.
- Biocompatible Circuitry:Heparin-coated, phosphorylcholine-treated, or silicone-free tubing and connectors reducing thrombogenicity and platelet activation.
Centrally supported systems dominate current installed base; biocompatible circuitry is expanding most quickly in replacement procurement.
Application:
Application mix varies by regional emergency medical infrastructure and organ transplantation availability, with some indications requiring specialized center designation for reimbursement.
- Respiratory Failure:Severe ARDS and refractory hypoxemia management through venovenous configuration, typically initiated after failure of lung-protective ventilation and prone positioning. Post-pandemic protocol expansion has broadened demand beyond traditional academic centers into community hospital systems in the United States and Germany. EMA MDR clinical evidence requirements now mandate registry participation for devices claiming extended duration support.
- Cardiac Arrest Support:Extracorporeal cardiopulmonary resuscitation (ECPR) deployment for refractory out-of-hospital or in-hospital cardiac arrest, requiring rapid cannulation and perfusion initiation. Japanese emergency medical services in Tokyo and Kanagawa prefecture have pioneered prehospital activation protocols, with PMDA device approvals contingent on demonstrated time-to-flow performance.
- Bridge to Transplant:Prolonged support maintaining organ perfusion while awaiting heart or lung transplantation, requiring durable circuit configurations and anticoagulation management.
- Postoperative Support:Temporary cardiopulmonary assistance following cardiac surgery, historically the foundational ECMO indication with established perfusionist training pathways.
- Neonatal Care:Specialized low-volume circuits for congenital diaphragmatic hernia, meconium aspiration, and persistent pulmonary hypertension in newborns.
Postoperative support retains the largest procedure volume; respiratory failure applications are climbing the fastest.
End User:
End user structure reflects the consolidation of ECMO programs into high-volume centers capable of sustaining 24/7 perfusionist coverage and multidisciplinary team coordination.
- Cardiovascular ICUs:Centralized units combining cardiac surgery, interventional cardiology, and critical care expertise with dedicated perfusion teams. German hospital networks have formalized this model through regional ECMO center certification, concentrating equipment procurement in Düsseldorf, Munich, and Berlin tertiary facilities. Staffing requirements limit expansion regardless of capital budget availability.
- Pediatric Facilities:Children's hospitals and neonatal intensive care units requiring specialized low-prime circuits and size-appropriate cannulation strategies. US children's hospitals in Boston, Philadelphia, and Cincinnati anchor demand, with LivaNova and Medtronic competing on specialized oxygenator surface area configurations.
- Specialized Clinics:Outpatient and ambulatory settings exploring wearable ECMO for bridge-to-transplant candidates, currently limited to investigational protocols.
- Critical Care Units:Medical ICU settings adopting ECMO for respiratory failure without surgical backup, requiring telemedicine links to specialized centers.
Cardiovascular ICUs dominate current procurement; pediatric facilities show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's cardiovascular surgery networks generate denser ECMO utilization than Japan's emergency medical services, yet both markets concentrate procurement in government-certified tertiary facilities with specialized perfusionist staffing.
United States
Academic medical centers in Boston, Philadelphia, and Cincinnati anchor ECMO program expansion for respiratory failure protocols. FDA 510(k) clearance pathways streamline predicate oxygenator approvals, accelerating product iteration cycles. Mid-sized community hospitals in the Southeast and Midwest are establishing telemedicine-linked ECMO capabilities without dedicated in-house perfusion teams.
Germany
Regional ECMO center certification concentrates equipment procurement in Düsseldorf, Munich, and Berlin tertiary facilities. EMA MDR conformity assessments mandate prospective registry data for extended perfusion duration claims, extending timelines for novel circuit designs. Cardiovascular ICUs in North Rhine-Westphalia and Bavaria formalize multidisciplinary team coordination with 24/7 perfusionist coverage.
Japan
PMDA center designation programs accelerate procurement in Tokyo and Osaka hospital networks with established extracorporeal life support programs. Government-certified ECMO centers receive preferential reimbursement and equipment subsidies, concentrating demand in tertiary facilities. Emergency medical services in Tokyo and Kanagawa prefecture pioneer prehospital activation protocols for refractory cardiac arrest.
China
Tertiary hospitals in Beijing, Shanghai, and Guangzhou expand ECMO capabilities for post-cardiotomy and severe ARDS indications. NMPA medical device registration requires distinct clinical evidence standards for long-term circulatory support devices, creating additional regulatory layers for market entrants. Provincial health commissions concentrate advanced life support equipment procurement in designated cardiovascular centers.
Brazil
ANVISA expedited review channels for life-support devices create first-mover positioning in Latin America's largest healthcare market with underdeveloped ECMO infrastructure. Tertiary facilities in São Paulo and Rio de Janeiro anchor initial program development. Private hospital networks in the Southeast region drive capital equipment procurement ahead of public sector adoption.
Global Extra Corporeal Membrane Oxygenation (ECMO) System Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the ECMO system landscape, creating a tiered structure where scale-driven portfolios intersect with niche clinical expertise. The vendor base clusters around three strategic archetypes: integrated critical care platform providers, specialized cardiovascular device manufacturers, and regional perfusion technology suppliers. Competitive dynamics center on biocompatibility coating differentiation and transport-capable system miniaturization. M&A activity targets complementary oxygenator membrane technologies, while strategic partnerships address perfusionist staffing shortages through outsourced service models.
Among diversified critical care platform providers, Getinge AB and Medtronic occupy positions representing integrated system architectures and established installed base leverage. LivaNova PLC exemplifies the specialized cardiovascular manufacturer archetype, with its corporate structure signaling focused clinical expertise. These three entities anchor competitive positioning across the premium equipment tier, with their geographic origins—Swedish, American, and UK-based respectively—reflecting the market's transatlantic concentration.
| Leading Market Players |
|---|
| Getinge AB |
| Medtronic |
| LivaNova PLC |
| Terumo Corporation |
| Fresenius Medical Care AG & Co. KGaA |
| Abbott Laboratories |
| MicroPort Scientific Corporation |
| EUROSETS |
| Nipro Corporation |
| Others |
Supply & Pricing Matrix
Perfusionist workforce concentration in Germany and Japan compresses labor-cost differentials into pricing-tier spreads between centralized cardiovascular ICUs and mid-sized community hospitals lacking dedicated staffing.
Pricing Analysis
Capacity additions in China are reshaping price floors for membrane oxygenator components as domestic NMPA-registered suppliers expand output. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) predicate tiering against novel MDR-compliant designs. Cost compression in standard-tier systems is intensifying because biocompatible coating commoditization erodes historical brand premiums. Community hospitals in the United States exhibit highest price sensitivity due to telemedicine-linked service contracting models, while Japanese PMDA-designated centers absorb premium positioning through government equipment subsidies.
Supply Chain Analysis
Direct-to-hospital channels handle high-acuity procurement for certified ECMO centers, with GPO-aggregated contracts serving mid-tier facilities. Microporous silicone sheet production draws from Japan, Germany, and select United States specialty polymer suppliers. Heparin coating substrates, phosphorylcholine surface treatment chemicals, and magnetically levitated pump bearings constitute critical input dependencies. Single-source vulnerability concentrates in long-duration oxygenator membrane supply, where three suppliers control medical-grade silicone polymerization. Distribution runs through regional cardiovascular device distributors with perfusionist training bundling, supplemented by third-party service providers capturing circuit management responsibilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between FDA 510(k) streamlined pathways and EMA MDR extended evidence requirements creates geographic cost differentials for product launch sequencing.
For Market Incumbents: Hedge against phosphorylcholine-heparin hybrid coating commoditization by deepening backward integration into silicone membrane polymerization. Secure captive supply of medical-grade silicone sheet through offtake agreements with Japanese and German specialty chemical suppliers. Capacity addition in China offers cost-position defense against emerging domestic competitors targeting Southeast Asian hospital networks. For New Entrants and Emerging Players: Launch via third-party perfusion service partnerships to bypass incumbent-installed base lock-in at mid-sized United States community hospitals. Brazil ANVISA expedited review channels present the most penetrable regulatory entry point for Latin American market establishment. Target neonatal circuit specialization as a go-to-market angle, leveraging lower evidence thresholds for pediatric indications against adult-bridge-to-transplant complexity. For Investors and Strategic Acquirers: Diversified critical care platform providers are the most active acquirer in this space, seeking complementary oxygenator membrane technologies to fill portfolio gaps. Long-term viability hinges on biocompatibility coating differentiation sustaining margin structure against coating commoditization. Acquisition target archetype: regional perfusion technology suppliers with established hospital service contracts and specialized pediatric circuit expertise. Watch PMDA center designation program expansion velocity as inflection indicator for Asia-Pacific demand concentration.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Conformity Assessment Investment | EMA registry data requirements extend timelines for novel circuit designs entering European hospital networks. |
| Biocompatibility Coating R&D Partnership | Phosphorylcholine-heparin hybrid development opens anticoagulant-free applications in interventional cardiology suites. |
| Third-Party Perfusion Service Expansion | Outsourced circuit management captures operational expenditure treatment preferences in United States community hospitals. |
| PMDA Center Designation Alignment | Government-certified ECMO center status unlocks preferential reimbursement and equipment subsidies in Tokyo and Osaka networks. |
| Mobile Stroke Unit Integration | Prehospital ECMO deployment for refractory cardiac arrest creates emergency medical services procurement channel distinct from hospital capital budgets. |
Research Methodology
Bottom-up cardiovascular ICU modeling reconciled against top-down oxygenator membrane production tracking forms the analytical core. Primary interviews with perfusionists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EMA MDR submission databases, PMDA approval records, and hospital procurement databases. Triangulation across stakeholder inputs and regulatory documentation ensures segmentation integrity.
Input-output matrices map membrane surface area configurations against cannulation strategy adoption patterns across the projection horizon. Segmentation dimensions modeled include product type, technology platform, clinical application, and end-user facility tier. CAGRs derive from installed base replacement cycles, center network expansion rates, and procedure volume elasticity to respiratory failure protocol adoption. Forecast inputs incorporate perfusionist staffing ratios, biocompatibility coating penetration curves, and transport-capable system miniaturization trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under silicone membrane supply disruption or accelerated MDR clinical evidence requirement expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiology Equipment
Global Coronary Artery Bypass Grafting Market
Cardiology Equipment
North America Cardiac Monitoring Market
Cardiology Equipment
Cardiopulmonary Auto-Transfusion System Market
Cardiology Equipment
Global Extracorporeal Membrane Oxygenation Machine Market
Cardiology Equipment
Heart Scan Market
Cardiology Equipment
Global Stethoscope Market
Cardiology Equipment
Cardiac Ultrasound Systems Market
Cardiology Equipment
Global Cardiac Restoration Systems Market
Cardiology Equipment
Europe Cardiac Monitoring Market
Cardiology Equipment
Europe ECG Electrodes Market
Cardiology Equipment
Rheumatic-Heart Disease Management Market
Cardiology Equipment
Cardiomyopathy Medication Market
Cardiology Equipment
Heart Lung Machine Market
Cardiology Equipment
Cardiotoxicity Market
Cardiology Equipment
Wireless Cardiac Monitoring Systems Market
Cardiology Equipment
Global Cardiac Monitoring Market