
 North America Cardiac Rhythm Management Market | 2026-2036
North America Cardiac Rhythm Management Market Size, Share, and Industry Trends Forecast 2026-2036
North America Cardiac Rhythm Management Market Insights
Magnetic resonance-conditional device certification is collapsing the barrier between cardiac implant eligibility and diagnostic imaging access. Medtronic leverages its integrated manufacturing footprint to control supply continuity for leadless pacing systems. Boston Scientific Corporation competes through specialized electrophysiology portfolios that anchor its position in ambulatory settings.
Cardiac rhythm management encompasses implantable and external technologies that monitor, regulate, or restore normal heart rhythm through electrical stimulation or pharmaceutical intervention, with devices typically specified by battery longevity, lead configuration, and MRI compatibility ratings. The primary purpose centers on reducing sudden cardiac death incidence and managing chronic arrhythmia burden across acute and chronic care pathways. Defibrillator systems lead device type revenue given their premium pricing and replacement cycle density, while loop recorders represent the fastest-expanding segment as diagnostic gatekeeping intensifies before invasive intervention. Hospitals command the dominant end user share through capital equipment concentration and procedural volume, though home care settings emerge as a margin-attractive channel as remote monitoring platforms mature.
FDA premarket approval requirements and HIPAA data security mandates shape product development timelines and post-market surveillance obligations for manufacturers operating in the United States. Health Canada's Medical Devices Bureau and ISO 14155 clinical investigation standards impose additional compliance layers for cross-border commercialization. Stakeholders must monitor reimbursement parity between remote monitoring and in-clinic follow-up as policy determinations will restructure patient retention economics and service model profitability.
Market Dynamics
Leadless pacing technology and MRI-conditional device certification are restructuring patient eligibility criteria and procurement specifications across integrated delivery networks. The FDA's streamlined premarket review pathways for subcutaneous defibrillators compress commercialization timelines while Medicare reimbursement parity debates reshape service economics.
Growth Catalysts
- CMS remote monitoring reimbursement codes:Medicare's expanded coverage for continuous cardiac monitoring creates financial viability for ambulatory care expansion beyond hospital settings.
- Subcutaneous ICD miniaturization:Elimination of transvenous leads reduces long-term complication rates and opens eligibility to patients previously excluded due to vascular access limitations.
- Ambulatory surgical center accreditation:Shifting procedure volumes to lower-cost settings accelerates device turnover and expands addressable patient populations.
Market Restraints
- Lithium-iodine battery supply concentration:Single-source dependencies for high-density power cells create vulnerability in implantable device manufacturing schedules.
- FDA premarket approval timelines:Extended review periods for novel leadless systems delay revenue recognition and compress effective patent life.
- Transcatheter aortic valve replacement substitution:Structural heart interventions for atrial fibrillation patients reduce arrhythmia burden and defer rhythm management device implantation.
Strategic Opportunities
- Home-based cardiac rehabilitation integration:Pairing rhythm management devices with remote physiologic monitoring creates subscription revenue streams outside acute episodes.
- Health Canada parallel review pathways:Synchronized FDA-Health Canada submissions accelerate cross-border commercialization for Canadian integrated delivery networks.
- Artificial intelligence-ECG convergence:Embedded algorithmic arrhythmia detection in consumer wearables creates diagnostic referral pipelines to specialized electrophysiology practices.
Industry Challenges
- Electrophysiology fellowship pipeline constraints:Procedural complexity outpaces specialist training capacity, creating regional access disparities for device implantation.
- Legacy device cybersecurity retrofitting:HIPAA-mandated data protection requirements force firmware updates for installed pacemaker and defibrillator bases without remote update capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Cardiac Rhythm Management Market |
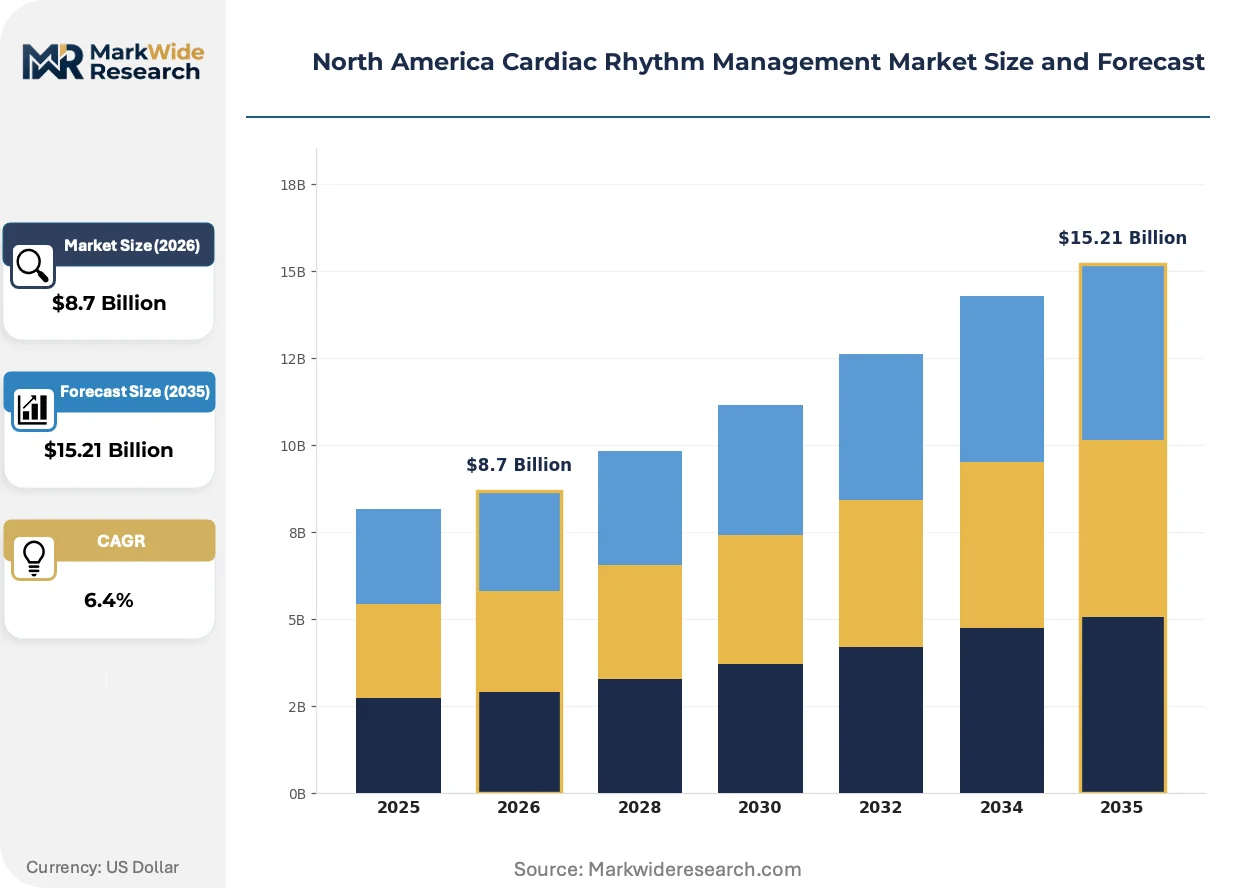
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Pacemakers, Defibrillators, Loop Recorders, Cardiac Monitors End User: Hospitals, Cardiology Clinics, Ambulatory Surgical Centers, Home Care Settings Therapy Area: Atrial Fibrillation, Heart Failure, Ventricular Tachycardia, Bradycardia Distribution Channel: Direct Sales, Distributors, Online Platforms, Third-party Providers |
| Companies Covered | Medtronic, Boston Scientific Corporation, Abbott, Koninklijke Philips, Biotronik, Johnson & Johnson, LivaNova, MicroPort Scientific Corporation, Stryker, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Cardiac Rhythm Management Market Trends and Innovations
Device miniaturization and algorithmic diagnostics are collapsing the distinction between implantable therapeutics and wearable monitoring, forcing portfolio reconfiguration across manufacturers serving North American health systems.
Leadless pacemaker technology is decomposing the traditional three-component system—pulse generator, transvenous lead, and electrode—into self-contained intracardiac capsules. Electrophysiology practices in high-volume academic medical centers are adopting these systems for bradyarrhythmia patients with compromised venous access. This convergence is decomposing the historical aftermarket for lead extraction procedures and revision surgeries.
FDA breakthrough device designation pathways for subcutaneous ICDs are compressing premarket review periods while maintaining safety benchmarks. The industrial consequence accelerates competitive entry against established transvenous systems. Device manufacturers are responding by building dedicated subcutaneous implant training infrastructure for community hospital electrophysiology programs.
Integrated delivery networks are consolidating cardiac device procurement through centralized value analysis committees. Independent ambulatory surgery centers are losing direct purchasing authority as health systems mandate standardized device formularies. This concentration is most visible in Texas and Florida markets where hospital system mergers have created dominant regional purchasing entities.
North America Cardiac Rhythm Management Market Segmentation
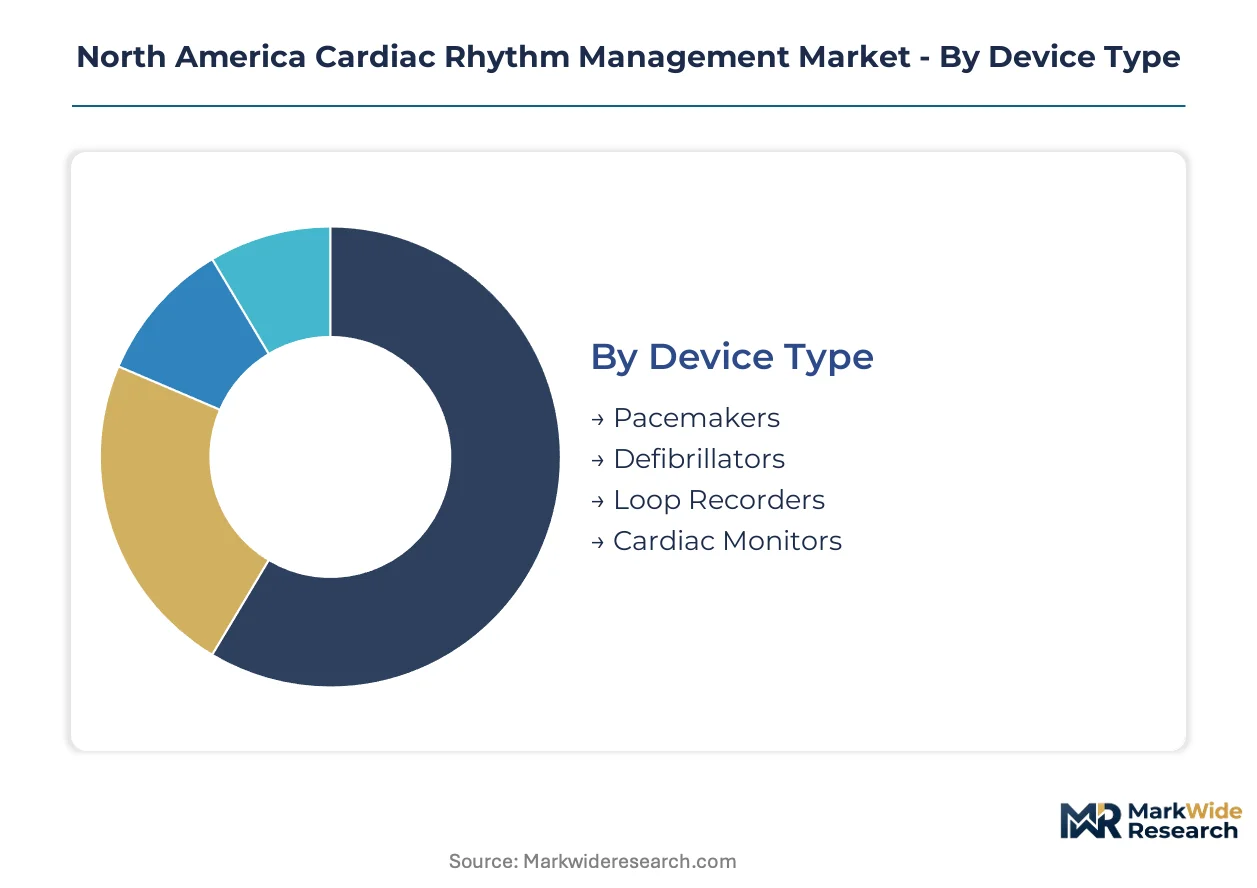
Cardiac rhythm management segmentation reflects divergent procurement pathways across integrated delivery networks and independent practice settings. Device specifications, reimbursement codes, and care site accreditation status reshape how manufacturers allocate sales resources and technical support infrastructure.
Device Type:
Pacemakers and defibrillators anchor domestic manufacturing output, while loop recorders and external monitors increasingly serve cross-border demand from Canadian health authorities seeking diagnostic capacity expansion.
- Pacemakers:Battery-powered pulse generators with transvenous or leadless configurations restore adequate heart rate in bradyarrhythmia patients. Demand concentrates in United States hospital systems where Medicare reimbursement for dual-chamber devices exceeds single-chamber alternatives, though leadless systems command premium positioning in academic medical centers with extraction capability.
- Defibrillators:Transvenous ICDs and subcutaneous variants deliver high-voltage therapy for ventricular tachyarrhythmias with programmable anti-tachycardia pacing. United States integrated delivery networks prioritize MRI-conditional systems to reduce imaging access barriers, while Health Canada parallel review pathways accelerate adoption in Ontario and Quebec procurement regions.
- Loop Recorders:Subcutaneous implantable monitors with wireless transmission capability enable extended ambulatory ECG surveillance.
- Cardiac Monitors:External patch-based and wearable systems provide short-term rhythm assessment in pre-implantation evaluation protocols.
Defibrillator systems command the established base. The steepest expansion runs through loop recorders.
End User:
Cost tier stratification separates capital-intensive hospital implant programs from margin-focused ambulatory settings where procedure reimbursement differentials determine site viability.
- Hospitals:Acute care facilities with electrophysiology laboratories maintain device inventory for emergency implantation and complex revision procedures. United States hospital systems in Texas and Florida markets leverage scale to negotiate exclusive device formularies, while Canadian tertiary centers anchor provincial cardiac device procurement.
- Cardiology Clinics:Specialized outpatient practices manage device programming, interrogation, and chronic disease follow-up with in-office telemetry systems. Demand clusters in United States metropolitan areas with electrophysiologist density sufficient to support dedicated device management revenue streams.
- Ambulatory Surgical Centers:Medicare-accredited sites perform low-complexity pacemaker implants at reduced reimbursement rates.
- Home Care Settings:Remote monitoring infrastructure enables transtelephonic follow-up outside clinical facilities.
Hospitals retain the volume concentration. Ambulatory surgical centers are climbing the fastest as site-of-service differentials widen.
Therapy Area:
Application urgency varies across arrhythmia types, with sudden cardiac death prevention driving premium device allocation versus chronic rate management protocols.
- Atrial Fibrillation:The most prevalent sustained arrhythmia requiring rate or rhythm control strategies, often complicating device selection for concomitant bradyarrhythmia. United States electrophysiology practices increasingly defer device implantation until after catheter ablation failure, compressing addressable volumes in high-ablation regions.
- Heart Failure:Cardiac resynchronization therapy indications depend on QRS morphology and ejection fraction thresholds with strict Medicare coverage criteria. Demand concentrates in United States heart failure referral networks where CRT-D systems integrate defibrillation capability with biventricular pacing.
- Ventricular Tachycardia:Life-threatening arrhythmia mandating ICD therapy for secondary prevention in post-infarction patients.
- Bradycardia:Symptomatic conduction system disease requiring permanent pacing across diverse etiologies.
Heart failure applications command the established base. Atrial fibrillation management is gaining share fastest as ablation-device sequencing evolves.
Distribution Channel:
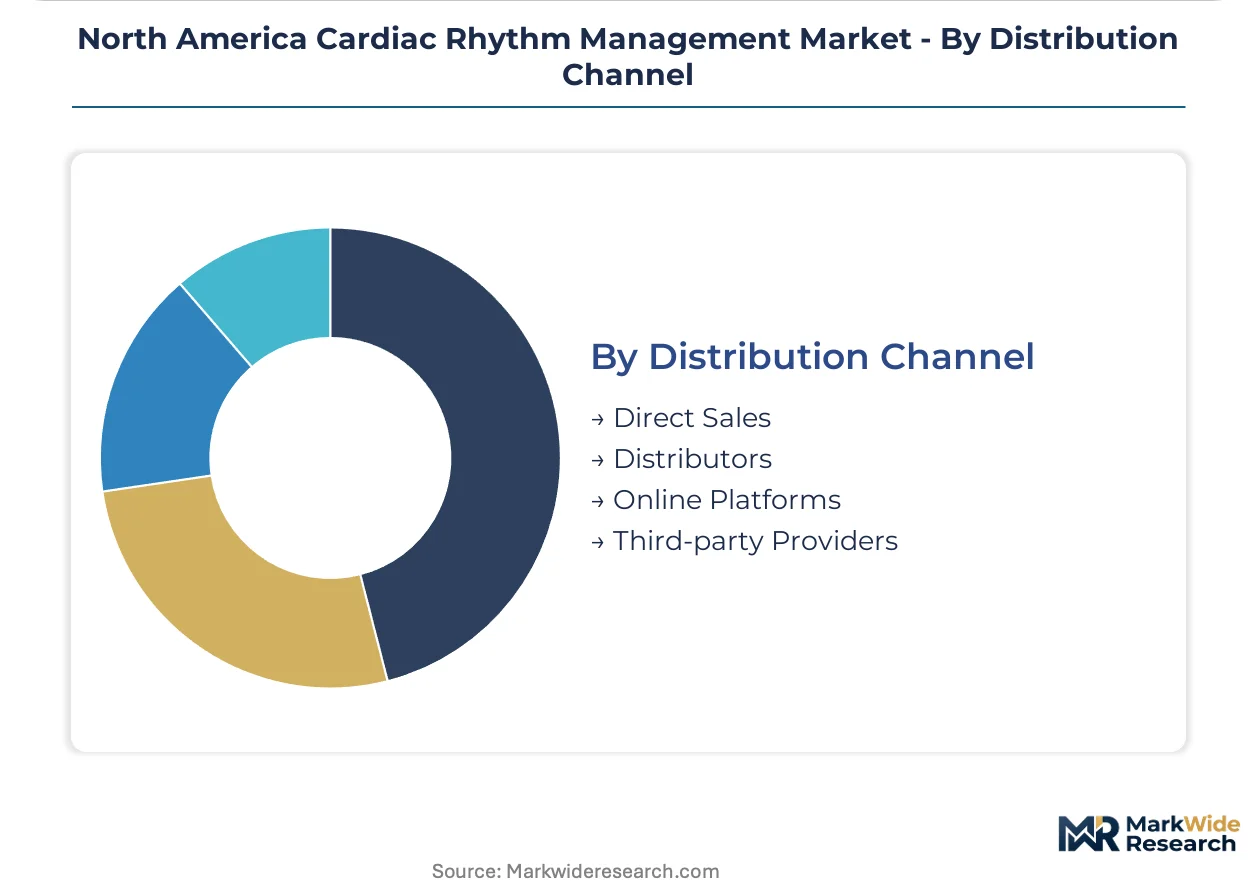
Customer type and purchase scale determine channel selection, with direct relationships dominating high-volume accounts and intermediaries serving fragmented access points.
- Direct Sales:Manufacturer-employed representatives manage contracting, implant support, and inventory logistics for United States integrated delivery networks with standardized formularies. Health Canada-registered devices move through parallel direct channels serving provincial health authorities with centralized procurement.
- Distributors:Regional medical device wholesalers stock inventory for community hospitals and independent cardiology practices lacking direct manufacturer contracts. Canadian distribution networks emphasize cross-provincial logistics to serve dispersed populations outside Toronto, Montreal, and Vancouver corridors.
- Online Platforms:Emerging procurement channels for external monitoring accessories and replacement components.
- Third-party Providers:Group purchasing organizations and implant management companies aggregate demand across independent sites.
Direct sales commands the established base. Third-party providers are expanding most quickly as purchasing consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing clusters concentrate in Minnesota and Massachusetts corridors, with regulatory pathways diverging sharply between FDA and Health Canada jurisdictions. Procurement consolidation in Texas and Florida hospital systems reshapes competitive access across the continent.
United States
Medicare reimbursement parity debates and integrated delivery network purchasing consolidation drive demand concentration in Texas and Florida markets. FDA breakthrough device designation pathways for subcutaneous ICDs compress premarket review timelines while maintaining safety benchmarks. The Minneapolis-St. Paul corridor anchors manufacturing for leadless pacing systems, with Medtronic leveraging integrated production footprints to control supply continuity.
Canada
Health Canada's Medical Devices Bureau and ISO 14155 clinical investigation standards impose compliance layers for cross-border commercialization into Ontario and Quebec procurement regions. Provincial health authorities in Toronto and Montreal anchor centralized cardiac device purchasing, with parallel FDA-Health Canada review pathways accelerating adoption timelines. Remote monitoring infrastructure expansion targets dispersed populations outside major urban corridors.
Mexico
Medical tourism corridors in Mexico City and Monterrey attract cross-border cardiac procedures from uninsured U.S. patients seeking cost-differentiated implant services. COFEPRIS regulatory alignment with FDA standards facilitates device importation for private hospital networks. Manufacturing presence remains limited to assembly operations serving domestic consumption and export to Central American markets.
California
Silicon Valley algorithm development clusters converge with Stanford and UCLA electrophysiology programs to advance AI-ECG diagnostic integration. Kaiser Permanente's integrated model demonstrates at-scale remote monitoring deployment, influencing reimbursement policy debates in Washington. Cybersecurity retrofitting obligations for legacy device bases impose firmware update costs concentrated in this high-installed-base region.
New York Metro
Academic medical centers in Manhattan and Long Island anchor complex lead extraction and revision surgery volumes, driving adoption of leadless systems among compromised venous access patients. State-level Medicaid reimbursement rates for device implantation lag Medicare benchmarks, compressing margins for safety-net hospital programs. Fellowship training pipeline constraints in Northeast electrophysiology programs create regional access disparities.
North America Cardiac Rhythm Management Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North American cardiac rhythm management sector. Consolidated manufacturing scale dominates implantable device categories while specialized electrophysiology portfolios anchor ambulatory setting penetration. Three strategic archetypes emerge: integrated diversified conglomerates with cardiovascular device divisions, pure-play cardiac rhythm specialists, and diversified medical technology platforms with electrophysiology extensions. Competitive moves concentrate on M&A for algorithmic diagnostics capability and strategic partnerships for remote monitoring platform integration.
Among diversified medical technology platforms, Medtronic and Boston Scientific Corporation exemplify contrasting strategic positions within the integrated delivery network procurement landscape. Abbott occupies a position bridging pharmaceutical and device portfolios, while Koninklijke Philips represents the diagnostic imaging convergence archetype. Biotronik anchors the European-origin specialist tier competing on MRI-conditional device certification timelines.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Abbott |
| Koninklijke Philips |
| Biotronik |
| Johnson & Johnson |
| LivaNova |
| MicroPort Scientific Corporation |
| Stryker |
| Others |
Pricing and Supply Chain Analysis
Lithium-iodine battery chemistry substitution for silver vanadium oxide in high-density implantable power cells simultaneously shifts supply geography toward Japanese and South Korean chemical processors and compresses pricing premiums for extended-longevity devices across Medicare reimbursement tiers.
Pricing Analysis
Medicare reimbursement parity dictates the pricing tier structure across the North American cardiac rhythm management landscape. Three-tier pricing structure across premium, standard, and economy levels separates MRI-conditional leadless systems from conventional dual-chamber pacemakers and basic single-chamber alternatives. Price differentiation rests on battery longevity specifications and lead configuration complexity. Cost compression in the standard tier is intensifying because integrated delivery networks negotiate exclusive formularies that strip brand premiums. Ambulatory surgical centers exhibit the highest price sensitivity due to thin procedure margins, while academic medical centers with extraction capabilities absorb premium positioning for leadless systems.
Supply Chain Analysis
Single-source lithium-iodine cell production from Japanese chemical conglomerates creates a chokepoint that underwrites manufacturing continuity risk for implantable device assemblers in Minnesota and Massachusetts corridors. Supply geography draws from Japan, South Korea, and Belgium for high-density power cells, precision capacitors, and biocompatible titanium housings. Raw material dependencies hinge on iodine extraction from Chilean caliche deposits, tantalum capacitor-grade powder from Central African conflict-mineral zones, and medical-grade silicone from German chemical processors. Tariff exposure on Chinese-sourced electronic components threatens cost structures for external monitoring accessories. Distribution runs through manufacturer-direct salesforces for integrated delivery networks, with regional distributors serving fragmented community hospital access points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North American cardiac rhythm management market sits in early-cycle expansion as leadless pacing technology penetrates patient populations previously excluded from implantable therapy due to venous access limitations.
For Market Incumbents: Secure extraction-capable electrophysiology training infrastructure to defend leadless system revenue streams against transcatheter aortic valve replacement substitution that defers rhythm management device implantation. Deepen backward integration into lithium-iodine cell supply through long-term offtake agreements with Japanese chemical processors to mitigate single-source battery vulnerability. Prioritize Health Canada parallel review pathway investment to accelerate cross-border commercialization ahead of reimbursement parity debates.
For New Entrants and Emerging Players: Lead with AI-ECG algorithm development partnerships with Silicon Valley diagnostic clusters to create diagnostic referral pipelines into underserved community electrophysiology practices. Target home-based cardiac rehabilitation integration as the most penetrable white space, pairing rhythm management devices with remote physiologic monitoring to capture subscription revenue outside acute episodes. Pursue ambulatory surgical center accreditation as the primary go-to-market angle to bypass integrated delivery network procurement concentration.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed electrophysiology practice management platforms consolidating community implant volumes ahead of hospital system merger waves. Long-term viability frames around algorithmic diagnostics capability and remote monitoring platform integration over the coming decade. Acquisition target archetypes include wearable ECG startups with FDA breakthrough device designation progress and specialized lead extraction service providers. Watch Medicare reimbursement parity determinations between remote monitoring and in-clinic follow-up as the signal for patient retention economics inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates premarket review timelines for subcutaneous ICD systems against established transvenous competitors. |
| Hospital System Partnership | Locks exclusive device formulary access through centralized value analysis committee relationships in Texas and Florida markets. |
| Reimbursement Strategy | Secures CMS remote monitoring code coverage parity to enable ambulatory care expansion beyond hospital settings. |
| Software Companion Development | Integrates AI-ECG diagnostic algorithms with implantable device data streams for predictive arrhythmia management. |
| CE Marking Pathway | Opens parallel European commercialization for MRI-conditional leadless systems manufactured in North American facilities. |
Research Methodology
A standing panel of electrophysiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA premarket approval filings, Health Canada Medical Devices Bureau submissions, CMS Medicare reimbursement databases, and integrated delivery network procurement records. Bottom-up device shipment modeling triangulated against top-down healthcare expenditure analysis across the analysis window.
Cross-referencing against external benchmarks confirmed consistency across volume and value outputs. The analytical framework segmented projections by device type, end user accreditation status, therapy area urgency, and distribution channel concentration throughout the forecast period. CAGRs derived from replacement cycle density, procedural volume trajectories, and reimbursement code expansion timelines. Forecast inputs incorporated electrophysiology fellowship pipeline constraints and legacy device cybersecurity retrofitting obligations.
The analysis sits within stated boundaries; outcomes outside FDA premarket approval timeline assumptions and Medicare reimbursement parity determinations would require recalibration. Forecasts reflect documented assumptions regarding lithium-iodine battery supply continuity and Health Canada parallel review pathway adoption rates. Practitioners should keep alternative scenarios live as integrated delivery network merger activity and transcatheter structural heart intervention substitution evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiology Equipment
Cardiac Catheterization Market
Cardiology Equipment
Global Cardiac Monitoring Market
Cardiology Equipment
Wireless Cardiac Monitoring Systems Market
Cardiology Equipment
North America Cardiac Monitoring Market
Cardiology Equipment
Cardiotoxicity Market
Cardiology Equipment
Left Atrial Appendage (LAA) Closure Market
Cardiology Equipment
Rheumatic-Heart Disease Management Market
Cardiology Equipment
Global Stethoscope Market
Cardiology Equipment
Global Coronary Artery Bypass Grafting Market
Cardiology Equipment
Mobile Cardiac Telemetry Systems Market
Cardiology Equipment
Europe ECG Electrodes Market
Cardiology Equipment
Smart Stethoscopes Market
Cardiology Equipment
Intracardiac Echocardiography (ICE) Market
Cardiology Equipment
Global Cardiac Restoration Systems Market
Cardiology Equipment
Cardiomyopathy Medication Market
Cardiology Equipment
Intracardiac Imaging Market